
 Global Clinical Trial Support Services Market | 2026-2036
Global Clinical Trial Support Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Clinical Trial Support Services Market Foresight
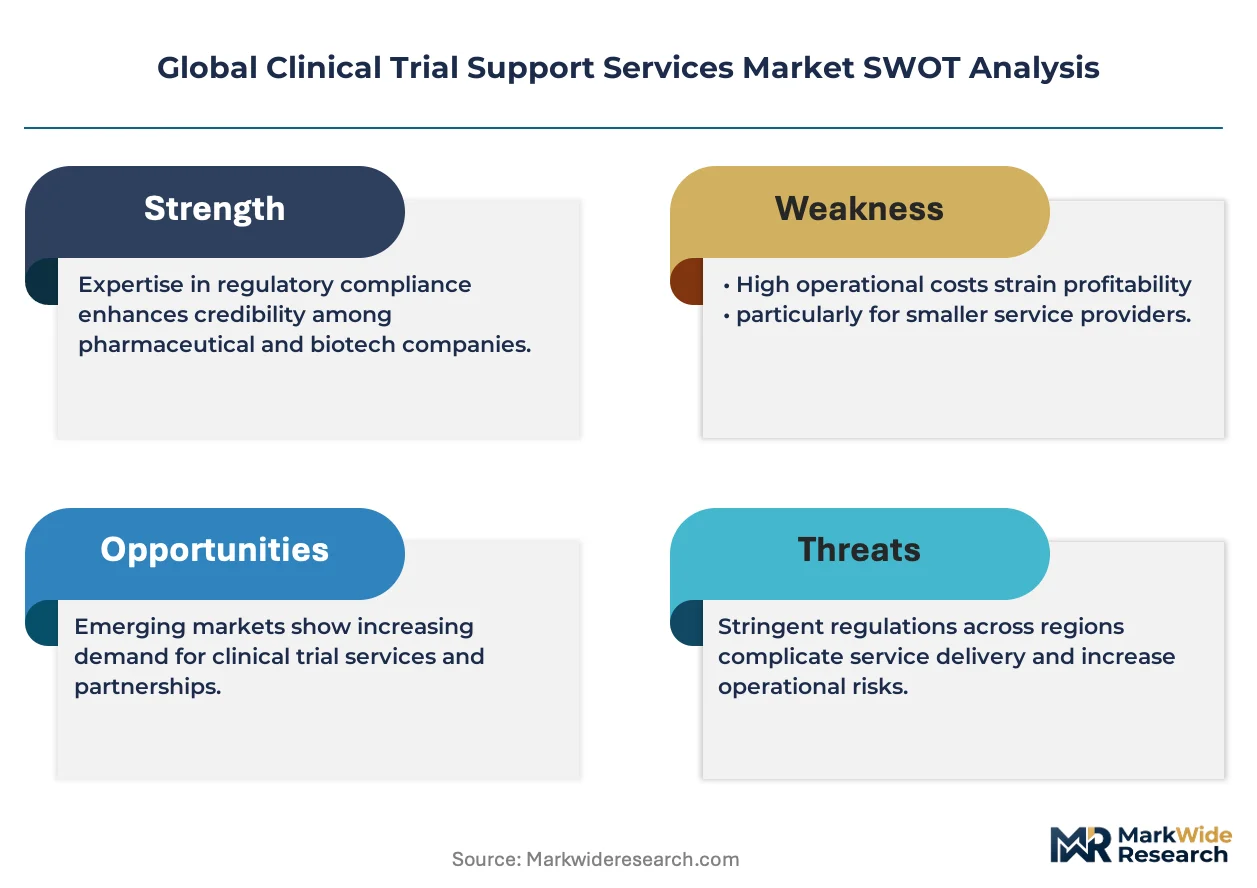
Site management revenue is rewriting margin economics across the clinical services value chain, pulling profitability away from pure data-processing contracts toward integrated patient-access and investigator-relationship offerings. IQVIA leverages its proprietary site network and real-world data assets to command premium pricing on full-service engagements. ICON plc anchors its competitive position through therapeutic-area depth in oncology and central nervous system trials. Charles River Laboratories International specializes in early-phase safety and pharmacology services that feed downstream into larger support contracts.
Clinical trial support services encompass the specialized operational, scientific, and regulatory functions that enable human studies to proceed from protocol design through database lock, including bioanalytical testing with GLP-compliant methodologies, electronic data capture systems validated to FDA 21 CFR Part 11 standards, and risk-based monitoring frameworks that optimize site oversight resource allocation. Patient recruitment and regulatory consulting command the widest margins among service types because sponsor desperation for enrollment velocity and submission readiness converts directly to pricing power. Oncology research and neurology trials represent the fastest-expanding application areas, driven by precision-medicine protocols that demand biomarker-integrated trial designs and adaptive statistical frameworks.
FDA's 21 CFR Part 11 and EMA's ICH-GCP E6(R2) guidelines shape demand for validated electronic systems and audit-ready quality management infrastructure, while the EU Clinical Trials Regulation harmonizes submission pathways across member states. Sponsors and providers must monitor how FDA's decentralized trial guidance and EMA's evolving expectations for direct-to-patient data capture reshape site selection and technology investment priorities.
Market Dynamics
FDA's decentralized trial guidance and EMA's direct-to-patient data capture mandates are compressing site selection timelines while forcing technology infrastructure upgrades across sponsor organizations.
Growth Catalysts
- Decentralized trial infrastructure:FDA's 2023 guidance on remote monitoring and direct-to-patient shipping enables sponsors to expand geographic reach without physical site expansion. Biopharmaceutical companies accelerate adoption of telemedicine-integrated protocols.
- EMA's ICH-GCP E6(R2):The guideline's risk-based monitoring framework mandates statistical sampling approaches that reduce on-site visits by up to 50 percent. CROs capture premium contracts for validated analytics platforms.
- Oncology protocol complexity:Precision-medicine trials requiring biomarker-integrated adaptive designs pull demand toward specialized providers with therapeutic-area depth. Patient stratification by genetic signature necessitates companion diagnostic coordination.
Market Restraints
- Investigator site concentration:Top-tier academic medical centers in the United States, Germany, and Japan control access to treatment-naive patient populations. Sponsor competition for these sites inflates startup fees and extends negotiation timelines.
- GLP laboratory capacity constraints:Bioanalytical testing for complex biologics requires specialized mass spectrometry and immunogenicity platforms. Equipment lead times and qualified personnel scarcity limit throughput expansion.
- Data localization requirements:China's NMPA and Russia's national data sovereignty rules prohibit cross-border transfer of patient records. Multinational sponsors must duplicate infrastructure or exclude these geographies from global protocols.
Strategic Opportunities
- Latin American site networks:Brazil's ANVISA and Mexico's COFEPRIS have streamlined clinical trial approval timelines to under 60 days. Untapped patient pools in oncology and infectious disease attract mid-phase study migration.
- Real-world evidence integration:Convergence of electronic health records with trial data capture enables protocol amendments based on ongoing safety signals. Sponsors reduce Phase III failure rates through adaptive enrollment criteria.
- EU Clinical Trials Regulation harmonization:The unified CTIS portal eliminates redundant national submissions across 27 member states. Single-application pathways reduce administrative burden for multi-country protocols.
Industry Challenges
- Clinical research associate talent scarcity:Monitoring workforce attrition exceeds replacement rates in the United States and Western Europe. Sponsors compete for professionals with therapeutic-area certification and risk-based monitoring credentials.
- Legacy EDC system integration:Sponsor investments in validated data capture platforms face obsolescence pressure from API-first architectures. Migration timelines extend 18-24 months due to revalidation requirements under FDA 21 CFR Part 11.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Clinical Trial Support Services Market |
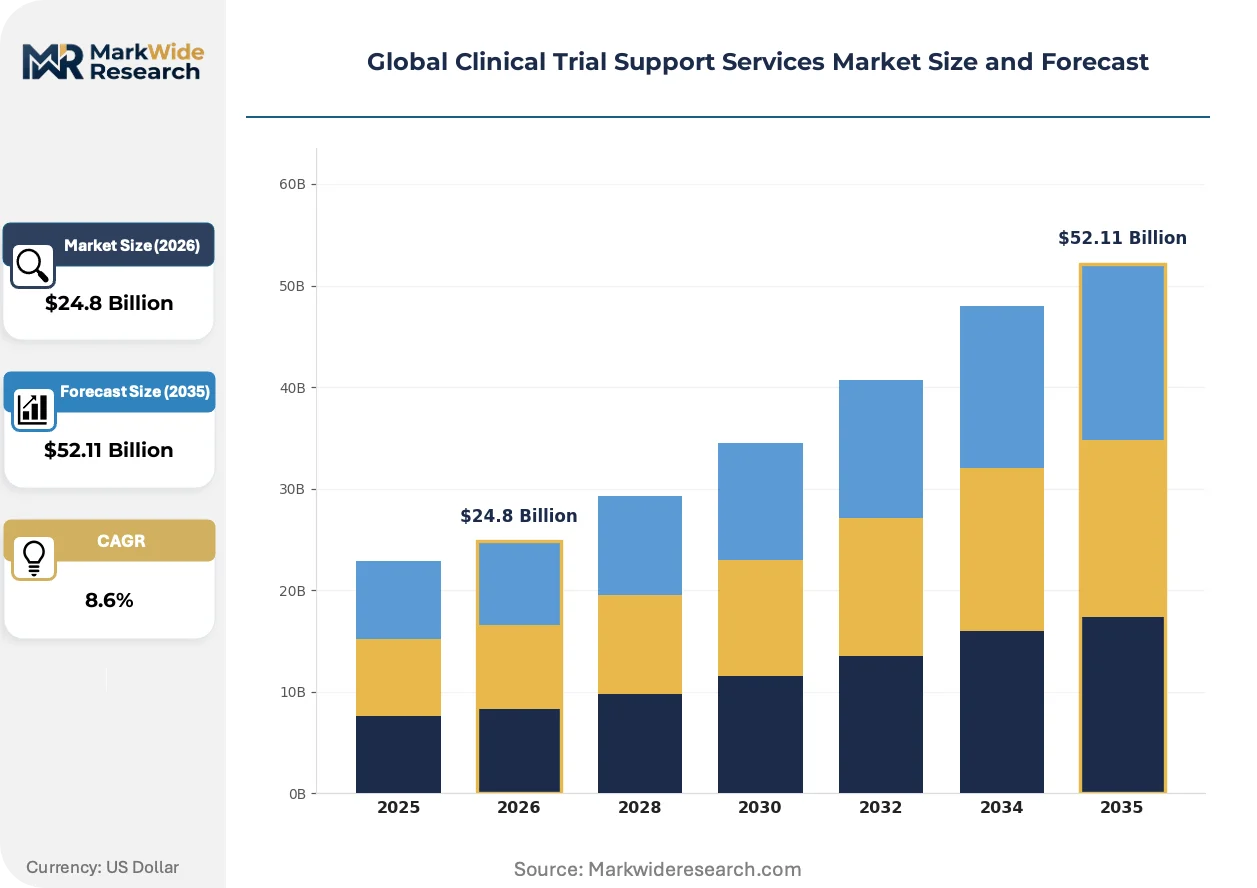
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $52.11 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Patient Recruitment, Data Management, Biostatistics, Medical Writing, Regulatory Consulting, Safety Management Application: Cardiovascular Studies, Oncology Research, Neurology Trials, Infectious Disease Assessments, Endocrinology Evaluations, Respiratory Investigations End User: Pharmaceutical Companies, Biotechnology Firms, Contract Research Organizations, Academic Research Centers, Medical Device Manufacturers, Regulatory Agencies Deployment Model: Onsite Support, Remote Monitoring, Hybrid Services, Decentralized Trials, Cloud-Based Platforms, Site Management |
| Companies Covered | IQVIA, ICON plc, Syneos Health, Parexel International Corporation, Charles River Laboratories International, Laboratory Corporation of America Holdings, Thermo Fisher Scientific, WuXi AppTec, Eurofins Scientific SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Clinical Trial Support Services Market Shifts & Advancements
Virtual trial delivery models are compressing traditional site-centric workflows while regulatory bodies on three continents issue conflicting guidance on remote consent and data provenance.
Decentralized clinical trial platforms combine telemedicine visits, direct-to-patient drug shipment, and wearable biometric capture into unified execution frameworks. Mid-cap biotech sponsors in oncology and rare disease adopt these models fastest to access dispersed patient populations. The technology is virtualizing physical site requirements and redistributing margin capture from site management fees toward platform licensing and logistics orchestration.
EMA's evolving expectations for electronic informed consent and direct data capture from patients' homes create compliance ambiguity for multinational protocols. Sponsors must reconcile EU requirements with FDA's more permissive stance on remote monitoring waivers. European trial operations teams face the steepest adaptation curve as national competent authorities interpret guidance inconsistently.
Biopharmaceutical procurement teams now unbundle full-service contracts into component sourcing for patient recruitment, data management, and safety surveillance. Large-cap sponsors negotiate directly with niche providers for biomarker analysis and central lab services. This pattern concentrates in the United States where sponsor procurement maturity and vendor density enable competitive disaggregation.
Global Clinical Trial Support Services Market Segmentation
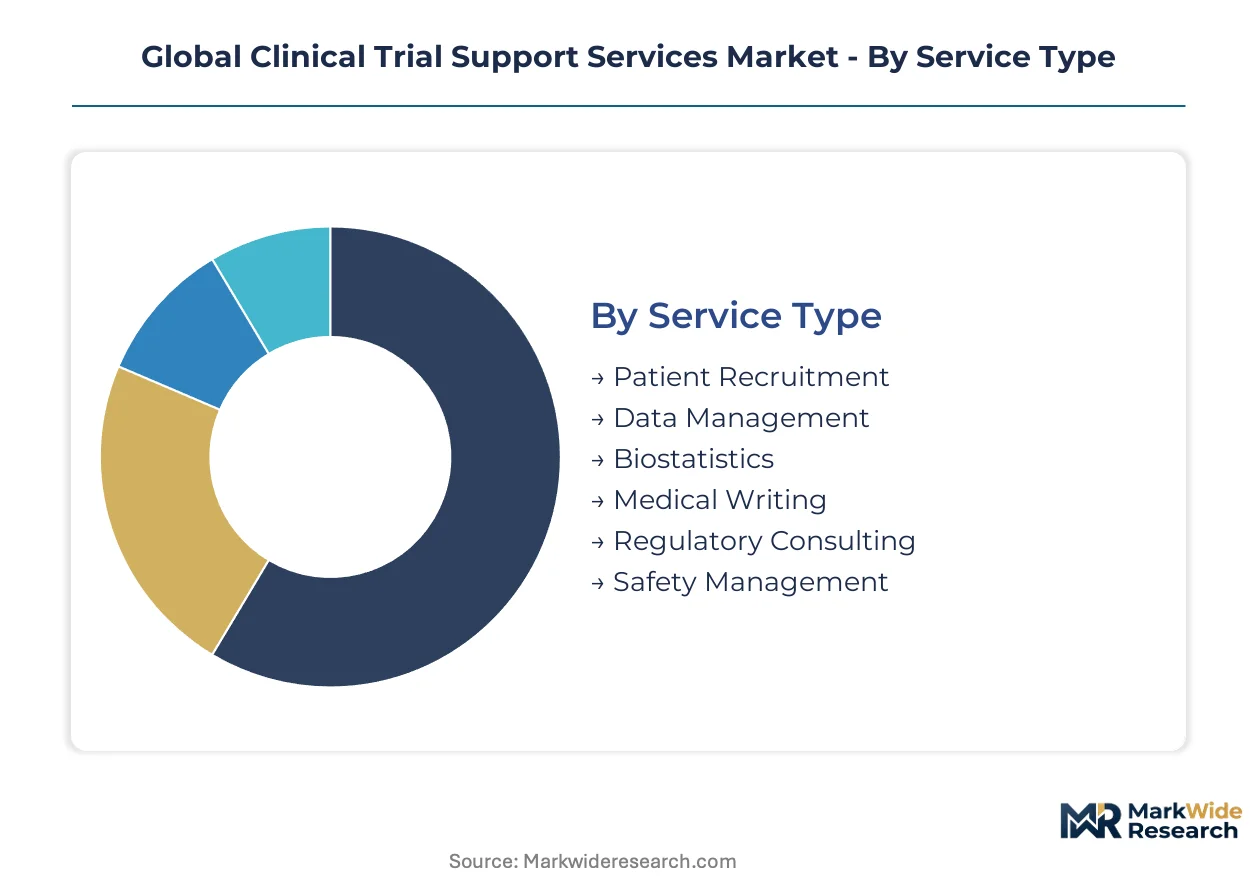
Service differentiation across the clinical trial support landscape determines pricing power and contract duration. Sponsors unbundle procurement based on therapeutic complexity and regulatory jurisdiction, creating distinct demand profiles for each segment category.
Service Type:
Cost tier stratification separates commodity data processing from high-margin advisory functions that command premium rates.
- Patient Recruitment:Specialized patient identification and enrollment acceleration services leverage site networks and real-world data matching. Sponsors in oncology and rare disease trials in the United States pay substantial premiums for guaranteed enrollment velocity where treatment-naive populations concentrate at academic medical centers.
- Regulatory Consulting:Submission strategy, FDA pre-IND meetings, and EMA scientific advice preparation require former agency personnel and established rapport with reviewers. European sponsors navigating the CTIS portal harmonization demand specialized guidance for multi-country protocol alignment.
- Data Management:Electronic data capture configuration and database lock execution.
- Biostatistics:Adaptive trial design and interim analysis planning.
- Medical Writing:Protocol and clinical study report preparation.
- Safety Management:Pharmacovigilance and adverse event reporting.
Regulatory consulting commands the established base. The steepest expansion runs through patient recruitment.
Application:
Therapeutic area concentration shapes capability requirements and site access strategies across sponsor portfolios.
- Oncology Research:Precision-medicine protocols demand biomarker-integrated adaptive designs with companion diagnostic coordination. Trials in the United States and Germany cluster at specialized academic centers with molecular profiling infrastructure and access to genetically stratified patient populations.
- Neurology Trials:Central nervous system studies require specialized rating scales, imaging protocols, and longitudinal cognitive assessment frameworks. Patient retention challenges in Alzheimer's and Parkinson's disease trials in Japan and the United States drive demand for decentralized visit models and home nursing support.
- Cardiovascular Studies:Large outcome trials with hard endpoints.
- Infectious Disease Assessments:Vaccine and antimicrobial development programs.
- Endocrinology Evaluations:Diabetes and metabolic disorder protocols.
- Respiratory Investigations:COPD and asthma clinical programs.
Cardiovascular studies anchor the established base. Oncology research follows the steepest expansion trajectory.
End User:
Customer type determines contract structure, with large pharma favoring full-service partnerships and emerging biotech seeking modular sourcing.
- Pharmaceutical Companies:Global sponsors with established procurement functions negotiate master service agreements spanning multiple therapeutic areas and geographic regions. Mid-cap biotech firms in the United States increasingly unbundle services, sourcing patient recruitment and biomarker analysis from niche specialists.
- Contract Research Organizations:Mid-tier CROs subcontract specialized functions—central lab services, imaging core labs, and regulatory consulting—to extend their full-service positioning without capital-intensive capability builds.
- Biotechnology Firms:Venture-backed developers with single-asset portfolios.
- Academic Research Centers:Investigator-initiated studies and cooperative group trials.
- Medical Device Manufacturers:PMA and 510(k) pathway support services.
- Regulatory Agencies:Post-market surveillance and registry studies.
Pharmaceutical companies command the established base. Biotechnology firms show the steepest expansion.
Deployment Model:
Technology infrastructure maturity separates legacy site-centric models from platform-enabled distributed execution.
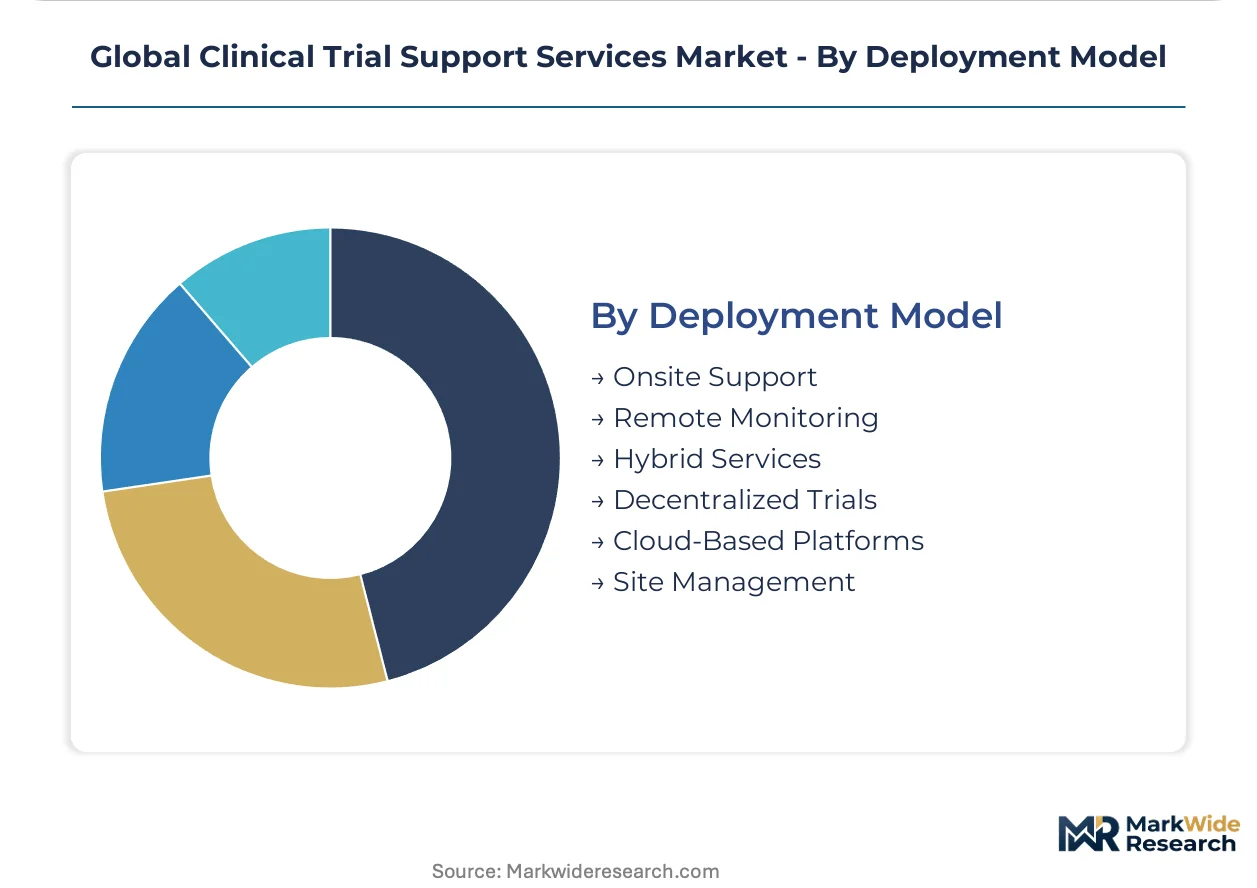
- Decentralized Trials:Telemedicine-integrated protocols with direct-to-patient drug shipment and wearable biometric capture eliminate geographic constraints on enrollment. FDA's 2023 guidance on remote monitoring enables sponsors to access dispersed rare disease populations without physical site infrastructure.
- Hybrid Services:Blended models combining traditional site visits with remote assessments balance regulatory familiarity with operational flexibility. European sponsors navigating EMA's evolving electronic consent expectations adopt hybrid structures to maintain compliance while reducing patient burden.
- Onsite Support:Traditional site monitoring and source document verification.
- Remote Monitoring:Risk-based oversight with statistical sampling approaches.
- Cloud-Based Platforms:API-first data capture and analytics infrastructure.
- Site Management:Investigator relationship and startup coordination services.
Onsite support commands the established base. Decentralized trials follow the steepest expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clinical trial sponsors deploy services differently across geographies, with the United States prioritizing decentralized infrastructure while Germany and Japan maintain site-centric execution models anchored in academic medical center density.
United States
FDA's 2023 decentralized trial guidance accelerates telemedicine-integrated protocol adoption among mid-cap biotech sponsors. The agency's risk-based monitoring waivers enable remote oversight with reduced on-site visit requirements. Greater Boston and the San Francisco Bay Area concentrate precision-medicine trial activity, with site networks competing for oncology biomarker-integrated studies.
Germany
EMA's ICH-GCP E6(R2) implementation drives demand for validated statistical sampling platforms among German sponsors. The EU Clinical Trials Regulation harmonization through the CTIS portal reduces multi-country submission timelines. Heidelberg and Munich academic medical centers anchor oncology and neurology trial concentration, with investigators controlling access to treatment-naive patient populations.
Japan
PMDA's evolving expectations for electronic data capture and direct-to-patient consent create compliance complexity for multinational protocols. Japan's aging demographic intensifies demand for Alzheimer's and Parkinson's disease trial infrastructure. Tokyo and Osaka metropolitan areas concentrate central nervous system study execution, with sponsors adopting hybrid visit models to address patient retention challenges.
China
NMPA data localization requirements prohibit cross-border transfer of patient records, forcing multinational sponsors to duplicate infrastructure or exclude China from global protocols. The regulator's streamlined trial approval timelines attract oncology and infectious disease study migration. Shanghai and Beijing biotech clusters expand early-phase capacity, though qualified personnel scarcity limits GLP laboratory throughput expansion.
Brazil
ANVISA's streamlined clinical trial approval timelines, now under 60 days, attract mid-phase oncology and infectious disease study migration. The regulator's alignment with international standards reduces protocol amendment delays. São Paulo and Rio de Janeiro concentrate site network development, with sponsors accessing untapped patient pools for rare disease trials.
Global Clinical Trial Support Services Market Competitive Landscape
Capability concentration sits with specialized providers holding therapeutic-area depth and proprietary site networks; scale advantage sits with integrated platforms offering end-to-end execution across multiple geographies. The market structures around three tiers: full-service global CROs with master service agreement relationships, mid-tier regional specialists with therapeutic focus, and niche providers delivering single-function excellence in patient recruitment or biomarker analysis. Dominant competitive moves include portfolio diversification into real-world evidence services and strategic partnerships to extend geographic coverage without capital-intensive infrastructure builds.
Within the full-service tier, IQVIA leverages its proprietary site network and real-world data assets, while ICON plc anchors its position through therapeutic-area concentration. Charles River Laboratories International occupies a specialist position in early-phase safety and pharmacology services that feed downstream into larger support contracts. These three exemplify distinct archetypes: data-integrated platform scale, therapeutic depth, and early-phase scientific specialization.
| Leading Market Players |
|---|
| IQVIA |
| ICON plc |
| Syneos Health |
| Parexel International Corporation |
| Charles River Laboratories International |
| Laboratory Corporation of America Holdings |
| Thermo Fisher Scientific |
| WuXi AppTec |
| Eurofins Scientific SE |
| Others |
Supply & Pricing Matrix
Air freight corridors connecting Frankfurt and Miami to São Paulo and Singapore transmit cost volatility directly into site activation fees and bioanalytical testing rates, concentrating margin pressure on mid-tier CROs while enabling premium capture by providers with captive laboratory networks and proprietary investigator relationships.
Pricing Analysis
Long-term master service agreements anchor pricing for pharmaceutical sponsors with multi-trial portfolios, while spot contracting dominates mid-cap biotech seeking modular patient recruitment or safety surveillance services. Price differentiation rests on therapeutic-area certification depth and FDA 21 CFR Part 11 validation status. Cost compression in data management services is intensifying because API-first EDC platforms displace legacy system maintenance revenues. Emerging biotech firms exhibit the highest price sensitivity, prioritizing enrollment guarantees over integrated service bundles.
Supply Chain Analysis
Extended payment terms from sponsor finance departments cascade through CRO vendor networks, compressing cash conversion cycles for central laboratories and site management organizations. Supply concentration sits in the United States, Germany, and India, with bioanalytical testing drawing from specialized mass spectrometry equipment, immunogenicity assay platforms, and GLP-certified personnel pools. Single-source vulnerability runs through qualified principal investigators at academic medical centers in Boston and Heidelberg. Distribution runs through direct sponsor-CRO contracting with limited intermediary presence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market is recovering from pandemic-era trial disruption as sponsor pipelines refill and FDA submission volumes normalize, with decentralized trial infrastructure investment serving as the cyclical recovery engine.
For Market Incumbents: Pre-empt niche specialist encroachment by acquiring biomarker analysis capabilities and real-world data assets before mid-cap biotech procurement teams complete vendor diversification. Lock in investigator site exclusivity through preferred site network agreements in oncology and neurology. Threat substitution from AI-enabled patient matching platforms demands counter-investment in proprietary enrollment algorithms.
For New Entrants and Emerging Players: Establish a beachhead in Latin American site management services, where ANVISA's streamlined approval timelines and untapped patient pools in oncology attract mid-phase study migration. Target infectious disease and rare disease protocols in Brazil and Mexico, where incumbent site density remains lowest. Go-to-market positioning should emphasize 60-day regulatory approval guarantees and local investigator relationship depth.
For Investors and Strategic Acquirers: Niche patient recruitment specialists with proprietary real-world data matching capabilities offer the most attractive acquisition profile for portfolio diversification. Long-term viability hinges on regulatory data integration moats rather than transactional site access. Watch FDA decentralized trial guidance expansion as the inflection signal for platform-enabled provider valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Real-World Evidence Integration | Convergence of EHR and trial data reduces Phase III failure rates through adaptive enrollment criteria. |
| Decentralized Trial Platform Buildout | FDA remote monitoring waivers enable geographic expansion without physical site infrastructure investment. |
| Therapeutic-Area Specialist Acquisition | Oncology biomarker-integrated design capabilities command premium pricing on full-service engagements. |
| Latin American Site Network Expansion | ANVISA's sub-60-day approval timelines attract mid-phase oncology and infectious disease migration. |
| GLP Laboratory Capacity Addition | Mass spectrometry and immunogenicity platform scarcity limits bioanalytical testing throughput expansion. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 21 CFR Part 11 guidance documents, EMA ICH-GCP E6(R2) implementation reports, ClinicalTrials.gov protocol registrations, and SEC 10-K filings from publicly traded CROs. Interviews with drug development executives, regulatory affairs leads, clinical operations directors, and site principal investigators informed capability assessment and procurement pattern analysis. Bottom-up service-type demand modeling triangulates against top-down sponsor R&D expenditure allocation.
Forecast inputs include therapeutic-area trial initiation rates, regulatory submission volumes, and decentralized trial adoption curves across the analysis window. Segmentation dimensions encompass service type, therapeutic application, end-user archetype, and deployment model complexity. CAGRs derive from sponsor outsourcing propensity trends and site network capacity expansion trajectories. Industry-specific inputs capture biomarker-integrated protocol proliferation and risk-based monitoring platform penetration.
Stress conditions across FDA guidance evolution, EMA CTIS portal harmonization timelines, and GLP laboratory capacity constraints were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory trajectory and sponsor procurement behavior. Macroeconomic contraction, abrupt regulatory reversal, or disruptive clinical trial technology emergence would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Research
AI-Based Clinical Trial Solutions for Patient Matching Market
Clinical Research
North America Contract Research Organization Market
Clinical Research
Global Clinical Trial Supply Management Market
Clinical Research
Clinical Trial Biorepository and Archiving Solutions Market
Clinical Research
Clinical Trial Patient Recruitment Services Market
Clinical Research
Atopic Dermatitis Clinical Trials Market
Clinical Research
Esource and Clinical Trials Market
Clinical Research
Clinical Trial Investigative Site Network Market
Clinical Research
US Clinical Trials Market
Clinical Research
HIV Clinical Trials Market
Clinical Research
US Virtual Clinical Trials Market
Clinical Research
Ecoa, Esource & Clinical Trials Market
Clinical Research
Pharmacovigilance Outsourcing Market
Clinical Research
Preclinical CRO Market
Clinical Research
Global Clinical Trial Management Systems Market
Clinical Research
Real World Evidence Linkage Services Market