
 Clinical Laboratory Services Market | 2026-2036
Clinical Laboratory Services Market Size, Share, and Industry Trends Forecast 2026-2036
Clinical Laboratory Services Market Analysis
North American reference laboratory networks is consolidating as independent hospital labs seek scale economies for esoteric testing. Laboratory Corporation of America Holdings anchors its position through national specimen logistics infrastructure. Quest Diagnostics Incorporated differentiates via integrated health information systems linking payers, physicians, and patients. Eurofins Scientific extends its footprint across specialized toxicology and genomic service lines.
Clinical laboratory services encompass the analysis of biological specimens using standardized analytical methods, automated analyzers, and quality-controlled protocols to generate diagnostic data for patient care decisions. These services process blood, tissue, urine, and molecular samples through techniques such as mass spectrometry, polymerase chain reaction, and flow cytometry to detect disease markers, therapeutic drug levels, and genetic variations. Molecular diagnostics within the technology dimension commands premium pricing as oncology profiling and infectious disease surveillance expand, while point-of-care testing reshapes delivery economics by shifting volume toward decentralized settings. Among end users, diagnostic laboratories capture the largest revenue share through centralized high-throughput operations, though academic clinics represent a concentrated growth vector for precision medicine protocols.
FDA oversight of Laboratory Developed Tests and Clinical Laboratory Improvement Amendments compliance shape analytical validity requirements and market access conditions for service providers. CAP accreditation and ISO 15189 standards further define quality benchmarks that influence payer contracting and institutional procurement decisions. Stakeholders must monitor evolving CMS reimbursement rules for multianalyte assays and algorithmic analyses to align service portfolios with sustainable revenue structures.
Market Dynamics
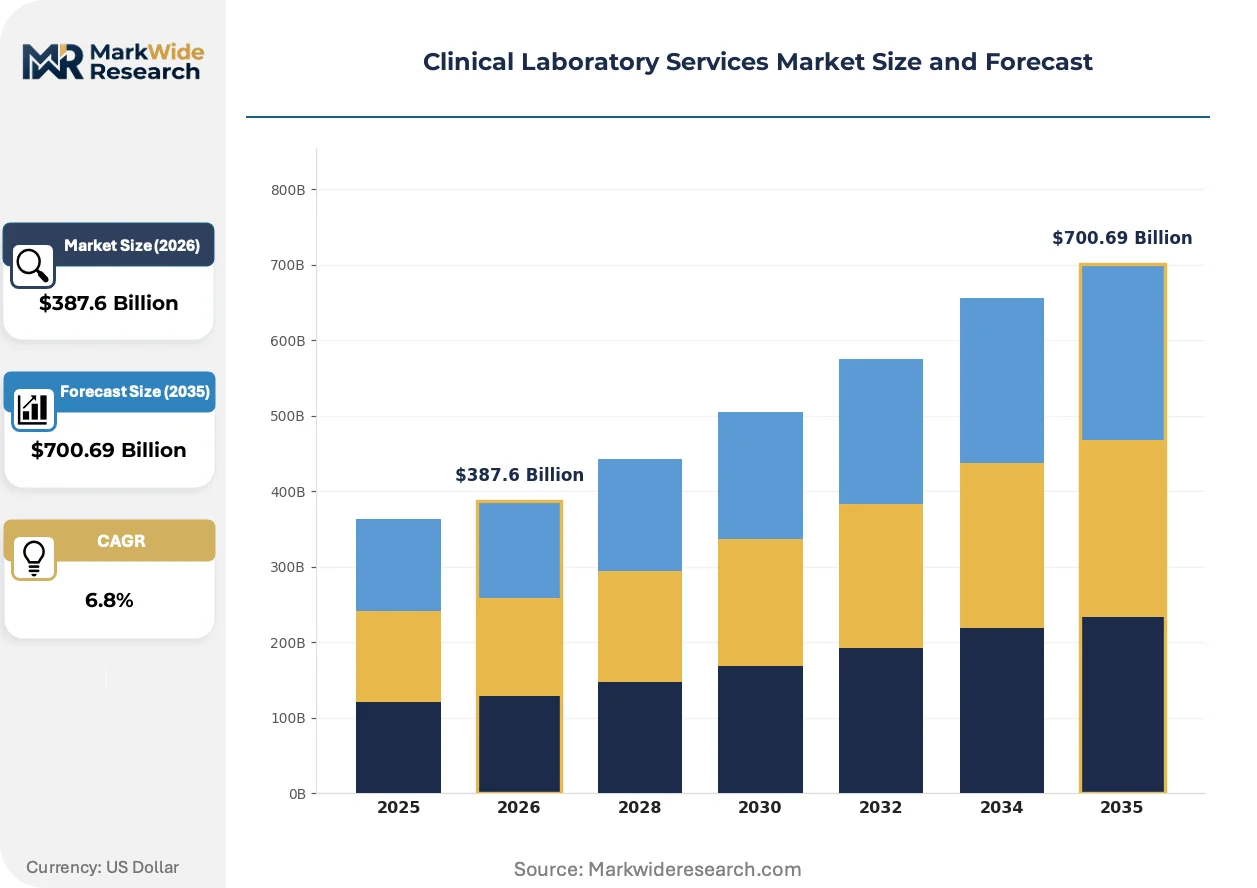
The FDA's Laboratory Developed Tests final rule is compressing compliance timelines for molecular diagnostics while CMS reimbursement recalibration redistributes revenue toward algorithmic assay categories.
Growth Catalysts
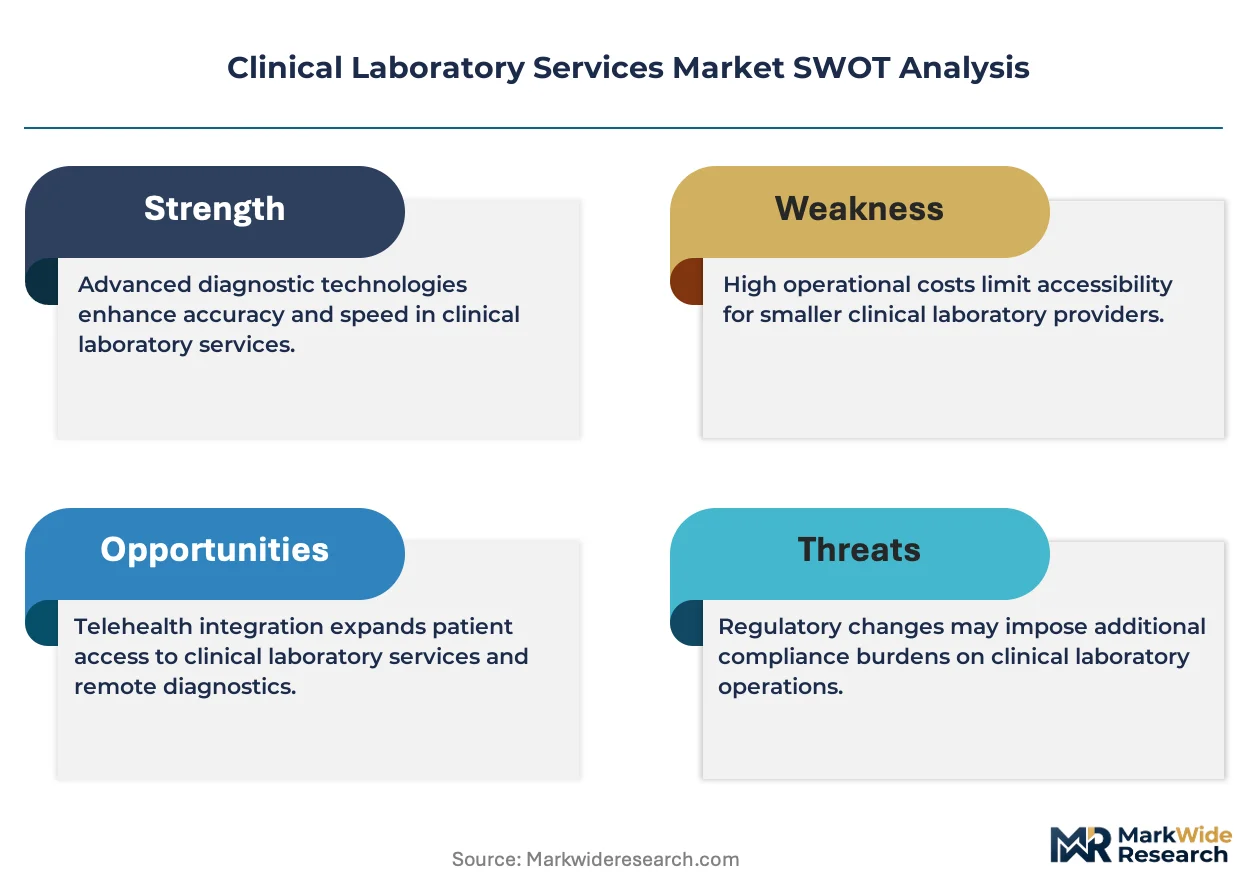
- Oncology profiling expansion:Solid tumor and liquid biopsy protocols are pulling volume into esoteric testing menus. Academic medical centers are scaling precision medicine infrastructure to capture companion diagnostic revenue.
- CLIA complexity:The Clinical Laboratory Improvement Amendments high-complexity certification requirements are creating barriers that protect incumbent reference laboratories from point-of-care entrants.
- Hospital outsourcing:Independent hospital laboratories are consolidating send-out testing partnerships with national reference networks to access specialized mass spectrometry and next-generation sequencing capacity.
Market Restraints
- Reagent supply concentration:Polymerase chain reaction consumables and sequencing flow cells depend on a limited supplier base concentrated in East Asian manufacturing clusters.
- CMS reimbursement compression:The Protecting Access to Medicare Act fee schedule reductions are constraining margins for routine chemistry and hematology panels.
- Technical substitution:Point-of-care immunoassay platforms are capturing infectious disease testing volume that previously flowed to centralized laboratories.
Strategic Opportunities
- Rural health integration:Federally qualified health centers in the United States present underpenetrated specimen collection infrastructure for hub-and-spoke logistics models.
- Toxicology-menu expansion:Medication-assisted therapy compliance monitoring and pain management drug testing are creating dedicated service line opportunities.
- AI-assisted pathology:Convergence of digital slide imaging and machine learning classification is enabling primary diagnosis outsourcing for dermatopathology and hematopathology subspecialties.
Industry Challenges
- Histotechnologist scarcity:Tissue processing and immunohistochemistry staining operations face recruitment gaps for specialized laboratory technologists.
- LIMS integration friction:Laboratory information management system upgrades for interoperability with electronic health records require multi-year capital deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clinical Laboratory Services Market |
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $700.69 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Clinical Chemistry, Hematology, Microbiology, Immunology Technology: Molecular Diagnostics, Circular RNA, Point-of-Care Testing, Rapid Testing End User: Hospitals, Diagnostic Laboratories, Research Institutes, Academic Clinics Test Type: Genetic Testing, Biochemistry Analysis, Infectious Disease Testing, Toxicology Screening |
| Companies Covered | Danaher Corporation, NeoGenomics Laboratories, Inc., Laboratory Corporation of America Holdings, Sonic Healthcare, Illumina, Inc., Quest Diagnostics Incorporated, Eurofins Scientific, UNILABS, Thermo Fisher Scientific Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clinical Laboratory Services Market Emerging Trajectories
Automation architectures and regulatory digitization are compressing turnaround times while reconfiguring workforce deployment across testing tiers.
Mass spectrometry-based steroid profiling and therapeutic drug monitoring is electrifying endocrinology and transplant service lines. Specialty reference laboratories are adopting high-resolution accurate-mass platforms to differentiate from automated immunoassay competitors. This technology is electrifying reimbursement capture for esoteric test categories that require chromatographic separation.
Europe's In Vitro Diagnostic Medical Devices Regulation is extending conformity assessment requirements to laboratory-developed tests previously exempt under directive frameworks. Notified body capacity constraints are delaying market entry for novel assay developers. Multinational reference laboratories with established quality management systems are accelerating EU IVDR certification to capture competitor displacement.
Health system procurement departments are consolidating laboratory contracts through sole-source agreements with integrated delivery networks. Independent laboratories and physician office labs are losing access to managed care panels as payers narrow preferred provider networks. This concentration is most visible in United States metropolitan markets where health system employment of physicians exceeds sixty percent.
Clinical Laboratory Services Market Segmentation
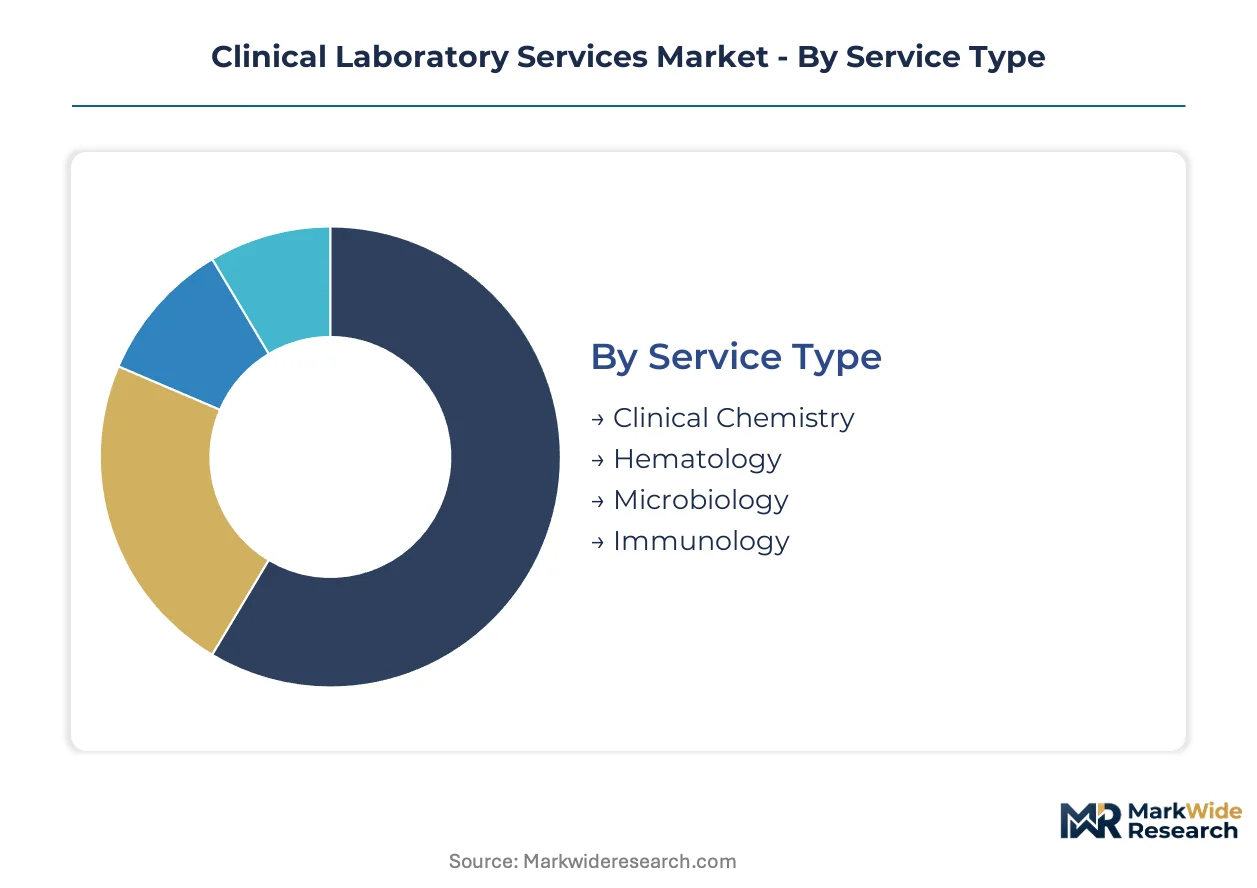
Service configuration in clinical laboratories determines capital intensity, reimbursement pathways, and regulatory burden. Segment boundaries increasingly blur as molecular platforms absorb chemistry workloads and point-of-care devices encroach on centralized testing.
Service Type:
CLIA high-complexity certification requirements vary sharply across these segments, with microbiology and immunology demanding specialized personnel qualifications that constrain market entry.
- Clinical Chemistry:Automated analyzers process electrolyte, enzyme, and metabolite panels through spectrophotometric and ion-selective electrode methods. Hospital laboratories in the United States retain this volume in-house to protect margin on routine panels despite reference laboratory pricing pressure.
- Hematology:Flow cytometry and automated cell counting generate complete blood count differentials and coagulation profiles. Academic medical centers concentrate demand for specialized leukemia immunophenotyping that exceeds standard hospital laboratory capabilities.
- Microbiology:Culture-based identification and antimicrobial susceptibility testing.
- Immunology:Autoantibody detection and allergen-specific IgE quantification.
Leading the category by volume: Clinical Chemistry. Growing fastest: Immunology.
Technology:
Capital deployment and reagent economics separate premium-tier molecular platforms from decentralized rapid testing alternatives.
- Molecular Diagnostics:Polymerase chain reaction, nucleic acid amplification, and next-generation sequencing detect genetic mutations and pathogen signatures. Oncology profiling and infectious disease surveillance in the United States drive premium pricing as FDA premarket authorization requirements filter out lower-complexity competitors.
- Point-of-Care Testing:Handheld immunoassay and biosensor devices deliver results at the collection site. Rural health clinics and emergency departments are absorbing glucose, cardiac marker, and infectious disease panels that previously flowed to centralized laboratories.
- Circular RNA:Emerging biomarker class for non-invasive disease monitoring.
- Rapid Testing:Lateral flow and immunochromatographic strip assays.
Revenue concentration: Molecular Diagnostics. Steepest expansion trajectory: Point-of-Care Testing.
End User:
Procurement scale and integration complexity fragment the customer base from high-volume hospital networks to specialized research operations.
- Diagnostic Laboratories:Centralized high-throughput facilities process specimens from multiple collection points through automated track systems. National reference networks in the United States capture economies of scale in esoteric testing that independent hospital laboratories cannot replicate.
- Hospitals:Inpatient and emergency department testing demands rapid turnaround. Health system consolidation is narrowing preferred vendor panels and squeezing independent laboratory access to managed care contracts.
- Research Institutes:Exploratory biomarker studies and clinical trial support services.
- Academic Clinics:Precision medicine protocols and companion diagnostic development.
Dominant revenue share: Diagnostic Laboratories. Gaining share fastest: Academic Clinics.
Test Type:
Reimbursement calibration by CMS and private payers stratifies profitability across routine panels versus specialized assays.
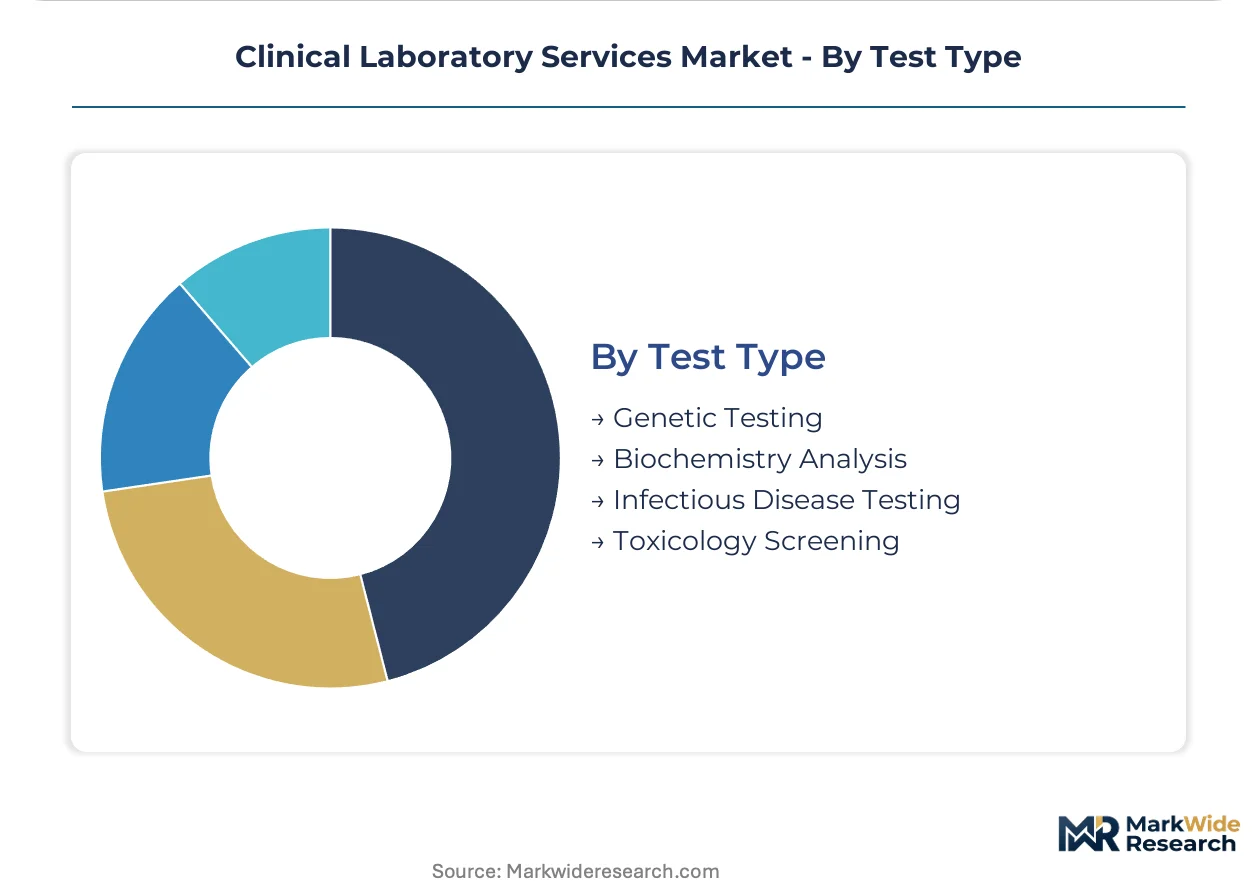
- Genetic Testing:Germline and somatic variant analysis guides hereditary risk assessment and therapeutic selection. Oncology practices in the United States are expanding next-generation sequencing panels as FDA-approved companion diagnostics unlock targeted therapy reimbursement.
- Toxicology Screening:Mass spectrometry and immunoassay detection of drugs of abuse and therapeutic drug levels. Pain management clinics and medication-assisted therapy programs are driving volume for compliance monitoring that requires chain-of-custody protocols.
- Biochemistry Analysis:Routine metabolic and organ function panels.
- Infectious Disease Testing:Pathogen identification and antimicrobial resistance profiling.
Highest volume: Biochemistry Analysis. Premium pricing capture: Genetic Testing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specimen collection infrastructure and reference laboratory networks anchor geographic demand patterns. Reimbursement calibration and regulatory digitization separate mature diagnostics corridors from emerging consolidation opportunities.
United States
Hospital outsourcing and precision medicine expansion concentrate demand for esoteric testing. FDA Laboratory Developed Tests rule compresses compliance timelines for molecular diagnostics developers. The Boston-Cambridge corridor anchors companion diagnostic development as academic medical centers scale next-generation sequencing infrastructure.
Germany
Industrial laboratory automation and statutory health insurance integration sustain centralized testing volume. EU In Vitro Diagnostic Medical Devices Regulation extends conformity assessment to previously exempt laboratory-developed tests. The Rhine-Ruhr metropolitan region concentrates reference laboratory capacity as health system procurement consolidates preferred vendor panels.
China
Hospital laboratory privatization and independent diagnostic laboratory licensing unlock third-party testing penetration. National Medical Products Administration streamlines in vitro diagnostic registration pathways for domestic manufacturers. The Yangtze River Delta anchors high-throughput molecular diagnostics infrastructure as municipal health bureaus consolidate regional testing networks.
United Kingdom
NHS pathology network consolidation and hub-and-spoke logistics reconfigure service delivery geography. Medicines and Healthcare products Regulatory Agency aligns post-Brexit device regulation with retained EU MDR requirements. The Greater Manchester pathology partnership exemplifies metropolitan-scale laboratory integration as integrated care systems rationalize redundant capacity.
Japan
Aging demographics and cancer screening program expansion sustain routine testing volume. Pharmaceuticals and Medical Devices Agency accelerates approval pathways for companion diagnostics linked to oncology therapies. The Keihin industrial corridor concentrates automated analyzer manufacturing as domestic suppliers defend market position against Korean and Chinese entrants.
Clinical Laboratory Services Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized toxicology and genomic service lines to bypass scale disadvantages. National reference networks consolidate through sole-source agreements with integrated delivery networks, compressing independent laboratory access to managed care contracts. Three archetypes dominate: diversified life science conglomerates with diagnostics divisions, pure-play reference laboratory networks, and precision medicine specialists anchored to academic medical center partnerships. Competitive positioning hardens around specimen logistics infrastructure and health information system integration rather than test menu breadth alone.
Among diversified instrumentation and consumables suppliers, Danaher Corporation and Thermo Fisher Scientific Inc. anchor the analytical platform tier through mass spectrometry and sequencing system portfolios. Laboratory Corporation of America Holdings and Quest Diagnostics Incorporated exemplify the national reference laboratory archetype, occupying positions defined by hub-and-spoke logistics networks and payer contracting scale. Sonic Healthcare represents the international consolidation model through multi-country laboratory platform integration.
| Leading Market Players |
|---|
| Danaher Corporation |
| NeoGenomics Laboratories, Inc. |
| Laboratory Corporation of America Holdings |
| Sonic Healthcare |
| Illumina, Inc. |
| Quest Diagnostics Incorporated |
| Eurofins Scientific |
| UNILABS |
| Thermo Fisher Scientific Inc. |
| Others |
Supply Flow & Price Mechanics
Reagent consumables—polymerase chain reaction primers, sequencing flow cells, and mass spectrometry solvents—flow from East Asian manufacturing clusters through distributor tiers to United States reference laboratories, with freight and cold-chain logistics layering cost premiums onto esoteric test menus while commodity chemistry panels face reimbursement compression.
Pricing Analysis
Warranty and service bundling separates premium-tier molecular diagnostics from unbundled point-of-care alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects CLIA certification grade and specimen logistics integration. Pricing pressure stems from CMS fee schedule reductions for routine panels. Hospital laboratories exhibit highest price sensitivity due to fixed reimbursement rates, while academic medical centers tolerate premium pricing for companion diagnostic development.
Supply Chain Analysis
Freight costs for temperature-controlled specimen transport and hazardous reagent handling concentrate margin pressure on rural collection networks. Manufacturing of polymerase chain reaction consumables and sequencing instrumentation centers on China, South Korea, and Japan. Raw material dependencies include optical polymers, semiconductor-grade silicon, and diagnostic-grade enzymes. Single-source vulnerability for flow cell production creates supply chain risk. Distribution runs through national reference laboratory hub-and-spoke networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation defines this market as CMS reimbursement compression and FDA compliance burdens force independent hospital laboratories toward acquisition or partnership with national reference networks.
For Market Incumbents: Anchor market position through captive specimen logistics infrastructure and exclusive payer contracting with integrated delivery networks. Acquire specialized toxicology or genomic laboratories to fill service line gaps. Defend against point-of-care substitution by embedding laboratory information systems within electronic health record workflows.
For New Entrants and Emerging Players: The gap between premium molecular diagnostics pricing and economy-tier routine panel rates opens white-space opportunities. Target rural health center specimen collection partnerships as the most penetrable entry vector. Pursue AI-assisted pathology subspecialties—dermatopathology and hematopathology—where histotechnologist scarcity constrains incumbent capacity. Lead with hub-and-spoke logistics models rather than capital-intensive analyzer deployment.
For Investors and Strategic Acquirers: EU IVDR certification delays for laboratory-developed tests are the leading indicator that notified body capacity constraints will displace smaller European competitors, creating acquisition targets. Five-to-ten-year viability favors reference laboratories with established quality management systems and multi-country footprints. Monitor FDA premarket authorization timelines for molecular diagnostics as the signal for consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| CLIA High-Complexity Certification Investment | FDA Laboratory Developed Tests rule elevates analytical validity requirements, filtering lower-complexity competitors from molecular diagnostics. |
| Specimen Logistics Infrastructure Expansion | Hub-and-spoke collection networks capture rural health center volume that national reference laboratories currently access through hospital outsourcing agreements. |
| LIMS-EHR Integration Development | Interoperability investments reduce turnaround time friction and protect incumbent laboratory access to health system preferred vendor panels. |
| EU IVDR Conformity Assessment Acceleration | Notified body certification delays displace smaller competitors, opening market share capture opportunities for established quality management systems. |
| AI-Assisted Pathology Platform Deployment | Digital slide imaging and machine learning classification address histotechnologist scarcity while enabling primary diagnosis outsourcing revenue streams. |
Methodological Framework
Document review covered FDA 510(k) filings, CMS Medicare reimbursement databases, and EU IVDR notified body registers, complemented by interviews with laboratory operations directors, health system procurement executives, CLIA compliance officers, and molecular diagnostics platform engineers. Secondary validation drew from hospital procurement databases, GPO contracts, and CAP accreditation records. Bottom-up service line volume estimates triangulated against top-down national healthcare expenditure allocations.
Market size outputs reflect segment-level modeling across service type, technology platform, end-user category, and test complexity tier throughout the forecast period. CAGRs were derived from historical volume trajectories adjusted for regulatory event impacts and reimbursement policy shifts. Forecast inputs incorporated FDA premarket authorization timelines, CMS fee schedule revision schedules, and health system consolidation velocity indices.
Underlying measurement precision varies by segment; clinical chemistry and hematology carry tighter precision than emerging circular RNA biomarker categories. Forecasts reflect assumptions about regulatory implementation pacing and payer contracting stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Services
Sera and Reagents Market
Laboratory Services
Global Medical Laboratories Market
Laboratory Services
Pathology Laboratories Market
Laboratory Services
Hematocrit Tests Market
Laboratory Services
Assessment Services Market
Laboratory Services
Global Office Based Lab Market
Laboratory Services
Nigeria Clinical Laboratory Services Market
Laboratory Services
Latin America Clinical Laboratory Services Market
Laboratory Services
Enterprise Laboratory Informatics Market
Laboratory Services
Veterinary Reference Laboratories Market
Laboratory Services
US Clinical Laboratory Services Market
Laboratory Services
Frozen Tissues Samples Market
Laboratory Services
Global Cell Viability Assays Market
Laboratory Services
Serum Separation Gel Market
Laboratory Services
Lab Mailers Market
Laboratory Services
Clinical Laboratory Tests Market