
 Autosampler Vials Market | 2026-2036
Autosampler Vials Market Size, Share, and Industry Trends Forecast 2026-2036
Autosampler Vials Market Outlook
Multi-source procurement among analytical consumables distributors is recalibrating how end-users secure vial supply chains. Agilent Technologies leverages its captive chromatography platform to bundle vial sales with instrument service contracts. Waters Corporation anchors its position through certified-vial programs that guarantee compatibility with its ACQUITY and Alliance systems. Thermo Fisher Scientific extends its reach via direct e-commerce channels that bypass traditional laboratory distributors.
Autosampler vials are precision-manufactured cylindrical containers, typically fabricated from borosilicate glass or inert polymers such as polypropylene, engineered to exacting dimensional tolerances of ±0.1 mm to ensure robotic arm compatibility in high-throughput chromatography systems. Their primary purpose is to contain liquid samples without adsorption, leaching, or volatilization during automated injection cycles in gas and liquid chromatography workflows. Clear glass vials dominate routine UV-Vis detection applications where optical transparency matters, while amber glass variants command premium positioning in light-sensitive pharmaceutical stability studies. Plastic vials are gaining share in ion chromatography and certain biological assays where metal ion contamination from glass must be eliminated.
FDA container closure integrity guidelines and USP Chapter 1661 on plastic packaging systems directly shape vial material selection and validation protocols for drug developers. EPA Method 8260 and related environmental testing standards mandate specific vial inertness levels for volatile organic compound analysis, creating compliance-driven replacement cycles. ISO 15378 certification requirements for primary packaging materials further filter supplier qualification in pharmaceutical quality control laboratories. Stakeholders must monitor evolving USP and EPA method revisions alongside state-level environmental enforcement intensity to anticipate demand shifts across material grades and closure formats.
Market Dynamics
Pharmaceutical quality control laboratories are consolidating chromatography workflows onto unified vendor platforms, forcing vial suppliers to certify compatibility across instrument ecosystems or risk exclusion from bundled procurement contracts. This platform-lock dynamic is reshaping supplier qualification criteria and margin structures.
Growth Catalysts
- FDA container closure integrity guidance:Updated sterility requirements for parenteral drug products mandate enhanced vial validation protocols, driving replacement demand for certified glass and polymer formats in US pharmaceutical manufacturing.
- High-throughput bioanalytical screening:Contract research organizations are scaling automated liquid chromatography-mass spectrometry workflows for pharmacokinetic studies, consuming precision-vial volumes at accelerated rates.
- Borosilicate glass supply concentration in Germany and China:Specialized glass manufacturers in these geographies are expanding pharmaceutical-grade production capacity to serve chromatography consumables demand.
Market Restraints
- Raw material cost volatility:Boron oxide and alumina prices fluctuate with energy markets, compressing margins for glass vial manufacturers unable to pass through input cost swings.
- Single-source instrument dependency:End-users locked into Agilent, Waters, or Thermo Fisher chromatography platforms face limited vial supplier choice, reducing price negotiation leverage.
- Polymer vial technical limitations:Polypropylene formats exhibit solvent compatibility constraints with aggressive organic mobile phases, restricting substitution in certain reversed-phase applications.
Strategic Opportunities
- India pharmaceutical manufacturing expansion:CDSCO's tightening quality standards for export-oriented drug production create demand for ISO 15378-certified vials in Mumbai and Hyderabad manufacturing clusters.
- Pre-slit silicone septum technology:Automated piercing compatibility is expanding into cell therapy and gene therapy quality control workflows where sample integrity is paramount.
- Direct e-commerce laboratory supply channels:Thermo Fisher's platform bypasses traditional distributors, offering vial suppliers alternative route-to-market with faster inventory turns.
Industry Challenges
- Dimensional tolerance certification backlog:ISO 15378 and USP Chapter 1661 validation timelines extend supplier qualification periods, delaying new vial format commercialization.
- Cross-platform robotic arm calibration:Vial geometry variations across Agilent, Waters, and Shimadzu autosamplers force laboratories to maintain multiple SKU inventories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autosampler Vials Market |
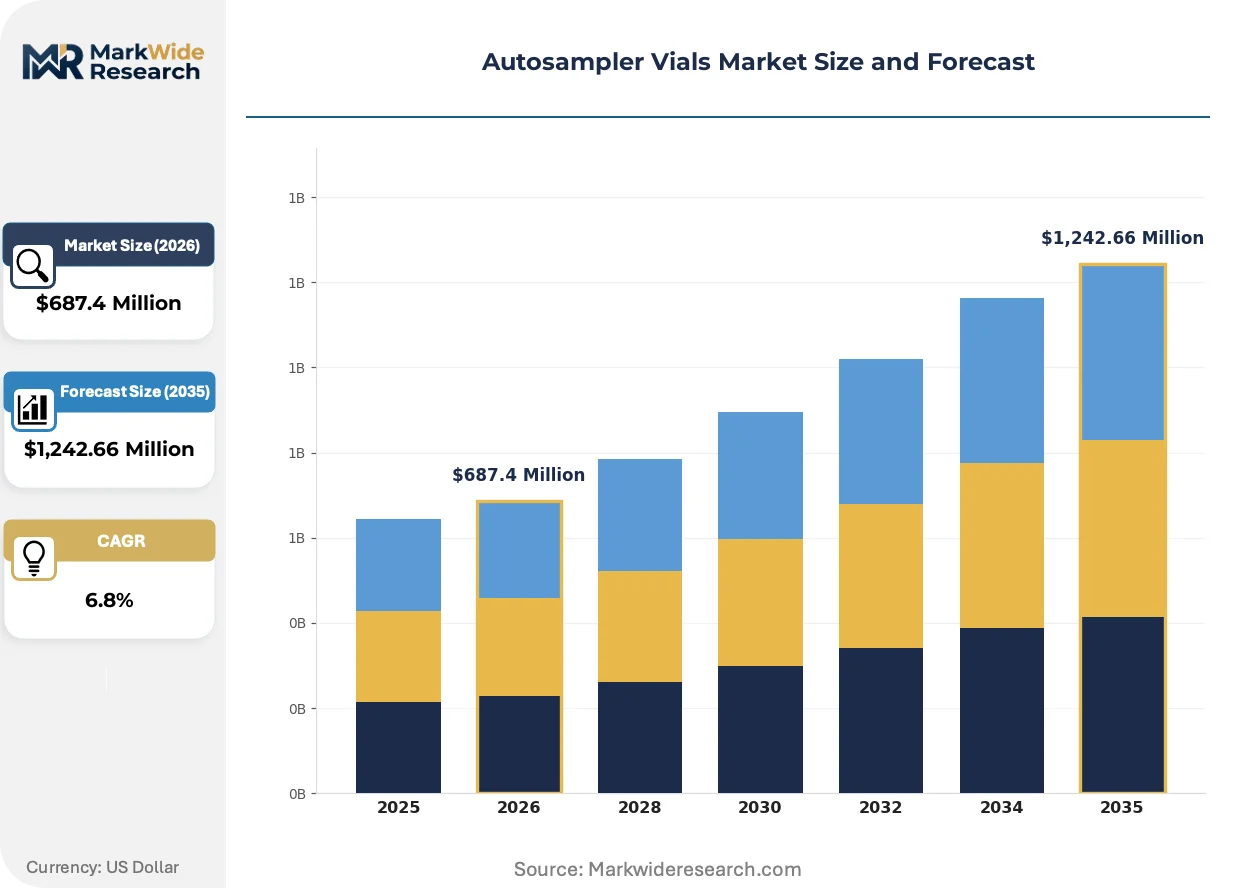
| Market Size in 2026 | $687.4 Million |
| Market Size in 2035 | $1,242.66 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clear Glass, Amber Glass, Plastic, Customized Application: Pharmaceuticals, Environmental Testing, Food Safety, Chemical Analysis End User: Laboratories, Research Institutions, Quality Control, Manufacturing Units Closure Type: Screw Cap, Crimp Cap, Snap Cap, Vial Seal |
| Companies Covered | Agilent Technologies, Waters Corporation, Thermo Fisher Scientific, Shimadzu Corporation, Merck KGaA, PerkinElmer, Restek Corporation, Gilson, Chemglass, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autosampler Vials Market Strategic Shifts
Material science advances and regulatory harmonization efforts are converging to redefine vial performance specifications. Suppliers are racing to develop formats that satisfy multiple jurisdiction requirements simultaneously.
Surface-deactivated borosilicate glass is expanding into biopharmaceutical applications where protein adsorption must be minimized. Monoclonal antibody developers in Boston and Basel are adopting silanized vials for stability studies, compressing the timeline for sample integrity validation. This technology is expanding into gene therapy vector analysis where trace-level recovery demands are most stringent.
EMA's updated guidance on extractables and leachables for plastic primary packaging is tightening polymer vial qualification thresholds. Drug developers must now submit comprehensive migration studies for polypropylene formats used in parenteral applications. European pharmaceutical quality control laboratories are responding by dual-sourcing glass and polymer vials to mitigate regulatory compliance risk.
Laboratory procurement teams are consolidating consumables purchasing through group purchasing organizations and integrated supply contracts. Traditional distributor relationships are yielding to direct manufacturer partnerships with price transparency and volume commitment structures. This behavioral shift is most visible in United States academic medical centers and national reference laboratories where procurement centralization has advanced furthest.
Autosampler Vials Market Segmentation
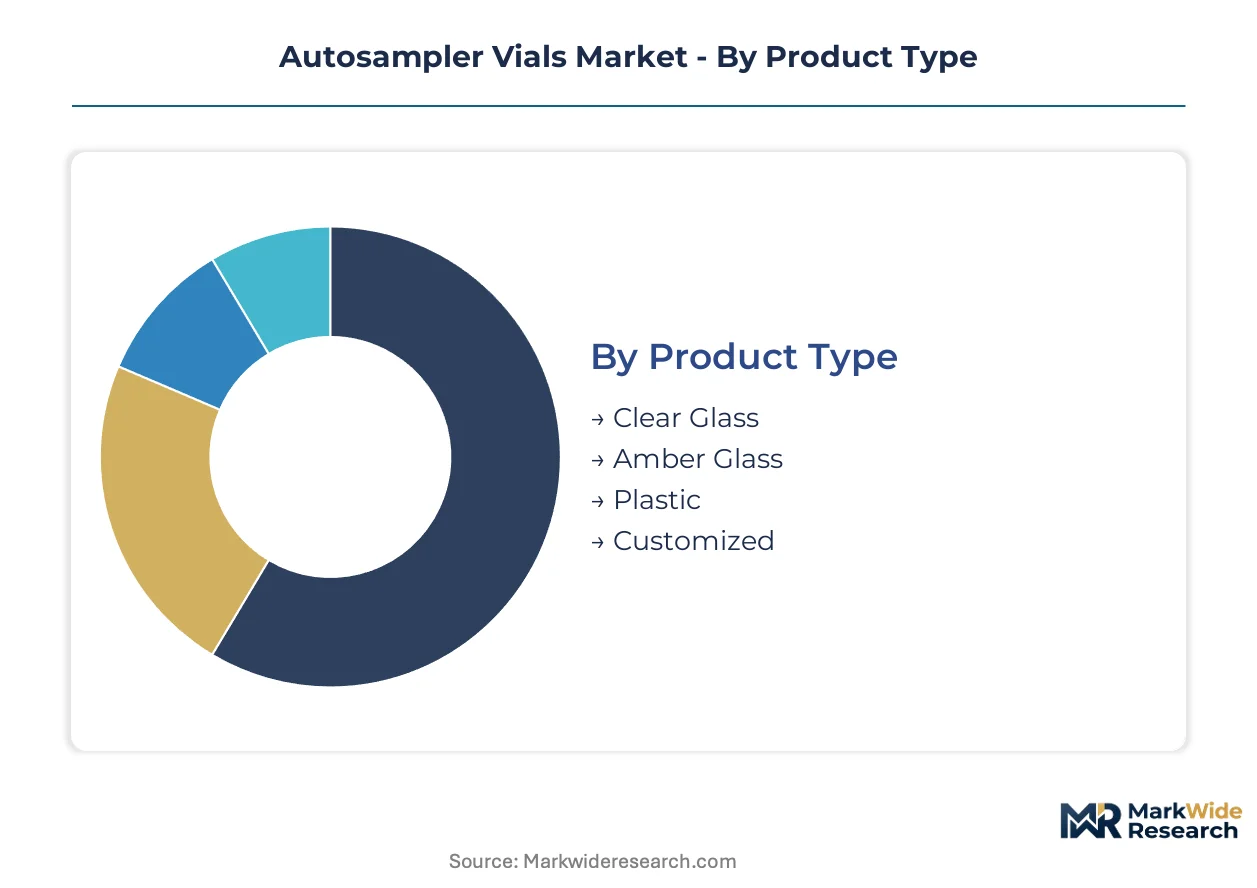
Autosampler vial selection hinges on compatibility matrices spanning instrument platforms, analyte chemistry, and regulatory validation requirements. Procurement teams balance unit cost against batch certification overhead when optimizing consumables budgets across high-throughput workflows.
Product Type:
Volume deployment favors basic optical grades, while premium-certified formats command validation-intensive pharmaceutical segments.
- Clear Glass:Borosilicate construction delivers UV-Vis transparency for routine HPLC quantification. Pharmaceutical QC laboratories in the United States consume certified lots for dissolution testing and potency assays, driven by USP Chapter 621 chromatography requirements.
- Amber Glass:Iron-doped borosilicate blocks sub-500nm wavelengths to protect light-sensitive analytes. Stability study groups at Boston and Basel biopharma clusters specify amber formats for forced degradation protocols, compelled by ICH Q1B photostability guidelines.
- Plastic:Polypropylene vials eliminate metal ion leaching in ion chromatography and certain biological matrices.
- Customized:Silanized or pre-slit septum configurations address specialized recovery requirements in cell therapy analytical development.
Mature deployment sits with Clear Glass. Newer deployment is concentrated in Customized surface-deactivated formats.
Application:
Regulatory enforcement intensity varies sharply across testing domains, reshaping vial specification tiers.
- Pharmaceuticals:Container closure integrity validation under FDA guidance demands documented dimensional tolerances and extractables profiles. Parenteral drug manufacturers in New Jersey and North Carolina maintain qualified supplier lists with ISO 15378 certification as table stakes for vial procurement.
- Environmental Testing:EPA Method 8260 and related VOC analysis protocols specify vial inertness thresholds to prevent analyte adsorption or contamination. Commercial environmental laboratories in California and Texas cycle through high volumes of certified-clean vials for groundwater and soil gas monitoring contracts.
- Food Safety:Pesticide residue and mycotoxin screening programs drive consumption in government and contract testing facilities.
- Chemical Analysis:Industrial QC and R&D applications span petrochemical, polymer, and specialty chemical sectors with variable certification requirements.
Pharmaceuticals anchors margin concentration. Environmental Testing delivers steepest volume expansion trajectory as enforcement tightens.
End User:
Procurement centralization patterns diverge between institutional and industrial settings.
- Laboratories:Academic, government, and hospital-based facilities consolidate purchasing through group contracting organizations. National reference laboratories in the United States negotiate multi-year supply agreements with direct manufacturer pricing transparency.
- Research Institutions:Exploratory chromatography workflows tolerate broader supplier flexibility than regulated manufacturing environments.
- Quality Control:Pharmaceutical and chemical manufacturing QC units enforce strict change-control protocols for vial sourcing, extending supplier qualification timelines.
- Manufacturing Units:In-process testing and release laboratories at production sites prioritize supply security and lot traceability.
Quality Control demands the most stringent certification overhead. Research Institutions permit greatest sourcing flexibility.
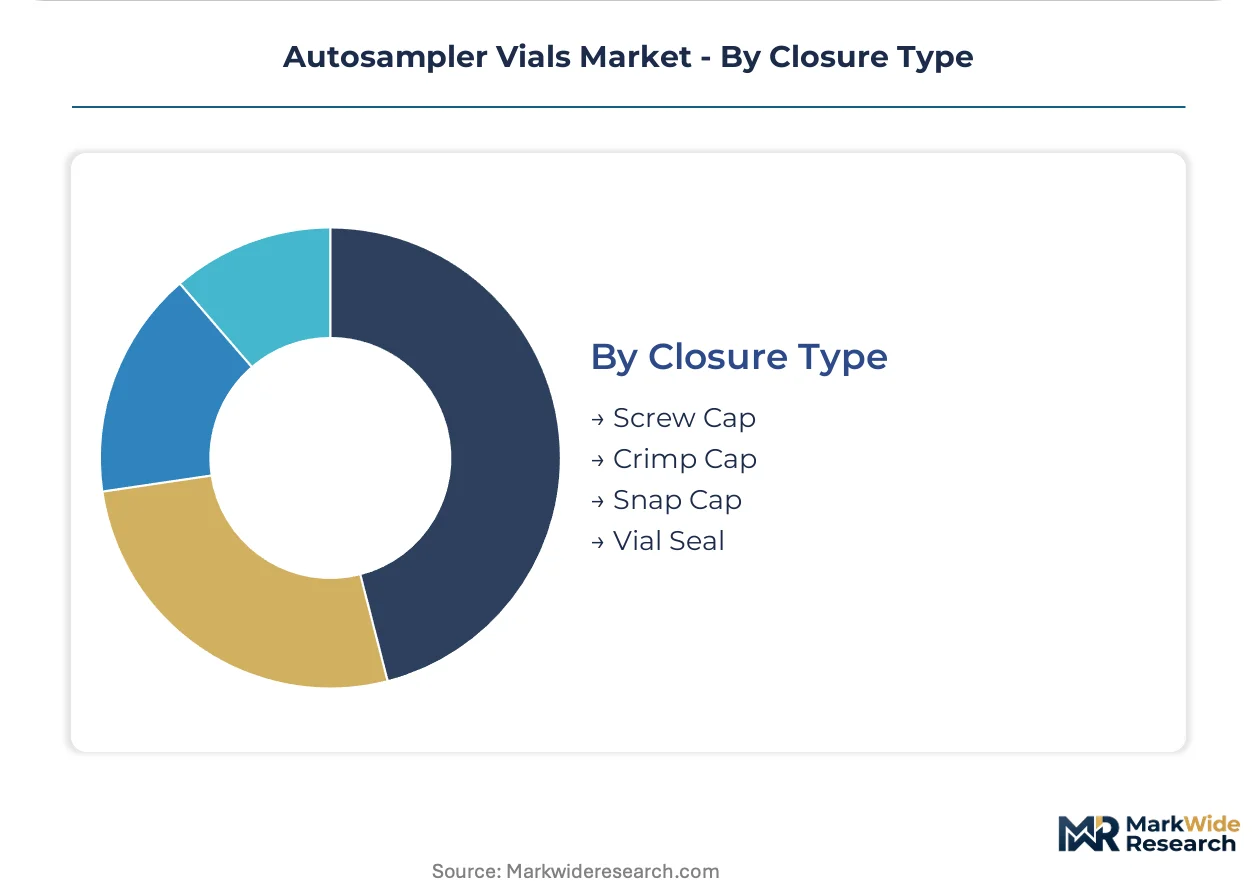
Closure Type:
Automation compatibility and seal integrity requirements segment closure selection across instrument platforms.
- Screw Cap:Polypropylene or phenolic caps with PTFE-faced septa support multiple injections and sample storage. Routine pharmaceutical analysis in high-throughput contract labs favors screw-cap convenience for sample queue management.
- Crimp Cap:Aluminum seals deliver superior hermetic integrity for volatile analyte containment. EPA-compliant environmental laboratories specify crimp seals for VOC and SVOC methods where sample preservation is critical.
- Snap Cap:Polyethylene snap-fit closures suit rapid sample processing with limited storage duration.
- Vial Seal:Pre-assembled cap-septum combinations streamline automated workflow setup.
Crimp Cap dominates volatility-critical applications. Screw Cap expands fastest as walk-up instrumentation proliferates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Borosilicate glass production concentrates in Germany and China, anchoring regional supply networks that feed precision chromatography consumables demand. Pharmaceutical manufacturing clusters and environmental testing enforcement intensity shape procurement patterns across major economies.
United States
Contract research organizations in Boston and San Diego scale automated LC-MS workflows for pharmacokinetic studies, consuming certified vial volumes at accelerated rates. FDA container closure integrity guidance mandates enhanced validation protocols for sterile drug products. New Jersey and North Carolina pharmaceutical manufacturing corridors maintain qualified supplier lists with ISO 15378 certification as procurement prerequisites.
Germany
Specialized glass manufacturers in Bavaria and Baden-Württemberg expand pharmaceutical-grade borosilicate capacity to serve chromatography consumables demand. EMA extractables and leachables guidance tightens polymer vial qualification thresholds for parenteral applications. Basel-proximate analytical clusters in southern Germany dual-source glass and polymer formats to mitigate regulatory compliance risk.
China
Domestic pharmaceutical quality control laboratories consolidate chromatography workflows onto unified platforms, driving certified vial consumption. NMPA alignment with international standards elevates container closure integrity requirements for export-oriented drug production. Yangtze River Delta manufacturing hubs in Shanghai and Suzhou expand ISO 15378-certified vial sourcing for biopharmaceutical analytical development.
India
CDSCO tightening of quality standards for export-oriented drug production creates demand for certified vials in Mumbai and Hyderabad manufacturing clusters. Contract research organizations in Bangalore scale high-throughput bioanalytical screening for global pharmaceutical clients. Gujarat pharmaceutical corridors invest in chromatography infrastructure that consumes precision-manufactured consumables.
Japan
PMDA quality standards for pharmaceutical packaging materials drive validation-intensive vial procurement in Osaka and Tokyo analytical laboratories. Shimadzu instrument installed base creates platform-specific compatibility requirements for consumables suppliers. Kansai region chemical and pharmaceutical manufacturers maintain strict change-control protocols for vial sourcing that extend supplier qualification timelines.
Autosampler Vials Market Competitive Environment
Platform-lock bundling dominates the current landscape as chromatography instrument vendors integrate consumables into service contracts. The market structure concentrates around three tiers: integrated analytical platform vendors with captive consumables arms, specialized precision-glass fabricators serving multi-vendor compatibility requirements, and regional distributors consolidating procurement for mid-sized laboratories. Strategic archetypes include instrument-anchored bundlers, certification-focused specialists, and direct-channel disintermediators. Competitive moves center on M&A for geographic footprint expansion and backward integration into borosilicate glass melting capacity.
Within the integrated platform tier, Agilent Technologies, Waters Corporation, and Thermo Fisher Scientific represent the instrument-anchored archetype that bundles vial sales with chromatography service contracts. These companies occupy positions where autosampler compatibility certification becomes a procurement gatekeeper for pharmaceutical and environmental testing laboratories. Their geographic footprints span United States, European, and Asia-Pacific analytical clusters where platform standardization is most advanced.
| Leading Market Players |
|---|
| Agilent Technologies |
| Waters Corporation |
| Thermo Fisher Scientific |
| Shimadzu Corporation |
| Merck KGaA |
| PerkinElmer |
| Restek Corporation |
| Gilson |
| Chemglass |
| Others |
Value Chain & Pricing Dynamics
Pharmaceutical quality control laboratories in the United States and Germany concentrate procurement volumes through multi-year service contracts with chromatography instrument vendors, embedding consumables pricing within bundled instrument maintenance agreements that obscure unit-level transparency.
Pricing Analysis
Instrument-anchored bundling includes certified vial compatibility guarantees and lot traceability documentation, while unbundled spot purchases from distributors exclude validation support. Three-tier pricing structure across premium-certified, standard optical, and economy non-certified levels tracks ISO 15378 certification status and dimensional tolerance grade. Cost compression in economy tiers is intensifying because contract research organizations are consolidating supplier lists to reduce qualification overhead. Academic and government laboratories exhibit highest price sensitivity due to fixed grant funding constraints, whereas biopharmaceutical stability study groups prioritize certification reliability over unit cost.
Supply Chain Analysis
Direct-to-instrument-vendor channels handle pharmaceutical manufacturing demand, while independent distributors serve mid-sized environmental testing laboratories with fragmented SKU requirements. Borosilicate glass melting capacity concentrates in Germany, China, and the United States, with pharmaceutical-grade tubing drawing from specialized furnaces in Bavaria and the Yangtze River Delta. Boron oxide and alumina feedstock costs hinge on energy market volatility, creating margin compression risks for fabricators without long-term supply agreements. Distribution runs through chromatography platform service contracts for regulated pharmaceutical segments, bypassing traditional laboratory supply distributors in high-volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The autosampler vials market is transitioning from commodity glass fabrication to surface-engineered precision consumables, as silanized and pre-slit septum technologies displace basic borosilicate formats in biopharmaceutical analytical workflows.
For Market Incumbents: Acquire specialized borosilicate glass melting capacity in Germany or China to secure captive supply of pharmaceutical-grade tubing against raw material cost volatility. Invest in ISO 15378 certification infrastructure to defend qualification status against emerging polymer vial substitutes that threaten glass dominance in ion chromatography applications. For New Entrants and Emerging Players: Surface-deactivated polymer formulations offer a technology-first wedge into cell therapy quality control workflows where protein adsorption sensitivity exceeds current polypropylene performance limits. Target Indian pharmaceutical manufacturing clusters in Mumbai and Hyderabad where CDSCO export standards are tightening faster than domestic glass vial supply can qualify, using direct e-commerce partnerships to bypass entrenched distributor relationships. For Investors and Strategic Acquirers: The window for entry favors precision-glass fabricators with existing pharmaceutical certifications and backward integration into boron oxide supply. Mid-cap specialists with ISO 15378 accreditation and established relationships with Waters or Agilent service contract channels represent consolidation targets. Monitor EMA and FDA extractables guidance revisions as the signal indicating accelerated polymer substitution timelines that would revalue glass-dependent assets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Borosilicate Melting | Captive glass supply secures margin control against energy-linked raw material swings. |
| Pre-slit Silicone Septum Technology Launch | Automated piercing compatibility opens cell therapy and gene therapy QC segments. |
| Direct E-commerce Channel Expansion | Thermo Fisher's platform demonstrates faster inventory turns than distributor networks. |
| ISO 15378 Certification Investment | Pharmaceutical-grade accreditation qualifies suppliers for FDA-regulated manufacturing contracts. |
| Surface Deactivation Process Development | Silanized vial formats capture biopharmaceutical stability study demand in Boston and Basel. |
Study Parameters
SEC 10-K filings, EMA regulatory guidance documents, and customs trade data formed the secondary backbone for supply chain and competitive positioning assessment. Primary interviews with chromatography platform product managers, pharmaceutical QC laboratory directors, and laboratory supply procurement officers validated demand patterns and pricing structures. Bottom-up and top-down triangulation reconciled instrument installed base estimates with consumables consumption rates across pharmaceutical, environmental, and food safety testing verticals.
Bottom-up modeling built from segment-level consumption intensity metrics, while top-down validation cross-checked against borosilicate glass production capacity and chromatography instrument shipment data. Product type, application, end user, and closure format dimensions structured the segmentation framework across the projection horizon. CAGRs derived from regression analysis of historical consumables intensity ratios applied to instrument platform growth trajectories, with EPA enforcement intensity and FDA guidance revision timelines as pharmaceutical and environmental testing demand modifiers.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden EPA method revisions or NMPA regulatory alignment accelerations in China. Forecasts reflect assumptions regarding borosilicate glass supply continuity and chromatography platform standardization trends. Periodic stress-testing of base assumptions is recommended against container closure integrity guidance updates and polymer vial technical performance breakthroughs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Services
Global Analytical Laboratory Services Market
Laboratory Services
US Clinical Laboratory Services Market
Laboratory Services
US Laboratory Disposable Products Market
Laboratory Services
Histopathology Services Market
Laboratory Services
Clinical Laboratory Tests Market
Laboratory Services
Karyotyping Service Market
Laboratory Services
Global Office Based Lab Market
Laboratory Services
Pathology Laboratories Market
Laboratory Services
Global Virology Specimen Collection Market
Laboratory Services
Veterinary Reference Laboratories Market
Laboratory Services
Hematocrit Tests Market
Laboratory Services
Enterprise Laboratory Informatics Market
Laboratory Services
Laboratory Disposable Products Market
Laboratory Services
Lab Mailers Market
Laboratory Services
Preeclampsia Laboratory Testing Market
Laboratory Services
Cytotoxicity Assays Market