
 Global Office Based Lab Market | 2026-2036
Global Office Based Lab Market Size, Share, and Industry Trends Forecast 2026-2036
Global Office Based Lab Market Foresight
Germany is tilting toward decentralized diagnostic capacity as statutory health insurance funds expand reimbursement for office-based laboratory services. Siemens Healthineers leverages its embedded installed base in German physician offices to sustain recurring consumable revenue. Abbott Laboratories anchors its competitive position through handheld immunoassay platforms designed for low-throughput clinical settings. Koninklijke Philips N.V. differentiates through integrated informatics that connect office lab results directly into electronic health records.
An office based lab comprises compact diagnostic instrumentation installed within non-hospital clinical settings, typically operating with CLIA-waived or moderate-complexity certification and delivering turnaround times under thirty minutes for routine chemistries, hematologies, and immunoassays. These facilities process capillary or venous specimens using cartridge-based reagent systems, enabling immediate clinical decision-making during patient encounters. Hematology analyzers occupy mature replacement cycles where margin pools concentrate in reagent contracts rather than hardware sales. Microfluidics technology represents the fastest-growing segment as manufacturers miniaturize multi-analyte panels onto disposable chips. Physician offices remain the dominant end-user channel, though outpatient clinics are expanding point-of-care testing menus to capture revenue previously referred to hospital laboratories.
FDA regulates office based labs through the Clinical Laboratory Improvement Amendments framework, stratifying test complexity and determining personnel, quality control, and proficiency testing requirements that directly shape instrument design and market access conditions. EMA's In Vitro Diagnostic Regulation imposes new conformity assessment obligations on manufacturers seeking European market entry, elevating documentation burdens for smaller device firms. ISO 15189 accreditation standards increasingly influence procurement decisions among managed care organizations evaluating laboratory service contracts. Stakeholders must monitor evolving payer policies on site-of-care reimbursement as Medicare Advantage plans experiment with capitated payments that reward diagnostic efficiency over test volume.
Market Dynamics
Microfluidics cartridge miniaturization is compressing instrument footprints while expanding test menus, forcing manufacturers to redesign around CLIA-waived workflows rather than laboratory-grade precision.
Growth Catalysts
- CLIA-waived pathway expansion:FDA's streamlined 510(k) clearance for moderate-complexity devices accelerates placement in endocrinology practices seeking same-day HbA1c and lipid panels.
- Germany's ambulatory reimbursement:Statutory health insurance funds now cover office-based chemistry and hematology, converting physician offices from referral sources to captive testing sites.
- Capillary specimen processing:Finger-stick collection eliminates phlebotomy infrastructure, enabling rapid deployment in retail clinic formats and urgent care satellites.
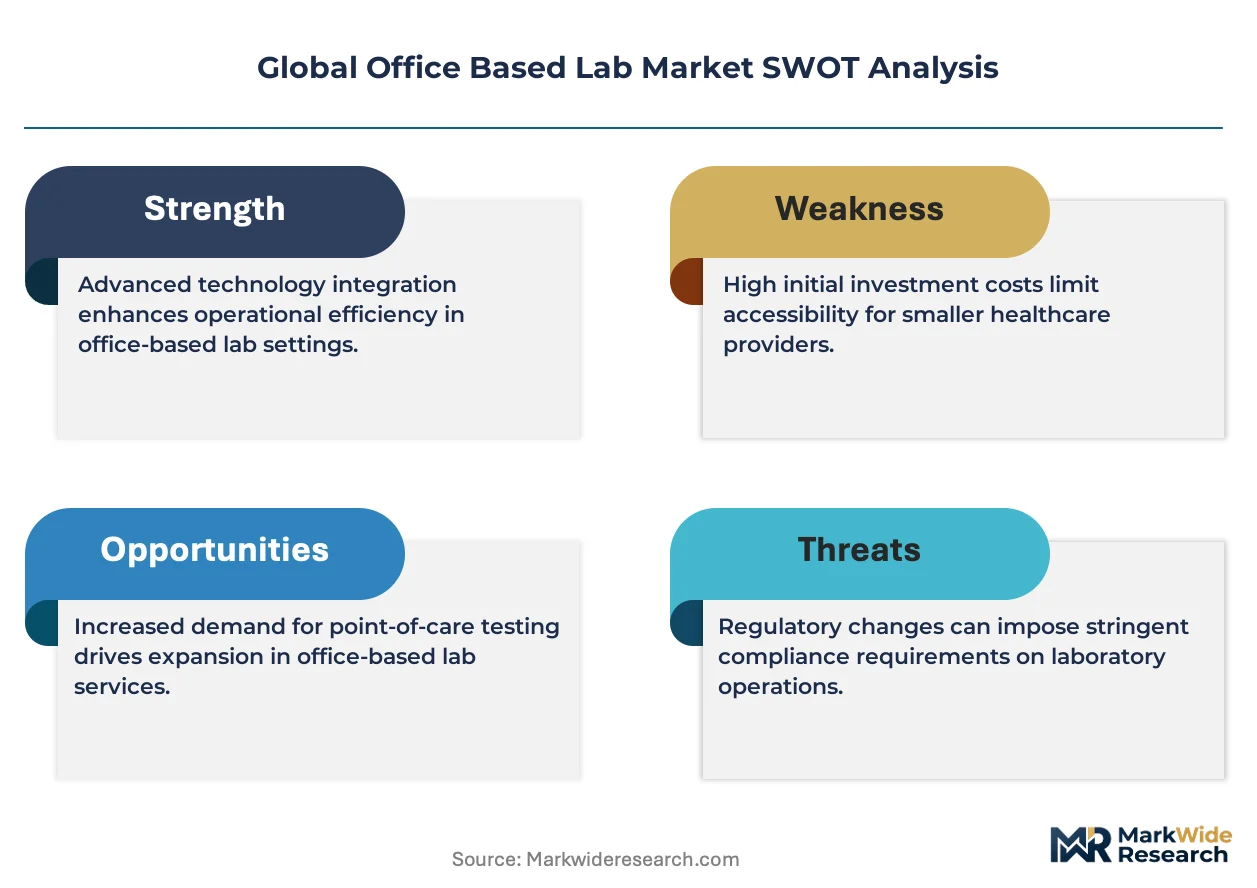
Market Restraints
- Reagent contract lock-in:Hematology analyzer installed bases bind practices to multi-year consumable agreements, suppressing competitive switching regardless of hardware innovation.
- IVDR documentation burden:EMA's In Vitro Diagnostic Regulation imposes conformity assessment costs that disproportionately burden smaller device manufacturers seeking European market entry.
- Hospital laboratory consolidation:Health system acquisition of independent practices reverses decentralization momentum, pulling testing volume back into centralized lab networks.
Strategic Opportunities
- Outpatient clinic menu expansion:Ambulatory surgery centers and dialysis clinics are adding point-of-care coagulation and chemistry to capture revenue previously referred externally.
- India's diagnostic infrastructure gap:Tier-2 and Tier-3 cities lack laboratory density, creating first-mover advantage for cartridge-based platforms deployable without cold-chain logistics.
- Medicare Advantage capitation experiments:Payer pilots rewarding diagnostic efficiency over test volume align site-of-care economics with office-based lab value propositions.
Industry Challenges
- ISO 15189 accreditation complexity:Managed care organizations increasingly require laboratory service contract bidders to demonstrate quality management system compliance, extending sales cycles.
- EHR integration fragmentation:Disconnected informatics architectures force practices to maintain parallel documentation workflows, eroding the turnaround-time advantage of in-office testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Office Based Lab Market |
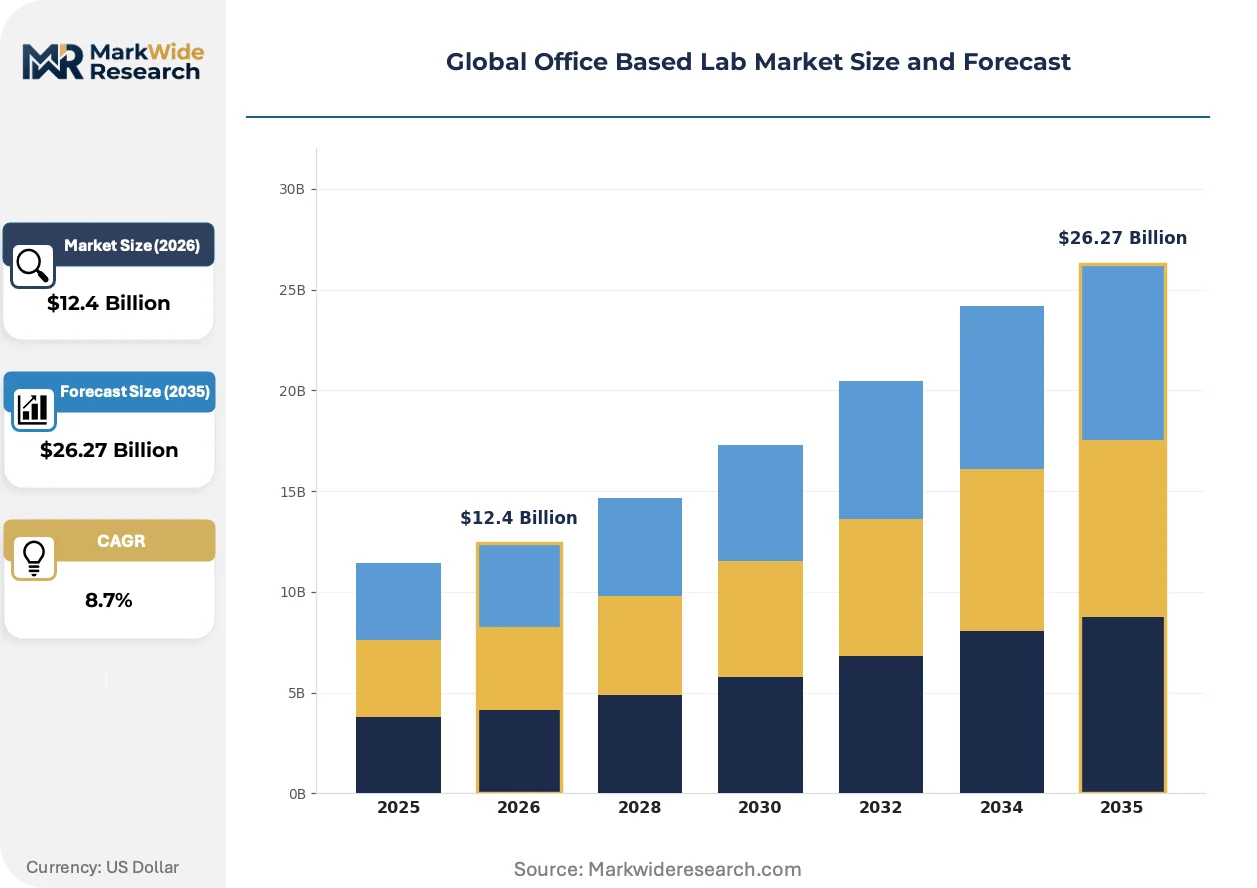
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $26.27 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hematology Analyzers, Clinical Chemistry Analyzers, Immunoassay Analyzers, Urinalysis Analyzers, Coagulation Analyzers Technology: Chromatography, Spectrophotometry, Immunofluorescence, Electrochemical Analysis, Microfluidics Application: Diabetes Monitoring, Infectious Disease Testing, Allergy Testing, Hormonal Analysis, Nutritional Assessment End User: Physician Offices, Dental Clinics, Veterinary Clinics, Research Institutes, Outpatient Clinics |
| Companies Covered | Medtronic, Siemens Healthineers, Koninklijke Philips N.V., GE Healthcare, Envision Healthcare, Surgery Care Associates, Inc., Edwards Lifesciences, Abbott Laboratories, Boston Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Office Based Lab Market Shifts & Advancements
Instrument architecture is converging around disposable cartridge ecosystems, compressing the traditional separation between sample preparation, reaction chemistry, and result interpretation into single-use consumables.
Multi-analyte microfluidic chips are hybridizing immunoassay, chemistry, and hematology functions onto single disposable platforms. Physician offices in Germany and the United States are adopting these systems to replace three separate instruments with one countertop unit. This convergence is hybridizing competitive dynamics, as chemistry specialists and immunoassay incumbents now compete directly for the same countertop real estate and consumable contracts.
EMA's In Vitro Diagnostic Regulation is recalibrating market access requirements for European entry. Manufacturers must now submit expanded clinical evidence and post-market surveillance protocols, elevating regulatory affairs staffing as a competitive capability. Smaller device firms without dedicated IVDR teams are withdrawing from European markets, concentrating supply among established multinationals with existing notified body relationships.
Capitated reimbursement pilots are restructuring buyer incentives across Medicare Advantage networks. Payers in Florida and Texas are testing bundled payments that reward practices for diagnostic episode efficiency rather than test volume. This shift favors office-based labs with sub-thirty-minute turnaround, as same-visit result availability eliminates follow-up appointment costs and improves risk-score capture accuracy.
Global Office Based Lab Market Segmentation
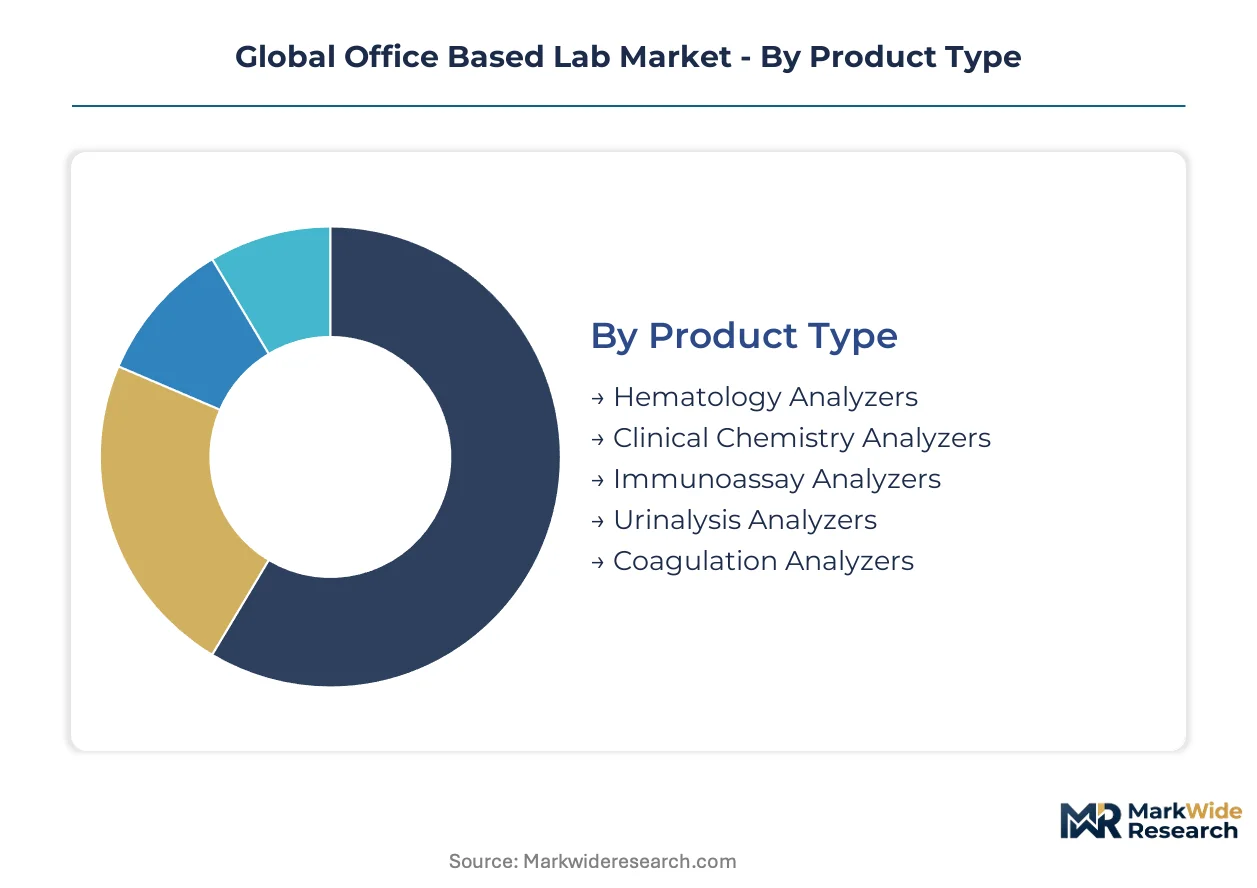
Segmentation in the office based lab market reveals how cartridge economics and test complexity dictate procurement patterns across clinical settings. Different product categories operate on fundamentally different replacement cycles, with some instruments generating recurring revenue for a decade while others face displacement within three years.
Product Type:
Replacement velocity varies dramatically across instrument categories, with consumable-driven systems refreshing faster than capital-intensive analyzers.
- Hematology Analyzers:These systems perform complete blood counts using impedance and optical detection methods. Mature installed bases in German physician offices and US endocrinology practices generate locked-in reagent contracts that suppress competitive switching regardless of hardware innovation.
- Clinical Chemistry Analyzers:Enzymatic and ion-selective electrode systems process routine metabolic panels. Demand concentrates in outpatient clinics expanding point-of-care menus to capture revenue previously referred to hospital laboratories.
- Immunoassay Analyzers:Sandwich and competitive binding assays detect hormones, cardiac markers, and infectious agents. CLIA-waived handheld platforms from Abbott anchor placement in low-throughput settings.
- Urinalysis Analyzers:Automated microscopy and dipstick readers evaluate renal function and metabolic status. These occupy mid-cycle replacement positions between hematology stability and microfluidics disruption.
- Coagulation Analyzers:Electromechanical clot detection systems monitor anticoagulation therapy. Ambulatory surgery centers and dialysis clinics are adding these to capture previously externalized testing.
Hematology analyzers dominate installed base. Microfluidics-enabled immunoassay platforms are where expansion concentrates.
Technology:
Cost tiers separate legacy optical methods from emerging cartridge-based systems, with price-performance ratios determining adoption sequencing.
- Microfluidics:Disposable chip architectures integrate sample preparation, reaction chemistry, and detection into single-use consumables. Miniaturized multi-analyte panels are expanding fastest in German and US physician offices seeking countertop consolidation.
- Immunofluorescence:Antibody-conjugated fluorophore detection enables high-sensitivity hormone and infectious disease testing. Endocrinology practices deploying same-day HbA1c and thyroid panels drive placement.
- Chromatography:Liquid and gas separation methods resolve complex metabolic profiles. These laboratory-grade systems see limited office adoption due to CLIA complexity requirements.
- Spectrophotometry:Absorbance-based quantification supports routine chemistry panels. Mature price compression limits margin expansion despite steady volume.
- Electrochemical Analysis:Ion-selective electrodes and amperometric sensors deliver glucose, electrolyte, and blood gas results. Capillary specimen compatibility enables rapid deployment in retail clinic formats.
Spectrophotometry dominates legacy installed base. Microfluidics is gaining share fastest as cartridge ecosystems displace discrete instruments.
Application:
Volume concentration tracks chronic disease prevalence and reimbursement alignment across clinical specialties.
- Diabetes Monitoring:HbA1c, glucose, and lipid panel testing supports glycemic management. Same-day result availability in US endocrinology practices eliminates follow-up appointment costs under Medicare Advantage capitation pilots.
- Infectious Disease Testing:Rapid strep, influenza, and respiratory pathogen detection guides antibiotic stewardship. CLIA-waived molecular platforms accelerate placement in urgent care satellites.
- Hormonal Analysis:Thyroid, cortisol, and reproductive hormone testing supports endocrine disorder diagnosis. German statutory insurance reimbursement expansion drives office-based chemistry adoption.
- Allergy Testing:IgE-mediated sensitivity panels identify environmental and food triggers. Lower test frequency limits instrument utilization compared to chronic disease monitoring.
- Nutritional Assessment:Vitamin, mineral, and metabolic marker evaluation supports functional medicine practices. Outlier positioning outside mainstream reimbursement constrains scale.
Diabetes monitoring dominates test volume. Infectious disease testing is where menu expansion concentrates.
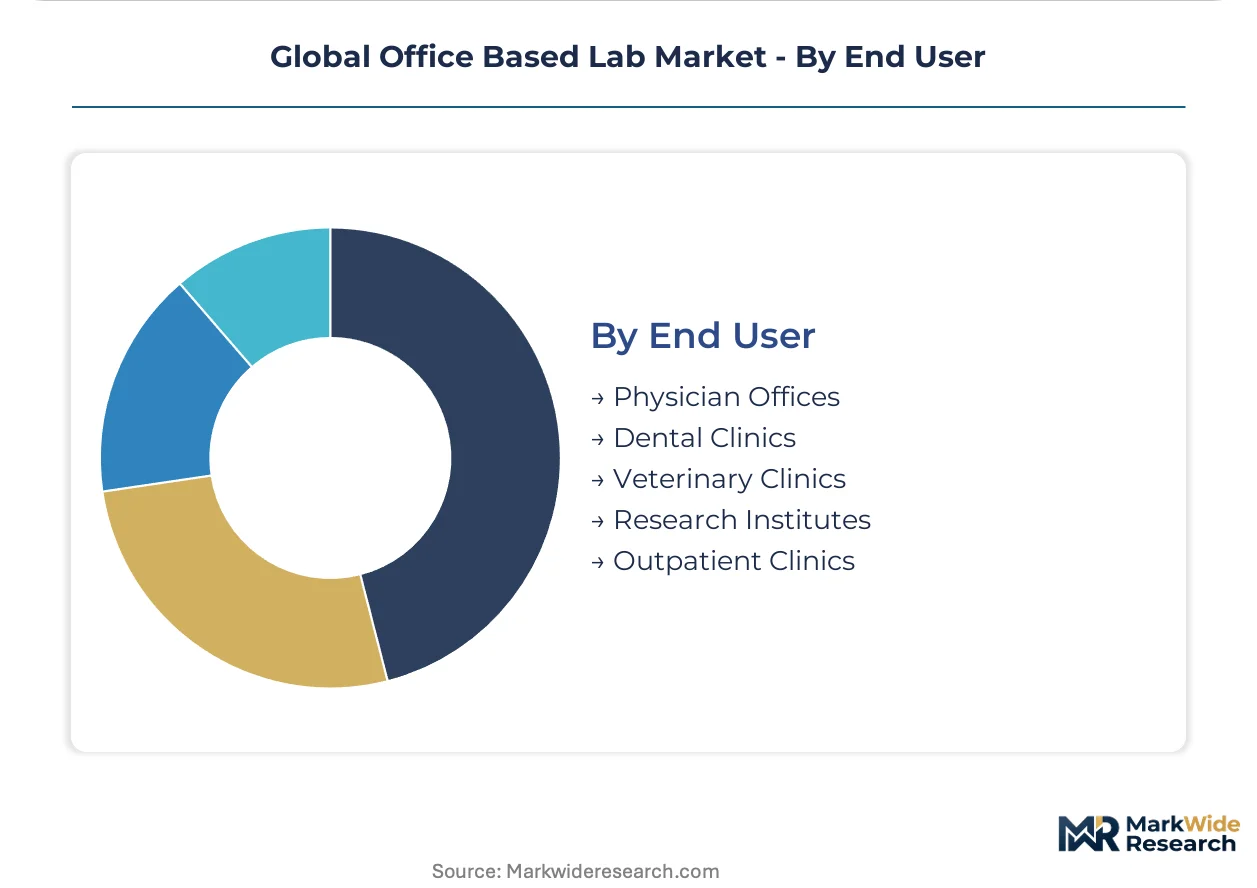
End User:
Customer type determines throughput requirements, space constraints, and integration complexity for instrument vendors.
- Physician Offices:Primary care and specialty practices with limited square footage prioritize countertop footprint and CLIA-waived workflows. Siemens Healthineers leverages embedded German installed bases for recurring consumable revenue.
- Outpatient Clinics:Ambulatory surgery centers and dialysis facilities expand testing menus to capture revenue previously referred externally. These settings tolerate moderate-complexity certification for broader test panels.
- Dental Clinics:Point-of-care coagulation and infectious disease testing supports perioperative management. Limited test volume constrains dedicated instrument economics.
- Veterinary Clinics:Companion animal chemistry and hematology mirrors human diagnostic workflows. Separate regulatory pathways through FDA Center for Veterinary Medicine shape product development.
- Research Institutes:Method development and clinical trial support demands laboratory-grade precision. These settings fall outside CLIA-waived market targeting.
Physician offices dominate channel volume. Outpatient clinics are where competitive displacement concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor underwrites Germany's central position in European diagnostic distribution, connecting manufacturing clusters in Bavaria to North Sea ports for intercontinental shipment of cartridge-based platforms.
Germany
Statutory health insurance funds have expanded reimbursement for office-based chemistry and hematology, converting physician offices from referral sources to captive testing sites. EMA's In Vitro Diagnostic Regulation imposes new conformity assessment obligations on manufacturers seeking European market entry. Siemens Healthineers leverages its embedded installed base in Bavarian and North Rhine-Westphalia physician offices to sustain recurring consumable revenue.
United States
Endocrinology practices are expanding point-of-care testing capabilities for same-day HbA1c and lipid panels. FDA's streamlined 510(k) clearance for moderate-complexity devices accelerates instrument placement under the Clinical Laboratory Improvement Amendments framework. Medicare Advantage capitation pilots in Florida and Texas reward diagnostic efficiency, favoring office-based labs with sub-thirty-minute turnaround times.
India
Tier-2 and Tier-3 cities lack laboratory density, creating first-mover advantage for cartridge-based platforms deployable without cold-chain logistics. The country's national pharmaceutical regulator oversees diagnostic device registration through streamlined pathways for waived-complexity systems. Diagnostic infrastructure deployment concentrates in Maharashtra and Karnataka, where ambulatory networks seek decentralized testing capacity.
Japan
PMDA regulates in vitro diagnostic devices through quality management system requirements that align with international standards. METI promotes healthcare digitization initiatives that connect office lab results into electronic health record architectures. Tokyo and Osaka metropolitan areas host concentrated demand from aging-population primary care practices seeking rapid turnaround capabilities.
Brazil
ANVISA governs diagnostic device registration with conformity assessment procedures that manufacturers navigate for Latin American market access. Ambulatory care expansion in São Paulo and Rio de Janeiro drives demand for compact instrumentation suitable for limited square footage. Private health insurance networks increasingly authorize reimbursement for point-of-care testing within physician office settings.
Global Office Based Lab Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in reagent and cartridge supply. The market structure concentrates among diversified medical technology conglomerates with established diagnostic divisions, while mid-scale specialists occupy niche application segments. Three archetypes dominate: installed-base incumbents leveraging recurring consumable contracts, handheld-platform innovators capturing CLIA-waived placement, and informatics-integrated vendors connecting results directly into electronic health records. Competitive moves center on multi-year reagent contract lock-in and microfluidics cartridge ecosystem development.
Among diversified health technology conglomerates, Siemens Healthineers and Koninklijke Philips N.V. exemplify the installed-base incumbent archetype, while Abbott Laboratories occupies a position within the handheld-platform tier. These entities represent contrasting strategic postures: the German and Dutch conglomerates anchor recurring revenue through embedded instrument placements, whereas the US-based corporation exemplifies mobility-focused CLIA-waived deployment. GE Healthcare and Boston Scientific Corporation sit within adjacent medical device ecosystems with selective diagnostic exposure. Medtronic, Edwards Lifesciences, and Envision Healthcare represent diversified healthcare service and device models where laboratory integration constitutes a portfolio component rather than core identity.
| Leading Market Players |
|---|
| Medtronic |
| Siemens Healthineers |
| Koninklijke Philips N.V. |
| GE Healthcare |
| Envision Healthcare |
| Surgery Care Associates, Inc. |
| Edwards Lifesciences |
| Abbott Laboratories |
| Boston Scientific Corporation |
| Others |
Supply & Pricing Matrix
Bavaria's precision manufacturing clusters anchor cartridge production capacity for European and North American markets, concentrating upstream supply power among established multinationals with dedicated IVDR compliance teams. This geographic concentration shapes downstream pricing leverage, as practices in Germany and the United States face limited alternative sourcing for CLIA-waived consumables.
Pricing Analysis
Volume-discount tiering structures dominate reagent contracting, with hematology analyzer placements locking practices into multi-year consumable agreements at differentiated rates. Pricing stratifies across premium, standard, and economy tiers based on test complexity certification and after-sales service bundling. Cost compression in economy-tier CLIA-waived devices is intensifying because microfluidics miniaturization reduces per-test manufacturing overhead. Outpatient clinics exhibit highest price sensitivity due to capital budget constraints, while integrated health systems leverage scale for preferential tier access.
Supply Chain Analysis
Polymer substrates and precision-molded plastics for disposable cartridges draw from Germany, China, and South Korea, with optical detection components sourced from Japan and Taiwan. Single-source vulnerability concentrates in microfluidic chip fabrication, where specialized cleanroom capacity remains limited to a handful of qualified suppliers. Distribution runs through regional medical device distributors with direct sales support for instrument installation and CLIA compliance training.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents an early-cycle expansion story, with Medicare Advantage capitation pilots and Germany's ambulatory reimbursement expansion creating structural tailwinds for point-of-care adoption.
For Market Incumbents: Harden reagent contract lock-in through extended consumable supply agreements that bundle instrument maintenance and regulatory compliance support. Deepen backward integration into microfluidic cartridge manufacturing to defend margin position against emerging platform competitors. Prioritize IVDR documentation investment to maintain European market access as smaller rivals withdraw.
For New Entrants and Emerging Players: Build out cartridge-based platforms for India's Tier-2 and Tier-3 diagnostic infrastructure gaps, where cold-chain-free deployment creates first-mover positioning. Target ambulatory surgery centers in the United States seeking coagulation and chemistry menu expansion. Pursue direct-to-clinic distribution partnerships that bypass established distributor markups.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors microfluidics-integrated platform developers with established CLIA-waived regulatory pathways over legacy optical instrument incumbents. Long-term viability hinges on consumable recurring revenue capture rather than hardware placement economics. Watch Medicare Advantage capitation pilot expansion across additional states as the primary demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Compliance Investment | EMA documentation requirements are concentrating European supply among multinationals with dedicated regulatory affairs teams. |
| Microfluidics Cartridge Ecosystem Development | Disposable chip architectures compress instrument footprints while expanding test menus for countertop consolidation. |
| Medicare Advantage Reimbursement Strategy | Capitation pilots in Florida and Texas reward diagnostic efficiency, favoring sub-thirty-minute turnaround platforms. |
| Hospital System Partnership | Health system acquisition of independent practices creates channel conflict with decentralized testing momentum. |
| EHR Integration Platform | Direct connectivity into electronic health records addresses fragmentation eroding point-of-care turnaround advantages. |
Research Methodology
A spread of perspectives from diagnostic instrument product managers, CLIA compliance officers, hospital purchasing committee members, and GPO contracts managers converged on the working assumptions. Primary field engagement combined with secondary validation from FDA 510(k) filings, CMS Medicare reimbursement databases, EMA IVDR submission records, and hospital procurement contract disclosures. Bottom-up instrument placement modeling and top-down addressable market sizing were triangulated for cross-verification.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology platform, clinical application, and end-user facility category. CAGRs were derived from instrument replacement cycle analysis and consumable attach rate projections. Forecast inputs incorporated CLIA-waived test volume growth and statutory insurance reimbursement policy trajectories.
Sensitivities concentrate around Medicare Advantage capitation pilot expansion velocity and IVDR documentation burden evolution for European market access. Forecasts reflect assumptions on physician practice acquisition trends and microfluidics manufacturing scale-up timelines. Material shifts in site-of-care reimbursement policy or cartridge supply concentration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Services
US Clinical Laboratory Services Market
Laboratory Services
Global Lab Consumables Market
Laboratory Services
Organ Function Assays Market
Laboratory Services
Global Elispot and Fluorospot Assay Market
Laboratory Services
Assessment Services Market
Laboratory Services
Biomarker Clinical Phase Outsourcing Services Market
Laboratory Services
Clinical Laboratory Tests Market
Laboratory Services
Clinical Laboratory Services Market
Laboratory Services
Global Medical Laboratories Market
Laboratory Services
Global Clinical Reference Laboratory Market
Laboratory Services
Hematocrit Tests Market
Laboratory Services
Laboratory Developed Tests Market
Laboratory Services
US Laboratory Disposable Products Market
Laboratory Services
Serum Separation Gel Market
Laboratory Services
Global Analytical Laboratory Services Market
Laboratory Services
Middle East and Africa Clinical Laboratory Services Market