
 UAE Camel Dairy Market | 2026-2036
UAE Camel Dairy Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Camel Dairy Market Intelligence
Multi-source feed procurement is rebalancing toward in-house fodder cultivation across UAE camel dairy operations. Emirates Industry for Camel Milk & Products (Camelicious) leverages vertical integration from breeding to retail shelf placement. Al Ain Farms anchors production scale through controlled desert farming protocols. Dubai Investments PJSC extends capital allocation into downstream processing capacity.
Camel dairy encompasses the collection, pasteurization, and value-added processing of milk from Camelus dromedarius, with raw milk typically containing 2.5-3.5% protein and 3-5% fat depending on feed and lactation stage. The industry serves nutritional, pharmaceutical, and premium foodservice applications where allergen-reduced profiles command functional premiums. Milk and yogurt segments dominate volume throughput due to established household familiarity and health-institution contracting. Specialty stores and direct sales channels capture margin pools through freshness positioning and subscription-based delivery models that bypass supermarket slotting fees.
MOHAP governs pharmaceutical-grade camel milk approvals for diabetes and autism protocol inclusion, while ESMA enforces product identity standards that distinguish pure camel milk from blended offerings. FSSAI-aligned import benchmarks for Indian expatriate consumers also shape cross-border sourcing verification. Stakeholders must track how federal quality mark expansion affects export eligibility to Gulf Cooperation Council markets.
Market Dynamics
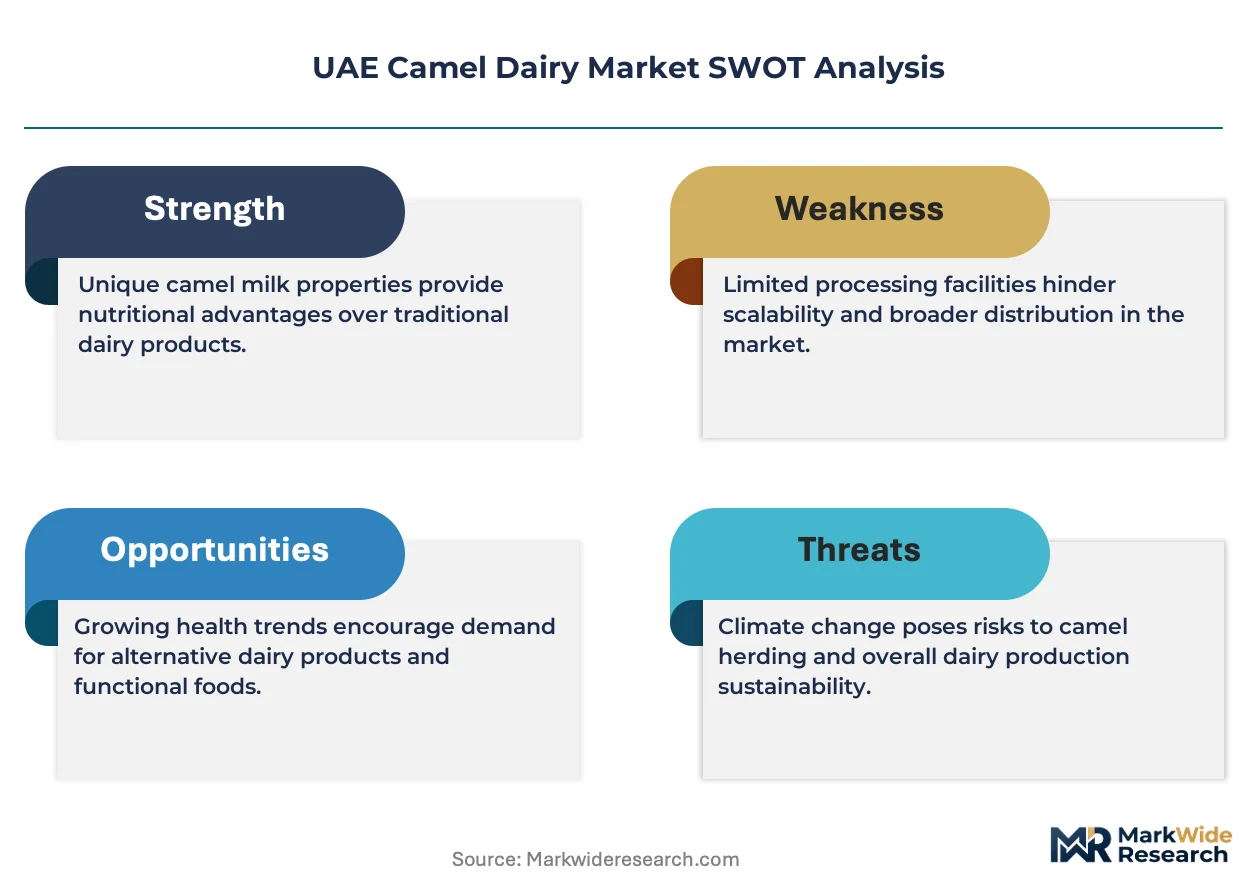
ESMA's tightened labeling requirements for camel milk products are compressing supply chain timelines and forcing producers toward certified procurement networks, fundamentally restructuring how value pools distribute across the Emirates.
Growth Catalysts
- MOHAP pharmaceutical-grade approvals:Therapeutic nutrition protocols for diabetes and autism management are institutionalizing camel dairy procurement across UAE health facilities.
- Medical tourism clusters:Abu Dhabi and Dubai wellness infrastructure concentrates high-value consumption nodes around premium retail and clinical distribution.
- Controlled desert farming:In-house fodder cultivation protocols reduce feed import dependency and stabilize input cost structures for scaled producers.
Market Restraints
- Alfalfa and Rhodes grass import volatility:UAE camel dairies source 70-80% of forage from international markets, exposing margins to shipping cost fluctuations and currency swings.
- Single-species production concentration:Camelus dromedarius dominates regional herds, creating genetic bottleneck risks and limiting disease resistance diversification.
- FSSAI-aligned import verification:Cross-border sourcing requirements for Indian expatriate consumer segments add documentation layers that slow procurement cycles.
Strategic Opportunities
- Al Ain production corridor:Controlled farming zones in the Eastern Region offer land lease advantages and proximity to heritage breeding stock for capacity expansion.
- Subscription-based direct delivery:Freshness-positioned channels bypass supermarket slotting fees and capture recurring revenue pools from health-conscious households.
- Pharmaceutical extraction partnerships:Immunoglobulin and insulin-like protein isolation from camel whey opens biopharma supply contracts beyond traditional food applications.
Industry Challenges
- Veterinary specialist scarcity:Camel reproductive health and mastitis management expertise concentrates in academic institutions, creating hiring competition among commercial operations.
- ESMA certification timeline compression:Federal quality mark expansion for GCC export eligibility requires simultaneous documentation upgrades across multiple product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Camel Dairy Market |
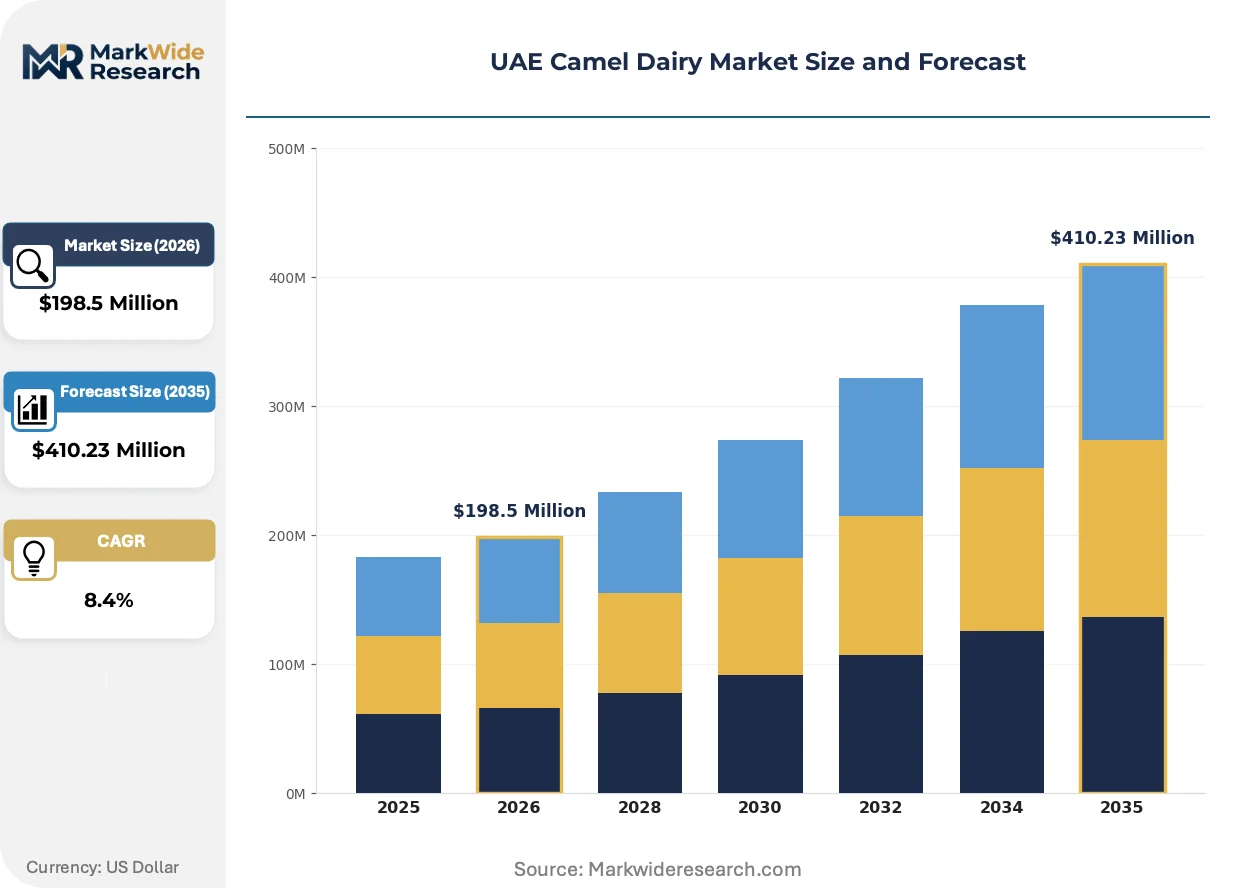
| Market Size in 2026 | $198.5 Million |
| Market Size in 2035 | $410.23 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cream, Milk, Cheese, Yogurt Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales End User: Households, Restaurants, Cafes, Health Institutions Packaging Type: Bottles, Tetra Packs, Cans, Bulk Containers |
| Companies Covered | Al Rawabi Dairy, Dubai Investments PJSC, Emirates Industry for Camel Milk & Products (Camelicious), Al Safi Danone, Unikai Foods PJSC, Al Ain Farms, Agthia Group PJSC, Baladna Q.P.S.C., Marmum Dairy Farm, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Camel Dairy Market Strategic Shifts & Innovations
Automation in milking parlors and cold chain digitization are compressing harvest-to-shelf timelines, while regulatory data transparency requirements reshape how producers document provenance and therapeutic claims.
Automated rotary milking systems designed for camel physiology are converging with IoT-enabled herd health monitoring. Large-scale operations in Abu Dhabi emirate are deploying these platforms to reduce labor dependency and capture real-time somatic cell count data. The technology is converging with blockchain traceability mandates, compressing audit preparation cycles from weeks to hours.
ESMA's product identity standards now distinguish pure camel milk from blended offerings through mandatory isotope ratio testing. This regulatory architecture forces reformulation of existing SKUs and disqualifies informal sector suppliers from formal retail placement. Specialty store channels absorb the highest compliance burden as they source from smaller, less-documented herds.
Health-institution procurement is consolidating around long-term therapeutic nutrition contracts rather than spot purchasing. Hospital foodservice operators in Dubai are displacing traditional dairy distributors with direct manufacturer relationships that include clinical outcome documentation. This pattern concentrates most visibly in diabetes management wards where MOHAP protocol inclusion drives vendor selection criteria.
UAE Camel Dairy Market Segmentation
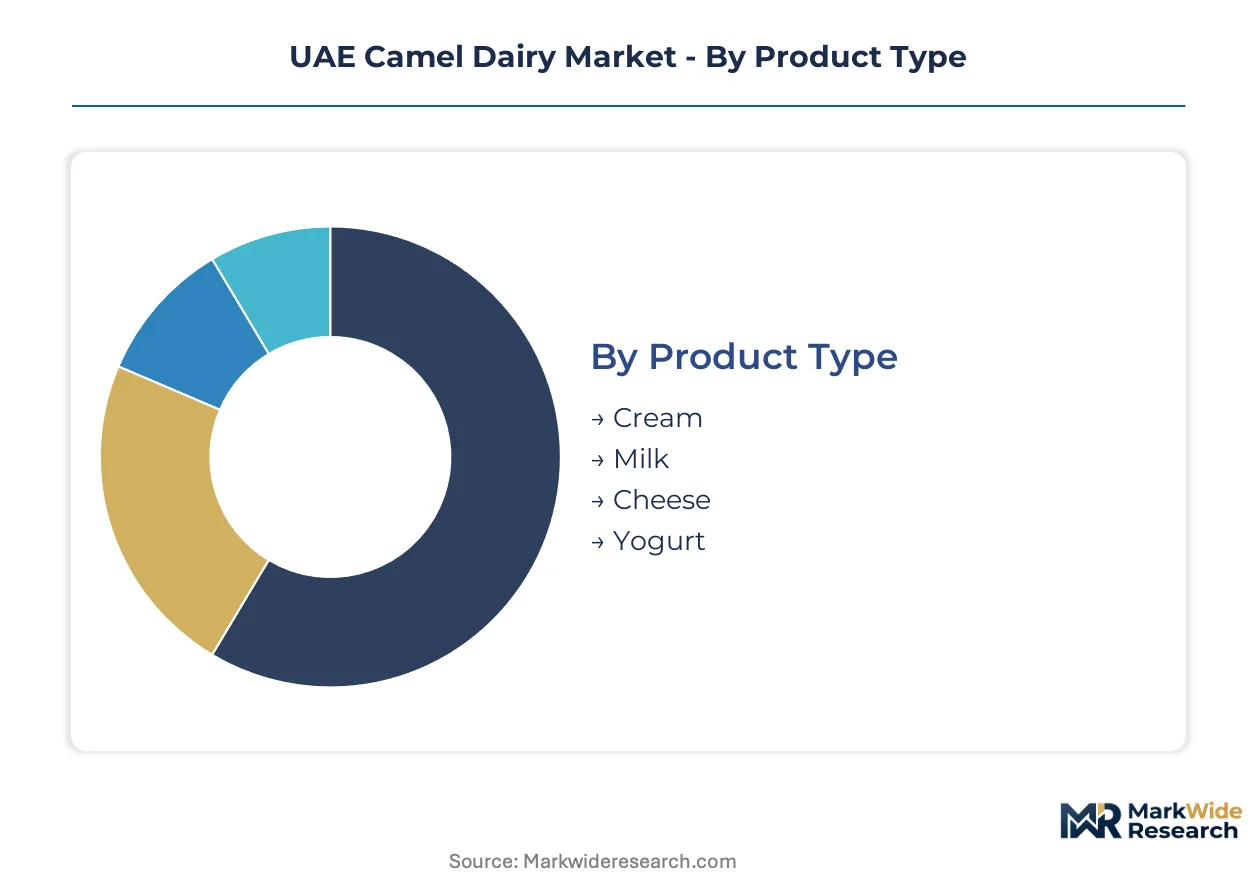
Segmentation in UAE camel dairy reveals how regulatory compliance burdens concentrate across product tiers and channel structures. ESMA certification requirements and MOHAP pharmaceutical approvals create divergent margin architectures that reshape competitive positioning.
Product Type:
Milk and yogurt carry baseline ESMA identity standards, while cheese and cream formulations trigger additional compositional testing protocols.
- Milk:Raw camel milk contains 2.5-3.5% protein and 3-5% fat depending on feed quality and lactation stage. Household consumption in Abu Dhabi and Dubai concentrates demand around pasteurized fresh variants, with MOHAP therapeutic protocols institutionalizing procurement across diabetes management wards.
- Yogurt:Fermented products command functional premiums through probiotic positioning and digestibility claims. Health institutions in Dubai medical tourism clusters specify live culture counts above retail grades, creating a parallel specification tier.
- Cheese:ESMA's isotope ratio testing mandates apply fully to aged and fresh cheese categories, compressing supply base to vertically integrated producers with captive laboratory capacity.
- Cream:Higher fat separation requirements and shorter shelf stability limit distribution radius, favoring Al Ain corridor production zones with direct Dubai access.
Leading the category by volume: Milk. Growing fastest: Yogurt.
Distribution Channel:
Channel selection determines documentation depth, with direct and specialty tiers absorbing disproportionate provenance verification costs.
- Direct Sales:Subscription models bypass supermarket slotting fees and capture recurring revenue from health-conscious households. Freshness positioning requires blockchain-enabled cold chain documentation that informal suppliers cannot sustain.
- Specialty Stores:Curated retail in Dubai and Abu Dhabi premium malls concentrates highest-margin SKUs, though smaller herd sourcing creates ESMA compliance bottlenecks.
- Supermarkets:Slotting fee structures favor scaled producers with consistent volume throughput, marginalizing smaller operations.
- Online Retail:Last-mile cold chain requirements and temperature-validated delivery windows add operational layers that concentrate share among integrated logistics operators.
Direct sales channels expand most quickly. Supermarkets retain volume leadership.
End User:
User type dictates specification stringency, with institutional procurement consolidating around therapeutic outcome documentation.
- Health Institutions:MOHAP pharmaceutical-grade approvals for diabetes and autism protocols require batch-level immunoglobulin testing and clinical outcome tracking. Hospital foodservice operators in Dubai displace traditional distributors with direct manufacturer relationships.
- Households:Premium retail infrastructure in Abu Dhabi and Dubai concentrates consumption among expatriate wellness segments and heritage-conscious nationals.
- Restaurants:Foodservice procurement emphasizes consistent fat content for recipe standardization, favoring contracted supply over spot purchasing.
- Cafes:Specialty coffee and wellness beverage applications drive demand for barista-grade frothing performance, a specification that filters supplier base by protein stability.
Health institutions command steepest expansion trajectory. Households anchor current volume.
Packaging Type:
Packaging selection balances shelf-life extension against ESMA labeling mandate compliance costs.
- Tetra Packs:Aseptic carton technology enables ambient distribution without cold chain dependency, opening retail placement beyond refrigerated fixture constraints.
- Bottles:Premium positioning in specialty channels favors transparent PET and glass formats that signal freshness, though shorter shelf life limits geographic reach.
- Cans:Extended stability supports export-oriented production targeting GCC markets, with ESMA quality mark expansion driving documentation upgrades.
- Bulk Containers:Foodservice and institutional procurement concentrates around 10-20 liter bag-in-box formats that minimize per-unit packaging cost for high-throughput users.
Tetra packs lead by volume. Bulk containers gain share fastest in institutional segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Al Ain corridor's controlled desert farming anchors production geography across the Emirates, with heritage breeding stock concentrated in Eastern Region lease zones. Feed cultivation localities in Abu Dhabi emirate reduce import dependency for Rhodes grass and alfalfa. Dubai's medical tourism infrastructure concentrates high-value consumption nodes.
Dubai
Wellness infrastructure and premium retail malls concentrate household and institutional demand. MOHAP pharmaceutical-grade approvals for diabetes protocols drive hospital foodservice procurement. Dubai Investments PJSC extends capital into downstream processing capacity near Jebel Ali logistics corridors.
Abu Dhabi
Medical tourism clusters and heritage breeding programs concentrate supply and demand. Emirates Industry for Camel Milk & Products leverages vertical integration from breeding to retail shelf placement. Al Ain Farms anchors production scale through controlled desert farming protocols in Eastern Region zones.
Sharjah
Heritage dairy operations and smaller herd holdings supply specialty store channels. ESMA labeling requirements compress supply chain timelines for informal sector participants. Industrial zones near Sharjah International Airport support cold chain logistics for export-oriented production.
Northern Emirates
Ras Al Khaimah and Fujairah land lease advantages attract capacity expansion for bulk container production. Fodder cultivation pilots in mountainous zones diversify feed sourcing beyond coastal import corridors. Regional producers serve institutional procurement contracts with reduced logistics costs to Dubai medical clusters.
UAE Camel Dairy Market Key Industry Players
Capacity expansion dominates the current landscape as scaled producers secure land leases in Al Ain corridor and Eastern Region zones. The vendor base concentrates around vertically integrated operations with captive laboratory capacity for ESMA isotope ratio testing. Three archetypes define positioning: heritage-integrated conglomerates with breeding-to-retail control, diversified dairy portfolios with camel line extensions, and specialist camel operations with therapeutic nutrition focus. Competitive moves center on backward integration into fodder cultivation and direct manufacturer relationships with hospital foodservice operators.
Within the heritage-integrated tier, Emirates Industry for Camel Milk & Products and Al Ain Farms exemplify vertical control from breeding stock through retail placement. Dubai Investments PJSC occupies a diversified holding-company position extending capital across downstream processing assets. These three anchors represent distinct strategic postures: captive supply chain dominance, production scale through controlled farming protocols, and portfolio diversification into value-added processing capacity.
| Leading Market Players |
|---|
| Al Rawabi Dairy |
| Dubai Investments PJSC |
| Emirates Industry for Camel Milk & Products (Camelicious) |
| Al Safi Danone |
| Unikai Foods PJSC |
| Al Ain Farms |
| Agthia Group PJSC |
| Baladna Q.P.S.C. |
| Marmum Dairy Farm |
| Others |
Cost & Logistics Intelligence
Sovereign-backed producers and family-owned heritage operations anchor supply discipline across the Emirates, translating captive fodder cultivation and laboratory certification capacity into pricing power that informal sector competitors cannot replicate. ESMA quality mark requirements and MOHAP pharmaceutical-grade protocols stratify the market into documented and undocumented supply tiers, with pricing premiums accruing to operators that internalize compliance costs rather than externalize them to spot-market procurement.
Pricing Analysis
Warranty and service bundling separates pharmaceutical-grade supply contracts from commodity spot transactions, with health institutions paying embedded premiums for batch-level immunoglobulin testing and clinical outcome documentation. Three-tier pricing structure across premium, standard, and economy levels reflects ESMA certification status, MOHAP protocol inclusion, and cold chain integrity guarantees. Cost compression in the standard tier intensifies as supermarket slotting fees and import feed volatility squeeze margins. Health institutions exhibit lowest price sensitivity due to therapeutic protocol mandates, while household retail segments demonstrate highest elasticity to freshness-positioned subscription alternatives.
Supply Chain Analysis
Direct-to-health-institution channels handle pharmaceutical-grade demand, while specialty store and supermarket distribution serves household consumption. Geographic supply concentrates in Abu Dhabi emirate's Al Ain corridor and Dubai's Jebel Ali logistics zones, with Northern Emirates land leases emerging for bulk production. Raw material dependencies center on Rhodes grass, alfalfa, and specialized camel feed formulations imported from Australia, Sudan, and regional cultivation pilots. Single-source vulnerability in veterinary specialist expertise creates hiring competition that delays herd expansion timelines. Distribution runs through vertically integrated operators with captive cold chain assets, marginalizing smaller heritage producers lacking blockchain traceability infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Emirates camel dairy sector is consolidating into a vertical-integration race where backward control over breeding stock, fodder cultivation, and laboratory certification determines margin capture. Players pursuing upstream feed security and downstream hospital foodservice relationships are separating from spot-market dependent competitors.
For Market Incumbents: Anchor market position through simultaneous ESMA quality mark expansion across multiple product lines and exclusive long-term therapeutic nutrition contracts with Dubai hospital foodservice operators. Emerging specialist operations with pharmaceutical extraction capabilities threaten to displace traditional dairy distributors in diabetes management wards. Priority investment in captive fodder cultivation reduces exposure to alfalfa import currency swings. For New Entrants and Emerging Players: Hospital foodservice procurement managers represent the most penetrable channel entry point, as direct manufacturer relationships displace traditional distributor intermediaries. White-space targets concentrate in immunoglobulin and insulin-like protein isolation for biopharma supply contracts beyond traditional food applications. Northern Emirates land lease advantages in Ras Al Khaimah and Fujairah offer capacity expansion economics with reduced logistics costs to Dubai medical clusters. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale heritage operations in Sharjah and Northern Emirates with established herd holdings but underdeveloped laboratory certification capacity. Long-term viability hinges on pharmaceutical-grade approval trajectories and GCC export eligibility expansion. The signal to monitor is MOHAP protocol inclusion decisions for additional therapeutic indications beyond diabetes and autism management.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fodder Cultivation | Al Ain corridor producers reduce Rhodes grass import dependency through controlled desert farming protocols. |
| Pharmaceutical-Grade Certification Investment | MOHAP approvals for diabetes protocols institutionalize procurement across hospital foodservice operations. |
| Direct Hospital Foodservice Relationships | Dubai medical tourism clusters displace traditional distributors with manufacturer-direct therapeutic nutrition contracts. |
| Biopharma Extraction Partnership Development | Camel whey immunoglobulin isolation opens supply contracts beyond traditional dairy applications. |
| Blockchain Cold Chain Documentation | ESMA traceability mandates compress audit preparation cycles from weeks to hours for compliant operators. |
Research Approach
ESMA regulatory filings, MOHAP pharmaceutical approval databases, and UAE customs trade records formed the secondary backbone, cross-referenced against primary interviews with camel dairy operations managers, hospital foodservice procurement directors, veterinary reproductive health specialists, and specialty retail category buyers. Bottom-up herd capacity and milk yield data triangulated against top-down consumption estimates derived from health institution procurement volumes and retail channel throughput.
Historical trendline analysis of camel dairy production volumes, feed import patterns, and regulatory compliance cost structures informed the analytical framework across the analysis window. Segmentation dimensions modeled include product type, distribution channel, end user category, and packaging format alongside ESMA certification tier and MOHAP protocol inclusion status. CAGRs derived from regression analysis of documented production capacity additions, land lease expansions, and health institution procurement contract growth trajectories.
Caveats apply where alfalfa and Rhodes grass import volatility, veterinary specialist scarcity, or GCC export eligibility timeline shifts could materially shift the outlook. Forecasts reflect assumptions around regulatory enforcement consistency and therapeutic protocol adoption rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Cholesterol Reduced Butter Market
Dairy Products
Russia Whey Protein Market
Dairy Products
Fermented Dairy Products Market
Dairy Products
Low Fat Yogurt Calories Market
Dairy Products
Middle East and Africa UHT Milk Market
Dairy Products
Milk Protein Concentrate Market
Dairy Products
Condensed Whey Market
Dairy Products
Fermented Dairy Ingredients Market
Dairy Products
United States Dairy Market
Dairy Products
Low Temperature Pasteurized Milk Market
Dairy Products
Sheep Milk Cheese Market
Dairy Products
South America Dairy Market
Dairy Products
North America Whole Milk Powder Market
Dairy Products
Lactose Free Dairy Products Market
Dairy Products
Smoked Cheese Market
Dairy Products
Goat Milk Market