
 Condensed Whey Market | 2026-2036
Condensed Whey Market Size, Share, and Industry Trends Forecast 2026-2036
Condensed Whey Market Analysis
Buyer concentration among sports nutrition and functional beverage formulators is restructuring procurement dynamics for condensed whey suppliers. Dairy Farmers of America leverages its cooperative milk supply base to secure raw whey streams at scale. Fonterra Co-operative Group Limited anchors Oceania production capacity and exports into Asian nutritional markets. Glanbia plc specializes in protein fractionation and extends its ingredient portfolio through downstream whey valorization.
Condensed whey is a heat-reduced liquid dairy derivative containing approximately 35-50% total solids, produced by evaporating water from fresh whey to create a viscous syrup with preserved lactose, protein, and mineral content for industrial food manufacturing. Protein-enriched variants command premium positioning as brands reformulate for elevated protein claims in ready-to-drink beverages and performance nutrition. Sweetened condensed whey maintains volume leadership in bakery and confectionery applications where Maillard browning and humectancy prove functionally critical. Packaging in aseptic pouches and Tetra Packs is gaining share among ingredient distributors seeking reduced freight costs and extended ambient shelf stability.
FDA food additive regulations and USDA dairy grading standards govern condensed whey composition, labeling, and interstate commerce in the United States, while EFSA and EU dairy hygiene directives shape product specifications for European ingredient trade. BIS food safety certifications and FSSAI dairy product standards create compliance thresholds for condensed whey entering Indian processed food channels. Stakeholders must monitor evolving protein content disclosure mandates and sustainability auditing requirements that will determine supplier eligibility in contract negotiations with multinational food manufacturers.
Market Dynamics
Sports nutrition manufacturers are consolidating procurement around protein-enriched condensed whey as clean-label mandates from FDA and EFSA force reformulation of legacy beverage portfolios. Supplier qualification now hinges on verified lactose-protein ratios and ambient stability credentials.
Growth Catalysts
- Performance Beverage Formulation:Ready-to-drink protein brands are specifying condensed whey with 40%+ solids content to hit elevated protein claims without powder dissolution issues. This specification pull is accelerating contract volume commitments from co-manufacturers.
- EU Green Deal Dairy Targets:Circular economy mandates for whey valorization are redirecting formerly waste-stream volumes into food-grade condensed whey channels. Processing infrastructure subsidies in the Netherlands and Denmark are expanding conversion capacity.
- Membrane Filtration Advances:Ultrafiltration-retentate blending is enabling real-time protein standardization during evaporation. This process integration is reducing batch-to-batch variability for bakery and confectionery buyers.
Market Restraints
- Fresh Whey Supply Concentration:Fluid milk processing in the Upper Midwest United States dominates raw whey availability. Any disruption to cheese production volumes in Wisconsin directly constrains condensed whey feedstock.
- Lactose Price Volatility:Crystallized lactose commodity markets swing with infant formula demand cycles. This input cost instability compresses margins on standard-grade condensed whey where lactose content exceeds 50%.
- Technical Limitation in Low-Acid Applications:Condensed whey pH profiles below 6.0 limit deployment in certain neutral pH beverage systems. Alternative protein hydrolysates capture these formulation slots despite higher unit costs.
Strategic Opportunities
- Indian Processed Food Channels:FSSAI dairy product standards are formalizing condensed whey specifications for the first time. Early entrants establishing BIS food safety certifications gain preferred supplier status with domestic bakery chains.
- Aseptic Pouch Distribution:Tetra Pak and Scholle IPN formats are reducing freight costs for ingredient distributors serving remote manufacturing clusters. Ambient shelf stability extends reach to Southeast Asian co-packers lacking cold chain infrastructure.
- Precision Fermentation Convergence:Whey protein isolate producers are exploring condensed whey as a growth medium feedstock. This cross-industry application opens non-food revenue streams for dairy processors with surplus volumes.
Industry Challenges
- Clean-Label Certification Timelines:Non-GMO Project and USDA Organic audits for condensed whey require 12-18 month validation cycles. These extended timelines mismatch quarterly procurement windows of multinational beverage brands.
- Evaporator Energy Intensity:Mechanical vapor recompression systems demand substantial capital deployment for efficiency compliance. Mid-scale processors face stranded asset risk on legacy steam-heated equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Condensed Whey Market |
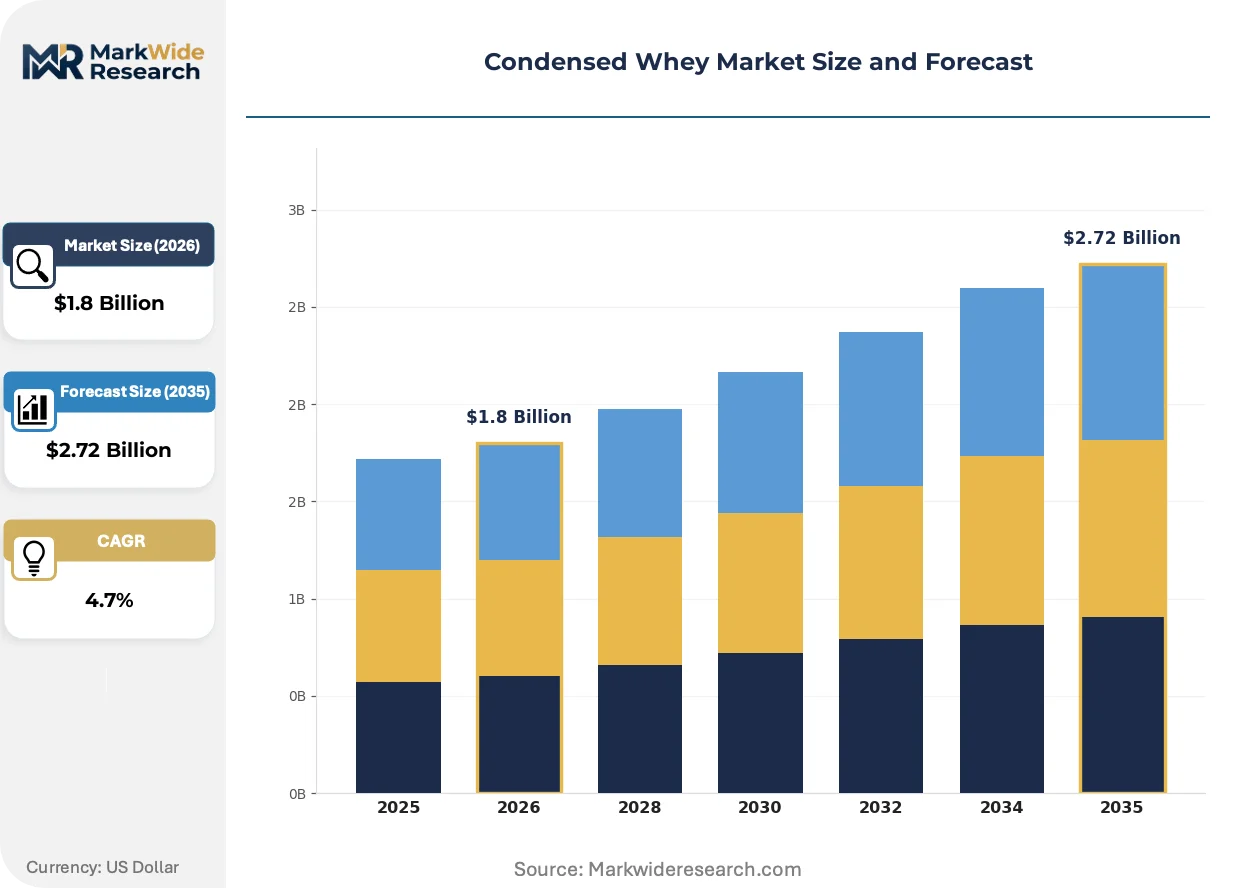
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sweetened, Unsweetened, Flavored, Protein-Enriched Packaging Type: Cans, Pouches, Tetra Packs, Bottles End User: Food & Beverage Industry, Nutritional Supplements, Bakery Products, Confectionery Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Wholesale Suppliers |
| Companies Covered | Dairy Farmers of America, Fonterra Co-operative Group Limited, Agri-Mark Inc., Leprino Foods Company Inc., Saputo Inc., Arla Foods AMBA, Glanbia plc, Lactalis Group, Associated Milk Producers Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Condensed Whey Market Emerging Trajectories
Automation of quality control and membrane processing is compressing production cycles while regulatory disclosure mandates are forcing ingredient transparency upgrades across supplier tiers.
Membrane filtration skids equipped with inline protein analyzers are automating real-time solids adjustment during whey concentration. Beverage co-manufacturers in the United States are adopting these systems at replacement cycle pace. This automation is reducing laboratory hold times from 4 hours to 15 minutes, enabling just-in-time tanker dispatch to ready-to-drink filling lines.
EFSA dairy hygiene directive updates are mandating extended shelf-life validation data for condensed whey entering European nutritional markets. Industrial consequence includes mandatory HACCP documentation for every evaporator batch. Protein-enriched variants face the steepest compliance burden, with German and French buyers now requiring 18-month ambient stability certificates.
Ingredient distributors are unbundling traditional tanker-minimum contracts into flex-volume aseptic pouch offerings. This procurement model change disrupts legacy dairy cooperative supply agreements. Co-manufacturers in Texas and California are piloting these programs, trading unit cost premiums for working capital relief and reduced obsolescence risk on slow-moving SKUs.
Condensed Whey Market Segmentation
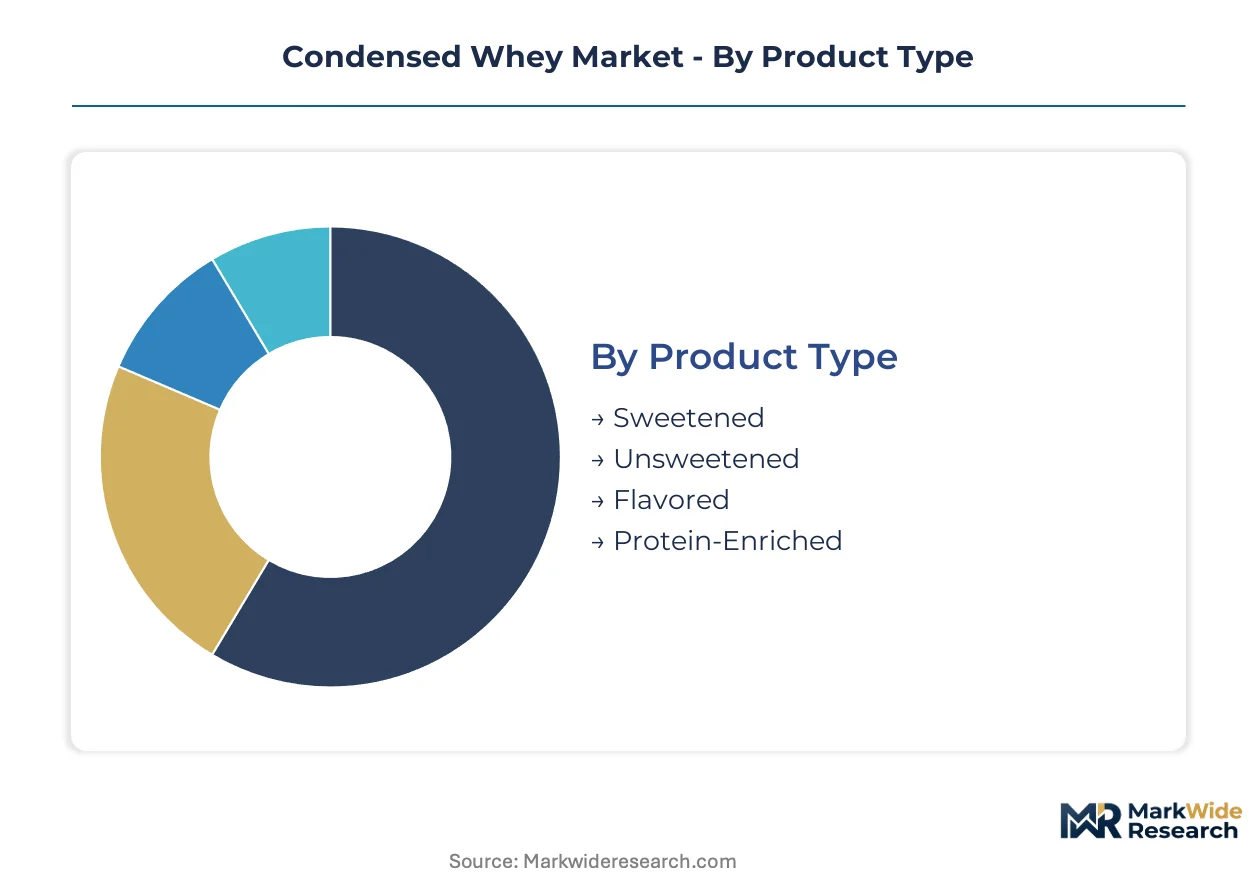
Segmentation in condensed whey markets exposes divergent margin structures between commodity-grade bakery feedstocks and premium protein concentrates. Procurement specifications vary sharply across end-use channels, forcing suppliers to maintain parallel production lines with distinct certification requirements.
Product Type:
Volume leadership sits with standard formulations, while protein-enriched variants capture disproportionate margin expansion.
- Protein-Enriched:Contains 40-50% total solids with elevated whey protein concentrate fractions. Ready-to-drink beverage brands in the United States specify this grade for clean-label protein fortification without powder dissolution failures.
- Sweetened:Standard lactose-rich formulation with approximately 35-45% total solids. Bakery and confectionery manufacturers in Wisconsin and Illinois dominate procurement for Maillard browning and humectancy functionality.
- Unsweetened:Neutral pH base for savory applications and controlled-sugar formulations. Processors blend this grade with mineral-adjusted profiles for infant nutrition pre-mixes.
- Flavored:Pre-compounded vanilla or chocolate bases for small-batch ice cream and dessert manufacturers. Limited volume but commands 15-20% price premiums over standard grades.
Mature deployment sits with Sweetened. Newer deployment is concentrated in Protein-Enriched.
Packaging Type:
Logistics cost pressures are accelerating format substitution away from traditional steel containers.
- Tetra Packs:Aseptic brick format with 12-month ambient shelf stability. Ingredient distributors serving Southeast Asian co-packers lacking cold chain infrastructure specify this format for reduced freight density.
- Pouches:Scholle IPN and similar flexible formats enable flex-volume procurement. Texas and California co-manufacturers pilot these programs to reduce working capital tied to slow-moving SKUs.
- Cans:Legacy steel packaging for industrial bakery accounts with established handling equipment. Volume share is compressing as freight costs penalize weight-heavy formats.
- Bottles:HDPE and PET containers for foodservice and small-scale manufacturing. Limited to applications requiring direct dispensing without intermediate transfer.
Established infrastructure favors Cans. Capacity expansion targets Pouches and Tetra Packs.
End User:
Application-driven specification divergence creates distinct supplier qualification tracks.
- Nutritional Supplements:Sports nutrition manufacturers demand verified protein content disclosure and ambient stability credentials. FDA food additive regulations and EFSA hygiene directives force reformulation of legacy beverage portfolios toward this segment.
- Food & Beverage Industry:Broad category spanning dairy-based beverages, processed cheese, and prepared meals. Procurement consolidates around large-scale whey processors with direct-to-beverage channel expansion.
- Bakery Products:Humectancy and browning control drive specification. Sweetened condensed whey maintains volume leadership here despite clean-label pressure.
- Confectionery:Caramel and fudge applications require precise lactose crystallization control. European confectioners source through Dutch and Danish conversion facilities subsidized under EU Green Deal dairy targets.
Traditional dominance rests with Food & Beverage Industry. Steepest expansion trajectory belongs to Nutritional Supplements.
Distribution Channel:
Channel restructuring reflects working capital optimization and traceability demands.
- Wholesale Suppliers:Tanker-minimum contracts and bulk tank farm deliveries serve large-scale dairy processors and co-manufacturers. Dairy Farmers of America leverages cooperative supply bases to anchor this channel.
- Online Retail:E-commerce platforms enable small-batch procurement for artisan bakeries and startup beverage brands. Order fragmentation challenges logistics efficiency.
- Supermarkets:Limited to consumer-sized condensed whey for home baking. Negligible share in industrial-grade volumes.
- Health Food Stores:Specialty organic and non-GMO certified grades for premium supplement brands. Clean-label certification timelines of 12-18 months restrict supplier eligibility.
Consolidated volume flows through Wholesale Suppliers. Emerging flexibility concentrates in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for condensed whey concentrates in the United States, where sports nutrition brands and ready-to-drink beverage manufacturers drive procurement volumes. Large-scale whey processing infrastructure in the Upper Midwest and direct-to-beverage channel expansion create sustained pull-through for protein-enriched grades. Regulatory frameworks and processing subsidies across multiple jurisdictions reshape competitive positioning for suppliers.
United States
Wisconsin and Illinois anchor North American production, with cheese-making operations generating raw whey feedstock for evaporator facilities. FDA food additive regulations and USDA dairy grading standards govern interstate commerce and protein content disclosure requirements. Dairy Farmers of America leverages its cooperative milk supply base to secure raw whey streams at scale across the Upper Midwest.
Germany
EFSA dairy hygiene directives mandate extended shelf-life validation data for condensed whey entering nutritional markets. German buyers now require 18-month ambient stability certificates for protein-enriched variants. Processing clusters in Bavaria and North Rhine-Westphalia concentrate conversion capacity serving continental bakery and confectionery accounts.
Netherlands
EU Green Deal dairy targets redirect formerly waste-stream whey volumes into food-grade condensed whey channels. Government processing infrastructure subsidies expand evaporator capacity in dairy-intensive provinces. Rotterdam and Groningen serve as export hubs for Asian nutritional markets seeking Oceania-competitive protein ingredients.
India
FSSAI dairy product standards formalize condensed whey specifications for processed food channels for the first time. BIS food safety certifications create compliance thresholds for domestic bakery chain procurement. Maharashtra and Gujarat industrial corridors attract early entrants establishing preferred supplier status ahead of regulatory enforcement.
Denmark
Circular economy mandates accelerate whey valorization investments with state-supported conversion facility expansion. Danish processors specialize in membrane filtration-retentate blending for protein standardization during evaporation. Copenhagen-Arhus corridor facilities export into German and French confectionery markets requiring precise lactose crystallization control.
Condensed Whey Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue protein fractionation and aseptic packaging differentiation. The supplier base consolidates around dairy cooperatives with captive milk supply and independent processors with membrane filtration capabilities. Three archetypes dominate: cooperative-owned evaporators with backward integration into raw whey, specialist protein fractionators extending downstream, and ingredient distributors unbundling tanker contracts into flex-volume formats. Competitive moves center on evaporator automation investments and aseptic pouch distribution partnerships.
Among cooperative-structured producers, Dairy Farmers of America and Fonterra Co-operative Group Limited exemplify supply-base anchoring strategies. Glanbia plc occupies a specialist position in protein fractionation and downstream whey valorization. These three represent distinct geographic and structural approaches to securing raw material streams and serving nutritional supplement formulators.
| Leading Market Players |
|---|
| Dairy Farmers of America |
| Fonterra Co-operative Group Limited |
| Agri-Mark Inc. |
| Leprino Foods Company Inc. |
| Saputo Inc. |
| Arla Foods AMBA |
| Glanbia plc |
| Lactalis Group |
| Associated Milk Producers Inc. |
| Others |
Supply Flow & Price Mechanics
Membrane filtration specialists in the Netherlands and Denmark command wage premiums that widen spreads between protein-enriched and standard-grade condensed whey. Labor-cost differentials between these technical clusters and commodity evaporator operations in Wisconsin and Illinois directly map to pricing-tier stratification across the category.
Pricing Analysis
Volume leadership sits with standard lactose-rich formulations while protein-enriched variants capture disproportionate margin expansion. Three-tier pricing structure across premium, standard, and economy levels separates certified organic grades from conventional protein-enriched and commodity bakery feedstocks. Price differentiation hinges on protein content verification and ambient stability credentials, with German buyers demanding 18-month certificates. Pricing pressure stems from lactose commodity volatility compressing margins on standard grades where lactose exceeds 50%. Bakery and confectionery manufacturers exhibit highest price sensitivity; sports nutrition brands tolerate premiums for verified protein disclosure.
Supply Chain Analysis
Certification gating through FDA food additive regulations, EFSA dairy hygiene directives, and FSSAI dairy product standards fragments supplier eligibility across major markets. Raw whey supply concentrates in the United States, Netherlands, and Denmark, with cheese-making operations in Wisconsin and Bavaria feeding evaporator networks. Processing infrastructure draws from fluid milk volumes, membrane filtration skids, and mechanical vapor recompression systems. Single-source vulnerability runs through Upper Midwest cheese production; any disruption to Wisconsin output directly constrains feedstock availability. Distribution runs through wholesale tanker-minimum contracts and emerging flex-volume aseptic pouch programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Condensed whey supply remains structurally constrained by evaporator capacity bottlenecks in protein fractionation, propping pricing power for qualified suppliers. Upper Midwest cheese-whey availability and European membrane filtration throughput create dual chokepoints that sustain margin premiums.
For Market Incumbents: Hedge against precision fermentation disruption by securing long-term whey supply contracts with Upper Midwest dairy cooperatives. Invest in evaporator automation and inline protein analyzers to compress batch-to-batch variability. Deepen backward integration into raw whey streams through cooperative supply-base anchoring. Defensive certification investment in Non-GMO Project and USDA Organic audits protects against clean-label reformulation mandates from multinational beverage brands. For New Entrants and Emerging Players: E-commerce platforms enable direct procurement relationships with artisan bakeries and startup beverage brands lacking tanker-minimum volumes. Target Indian processed food channels where FSSAI standards are formalizing specifications for the first time; early BIS certification secures preferred supplier status with domestic bakery chains. Aseptic pouch distribution partnerships with Scholle IPN and Tetra Pak reduce capital barriers to serving remote Southeast Asian co-packers. For Investors and Strategic Acquirers: Re-rating potential sits with membrane filtration-equipped processors given EU Green Deal subsidy flows and whey valorization mandates. Five-to-ten year viability favors specialists with protein standardization capabilities and ambient stability validation infrastructure. Acquisition focus should target mid-scale evaporator operators in the Netherlands and Denmark with export positioning into Asian nutritional markets. Signal to monitor: FSSAI enforcement timelines and Indian bakery chain procurement consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Automation | Inline protein analyzers reduce laboratory hold times from 4 hours to 15 minutes for just-in-time dispatch. |
| Aseptic Pouch Distribution Partnership | Scholle IPN and Tetra Pak formats extend reach to Southeast Asian co-packers lacking cold chain infrastructure. |
| EU Green Deal Processing Subsidy Capture | Dutch and Danish government funding expands evaporator capacity for waste-stream whey valorization. |
| Clean-Label Certification Investment | Non-GMO Project and USDA Organic audits secure eligibility in multinational beverage brand procurement. |
| Indian FSSAI Early Compliance | BIS food safety certifications establish preferred supplier status ahead of regulatory enforcement. |
Methodological Framework
USDA dairy grading standards, FDA food additive filings, and EU dairy hygiene directive updates formed the secondary backbone for supply-side validation. Primary interviews with evaporator operations managers, sports nutrition procurement leads, bakery chain technical directors, and ingredient distributor logistics heads combined with customs records and cooperative milk supply disclosures. Bottom-up triangulation across production capacity by facility and top-down validation through end-use demand modeling anchored volume estimates.
Bottom-up modeling of evaporator throughput by protein grade and packaging format intersected with top-down demand segmentation across nutritional supplements, bakery, and confectionery channels. Segmentation dimensions included product type, packaging configuration, end-use application, and distribution channel across the analysis window. CAGRs derived from production capacity expansion timelines, regulatory enforcement schedules, and channel shift trajectories. Forecast inputs incorporated membrane filtration adoption curves and EU subsidy disbursement patterns.
Inputs from evaporator operators and dairy cooperatives were available through the study window; gaps in real-time whey protein spot pricing introduce uncertainty bands around margin projections. Forecasts reflect documented assumptions on regulatory enforcement pacing and clean-label certification adoption. A model refresh is warranted upon material change in FDA protein content disclosure mandates or FSSAI enforcement timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Evaporated Milk Market
Dairy Products
Kuwait Dairy Products Market
Dairy Products
Global Grass Fed Dairy Product Market
Dairy Products
India Milk Protein Market
Dairy Products
Skimmed Milk Powder Market
Dairy Products
Ultra High Temperature Sterilized Milk Market
Dairy Products
Organic Dairy Market
Dairy Products
Fat-Filled Milk Powder Market
Dairy Products
North America A2 Milk Market
Dairy Products
Milk Mineral Market
Dairy Products
Low Fat Yogurt Market
Dairy Products
Citrus Yogurt Market
Dairy Products
Colombia Dairy Market
Dairy Products
Middle East and Africa UHT Milk Market
Dairy Products
Butter and Margarine Market
Dairy Products
Fermented Dairy Ingredients Market