
 Smoked Cheese Market | 2026-2036
Smoked Cheese Market Size, Share, and Industry Trends Forecast 2026-2036
Smoked Cheese Market Outlook
Premium artisanal smoked cheese is decoupling from commodity private-label offerings on the basis of provenance claims, cold-smoking duration, and milk sourcing transparency. Leprino Foods Company leverages its massive whey recovery infrastructure to sustain cost advantages in mozzarella-based smoked formats. Carr Valley Cheese Company differentiates through Wisconsin-specific aging protocols and regional milk partnerships. Arla Foods anchors European supply with cooperative-owned dairy networks spanning Denmark and Sweden.
Smoked cheese denotes cheese varieties exposed to controlled smoke from burning wood chips or vaporized liquid smoke, typically achieving surface phenol concentrations that impart color, flavor, and preservative effects through cold-smoking below 30°C or hot-smoking up to 90°C. The process extends shelf life while delivering the distinctive aromatic profile demanded by deli counters, pizza manufacturers, and charcuterie platters. Cheddar and gouda dominate value pools in retail blocks and slices, where aging-smoke interaction commands price premiums over younger variants. Vacuum-sealed packaging leads volume throughput for foodservice distributors, though specialty stores increasingly stock paper-wrapped wedges for direct consumer engagement.
FDA dairy plant inspection standards and USDA organic certification requirements shape product safety and label claims in the United States, while EFSA food contact material rules and EU protected geographical indication frameworks govern smoked cheese trade across member states. The EU Green Deal's methane reduction targets are pressuring dairy processors to document emissions from milk collection through smoking operations. Stakeholders must weigh cold-smoking capital expenditure against accelerated liquid smoke adoption as energy costs and carbon accounting tighten margin structures.
Market Dynamics
The EU F-Gas Regulation is compressing traditional cold-smoking infrastructure economics while liquid smoke vaporization systems gain capital allocation priority among mid-scale processors. Energy cost volatility and carbon accounting mandates are forcing facility-level decisions on smoking method mix.
Growth Catalysts
- Artisanal menu expansion:Foodservice operators in Germany and the United States are embedding smoked gouda and cheddar into prepared meal lines, creating pull-through for specialty dairy distributors.
- REACH-compliant packaging materials:EFSA food contact material rules are accelerating vacuum-seal and paper-wrap format adoption that extends shelf-stable distribution reach.
- Cold-chain infrastructure buildout:Warehouse refrigeration investments across Poland and the Netherlands are reducing temperature-abuse losses in smoked cheese transit.
Market Restraints
- Wood chip supply concentration:Beech and oak smoking wood sourcing clusters in Eastern European forests create input cost volatility during harvest disruptions.
- Regulatory friction from EU Green Deal:Methane reduction documentation requirements add compliance overhead to milk collection and smoking operations without immediate price recovery mechanisms.
- Plant-based cheese substitution:Coconut oil and cashew-based smoked alternatives are capturing shelf space in UK and Scandinavian retail channels.
Strategic Opportunities
- Protected Geographical Indication expansion:EU frameworks for regional smoking protocol certification create margin expansion potential for traditional method producers in Denmark and Sweden.
- E-commerce direct-to-consumer channels:Subscription cheese box platforms in the United States are bypassing traditional distributor markups for artisanal wedge formats.
- Precision fermentation convergence:Dairy protein synthesis technologies are enabling smoke flavor integration without conventional milk supply chain exposure.
Industry Challenges
- Cold-smoking technician scarcity:Master smokehouse operator apprenticeship pipelines in Germany and Wisconsin are failing to replace retiring craft specialists.
- Legacy facility retrofit capex:Converting hot-smoking lines to hybrid cold-smoke capability requires kiln ventilation and humidity control investments that strain processor balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smoked Cheese Market |
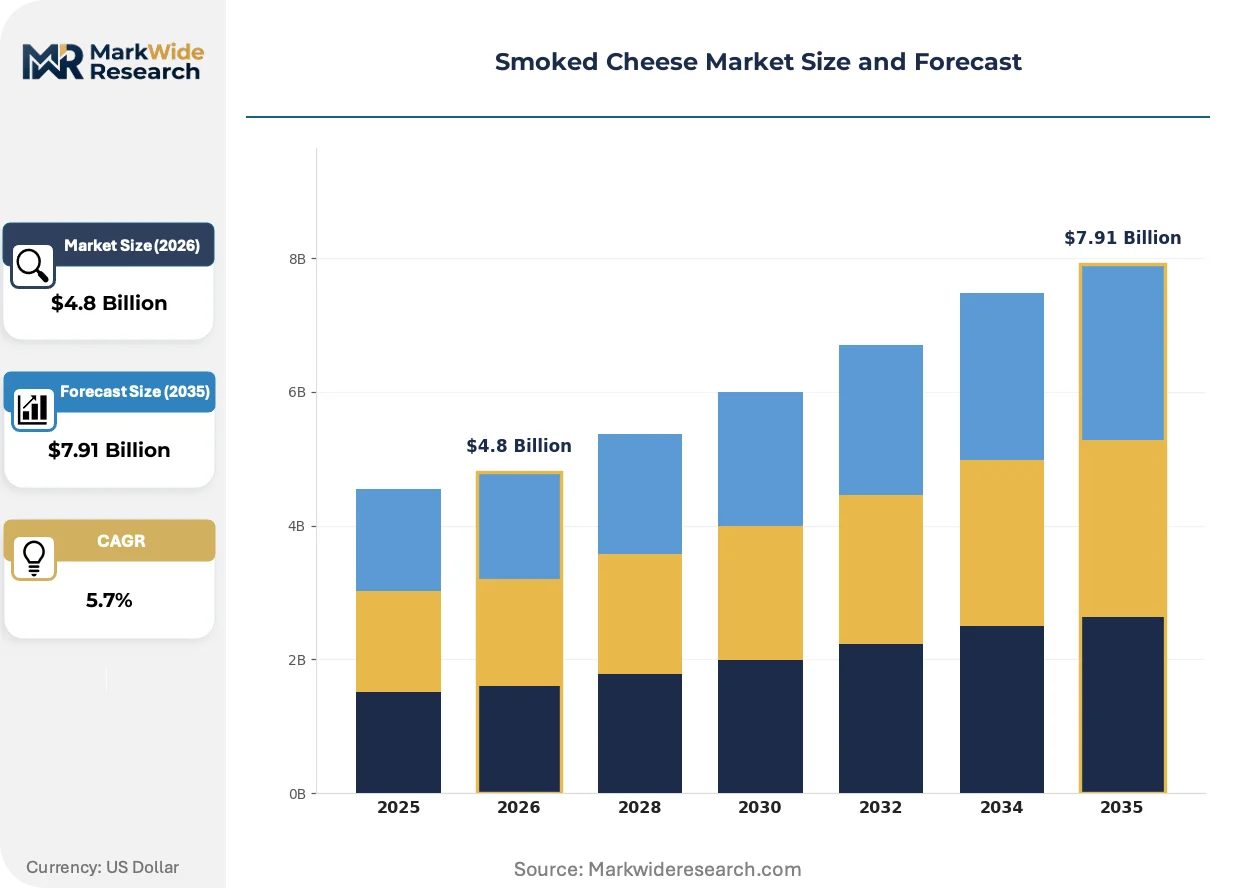
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cheddar, Gouda, Mozzarella, Provolone Packaging Type: Vacuum-Sealed, Blocks, Slices, Shredded Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Foodservice End User: Households, Restaurants, Food Manufacturers, Caterers |
| Companies Covered | Leprino Foods Company, Hilmar Cheese Company, Carr Valley Cheese Company, Gilman Cheese Corporation, Arla Foods, Saputo Inc., Dewlay Cheesemakers, Lioni Latticini, Ludlow Food Centre, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smoked Cheese Market Strategic Shifts
Smoke application technology and regulatory carbon accounting are rewriting facility investment priorities. Consumer transparency demands and channel fragmentation are simultaneously pulling product formats in divergent directions.
Electrostatic smoke deposition systems are decentralizing flavor application away from centralized smokehouse infrastructure. Mid-scale Wisconsin and Dutch processors are adopting these units to maintain batch flexibility without kiln capital commitment. This equipment shift is decentralizing production geography and enabling micro-dairy participation in smoked cheese value chains.
The EU F-Gas Regulation is phasing out hydrofluorocarbon refrigerants in cold-smoking operations, forcing facility retrofits or liquid smoke adoption. Processors in Denmark and Germany face compressed timelines for equipment replacement. Smaller smokehouses are responding with accelerated liquid smoke vaporization technology deployment to bypass refrigeration-dependent cold-smoking entirely.
Buyer concentration among foodservice distributors is compressing supplier negotiation cycles and unbundling technical support from base product pricing. Large pizza manufacturers and deli chains are consolidating purchase volumes through direct processor contracts, displacing traditional distributor intermediaries. This pattern is most visible in North American foodservice procurement, where Leprino-scale suppliers command dedicated line allocation.
Smoked Cheese Market Segmentation
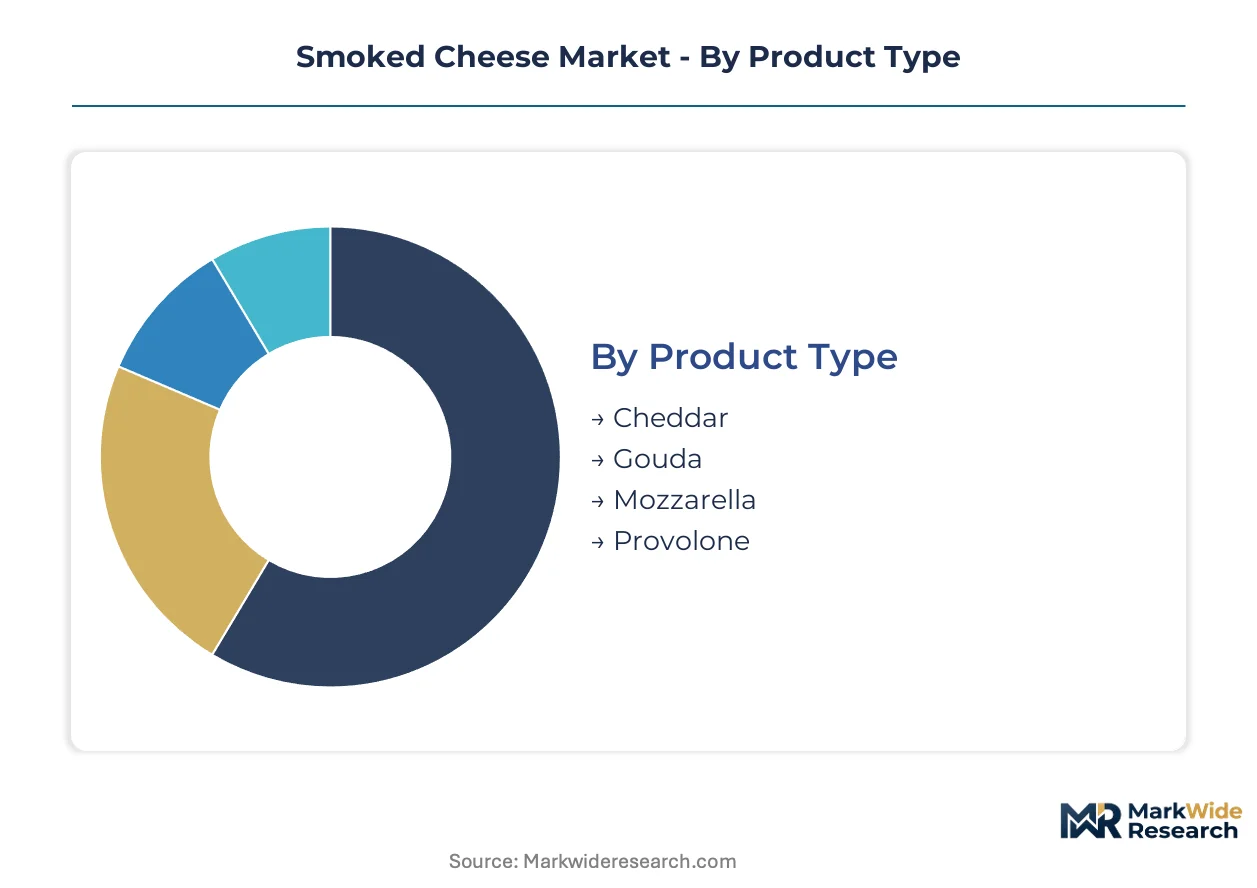
Smoked cheese segmentation reveals divergent margin structures across aging protocols, packaging formats, and channel access tiers. Certification requirements from FDA dairy plant inspections and EU protected geographical indication frameworks create asymmetric compliance burdens that reshape competitive positioning within each category.
Product Type:
FDA dairy plant inspection standards apply universally across all cheese varieties, while EU protected geographical indication frameworks create tiered certification complexity for traditional smoking protocols.
- Cheddar:Aged cheddar develops pronounced phenol interaction during extended cold-smoking below 30°C, creating dense flavor concentration prized by deli counters and charcuterie platters. German retailers command premium positioning for farmhouse cheddar with documented smoke duration exceeding 48 hours.
- Gouda:Dutch-origin gouda leverages cooperative milk sourcing transparency to sustain provenance claims in European retail. Wisconsin processors replicate aging-smoke protocols for North American foodservice distributors seeking consistent melt performance in prepared meals.
- Mozzarella:Low-moisture mozzarella absorbs liquid smoke vaporization efficiently, enabling cost-competitive production for pizza manufacturers demanding standardized flavor delivery.
- Provolone:Italian-style provolone requires specific humidity-controlled smoking kilns that limit producer entry and sustain artisanal price premiums in specialty channels.
Leading the category by volume: Cheddar. Growing fastest: Gouda.
Packaging Type:
REACH-compliant packaging materials and EFSA food contact material rules drive format selection, with vacuum-seal and paper-wrap specifications commanding divergent capital allocation from processors.
- Vacuum-Sealed:Oxygen-barrier films extend shelf-stable distribution reach for foodservice distributors operating across Poland and Netherlands cold-chain networks. Large pizza manufacturers consolidate purchase volumes through direct processor contracts favoring this format.
- Blocks:Retail block formats enable consumer-controlled portioning and aging continuation in home storage, sustaining demand in German and United States supermarket channels.
- Slices:Pre-sliced formats target convenience-oriented households and quick-service restaurant applications where labor cost reduction outweighs per-unit premium.
- Shredded:Shredded smoked cheese captures industrial food manufacturing demand for ready-to-disperse ingredients in frozen prepared meal production.
Vacuum-sealed formats dominate foodservice procurement. Shredded formats expand most quickly in manufacturing channels.
Distribution Channel:
Channel selection determines margin capture and consumer engagement depth, with direct-to-consumer platforms bypassing traditional distributor markups.
- Supermarkets:Mass retail channels concentrate volume throughput for private-label and branded block formats, with shelf space allocation favoring provenance-transparent suppliers.
- Online Retailers:Subscription cheese box platforms in the United States enable artisanal wedge distribution without intermediary markups, though cold-chain integrity requirements limit geographic reach.
- Specialty Stores:Independent retailers stock paper-wrapped wedges for direct consumer engagement, prioritizing Wisconsin-specific aging protocols and regional milk partnerships.
- Foodservice:Distributor consolidation compresses supplier negotiation cycles, with Leprino-scale suppliers commanding dedicated line allocation for mozzarella-based smoked formats.
Foodservice channels lead by volume. Online retailers gain share fastest.
End User:
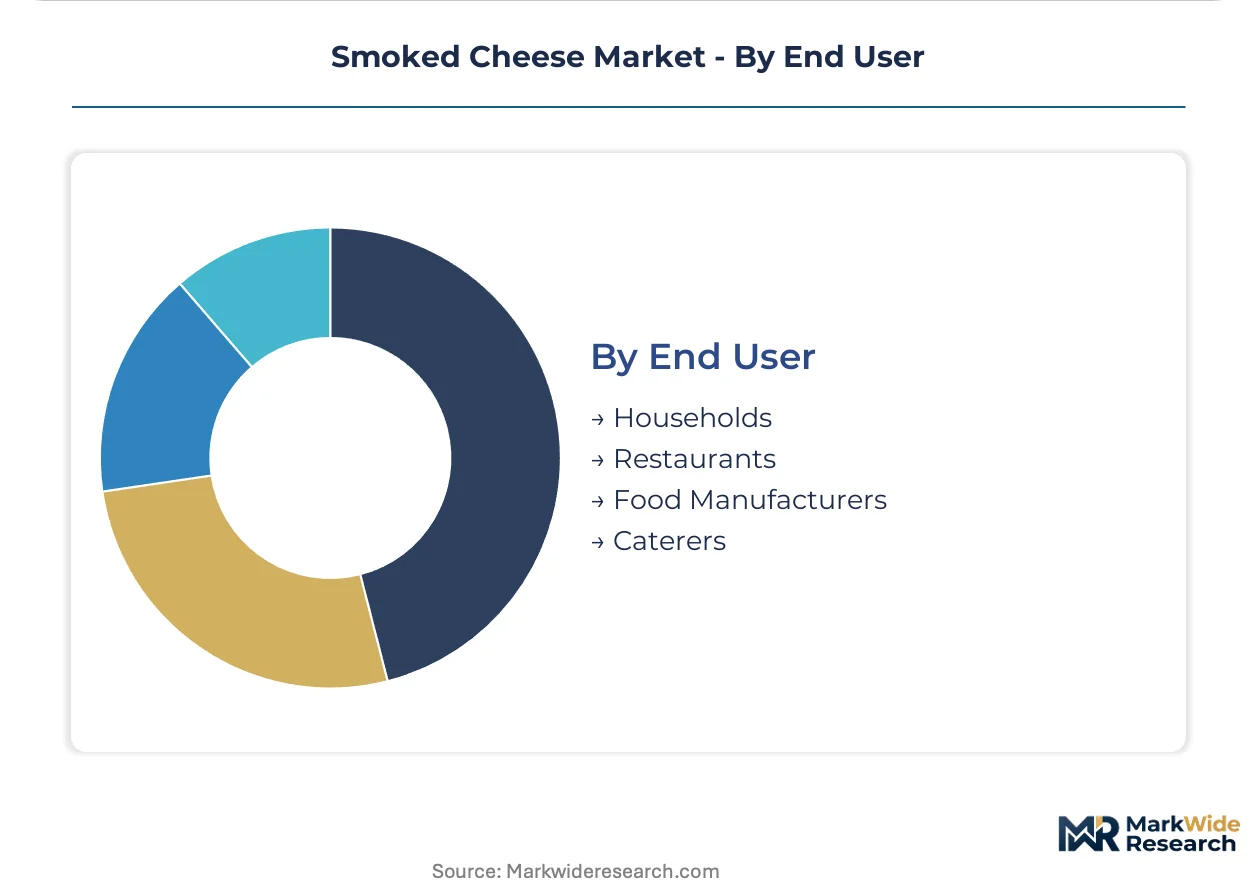
End-user segmentation maps directly to application complexity and price sensitivity, with food manufacturers demanding standardized specifications versus household preference for artisanal variation.
- Households:Consumer purchasers prioritize provenance claims and cold-smoking duration transparency, driving premium positioning for paper-wrapped wedge formats in specialty retail.
- Restaurants:Independent and chain restaurant operators embed smoked gouda and cheddar into prepared meal lines, creating pull-through for specialty dairy distributors with technical support capabilities.
- Food Manufacturers:Industrial processors demand consistent smoke flavor integration for frozen pizza and prepared meal applications, favoring liquid smoke vaporization systems for batch standardization.
- Caterers:Event catering operations require portion-controlled formats and reliable cold-chain delivery, concentrating procurement through foodservice distributors with temperature monitoring infrastructure.
Food manufacturers dominate volume absorption. Restaurants expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wisconsin's dairy corridor anchors smoked cheese production capacity, with German and Dutch processors commanding premium positioning through protected geographical indication frameworks and cooperative milk sourcing networks.
United States
Foodservice distributors consolidate mozzarella-based smoked cheese procurement through direct processor contracts, bypassing traditional intermediaries. FDA dairy plant inspection standards and USDA organic certification requirements shape facility compliance investments. Wisconsin processors cluster around aging-smoke protocol expertise, supplying North American pizza manufacturers and deli chains.
Germany
Traditional cold-smoking methods sustain category loyalty through documented smoke duration claims exceeding 48 hours. The EU F-Gas Regulation compresses refrigeration-dependent infrastructure economics, accelerating liquid smoke vaporization adoption. Master smokehouse operator apprenticeship pipelines in Bavaria face replacement gaps as craft specialists retire.
Netherlands
Cooperative-owned dairy networks span cold-chain infrastructure investments reducing temperature-abuse transit losses. EFSA food contact material rules drive vacuum-seal format standardization for shelf-stable distribution. Gouda processors in the Randstad region leverage provenance transparency for European retail premium positioning.
Denmark
Protected geographical indication frameworks create margin expansion potential for traditional smoking protocol certification. EU Green Deal methane reduction documentation requirements add compliance overhead to milk collection operations. Arla Foods anchors cooperative supply networks across Scandinavian retail channels.
United Kingdom
Subscription cheese box platforms enable artisanal wedge distribution without distributor markups, though cold-chain integrity limits geographic reach. Plant-based coconut oil and cashew alternatives capture retail shelf space in London and Scandinavian-influenced markets. REACH-compliant packaging accelerates format adoption for extended distribution.
Smoked Cheese Market Competitive Environment
Premium-margin players sit above commodity-margin players across provenance documentation, cold-smoking duration transparency, and milk sourcing verification. The vendor base stratifies into cooperative-owned dairy networks, specialty regional processors, and scale-driven mozzarella suppliers. Three archetypes dominate: artisanal smokehouse specialists with protected protocol certification, mid-scale hybrid processors balancing liquid and traditional smoke systems, and commodity-scale suppliers leveraging whey recovery infrastructure. Competitive moves concentrate on geographic indication certification expansion and direct-to-consumer channel bypass.
Within the cooperative-owned tier, Arla Foods exemplifies network-scale supply anchoring across Scandinavian and broader European retail. Among specialty regional processors, Carr Valley Cheese Company and Dewlay Cheesemakers occupy positions defined by Wisconsin-specific and British aging protocol differentiation respectively. At the commodity-scale end, Leprino Foods Company represents cost-position defense through massive whey recovery infrastructure sustaining mozzarella-based smoked format economics.
| Leading Market Players |
|---|
| Leprino Foods Company |
| Hilmar Cheese Company |
| Carr Valley Cheese Company |
| Gilman Cheese Corporation |
| Arla Foods |
| Saputo Inc. |
| Dewlay Cheesemakers |
| Lioni Latticini |
| Ludlow Food Centre |
| Others |
Value Chain & Pricing Dynamics
EU F-Gas Regulation compliance timelines gate qualified supply access and premium-tier pricing power by forcing cold-smoking facility retrofits or liquid smoke conversion investments. Carbon accounting mandates under the EU Green Deal further stratify pricing tiers between documented low-methane milk sourcing and conventional supply chains.
Pricing Analysis
Cold-smoking duration transparency anchors value-based pricing for artisanal tiers, with documented 48-hour protocols commanding substantial premiums over accelerated liquid smoke alternatives. Three-tier pricing structure across premium, standard, and economy levels separates protected geographical indication-certified farmhouse production from cooperative-sourced regional blocks and commodity private-label formats. Cost compression in standard tiers is intensifying because liquid smoke vaporization systems bypass refrigeration-dependent infrastructure entirely. Food manufacturers exhibit highest price sensitivity due to standardized specification requirements, while specialty retailers and direct-to-consumer channels absorb premiums for provenance documentation.
Supply Chain Analysis
Domestic-content mandates in EU protected geographical indication frameworks are reshaping sourcing toward cooperative-owned milk networks in Denmark, Germany, and the Netherlands. Beech and oak wood chip supply draws from Eastern European forest clusters, while liquid smoke concentrate production centers on North American and Western European chemical processing hubs. Single-source vulnerability concentrates in master smokehouse operator apprenticeship pipelines failing to replace retiring craft specialists in Bavaria and Wisconsin. Distribution runs through foodservice distributor consolidation and direct processor contracts for large pizza manufacturers, with specialty retail bypassing intermediaries via subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Master smokehouse operator scarcity props pricing power across traditional cold-smoking tiers, constraining qualified supply expansion regardless of capital availability.
For Market Incumbents: Hedge against liquid smoke substitution by securing protected geographical indication certification for regional smoking protocols in Denmark and Sweden, while simultaneously investing in hybrid facility capability to serve both artisanal and foodservice volume contracts. Cold-smoking technician apprenticeship pipeline collapse threatens capacity expansion in Germany and Wisconsin, making cooperative partnerships with dairy technology institutes the priority lever for talent replenishment. For New Entrants and Emerging Players: Subscription cheese box platforms represent the most penetrable buyer archetype, bypassing entrenched foodservice distributor relationships and capturing premium margins through direct consumer engagement. Precision fermentation-enabled dairy protein synthesis offers a white-space entry path without conventional milk supply chain exposure, targeting UK and Scandinavian retail channels where plant-based alternatives have already conditioned consumer acceptance of non-traditional production methods. For Investors and Strategic Acquirers: Accelerated liquid smoke vaporization technology deployment among mid-scale Dutch and Wisconsin processors is the leading indicator that cold-smoking infrastructure economics have reached an inflection point. Long-term viability favors acquisition targets with hybrid production capability spanning traditional and liquid smoke formats, cooperative milk sourcing contracts, and established e-commerce fulfillment infrastructure. Facility retrofit completion rates in Germany signal when premium-tier supply constraints will ease.| Strategic Initiative | Industry Significance |
|---|---|
| Protected Geographical Indication Certification | EU framework compliance enables margin expansion for Danish and Swedish traditional method producers. |
| Liquid Smoke Vaporization Deployment | Mid-scale processors bypass EU F-Gas Regulation refrigeration retrofit requirements entirely. |
| Direct-to-Consumer Channel Launch | Subscription platforms eliminate foodservice distributor markups for artisanal wedge formats. |
| Cold-Chain Infrastructure Partnership | Polish and Dutch warehouse refrigeration investments reduce temperature-abuse transit losses. |
| Precision Fermentation Integration | Dairy protein synthesis enables smoke flavor delivery without conventional milk supply exposure. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this smoked cheese market assessment, supplemented by primary interviews with dairy plant managers, smokehouse operations directors, foodservice procurement leads, and specialty retail category buyers. FDA dairy plant inspection standards, EU F-Gas Regulation implementation timelines, and EFSA food contact material compliance documentation provided regulatory validation layers. Bottom-up volume triangulation across product type, packaging format, and distribution channel segments reconciled with top-down value estimates derived from cooperative processor revenue disclosures and foodservice distributor contract structures.
Data-stream reconciliation integrated cold-chain infrastructure investment tracking, wood chip supply cluster mapping, and master smokehouse operator apprenticeship pipeline status across the projection horizon. Segmentation dimensions modeled include cheese variety, smoking method, packaging technology, channel access tier, and end-user application complexity. CAGRs were derived from facility capacity expansion announcements, cooperative milk collection volume trends, and foodservice menu embedding rates for smoked gouda and cheddar applications. Carbon accounting compliance costs and liquid smoke technology adoption curves served as industry-specific forecast modifiers.
Revisions become necessary when EU Green Deal methane reduction documentation requirements intensify, F-Gas Regulation phase-out timelines accelerate, or precision fermentation dairy protein achieves cost parity with conventional milk supply chains. Forecasts reflect assumptions regarding cold-smoking technician replacement rates, cooperative network stability, and foodservice distributor consolidation patterns. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
North America Condensed Milk Market
Dairy Products
Emmental Cheese Market
Dairy Products
Ready-To-Use Cheese Market
Dairy Products
Drinkable Yogurt Market
Dairy Products
GCC Cheese Market
Dairy Products
Cream and Soft Cheese Market
Dairy Products
Europe Casein and Caseinates Market
Dairy Products
Low Temperature Yogurt Market
Dairy Products
Dry Buttermilk Market
Dairy Products
Europe Yogurt Market
Dairy Products
Fluid Milk Market
Dairy Products
Clotted Cream Market
Dairy Products
United Kingdom Casein and Caseinates Market
Dairy Products
Butter Concentrate Market
Dairy Products
Fermented Dairy Products Market
Dairy Products
Middle East Dairy Market