
 Fermented Dairy Products Market | 2026-2036
Fermented Dairy Products Market Size, Share, and Industry Trends Forecast 2026-2036
Fermented Dairy Products Market Foresight
Probiotic strain licensing is rewriting margin economics for dairy processors seeking value beyond commodity milk. Danone SA leverages its specialized culture libraries to command premium positioning in functional yogurt segments across European pharmacies and Asian convenience chains. Arla Foods Amba sustains cooperative-backed supply security that anchors its fermented cheese volumes in Middle Eastern export markets. Lactalis Group dominates artisanal and industrial cheese production through backward integration into raw milk collection networks across France, Italy, and Poland.
Fermented dairy products comprise milk substrates transformed by defined bacterial cultures—primarily Lactobacillus, Streptococcus, and Bifidobacterium genera—into acidified, shelf-extended, and microbiologically stabilized foods with enhanced digestibility and bioactive peptide profiles. These products serve commercial purposes spanning direct human nutrition, ingredient functionality in processed foods, and probiotic health applications where live culture counts exceed regulatory thresholds. Yogurt occupies the largest margin pool among product types, while kefir generates the fastest growth trajectory as beverage manufacturers integrate it into functional drink portfolios. Within distribution channels, supermarkets still control volume throughput, though online stores are capturing the highest growth rates in subscription-based probiotic delivery models across urban China and South Korea.
FDA standards for Grade A pasteurized milk and EU hygiene regulations under EC 853/2004 govern culture safety, labeling claims, and cross-border trade access for fermented dairy exports into the United States and European Union. China's SAMR enforces GB standards for fermented milk that restrict permissible additives and mandate live culture declarations, shaping formulation decisions for exporters targeting domestic premium segments. India's FSSAI has tightened probiotic count verification requirements, redirecting investment toward in-house laboratory certification capabilities. Stakeholders must monitor evolving strain-specific health claim approvals and carbon footprint disclosure mandates that will determine which fermentation technologies secure preferential retail placement and institutional procurement contracts.
Market Dynamics
Live culture count verification mandates across India, China, and the European Union are forcing dairy processors to reallocate capital from flavor innovation toward in-house laboratory infrastructure and third-party certification partnerships.
Growth Catalysts
- EC 853/2004 hygiene protocols:EU regulations mandating defined bacterial culture safety standards create export-ready compliance frameworks that premium processors leverage for cross-border market access into Middle Eastern retail chains.
- Urban food service concentration:Restaurant and café channels in São Paulo, Shanghai, and Mexico City are expanding kefir-based beverage placements as synthetic additive displacement accelerates in menu formulation decisions.
- Precision fermentation infrastructure:Bioreactor-scale culture propagation systems reduce strain variability and batch failure rates, enabling consistent probiotic titers that satisfy pharmacy-grade yogurt specifications.
Market Restraints
- Raw milk supply concentration:Cooperative-backed collection networks in France, Italy, and Poland limit independent processor access to high-quality substrates, constraining artisanal cheese production scaling.
- FSSAI verification timelines:India's tightened probiotic count certification requirements extend product launch cycles by 8-14 months for exporters lacking in-house analytical capabilities.
- Plant-based culture substrates:Oat and coconut milk alternatives with added bacterial cultures capture shelf space in German and US natural food channels, pressuring conventional dairy fermentation volume.
Strategic Opportunities
- Subscription-based probiotic delivery:Direct-to-consumer models in urban China and South Korea bypass supermarket margin extraction while capturing recurring revenue from health-conscious households.
- Clean-label sour cream formulations:Sodium reduction mandates in processed foods redirect R&D budgets toward reduced-salt cultured dairy ingredients for industrial food manufacturing.
- Carbon footprint disclosure mandates:EU Green Deal-aligned retail placement preferences reward fermentation technologies with verified lower Scope 3 emissions, creating procurement advantages for early adopters.
Industry Challenges
- Strain-specific IP licensing complexity:Proprietary Lactobacillus and Bifidobacterium culture libraries require multi-jurisdictional patent navigation, delaying product formulation decisions.
- Legacy cold chain reconfiguration:Live culture viability requirements demand continuous refrigeration infrastructure upgrades in last-mile distribution networks across tropical climates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fermented Dairy Products Market |
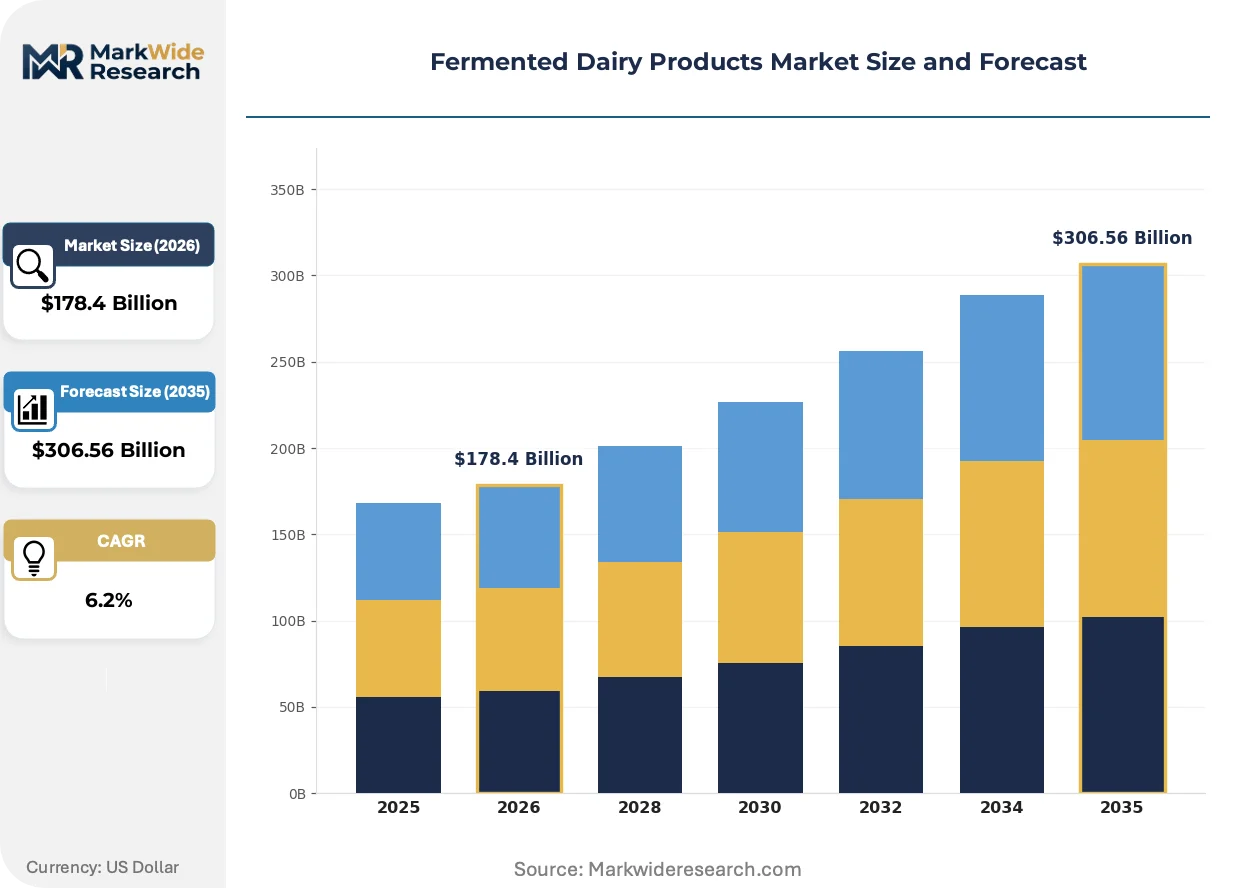
| Market Size in 2026 | $178.4 Billion |
| Market Size in 2035 | $306.56 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Yogurt, Kefir, Cheese, Sour Cream End User: Households, Food Service, Retailers, Food Manufacturers Distribution Channel: Supermarkets, Online Stores, Convenience Stores, Specialty Shops Packaging Type: Glass Containers, Plastic Cups, Cartons, Pouches |
| Companies Covered | Danone SA, Arla Foods Amba, Lactalis Group, Amul, Fonterra, Nestlé, Saputo Inc, Yili Group, Chobani LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fermented Dairy Products Market Shifts & Advancements
Fermentation protocols are converging with digital monitoring systems and precision nutrition science, compressing development timelines while expanding addressable health claim categories beyond basic digestive wellness.
Precision fermentation control systems integrating real-time pH monitoring with automated culture inoculation are hybridizing artisanal production consistency with industrial throughput. Small-batch cheese makers in Denmark and the Netherlands deploy these platforms to maintain terroir differentiation while satisfying supermarket chain volume commitments. The technology is compressing the historical trade-off between scale and microbiological complexity.
China's SAMR enforcement of GB standards for fermented milk additives and live culture declarations is restructuring formulation priorities for exporters targeting domestic premium segments. Multinational processors now maintain parallel product lines: simplified ingredient decks for Chinese regulatory compliance versus fuller flavor profiles for less restrictive markets. Yogurt SKUs with explicit CFU labeling command preferential placement in tier-one city convenience chains.
Health-conscious households in Germany, India, and the United States are rotating toward functional yogurt with verified strain-specific benefits, displacing conventional dessert-positioned dairy purchases. Pharmacy and clinic channels in Seoul and Mumbai now stock refrigerated probiotic yogurts alongside supplements, blurring historical category boundaries. This channel migration rewards processors with clinical trial investments and strains with documented immune or metabolic outcomes.
Fermented Dairy Products Market Segmentation
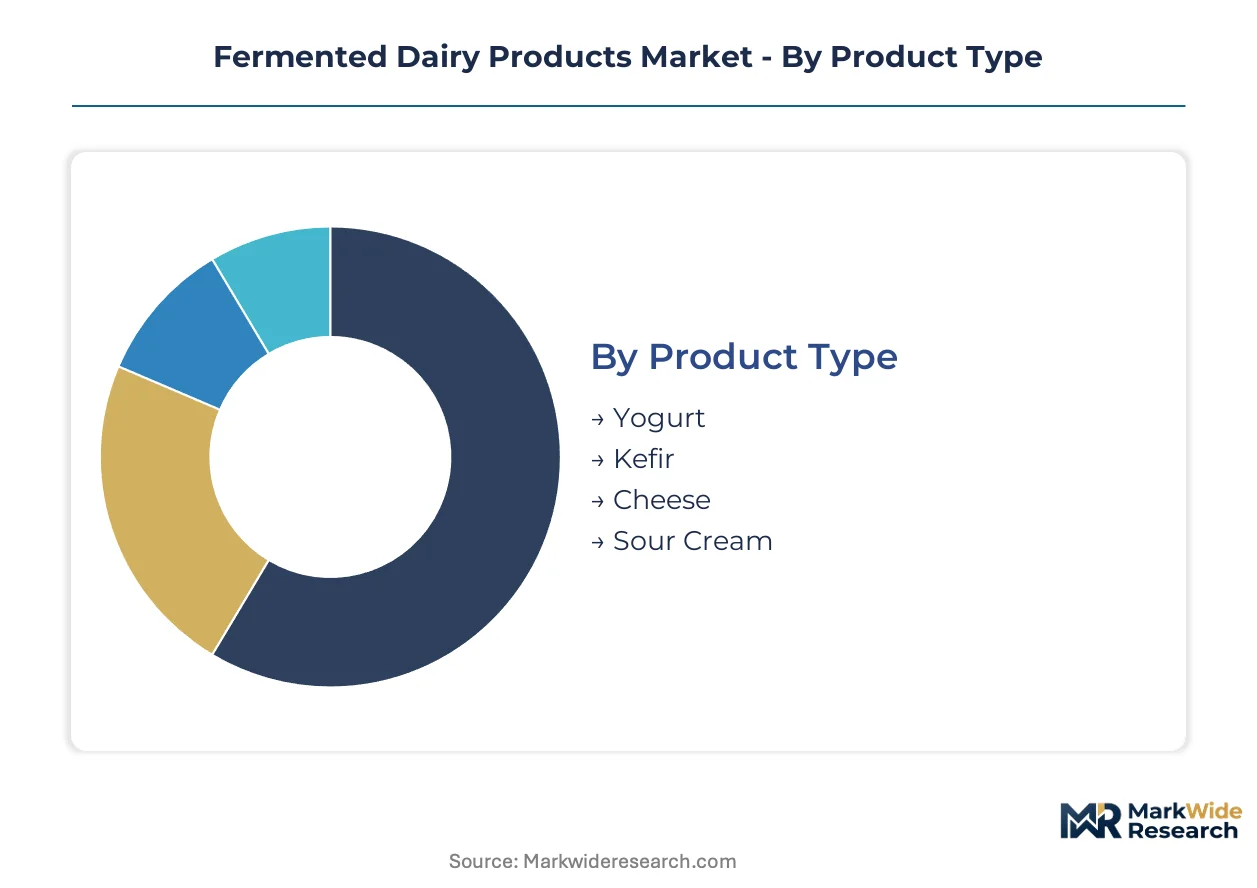
Segmentation in fermented dairy reveals divergent margin pools across product maturity and channel access. Processors optimize formulations differently for pharmacy-grade probiotic delivery versus commodity food service supply, while packaging choices increasingly reflect cold chain infrastructure limitations in tropical distribution networks.
Product Type:
Mature categories dominate current revenue capture, though emerging formats are rewriting growth trajectories through functional positioning.
- Yogurt:Acidified milk gel with defined Lactobacillus and Streptococcus cultures producing shelf-stable, high-protein substrates. Pharmacy and clinic channels in Seoul and Mumbai now stock refrigerated probiotic yogurts alongside supplements, displacing conventional dessert-positioned purchases. Yogurt handles the majority of throughput; kefir is the fastest mover on share.
- Kefir:Fermented beverage incorporating yeast and bacterial symbiotic cultures yielding effervescent, drinkable acidity profiles with enhanced bioactive peptide diversity. São Paulo, Shanghai, and Mexico City restaurants are expanding kefir-based beverage placements as synthetic additive displacement accelerates in menu formulation decisions.
- Cheese:Coagulated and cultured milk solids with proteolytic aging developing flavor complexity and extended shelf stability.
- Sour Cream:High-fat cultured cream with mesophilic fermentation delivering tang and viscosity for industrial ingredient applications.
Yogurt commands the largest margin pool through functional health claims; kefir generates the steepest expansion trajectory as beverage portfolios integrate probiotic positioning.
End User:
Customer type determines formulation complexity, with direct consumption requiring live culture verification while industrial buyers prioritize functional ingredient consistency.
- Households:Individual consumers purchasing retail-packaged fermented dairy for direct nutrition, increasingly selecting verified strain-specific benefits over conventional dessert positioning. Germany, India, and United States households are rotating toward functional yogurt with clinical trial documentation.
- Food Service:Restaurant, café, and institutional channels requiring bulk cultured dairy for menu integration and ingredient functionality. Urban concentration in São Paulo, Shanghai, and Mexico City drives kefir-based beverage adoption as synthetic additive displacement accelerates.
- Retailers:Supermarket and convenience chain buyers controlling shelf placement and promotional mechanics for branded fermented dairy portfolios.
- Food Manufacturers:Industrial processors sourcing cultured dairy ingredients for processed food formulation, particularly reduced-salt sour cream applications under sodium limitation mandates.
Households absorb the highest absolute volume; food service is climbing the fastest as urban menu reformulation accelerates.
Distribution Channel:
Channel selection constrains viable packaging formats and temperature control investments, with digital platforms enabling subscription models that bypass traditional retail margin extraction.
- Supermarkets:Multi-brand retail environments with refrigerated display infrastructure controlling volume throughput for mainstream yogurt and cheese categories. Tier-one city convenience chains in China preferentially place SKUs with explicit CFU labeling.
- Online Stores:Direct-to-consumer platforms capturing recurring revenue through subscription-based probiotic delivery models. Urban China and South Korea channels are expanding fastest as health-conscious households bypass supermarket margin extraction.
- Convenience Stores:Small-format urban retail with limited cold chain footprint favoring single-serve packaging and extended shelf-life formulations.
- Specialty Shops:Curated retail environments emphasizing artisanal production, regional terroir, and premium strain-specific positioning.
Supermarkets maintain dominant throughput; online stores are gaining share fastest through subscription mechanics.
Packaging Type:
Material selection balances live culture viability requirements against sustainability positioning and cost constraints across distribution distances.
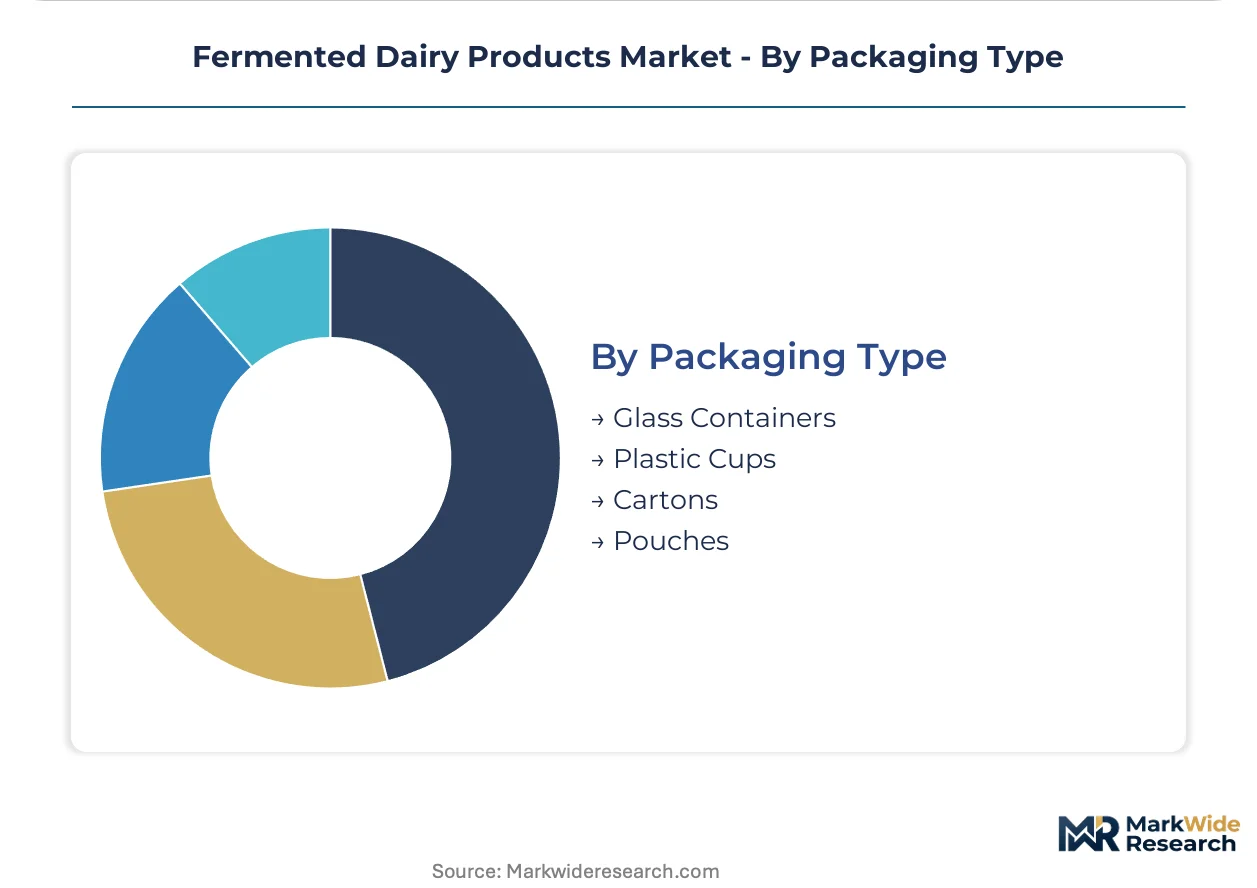
- Glass Containers:Inert, reusable packaging format preserving flavor integrity and supporting premium positioning in pharmacy and specialty channels. Higher weight and breakage rates limit applicability in extended cold chain networks.
- Plastic Cups:Lightweight, sealable single-serve containers dominating supermarket and convenience store yogurt distribution with cost-efficient manufacturing.
- Cartons:Fiber-based multi-serve packaging for ambient-stable fermented dairy beverages with extended shelf-life processing.
- Pouches:Flexible, lightweight format reducing transport cost and enabling novel consumption occasions, particularly in children's probiotic products.
Plastic cups handle majority volume throughput; pouches are expanding most quickly through format innovation and reduced logistics cost.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. German households prioritize pharmacy-grade probiotic verification, while Chinese urban consumers favor subscription-based delivery models. Brazilian food service channels drive kefir adoption as synthetic additive displacement accelerates in menu formulations.
United States
Health-conscious households in metropolitan corridors rotate toward functional yogurt with clinical trial documentation. FDA standards for Grade A pasteurized milk govern culture safety and labeling claims, shaping export-ready compliance frameworks. Pharmacy and clinic channels in New York and Los Angeles now stock refrigerated probiotic yogurts alongside supplements, blurring historical category boundaries.
Germany
Clean-label fermentation protocols redirect R&D budgets toward reduced-salt sour cream formulations under sodium limitation mandates. EU hygiene regulations under EC 853/2004 enforce defined bacterial culture safety standards across member states. Urban food service channels in Berlin and Munich expand kefir-based beverage placements as synthetic additive displacement accelerates.
China
Subscription-based probiotic delivery models capture recurring revenue from health-conscious households in tier-one cities. SAMR enforces GB standards for fermented milk that restrict permissible additives and mandate live culture declarations. Convenience chains in Shanghai and Beijing preferentially place SKUs with explicit CFU labeling, restructuring formulation priorities for exporters.
India
Household demand concentrates in functional yogurt segments as verified strain-specific benefits displace conventional dessert positioning. FSSAI has tightened probiotic count verification requirements, extending product launch cycles for exporters lacking in-house analytical capabilities. Mumbai and Delhi-NCR clusters anchor domestic production capacity for cooperative-backed supply networks.
Brazil
Urban food service channels in São Paulo drive kefir-based beverage adoption as restaurant menu reformulation accelerates. National sanitary surveillance agency protocols align with import market access requirements for cross-border trade. São Paulo's metropolitan concentration anchors both artisanal production clusters and industrial-scale fermentation infrastructure serving Latin American export corridors.
Fermented Dairy Products Market Competitive Landscape
Capability concentration sits with specialized culture library holders; scale advantage sits with cooperative-backed milk collection networks. The market structures around three tiers: multinational processors with proprietary strain portfolios, cooperative federations securing raw milk supply, and regional specialists commanding terroir differentiation. Dominant competitive moves include backward integration into raw milk collection networks and precision fermentation infrastructure deployment for consistent probiotic titers.
Within the multinational processor tier, Danone SA and Nestlé occupy positions anchored by specialized culture libraries and pharmacy-grade distribution access. Cooperative-backed federations exemplified by Arla Foods Amba and Fonterra secure substrate supply security that underpins volume commitments across export markets. Regional scale specialists including Lactalis Group and Yili Group sit within industrial cheese and domestic yogurt segments respectively, leveraging geographic production density for cost positioning.
| Leading Market Players |
|---|
| Danone SA |
| Arla Foods Amba |
| Lactalis Group |
| Amul |
| Fonterra |
| Nestlé |
| Saputo Inc |
| Yili Group |
| Chobani LLC |
| Others |
Supply & Pricing Matrix
Cooperative-backed raw milk collection networks in France, Italy, and Poland concentrate substrate control upstream, anchoring margin capture in pharmacy-grade probiotic yogurt and artisanal cheese tiers where strain verification commands premium positioning.
Pricing Analysis
Long-term offtake contracts between dairy processors and cooperative federations dominate substrate procurement, stabilizing input costs against commodity spot volatility. Three-tier pricing structure across premium, standard, and economy levels separates pharmacy-grade SKUs with CFU labeling from mass-market dessert-positioned yogurts. Cost compression in industrial sour cream is intensifying because sodium reduction mandates require reformulation investment without corresponding price recovery. Food manufacturers exhibit highest price sensitivity due to ingredient cost pass-through limitations, while pharmacy channels demonstrate lowest sensitivity given strain-specific health claim premiums.
Supply Chain Analysis
EU hygiene regulations under EC 853/2004 and China's GB standards for fermented milk function as de facto export-control regimes, restricting culture library flows to compliant processors. Raw material dependencies center on high-quality raw milk substrates, defined bacterial culture libraries, and cold chain refrigeration infrastructure. Single-source vulnerability concentrates in proprietary Lactobacillus and Bifidobacterium strain licensing, where patent holders control access to premium functional positioning. Distribution runs through supermarket refrigerated display networks for volume throughput, with online subscription platforms capturing fastest expansion in urban China and South Korea.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
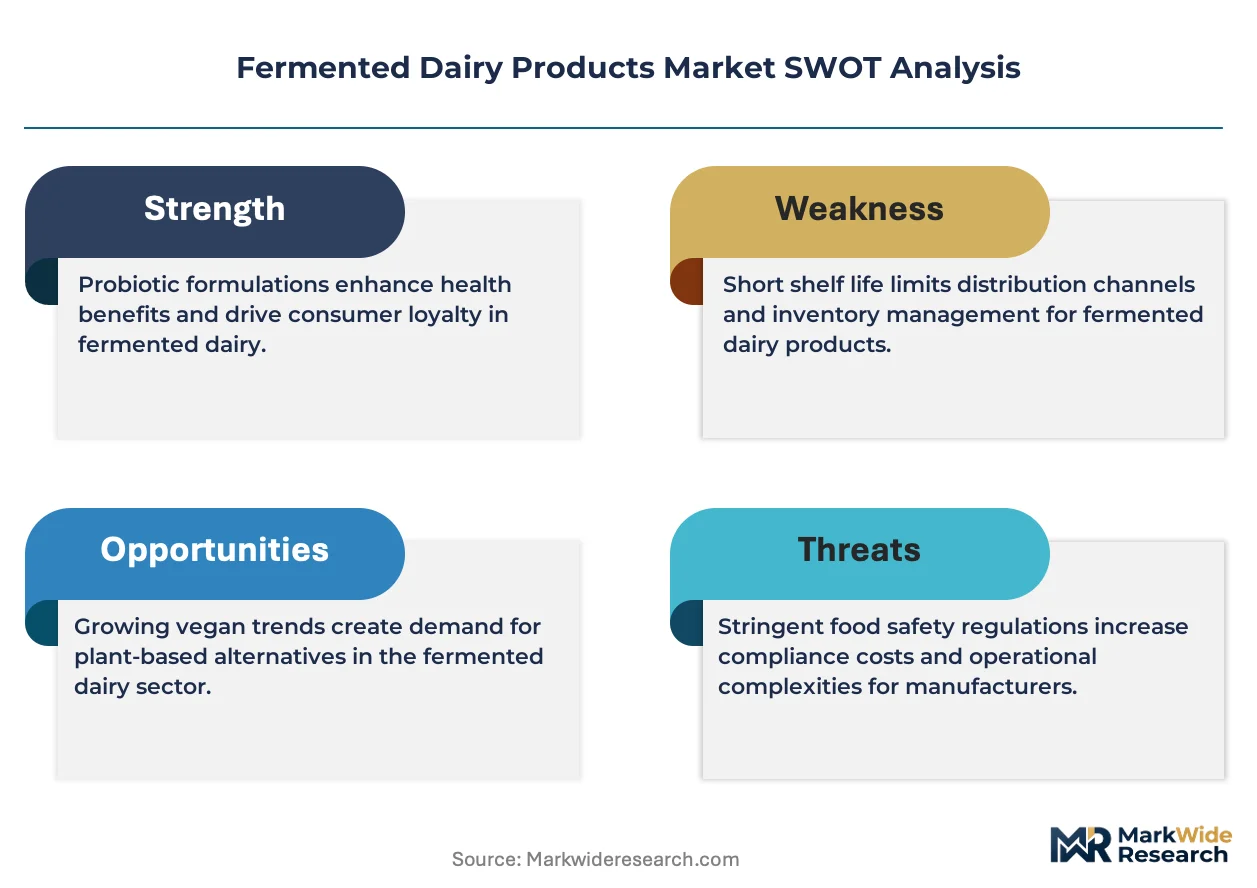
Specialized culture library holdings and precision fermentation infrastructure constitute scarce capabilities that determine competitive positioning, with strain-specific IP and bioreactor-scale propagation systems separating premium processors from commodity milk suppliers.
For Market Incumbents: Entrench position through backward integration into raw milk collection networks across France, Italy, and Poland, securing substrate supply security against cooperative concentration. Deploy precision fermentation infrastructure to reduce batch failure rates and maintain consistent probiotic titers that satisfy pharmacy-grade specifications. Channel control through clinic and pharmacy distribution partnerships defends margin pools against supermarket price erosion. For New Entrants and Emerging Players: Build out direct-to-consumer subscription platforms in urban China and South Korea, bypassing incumbent supermarket margin extraction through recurring revenue models. Target kefir-based beverage white space in São Paulo, Shanghai, and Mexico City food service channels where synthetic additive displacement accelerates menu reformulation. Lead with clean-label positioning and explicit CFU labeling to capture health-conscious household rotation from conventional dessert-positioned dairy. For Investors and Strategic Acquirers: Capital is best deployed toward specialized culture library holders with documented clinical trial investments and pharmacy-grade distribution access, as these assets generate durable premium positioning over the projection horizon. Acquisition target archetype includes precision fermentation infrastructure operators with bioreactor-scale capabilities and verified low-Scope 3 emission profiles aligned with EU Green Deal procurement preferences. Signal to watch is strain-specific health claim approval velocity by EFSA and FDA, which would accelerate pharmacy channel migration and expand addressable premium segments.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Infrastructure Deployment | Bioreactor-scale culture propagation reduces variability and satisfies pharmacy-grade yogurt specifications for Danone SA and Nestlé. |
| Backward Integration into Raw Milk Collection | Arla Foods Amba and Lactalis Group secure cooperative-backed substrate supply security across Middle Eastern export corridors. |
| Direct-to-Consumer Subscription Platform Launch | Urban China and South Korea models bypass supermarket margin extraction while capturing recurring revenue from health-conscious households. |
| Clean-Label Sour Cream Reformulation | Sodium reduction mandates redirect R&D budgets toward reduced-salt cultured dairy ingredients for industrial food manufacturers. |
| Strain-Specific Clinical Trial Investment | Documentation of immune or metabolic outcomes enables pharmacy and clinic channel placement alongside supplements in Seoul and Mumbai. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with dairy processing executives, cooperative federation procurement leads, regulatory affairs specialists at multinational processors, and pharmacy channel buyers in Seoul, Mumbai, and Berlin. Secondary validation drew from FDA Grade A pasteurized milk standards, EU EC 853/2004 hygiene regulations, China's SAMR GB standards for fermented milk, India's FSSAI probiotic count verification protocols, and customs trade data for fermented dairy exports. Bottom-up volume modeling triangulated against top-down value estimates across product type, end user, distribution channel, and packaging format segmentation.
Calibration approaches anchored volume and value outputs across the analysis window through historical growth pattern analysis and elasticity-adjusted demand projection. Segmentation dimensions modeled include product maturity tier, channel access level, regulatory compliance cluster, and cold chain infrastructure availability. CAGRs were derived from regression-adjusted trend extrapolation incorporating urban food service concentration indices and subscription platform penetration rates. Industry-specific forecast inputs encompass live culture count verification timelines and carbon footprint disclosure mandate implementation schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by plant-based culture substrate innovators or precision fermentation biotech entrants would shift outcomes. Material shifts in EFSA strain-specific health claim approval velocity, FSSAI verification timeline compression, or EU Green Deal carbon disclosure enforcement stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
North America Organic Dairy Market
Dairy Products
Russia Whey Protein Market
Dairy Products
Canada Milk Protein Market
Dairy Products
Asia-Pacific Dairy Protein Market
Dairy Products
Camel Dairy Market
Dairy Products
Lactose-Free Sour Cream Market
Dairy Products
Organic Milk Market
Dairy Products
United States Yogurt Market
Dairy Products
Green Tea Butter Market
Dairy Products
UHT Whipping Cream Market
Dairy Products
Global Fortified Dairy Products Market
Dairy Products
Saudi Arabia Camel Dairy Market
Dairy Products
US Yogurt and Probiotic Drink Market
Dairy Products
Probiotic Yogurt Market
Dairy Products
Evaporated Filled Milk Market
Dairy Products
Sweet Whey Market