
 Halal Cheese Market | 2026-2036
Halal Cheese Market Size, Share, and Industry Trends Forecast 2026-2036
Halal Cheese Market Foresight
Asset-light contract manufacturing and third-party halal certification leasing is reconfiguring competitive entry barriers for mid-sized dairy processors. Almarai leverages its captive dairy farming network across the Middle East to secure consistent halal milk supply. Arla Foods sustains European production dominance through dedicated halal-segregated processing lines. Lactalis competes via specialized hard cheese formats tailored to North African export channels.
Halal cheese comprises dairy products manufactured with microbial or plant-derived rennet substitutes and full halal supply-chain verification, ensuring compliance with Islamic dietary law across enzyme sourcing, processing equipment sanitation, and packaging integrity. The product serves commercial foodservice operators and retail consumers requiring guaranteed permissibility under religious guidelines. Soft cheese and processed cheese categories anchor current volume demand due to extended shelf stability and broader recipe compatibility across restaurant and bakery applications. Online retailers represent the fastest-expanding distribution channel as direct-to-consumer halal verification tools reduce purchase friction for diaspora populations.
JAKIM in Malaysia, MUI in Indonesia, and the Emirates Authority for Standardization and Metrology collectively enforce the strictest cross-border halal dairy protocols, with each body maintaining non-mutual recognition that fragments export certification costs. These regulatory silos compel manufacturers to maintain parallel documentation systems and duplicate facility audits for multi-country market access. Stakeholders must monitor emerging blockchain-based halal traceability mandates that promise to consolidate verification costs but demand substantial upstream technology investment.
Market Dynamics
Regulatory fragmentation across halal certification bodies is forcing dairy processors to maintain parallel compliance systems, inflating audit costs and compressing margins for exporters serving multiple Muslim-majority markets simultaneously.
Growth Catalysts
- JAKIM Supply-Chain Traceability Mandate:Malaysia's 2024 enzyme-sourcing disclosure rules compel manufacturers to document rennet origins through blockchain-verified records, creating competitive differentiation for early adopters.
- Quick-Service Restaurant Expansion:Southeast Asian fast-food chains are adding halal-certified cheese SKUs to capture Muslim consumer segments, pulling volume through centralized procurement contracts.
- Microbial Rennet Maturation:Biotech-derived coagulants now match animal rennet performance at commercial scale, eliminating the theological ambiguity that previously constrained product formulation.
Market Restraints
- Non-Mutual Recognition Regimes:JAKIM, MUI, and ESMA maintain incompatible certification standards, compelling exporters to undergo duplicate facility audits for Indonesia, Malaysia, and UAE market access.
- Dairy Input Concentration:Halal milk supply clusters in Saudi Arabia and New Zealand, exposing processors to freight cost volatility and seasonal availability constraints.
- Enzyme Cost Premium:Microbial and plant-derived rennet substitutes command 15-40% price premiums over conventional animal rennet, squeezing margin structures in commoditized cheese categories.
Strategic Opportunities
- Blockchain Traceability Consolidation:Emerging halal verification platforms promise to unify documentation across JAKIM, MUI, and ESMA requirements, reducing compliance overhead for multi-market exporters.
- Diaspora Direct-to-Consumer Channels:Online retailers with embedded halal verification tools are capturing Muslim consumers in non-Muslim majority countries, bypassing traditional retail distribution.
- Specialized Hard Cheese Formats:Extended-shelf-life varieties tailored to North African and Middle Eastern climate conditions and taste preferences remain underdeveloped relative to soft cheese saturation.
Industry Challenges
- Halal Technical Auditor Scarcity:Qualified personnel capable of evaluating both dairy processing and Islamic compliance requirements command premium compensation, constraining certification throughput.
- Segregated Production Line Capital Requirements:Dedicated halal-only equipment and sanitation protocols demand facility reconfiguration investments that mid-sized processors struggle to finance.
- Cross-Border Documentation Latency:Paper-based certificate of analysis transfers between origin dairies, certification bodies, and import authorities create shipment delays and inventory write-downs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Halal Cheese Market |
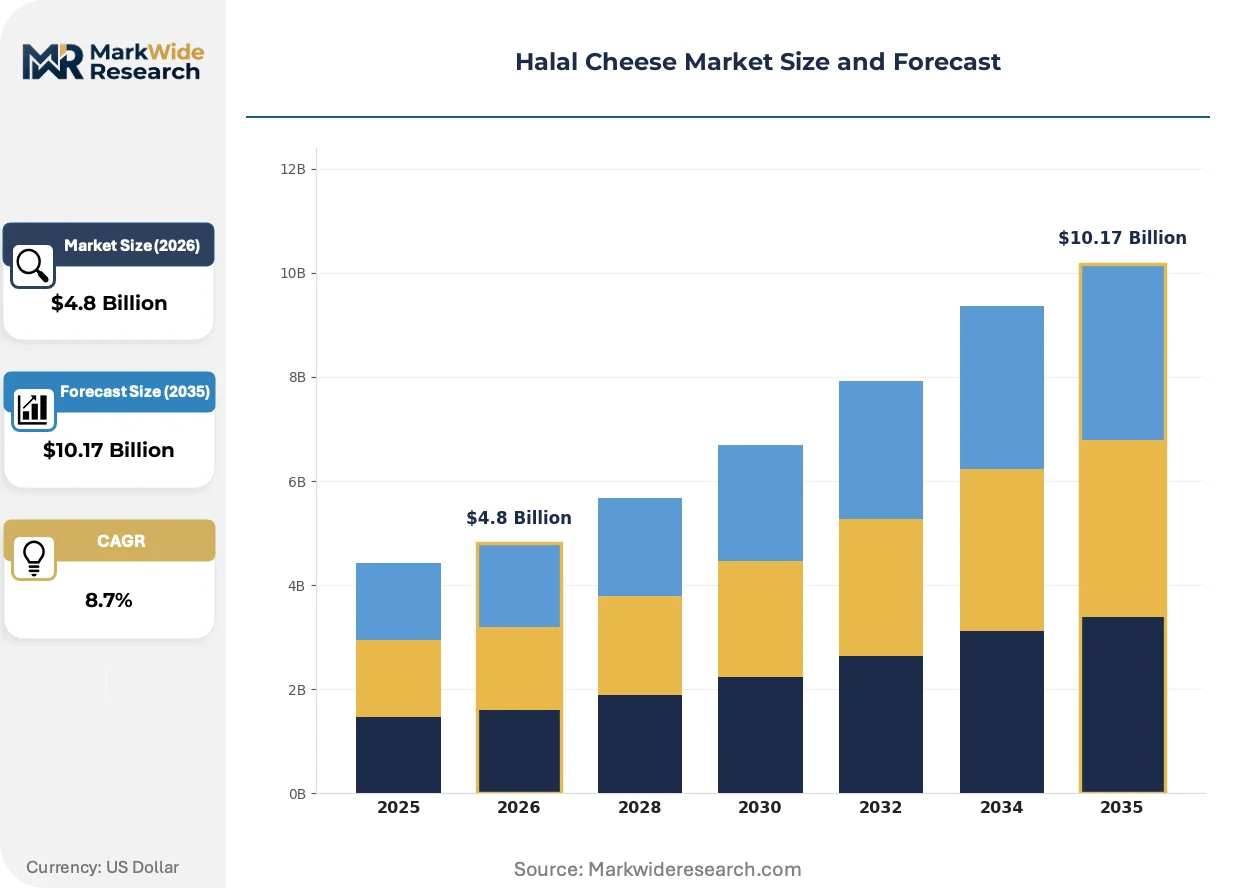
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft Cheese, Hard Cheese, Processed Cheese, Cream Cheese Distribution Channel: Online Retailers, Supermarkets, Specialty Stores, Wholesale End User: Households, Restaurants, Cafes, Bakeries Ingredient Source: Imported, Locally Sourced, Organic, Conventional |
| Companies Covered | Almarai, Arla Foods, Emmi AG, Glanbia Cheese Ltd, Lactalis, FrieslandCampina, Danone S.A., Fonterra, Bel Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Halal Cheese Market Shifts & Advancements
Distributed ledger verification systems are compressing the cost structure of multi-jurisdiction halal compliance, while biotech enzyme advances and channel disintermediation reshape competitive positioning.
Blockchain-based halal traceability infrastructure is virtualizing the documentation burden that previously required parallel paper trails for each certification body. Major dairy cooperatives in Europe and Oceania are piloting shared ledger systems that JAKIM, MUI, and ESMA auditors can access simultaneously. This technology is virtualizing compliance costs by eliminating redundant facility inspections and enabling real-time ingredient provenance verification.
REACH chemical safety disclosures in the European Union are extending to enzyme processing aids used in cheese manufacturing, requiring full material safety data sheet transparency for microbial rennet formulations. Dairy processors exporting to EU markets must now document fermentation substrate origins and processing agent residues. Small and mid-sized halal cheese exporters serving European foodservice channels face the steepest documentation adaptation costs.
Foodservice procurement teams at Southeast Asian quick-service restaurant chains are consolidating halal cheese suppliers to reduce audit complexity, favoring processors with multi-certification coverage. Direct supplier relationships are replacing distributor intermediaries for volume accounts, compressing margin capture by traditional import agents. This concentration is most visible in Indonesia's quick-service restaurant expansion, where centralized procurement mandates now specify dual JAKIM-MUI certification as a baseline qualification.
Halal Cheese Market Segmentation
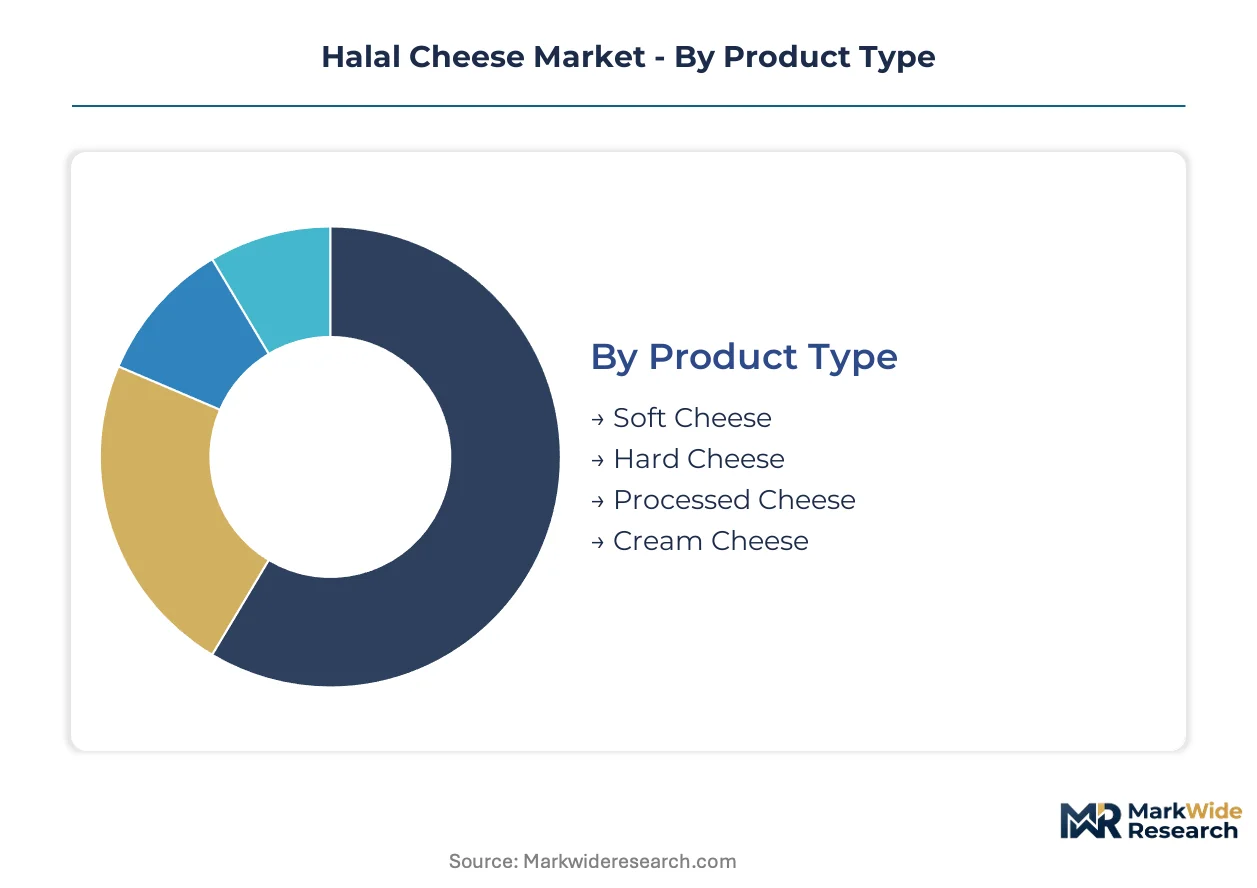
Halal cheese segmentation reveals how religious compliance requirements intersect with conventional dairy economics. Product format and certification complexity create divergent margin profiles across soft, hard, and processed categories. Distribution channel selection determines whether processors capture retail premiums or compete on foodservice volume contracts.
Product Type:
Cost tier differentiation separates commodity formats from value-added varieties with extended certification overhead.
- Soft Cheese:High-moisture varieties including mozzarella and feta require precise temperature control during microbial rennet coagulation. Quick-service restaurant chains in Indonesia and Malaysia specify soft cheese for pizza and pastry applications, pulling volume through centralized procurement tenders.
- Hard Cheese:Extended aging periods demand segregated halal storage facilities with dedicated humidity monitoring systems. North African export channels favor aged cheddar and gouda formats for ambient distribution resilience.
- Processed Cheese:Emulsified formats blend halal-compliant milk solids with vegetable-derived stabilizers for extended shelf stability.
- Cream Cheese:Fresh acid-coagulated varieties serve bakery and dessert channels with shorter production cycles.
Soft cheese commands the established base. The steepest expansion runs through hard cheese formats tailored to climate-stressed distribution corridors.
Distribution Channel:
Application urgency shapes channel selection, with foodservice procurement prioritizing certification reliability over retail browsing convenience.
- Online Retailers:Direct-to-consumer platforms embed JAKIM and MUI verification badges that reduce purchase friction for diaspora populations in Europe and North America. Muslim consumers in non-Muslim majority countries bypass traditional retail entirely through specialized e-commerce portals.
- Supermarkets:Mass retail placement requires dual-shelf positioning alongside conventional cheese, compressing margin capture through slotting fee structures.
- Specialty Stores:Ethnic grocery channels in Malaysia and UAE concentrate authenticated halal SKUs with premium positioning.
- Wholesale:Foodservice distributors aggregate volume for restaurant and bakery accounts with consolidated certification documentation.
Wholesale channels anchor current volume throughput. Online retailers are expanding most quickly as verification technology reduces consumer trust barriers.
End User:
Customer type determines whether procurement prioritizes recipe flexibility or household convenience.
- Households:Retail consumers select packaged formats with visible certification marks for home preparation and religious observance.
- Restaurants:Full-service operators in Saudi Arabia and UAE require batch-traceable halal documentation for menu compliance audits.
- Cafes:Beverage-focused outlets specify cream cheese and processed varieties for beverage topping applications with minimal preparation.
- Bakeries:Industrial-scale pastry producers in Indonesia absorb processed cheese volumes for filled product manufacturing.
Restaurants command the established base. Bakeries show the steepest expansion trajectory as Southeast Asian snack production scales.
Ingredient Source:
Supply concentration risk separates geographically constrained inputs from diversified sourcing strategies.
- Imported:Halal milk powder and rennet concentrates from New Zealand and Saudi Arabia supply processors lacking captive dairy networks.
- Locally Sourced:Domestic milk collection in Malaysia and Indonesia reduces freight exposure but faces seasonal availability constraints.
- Organic:Certified organic halal cheese carries dual compliance overhead, limiting production to specialized cooperatives.
- Conventional:Standard agricultural inputs dominate volume production with lower certification layering.
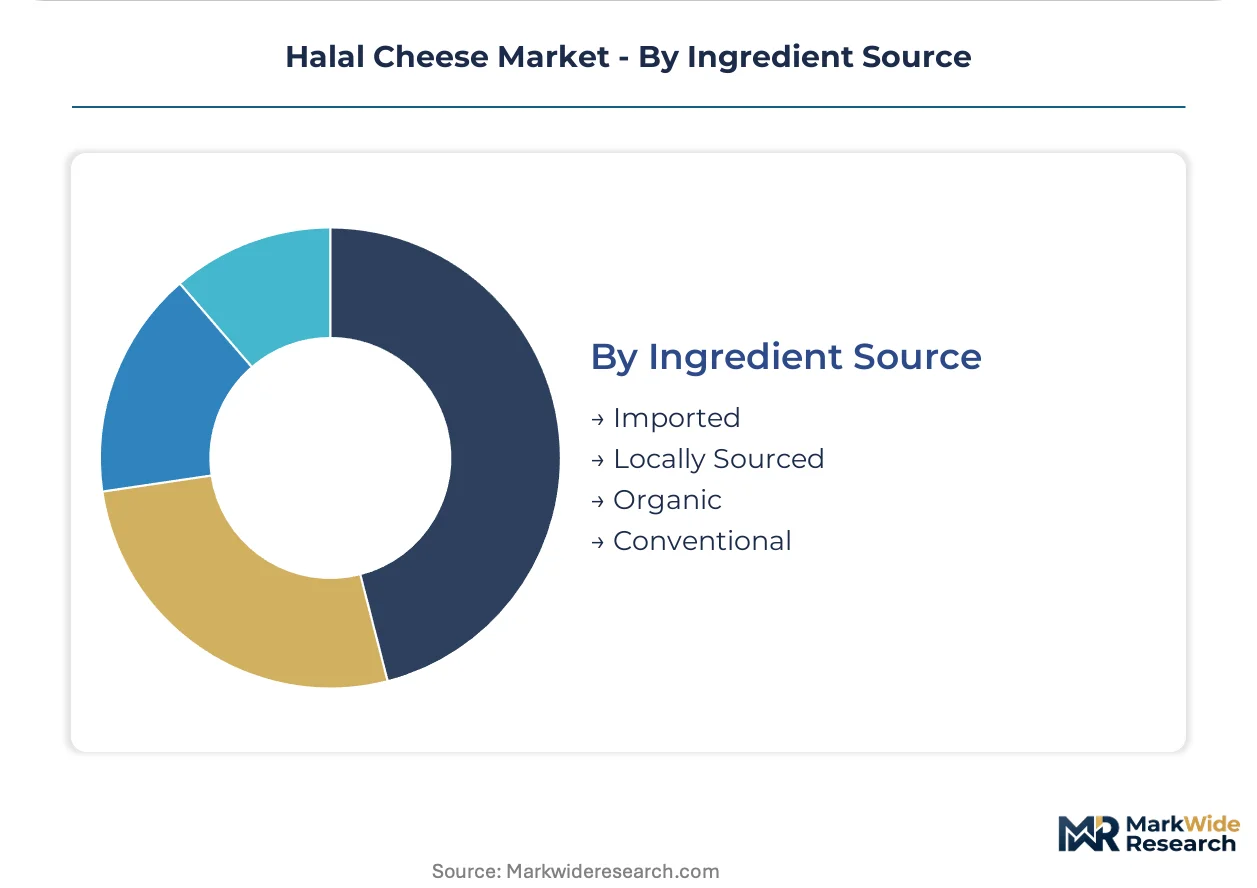
Conventional sourcing commands the established base. Imported inputs are gaining share fastest as processors prioritize supply security over origin proximity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government halal certification mandates across Muslim-majority markets are restructuring dairy trade corridors and forcing exporters to establish localized compliance infrastructure.
Indonesia
Quick-service restaurant chains in Jakarta and Surabaya are consolidating cheese procurement through centralized tenders that specify dual JAKIM-MUI certification. The country's national halal regulator, MUI, enforces strict enzyme disclosure rules for imported dairy products. Industrial bakery clusters in West Java absorb processed cheese volumes for snack manufacturing expansion.
Malaysia
JAKIM's 2024 blockchain traceability mandate for dairy enzymes is compressing export timelines for compliant manufacturers. The Department of Islamic Development Malaysia now requires full supply-chain documentation for rennet sourcing. Penang and Selangor host the densest concentrations of halal-certified dairy processing facilities serving ASEAN re-export channels.
Saudi Arabia
SFDA halal standards align with Gulf Cooperation Council technical regulations, creating a unified compliance entry point for regional distribution. The Saudi Food and Drug Authority mandates segregated production line certification for imported cheese. Riyadh and Jeddah anchor foodservice demand as quick-service restaurant chains expand halal menu offerings.
United Arab Emirates
MOHAP and ESMA maintain non-mutual recognition with Southeast Asian certification bodies, forcing parallel documentation for re-export to Indonesia and Malaysia. The Emirates Authority for Standardization and Metrology enforces ambient storage compliance for hard cheese varieties. Dubai's logistics free zones concentrate halal dairy redistribution to North African markets.
United States
Diaspora populations in Michigan and Illinois are driving direct-to-consumer halal cheese demand through specialized e-commerce platforms. The USDA Organic label overlaps with halal requirements for some consumer segments, though no federal halal standard exists. Chicago and Detroit metropolitan areas host the largest concentrations of ethnic grocery retail stocking authenticated halal SKUs.
Halal Cheese Market Competitive Landscape
On the supply side, the industry is consolidating around three structural tiers: integrated dairy cooperatives with captive milk supply, specialized cheese processors with multi-certification coverage, and contract manufacturers serving private-label retail channels. Strategic archetypes include vertically integrated Middle Eastern dairy giants, European cooperatives with dedicated halal-segregated lines, and asset-light Asian processors leveraging third-party certification leasing. Dominant competitive moves center on backward integration into halal milk sourcing and technology licensing for blockchain traceability compliance.
Within the integrated dairy tier, Almarai anchors supply security through captive farming networks, while Arla Foods exemplifies European production dominance via dedicated facility segregation. Lactalis occupies a position specializing in hard cheese formats for climate-stressed distribution corridors. These three entities represent distinct strategic postures: geographic supply control, processing infrastructure separation, and product-format specialization respectively.
| Leading Market Players |
|---|
| Almarai |
| Arla Foods |
| Emmi AG |
| Glanbia Cheese Ltd |
| Lactalis |
| FrieslandCampina |
| Danone S.A. |
| Fonterra |
| Bel Group |
| Others |
Supply & Pricing Matrix
Halal milk supply clusters in Saudi Arabia and New Zealand concentrate upstream pricing power among processors with captive dairy networks, while downstream margin pools accrue to manufacturers holding multi-certification coverage across JAKIM, MUI, and ESMA jurisdictions.
Pricing Analysis
Certification level creates the primary spread between commodity and premium tiers, with dual JAKIM-MUI coverage commanding 15-40% premiums over single-certification alternatives. Three-tier pricing structure across premium, standard, and economy levels stratifies by enzyme source transparency and blockchain documentation depth. Cost compression in economy-tier processed cheese is intensifying because microbial rennet substitutes face biotech input inflation. Quick-service restaurant chains exhibit lowest price sensitivity due to centralized procurement mandates, while ethnic grocery retailers negotiate hardest on slotting fees.
Supply Chain Analysis
Tariff exposure between Southeast Asian markets and Gulf Cooperation Council members dominates supply chain risk calculus for re-export-dependent distributors. Raw material flows draw from New Zealand milk powder, Saudi captive dairy networks, and European microbial rennet fermentation facilities. Single-source vulnerability concentrates in halal-certified enzyme suppliers with limited geographic diversification. Distribution runs through Dubai logistics free zones for North African redistribution, while direct-to-consumer channels bypass traditional wholesale layers entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Halal cheese penetration in non-Muslim majority diaspora markets remains early-cycle, with embedded verification technology on e-commerce platforms accelerating adoption curves among Muslim consumers in Europe and North America.
For Market Incumbents: Harden certification moats by securing blockchain traceability infrastructure ahead of mandatory JAKIM disclosure deadlines. Deepen backward integration into captive halal milk supply to insulate margin structures from New Zealand freight volatility. Prioritize dual JAKIM-MUI coverage to capture Indonesian quick-service restaurant procurement consolidation. For New Entrants and Emerging Players: North African hard cheese distribution corridors remain underpenetrated relative to saturated soft cheese segments in Southeast Asia. Specialty aged formats tailored to ambient climate resilience offer the most penetrable white space. Launch through Dubai free zone redistribution hubs to access multi-country market exposure without parallel facility audits. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European dairy cooperatives holding dedicated halal-segregated production lines but lacking Southeast Asian certification coverage. Five-to-ten-year viability hinges on regulatory consolidation across JAKIM, MUI, and ESMA blockchain mandates. Monitor halal technical auditor compensation inflation as the inflection signal for certification throughput constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Traceability Implementation | JAKIM's 2024 mandate compresses timelines for compliant manufacturers seeking competitive differentiation. |
| Multi-Certification Coverage Expansion | Dual JAKIM-MUI qualification captures Indonesian quick-service restaurant procurement consolidation. |
| Backward Integration into Halal Milk Supply | Captive dairy networks in Saudi Arabia insulate processors from New Zealand freight cost volatility. |
| Hard Cheese Format Specialization | Extended-shelf-life varieties address underdeveloped North African ambient distribution channels. |
| Direct-to-Consumer Channel Development | Embedded verification tools on e-commerce platforms reduce purchase friction for diaspora populations. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with dairy processing executives, halal certification auditors, and quick-service restaurant procurement directors; and secondary validation against JAKIM regulatory filings, MUI enzyme disclosure databases, and customs trade records. Bottom-up volume triangulation across product format segments was cross-checked against top-down market sizing from cooperative production disclosures.
Forecast inputs considered microbial rennet maturation curves, blockchain traceability adoption rates, and quick-service restaurant expansion timelines across the projection horizon. Segmentation dimensions modeled include product format, certification jurisdiction, distribution channel, and end-user application. CAGRs were derived from slope analysis of historical penetration patterns adjusted for regulatory mandate acceleration.
The forecast holds incumbent behavior within observed patterns; aggressive moves by asset-light contract manufacturers with third-party certification leasing would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Europe Cow Milk Minerals Market
Dairy Products
Probiotic Cheese Market
Dairy Products
Whipping Cream Market
Dairy Products
Dry Whole Milk Powder Market
Dairy Products
Camel Dairy Market
Dairy Products
North America Anhydrous Milk Fat Market
Dairy Products
Fat-Filled Milk Powder Market
Dairy Products
Goat Milk Products Market
Dairy Products
High Protein Yogurt Market
Dairy Products
Canada Casein and Caseinate Market
Dairy Products
Recombined Milk Market
Dairy Products
Reduced Lactose Whey Market
Dairy Products
Global Quark and Fromage Frais Market
Dairy Products
Milk Mineral Market
Dairy Products
US and Europe Nuts and Seeds Cheese Market
Dairy Products
Buttermilk Powder Market