
 Goat Milk Market | 2026-2036
Goat Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Goat Milk Market Outlook
EU dairy hygiene regulations is hardening the cost-of-entry calculus for new processors entering the goat milk value chain. Emmi Group leverages its Swiss processing heritage to sustain premium positioning across European retail channels. Xi'an Baiyue Goat Dairy Group anchors its operations on domestic herd consolidation and powdered milk specialization for the Chinese market.
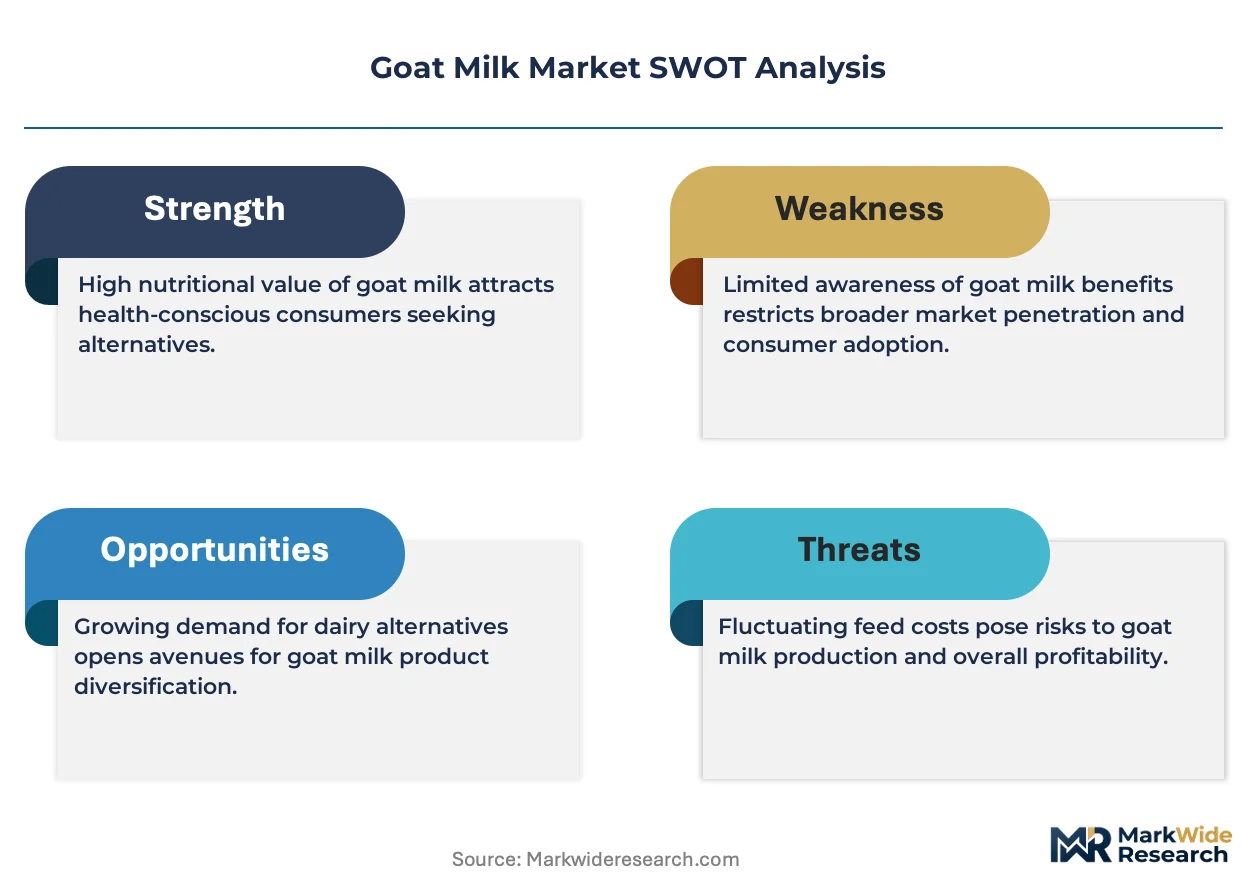
Goat milk is the lacteal secretion obtained from domestic goats (Capra hircus), containing approximately 3.5% protein, 4.1% fat, and 4.5% lactose by weight, with smaller fat globules and distinct casein micelle structures that enhance digestibility compared to bovine milk. The liquid serves commercial purposes ranging from direct consumption to specialized infant formula, aged cheese production, and functional nutraceutical applications. Powdered milk commands the dominant value share within product type segmentation due to extended shelf stability and concentrated export logistics. Infant nutrition applications absorb disproportionate margin pools as pharmaceutical-grade processing standards and clinical validation requirements create pricing power for certified suppliers.
FDA Grade A Pasteurized Milk Ordinance, EFSA food contact material rules, and China's SAMR dairy registration requirements collectively shape product standards, labeling protocols, and cross-border market access for goat milk derivatives. These frameworks elevate compliance investments while screening out informal producers incapable of sustaining batch traceability and pathogen testing protocols. Stakeholders must monitor evolving novel food designations and allergen disclosure mandates as regulators tighten scrutiny on alternative dairy claims and cross-species labeling accuracy.
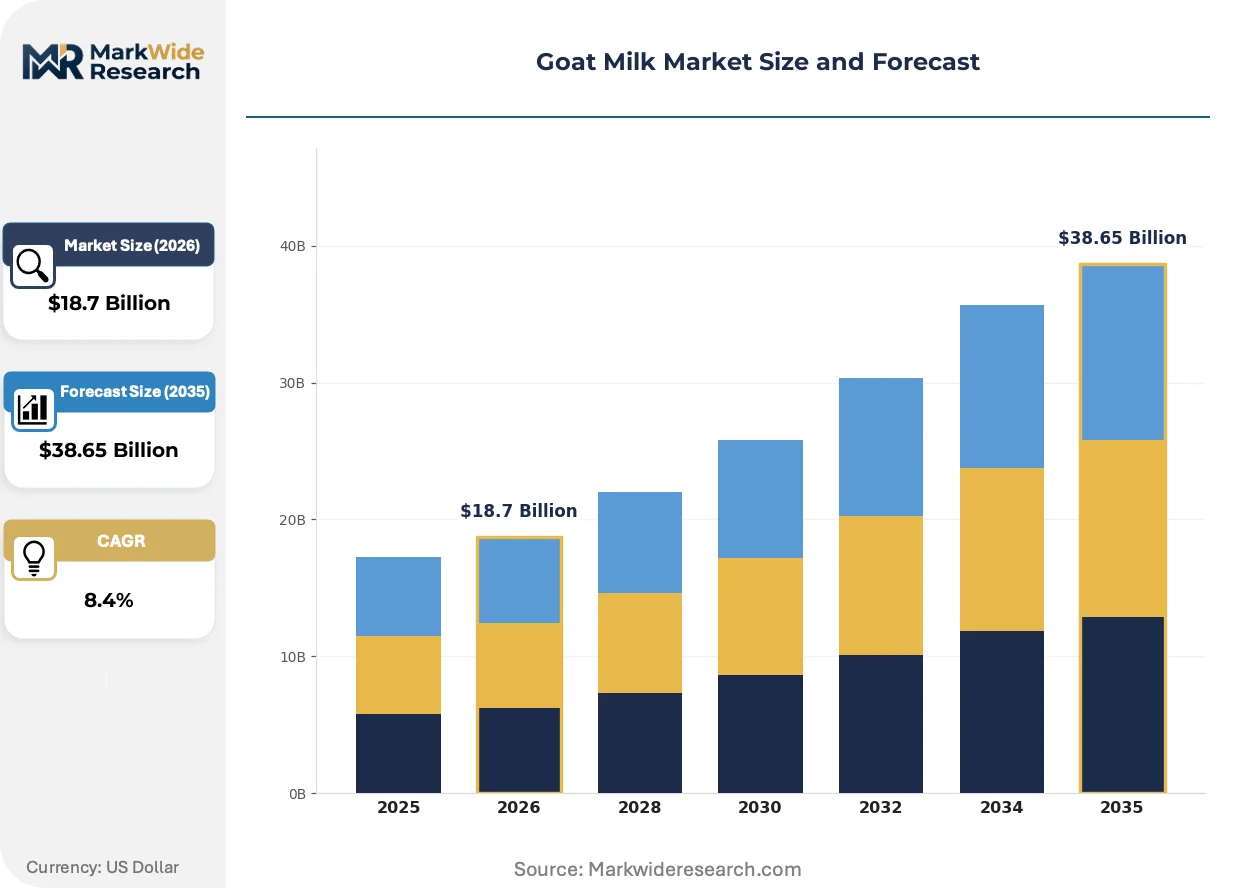
Market Dynamics
EFSA novel food designations and China's SAMR dairy registration requirements are compressing market access timelines while elevating batch traceability standards across the goat milk value chain.
Growth Catalysts
- Infant Formula Premiumization:Pharmaceutical-grade processing standards for pediatric nutrition applications create margin expansion for certified suppliers meeting clinical validation protocols.
- REACH-compliant Packaging Migration:European dairy processors are retrofitting production lines to satisfy EFSA food contact material rules for extended shelf-stable formats.
- Artisanal Cheese Cluster Density:France, the Netherlands, and Spain maintain concentrated demand pools for aged goat cheese production, anchoring regional procurement volumes.
Market Restraints
- Seasonal Herd Volatility:Goat milk supply fluctuates with lactation cycles, forcing processors to maintain costly buffer inventories or absorb spot price spikes.
- Dual Certification Burden:Exporters to China must satisfy both GB standards for dairy imports and domestic origin-country hygiene regulations, duplicating compliance overhead.
- Bovine Milk Substitution Pressure:Industrial buyers in commodity dairy applications switch to cow milk derivatives when goat milk premiums exceed formulation tolerance thresholds.
Strategic Opportunities
- Functional Nutraceutical White Space:Bioactive peptide extraction from goat milk proteins offers entry into sports nutrition and geriatric supplement segments with limited incumbent competition.
- Direct-to-Consumer Subscription Channels:Specialty retailers in Germany and Switzerland are building recurring revenue models around fresh goat milk delivery, bypassing conventional wholesale markups.
- SAMR Registration Arbitrage:First-mover foreign suppliers securing Chinese infant formula registration gain protected shelf access before quota saturation tightens.
Industry Challenges
- Veterinary Pharmaceutical Residue Testing:Herd health management protocols must document antibiotic withdrawal periods to satisfy export market MRL standards, extending batch release timelines.
- Spray Dryer Capacity Constraints:Powdered milk specialization requires capital-intensive dehydration infrastructure with long lead times for equipment procurement and installation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Goat Milk Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Milk, Powdered Milk, Cheese, Yogurt Distribution Channel: Supermarkets, Online Retail, Health Food Stores, Specialty Stores End User: Households, Restaurants, Cafes, Dairy Processors Application: Infant Nutrition, Adult Nutrition, Bakery Products, Nutraceuticals |
| Companies Covered | AVH Dairy Trade B.V., Meyenberg Goat Milk, Ausnutria Dairy Corporation Ltd, St Helen's Farm, Dairy Goat Co-operation, Emmi Group, Granarolo S.p.A., Xi'an Baiyue Goat Dairy Group Co.Ltd., Goat Partners International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Goat Milk Market Strategic Shifts
Processing automation and regulatory harmonization are compressing batch-to-market timelines while specialty nutrition applications pull goat milk derivatives into higher-margin formulation categories.
Robotic milking systems equipped with optical somatic cell counters are automating parlour operations across mid-scale European goat dairies. Herd management software integration allows real-time yield optimization. This automation is compressing labour cost structures while improving raw milk consistency for downstream powder processing.
China's GB 19644-2010 dairy powder standards and accompanying SAMR registration renewal cycles are forcing foreign suppliers into recurring compliance investments. Documented traceability from farm gate to finished product now constitutes a non-negotiable market entry ticket. Infant formula manufacturers with established Chinese registrations are absorbing these fixed costs into pricing power that late entrants cannot replicate.
Pediatric allergists in France and Switzerland are steering families toward goat milk-based follow-on formulas as cow milk protein intolerance diagnoses accumulate. Pharmacy channel placement is displacing conventional grocery distribution for these premium positioning strategies. This channel migration concentrates margin capture with clinically credentialed suppliers capable of substantiating digestibility claims through published trials.
Goat Milk Market Segmentation
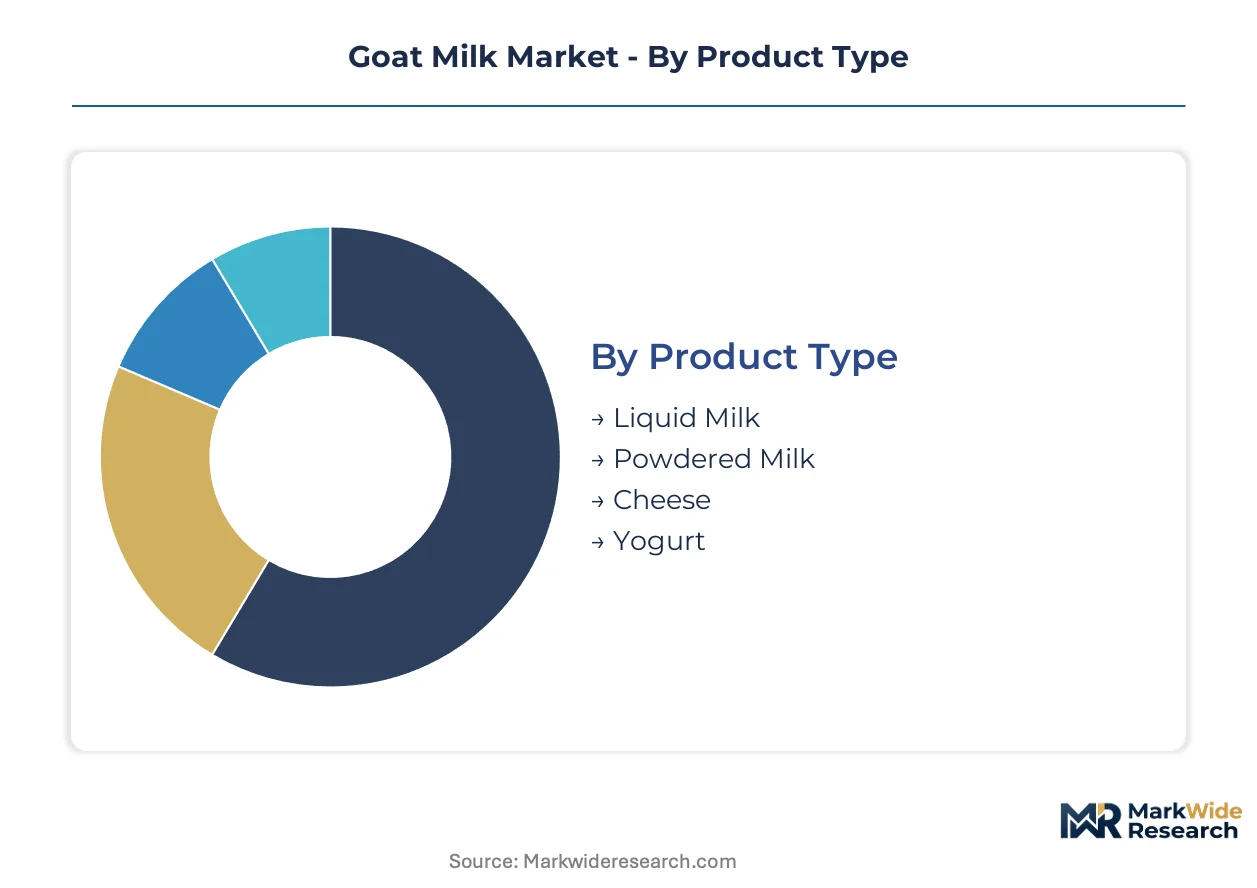
Goat milk derivatives occupy distinct value tiers based on processing intensity and shelf stability requirements. Powdered formats command logistics advantages for cross-border trade, while fresh liquid segments anchor regional procurement relationships with shorter lead times.
Product Type:
Volume concentration favors dehydrated formats, yet margin pools concentrate in aged dairy derivatives requiring extended curing infrastructure.
- Powdered Milk:Dehydrated goat milk with protein content standardized between 25-30% enables ocean freight economics for infant formula manufacturers. Chinese SAMR registration holders leverage this format to satisfy GB 19644-2010 compositional mandates while minimizing cold chain expenditure. Demand clusters with pharmaceutical-grade processors seeking 18-month shelf stability for export markets.
- Cheese:Aged goat cheese production concentrates procurement volumes across France's Poitou-Charentes and Spain's Castilla-La Mancha, where PDO designations protect terroir-based pricing. Lactation cycle volatility forces affineurs to maintain multi-month inventory buffers, elevating working capital requirements relative to fresh dairy segments.
- Liquid Milk:Fresh pasteurized goat milk serves direct consumption channels within 200-kilometer radius of production, constraining scale economics.
- Yogurt:Fermented goat milk products target digestive health positioning in German and Swiss pharmacy retail channels.
Today's leader: Powdered Milk. Tomorrow's challenger: Cheese.
Distribution Channel:
Channel selection determines margin retention versus volume throughput, with regulatory compliance costs filtering informal participants from pharmacy and specialty tiers.
- Supermarkets:Mass retail placement demands UHT processing and multilingual labeling compliant with EFSA food contact material rules. Emmi Group and similar processors leverage Swiss retail relationships to secure refrigerated case positioning for fresh liquid formats, though slotting fees compress net margins below 15%.
- Online Retail:Direct-to-consumer subscription models in Germany bypass wholesale markups while requiring cold chain integrity documentation for cross-border EU shipments. Customer acquisition costs for goat milk specialty products run 2-3x conventional dairy due to allergen-specific targeting requirements.
- Health Food Stores:Pharmacy-adjacent placement in France supports premium pricing for organic-certified goat milk derivatives.
- Specialty Stores:Artisanal cheese mongers in the Netherlands curate regional goat cheese portfolios with provenance documentation.
Supermarkets dominate volume throughput. Online Retail gains share fastest among urban households seeking subscription convenience.
End User:
Procurement scale inversely correlates with formulation flexibility, as industrial processors impose strict compositional specifications unavailable to foodservice operators.
- Dairy Processors:Industrial buyers consolidate goat milk intake for fractionation into protein isolates and lipid derivatives used in sports nutrition formulations. Spray dryer capacity constraints at this tier create supply bottlenecks during Q3 lactation peaks, forcing spot market premiums.
- Households:Direct consumption demand clusters in Alpine regions where goat herding traditions sustain fresh milk availability through cooperative distribution networks. Price sensitivity limits penetration in markets where bovine milk subsidies maintain 40-50% cost advantages.
- Restaurants:Fine dining establishments in Paris and Lyon source farm-specific goat cheese for menu differentiation.
- Cafes:Specialty coffee chains in Switzerland trial goat milk as a foam-stable alternative for lactose-intolerant clientele.
Dairy Processors anchor procurement volume. Households represent the steepest expansion trajectory as pharmacy channel migration accelerates.
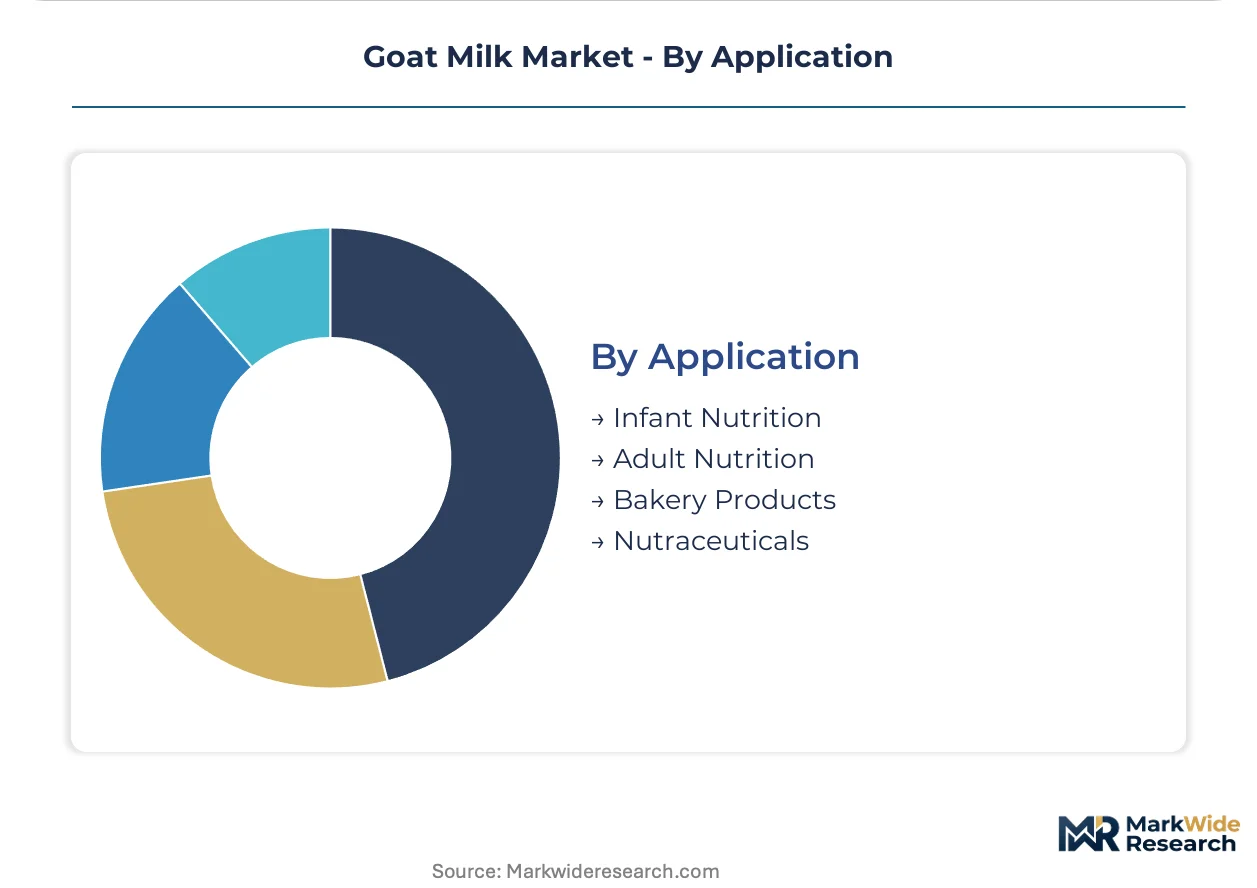
Application:
Clinical validation requirements stratify applications into commodity dairy substitutes versus pharmaceutical-grade nutrition platforms with divergent margin structures.
- Infant Nutrition:Pediatric formula applications demand batch traceability from farm gate through finished product, satisfying China's SAMR registration protocols. Published trials on cow milk protein intolerance substantiate pharmacy channel placement at 3-4x commodity milk pricing.
- Nutraceuticals:Bioactive peptide extraction from goat whey targets sports nutrition and geriatric supplement segments with limited incumbent competition. Caprine-derived immunoglobulins command research-stage premiums as functional ingredient suppliers build clinical dossiers for EFSA health claim submissions.
- Adult Nutrition:Medical nutrition products for malabsorption patients leverage goat milk digestibility in hospital formulary contracts.
- Bakery Products:Industrial bakeries substitute goat milk powder for moisture retention in premium artisanal bread lines.
Infant Nutrition captures dominant margin pools. Nutraceuticals climb the fastest as peptide fractionation technology matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized goat herding communities in France, Spain, and the Netherlands anchor European artisanal cheese production, while China's dairy technicians drive pharmaceutical-grade powder processing expansion.
France
Poitou-Charentes and the Loire Valley sustain dense goat cheese affineur networks producing PDO-certified chèvre. ANSM enforces strict veterinary residue protocols for dairy exports. Parisian pharmacy channels now stock goat milk infant formula at premium price points.
China
Shaanxi Province's herd consolidation programs supply raw material for SAMR-registered infant formula manufacturers. GB 19644-2010 powder standards mandate batch traceability from farm gate. Xi'an processing clusters specialize in dehydration infrastructure for cross-border export.
Spain
Castilla-La Mancha and Murcia host concentrated caprine populations serving Manchego-style cheese production. Spanish food safety authorities align with EFSA novel food designations for functional ingredient claims. Valencia processors are retrofitting lines for extended shelf-stable formats.
Netherlands
Friesland and Gelderland maintain cooperative dairy structures integrating robotic milking systems. Dutch food contact material rules implement REACH-compliant packaging migration standards. Amsterdam specialty retailers curate regional goat cheese portfolios with provenance documentation.
Switzerland
Alpine cantons preserve traditional goat herding through cooperative distribution networks. Swissmedic oversees medical nutrition product registrations for malabsorption formulations. Zurich and Geneva pharmacies command premium positioning for digestibility-validated pediatric formulas.
Goat Milk Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered value pools. The vendor base stratifies between pharmaceutical-grade processors and artisanal cheese affineurs. Three archetypes dominate: Swiss heritage dairies leveraging retail relationships, Chinese herd-integrated powder specialists, and European cooperative federations. Capacity expansion in spray dryer infrastructure and SAMR registration acquisition constitute the primary competitive vectors.
Among Swiss-anchored processors, Emmi Group occupies a heritage-tier position exemplifying premium retail channel penetration. Xi'an Baiyue Goat Dairy Group represents the herd-integrated specialization archetype, with its naming geography signaling Shaanxi Province concentration. Granarolo S.p.A. anchors the Southern European cooperative model, its corporate structure reflecting Italian federation traditions. These three entities exemplify divergent strategic postures: heritage brand leverage, upstream supply control, and regional cooperative scale.
| Leading Market Players |
|---|
| AVH Dairy Trade B.V. |
| Meyenberg Goat Milk |
| Ausnutria Dairy Corporation Ltd |
| St Helen's Farm |
| Dairy Goat Co-operation |
| Emmi Group |
| Granarolo S.p.A. |
| Xi'an Baiyue Goat Dairy Group Co.Ltd. |
| Goat Partners International |
| Others |
Value Chain & Pricing Dynamics
Captive upstream integration into Shaanxi Province herd consolidation anchors both raw material security and infant formula pricing power for Chinese powder specialists. EFSA novel food compliance costs and SAMR registration investments create fixed cost barriers that filter informal producers while concentrating margin capture with certified suppliers.
Pricing Analysis
The bundled infant formula registration service separates from unbundled commodity milk powder spot trading. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade certification levels reflects batch traceability investments and clinical validation documentation. Cost compression in commodity tiers is intensifying because bovine milk substitution pressure forces goat milk processors to absorb spot price volatility. Household direct consumption segments exhibit highest price sensitivity, while infant nutrition manufacturers demonstrate lowest sensitivity due to formulation lock-in effects.
Supply Chain Analysis
Seasonal labor availability constraints in French Poitou-Charentes and Spanish Castilla-La Mancha cheese affineur networks limit production scaling during lactation peaks. Raw material sourcing draws from concentrated caprine populations in Shaanxi Province, the Netherlands' Friesland cooperative belt, and Alpine Swiss cantons. Single-source vulnerability around spray dryer dehydration infrastructure creates supply bottlenecks during Q3 processing surges. Distribution runs through pharmaceutical channel partnerships for infant formula and cooperative networks for fresh liquid formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where China's SAMR registration renewal cycles and EFSA novel food designations continuously elevate compliance investment thresholds, filtering marginal participants while protecting incumbent pricing power.
For Market Incumbents: Hedge against bovine milk substitution pressure by securing backward integration into named PDO cheese affineur networks in France and Spain. Prioritize spray dryer capacity additions in Shaanxi Province processing clusters to capture infant formula export demand before SAMR quota saturation tightens.
For New Entrants and Emerging Players: Enter via functional nutraceutical white space in bioactive peptide extraction for sports nutrition applications, where limited incumbent competition and lower clinical validation burdens enable faster market penetration. Target direct-to-consumer subscription channels in German urban households seeking fresh goat milk delivery convenience.
For Investors and Strategic Acquirers: Roll-up economics work for herd-integrated powder specialists because SAMR registration assets constitute non-replicable market access tickets with protected shelf positioning. Monitor veterinary pharmaceutical residue testing protocol expansions as the inflection signal for compliance cost escalations that will accelerate consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| SAMR Registration Acquisition | Secures protected shelf access in Chinese infant formula channels before quota saturation tightens. |
| Backward Integration into Herd Consolidation | Captures Shaanxi Province raw material security and traceability documentation for export compliance. |
| Spray Dryer Capacity Expansion | Alleviates dehydration bottlenecks during Q3 lactation peaks and enables pharmaceutical-grade powder output. |
| Pharmacy Channel Partnership Development | Displaces grocery distribution for digestibility-validated pediatric formulas in French and Swiss markets. |
| Bioactive Peptide Fractionation Investment | Opens sports nutrition and geriatric supplement segments with limited incumbent competition and higher margins. |
Study Parameters
Direct dialogue with dairy processing executives, herd management specialists, SAMR registration consultants, and pharmacy channel buyers grounded qualitative findings in operational realities. Secondary validation drew from EFSA novel food designations, China's GB 19644-2010 dairy standards, ANSM veterinary residue protocols, and cooperative federation procurement disclosures. Bottom-up volume modeling across herd counts and lactation yields triangulated against top-down value estimates from infant formula pricing data.
Bottom-up segmentation modeling tracked product type, distribution channel, end user, and application dimensions across the projection horizon. CAGRs emerged from regression analysis of historical volume trajectories and regulatory milestone impacts. Forecast inputs incorporated spray dryer capacity installation timelines, SAMR registration renewal cycles, and lactation cycle volatility patterns.
The model holds under stable regulatory enforcement intensity; deviation in EFSA novel food designation expansion pace or SAMR quota allocation shifts would revise volume trajectories. Practitioners should monitor veterinary pharmaceutical residue testing protocol harmonization across export markets for early signals of compliance cost escalation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Africa Dairy Protein Market
Dairy Products
Saudi Arabia Camel Dairy Market
Dairy Products
Smoked Cheese Market
Dairy Products
Asia-Pacific Milk Protein Market
Dairy Products
Condensed Whey Market
Dairy Products
GCC Casein Market
Dairy Products
Recombined Milk Market
Dairy Products
Sweet Whey Market
Dairy Products
Halloumi Cheese Market
Dairy Products
Canada Milk Protein Market
Dairy Products
Buttermilk Powder Market
Dairy Products
Dairy Dessert and Yogurt Market
Dairy Products
United States Milk Protein Market
Dairy Products
Oman Dairy Products and Juice Market
Dairy Products
GCC Fresh Milk Market
Dairy Products
Sheep Milk Cheese Market