
 North America Whole Milk Powder Market | 2026-2036
North America Whole Milk Powder Market Size, Share, and Industry Trends Forecast 2026-2036
North America Whole Milk Powder Market Intelligence
Modular pouch-and-sachet sizing is shifting buyer choice away from bulk institutional bags toward portion-controlled formats that reduce waste in food service kitchens. Dairy Farmers of America leverages its cooperative structure to anchor supply contracts with institutional bakers across the Midwest. Nestle competes through vertical control over infant nutrition formulation, while Land O'Lakes specializes in private-label whole milk powder for retail channels. FrieslandCampina extends its reach via direct sales to North American confectionery producers seeking consistent fat profiles.
Whole milk powder consists of pasteurized whole milk that has been evaporated and spray-dried into a free-flowing powder containing approximately 26-40% milk fat and no more than 5% moisture, serving primarily as a shelf-stable dairy ingredient for recombination, baking, and processed food manufacturing. Instant whole milk powder dominates value generation due to its superior reconstitution properties in beverage applications, while organic whole milk powder captures expanding margin pools as certified dairy operations in Wisconsin and Vermont scale output. The food service end user segment leads volume throughput, though confectionery producers represent the fastest-growing demand pocket as chocolate manufacturers reformulate with whole milk powder to replace liquid dairy logistics.
The USDA Agricultural Marketing Service grades whole milk powder under U.S. Extra and U.S. Standard tiers, while the FDA enforces microbiological limits under 21 CFR 131, and Canada's Canadian Food Inspection Agency applies Safe Food for Canadians Regulations to cross-border shipments. These frameworks elevate compliance costs for smaller processors but create market access advantages for cooperatives with in-house laboratories and grading infrastructure. Stakeholders must monitor pending revisions to FDA dairy plant inspection protocols and potential harmonization pressures between USDA grade standards and Canadian compositional requirements.
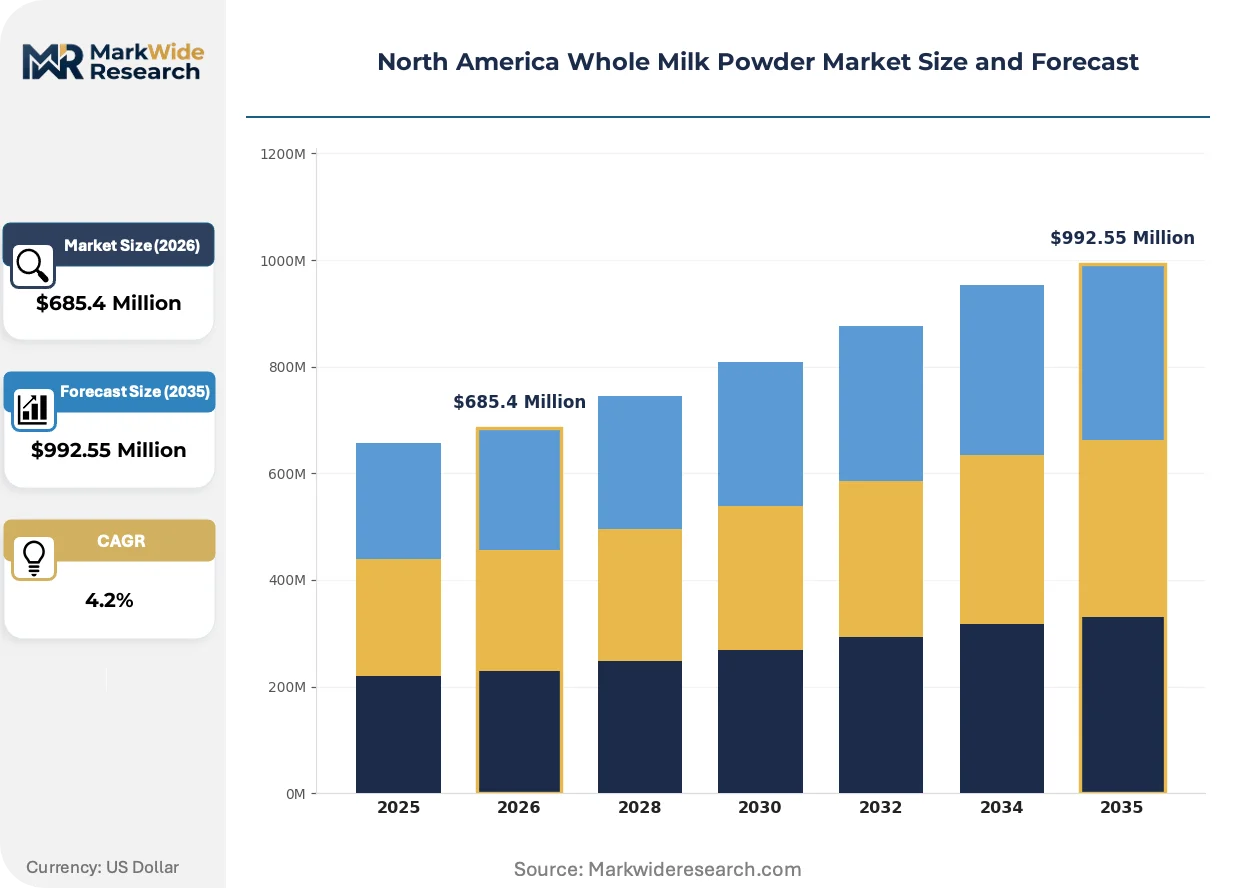
Market Dynamics
USDA grade standard tightening and FDA plant inspection protocol revisions are compressing supplier margins while favoring cooperatives with captive laboratory infrastructure across the Upper Midwest dairy belt.
Growth Catalysts
- Infant formula base demand:Manufacturers in the United States and Mexico are expanding procurement of instant whole milk powder for recombination processes, pulling volume through specialized dairy cooperatives.
- Safe Food for Canadians Regulations:Canada's tightened protein content and microbiological specifications for cross-border shipments are filtering out marginal importers and consolidating trade flows through certified US processors.
- Confectionery reformulation:Chocolate manufacturers are substituting whole milk powder for liquid dairy to eliminate refrigerated logistics, with Wisconsin and Vermont operations scaling certified organic output to capture this demand pocket.
Market Restraints
- Feed cost volatility:Corn and soybean meal price swings transmit directly into milk powder production economics, squeezing margin predictability for non-vertically integrated processors.
- Upper Midwest supply concentration:Dairy Farmers of America and regional cooperatives control the bulk of nonfat solids processing capacity, creating single-source dependency risks for institutional bakers.
- Plant-based dairy substitution:Oat and almond protein isolates are capturing share in beverage recombination applications where fat profile flexibility outweighs dairy authenticity requirements.
Strategic Opportunities
- Vermont organic certification expansion:Certified dairy operations in this sub-region are scaling output to capture expanding margin pools in retail private-label channels.
- Modular pouch-and-sachet formats:Portion-controlled packaging is shifting food service procurement away from bulk institutional bags, opening white space for mid-size processors with flexible filling lines.
- USDA grade harmonization pressure:Pending alignment between US Extra tier standards and Canadian compositional requirements would streamline cross-border contract structuring for qualified suppliers.
Industry Challenges
- Microbiological testing capacity:Smaller processors face capex burdens to deploy in-house PCR screening infrastructure required under evolving FDA dairy plant inspection protocols.
- Instant powder reconstitution IP:Proprietary agglomeration process licensing from European technology holders creates entry barriers for North American entrants seeking beverage-grade product qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Whole Milk Powder Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $992.55 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instant Whole Milk Powder, Regular Whole Milk Powder, Organic Whole Milk Powder, Non-Fat Whole Milk Powder End User: Dairy Manufacturers, Food Service, Retail, Confectionery Producers Packaging Type: Pouches, Tetra Packs, Bags, Cans Distribution Channel: Online Retail, Supermarkets, Wholesale, Direct Sales |
| Companies Covered | Dairy Farmers of America, All American Foods, Land O'Lakes, Nestle, Kraft Foods, FrieslandCampina, Arla Foods amba, Fonterra Co-operative Group, Agri-Dairy Products, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Whole Milk Powder Market Strategic Shifts & Innovations
Spray-drying technology advancement and packaging format diversification are compressing the traditional bulk-to-institutional supply chain, while regulatory grade convergence is reshaping cross-border trade economics.
Instant agglomeration technology is unifying particle structure control with reconstitution speed optimization. Food service beverage manufacturers are adopting these powders at accelerated replacement rates for conventional spray-dried product. This unification is compressing the premium-commodity price spread and forcing standard-grade processors toward specialty fat-profile segmentation.
USDA Agricultural Marketing Service grade standard revisions are elevating protein floor requirements for US Extra tier classification. FDA enforcement of 21 CFR 131 microbiological limits is intensifying plant inspection frequency. Infant formula manufacturers in the United States are responding by locking multi-year procurement contracts with cooperatives possessing integrated grading laboratories.
Buyer concentration among institutional bakers is compressing supplier negotiation leverage and accelerating contract term standardization. Direct sales relationships with confectionery producers are displacing traditional distributor intermediaries in fat-profile-sensitive applications. This pattern is most visible in the Upper Midwest, where Land O'Lakes and FrieslandCampina have established captive supply arrangements with chocolate manufacturers seeking consistent 26-40% milk fat specification.
North America Whole Milk Powder Market Segmentation
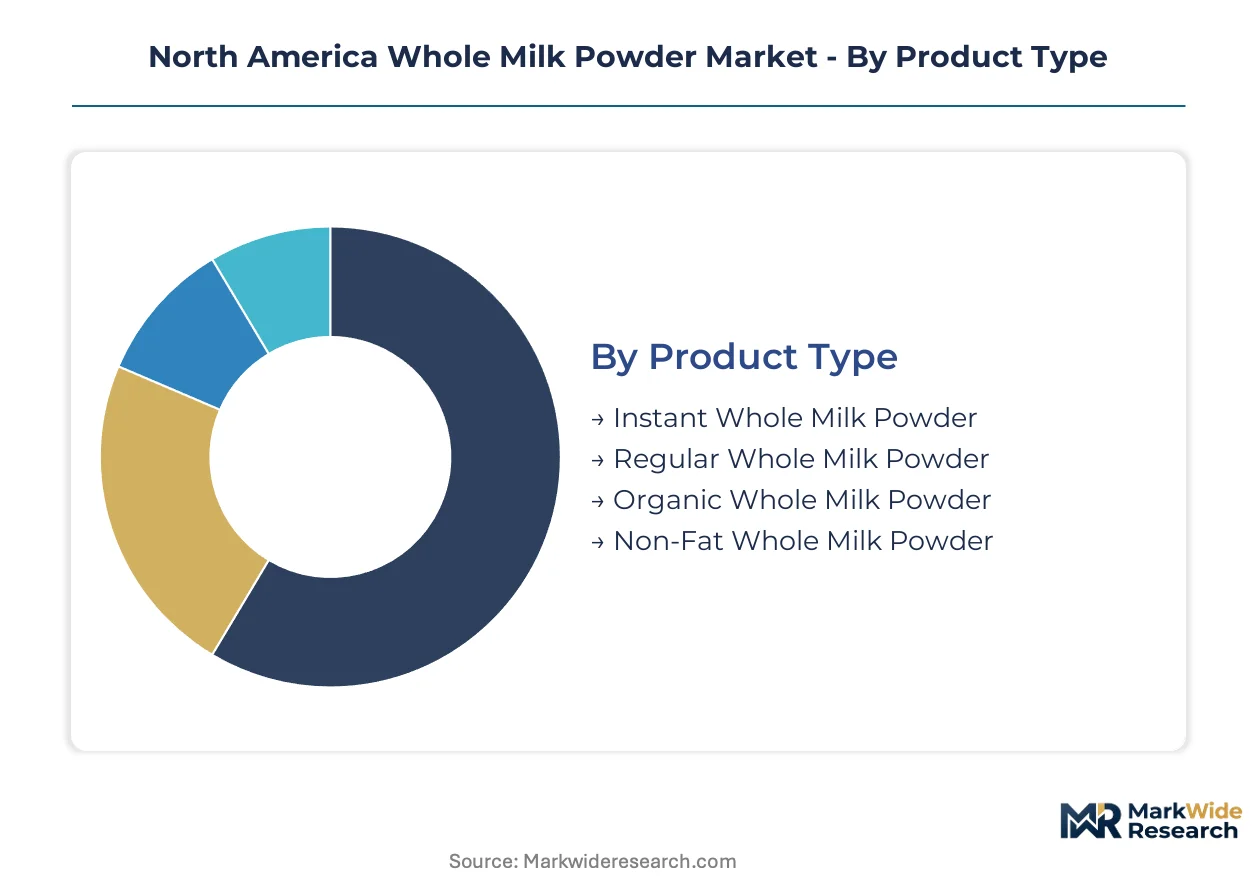
Whole milk powder segmentation in North America reflects divergent capital requirements across processing technologies, packaging formats, and compliance tiers. Product type divisions separate commodity spray-dried output from instant agglomeration lines requiring proprietary European licensing. End-user concentration determines whether processors invest in food-grade laboratory infrastructure or maintain bulk commodity operations.
Product Type:
Instant agglomeration technology demands the heaviest upfront investment due to proprietary particle structure control systems and European process licensing fees.
- Instant Whole Milk Powder:Agglomerated particles with controlled porosity enable rapid cold-water reconstitution without mechanical agitation. Infant formula manufacturers in the United States and Mexico are locking multi-year procurement contracts with cooperatives possessing integrated grading laboratories to secure supply of this grade.
- Regular Whole Milk Powder:Conventional spray-dried powder with standard reconstitution properties serves recombination and baking applications where hydration speed is secondary to cost. Food service kitchens across the Upper Midwest dairy belt specify this grade for hot-beverage preparation where mechanical mixing is available.
- Organic Whole Milk Powder:Certified operations in Wisconsin and Vermont scale output to capture expanding margin pools in retail private-label channels. USDA organic certification and Canadian organic equivalency recognition create cross-border trade advantages for qualified processors.
- Non-Fat Whole Milk Powder:Anomalous category designation capturing reduced-fat formulations for specific confectionery applications. Chocolate manufacturers seeking fat-profile flexibility below the standard 26-40% range specify this grade for recipe calibration.
Most installed capacity flows through Regular Whole Milk Powder. Expansion is steepest in Instant Whole Milk Powder.
End User:
Customer concentration determines contract structure, with institutional volume buyers extracting standardized multi-year terms while specialty segments accept premium pricing for fat-profile precision.
- Dairy Manufacturers:Recombination facilities blend whole milk powder with water and additives to produce fluid milk, yogurt bases, and processed cheese. FDA 21 CFR 131 microbiological enforcement intensifies supplier qualification requirements for this segment.
- Food Service:Portion-controlled packaging shifts procurement away from bulk institutional bags toward modular pouch-and-sachet formats. Kitchen waste reduction mandates drive specification changes across hospital, school, and hotel channels.
- Retail:Private-label whole milk powder for home reconstitution concentrates in club store and online channels. Organic certification commands shelf price premiums in Vermont and Wisconsin metropolitan markets.
- Confectionery Producers:Chocolate manufacturers substitute whole milk powder for liquid dairy to eliminate refrigerated logistics. Direct sales relationships displace distributor intermediaries in fat-profile-sensitive applications.
Dairy Manufacturers absorb the largest volume share. Confectionery Producers are gaining share fastest as reformulation accelerates.
Packaging Type:
Format selection traces directly to end-user handling infrastructure and shelf-life requirements, with capital-intensive filling lines creating tiered entry barriers.
- Pouches:Flexible laminate structures with zipper closures dominate food service portion control. Mid-size processors with adaptable filling lines capture white space as procurement shifts away from bulk bags.
- Tetra Packs:Aseptic brick packaging extends ambient shelf stability for retail export applications. Limited installed base in North America restricts availability.
- Bags:Multi-wall paper or woven polypropylene bulk containers remain standard for institutional dairy manufacturers. Dairy Farmers of America anchors supply contracts using this format across Midwest recombination facilities.
- Cans:Metal containers with nitrogen flushing target premium retail and emergency preparedness channels. Higher unit economics limit penetration outside specialty applications.
Bags retain the dominant installed base. Pouches demonstrate the steepest expansion trajectory as food service kitchens retool procurement.
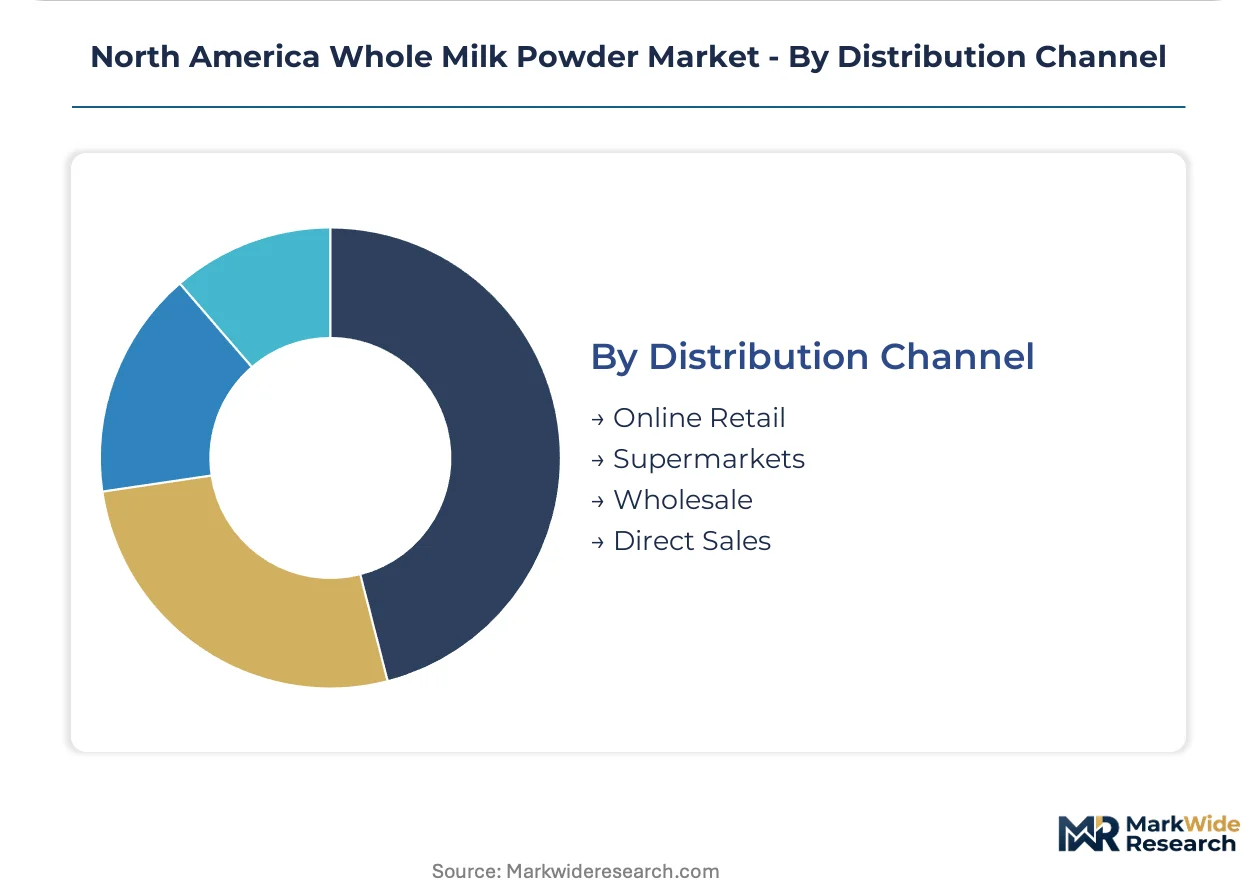
Distribution Channel:
Channel economics separate commodity volume flows through wholesale intermediaries from specialty grade direct relationships where technical specification matters.
- Online Retail:E-commerce platforms aggregate niche organic and specialty fat-profile SKUs for home reconstitution buyers. Subscription models emerge for institutional replenishment.
- Supermarkets:Club store and mass merchant shelf space concentrates private-label offerings from Land O'Lakes and cooperative processors. Slotting fees favor established suppliers with grading laboratory infrastructure.
- Wholesale:Food service distributors and dairy supply houses handle bulk bag logistics for recombination and baking customers. Upper Midwest cooperative concentration creates single-source dependency risks.
- Direct Sales:Confectionery producers establish captive supply arrangements bypassing traditional intermediaries. FrieslandCampina leverages this channel for consistent 26-40% milk fat specification delivery.
Wholesale channels move the largest volume. Direct Sales are climbing the fastest as chocolate manufacturers consolidate supplier relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Whole milk powder processing in North America traces its industrial lineage to post-war dairy cooperative consolidation across the Upper Midwest, where spray-drying infrastructure first scaled to serve military and institutional recombination demand.
United States
Infant formula manufacturers in the Upper Midwest and Southwest are expanding procurement of instant whole milk powder for recombination processes. The FDA enforces microbiological limits under 21 CFR 131, intensifying plant inspection frequency and supplier qualification requirements. Wisconsin and Vermont certified organic operations scale output to capture retail private-label margin pools.
Canada
Cross-border confectionery producers source whole milk powder to eliminate refrigerated logistics in chocolate manufacturing. The Canadian Food Inspection Agency applies Safe Food for Canadians Regulations to tighten protein content and microbiological specifications for imported powders. Quebec and Ontario dairy processing clusters filter marginal importers and consolidate trade flows through certified US processors.
Mexico
Infant formula base demand pulls volume through specialized dairy cooperatives serving recombination facilities. The country's national food safety regulator enforces compositional standards aligned with North American trade integration pressures. Northern border states concentrate import processing infrastructure for US-sourced powder redistribution.
North America Whole Milk Powder Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification tier and laboratory infrastructure access. Cooperative processors with captive grading facilities capture USDA Extra tier premiums while smaller independents compete on standard-grade volume. Three archetypes dominate: vertically integrated dairy cooperatives, multinational nutrition conglomerates with formulation control, and specialized organic certifiers. Capacity expansion and direct sales relationship-building represent the dominant competitive moves as chocolate manufacturers consolidate supplier arrangements.
Within the cooperative archetype tier, Dairy Farmers of America and Land O'Lakes exemplify Upper Midwest concentration with laboratory-anchored supply contracts. Among multinational nutrition specialists, Nestle occupies a position emphasizing vertical formulation control, while FrieslandCampina represents European-origin direct sales penetration into North American confectionery channels.
| Leading Market Players |
|---|
| Dairy Farmers of America |
| All American Foods |
| Land O'Lakes |
| Nestle |
| Kraft Foods |
| FrieslandCampina |
| Arla Foods amba |
| Fonterra Co-operative Group |
| Agri-Dairy Products |
| Others |
Cost & Logistics Intelligence
Institutional bakers and confectionery manufacturers concentrate procurement volume across the Upper Midwest dairy belt, anchoring a contract-based pricing structure where multi-year supply agreements with cooperatives dominate spot-market transactions. USDA Extra tier premiums and FDA compliance certification costs stratify supplier access, compressing margins for non-integrated processors while locking in price stability for buyers with captive laboratory relationships.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates USDA Extra certified instant powder from standard-grade regular product and non-certified commodity output. Price differentiation rests on microbiological testing infrastructure access and organic certification status, with Vermont and Wisconsin organic operations commanding shelf premiums in retail channels. Cost compression in standard-grade segments is intensifying because feed cost volatility transmits directly into milk powder production economics. Food service kitchens exhibit highest price sensitivity due to waste reduction mandates, while infant formula manufacturers accept premium pricing for guaranteed supply security.
Supply Chain Analysis
Direct-to-confectionery channels handle fat-profile-sensitive demand, displacing traditional distributor intermediaries as chocolate manufacturers consolidate supplier relationships. Geographic supply concentrates in the United States Upper Midwest, Canada Quebec-Ontario corridor, and Mexico northern border states. Raw material flows draw from corn and soybean meal feed inputs, dairy cow herd inventories, and spray-drying energy requirements. Single-source vulnerability risks emerge from Dairy Farmers of America and regional cooperative control of nonfat solids processing capacity. Distribution runs through wholesale dairy supply houses for bulk institutional bags and flexible filling lines for modular pouch formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
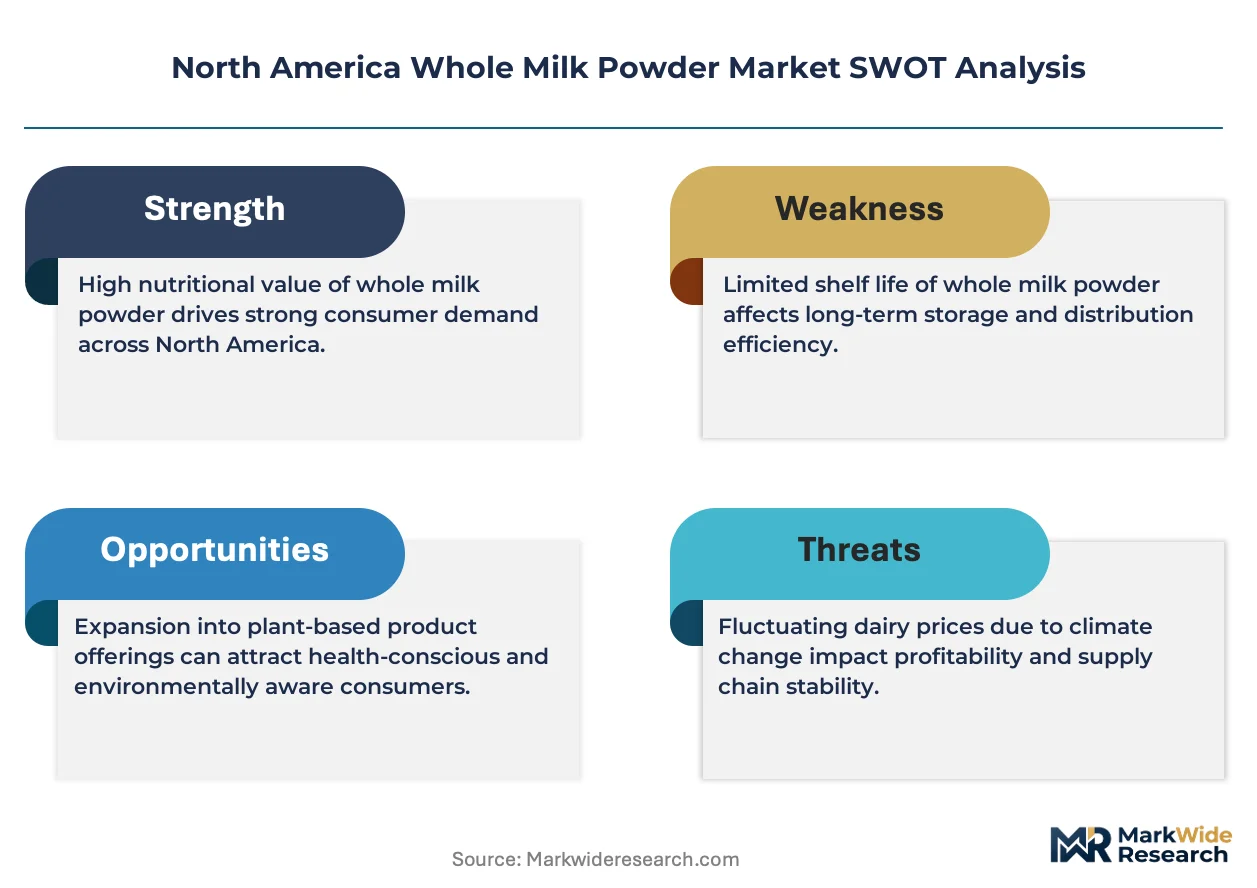
This market functions as a geographic-arbitrage play between US Upper Midwest production costs and Canadian Safe Food for Canadians Regulations compliance premiums, with cross-border certification harmonization poised to reshape contract economics.
For Market Incumbents: Hedge feed cost volatility through backward integration into dairy herd operations or long-term forage supply agreements. Lock multi-year procurement contracts with infant formula manufacturers before FDA dairy plant inspection protocol revisions elevate compliance barriers. Prioritize laboratory infrastructure investment to defend USDA Extra tier positioning against standard-grade competitors. For New Entrants and Emerging Players: Enter via modular pouch-and-sachet format production for food service kitchens retooling procurement away from bulk institutional bags. Target Vermont and Wisconsin organic certification expansion as the most penetrable white space, where certified dairy operations scale output for retail private-label margin pools. Pursue direct sales relationships with mid-size confectionery producers seeking consistent 26-40% milk fat specification outside established cooperative networks. For Investors and Strategic Acquirers: Multinational nutrition conglomerates with vertical formulation control represent the most active acquirer category in this space. Five-to-ten year viability hinges on regulatory grade convergence between US and Canadian standards streamlining cross-border trade. Acquisition target archetype: mid-size processors with flexible filling lines and pending organic certification. Monitor FDA dairy plant inspection protocol revision timing as inflection indicator for compliance cost spikes favoring integrated laboratory operators.| Strategic Initiative | Industry Significance |
|---|---|
| Laboratory Infrastructure Investment | In-house PCR screening capability secures USDA Extra tier access under evolving FDA inspection protocols. |
| Organic Certification Expansion | Vermont and Wisconsin certified operations capture retail private-label margin pools in metropolitan markets. |
| Direct Sales Channel Development | Confectionery producer captive supply arrangements bypass distributor intermediaries for fat-profile-sensitive applications. |
| Modular Packaging Format Adoption | Flexible filling lines capture food service procurement shift toward portion-controlled pouch-and-sachet formats. |
| Cross-Border Certification Harmonization | US-Canada organic equivalency recognition streamlines trade flows through qualified processors. |
Research Approach
Multiple input streams — cooperative procurement managers, confectionery manufacturer R&D directors, food service distribution channel heads, and dairy regulatory affairs specialists — were reconciled with secondary validation from USDA Agricultural Marketing Service grade reports, FDA 21 CFR 131 enforcement records, Canadian Food Inspection Agency cross-border trade data, and SEC filings from publicly traded dairy processors. Bottom-up volume modeling across spray-drying capacity installations and top-down demand segmentation by end-use application were triangulated to produce market estimates.
Data-stream reconciliation applied analytical frameworks across the analysis window, modeling product type segmentation by agglomeration technology, end user concentration by procurement contract structure, packaging format by filling line capital requirements, and distribution channel by buyer negotiation leverage. CAGRs were derived from trend extrapolation of infant formula base demand, confectionery reformulation rates, and organic certification expansion trajectories, stress-tested against feed cost volatility and regulatory inspection frequency assumptions.
Inputs from cooperative supply managers and confectionery procurement directors were available through the study window; gaps in real-time spray-drying capacity utilization data introduce uncertainty bands around short-term supply elasticity estimates. Forecasts reflect documented assumptions regarding FDA protocol revision timing and US-Canada grade standard harmonization progress. Periodic stress-testing of base assumptions against feed commodity price movements and plant-based dairy substitution rates is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Butter Concentrate Market
Dairy Products
Fermented Milk Products Market
Dairy Products
Mozzarella Cheese Market
Dairy Products
UAE Camel Dairy Market
Dairy Products
Saudi Arabia Dairy Products Market
Dairy Products
Europe Milk Protein Market
Dairy Products
Fruit Yogurt Market
Dairy Products
Global Yogurt Powder Market
Dairy Products
Goat Milk Market
Dairy Products
Nonfat Dry Milk Market
Dairy Products
Probiotic Yogurt Market
Dairy Products
Butter Fat Fraction Market
Dairy Products
Cheese Shreds Market
Dairy Products
Recombined Milk Market
Dairy Products
Dry Whole Milk Powder Market
Dairy Products
North America Condensed Milk Market