
 Low Temperature Pasteurized Milk Market | 2026-2036
Low Temperature Pasteurized Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Low Temperature Pasteurized Milk Market Insights
GB 19645 pasteurization certification is bifurcating the competitive landscape between national dairy conglomerates and regional cold-chain specialists. Inner Mongolia Yili Industrial Group Co., Ltd. leverages its vertically controlled pasture-to-shelf infrastructure to dominate shelf placement in tier-one supermarkets. Hartzler Family Dairy anchors its position through Amish-country brand authenticity and direct farm-to-door subscription channels. Meiji Holdings Co., Ltd. competes on ESL technology leadership, extending product freshness windows without additive use.
Low temperature pasteurized milk undergoes heating to 63-65°C for 30 minutes or 72-75°C for 15-20 seconds, preserving lactoferrin and immunoglobulin activity while eliminating vegetative pathogens. The process requires uninterrupted 2-6°C cold chain distribution from processing through retail, making logistics infrastructure the primary commercial constraint. Whole milk and low fat milk together capture the bulk of volume, though flavored milk carries disproportionate margin contribution in convenience store channels. Cartons and bottles retain dominance in supermarkets, while pouches gain traction in online retail where shipping weight drives packaging selection.
China's SAMR enforces GB 19645 microbiological limits and cold-chain traceability mandates that disqualify smaller processors lacking HACCP integration. Japan's Ministry of Health, Labour and Welfare maintains parallel standards through Food Sanitation Act provisions that Meiji and Snow Brand must satisfy for domestic distribution. Stakeholders should monitor regulatory divergence between China's evolving national standards and Japan's existing framework, as dual compliance costs will determine which processors can operate across both markets without product line duplication.
Market Dynamics
Cold-chain infrastructure gaps are fragmenting distribution reach across China's provincial markets, forcing processors to choose between asset-heavy direct delivery and margin-eroding third-party logistics partnerships. This structural constraint is reshaping competitive boundaries more decisively than product differentiation.
Growth Catalysts
- GB 19645 Certification Mandate:China's SAMR enforcement is disqualifying subscale processors, concentrating shelf space among compliant operators with HACCP-integrated traceability systems.
- Specialty Coffee Channel Expansion:Third-wave cafes in Shanghai and Beijing are specifying low-temperature pasteurized milk for latte art performance, creating premium procurement contracts.
- ESL Technology Maturation:Extended shelf-life processing without additive use is opening convenience store distribution windows previously closed to fresh milk.
Market Restraints
- Refrigerated Logistics Cost Structure:Diesel price volatility and cold-storage facility scarcity in central provinces inflate landed costs beyond mass-market price elasticity.
- Supply Concentration Risk:Inner Mongolia pasture networks control raw milk pricing, leaving processors exposed to regional drought and feed cost spikes.
- Ultra-High Temperature Substitution:Ambient-stable UHT milk retains price advantage in lower-tier cities where cold-chain reliability remains inconsistent.
Strategic Opportunities
- Direct-to-Consumer Subscription Channels:Farm-to-door delivery apps in Hangzhou and Shenzhen are bypassing supermarket slotting fees entirely.
- Flavored Milk Convenience Penetration:Coffee and tea flavor variants are capturing impulse purchase occasions in 24-hour retail formats.
- Traceability Technology Convergence:Blockchain-integrated cold-chain monitoring is satisfying SAMR documentation requirements while enabling premium positioning.
Industry Challenges
- Cold-Chain Technician Scarcity:Qualified refrigeration engineers and HACCP auditors command wage premiums that strain regional processor margins.
- GB 19645 Compliance Timeline Compression:Retrofitting legacy pasteurization lines to meet microbiological limits requires capital deployment that smaller cooperatives cannot access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Temperature Pasteurized Milk Market |
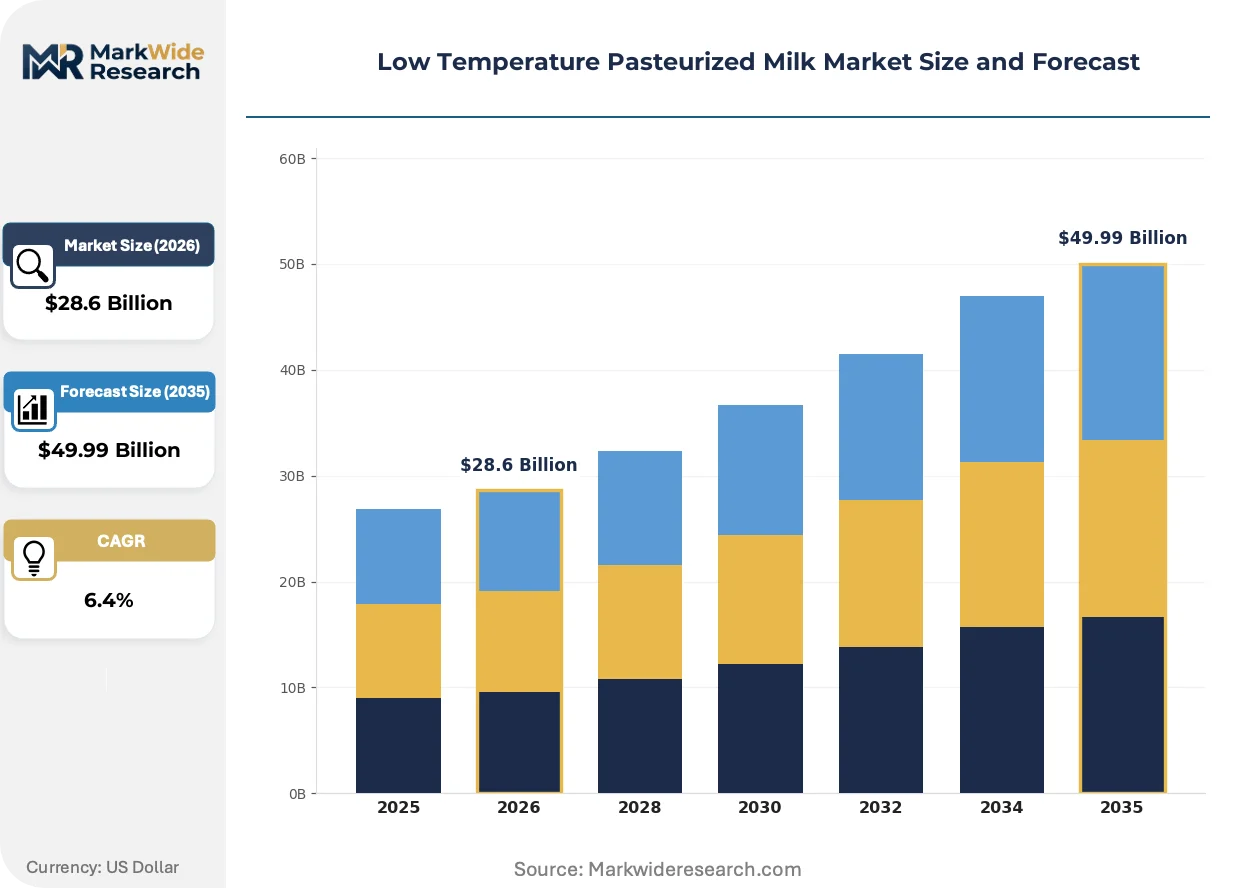
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $49.99 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Milk, Skim Milk, Low Fat Milk, Flavored Milk Packaging Type: Cartons, Bottles, Pouches, Tetra Pak Sales Channel: Supermarkets, Convenience Stores, Online Retail, HoReCa End User: Households, Cafes, Restaurants, Food Manufacturers |
| Companies Covered | Bright Dairy & Food Co., Ltd., Inner Mongolia Yili Industrial Group Co., Ltd., China Mengniu Dairy Company Limited, Hartzler Family Dairy, New Hope Dairy, Beijing Sanyuan Foods Co., Ltd., Meiji Holdings Co., Ltd., Snow Brand Milk Products Co., Ltd., CLASSY.KISS Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Temperature Pasteurized Milk Market Trends and Innovations
Processing technology and distribution infrastructure are converging to redefine freshness windows and channel economics. These shifts are compressing the viable operating model for mid-scale processors while rewarding operators with capital depth and geographic concentration.
Pouch packaging formats are supplanting rigid bottles in e-commerce channels where shipping weight directly determines fulfillment economics. Alibaba and JD.com fulfillment centers are prioritizing flexible packaging for last-mile efficiency. This transition is compressing packaging supplier margins while enabling processors to absorb delivery cost premiums.
China's SAMR cold-chain labeling requirements are mandating real-time temperature logging from processing through retail. Processors must integrate IoT sensors and cloud-based documentation systems to maintain distribution authorization. Tier-one supermarket chains are responding by consolidating supplier rosters to those with proven traceability infrastructure.
Specialty cafes are consolidating procurement around single-source milk with documented pasture provenance. This specification behavior is displacing commodity purchasing in Shanghai and Beijing metropolitan clusters. Roasters with direct farm relationships are capturing latte art and flavor clarity premiums that standard processors cannot match.
Low Temperature Pasteurized Milk Market Segmentation
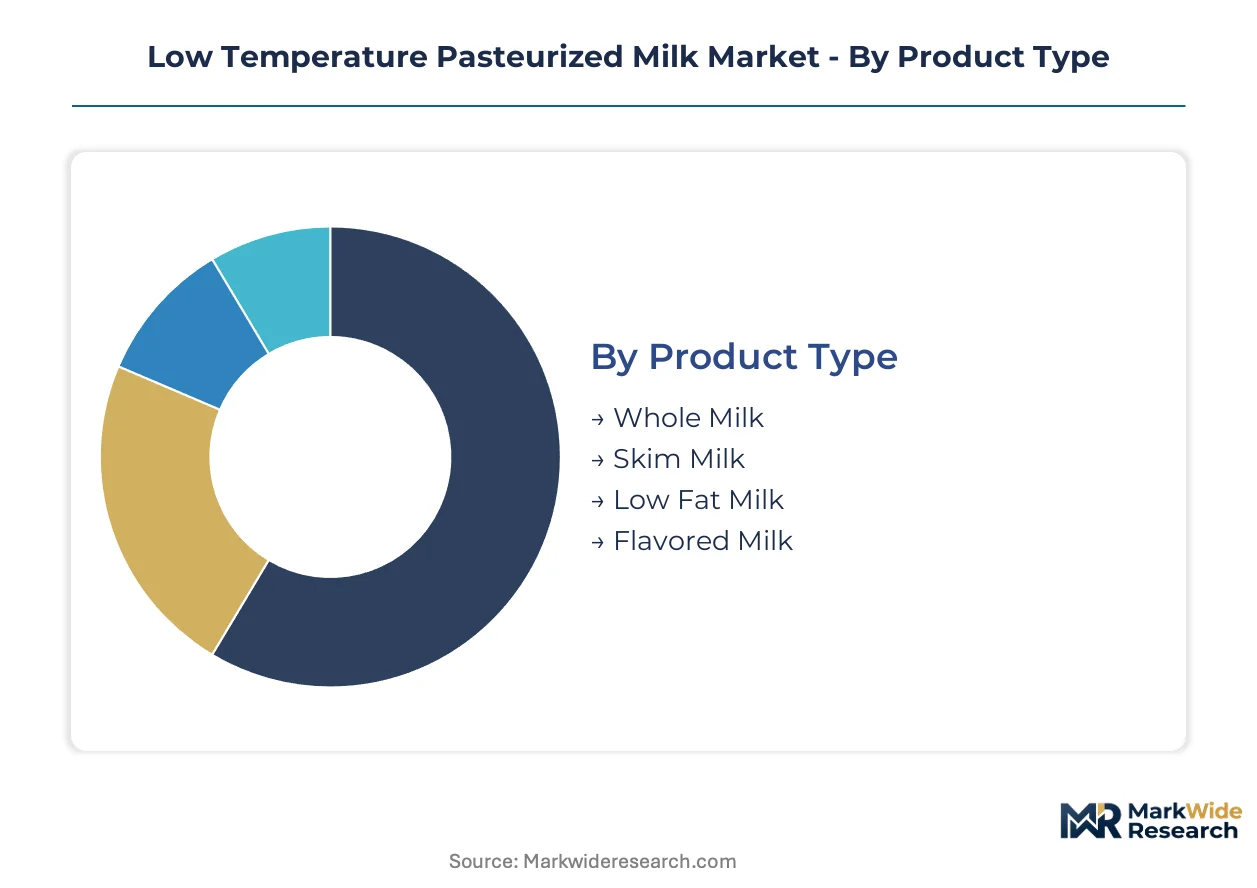
Segmentation in low temperature pasteurized milk reflects divergent cold-chain capabilities and channel economics. Product specifications, packaging formats, and distribution pathways each impose distinct infrastructure requirements that reshape competitive boundaries across processing tiers.
Product Type:
GB 19645 certification thresholds create tiered compliance burdens that favor processors with integrated HACCP systems over commodity operators.
- Whole Milk:Retains full butterfat content (3.25-4.0%) that preserves mouthfeel and foaming properties essential for latte art. Specialty cafes in Shanghai and Beijing specify whole milk for espresso-based beverages, driving premium procurement contracts that bypass supermarket slotting fees.
- Low Fat Milk:Reduced fat content (1-2%) meets health-positioned demand in first-tier urban households. Convenience store channels in Shenzhen and Hangzhou stock low fat variants for impulse breakfast purchases, though cold-chain reliability constraints limit penetration into central provinces.
- Skim Milk:Near-zero fat formulation appeals to fitness-oriented consumers and institutional foodservice accounts.
- Flavored Milk:Coffee, tea, and fruit variants command disproportionate margin contribution in 24-hour retail formats.
Established volume favors whole milk; emerging adoption favors flavored milk.
Packaging Type:
Shipping weight economics and shelf-life extension technologies are redistributing format preferences across physical and digital retail channels.
- Cartons:Gable-top paperboard dominates supermarket dairy cases with established recycling infrastructure and print branding surface. Tier-one chains in Beijing and Guangzhou consolidate shelf space around carton formats from processors with SAMR-documented cold-chain traceability.
- Pouches:Flexible film packaging reduces shipping weight by 60-70% versus rigid alternatives, enabling e-commerce fulfillment economics. JD.com and Alibaba fulfillment centers prioritize pouch formats for last-mile efficiency in subscription delivery models.
- Bottles:PET and HDPE rigid containers retain visibility in convenience store cold cases.
- Tetra Pak:Aseptic carton technology bridges fresh and extended shelf-life positioning.
Cartons retain channel dominance; pouches gain share fastest in digital retail.
Sales Channel:
Cold-chain infrastructure maturity determines viable channel entry, fragmenting processor strategies between asset-heavy direct delivery and third-party logistics partnerships.
- Supermarkets:Tier-one chains impose supplier consolidation, requiring real-time temperature logging and blockchain-integrated documentation. SAMR compliance mandates are disqualifying smaller processors from shelf placement in Carrefour, Walmart China, and domestic premium banners.
- HoReCa:Hotels, restaurants, and cafes specify single-source milk with documented pasture provenance for latte art performance. Third-wave coffee chains in Shanghai metropolitan clusters capture flavor clarity premiums that commodity processors cannot match.
- Convenience Stores:24-hour retail formats drive impulse flavored milk purchases with localized delivery requirements.
- Online Retail:Direct-to-consumer subscription apps bypass traditional slotting fees entirely.
Supermarkets anchor volume concentration; HoReCa delivers steepest margin expansion.
End User:
Application-specific quality requirements are segmenting procurement behavior between commodity volume and premium specification markets.
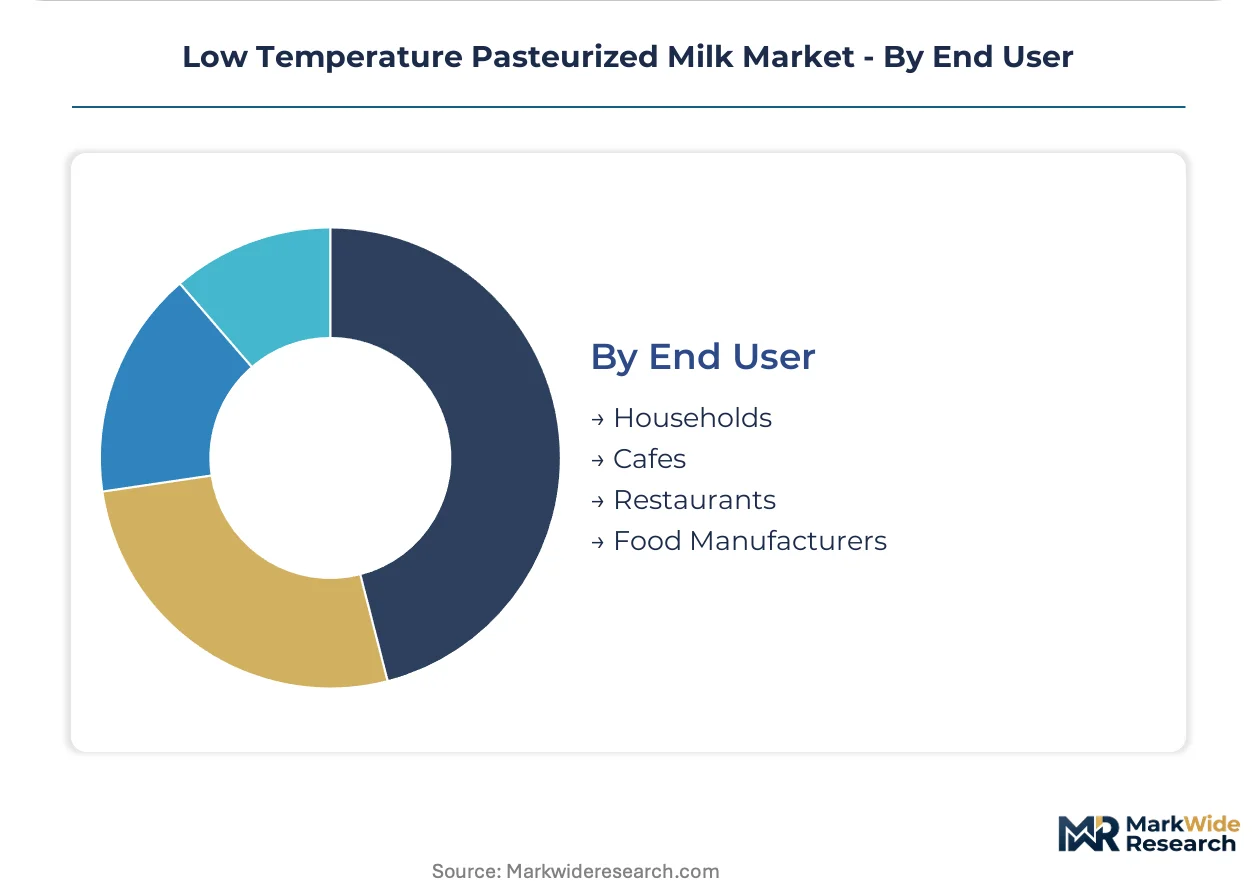
- Households:First-tier urban consumers in Beijing, Shanghai, and Shenzhen drive per capita consumption premiums that outpace national averages by substantial margins. Cold-chain reliability in these metropolitan clusters supports weekly subscription delivery models.
- Cafes:Specialty coffee operators specify low-temperature pasteurized milk for protein stability and microfoam texture. Roasters with direct farm relationships in Inner Mongolia pasture networks capture procurement premiums through documented provenance.
- Restaurants:Mid-tier foodservice accounts balance quality positioning against logistics cost constraints.
- Food Manufacturers:Industrial ingredient buyers prioritize volume scale and microbiological consistency for processed dairy applications.
Households represent the largest volume pool; cafes generate the highest unit economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's SAMR cold-chain labeling mandates are reshaping procurement patterns across East Asian markets, concentrating distribution authority among processors with integrated traceability infrastructure. Japan's Food Sanitation Act provisions and South Korea's MFDS dairy standards create parallel compliance frameworks that favor capital-intensive operators.
China
First-tier metropolitan clusters in Shanghai, Beijing, and Shenzhen drive per capita consumption premiums that substantially outpace national averages. SAMR's GB 19645 certification disqualifies subscale processors lacking HACCP-integrated systems, consolidating shelf space among compliant national conglomerates. The Yangtze River Delta anchors cold-chain infrastructure investment, where JD.com and Alibaba fulfillment centers prioritize pouch-format distribution.
Japan
Specialty coffee operators in Tokyo and Osaka specify low-temperature pasteurized milk for protein stability and microfoam performance. The Ministry of Health, Labour and Welfare enforces Food Sanitation Act provisions that Meiji and Snow Brand must satisfy for domestic distribution. Kanto region processors leverage ESL technology leadership to extend freshness windows without additive use.
South Korea
Seoul Capital Area households sustain premium dairy consumption through direct-to-consumer subscription channels bypassing traditional retail. MFDS maintains microbiological standards that parallel Japanese frameworks, creating dual compliance burdens for cross-border operators. Busan-Ulsan logistics hubs face cold-storage facility scarcity that inflates landed costs beyond mass-market price elasticity.
United States
Amish-country brand authenticity anchors regional processor positioning in direct farm-to-door subscription models. FDA pasteurization standards bifurcate the landscape between national dairy conglomerates and cold-chain specialists. Midwest pasture networks control raw milk pricing, exposing processors to feed cost volatility and regional drought risk.
Australia
New South Wales and Victoria metropolitan consumers sustain weekly delivery models where cold-chain reliability supports premium positioning. Food Standards Australia New Zealand enforces dairy safety requirements that processors must integrate with export documentation for Asian market access. Sydney and Melbourne specialty cafes consolidate procurement around single-source milk with documented pasture provenance.
Low Temperature Pasteurized Milk Market Competitive Landscape
Player mix skews toward vertically integrated national conglomerates with pasture-to-shelf infrastructure and regional cold-chain specialists with direct subscription channels. Market structure concentrates shelf placement authority among operators with SAMR-documented traceability systems, while mid-scale processors face margin compression from compliance retrofit costs. Two strategic archetypes dominate: capital-intensive national brands with logistics scale, and authenticity-positioned regional dairies with farm-direct relationships. Competitive moves center on M&A consolidation of cold-chain networks and capacity expansion in ESL processing technology.
Within the national conglomerate tier, Inner Mongolia Yili Industrial Group Co., Ltd. and China Mengniu Dairy Company Limited occupy positions defined by vertically controlled supply infrastructure. Among regional specialists, Hartzler Family Dairy exemplifies the farm-to-door subscription archetype. Meiji Holdings Co., Ltd. sits within the technology-differentiated segment, representing ESL processing leadership without additive use.
| Leading Market Players |
|---|
| Bright Dairy & Food Co., Ltd. |
| Inner Mongolia Yili Industrial Group Co., Ltd. |
| China Mengniu Dairy Company Limited |
| Hartzler Family Dairy |
| New Hope Dairy |
| Beijing Sanyuan Foods Co., Ltd. |
| Meiji Holdings Co., Ltd. |
| Snow Brand Milk Products Co., Ltd. |
| CLASSY.KISS Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Scale economies in cold-chain infrastructure deployment create durable barriers that concentrate supply authority among processors with vertically integrated pasture networks and HACCP-certified traceability systems. This concentration shapes price floors by forcing subscale operators into margin-eroding third-party logistics partnerships or complete market exit.
Pricing Analysis
Certification level creates the primary spread between GB 19645-compliant processors and legacy operators lacking SAMR-documented cold-chain traceability. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by ESL technology maturity, single-source pasture provenance, and direct subscription channel access. Cost compression in the economy tier is intensifying because UHT substitution retains price advantage in lower-tier cities where cold-chain reliability remains inconsistent. Mass-market households in central provinces exhibit highest price sensitivity, while specialty cafes in Shanghai and Beijing demonstrate lowest sensitivity due to latte art performance requirements.
Supply Chain Analysis
China and Inner Mongolia anchor raw milk production through vertically controlled pasture networks that set baseline input pricing for downstream processors. The supply chain draws from diesel fuel markets, refrigerated transport fleets, and IoT-enabled temperature logging equipment. Single-source vulnerability concentrates in Inner Mongolia pasture networks exposed to regional drought and feed cost spikes. Distribution runs through tier-one supermarket chains consolidating supplier rosters around SAMR-compliant operators, alongside direct-to-consumer subscription apps bypassing traditional slotting fees entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through GB 19645 certification creates durable competitive barriers. SAMR compliance mandates generate switching costs that lock in shelf placement authority for incumbent processors.
For Market Incumbents: Secure HACCP-integrated traceability infrastructure investments to disqualify subscale competitors from tier-one supermarket placement. Extend ESL technology leadership to capture convenience store distribution windows previously closed to fresh milk. Channel control through direct-to-consumer subscription apps defends against margin erosion from third-party logistics partnerships. For New Entrants and Emerging Players: GB 19645 certification fast-track through regional cooperative partnerships offers entry path into Hangzhou and Shenzhen metropolitan clusters. Target underpenetrated flavored milk convenience store channels where impulse purchase occasions reward localized delivery capabilities. Farm-to-door subscription positioning bypasses supermarket slotting fee barriers entirely. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors processors with proven ESL processing capabilities and blockchain-integrated cold-chain documentation. Long-term viability rests on acquisition of regional cold-chain specialists with established direct subscription channels. Watch for SAMR enforcement intensity as inflection indicator for competitive consolidation pace.| Strategic Initiative | Industry Significance |
|---|---|
| ESL Technology Licensing | Meiji Holdings extends freshness windows without additive use, opening convenience store channels. |
| Backward Integration into Pasture Networks | Inner Mongolia Yili controls raw milk pricing through captive supply infrastructure. |
| Blockchain Cold-Chain Documentation | SAMR-compliant traceability satisfies regulatory mandates while enabling premium positioning. |
| Direct-to-Consumer Subscription Launch | Hartzler Family Dairy bypasses supermarket slotting fees through farm-to-door delivery apps. |
| Regional Cold-Chain Acquisition | Consolidation of third-party logistics networks reduces diesel price volatility exposure. |
Research Methodology
A standing panel of dairy processing executives, cold-chain logistics operators, supermarket category buyers, and SAMR compliance auditors provided ongoing calibration across the research phase. Primary interviews with specialty cafe procurement managers and flavored milk product developers combined with secondary validation from customs records, GB standards documentation, and JD.com fulfillment data. Bottom-up volume modeling triangulated against top-down macroeconomic indicators anchored forecast reliability.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, packaging format, sales channel, and regional cold-chain infrastructure maturity. CAGRs derived from historical trajectory analysis adjusted for ESL technology adoption curves and SAMR enforcement timeline compression. Industry-specific forecast inputs incorporated diesel price volatility patterns and Inner Mongolia pasture yield variability.
Underlying assumptions cover cold-chain reliability maintenance, GB 19645 compliance timeline adherence, and specialty coffee channel expansion continuity, with deviation risk concentrated in central provincial logistics infrastructure gaps and regional drought frequency. Recalibration cycles align with material shifts in SAMR enforcement intensity and ESL technology licensing velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Low Fat Cream Cheese Nutrition Market
Dairy Products
GCC Camel Dairy Market
Dairy Products
Cream Powder Market
Dairy Products
Skimmed Milk Powder Market
Dairy Products
Germany Milk Protein Market
Dairy Products
UAE Camel Dairy Market
Dairy Products
Cultured Whey Products Market
Dairy Products
Goat Milk Products Market
Dairy Products
Lactose Free Probiotic Yogurt Market
Dairy Products
Middle East and Africa Whey Protein Market
Dairy Products
Asia-Pacific Cow Milk Minerals Market
Dairy Products
US and Europe Nuts and Seeds Cheese Market
Dairy Products
Dairy Spreads Market
Dairy Products
Butter Concentrate Market
Dairy Products
GCC Fresh Milk Market
Dairy Products
Green Tea Butter Market