
 Cholesterol Reduced Butter Market | 2026-2036
Cholesterol Reduced Butter Market Size, Share, and Industry Trends Forecast 2026-2036
Cholesterol Reduced Butter Market Outlook
Plant sterol esters derived from tall oil and vegetable sources is broadening the ingredient base for cholesterol-reduced spreads, lowering reliance on dairy-only formulations. Kraft Heinz leverages its refrigerated-distribution network to sustain shelf presence across North American retail channels. Land O'Lakes, Inc. anchors its position through cooperative sourcing that controls milkfat supply variability. AMUL Dairy competes on manufacturing scale, operating some of Asia's largest dedicated butter processing facilities.
Cholesterol reduced butter denotes a spreadable fat product where cholesterol content has been lowered through direct extraction, enzymatic conversion, or blending with plant-sterol-enriched fractions, typically achieving reductions of 50 percent or more while retaining functional properties such as melt point and creaming ability for baking. The product serves commercial bakeries and health-conscious households requiring saturated-fat moderation without sacrificing lamination or crumb structure. Spreads occupy the largest margin pool due to premium positioning at retail, while Baking Ingredients represents the fastest-growing category as industrial users reformulate standard recipes for nutritional claims. Online Retailers are gaining share fastest among distribution channels, though Supermarkets still control the majority of volume throughput.
The FDA governs cholesterol-content labeling and health claims in the United States, requiring substantiation that directly shapes product positioning and packaging communication. The EFSA evaluates novel plant-sterol applications under EU novel food regulations, creating a dual compliance pathway for exporters. India's FSSAI monitors dairy-fat standards and fortification claims, affecting how AMUL Dairy and others navigate domestic versus export formulations. Stakeholders must track evolving sterol-inclusion thresholds and claim permissibility across these jurisdictions to anticipate reformulation cycles and avoid market-access friction.
Market Dynamics
The EU's updated F-Gas Regulation is compressing refrigeration costs for cholesterol-reduced butter storage while plant-sterol extraction capabilities expand manufacturing flexibility. This dual pressure is restructuring competitive economics between dairy-centric and hybrid formulations.
Growth Catalysts
- Clean-label bakery commitments:Pastry chains across Germany and France are mandating cholesterol-reduced inputs to meet menu transparency pledges, pulling industrial-grade volumes into reformulation pipelines.
- REACH-compliant tall oil derivatives:European suppliers of plant sterol esters have secured novel food approvals under EFSA pathways, broadening the ingredient base beyond traditional dairy fractionation.
- India:AMUL Dairy's manufacturing scale creates downstream price elasticity that accelerates household penetration in price-sensitive segments.
Market Restraints
- Milkfat input volatility:Cooperative sourcing structures limit price hedging flexibility, exposing margins to feed-cost fluctuations in major dairy regions.
- EFSA novel food timelines:Sterol-inclusion thresholds require multi-year substantiation studies, delaying product line extensions for exporters targeting European retail.
- Oleogels and structured emulsions:These next-generation fat replacers threaten displacement in commercial baking where functional performance outweighs dairy provenance.
Strategic Opportunities
- Online retail channel expansion:Direct-to-consumer platforms bypass traditional supermarket slotting fees, enabling niche positioning for premium cholesterol-reduced spreads.
- FSSAI fortification harmonization:India's evolving standards for dairy-fat claims may align domestic and export specifications, simplifying SKU complexity for subcontinent producers.
- Enzymatic conversion + membrane filtration convergence:Combined processing technologies promise cholesterol reduction without sterol additives, opening clean-label positioning in jurisdictions with strict novel food regimes.
Industry Challenges
- Sterol stability expertise gap:Formulation chemists capable of optimizing plant-ester shelf life in refrigerated distribution remain concentrated in Northern European technical centers.
- Dual certification burden:Products requiring both FDA cholesterol-content validation and EFSA novel food clearance face elongated commercialization timelines that compress first-mover windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cholesterol Reduced Butter Market |
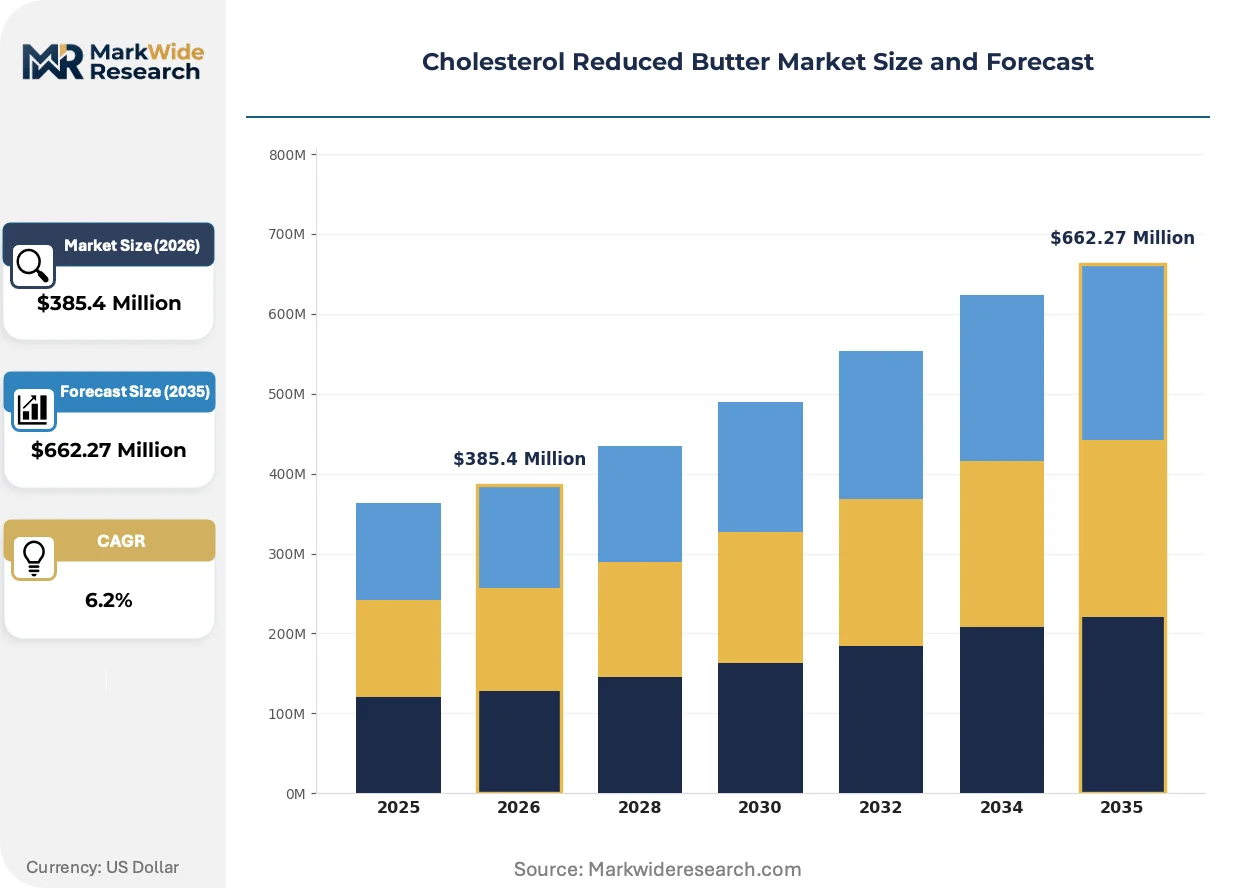
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $662.27 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spreads, Baking Ingredients, Cooking Butter, Whipped Butter Distribution Channel: Supermarkets, Health Food Stores, Online Retailers, Convenience Stores End User: Households, Restaurants, Bakeries, Cafes Packaging Type: Tubs, Sticks, Pouches, Jars |
| Companies Covered | The J.M. Smucker Company, Procter & Gamble, Kraft Heinz, Land O'Lakes, Inc., AMUL Dairy, Palsgaard, Ornua Co-operative Limited, Fonterra Co-operative Group, Boulder Brands Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cholesterol Reduced Butter Market Strategic Shifts
Processing technology and regulatory architecture are jointly redefining what constitutes a viable cholesterol-reduced butter product, with implications rippling from ingredient sourcing through final packaging claims.
Membrane filtration systems paired with enzymatic cholesterol reductases are overtaking solvent-based extraction as the preferred production architecture for mid-scale processors. Commercial bakeries in Germany and the Netherlands are adopting these systems at accelerated procurement cycles. The shift is compressing capital requirements for market entry while raising quality consistency thresholds that disadvantage legacy equipment operators.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon refrigerants is forcing cold-chain infrastructure reinvestment across dairy distribution networks. Industrial users of cholesterol-reduced butter face storage cost inflation that favors concentrated, shelf-stable baking ingredient formats over bulk spreadable products. German retail cooperatives are responding by consolidating refrigerated SKUs and demanding extended ambient stability from suppliers.
Ingredient procurement by commercial bakeries is rotating toward specification-driven contracts that lock sterol-content tolerances and functional performance metrics. Supermarket private-label programs are displacing branded spread volumes as the primary volume outlet in France and Belgium. This behavioral pivot is most visible in the Paris and Brussels metropolitan clusters where bakery chains centralize procurement decisions at headquarters level.
Cholesterol Reduced Butter Market Segmentation
Product differentiation in cholesterol-reduced butter hinges on functional performance thresholds that vary sharply across end-use scenarios. Procurement patterns diverge between retail consumers prioritizing spreadability and industrial buyers enforcing precise melt-point specifications for laminated dough production.
Product Type:
Formulation chemistry determines price positioning and regulatory pathway complexity for each product variant.
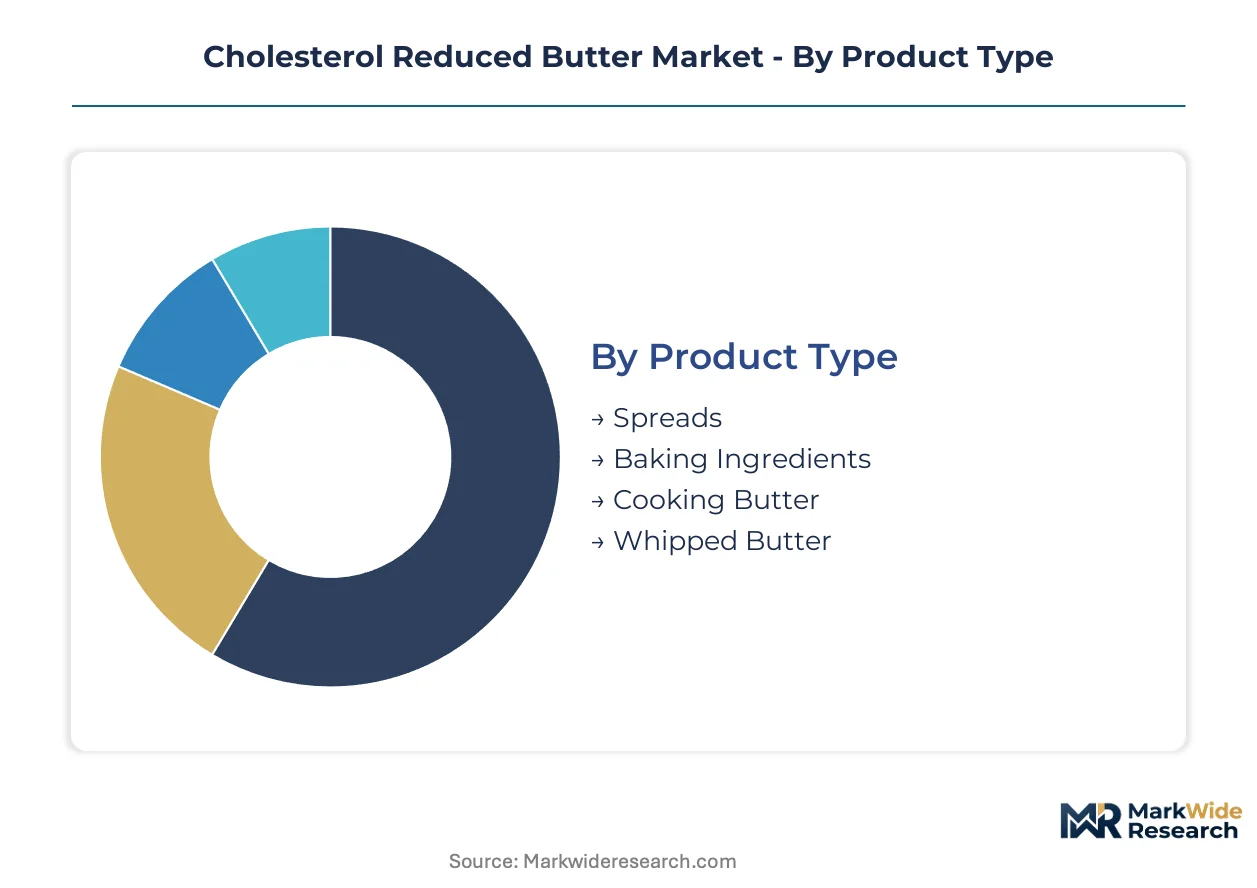
- Spreads:These retail-facing products combine plant-sterol esters with cultured cream bases to achieve 50 percent cholesterol reduction while maintaining cold-spread functionality. German supermarket chains dominate procurement volume, driven by clean-label positioning that commands premium shelf placement. Margins concentrate here due to direct-to-consumer pricing power and repeat purchase frequency.
- Baking Ingredients:Industrial formulations prioritize plasticity range and moisture retention for croissant and puff-pastry lamination. Paris-based bakery cooperatives and Amsterdam industrial bakeries are expanding specification-driven contracts that lock sterol-content tolerances and functional performance metrics. This segment is expanding most quickly as commercial users reformulate standard recipes for nutritional claims.
- Cooking Butter:High-heat stability variants target sauté and pan-fry applications with elevated smoke points through fractionated milkfat blending.
- Whipped Butter:Aerated structures reduce density for portion-controlled foodservice dispensing, common in Mumbai and Delhi cafe chains.
Spreads lead on scale; Baking Ingredients leads on momentum.
Distribution Channel:
Channel selection shapes margin capture and regulatory exposure differently across geographies.
- Supermarkets:Refrigerated dairy cases in France and Belgium still control majority volume throughput, though slotting fees compress margins for branded entrants. Private-label programs are displacing branded spread volumes as the primary outlet in Paris and Brussels metropolitan clusters.
- Online Retailers:Direct-to-consumer platforms bypass traditional supermarket slotting fees, enabling niche positioning for premium cholesterol-reduced spreads with extended shelf-life claims. Mumbai and Bangalore urban households drive adoption through subscription replenishment models.
- Health Food Stores:Specialist retailers in Germany and the Netherlands curate functional-dairy assortments targeting cardiologist-recommended diet adherence.
- Convenience Stores:Grab-and-go tub formats serve travel corridors and fuel-station retail in high-density Indian urban corridors.
Supermarkets dominate current volume; Online Retailers show steepest expansion trajectory.
End User:
User sophistication determines specification stringency and contract structure.
- Bakeries:Centralized procurement at headquarters level in German and French pastry chains mandates cholesterol-reduced inputs for menu transparency pledges, pulling industrial-grade volumes into reformulation pipelines with locked sterol-content tolerances.
- Households:Health-conscious consumers in price-sensitive segments respond to AMUL Dairy's manufacturing scale that creates downstream price elasticity and accelerates penetration in Indian metropolitan markets.
- Restaurants:Foodservice operators balance portion cost against nutritional claim permissibility for menu labeling.
- Cafes:Mumbai and Bangalore cafe chains specify whipped butter formats for consistent dispensing and waste reduction.
Bakeries anchor industrial demand; Households drive volume scaling.
Packaging Type:
Packaging format selection reflects distribution cold-chain reliability and use-case convenience requirements.
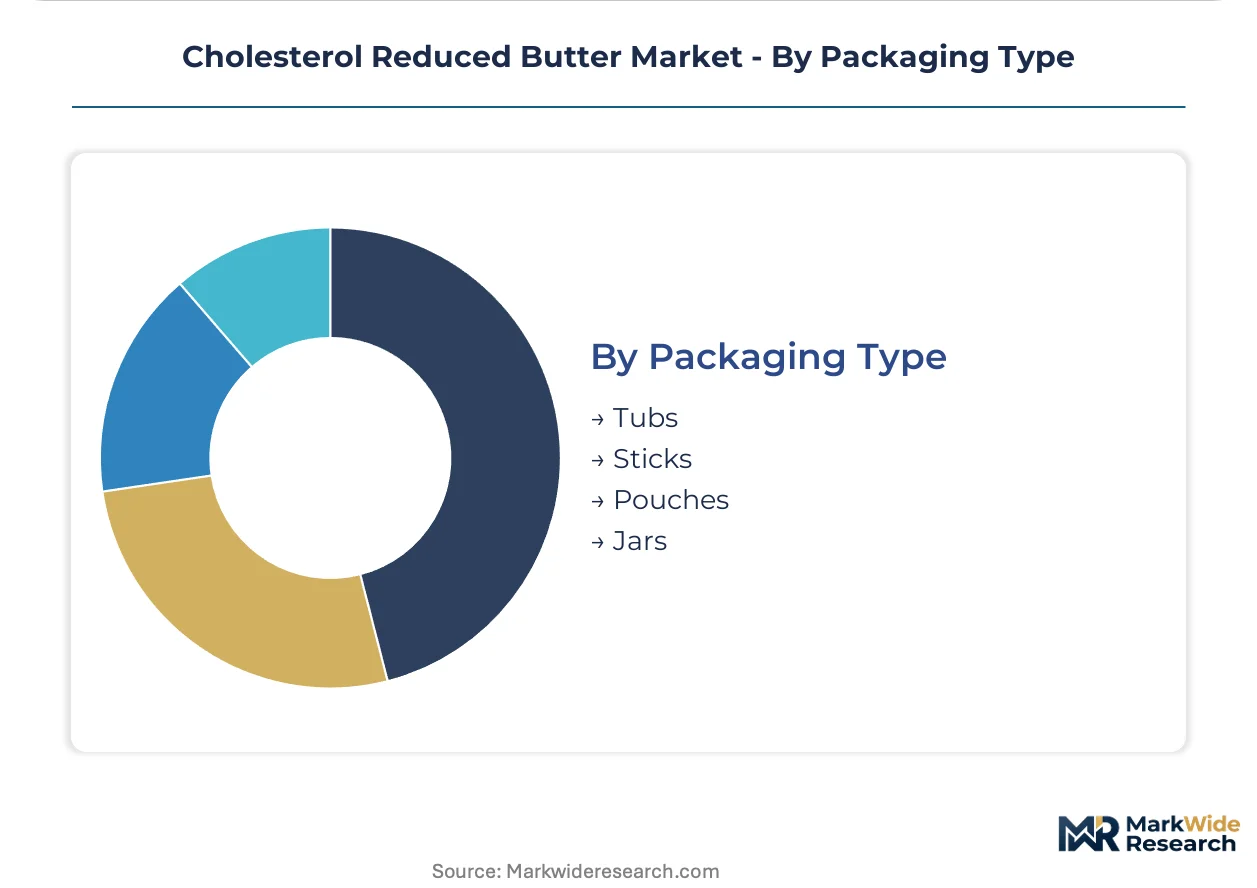
- Tubs:Wide-mouth containers dominate retail spreads in German and French supermarkets, enabling easy portion extraction and reseal functionality for household refrigeration.
- Sticks:Quarter-pound wrapped formats serve US baking traditions and precise recipe measurement needs, common in North American household procurement.
- Pouches:Flexible single-serve sachets target foodservice portion control and airline catering applications where waste minimization overrides unit cost.
- Jars:Glass or PET containers with vacuum-seal closures extend ambient stability for export shipments to markets with unreliable cold-chain infrastructure.
Tubs capture the largest margin pool; Pouches address the most constrained supply scenarios.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German supermarket chains anchor procurement volume for cholesterol-reduced spreads, driven by clean-label positioning and the widest functional-dairy assortment in Europe. Demand concentrates in metropolitan clusters where bakery chains centralize procurement decisions at headquarters level.
United States
FDA cholesterol-content labeling requirements shape product positioning and packaging communication for health claims. Refrigerated-distribution networks sustain shelf presence across retail channels, with quarter-pound stick formats serving traditional baking measurement needs. Greater Boston and Pacific Northwest metropolitan areas show concentrated adoption of premium spreadable products through subscription replenishment models.
Germany
Paris and Brussels bakery cooperatives mandate cholesterol-reduced inputs for menu transparency pledges, pulling industrial-grade volumes into reformulation pipelines. The EU F-Gas Regulation compresses refrigeration costs while forcing cold-chain infrastructure reinvestment. Frankfurt and Munich retail cooperatives consolidate refrigerated SKUs and demand extended ambient stability from suppliers.
France
EFSA novel food evaluations for plant-sterol applications create compliance pathways for hybrid formulation exporters. Supermarket private-label programs displace branded spread volumes as the primary outlet in metropolitan clusters. Lyon and Marseille industrial bakeries expand specification-driven contracts locking sterol-content tolerances and functional performance metrics.
India
FSSAI dairy-fat standards and fortification claims affect domestic versus export formulation strategies for price-sensitive segments. Mumbai and Bangalore urban households drive adoption through online subscription replenishment models. Delhi-NCR cafe chains specify whipped butter formats for consistent dispensing and waste reduction in high-density corridors.
Netherlands
REACH-compliant tall oil derivative suppliers secure novel food approvals, broadening the plant-sterol ingredient base beyond traditional dairy fractionation. Amsterdam industrial bakeries accelerate procurement cycles for membrane filtration systems paired with enzymatic cholesterol reductases. Rotterdam distribution hubs face storage cost inflation favoring concentrated, shelf-stable baking ingredient formats.
Cholesterol Reduced Butter Market Competitive Environment
Strategic partnerships dominate the current landscape as processors seek sterol stability expertise and distribution scale. The vendor base clusters around three archetypes: dairy cooperatives controlling milkfat supply variability, multinational food conglomerates leveraging refrigerated networks, and specialty ingredient houses supplying plant-sterol esters. Consolidation pressures favor players with backward integration into milkfat sourcing or captive supply of tall oil derivatives. Technology licensing agreements for enzymatic conversion processes represent a second competitive vector reshaping production economics.
Within the cooperative sourcing tier, Land O'Lakes, Inc. and Fonterra Co-operative Group exemplify structures that anchor milkfat supply control. Kraft Heinz occupies a position representing multinational scale advantages in refrigerated distribution network access. AMUL Dairy exemplifies manufacturing scale archetypes operating dedicated butter processing facilities. These three entities represent distinct competitive positioning strategies: cooperative supply control, branded retail channel dominance, and production scale efficiency respectively.
| Leading Market Players |
|---|
| The J.M. Smucker Company |
| Procter & Gamble |
| Kraft Heinz |
| Land O'Lakes, Inc. |
| AMUL Dairy |
| Palsgaard |
| Ornua Co-operative Limited |
| Fonterra Co-operative Group |
| Boulder Brands Inc. |
| Others |
Value Chain & Pricing Dynamics
Membrane filtration systems paired with enzymatic cholesterol reductases are compressing capital requirements for mid-scale processors while simultaneously concentrating production economics among equipment operators capable of meeting quality consistency thresholds. This technological shift is restructuring how German and Dutch bakeries negotiate specification-driven contracts and how price premiums attach to sterol-content tolerances.
Pricing Analysis
Input-cost pass-through from milkfat feedstocks and tall oil derivative supplies is fragmenting pricing structures across formulation tiers. Three-tier pricing stratifies across premium plant-sterol-enriched spreads, standard enzymatic-reduction products, and economy blended formulations. Price differentiation rests on sterol-content certification and functional performance metrics for laminated dough applications. Pricing pressure stems from oleogel substitutes in commercial baking where functional performance outweighs dairy provenance. Household consumers in Indian metropolitan markets exhibit highest price sensitivity, while Paris-based bakery cooperatives enforce specification premiums with limited elasticity.
Supply Chain Analysis
Reverse-logistics flows for refrigerated cholesterol-reduced butter remain underdeveloped, with expired or temperature-compromised inventory typically diverted to industrial rendering rather than reprocessing. Geographic supply concentration centers on Germany, the Netherlands, and India for processing capacity, with New Zealand and Ireland anchoring milkfat sourcing. Raw material dependencies draw from tall oil derivatives, fractionated milkfat, and plant-sterol ester concentrates. Supply chain risk concentrates in single-source vulnerability for novel food-approved sterol suppliers under EFSA timelines. Distribution runs through refrigerated dairy networks controlled by supermarket cooperatives in France and Belgium, with direct-to-consumer platforms gaining share fastest in Mumbai and Bangalore urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cholesterol reduced butter market functions as a regulatory compounder where the EU F-Gas Regulation's refrigeration cost compression and EFSA novel food pathways jointly determine viable product economics and geographic expansion feasibility.
For Market Incumbents: Extend sterol stability expertise through technology licensing agreements for enzymatic conversion processes, locking formulation chemist talent concentrated in Northern European technical centers. Defend against oleogel displacement in commercial baking by embedding functional performance guarantees into specification-driven contracts with Paris and Amsterdam industrial bakeries. Prioritize backward integration into tall oil derivative sourcing to secure REACH-compliant supply chains.
For New Entrants and Emerging Players: Capture online retail channel share in Mumbai and Bangalore through subscription replenishment models that bypass supermarket slotting fees. Target household segments in price-sensitive Indian metropolitan markets where AMUL Dairy's scale has established downstream price elasticity expectations. Lead with clean-label positioning in jurisdictions with strict novel food regimes, leveraging membrane filtration without sterol additives.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale processors with captive membrane filtration capabilities because capital requirements for enzymatic conversion entry are compressing while quality consistency thresholds are rising. Long-term viability hinges on regulatory arbitrage across FDA, EFSA, and FSSAI jurisdictions. Watch for EFSA novel food approval accelerations as inflection indicators for European market access expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Technology Licensing Agreement | Enzymatic conversion process transfers compress capital barriers for mid-scale processors in Germany and the Netherlands. |
| Backward Integration | Captive tall oil derivative supply secures REACH compliance and insulates margins from feedstock volatility. |
| Direct-to-Consumer Launch | Subscription models in Mumbai and Bangalore bypass supermarket slotting fees and capture premium positioning. |
| Regulatory Certification Investment | Dual FDA and EFSA clearance unlocks transatlantic market access despite elongated commercialization timelines. |
| Specification-Driven Contracting | Locked sterol-content tolerances with Paris bakery cooperatives defend against oleogel substitution threats. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with dairy processing executives, bakery cooperative procurement directors, plant-sterol formulation chemists, and refrigerated distribution logistics managers with secondary validation. Secondary sources included EFSA novel food submission databases, FSSAI dairy-fat standard notifications, EU F-Gas Regulation implementation tracking, and customs trade data for tall oil derivative flows. Bottom-up segment sizing and top-down market triangulation cross-validated volume and value estimates.
Segment-weighting approaches distributed projections across product type, distribution channel, end user, and packaging format dimensions, with additional layering for regulatory jurisdiction clusters. CAGRs were derived from trend extrapolation anchored to documented procurement cycles and capacity expansion announcements. Forecast inputs incorporated membrane filtration adoption curves, EFSA approval timeline distributions, and cold-chain infrastructure reinvestment patterns across the projection horizon.
Underlying measurement precision varies by segment; spreads and baking ingredients carry tighter precision than cooking butter and whipped formats due to more transparent procurement data. Forecasts reflect assumptions about sterol-inclusion threshold stability and novel food pathway durations. Practitioners should monitor EFSA evaluation acceleration signals, FSSAI fortification harmonization announcements, and oleogel functional performance breakthroughs for early indicators of forecast revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
India Milk Protein Market
Dairy Products
GCC UHT Milk Market
Dairy Products
Canada Milk Protein Market
Dairy Products
Global Quark and Fromage Frais Market
Dairy Products
Cream and Soft Cheese Market
Dairy Products
Lactose and Derivative Market
Dairy Products
South America Dairy Protein Market
Dairy Products
North America Condensed Milk Market
Dairy Products
United States Camel Dairy Market
Dairy Products
United States Milk Protein Market
Dairy Products
Low Calorie Whipped Cream Market
Dairy Products
Malted Milk Powder Market
Dairy Products
Asia-Pacific Casein and Caseinates Market
Dairy Products
Dairy Protein Market
Dairy Products
North America Cheese Market
Dairy Products
Sour Cream Market