
 Low Fat Yogurt Calories Market | 2026-2036
Low Fat Yogurt Calories Market Size, Share, and Industry Trends Forecast 2026-2036
Low Fat Yogurt Calories Market Analytics
Asset-light contract manufacturing and private-label leasing arrangements is fragmenting competitive control across the low fat yogurt calories category. Danone S.A. leverages its captive dairy network and cold-chain infrastructure to sustain cost advantages in European retail. Chobani LLC anchors its position through Greek-style specialization and direct-store-delivery channel control in North American supermarkets. Nestlé S.A. competes via multi-format packaging scale and co-manufacturing partnerships that reduce capital intensity for regional entrants.
Low fat yogurt calories denotes dairy-based fermented products containing reduced lipid content, typically manufactured through controlled skim-milk processing and live bacterial culture fermentation at specific temperature parameters, yielding a functional food positioned for weight management and protein supplementation applications. Greek-style formulations lead volume contribution due to elevated protein density and premium price realization, while fruit-infused variants capture faster growth through flavor novelty and expanded snacking occasions. Cup packaging dominates margin pools through portion-controlled convenience and retail shelf visibility, though pouch formats gain traction in on-the-go consumption segments.
FDA nutrition labeling requirements and USDA organic certification standards shape product formulation and market access conditions for domestic manufacturers, while EU EFSA health claim regulations and F-Gas refrigeration rules constrain processing technology choices for European suppliers. Stakeholders must monitor evolving clean-label enforcement intensity and refrigeration energy standards to align capital deployment with compliance trajectories.
Market Dynamics
Clean-label formulation mandates and F-Gas refrigeration phase-downs are forcing dairy processors to retool fermentation infrastructure and reformulate stabilizer systems simultaneously, compressing margin structures while elevating compliance capital requirements.
Growth Catalysts
- USDA Organic Certification:Retail grocery buyers in the United States prioritize certified organic SKUs, pulling processors toward pasture-sourced milk pools and extended fermentation protocols that command shelf price premiums.
- Protein density positioning:Weight management applications drive Greek-style formulation R&D, with elevated casein content becoming the default specification for meal-replacement and post-workout consumption occasions.
- Skim-milk powder volatility hedging:Large cooperatives in New Zealand and the Netherlands deploy forward-contract instruments that stabilize input costs for contract manufacturers serving private-label retailers.
Market Restraints
- Fresh milk sourcing radius:Cold-chain economics limit viable dairy procurement to 300-kilometer radii around processing plants, constraining facility location flexibility in land-constrained Western European markets.
- Live culture viability windows:Lactobacillus bulgaricus and Streptococcus thermophilus strains require precise temperature maintenance through distribution, elevating spoilage risk in last-mile channels lacking refrigerated logistics.
- Plant-based yogurt substitution:Oat and coconut fermented alternatives capture lactose-intolerant and vegan households, eroding addressable household penetration for dairy-based low-fat variants.
Strategic Opportunities
- Pouch format expansion:On-the-go consumption in German and French urban transit corridors favors single-serve flexible packaging that reduces unit shipping weight versus traditional cup formats.
- EU EFSA health claim authorization:Approved digestive wellness and protein synthesis claims enable premium positioning in pharmacy and fitness retail channels previously closed to functional food marketers.
- Direct-to-subscription models:Cold-chain delivery platforms in London and Paris metro areas bypass conventional supermarket slotting fees while capturing recurring revenue from health-conscious households.
Industry Challenges
- Clean-label reformulation timelines:Removing modified food starch and artificial stabilizers extends product development cycles by 8-12 months as processors validate texture and shelf-life performance through accelerated aging protocols.
- Refrigeration technician scarcity:Specialized ammonia and CO2 refrigeration system expertise required for F-Gas-compliant dairy plants concentrates in Northern Italy and Denmark, creating hiring bottlenecks for facility expansions elsewhere.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Fat Yogurt Calories Market |
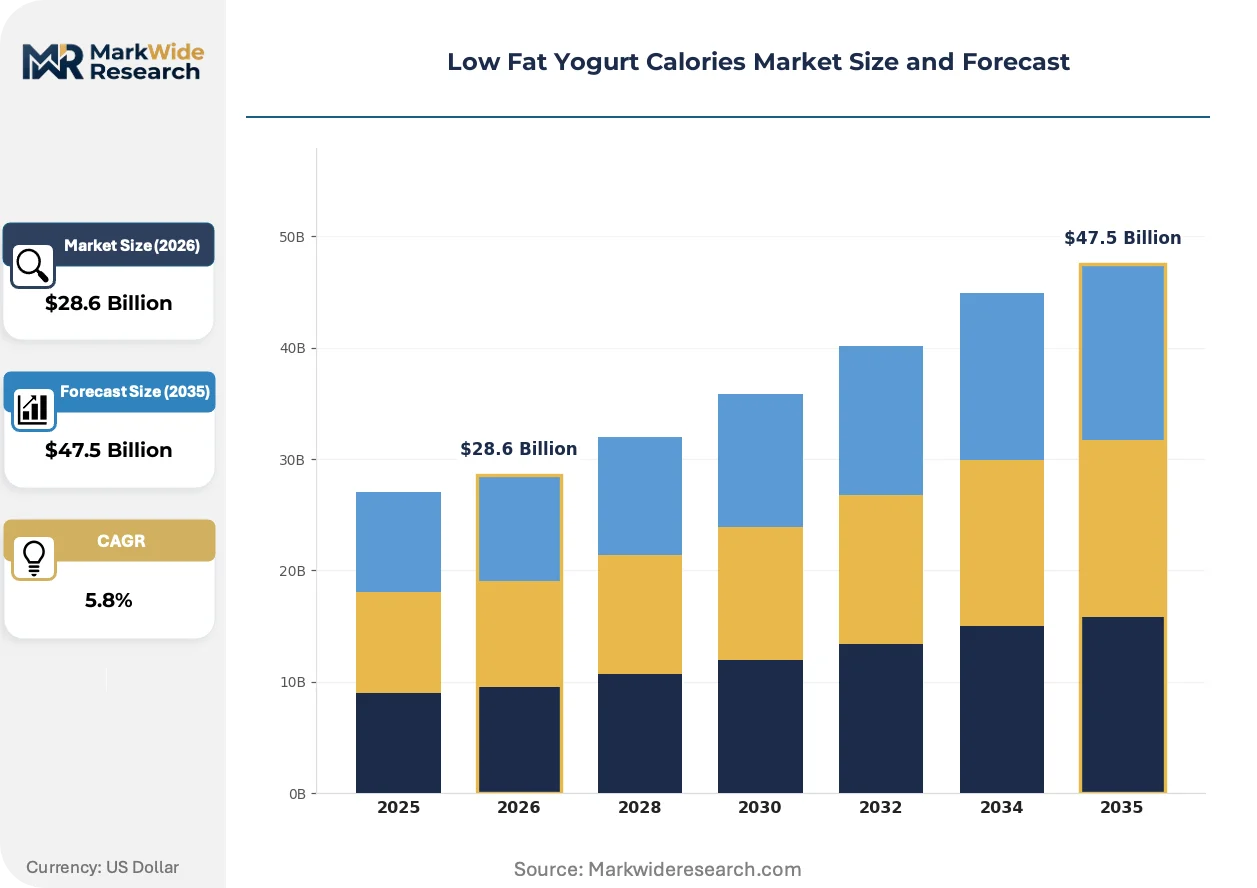
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Greek, Fruit-Infused, Bulky, Plain Fat Content: 0%, 1%, 2%, Reduced Fat Flavor Profile: Vanilla, Strawberry, Blueberry, Peach Packaging Type: Cup, Bottle, Pouch, Tub |
| Companies Covered | Danone S.A., Chobani LLC, Nestlé S.A., General Mills Inc., Fage International S.A., Muller UK & Ireland Group, CP-Meiji Company Ltd., Parmalat S.p.A., Tillamook, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Fat Yogurt Calories Market Evolving Landscape
Processing technology convergence and consumption occasion fragmentation are simultaneously elevating product complexity and shortening development cycles, forcing manufacturers to balance artisan positioning with industrial scale.
Membrane filtration technology is hybridizing traditional skimming and protein concentration steps into continuous-flow systems that reduce water usage and whey waste streams. Mid-scale processors in the Netherlands and Wisconsin are retrofitting existing plants with ceramic microfiltration modules that yield Greek-style protein levels without secondary straining operations. This convergence is compressing capital requirements for premium product entry while raising technical barriers for conventional stirred-yogurt specialists.
EU F-Gas Regulation phase-down schedules are mandating CO2 and ammonia refrigeration retrofits across dairy processing infrastructure by 2030. Plant engineers in France and Germany face 18-24 month lead times for compressor and heat-exchanger procurement, delaying capacity expansions and forcing temporary outsourcing to contract manufacturers. Greek-style and strained yogurt categories absorb disproportionate compliance costs due to extended cold-hold requirements during drainage and blending stages.
Retail buyers in United States and United Kingdom markets are consolidating SKU counts while demanding regional flavor localization, pressuring manufacturers to maintain variety with reduced production runs. Direct-store-delivery networks that bypass warehouse distribution centers enable faster flavor rotation and temperature control but require dedicated fleet investments that favor larger processors with captive logistics assets. This channel bifurcation is most visible in metropolitan corridors of New York, London, and Los Angeles where premium placement fees in conventional retail have reached prohibitive levels for mid-tier brands.
Low Fat Yogurt Calories Market Segmentation
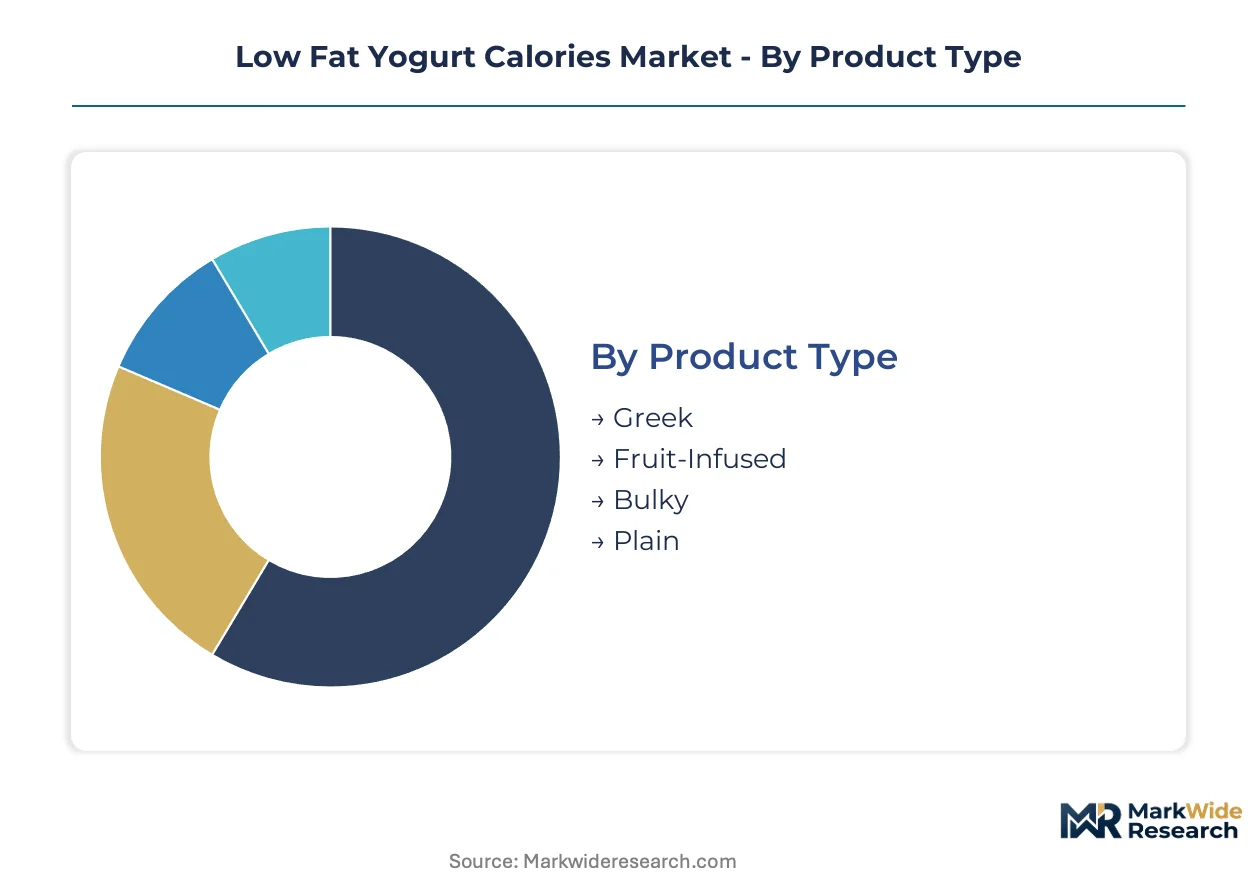
Low fat yogurt calories segmentation reflects divergent consumer priorities across convenience, sensory experience, and nutritional specification. Manufacturers configure production lines around these dimensions to optimize slotting fees and velocity metrics in distinct retail channels.
Product Type:
Mature Greek formulations dominate refrigerated dairy cases while emerging formats reshape snacking occasions through texture innovation.
- Greek:Strained through membrane filtration or mechanical separation to achieve elevated protein density, typically 10-15 grams per serving. Concentrated demand from United States metropolitan fitness consumers and German pharmacy retail channels drives premium price realization. Texture stability requirements extend fermentation hold times, elevating capital intensity versus conventional stirred products.
- Fruit-Infused:Base yogurt blended with fruit preparations or bottom-layer fruit compotes prior to cup filling. United Kingdom and French supermarket buyers prioritize flavor rotation programs that sustain basket velocity through novelty. Clean-label reformulation pressures have eliminated artificial colors and shifted processors toward natural anthocyanin sources.
- Bulky:Contains particulate inclusions such as granola clusters, chia seeds, or oat flakes packaged in dual-chamber configurations. Texture contrast targets extended consumption occasions beyond traditional breakfast.
- Plain:Unflavored base used as cooking ingredient or customizable canvas for consumer-added toppings. Institutional foodservice procurement in United States school nutrition programs specifies this format for recipe flexibility.
Greek handles the majority of throughput; Fruit-Infused is the fastest mover on share.
Fat Content:
Cost tier stratification aligns with USDA organic certification premiums and private-label positioning strategies.
- 0%:Non-fat milk solids processed through centrifugal separation eliminate all milkfat, yielding 35-45 calories per 100 grams. Weight management positioning in United States coastal urban markets commands shelf price premiums of 15-20 percent above standard low-fat equivalents. Extended shelf-life requirements demand modified stabilizer systems that complicate clean-label transitions.
- 1%:Minimal fat retention provides mouthfeel improvement over non-fat variants without significant caloric increase. German and Dutch retail discounters utilize this specification as private-label standard to balance nutrition claims with production cost control.
- 2%:Retains sufficient milkfat for creamy texture while maintaining sub-100 calorie positioning per standard serving. Preferred by French and Italian consumers prioritizing gustatory satisfaction over maximal fat reduction.
- Reduced Fat:Variable specification typically 25-50 percent fat reduction from whole milk baseline, allowing formulation flexibility across regional taste preferences. Common in emerging market introductions where consumer education on fat content labeling remains incomplete.
1% specifications capture the highest volume throughput; 0% formats are expanding most quickly in premium channels.
Flavor Profile:
Customer type fragmentation between habitual purchase patterns and experimental trial behavior shapes flavor portfolio construction.
- Vanilla:Bourbon and Tahitian vanilla extract variants provide neutral base compatible with both direct consumption and recipe applications. United States Midwest and Southern states demonstrate persistent preference for this traditional profile.
- Strawberry:Most widely distributed fruit flavor globally, utilizing both strawberry puree and natural flavor systems. Seasonal procurement from California and Mexico processing districts influences cost structures.
- Blueberry:Wild blueberry specifications from Maine and Canadian maritime provinces command premium positioning in Northeast United States markets. Anthocyanin content supports antioxidant marketing claims subject to EFSA and FDA substantiation requirements.
- Peach:Clingstone peach preparations from Georgia and South Carolina orchards dominate North American formulations. European variants utilize Mediterranean cling peach sources with distinct aroma profiles.
Strawberry maintains the largest volume footprint; Blueberry is climbing the fastest on share expansion.
Packaging Type:
Supply concentration in cup manufacturing equipment constrains format innovation despite shifting consumption occasion requirements.
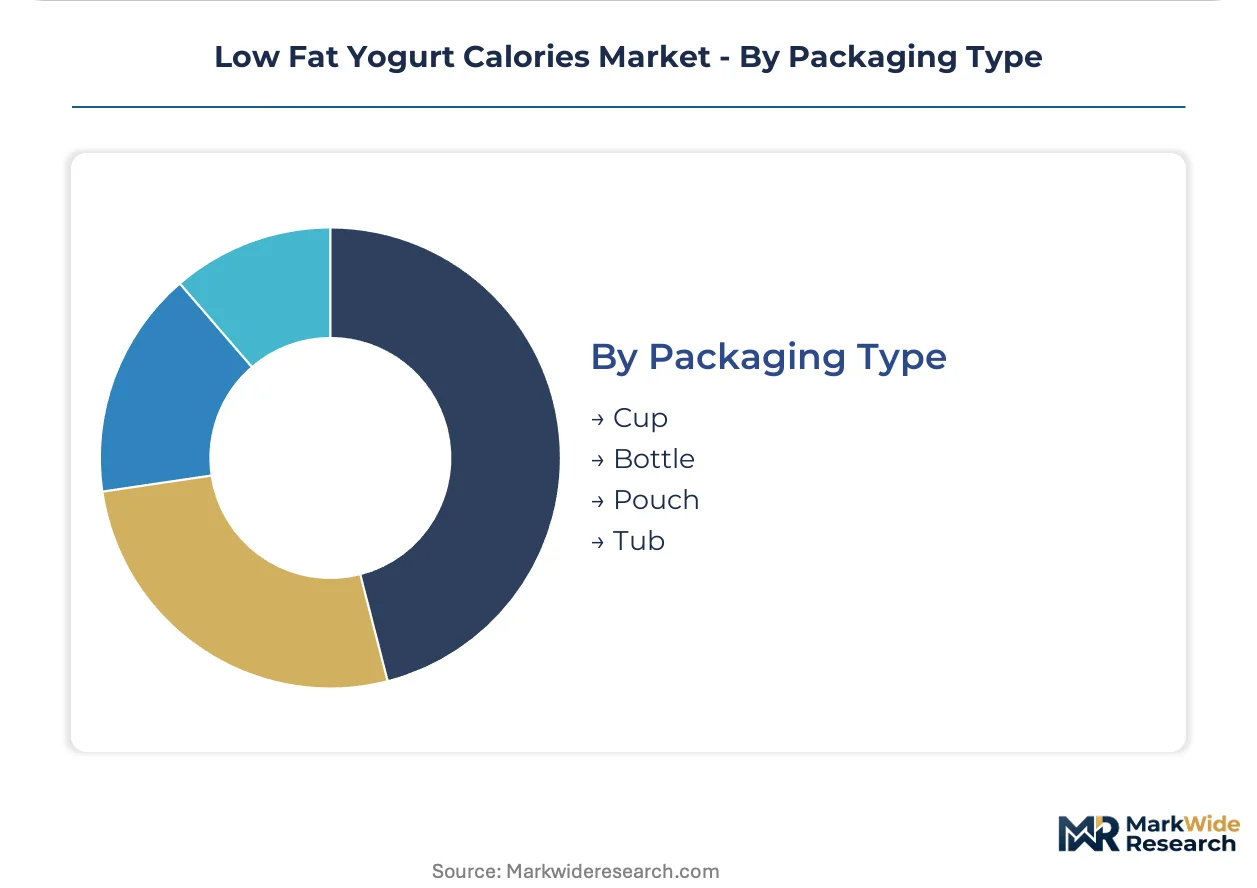
- Cup:Polystyrene or polypropylene thermoformed containers with foil lidding dominate retail dairy cases. Shelf visibility and portion-controlled convenience sustain preference among United States supermarket buyers despite environmental pressure on single-use plastics.
- Bottle:HDPE or PET containers with screw-cap closures enable resealability and drinking consumption. German commuter rail stations and French highway service areas favor this format for on-the-go breakfast replacement.
- Pouch:Flexible laminated films with spout fitments reduce shipping weight and enable single-hand consumption. United Kingdom urban transit corridors and Netherlands cycling culture drive adoption despite higher per-unit packaging costs.
- Tub:Larger format polypropylene containers target family consumption and recipe ingredient applications. United States warehouse club channels specify multi-pound tubs for value positioning.
Cup configurations handle the majority of throughput; Pouch formats are gaining share fastest in metropolitan convenience channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fitness-oriented professionals and weight-conscious households concentrate in coastal metropolitan corridors, while pharmacy retail channels anchor premium positioning in German and French urban centers. Cold-chain infrastructure density and organic certification penetration vary sharply across national boundaries.
United States
Direct-store-delivery networks dominate supermarket penetration in New York, Los Angeles, and Chicago metro areas. FDA nutrition labeling requirements and USDA organic certification standards shape formulation decisions for processors serving retail grocery buyers. Greek-style production clusters concentrate in upstate New York and Idaho dairy belts, where membrane filtration retrofit investments accelerate.
Germany
Retail discounters in Berlin, Munich, and Hamburg metro corridors specify 1% fat content as private-label standard. EU F-Gas Regulation phase-down schedules mandate CO2 refrigeration retrofits by 2030, compressing facility expansion timelines. Bavarian dairy cooperatives deploy forward-contract instruments to hedge skim-milk powder volatility for contract manufacturers.
France
Pharmacy retail channels in Paris and Lyon absorb premium-positioned digestive wellness claims authorized under EU EFSA health claim regulations. French consumers prioritize 2% fat retention for gustatory satisfaction over maximal fat reduction. Normandy and Brittany dairy belts sustain pasture-sourced milk pools for organic certification premiums.
United Kingdom
Urban transit corridors in London, Manchester, and Birmingham drive pouch format adoption for on-the-go breakfast replacement. Clean-label enforcement intensity from major supermarket buyers has eliminated artificial colors from fruit-infused variants. Scottish dairy processors face extended distribution radius challenges to serve southern England markets.
Netherlands
Cycling culture in Amsterdam, Rotterdam, and Utrecht favors lightweight flexible packaging formats. Ceramic microfiltration module retrofits in Friesland and Gelderland processing plants yield Greek-style protein levels without secondary straining. Dutch cooperatives stabilize input costs for private-label retailers serving Benelux discount channels.
Low Fat Yogurt Calories Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented tier structures. Cold-chain captive networks and direct-store-delivery assets separate scale-driven processors from contract-manufacturing-dependent entrants. Three archetypes dominate: integrated dairy cooperatives with captive milk supply, Greek-style specialists with protein-concentration expertise, and multi-format packagers leveraging co-manufacturing partnerships. Competitive moves concentrate on membrane filtration technology licensing and private-label leasing arrangements that reduce capital intensity.
Within the integrated dairy tier, Danone S.A. and Nestlé S.A. occupy positions anchored by captive supply networks and multi-format scale. Chobani LLC exemplifies the product-specialist archetype through Greek-style concentration expertise. These three names represent divergent strategic paths: continental European cold-chain integration, Swiss-packaged multi-brand scale, and North American direct-store-delivery channel control.
| Leading Market Players |
|---|
| Danone S.A. |
| Chobani LLC |
| Nestlé S.A. |
| General Mills Inc. |
| Fage International S.A. |
| Muller UK & Ireland Group |
| CP-Meiji Company Ltd. |
| Parmalat S.p.A. |
| Tillamook |
| Others |
Value Network & Pricing Analysis
Skim-milk powder futures volatility determines both pricing tier spreads and supply chain shape across the low fat yogurt calories category. New Zealand and Dutch cooperative hedging instruments compress margin buffers for processors lacking forward-contract coverage, forcing tier separation between indexed contract buyers and spot-market dependents.
Pricing Analysis
Cost-plus contracts indexed to Global Dairy Trade auction settlements dominate procurement between large cooperatives and private-label retailers. Three-tier pricing structure across premium, standard, and economy levels separates USDA organic certified SKUs from conventional formulations and private-label discounter specifications. Pricing pressure stems from clean-label reformulation costs that extend product development cycles without commensurate shelf price recovery. Discounter channel buyers in Germany and the Netherlands exhibit highest price sensitivity, while pharmacy retail channels in France absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Extended payment terms from supermarket consolidators in the United Kingdom and France strain working capital for mid-tier processors, accelerating supply-chain finance facility adoption. Fresh milk sourcing concentrates in New Zealand, the Netherlands, and Germany, with membrane filtration equipment dependence on Danish and Italian engineering specialists. Tariff exposure on whey protein concentrate imports from the United States threatens Greek-style formulation cost structures. Distribution runs through direct-store-delivery networks in North American metropolitan corridors and temperature-controlled warehouse systems in European retail discounters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
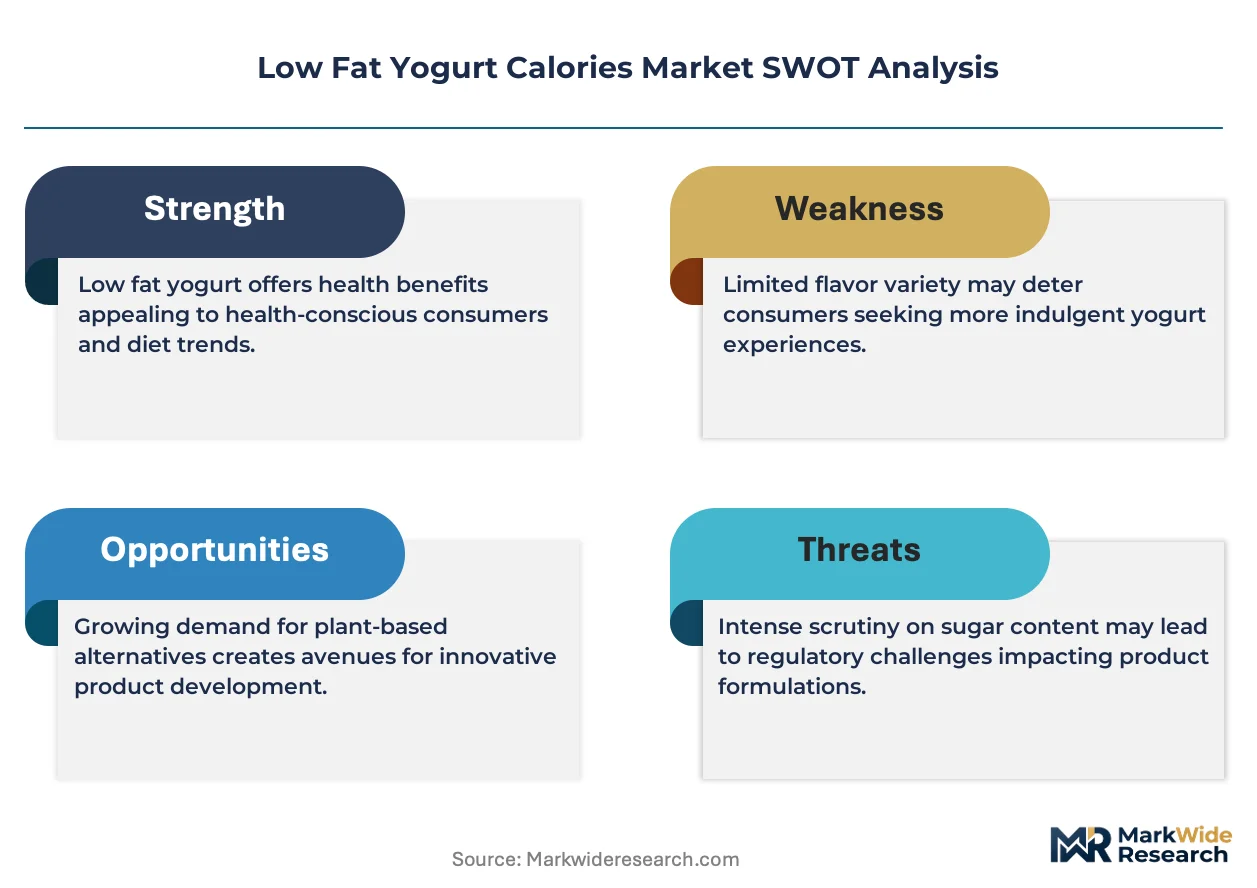
Cold-chain delivery platform interoperability with fitness app ecosystems signals a platform-economics inflection, enabling subscription revenue capture beyond conventional retail slotting fees.
For Market Incumbents: Pre-empt pouch format specialists by acquiring flexible packaging co-manufacturers in the United Kingdom and Netherlands cycling corridors. Deepen upstream control over pasture-sourced milk pools in Normandy and Brittany to secure organic certification premiums before EU F-Gas refrigeration retrofits compress facility expansion timelines.
For New Entrants and Emerging Players: Direct-to-subscription models in London and Paris metro areas represent the most penetrable entry point, bypassing prohibitive supermarket placement fees while capturing recurring revenue from health-conscious households. Ceramic microfiltration technology licensing from Dutch engineering specialists enables Greek-style protein positioning without capital-intensive straining infrastructure.
For Investors and Strategic Acquirers: EU F-Gas Regulation phase-down completion reshapes the acquisition landscape toward CO2 refrigeration-ready assets in Northern Italy and Denmark. Mid-scale processors with membrane filtration retrofit capabilities and captive organic milk contracts offer strongest long-term viability. Watch ammonia refrigeration technician certification program expansion as inflection signal for facility expansion feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Licensing | Ceramic microfiltration retrofits compress capital requirements for Greek-style protein concentration without secondary straining operations. |
| Direct-to-Subscription Launch | Cold-chain delivery platforms in London and Paris bypass conventional supermarket slotting fees while capturing recurring household revenue. |
| Organic Certification Investment | USDA and EU organic standards command 15-20 percent shelf price premiums in United States coastal urban markets. |
| Pouch Format Expansion | Flexible laminated packaging reduces shipping weight for German and French urban transit corridor consumption occasions. |
| CO2 Refrigeration Retrofit | F-Gas Regulation compliance enables facility expansion in France and Germany despite 18-24 month equipment lead times. |
Research Methodology
Operator-level perspectives from dairy plant managers, retail category buyers, cold-chain logistics coordinators, and membrane filtration equipment engineers anchored the qualitative base. Primary interviews combined with secondary validation against Global Dairy Trade auction records, EU EFSA health claim authorization filings, and Nielsen retail audit data for refrigerated dairy categories. Bottom-up volume modeling across production facility capacities and top-down expenditure tracking through supermarket procurement databases enabled triangulation.
Scenario-bracketing framed the analytical approach across the analysis window, with segmentation dimensions spanning product type, fat content tier, packaging format, and regional regulatory cluster. CAGRs derived from production capacity expansion announcements, organic certification penetration curves, and cold-chain infrastructure investment flows. Inputs included skim-milk powder futures volatility patterns and EU F-Gas Regulation compliance timelines.
Practitioners should monitor clean-label enforcement intensity shifts and refrigeration technician certification program expansion for early signals of margin compression or facility expansion bottlenecks. Forecasts reflect documented assumptions on organic certification premium sustainability and membrane filtration technology adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Dairy Protein Market
Dairy Products
South America Flavored Milk Market
Dairy Products
Textured Butter Market
Dairy Products
Organic Dairy Products Market
Dairy Products
Cream Market
Dairy Products
Sour Milk Drinks Market
Dairy Products
Flavored Yogurt Market
Dairy Products
Low-Fat Cheese Nutrition Market
Dairy Products
GCC Camel Dairy Market
Dairy Products
China Dairy Market
Dairy Products
Spoonable Yogurt Market
Dairy Products
Global Dairy Cream Market
Dairy Products
Anhydrous Milk Fat (Butter Oil) Market
Dairy Products
Global Yogurt Market
Dairy Products
Table Butter Market
Dairy Products
Nigeria Yogurt Drinks Market