
 Used Commercial Freezer Market | 2026-2036
Used Commercial Freezer Market Size, Share, and Industry Trends Forecast 2026-2036
Used Commercial Freezer Market Analytics
Market Context
Restaurant chain expansion into secondary markets is decoupling from new equipment procurement budgets, creating parallel demand for certified pre-owned refrigeration assets. True Refrigeration leverages its extensive service network to dominate the refurbishment certification pipeline for reach-in units. Hoshizaki America anchors the high-capacity segment through specialized remanufacturing programs for walk-in freezer systems. Traulsen competes on temperature precision guarantees that extend equipment residual value across multiple ownership cycles.
Technical Definition and Segment Structure
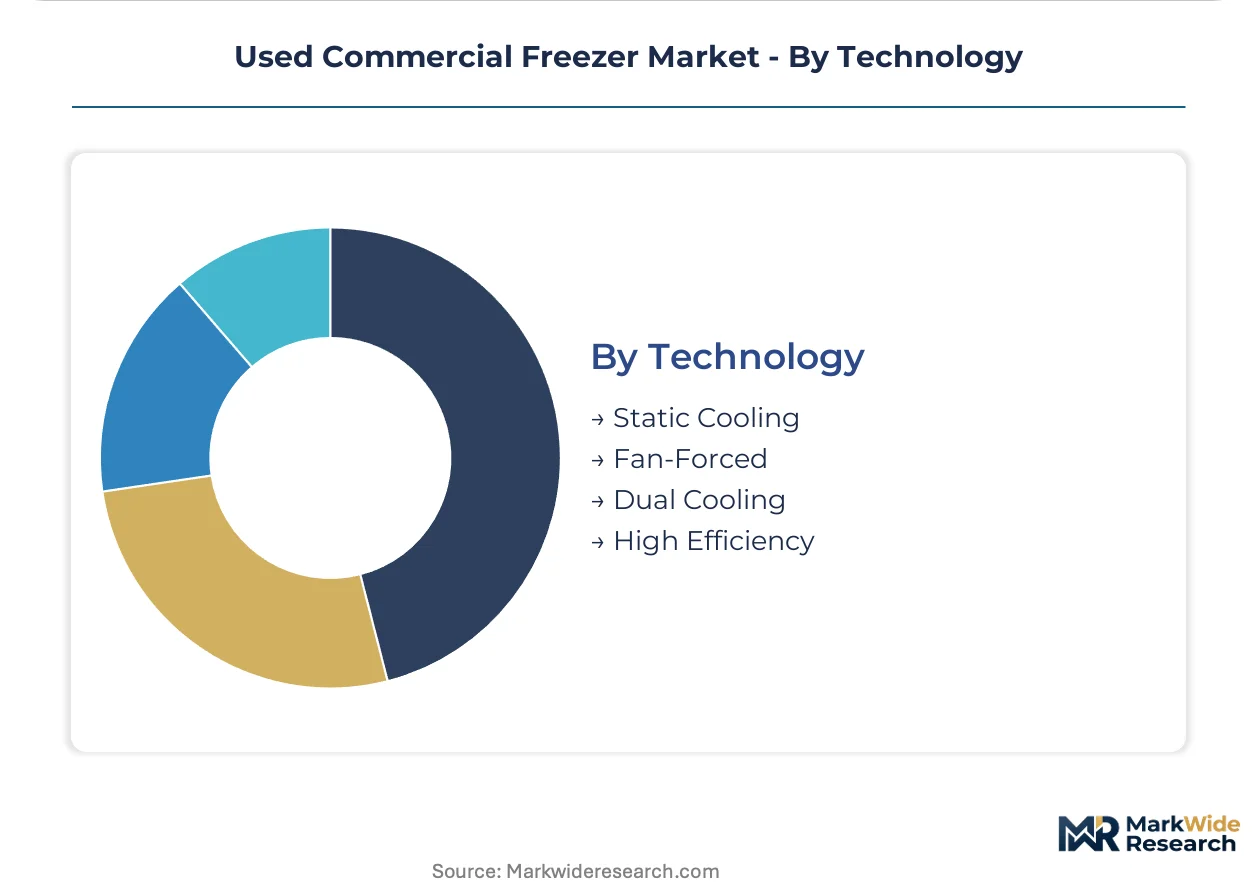
A used commercial freezer denotes a previously operated insulated cabinet or room-scale enclosure, typically constructed from galvanized or stainless steel with polyurethane foam insulation and vapor-compression refrigeration circuits between 1 and 50 horsepower, designed to maintain food products at temperatures at or below 0 degrees Fahrenheit for commercial food storage and display. Reach-in units capture the largest transaction volume due to standardized dimensions and simpler refurbishment protocols, while walk-in systems command superior margin pools because of custom panel fabrication requirements and specialized installation labor. Fan-forced cooling technology leads the resale channel as buyers prioritize uniform temperature distribution and faster pull-down times over static cooling alternatives.
Regulatory Framework and Outlook
The EPA enforces refrigerant phaseout schedules under the AIM Act that compel refurbishers to retrofit or replace hydrofluorocarbon-based systems before resale eligibility. The Department of Energy's commercial refrigeration efficiency standards constrain which legacy units qualify for interstate commerce, filtering supply quality and reshaping refurbishment economics. Stakeholders must monitor state-level appliance efficiency variations and emerging refrigerant compliance databases to anticipate which equipment vintages will retain tradable value.
Market Dynamics
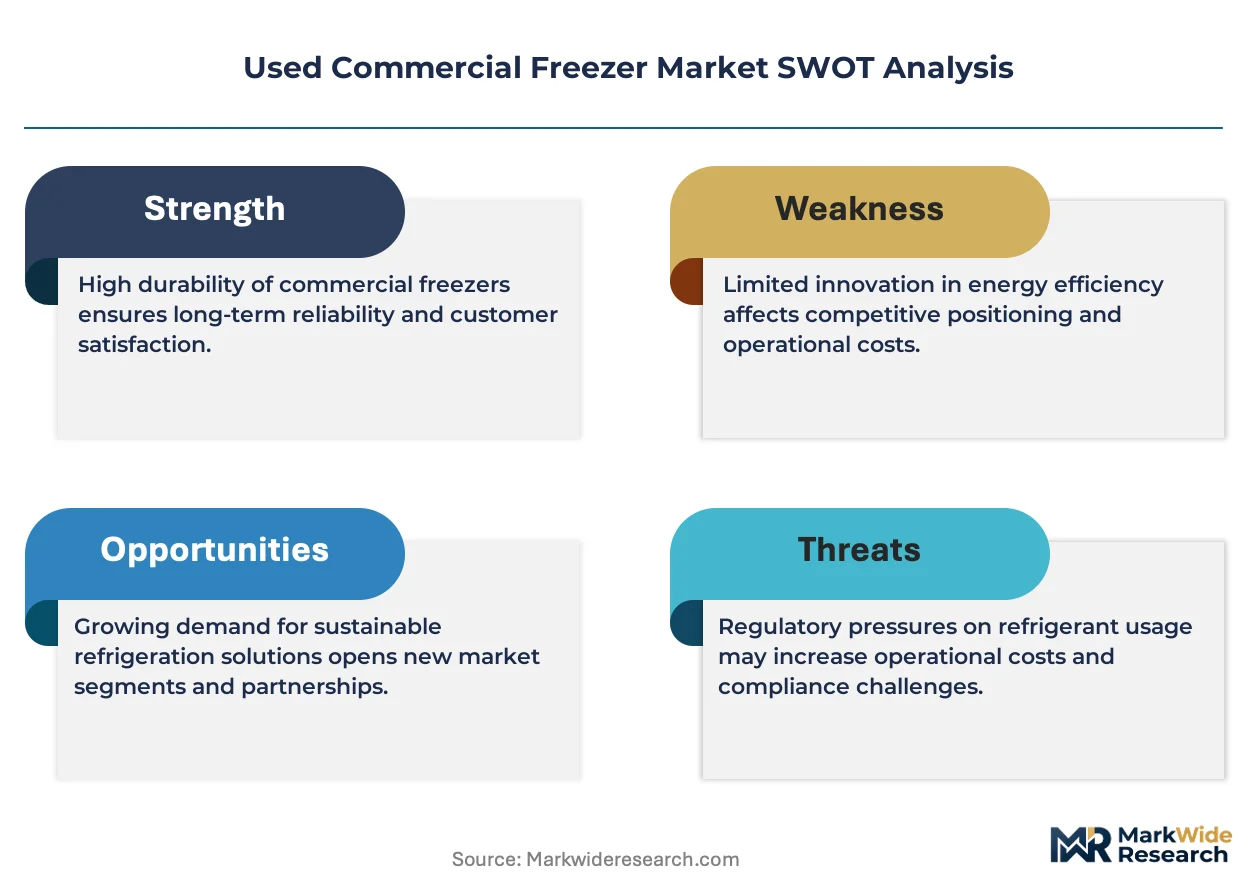
The EPA's phasedown of hydrofluorocarbon refrigerants under the AIM Act is compressing refurbishment timelines and redirecting capital flows toward compliant used equipment with retrofitted coolant systems.
Growth Catalysts
- AIM Act Compliance Deadlines:The EPA's refrigerant phaseout schedule accelerates replacement demand as operators seek pre-upgraded units to avoid retrofit costs.
- Ghost Kitchen Proliferation:Delivery-only foodservice operators in the southeastern United States prioritize refurbished reach-in units to minimize upfront capital deployment.
- Polyurethane Foam Reclamation:Advanced insulation recovery processes reduce panel replacement costs and extend walk-in system refurbishment viability.
Market Restraints
- Copper and Aluminum Price Volatility:Compressor coil and heat exchanger materials expose refurbishers to input cost swings that compress margin predictability.
- Certified Technician Concentration:Skilled refrigeration mechanics cluster in metropolitan Texas and Florida markets, creating service access gaps in secondary geographies.
- Static Cooling Obsolescence:Temperature uniformity limitations in gravity-fed systems render legacy inventory unsalable to food safety-conscious buyers.
Strategic Opportunities
- Texas Secondary Market Penetration:Houston and Dallas-Fort Worth foodservice density growth outpaces new equipment distribution capacity, creating arbitrage potential for certified pre-owned inventory.
- Remote Monitoring Integration:IoT sensor retrofits on refurbished units enable subscription-based temperature compliance services for multi-location operators.
- Georgia Tax Incentive Programs:State-level energy efficiency rebates for commercial kitchen equipment reduce net acquisition costs for refurbished freezer buyers.
Industry Challenges
- EPA 608 Certification Bottlenecks:Technician credentialing delays constrain refurbishment throughput during peak replacement seasons.
- Legacy Control System Integration:Analog thermostat units require specialized interface adapters to connect with modern building management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Used Commercial Freezer Market |
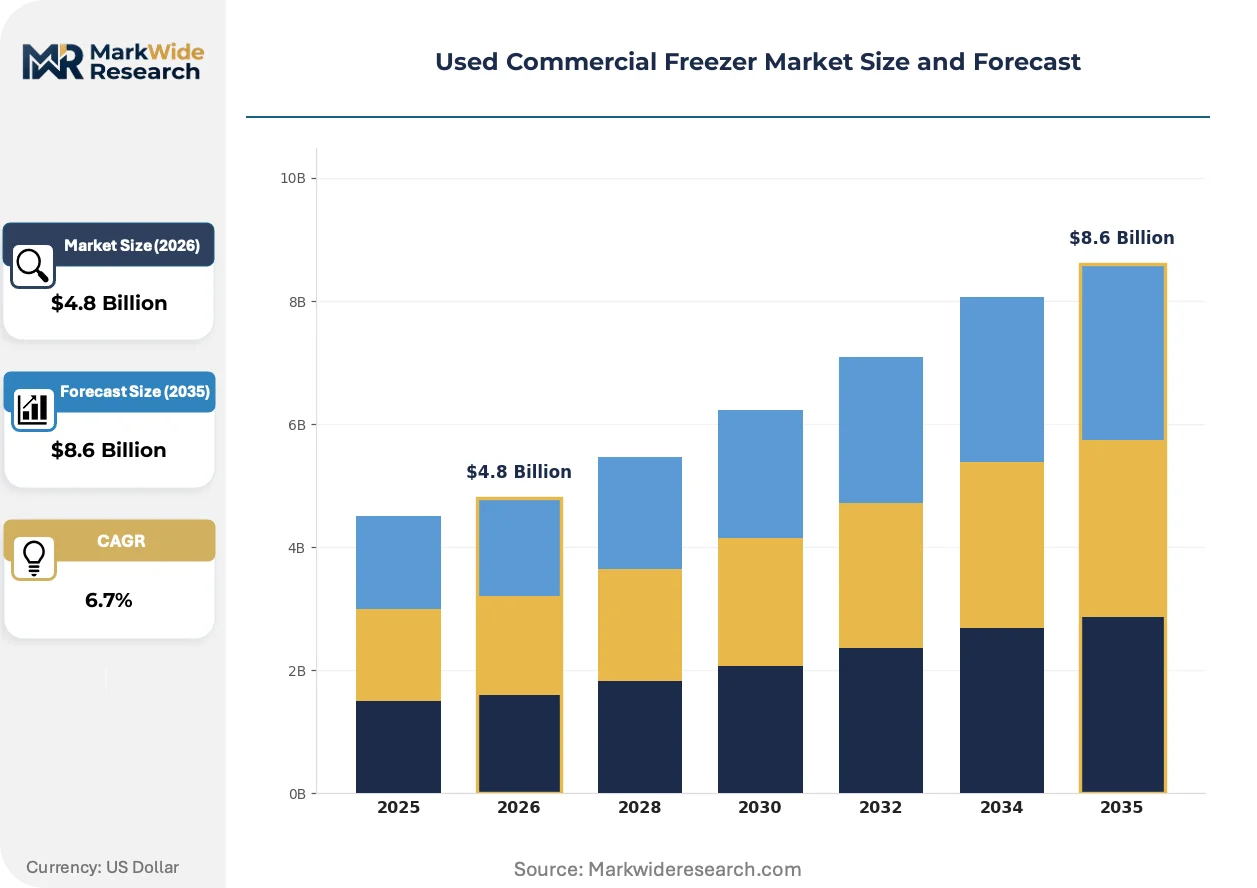
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reach-In, Walk-In, Display Freezers, Chest Freezers End User: Restaurants, Supermarkets, Convenience Stores, Foodservice Providers Size: Small, Medium, Large, Extra Large Technology: Static Cooling, Fan-Forced, Dual Cooling, High Efficiency |
| Companies Covered | True Refrigeration, Hoshizaki America, Traulsen, Beverage-Air, Turbo Air, Follett Corporation, Nor-Lake, Master-Bilt, ACityDiscount, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Used Commercial Freezer Market Evolving Landscape
Digital retrofit technologies and refrigerant chemistry advances are compressing equipment lifecycles while creating new service revenue layers around refurbished assets.
Variable-speed compressor drives are unifying energy efficiency with temperature precision in refurbished reach-in units. Independent restaurants in North Carolina and South Carolina adopt these retrofitted systems at accelerating rates. The technology is unifying what were previously separate premium and standard equipment tiers into a single certified pre-owned category.
The EPA's refrigerant management certification requirements under Section 608 tighten enforcement through 2025. Refurbishers must document coolant recovery and replacement protocols to maintain interstate resale eligibility. Walk-in freezer systems face the steepest compliance burden due to larger refrigerant charge volumes and complex circuit architectures.
Subscription-based equipment-as-a-service contracts are displacing traditional capital purchase models among multi-unit restaurant operators. Third-party refurbishment specialists capture recurring revenue through bundled maintenance and compliance monitoring. This shift concentrates in Florida and Texas markets where private equity-backed restaurant groups pursue balance sheet efficiency.
Used Commercial Freezer Market Segmentation
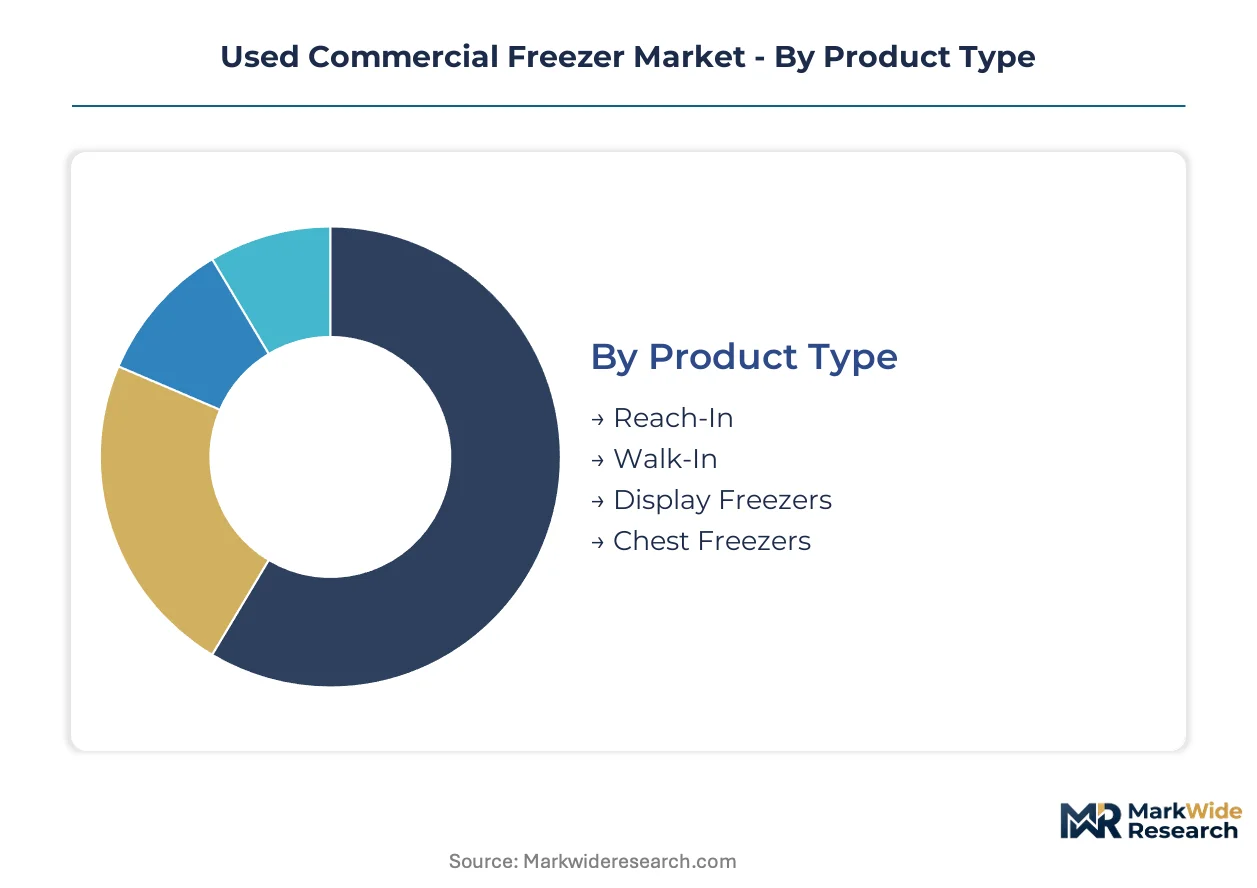
Segmentation in the used commercial freezer market determines refurbishment economics and resale velocity. Equipment configuration, operator scale, and technology vintage create distinct value tiers that reshape procurement patterns across foodservice channels.
Product Type:
Customization intensity varies sharply across this category, from standardized cabinet dimensions to site-fabricated envelope systems.
- Reach-In:Self-contained vertical cabinets with single or multiple doors, typically 1 to 3 horsepower refrigeration circuits, designed for kitchen back-of-house storage. Ghost kitchen operators in Texas and Florida concentrate procurement here to minimize capital deployment and accelerate facility launches.
- Walk-In:Modular panel-constructed rooms requiring on-site assembly, with refrigeration systems from 5 to 50 horsepower. Foodservice providers pursuing high-volume frozen inventory storage drive demand, though custom panel fabrication and specialized installation labor compress margin pools for refurbishers.
- Display Freezers:Glass-door merchandising units with integrated lighting and temperature visibility for retail environments. Convenience stores favor these for frozen food and ice cream presentation.
- Chest Freezers:Horizontal top-opening cabinets with static or fan-forced cooling, common in supermarket back rooms and small restaurants. Lower refurbishment complexity sustains supply liquidity.
Most installed capacity flows through Reach-In units. Expansion is steepest in Walk-In systems as foodservice density growth outpaces new equipment distribution capacity in secondary markets.
End User:
Capital intensity and replacement frequency differentiate procurement patterns across operator categories.
- Restaurants:Independent and chain operators with varying equipment scale requirements, from single reach-in units to multi-zone walk-in systems. The EPA's AIM Act refrigerant phaseout redirects capital toward pre-upgraded used equipment to avoid retrofit costs and compliance delays.
- Supermarkets:Large-format retailers with extensive frozen food and ice cream display requirements. These operators prioritize fan-forced cooling technology for temperature uniformity across high-traffic merchandising floors.
- Convenience Stores:Limited-footprint operators seeking compact reach-in or chest freezer solutions for frozen beverage and packaged food categories. Procurement concentrates on standardized dimensions to maximize linear shelf productivity.
- Foodservice Providers:Institutional and contract catering operations with centralized production facilities. Walk-in systems dominate here due to batch cooking and bulk frozen storage requirements.
Volume leadership sits with Restaurants. Foodservice Providers are gaining share fastest as institutional outsourcing and ghost kitchen proliferation accelerate equipment turnover.
Size:
Physical scale determines transportation logistics, refurbishment facility requirements, and installation labor specialization.
- Small:Under-counter and worktop units below 10 cubic feet, common in compact kitchen layouts. Bars and cafes in metropolitan clusters drive replacement cycles.
- Medium:Single-door reach-in and small chest configurations between 10 and 30 cubic feet. Independent restaurants dominate transactions in this tier.
- Large:Multi-door reach-in and modest walk-in systems from 30 to 100 cubic feet. Supermarket back rooms and central kitchens concentrate demand here.
- Extra Large:Industrial-scale walk-in and warehouse freezer systems exceeding 100 cubic feet. Distribution centers and large food manufacturing facilities require specialized refurbishment protocols.
Transaction liquidity peaks in Medium sizes. Extra Large systems are expanding most quickly as cold storage infrastructure strains under e-commerce grocery fulfillment demands.
Technology:
Energy efficiency mandates and food safety standards are compressing viable technology vintages while elevating retrofit value.
- Static Cooling:Gravity-fed refrigerant circulation without mechanical air distribution. Temperature uniformity limitations render legacy inventory unsalable to food safety-conscious buyers, accelerating obsolescence.
- Fan-Forced:Mechanical air circulation with evaporator fans for rapid temperature recovery and uniform distribution. This technology leads the resale channel as operators prioritize pull-down speed and zone consistency.
- Dual Cooling:Separate refrigeration circuits for freezer and refrigerator compartments in combination units. Convenience stores and small restaurants favor these for space-constrained layouts.
- High Efficiency:Variable-speed compressor drives, advanced insulation, and optimized heat exchanger designs meeting or exceeding current DOE standards. North Carolina and South Carolina restaurants adopt these retrofitted systems at accelerating rates.
Fan-Forced systems command the largest installed base. High Efficiency retrofits are climbing the fastest as energy cost pressures and rebate programs reshape procurement calculus.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting refurbishment capacity toward jurisdictions with streamlined EPA compliance pathways and lower refrigerant recovery costs. The United States dominates transaction volume, though state-level efficiency variations create internal migration patterns for certified pre-owned inventory.
United States
Independent restaurants and ghost kitchen operators in Texas and Florida drive replacement demand for reach-in units with retrofitted coolant systems. The EPA's AIM Act refrigerant phaseout compels buyers toward pre-upgraded equipment to avoid compliance delays. Houston and Dallas-Fort Worth foodservice density growth outpaces new equipment distribution, creating arbitrage potential for certified inventory.
Germany
Commercial kitchens and institutional foodservice providers prioritize energy-efficient refurbished walk-in systems with advanced insulation. The EU F-Gas Regulation tightens hydrofluorocarbon restrictions, redirecting procurement toward compliant used equipment. Bavaria's manufacturing clusters and North Rhine-Westphalia's logistics hubs concentrate refurbishment expertise and cold storage infrastructure investment.
United Kingdom
Convenience store chains and supermarket back-room operators seek fan-forced cooling retrofits for temperature uniformity compliance. Post-Brexit regulatory divergence from EU F-Gas schedules creates uncertainty in equipment import eligibility. Greater London and Midlands urban foodservice density accelerates replacement cycles for medium-capacity reach-in units.
Japan
Compact kitchen operators and convenience store franchises drive demand for small-format refurbished freezers with IoT monitoring compatibility. METI energy efficiency standards filter which equipment vintages retain resale value. Kanto region Tokyo-Osaka corridor concentration supports specialized refurbishment facilities for high-precision temperature control systems.
Australia
Remote mining camp catering and coastal tourism foodservice operators prioritize durable refurbished chest freezers with static cooling alternatives. State-level appliance efficiency variations create procurement complexity across Queensland and Western Australia. Sydney and Melbourne metropolitan clusters anchor certified technician networks for complex walk-in system refurbishment.
Used Commercial Freezer Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with OEM-affiliated refurbishers commanding premium pricing for certified pre-owned units while independent operators compete on transaction velocity. The vendor base organizes into three tiers: manufacturer-authorized certification programs, regional refurbishment specialists, and secondary equipment brokers. Consolidation pressure concentrates among mid-scale operators seeking EPA 608 certification infrastructure. Dominant competitive moves include backward integration into refrigerant recovery services and geographic expansion into underserved secondary markets.
Among manufacturer-authorized specialists, True Refrigeration, Hoshizaki America, and Traulsen occupy positions that exemplify the branded certification archetype. True Refrigeration represents the reach-in refurbishment pipeline dominance visible in extensive service network leverage. Hoshizaki America anchors the high-capacity walk-in segment through specialized remanufacturing program structures. Traulsen exemplifies temperature precision guarantee positioning that extends equipment residual value across multiple ownership cycles.
| Leading Market Players |
|---|
| True Refrigeration |
| Hoshizaki America |
| Traulsen |
| Beverage-Air |
| Turbo Air |
| Follett Corporation |
| Nor-Lake |
| Master-Bilt |
| ACityDiscount |
| Others |
Value Network & Pricing Analysis
Variable-speed compressor retrofits are compressing refurbishment economics while concentrating supply capability among EPA-certified operators with captive refrigerant recovery infrastructure. This technology transition simultaneously elevates input costs for copper windings and electronic drives while filtering uncertified competitors from viable supply tiers.
Pricing Analysis
Retailer markup layers in the certified pre-owned channel typically run 35-50 points above refurbishment cost, with manufacturer-authorized certification programs commanding the widest spreads. Pricing stratifies across OEM-backed premium tiers, independent specialist standard tiers, and broker-mediated economy tiers based on warranty length and EPA 608 documentation completeness. Cost compression in the economy tier is intensifying because copper and aluminum volatility erodes refurbisher margin predictability. Ghost kitchen operators in Texas and Florida exhibit the highest price sensitivity, while institutional foodservice providers prioritize temperature precision guarantees over acquisition cost.
Supply Chain Analysis
EPA 608 certification gating restricts viable refurbishment capacity to operators with documented refrigerant recovery protocols and interstate commerce eligibility. Supply concentrates in the United States, Germany, and Japan where regulatory enforcement maturity supports certified pre-owned equipment flows. Production draws from reclaimed compressor cores, recovered polyurethane foam insulation, and retrofitted electronic control systems. Single-source vulnerability sits with copper coil suppliers exposed to commodity price swings. Distribution runs through manufacturer-authorized service networks, regional refurbishment specialists, and secondary equipment brokers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The used commercial freezer market reads as a late-cycle quality story as EPA AIM Act compliance redirects procurement toward certified pre-owned units with retrofitted coolant systems over uncertified alternatives.
For Market Incumbents: Lock in backward integration into refrigerant recovery services to capture margin pools currently leaking to third-party EPA 608 contractors. Consolidate regional refurbishment specialists in Texas and Florida to secure technician concentration advantages against emerging broker platforms. The priority lever centers on captive certification infrastructure that filters price-competitive uncertified rivals from interstate resale eligibility. For New Entrants and Emerging Players: The mid-market price-point gap between True Refrigeration's premium certified tier and uncertified broker inventory creates arbitrage space for independent specialists with targeted EPA compliance investment. White-space targets include Georgia's tax incentive-eligible refurbished equipment channel and remote monitoring subscription bundling for multi-location restaurant operators. The most penetrable entry vector runs through Houston and Dallas-Fort Worth foodservice density growth outpacing new equipment distribution capacity. For Investors and Strategic Acquirers: Valuations sit cheapest among independent regional refurbishers lacking EPA 608 certification infrastructure but possessing established technician networks and local customer relationships. Long-term viability favors operators with demonstrated compliance documentation capabilities and geographic positioning in AIM Act acceleration corridors. The signal to watch is EPA enforcement intensity tightening refrigerant recovery documentation requirements, which would compress uncertified inventory liquidity and concentrate share among compliant operators.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Recovery Infrastructure Investment | EPA 608 compliance documentation secures interstate resale eligibility and filters price-competitive rivals. |
| IoT Sensor Retrofit Integration | Remote temperature monitoring subscriptions capture recurring revenue from multi-location restaurant operators. |
| Regional Certification Program Expansion | Georgia and Texas tax incentive alignment reduces net acquisition costs and accelerates procurement velocity. |
| Polyurethane Foam Reclamation Scale-Up | Advanced insulation recovery processes extend walk-in system refurbishment viability and compress panel replacement economics. |
| Variable-Speed Drive Retrofit Deployment | Energy efficiency retrofits unify premium and standard equipment tiers into single certified pre-owned category. |
Research Methodology
Bottom-up foodservice operator modeling reconciled against top-down refurbishment capacity tracking forms the analytical core of this study. Primary interviews with commercial kitchen equipment procurement directors, EPA-certified refrigeration technicians, ghost kitchen facility operators, and institutional foodservice contract managers combined with secondary validation from EPA AIM Act regulatory filings, DOE commercial refrigeration efficiency standards, and state-level appliance rebate program databases. Trade flow analysis of copper and aluminum pricing volatility informed input cost assumptions.
Input-output matrices map reach-in versus walk-in unit refurbishment throughput against end-user segment replacement cycles across the projection horizon. Segmentation dimensions include product configuration, operator scale category, technology vintage tier, and regional regulatory cluster. CAGRs derive from equipment stock turnover rates, refrigerant phaseout compliance deadlines, and foodservice density growth patterns. Forecast inputs incorporate polyurethane foam reclamation process maturation and variable-speed compressor retrofit adoption curves.
Caveats apply where EPA enforcement intensity or copper price volatility could materially shift refurbishment economics and certified pre-owned equipment availability. Forecasts reflect assumptions about AIM Act implementation timelines and state-level efficiency standard convergence. A model refresh is warranted upon material change in refrigerant recovery cost structures or technician certification throughput capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Magnetic Grill Market
Food Processing Equipment
Walk-In Refrigerator Market
Food Processing Equipment
UHT Systems Market
Food Processing Equipment
Pasteuriser Market
Food Processing Equipment
Individual Quick Freezing Market
Food Processing Equipment
Canning Equipment Market
Food Processing Equipment
High-Pressure Processing Equipment Market
Food Processing Equipment
Countertop Blast Chiller Market
Food Processing Equipment
Global Food and Beverage Coding and Marking Equipment Market
Food Processing Equipment
North America Beverage Filling and Capping Machine Market
Food Processing Equipment
Contact and Convective Dryers Market
Food Processing Equipment
Ice Cream Freezer Market
Food Processing Equipment
Food Preservation Equipment Market
Food Processing Equipment
Industrial Food Milling Machine Market
Food Processing Equipment
Industrial Planetary Mixers Market
Food Processing Equipment
Industrial Steam Peeler Market