
 South America Dairy Market | 2026-2036
South America Dairy Market Size, Share, and Industry Trends Forecast 2026-2036
South America Dairy Market Insights
Subscription-based cold-chain monitoring and predictive maintenance contracts is realigning how dairy processors monetize equipment uptime and quality assurance. Groupe Lactalis leverages its Brazilian processing footprint to dominate UHT milk distribution across the Mercosur corridor. Nestlé S.A. anchors premium yogurt and specialized nutrition lines through controlled retail shelf space in Colombian and Peruvian cities. Danone S.A. differentiates on probiotic R&D, sustaining consumer loyalty in Argentina's competitive fermented dairy segment.
Dairy encompasses fluid milk, fermented products, concentrated solids, and fat-based derivatives standardized for protein content, microbial safety, and shelf stability through pasteurization, homogenization, or ultra-high-temperature treatment; these outputs serve human nutrition, food manufacturing, and food service preparation across industrial and commercial channels. Milk commands the largest volume share but faces margin compression from private-label competition, while cheese captures disproportionate value pools in Brazilian and Argentine export channels. Yogurt competes on functional positioning, with probiotic strains and reduced-sugar formulations reshaping supermarket and convenience store assortment priorities.
ANVISA in Brazil and SENASA in Argentina enforce microbiological standards and labeling rules that determine which processors gain retail and food service access, while Mercosur harmonization protocols streamline cross-border dairy trade certification. The country's national food safety regulator in Uruguay maintains stricter somatic cell count thresholds than regional neighbors, filtering export eligibility for smaller cooperatives. Stakeholders must track how evolving phytosanitary negotiations and carbon-footprint disclosure requirements reshape sourcing decisions and plant investment timelines.
Market Dynamics
Mercosur food safety harmonization is compressing cross-border certification timelines while cold-chain subscription models restructure processor capital allocation away from asset ownership toward uptime guarantees.
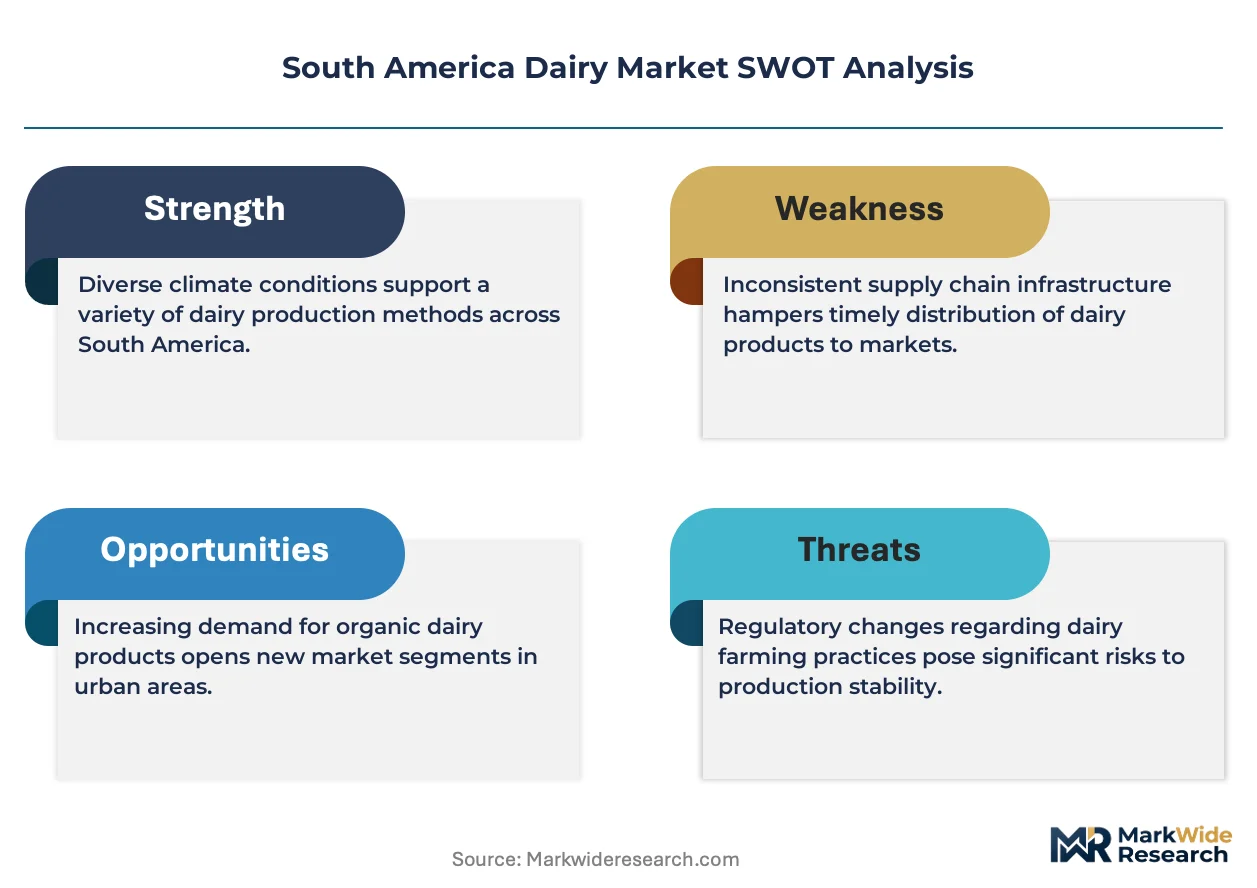
Growth Catalysts
- ANVISA-SENASA Mutual Recognition:Brazilian and Argentine regulators now accept each other's pasteurization certifications, cutting border inspection delays for fluid milk shipments.
- Food Service Procurement Centralization:São Paulo-based restaurant chains are consolidating dairy purchasing through contracted processors, locking in volume commitments for UHT and condensed milk.
- Precision Fermentation Monitoring:IoT-enabled pH and temperature sensors in Argentine yogurt plants are reducing batch failure rates and extending culture viability windows.
Market Restraints
- Fodder Cost Volatility:Argentine alfalfa and Brazilian soybean meal prices swing with climate patterns, squeezing cooperative margins before milk reaches processors.
- Processor Concentration in São Paulo State:Three facilities control over half of Brazil's fluid milk pasteurization capacity, creating single-point vulnerability for southeastern distribution.
- Substitution by Plant-Based Beverages:Oat and soy drink formulations are capturing shelf space in Colombian and Peruvian supermarket dairy aisles.
Strategic Opportunities
- Uruguayan Export Channel Expansion:Stricter national somatic cell standards position Uruguayan cooperatives for premium Asian market access where competitors face rejection.
- Direct-to-Horeca Distribution:Bypassing traditional wholesale layers, Colombian processors are building refrigerated truck fleets serving Bogotá hotel and restaurant kitchens directly.
- Carbon Footprint Disclosure Mandates:Emerging Mercosur environmental labeling requirements favor early adopters with audited supply chain data for methane and energy intensity.
Industry Challenges
- Refrigeration Technician Scarcity:Cold-chain maintenance expertise concentrates in São Paulo and Buenos Aires, leaving regional plants dependent on fly-in contractors.
- Legacy ERP Integration:Argentine cooperatives running 1990s inventory systems face data fragmentation when connecting to modern traceability platforms demanded by ANVISA.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Dairy Market |
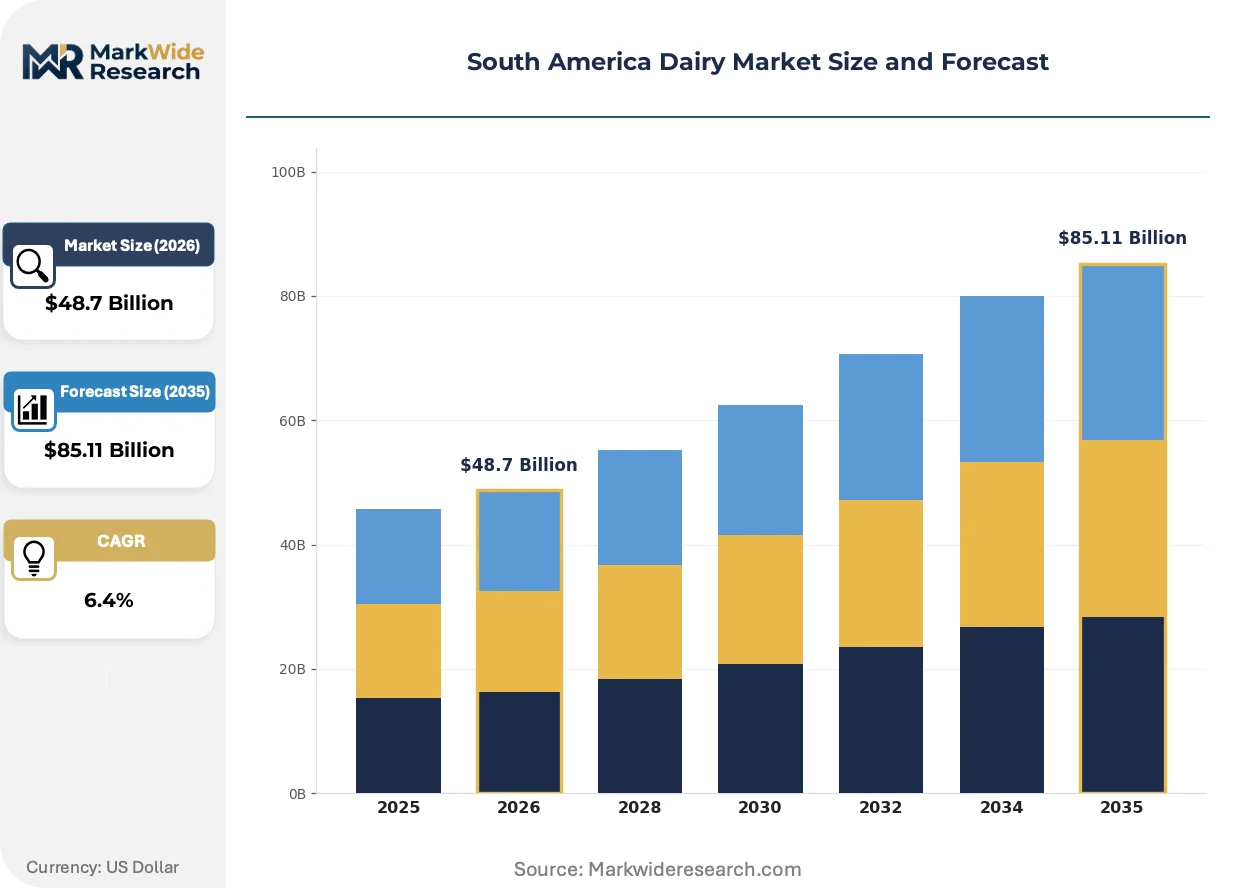
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $85.11 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milk, Cheese, Butter, Yogurt End User: Households, Food Service, Retail, Industrial Distribution Channel: Supermarkets, Online, Dairy Shops, Convenience Stores Packaging Type: Bottles, Tetra Packs, Cartons, Pouches |
| Companies Covered | Groupe Lactalis, Mastellone Hermanos SA, Danone S.A., Nestlé S.A., Laticinios Bela Vista Ltda (Piracanjuba), Fonterra Co-Operative, SanCor, Conaprole, Colanta, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Dairy Market Trends and Innovations
Digital monitoring infrastructure and shifting protein sourcing preferences are restructuring how dairy value is captured and delivered across South American markets.
Continuous-flow pasteurization systems with real-time microbial detection are expanding into mid-sized Brazilian processors previously limited to batch equipment. Minas Gerais and Paraná cooperatives are retrofitting plants with these units to qualify for extended-shelf-life contracts with retail chains. The technology is expanding into private-label supply agreements previously dominated by multinational-owned facilities.
ANVISA's updated nutrition labeling rules now mandate added-sugar disclosure on flavored milk and drinkable yogurt packaging. Brazilian reformulation teams are accelerating clean-label development to avoid front-of-package warning symbols. The regulation most impacts São Paulo-based processors supplying competitive supermarket channels where shelf positioning depends on compliance timing.
Colombian convenience store chains are unbundling dairy procurement from traditional distributor bundles, negotiating direct refrigerated delivery agreements with regional cheese and yogurt makers. This bypasses Bogotá wholesale terminals and compresses delivery cycles from weekly to thrice-weekly. The pattern is most visible in Medellín and Cali urban corridors where store density supports dedicated route economics.
South America Dairy Market Segmentation
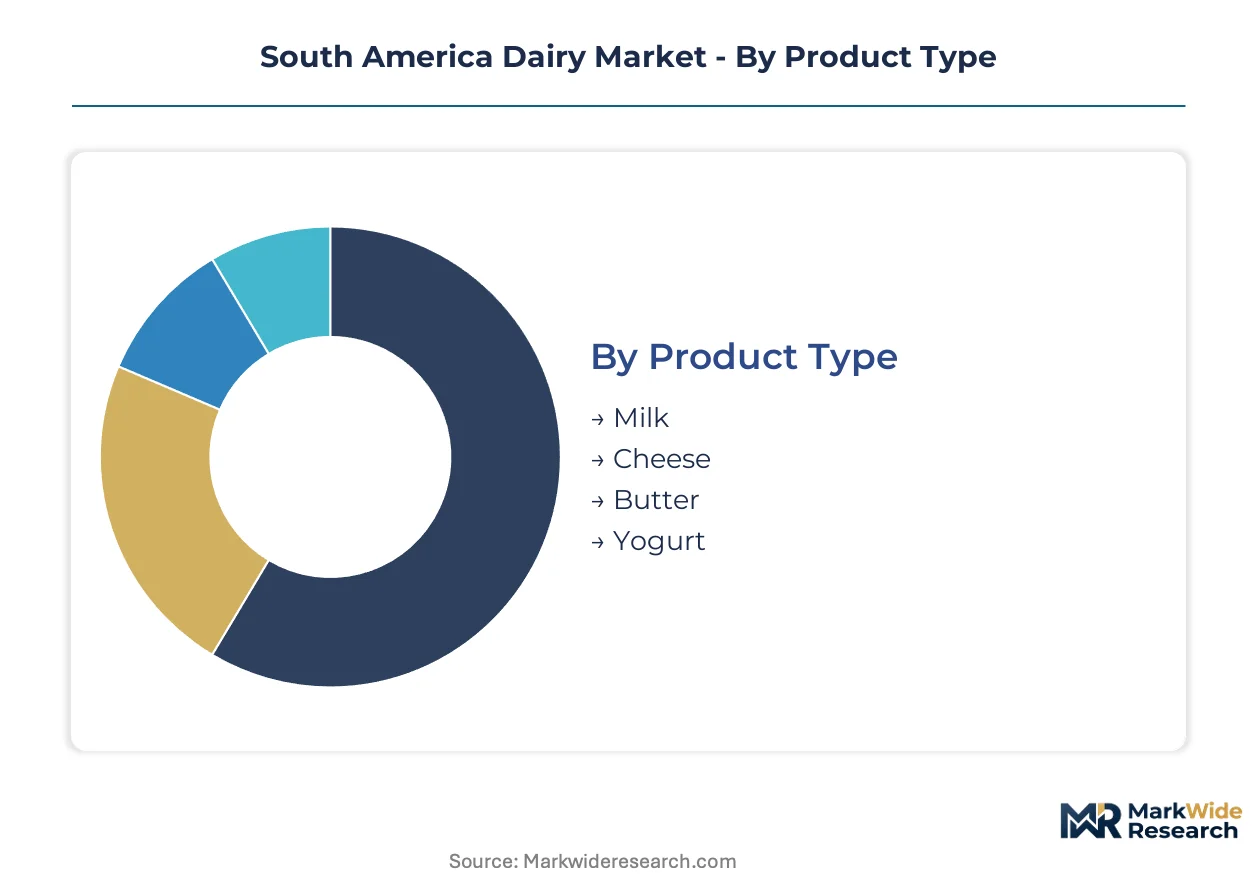
Dairy processors across South America configure production lines and certification pathways around four distinct taxonomies. Each segmentation dimension carries unique regulatory burdens and margin structures that determine facility investment priorities.
Product Type:
ANVISA pasteurization certificates govern fluid milk and UHT products, while SENASA's cheese aging protocols and probiotic strain registrations create layered approval requirements for fermented and fat-based derivatives.
- Milk:Standardized fluid and UHT variants dominate procurement contracts from São Paulo restaurant chains. ANVISA's mutual recognition with SENASA accelerates cross-border shipment clearances for pasteurized volumes. Leading the category by volume: Milk. Growing fastest: Yogurt.
- Cheese:Aged and fresh curd varieties command premium positioning in Brazilian export channels. Stricter Uruguayan somatic cell thresholds filter cooperatives seeking Asian market access. Argentine processors leverage Mercosur harmonization to reduce certification duplication for hard cheese exports.
- Butter:Fat-standardized spreads and cooking fats serve industrial bakery and food service channels. Brazilian private-label competition compresses margins for commodity-grade production.
- Yogurt:Probiotic and reduced-sugar formulations reshape Colombian and Peruvian retail assortments. ANVISA's added-sugar disclosure mandates accelerate clean-label reformulation timelines.
Volume concentrates in fluid milk procurement. Steepest expansion trajectory: probiotic yogurt lines.
End User:
Customer type determines cold-chain intensity and payment cycle structures, with food service operators demanding extended shelf-life guarantees that households rarely require.
- Households:Supermarket and convenience store purchases drive standardized UHT and fresh milk volumes. São Paulo state processors capture dominant share through retail shelf-space negotiations.
- Food Service:São Paulo-based restaurant chains consolidate dairy purchasing through contracted processors, locking in volume commitments for condensed milk and cooking creams. Direct-to-Horeca distribution models in Bogotá bypass traditional wholesale layers.
- Retail:Supermarket private-label competition compresses fluid milk margins while cheese and yogurt retain value through branded positioning. Colombian convenience chains unbundle procurement from distributor bundles for dedicated refrigerated routes.
- Industrial:Bakery and confectionery manufacturers source butter solids and milk powders through bulk contracts. Argentine cooperatives face data fragmentation when connecting legacy ERP systems to modern traceability platforms demanded by ANVISA.
Dominant demand source: retail channels. Expanding most quickly: food service procurement centralization.
Distribution Channel:
Channel selection dictates refrigeration infrastructure requirements and certification documentation depth, with online platforms introducing last-mile temperature monitoring obligations.
- Supermarkets:Dominant shelf-space allocation determines brand visibility for yogurt and cheese lines. ANVISA nutrition labeling compliance timing affects competitive positioning in São Paulo's contested retail corridors.
- Online:Direct-to-consumer refrigerated delivery requires cold-chain subscription monitoring to maintain quality guarantees. Emerging channel with infrastructure investment concentrated in Buenos Aires and São Paulo metropolitan zones.
- Dairy Shops:Traditional specialized retailers persist in Argentine and Uruguayan urban centers, emphasizing fresh curd and artisan cheese varieties.
- Convenience Stores:Colombian chains in Medellín and Cali negotiate thrice-weekly direct delivery from regional processors, compressing traditional weekly wholesale cycles.
Highest volume throughput: supermarkets. Gaining share fastest: convenience store direct distribution.
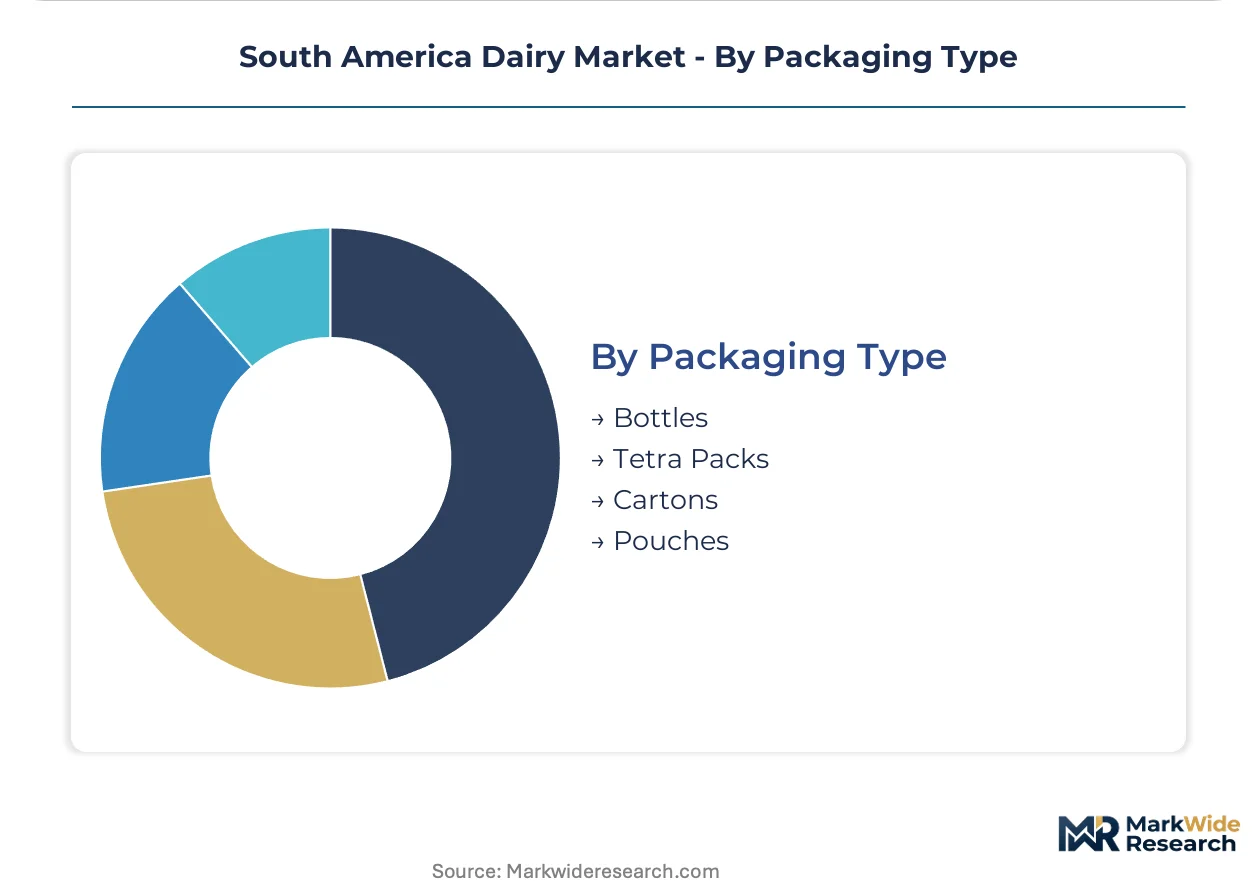
Packaging Type:
Material selection shapes shelf-life extension capabilities and recycling compliance burdens under emerging Mercosur environmental labeling frameworks.
- Bottles:PET and HDPE containers dominate fresh milk distribution with shorter shelf-life requirements. Brazilian recycling infrastructure varies by state, affecting post-consumer compliance costs.
- Tetra Packs:Aseptic carton technology enables UHT milk distribution across the Mercosur corridor without continuous refrigeration. Groupe Lactalis leverages Brazilian processing footprint for extended-shelf-life contract fulfillment.
- Cartons:Gable-top containers serve refrigerated fresh milk segments with moderate shelf-life demands. São Paulo processors favor this format for private-label retail contracts.
- Pouches:Flexible film packaging reduces material costs for commodity milk and drinkable yogurt in price-sensitive Colombian and Peruvian markets. Limited recycling infrastructure constrains environmental positioning.
Dominant format by volume: Tetra Packs. Climbing the fastest: pouch formats in emerging markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil produces more milk than any South American country yet Argentina and Uruguay dominate cheese exports. Consumption concentrates in coastal cities while interior production zones face cold-chain gaps.
Brazil
São Paulo state processors command dominant fluid milk volumes through retail shelf-space negotiations. ANVISA pasteurization certificates govern cross-border shipments under mutual recognition with Argentine regulators. Minas Gerais and Paraná cooperatives retrofit plants with continuous-flow pasteurization to qualify for extended-shelf-life retail contracts.
Argentina
Buenos Aires anchors fermented dairy demand where probiotic yogurt lines reshape supermarket assortments. SENASA cheese aging protocols and strain registrations create layered approval requirements for export-bound production. Córdoba and Santa Fe dairy belts concentrate processing capacity for hard cheese varieties targeting Mercosur markets.
Colombia
Bogotá hotel and restaurant kitchens drive direct-to-Horeca distribution models bypassing traditional wholesale layers. Convenience store chains in Medellín and Cali negotiate thrice-weekly refrigerated delivery from regional cheese and yogurt makers. Colombian processors build captive truck fleets serving urban corridors with dedicated route economics.
Uruguay
Stricter national somatic cell count thresholds than regional neighbors filter export eligibility for smaller cooperatives. The country's national food safety regulator maintains premium standards positioning Uruguayan producers for Asian market access. Montevideo-based cooperatives leverage certification advantages where competitors face rejection.
Peru
Lima metropolitan demand concentrates in supermarket private-label competition compressing fluid milk margins. Oat and soy drink formulations capture shelf space in dairy aisles alongside traditional offerings. Arequipa and Trujillo regional processors face cold-chain infrastructure gaps limiting fresh product distribution reach.
South America Dairy Market Competitive Landscape
Top-tier vendors anchor multinational scale, while domestic cooperatives and regional specialists occupy mid-tier positioning. The market structure reflects consolidation around processing capacity in southeastern Brazil alongside fragmentation across Argentine cooperative networks. Three strategic archetypes predominate: multinational brand owners leveraging controlled retail shelf space, national cooperatives with backward integration into milk supply, and regional processors specializing in fresh curd and artisan varieties. Capacity expansion and direct distribution network buildout represent the dominant competitive moves reshaping procurement relationships.
Among French-based multinational operators, Groupe Lactalis and Danone S.A. occupy positions exemplifying scale-driven UHT and probiotic specialization respectively. Argentine cooperative Mastellone Hermanos S.A. represents the national dairy archetype with integrated supply chain control. These three entities illustrate how geographic origin and corporate structure map to distinct competitive positioning within the regional market hierarchy.
| Leading Market Players |
|---|
| Groupe Lactalis |
| Mastellone Hermanos SA |
| Danone S.A. |
| Nestlé S.A. |
| Laticinios Bela Vista Ltda (Piracanjuba) |
| Fonterra Co-Operative |
| SanCor |
| Conaprole |
| Colanta |
| Others |
Pricing and Supply Chain Analysis
Food service procurement centralization in São Paulo restaurant chains forces processors to absorb cold-chain subscription costs into contract pricing, compressing margins for smaller cooperatives unable to scale uptime guarantees. ANVISA's mutual recognition with SENASA accelerates cross-border fluid milk shipments but intensifies price competition as Argentine processors gain shelf access in Brazilian retail corridors.
Pricing Analysis
Margin tightening in private-label fluid milk reflects São Paulo supermarket chains leveraging volume concentration to extract annual cost-down commitments from processors. Pricing stratifies across premium probiotic yogurt, standard UHT milk, and economy pouch formats in Colombian price-sensitive markets. Price differentiation hinges on ANVISA certification tier and cold-chain subscription bundling. Food service operators demonstrate lowest price sensitivity due to locked-in volume contracts, while household retail segments drive aggressive private-label substitution.
Supply Chain Analysis
Domestic-content mandates in Brazilian dairy procurement favor cooperatives with backward integration into Minas Gerais and Paraná milk supply basins over import-dependent competitors. Supply concentrates in São Paulo state pasteurization facilities, Argentine Córdoba-Santa Fe cheese belts, and Uruguayan Montevideo export cooperatives. Raw material flows draw from Brazilian soybean meal processors, Argentine alfalfa growers, and regional Tetra Pack aseptic carton suppliers. Single-source vulnerability persists in southeastern Brazil where three facilities control majority fluid milk capacity. Distribution runs through supermarket retail chains, direct-to-Horeca refrigerated fleets, and traditional wholesale layers in secondary cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ANVISA's updated nutrition labeling mandates and added-sugar disclosure rules erect compliance barriers that favor incumbent processors with dedicated reformulation teams and shelf-space negotiation leverage.
For Market Incumbents: Acquire direct-to-Horeca refrigerated distribution fleets to bypass wholesale margin erosion in Bogotá and Medellín urban corridors. Lock in exclusive volume commitments from São Paulo restaurant chains through multi-year UHT and condensed milk contracts. Defend against oat and soy beverage substitution by accelerating clean-label probiotic yogurt development ahead of ANVISA compliance deadlines. For New Entrants and Emerging Players: Begin with Uruguayan cooperative export channels where stricter somatic cell standards create premium positioning for Asian market access unavailable to Argentine competitors. Target Colombian convenience store direct distribution in Cali and Medellín corridors where thrice-weekly delivery models bypass traditional wholesale layers. Establish go-to-market presence through carbon footprint audit services as Mercosur environmental labeling requirements emerge. For Investors and Strategic Acquirers: The window for entry favors vertically integrated cooperatives with captive milk supply in Minas Gerais or Paraná production zones. Monitor ANVISA-SENASA harmonization progress as inflection signal—accelerated mutual recognition protocols will compress cross-border certification timelines and reward early-compliant processing assets. Long-term viability rests on cold-chain subscription model adoption and precision fermentation monitoring infrastructure deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Horeca Distribution Buildout | Bypasses Bogotá wholesale terminals and locks in food service volume commitments. |
| Continuous-Flow Pasteurization Retrofit | Qualifies Minas Gerais cooperatives for extended-shelf-life retail contracts. |
| Carbon Footprint Audit Program | Positions early adopters for Mercosur environmental labeling compliance advantages. |
| Precision Fermentation Monitoring | Reduces Argentine yogurt batch failure rates through IoT-enabled pH sensors. |
| Cross-Border Certification Harmonization | Accelerates SENASA-ANVISA mutual recognition for fluid milk export expansion. |
Research Methodology
Document review covered ANVISA regulatory filings, SENASA cheese aging protocols, Mercosur trade harmonization texts, and supermarket private-label procurement contracts, complemented by interviews with Brazilian dairy plant managers, Argentine cooperative technical directors, Colombian food service procurement leads, and Uruguayan export certification officers. Secondary validation drew from customs trade databases, cold-chain logistics provider disclosures, and retail audit data. Bottom-up volume modeling and top-down value reconciliation ensured triangulation across stakeholder inputs.
Segment-level outputs across product type, end user, distribution channel, and packaging format dimensions were generated through the analytical framework. CAGRs were derived from trend extrapolation of procurement centralization patterns, regulatory compliance timelines, and substitution elasticity estimates for plant-based beverages. Forecast inputs incorporated fodder cost volatility indices and cold-chain technician scarcity metrics as industry-specific modifiers.
Underlying measurement precision varies by segment; fluid milk and UHT categories carry tighter precision due to consolidated processor reporting, while artisan cheese and direct-to-Horeca channels exhibit higher variance from fragmented cooperative structures. Forecasts reflect assumptions around ANVISA enforcement consistency and Mercosur harmonization pace. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Russia Whey Protein Market
Dairy Products
US Cheese Market
Dairy Products
Europe Chocolate Milk Market
Dairy Products
Soluble Milk Protein Market
Dairy Products
Global Yogurt Market
Dairy Products
Probiotic Yogurt Market
Dairy Products
Nonfat Dry Milk Market
Dairy Products
Low-Calorie Butter Market
Dairy Products
United States Camel Dairy Market
Dairy Products
Global Yogurt Powder Market
Dairy Products
Milk Protein Hydrolysate Market
Dairy Products
Asia-Pacific Dairy Protein Market
Dairy Products
South America Dairy Protein Market
Dairy Products
Europe Casein and Caseinates Market
Dairy Products
Dairy Based Dressings Market
Dairy Products
Probiotic Dairy Products Market