
 Middle East and Africa UHT Milk Market | 2026-2036
Middle East and Africa UHT Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa UHT Milk Market Foresight
Food service buyers are bifurcating from traditional household purchasers as the dominant demand archetype across the Middle East and Africa UHT milk landscape. Almarai leverages its integrated dairy operations across the Gulf to secure raw milk supply and control distribution costs. Juhayna Food Industries anchors Egyptian demand through deep penetration of modern trade channels and branded dairy portfolios. Nestlé S.A. competes via technology leadership in aseptic packaging formats that extend shelf life in climates with limited cold chain coverage.
Ultra-high temperature milk undergoes heating at 135–150°C for 2–5 seconds to eliminate spoilage organisms, then aseptically packages the sterile product for ambient storage up to nine months; this thermal process enables commercial distribution in regions where refrigerated logistics remain sparse or costly. Shelf-stable UHT variants dominate volume across the Middle East and Africa due to their alignment with heat-stressed climates and intermittent electricity supply, while flavored UHT offerings capture premium positioning among younger demographics in urban centers. Tetra Pak cartons hold structural advantage in packaging type segmentation because of their lightweight logistics profile and established recycling infrastructure in South Africa and the UAE.
Saudi Food and Drug Authority (SFDA) standards govern dairy safety and labeling across the Kingdom, while South Africa's Department of Health enforces nutrient composition rules that directly shape product formulation decisions for manufacturers serving both markets. The UAE's Ministry of Climate Change and Environment coordinates with Gulf standardization bodies to align import requirements, creating a regulatory convergence zone that simplifies market access for compliant producers. Stakeholders must monitor evolving shelf-life disclosure mandates and fortification requirements as Gulf and North African regulators tighten consumer protection frameworks without harmonized timelines.
Market Dynamics
Urban household penetration of UHT milk across the Middle East and Africa is deepening as refrigeration infrastructure remains unevenly distributed, creating structural dependence on ambient-stable dairy formats that bypass cold-chain requirements entirely.
Growth Catalysts
- SASO Food Safety Standards:Saudi Arabia's technical regulations for dairy safety are elevating product quality benchmarks across Gulf supply chains, forcing compliance upgrades that reduce spoilage rates and extend viable distribution radii.
- Flavored UHT Formulations:Product innovation targeting younger urban demographics is capturing premium shelf positioning in Cairo, Lagos, and Johannesburg supermarkets, expanding per-unit economics beyond commoditized white milk.
- Nigeria's Lagos-Abuja Corridor:Concentrated demand in this dense population belt, served by informal retail networks, is creating volume anchors that justify dedicated production capacity and localized packaging investments.
Market Restraints
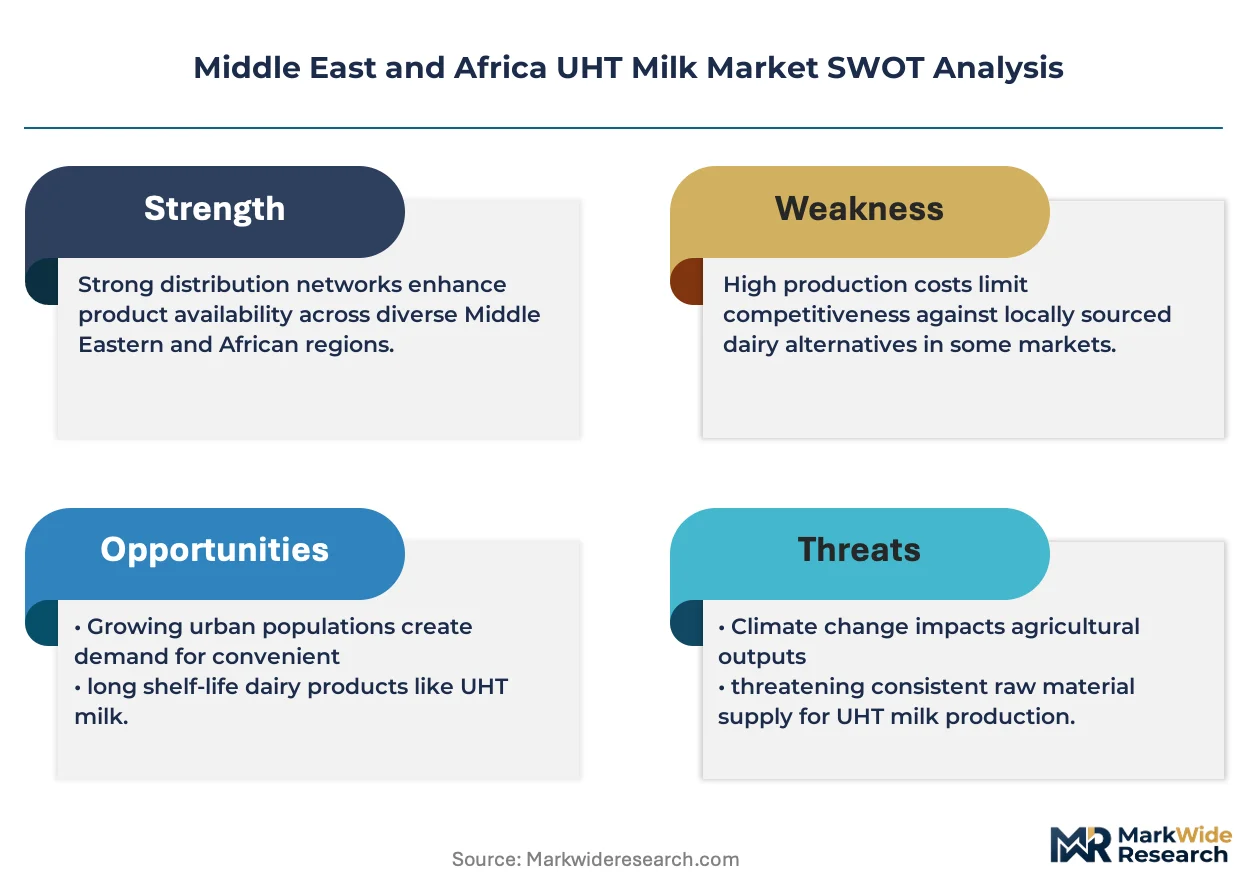
- Raw Milk Input Volatility:Feed cost fluctuations and water scarcity pressures across Saudi Arabia and Egypt are compressing processor margins and limiting price competitiveness against reconstituted milk alternatives.
- South African Distribution Concentration:Last-mile logistics cluster around a handful of refrigerated trucking operators, creating bottleneck vulnerability and service coverage gaps in secondary cities.
- Tetra Pak Carton Recycling Infrastructure:Limited industrial composting and fiber recovery capacity outside South Africa and the UAE elevates packaging waste compliance costs and consumer backlash risk.
Strategic Opportunities
- Ethiopia's Underpenetrated Urban Markets:Addis Ababa's expanding middle class and nascent modern trade presence offer first-mover positioning before competitive saturation accelerates.
- SFDA Fortification Mandates:Saudi Arabia's evolving nutrient composition rules create product differentiation pathways through vitamin D and calcium enrichment that command retail price premiums.
- E-commerce Direct-to-Consumer Channels:Platform partnerships with Jumia and Noon are bypassing traditional wholesale layers, capturing margin recovery and consumption data previously opaque to manufacturers.
Industry Challenges
- Aseptic Engineering Talent Scarcity:Specialized technicians capable of maintaining UHT line sterility protocols remain concentrated in South Africa and the UAE, constraining operational expansion in secondary markets.
- Dual Certification Timelines:Simultaneous compliance with Gulf standardization bodies and national regulators like Egypt's EOS extends product launch cycles and elevates pre-revenue burn.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa UHT Milk Market |
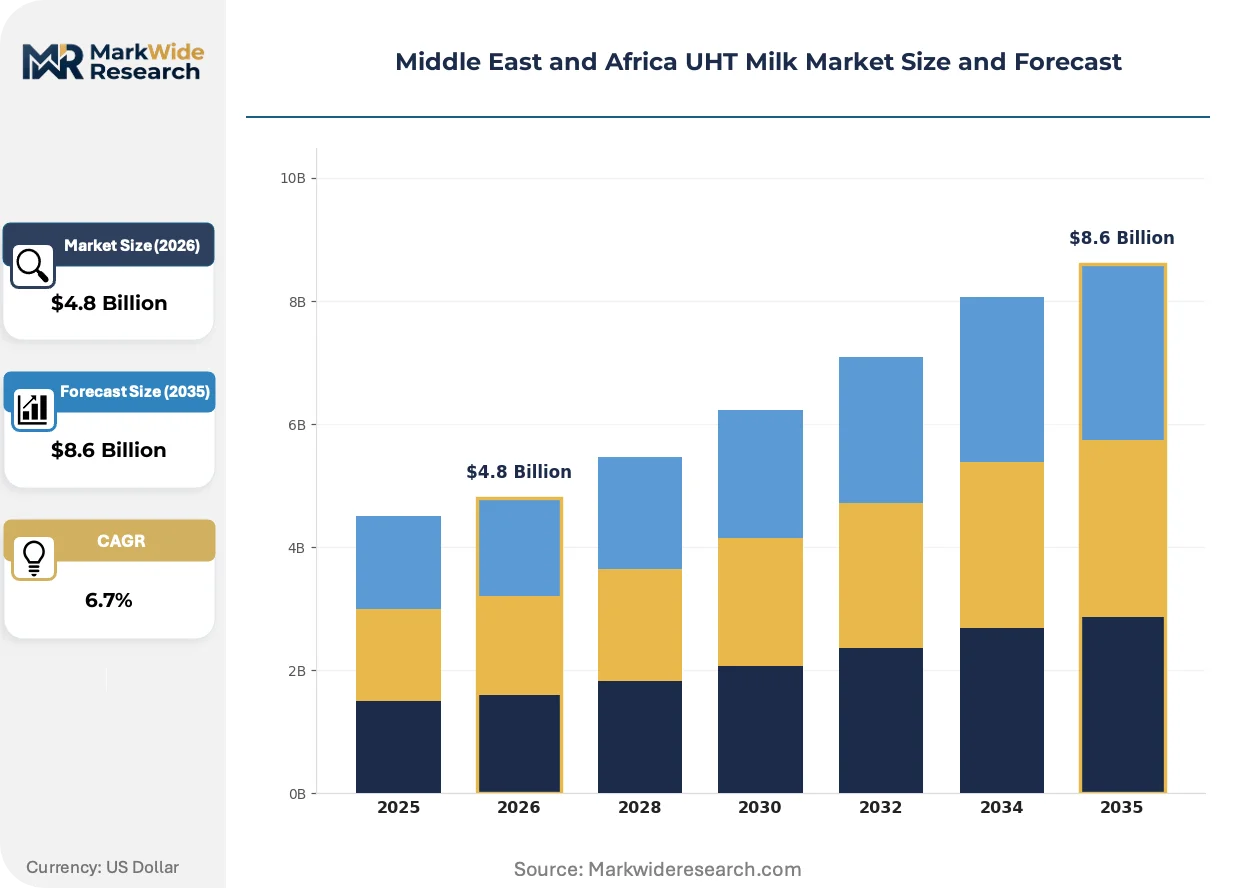
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shelf-Stable, Flavored, Organic, Non-Dairy Distribution Channel: Supermarkets, Online Retail, Convenience Stores, HoReCa Packaging Type: Cartons, Plastic Bottles, Tetra Packs, Bulk Containers End User: Households, Food Service, Retailers, Manufacturers |
| Companies Covered | Nestlé S.A., Juhayna Food Industries, Almarai, Mazoon Dairy, NADEC, Saudia Dairy & Foodstuff Co. (SADAFCO), Clover Industries Ltd, Baladna Food Industries, Lactalis Group, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa UHT Milk Market Shifts & Advancements
Aseptic packaging formats and thermal processing configurations are actively fragmenting competitive positioning across the Middle East and Africa, as climate stress and electricity reliability concerns reshape what constitutes viable dairy logistics.
Extended-shelf-life ESL variants are fragmenting the traditional UHT category by offering 60-90 day ambient stability with superior taste profiles, enabling premium positioning among Gulf retail chains that previously accepted standard UHT limitations. Hotel and foodservice buyers in Dubai and Riyadh are adopting ESL as a middle-ground solution that reduces waste without full cold-chain dependency. This technology is fragmenting procurement patterns by creating a three-tier shelf-stable hierarchy that complicates supplier consolidation strategies.
South Africa's Department of Health nutrient disclosure rules are tightening label transparency requirements for dairy fat content and added sugar declarations, forcing reformulation investments across brands serving the SACU trade zone. Manufacturers are responding by standardizing packaging artwork across regional SKUs to amortize compliance costs. The flavored UHT segment faces the steepest adaptation curve as youth-oriented products historically relied on opacity around sweetener loads.
Informal retail consolidation in Nigeria is compressing traditional distributor layers as larger cash-and-carry operators absorb fragmented kiosks and corner shops, altering credit terms and inventory turnover expectations. Dairy processors are restructuring field sales organizations to serve fewer, larger accounts with direct delivery rather than wholesaler intermediation. This pattern is most visible in Lagos, where Dangote's retail footprint and foreign supermarket chains are displacing legacy open-market milk distribution.
Middle East and Africa UHT Milk Market Segmentation
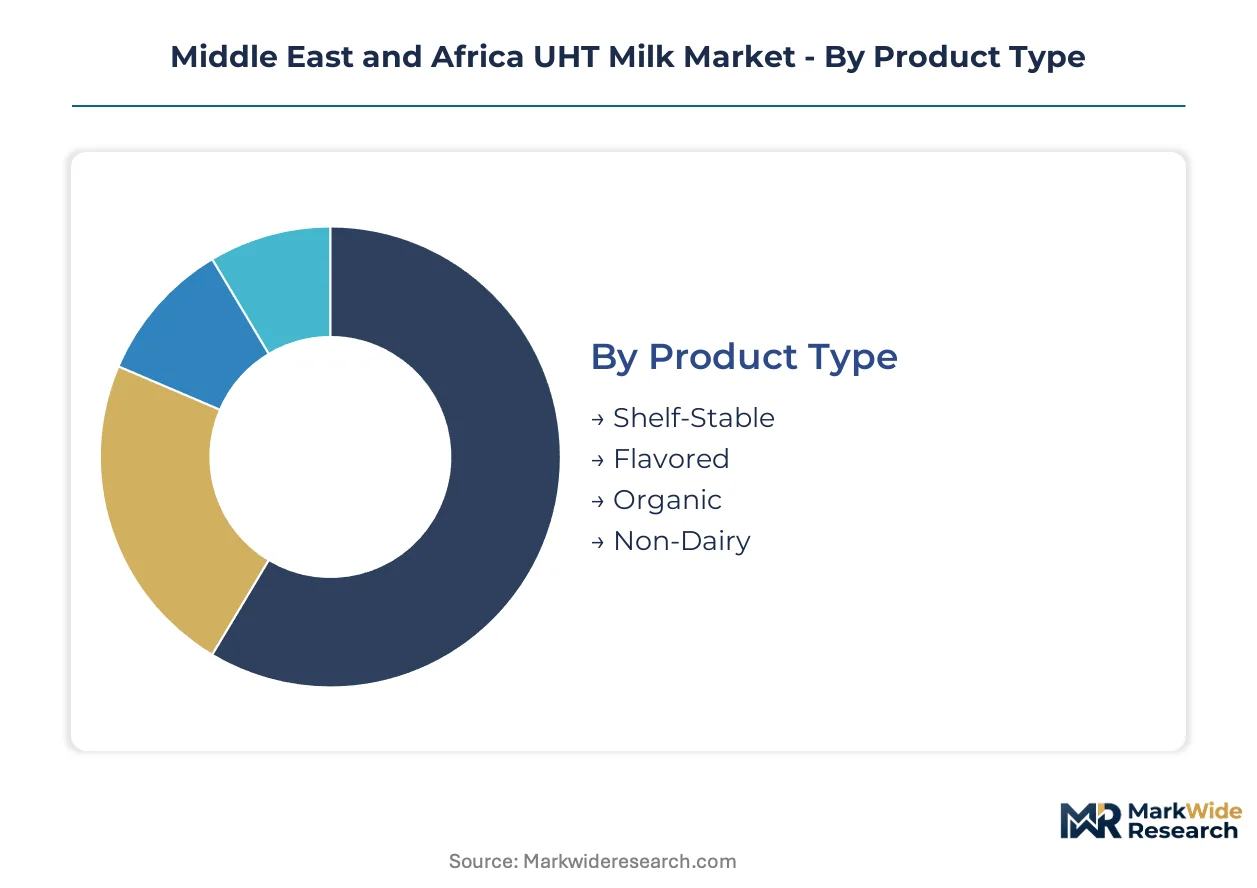
Segmentation in the Middle East and Africa UHT milk market reveals divergent growth vectors shaped by infrastructure asymmetries and consumption pattern shifts. Understanding how product formats, channel structures, and packaging technologies map onto distinct demand clusters enables targeted capacity allocation and margin capture strategies.
Product Type:
Shelf-stable white milk dominates domestic consumption across Egypt, Saudi Arabia, and Nigeria, while flavored and organic variants increasingly serve export-oriented Gulf retail chains and premium urban households.
- Shelf-Stable:Standard UHT white milk undergoes thermal processing at 135–150°C for 2–5 seconds, delivering nine-month ambient stability. Demand concentrates in Nigeria's Lagos-Abuja corridor where refrigeration gaps force complete reliance on non-cold-chain formats. Nigerian informal retail networks and Egyptian subsidized distribution programs anchor volume.
- Flavored:Chocolate, strawberry, and vanilla formulations target younger demographics in Cairo, Johannesburg, and Dubai supermarkets. Premium shelf positioning and higher per-unit margins attract Juhayna and Almarai innovation investments. Heat-stressed climates amplify refreshment positioning.
- Organic:Certified grass-fed and hormone-free supply chains serve affluent Gulf expatriate communities and South African health-conscious segments. Limited local organic dairy infrastructure forces import dependency or dedicated farm investments.
- Non-Dairy:Oat, almond, and soy UHT alternatives capture lactose-intolerant populations and flexitarian urbanites in UAE and South Africa. Category growth tracks modern trade expansion and Western dietary influence.
Shelf-stable holds the largest share; momentum sits with flavored formulations.
Distribution Channel:
Channel economics fragment sharply between capital-intensive modern trade requiring cold-chain handoffs and ambient-stable formats penetrating informal retail with minimal infrastructure.
- Supermarkets:Carrefour, Lulu, and Shoprite operations in Dubai, Riyadh, and Johannesburg drive premium SKU placement and promotional visibility. Extended shelf-life ESL variants gain traction here as waste reduction tools.
- Online Retail:Jumia and Noon platform partnerships enable direct-to-consumer margin recovery and consumption data capture previously opaque to manufacturers. Same-day delivery capabilities remain concentrated in Gulf urban centers.
- Convenience Stores:Fragmented kiosk and corner shop networks across Lagos and Cairo sustain single-serve UHT sachet and small-format carton demand. Cash-and-carry consolidation is compressing traditional wholesaler layers.
- HoReCa:Hotel, restaurant, and institutional buyers in Dubai and Riyadh adopt ESL milk as middle-ground solutions reducing spoilage without full refrigeration dependency. Procurement patterns favor contracted supply over spot purchasing.
Supermarkets command the revenue base; online retail is climbing the fastest.
Packaging Type:
Material selection balances logistics economics, recycling infrastructure availability, and regulatory compliance across disparate national frameworks.
- Cartons:Paperboard laminates with aluminum foil barriers dominate South African and UAE retail due to established fiber recovery infrastructure and lightweight shipping profiles. Tetra Pak's regional manufacturing presence reinforces format lock-in.
- Plastic Bottles:HDPE and PET formats suit Nigerian and Egyptian price-sensitive segments with lower per-unit packaging costs. Limited industrial recycling elevates waste compliance exposure.
- Tetra Packs:Aseptic brick and gable-top configurations enable nine-month shelf stability with minimal preservatives. Gulf standardization bodies favor this format for import uniformity.
- Bulk Containers:Food service and manufacturing buyers in Saudi Arabia and South Africa procure 5–20 liter bag-in-box or intermediate bulk containers for institutional kitchens and dairy processing inputs.
Cartons lead volume; Tetra Packs show the steepest expansion trajectory in premium retail.
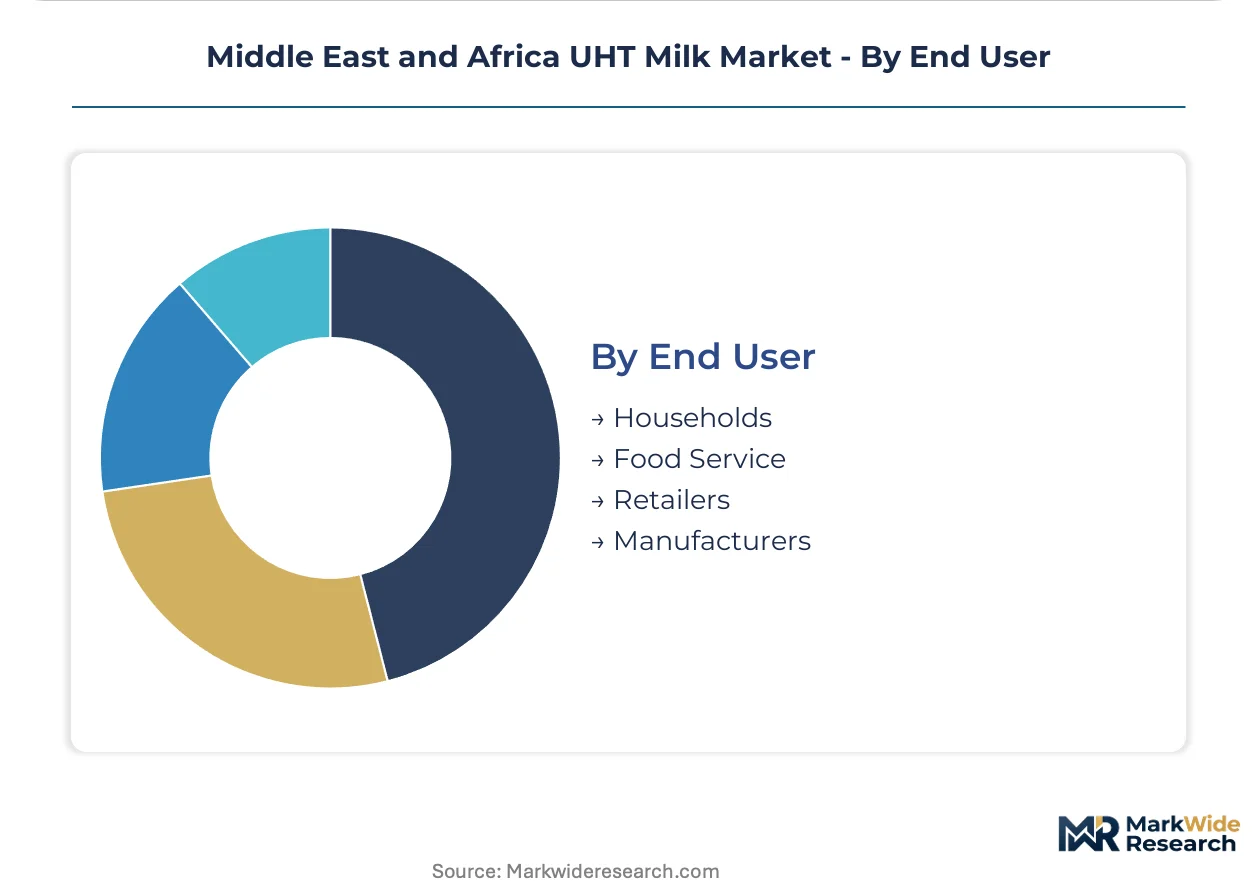
End User:
User archetypes diverge between household stockpiling behaviors and institutional procurement protocols with divergent quality specifications and price sensitivities.
- Households:Urban family units across Jeddah, Lagos, and Johannesburg purchase multi-pack cartons for pantry storage, prioritizing shelf stability over taste optimization. Electricity reliability concerns reinforce UHT preference over fresh milk.
- Food Service:Hotels, restaurants, and catering operations in Dubai and Cairo demand consistent fat content and foaming performance for coffee applications. Extended shelf-life ESL adoption is fragmenting traditional UHT procurement here.
- Retailers:Supermarket and convenience store operators manage inventory turnover and spoilage risk through promotional calendars and private-label UHT programs. Dangote's retail footprint in Nigeria is displacing legacy open-market distribution.
- Manufacturers:Dairy processors and confectionery producers in Egypt and South Africa source bulk UHT milk as ingredient inputs for yogurt, cheese, and baked goods production.
Households anchor demand volume; food service is gaining share fastest among institutional segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Jebel Ali Port-Dubai Logistics Corridor underwrites the Gulf's role as the primary re-export hub for UHT milk entering African markets, while the Suez Canal Economic Zone anchors Egyptian processing capacity serving North African demand clusters.
Saudi Arabia
Urban household stockpiling and foodservice procurement drive volume growth in Riyadh and Jeddah. SFDA fortification mandates for vitamin D and calcium reshape product formulation requirements. The Eastern Province dairy cluster around Al-Kharj concentrates integrated processing facilities serving domestic and export Gulf markets.
United Arab Emirates
Expatriate population density and tourism-sector foodservice demand elevate per-capita UHT consumption in Dubai and Abu Dhabi. MOCCAE coordination with Gulf standardization bodies streamlines import compliance for regional re-export operations. Jebel Ali Free Zone warehousing enables duty-efficient redistribution into East African markets.
Egypt
Subsidized distribution programs and informal retail penetration sustain mass-market volume across Greater Cairo and the Nile Delta. EOS labeling requirements and nutrient disclosure rules extend product launch timelines for reformulated SKUs. Alexandria's port infrastructure handles imported milk powder inputs for local reconstitution and UHT processing.
South Africa
Modern trade expansion and private-label proliferation drive premium SKU growth in Johannesburg and Cape Town metropolitan areas. The Department of Health enforces strict dairy fat content and added sugar disclosure rules across the SACU trade zone. KwaZulu-Natal's dairy belt supplies raw milk inputs to Gauteng processing facilities facing distribution bottlenecks in secondary cities.
Nigeria
Refrigeration infrastructure gaps and intermittent electricity supply entrench complete dependence on ambient-stable formats across the Lagos-Abuja corridor. NAFDAC registration requirements and import tariff structures elevate compliance costs for foreign suppliers. Dangote's retail footprint and cash-and-carry consolidation in Lagos displace legacy open-market milk distribution networks.
Middle East and Africa UHT Milk Market Competitive Landscape
Listed leaders compete with private specialists across Gulf and North African dairy operations, creating a tiered structure where scale-driven multinationals and integrated national champions hold distinct competitive positions. The vendor base clusters around three strategic archetypes: vertically integrated desert dairy operators with captive raw milk supply, multinational packaged food conglomerates leveraging aseptic technology licensing, and regional specialists dominating single-country distribution networks. M&A activity concentrates on informal retail consolidation in Nigeria and capacity expansion in Saudi Arabia's Eastern Province, while strategic partnerships with e-commerce platforms reshape last-mile economics.
Within the integrated dairy archetype, Almarai and Juhayna Food Industries exemplify regional scale positioning, while Nestlé S.A. occupies the multinational technology-licensing tier. Almarai represents Gulf-based vertical integration into raw milk production and controlled distribution networks. Juhayna Food Industries anchors Egyptian demand through deep modern trade penetration. Nestlé S.A. exemplifies global aseptic packaging leadership adapted to heat-stressed climates with limited cold chain coverage.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Juhayna Food Industries |
| Almarai |
| Mazoon Dairy |
| NADEC |
| Saudia Dairy & Foodstuff Co. (SADAFCO) |
| Clover Industries Ltd |
| Baladna Food Industries |
| Lactalis Group |
| Others |
Supply & Pricing Matrix
Reconstituted milk powder substituting for fresh raw milk across Egyptian and Nigerian processing lines simultaneously shifts procurement geography toward European and Oceanian dairy exporters while compressing per-unit production economics for integrated Gulf operators. This input substitution rewards processors with backward integration into captive milk supply while exposing merchant buyers to commodity powder price cycles and currency translation effects.
Pricing Analysis
Volume-discount tiering structures separate bulk institutional contracts from single-serve retail sachets across the Lagos-Abuja corridor and Greater Cairo. Three-tier pricing stratifies across premium ESL variants for Gulf supermarkets, standard UHT cartons for Egyptian subsidized distribution, and economy sachets for Nigerian informal retail. Pricing pressure stems from feed cost volatility and water scarcity compressing margins for Saudi integrated operators. Food service buyers in Dubai and Riyadh exhibit lowest price sensitivity due to waste-reduction priorities, while Nigerian kiosk operators face acute cost pressure from cash-flow constraints and electricity unreliability.
Supply Chain Analysis
Saudi Arabia and Egypt anchor raw milk production and integrated UHT processing capacity across the Middle East and Africa region. Production draws from alfalfa-fed dairy herds in the Eastern Province and Nile Delta smallholder networks respectively. Single-source vulnerability concentrates in aseptic packaging equipment and technical service capacity clustered in South Africa and the UAE. Distribution runs through Jebel Ali Free Zone warehousing for Gulf re-export, informal cash-and-carry consolidation in Lagos, and subsidized public distribution networks across Egyptian governorates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
UHT milk packaging-as-a-service and technical maintenance contracts expand faster than commodity milk sales as processors seek recurring revenue streams and operational lock-in with food service accounts.
For Market Incumbents: Secure captive raw milk supply through farm acquisitions or long-term offtake agreements in the Eastern Province and Al-Kharj cluster before feed cost volatility intensifies. Defend market position by embedding ESL technical service contracts with Dubai and Riyadh hotel chains, creating switching costs that reconstituted milk alternatives cannot match. For New Entrants and Emerging Players: Lead with fortified UHT formulations targeting SFDA vitamin D and calcium mandates as a compliance-first entry wedge into Saudi retail. Ethiopia's Addis Ababa modern trade expansion offers the most penetrable white-space geography before competitive saturation accelerates. Partner with Jumia or Noon for direct-to-consumer data capture and margin recovery bypassing traditional wholesale layers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional dairy specialists holding strong Nigerian distribution networks but lacking Gulf regulatory compliance infrastructure. Long-term viability over the next decade hinges on fortification capability and aseptic engineering talent access. Watch for NAFDAC registration timeline compression as an inflection signal for foreign supplier entry costs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Dairy Farming | Secures raw milk supply in Saudi Arabia's Eastern Province against feed cost volatility and water scarcity pressures. |
| ESL Technical Service Contracting | Creates recurring revenue attachment with Dubai and Riyadh hotel chains while embedding operational switching costs. |
| Fortification Compliance Investment | Enables SFDA-mandated vitamin D and calcium enrichment commanding retail price premiums in Saudi supermarkets. |
| E-commerce Platform Partnership | Bypasses fragmented Nigerian wholesale layers through Jumia and Noon direct-to-consumer channels capturing margin recovery. |
| Aseptic Engineering Talent Development | Addresses technician scarcity constraining UHT line expansion beyond South Africa and the UAE into secondary markets. |
Research Methodology
A spread of perspectives from dairy processing executives, regulatory affairs managers at Gulf standardization bodies, modern trade category buyers, informal retail distributors in Lagos, and aseptic packaging engineers converged on the working assumptions shaping this analysis. Primary field engagement combined with secondary validation from SFDA technical regulations, NAFDAC registration databases, Egyptian customs trade records, and Tetra Pak regional capacity disclosures. Bottom-up volume modeling and top-down macroeconomic triangulation anchored the quantitative framework.
Segmentation dimensions modeled span product format variants, packaging material technologies, distribution channel economics, and end-user procurement protocols across the analysis window. CAGRs derived from historical trajectory analysis and forward-looking capacity announcements. Forecast inputs incorporated electricity reliability indices, cold-chain infrastructure penetration rates, and regulatory compliance timeline assumptions specific to dairy fortification mandates.
The analysis sits within stated boundaries; outcomes outside sustained Gulf urbanization, Nigerian cash-and-carry consolidation, or Egyptian subsidy program continuity would require recalibration. Forecasts reflect documented assumptions about feed cost trajectories and aseptic equipment import availability. Recalibration cycles align with material shifts in SFDA regulatory amendments and NAFDAC registration procedural changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Milk Mineral Market
Dairy Products
North America Milk Powder Market
Dairy Products
Cheese Packaging Market
Dairy Products
Ricotta Market
Dairy Products
Low Temperature Yogurt Market
Dairy Products
South America Dairy Protein Market
Dairy Products
Sour Cream Market
Dairy Products
Milk Protein Hydrolysate Market
Dairy Products
Dairy Blends Market
Dairy Products
Hydrolyzed Casein Market
Dairy Products
North America Sour Cream Market
Dairy Products
Global Lipolyzed Butter Fat Market
Dairy Products
Butter Concentrate Market
Dairy Products
Indonesia Whey Protein Market
Dairy Products
Ghee Market
Dairy Products
Paneer Market