
 Sheep Milk Cheese Market | 2026-2036
Sheep Milk Cheese Market Size, Share, and Industry Trends Forecast 2026-2036
Sheep Milk Cheese Market Insights
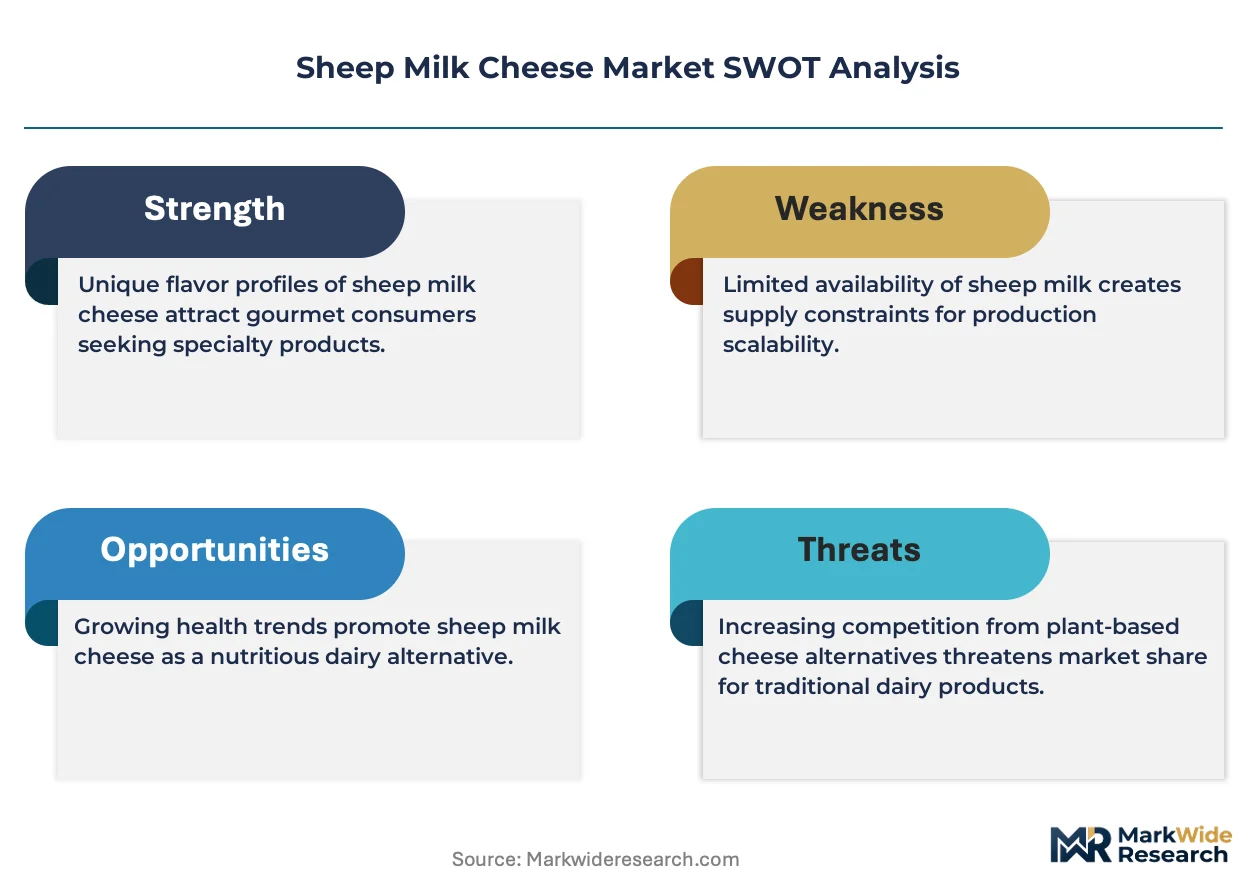
Capital-intensity divergence between industrial-scale creameries and artisan operations is collapsing as mid-sized producers adopt shared dairy infrastructure. Savencia Fromage & Dairy leverages its continental distribution network to sustain volume leadership across European retail channels. Bellwether Farms anchors its position through in-house flock management and direct-to-consumer sales in North American markets. Wensleydale Creamery differentiates through heritage branding and limited-batch production that commands premium shelf placement.
Sheep milk cheese denotes cheese manufactured from the milk of domestic sheep, typically containing 6-8% butterfat and 4-5% protein, which exceeds cow milk fat content and yields a denser curd structure suited to extended aging regimens. The primary commercial purpose centers on premium foodservice and specialty retail segments where fat-rich profiles justify price positioning above standard bovine alternatives. Feta and Manchego occupy the largest volume pools due to established PDO recognition and export infrastructure, while Roquefort commands the deepest margin concentration through restricted geographic production and controlled cave-aging requirements. Soft-textured varieties represent the fastest-growing texture category as clean-label and spreadable formats gain traction in urban deli and direct-to-consumer channels.
EFSA microbiological standards, EU PDO frameworks, and national food safety regulators in France and Spain enforce strict flock-to-fork traceability that shapes market access for imported sheep milk cheese. FDA oversight in the United States and CFIA requirements in Canada impose additional pathogen-testing thresholds that filter which overseas producers qualify for North American distribution. Stakeholders must monitor evolving raw-milk regulations and climate-adapted pasture policies that will determine which regional supply bases can maintain consistent seasonal output.
Market Dynamics
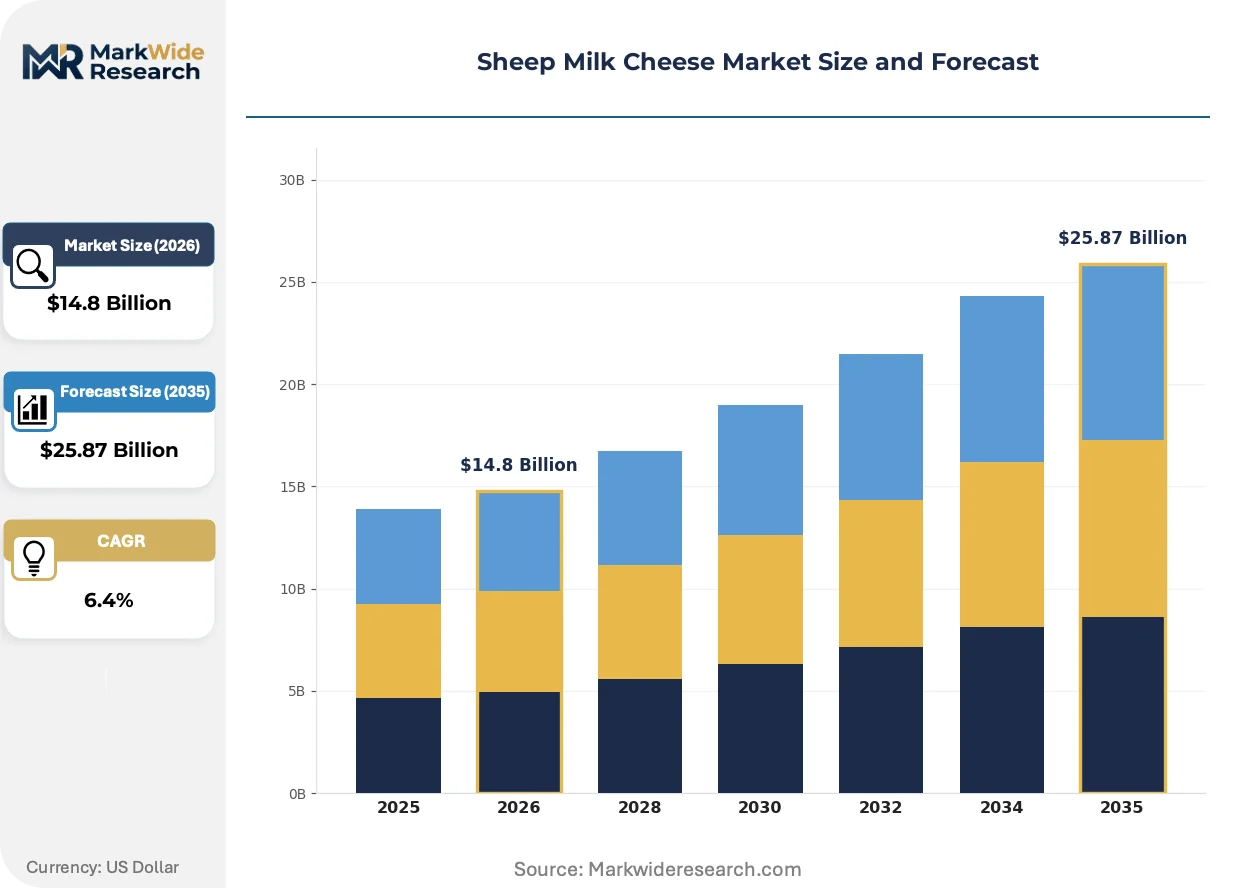
Shared dairy infrastructure is collapsing the capital-intensity gap between industrial-scale creameries and artisan operations, enabling mid-sized producers to achieve scale economies previously locked behind vertical integration. This structural compression is redrawing competitive boundaries across the value chain.
Growth Catalysts
- EU PDO Framework Expansion:Protected designation of origin protocols in France and Spain are tightening origin-verification requirements, creating defensive moats for established regional producers against commodity imports.
- Specialty Retail Channel Absorption:Aged sheep milk varieties are capturing expanded shelf space in Mediterranean basin delis and urban food halls, particularly in Barcelona and Athens clusters.
- Clean-Label Spreadable Formats:Soft-textured varieties are displacing processed alternatives in direct-to-consumer channels where fat-rich nutritional profiles command premium positioning.
Market Restraints
- Seasonal Output Volatility:Climate-adapted pasture policies in Greece and Spain are compressing flock lactation windows, constraining year-round raw milk availability for extended aging regimens.
- Raw-Milk Regulatory Friction:FDA pathogen-testing thresholds in the United States filter overseas producers from North American distribution, raising compliance costs for European exporters.
- Input Cost Concentration:Organic feed certification requirements under EFSA protocols are concentrating supply among approved Mediterranean fodder suppliers, amplifying margin pressure.
Strategic Opportunities
- Urban Direct-to-Consumer Channels:Subscription-based cheese clubs in London and Paris are bypassing traditional retail markups, capturing full margin from affluent household segments.
- EFSA Microbiological Standard Harmonization:Converging EU-wide traceability mandates are creating transferable compliance frameworks that reduce multi-market certification redundancy for cross-border producers.
- Aging Infrastructure Technology:Climate-controlled cave replication systems are enabling terroir-independent production in non-traditional geographies without geographic PDO restrictions.
Industry Challenges
- Artisan Skill Succession Gaps:Traditional flock-to-fork cheesemaking expertise in Basque and Sardinian production clusters faces generational transfer risks as younger workers migrate to urban manufacturing.
- Capex Intensity for Traceability Systems:EFSA-mandated digital flock tracking requires substantial upfront investment in RFID and blockchain infrastructure that strains smallholder balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sheep Milk Cheese Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Feta, Pecorino, Manchego, Roquefort Texture: Soft, Hard, Semi-Hard, Creamy Flavor Profile: Salty, Sweet, Tangy, Nutty Packaging Type: Vacuum Sealed, Waxed, Glass Jar, Plastic Tub |
| Companies Covered | Nordic Creamery, Quality Cheese Inc., Valbreso Cheese, Eurial, Savencia Fromage & Dairy, Wensleydale Creamery, Bellwether Farms, Lacteos Segarra, Kirwee Farmers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sheep Milk Cheese Market Trends and Innovations
Technology convergence and regulatory tightening are compressing production timelines while fragmenting distribution pathways. These forces are simultaneously enabling new market entrants and raising compliance barriers for incumbents.
Automated curd-cutting and pressing systems are miniaturizing. Specialty creameries in Portugal and Croatia are adopting these units to achieve batch consistency without industrial-scale capital outlay. The technology is compressing quality variance between artisan and mechanized output, eroding traditional differentiation claims.
REACH-aligned chemical safety protocols are extending into dairy contact materials. ECHA substance restrictions on packaging coatings are forcing reformulation of wax and brine solutions used in Roquefort-style aging. French producers are responding by accelerating investment in inert ceramic and glass aging vessels that bypass polymer compliance entirely.
Urban deli buyers are consolidating purchasing through centralized procurement platforms that disintermediate regional distributors. This channel compression is most visible in Copenhagen and Stockholm, where restaurant groups and retail chains now source directly from Basque and Pyrenean creameries. The shift is forcing traditional importers to pivot toward logistics and compliance services rather than trading margins.
Sheep Milk Cheese Market Segmentation
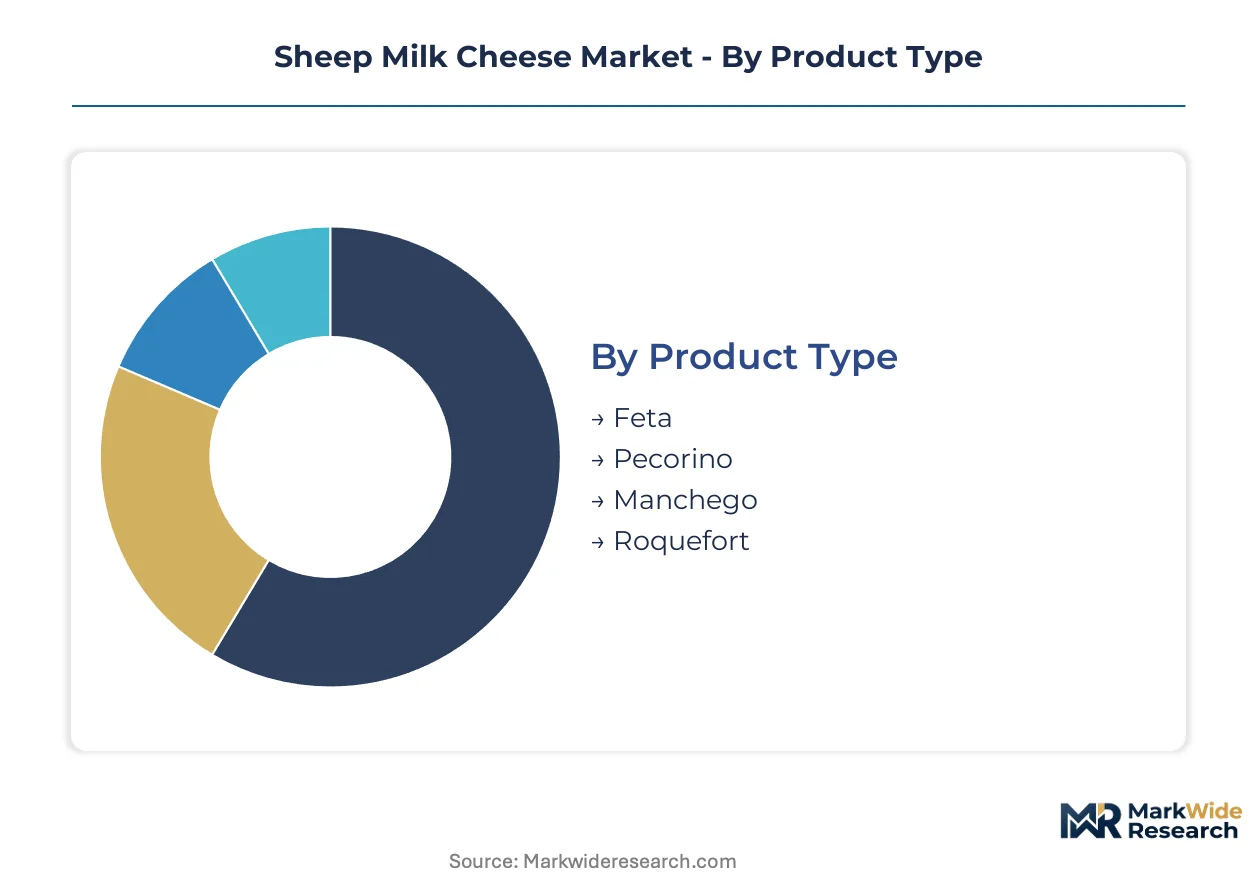
Sheep milk cheese segmentation reveals how fat content, aging protocols, and moisture levels determine channel access and margin capture. Distinct product formats face varying pressure from plant-based alternatives and cow milk equivalents across retail and foodservice environments.
Product Type:
Feta and Pecorino face the strongest substitution pressure from cow milk versions in price-sensitive retail channels, while PDO-protected varieties maintain defensive positioning.
- Feta:Brined white cheese with 45-60% moisture content and crumbly texture. Greek and Bulgarian production clusters supply Mediterranean delis in Barcelona and Athens where origin-verification commands shelf placement.
- Manchego:Pressed curd cheese aged 60 days to 2 years under Spanish PDO protocols. La Mancha producers supply aged wheels to specialty retailers in Madrid and export markets where nutty profiles justify premium positioning above cow milk Manchego-style alternatives.
- Pecorino:Italian sheep milk cheese with granular texture and sharp flavor from Sardinian and Tuscan production zones.
- Roquefort:French blue cheese aged in natural Combalou caves with Penicillium roqueforti mold penetration, restricted to Aveyron region under PDO.
Feta retains volume leadership; Roquefort holds the steepest expansion curve in premium channels.
Texture:
Cost tier stratification separates artisan cave-aged formats from industrial soft varieties, with capital requirements determining producer entry points.
- Soft:High-moisture varieties with 50-60% water content and minimal aging. Portuguese and Croatian creameries supply spreadable formats to urban direct-to-consumer channels in London and Paris where clean-label positioning displaces processed alternatives.
- Hard:Low-moisture pressed cheeses aged 6-24 months. Basque producers like Ossau-Iraty supply aged wheels to Copenhagen and Stockholm procurement platforms where restaurant groups source directly for shaving and grating applications.
- Semi-Hard:Intermediate moisture cheeses with 40-50% water content and 3-6 month aging regimens.
- Creamy:Spreadable fresh cheeses with 60-70% moisture and no aging requirement, often blended with herbs or honey.
Hard textures dominate export value; Soft varieties are gaining share fastest in subscription and deli channels.
Flavor Profile:
Application-specific demand concentrates flavor preferences across foodservice versus retail consumption occasions.
- Salty:Brined and surface-salted varieties with 2-4% sodium content. Feta and halloumi-style producers target salad applications and mezze platters in Greek and Turkish foodservice where salt-forward profiles match olive and tomato pairings.
- Nutty:Aged varieties with Maillard-developed flavor compounds from 12+ month aging. Manchego and Pecorino Romano producers supply grating and table cheese segments in Italian and Spanish retail where extended aging creates umami depth.
- Sweet:Fresh and young cheeses with lactose-forward profiles, often paired with fruit or honey.
- Tangy:Lactic-acid prominent varieties with cultured sharpness from specific starter bacteria.
Salty profiles anchor Mediterranean foodservice volume; Nutty varieties show the strongest premiumization trajectory in aged cheese counters.
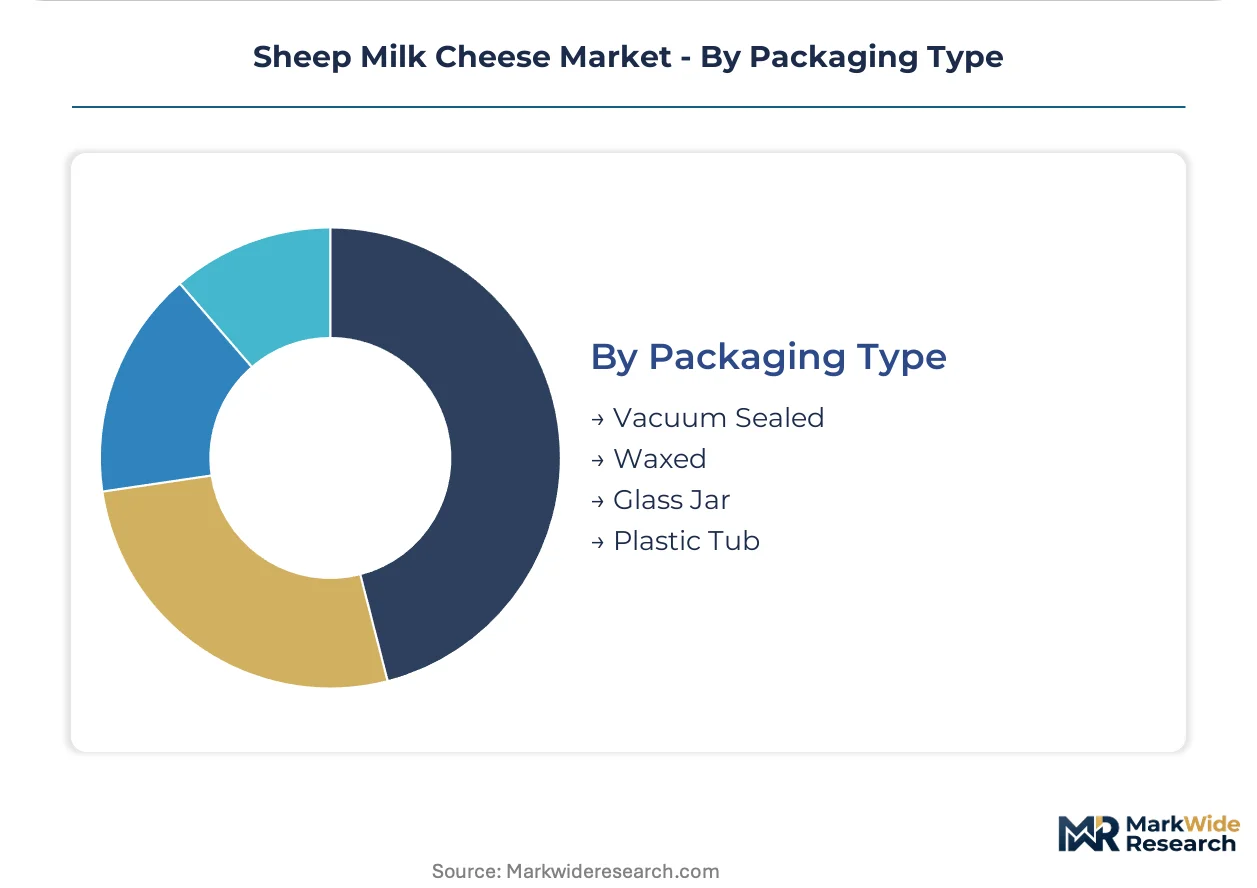
Packaging Type:
Supply concentration in Mediterranean packaging suppliers shapes format availability and EFSA compliance costs for exporters.
- Vacuum Sealed:Oxygen-barrier films extending shelf life to 90-180 days for hard varieties. Industrial creameries in Spain and Greece deploy modified-atmosphere packaging for retail distribution across EFSA-regulated markets where extended dating reduces spoilage claims.
- Waxed:Traditional paraffin or microcrystalline wax coatings for natural rind protection. French Roquefort producers maintain waxed wheel formats for specialty importers serving North American markets where aesthetic authenticity supports premium positioning despite higher labor intensity.
- Glass Jar:Brine-packed feta and marinated soft cheeses in hermetic containers.
- Plastic Tub:Fresh creamy varieties in polypropylene containers for refrigerated retail.
Vacuum sealed dominates volume throughput; Glass jar formats are climbing fastest in gift and specialty export segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between Mediterranean heritage markets where sheep milk cheese anchors daily cuisine and North American markets where it occupies premium specialty positioning. Spain and Greece integrate aged varieties into standard grocery baskets, while US and Canadian buyers treat these products as artisanal indulgences with pronounced seasonality.
Spain
Manchego PDO wheels drive retail volume through Madrid and Barcelona distribution clusters where aged formats command permanent shelf space. Spain's national food safety authority enforces strict La Mancha origin verification under EU PDO frameworks, filtering non-compliant imports from Latin American competitors. The Castilla-La Mancha production belt surrounding Toledo maintains the deepest aging cellar infrastructure in Europe.
France
Roquefort's cave-aged blue cheese sustains the steepest margin premiums through controlled Aveyron production and restricted Combalou cave access. ANSM and EFSA microbiological standards enforce pathogen thresholds that shape export eligibility for North American markets. The Occitanie region's Laguiole and Société creameries concentrate heritage branding expertise that commands Parisian fine-dining procurement.
Greece
Feta consumption dominates domestic foodservice where brined white cheese accompanies mezze and salad applications across Athens and Thessaloniki restaurant networks. EFSA flock-to-fork traceability mandates and national PDO enforcement compress raw milk availability outside designated Epirus and Macedonia production zones. Crete and Lesvos island creameries face climate-adapted pasture constraints that shorten seasonal lactation windows.
United States
Direct-to-consumer subscription channels and urban deli counters in New York and San Francisco absorb aged Pecorino and Manchego-style imports at premium price points. FDA pathogen-testing thresholds and raw-milk restrictions filter European exporters, raising compliance costs for specialty importers. California's Sonoma and Marin County creameries anchor domestic artisan production through in-house flock management and farmers market distribution.
Italy
Pecorino Romano and Sardinian varieties supply grating applications through Rome and Milan retail where extended aging creates umami depth for pasta and risotto. Italy's national agricultural quality system enforces Sardinian and Tuscan origin protocols under EU PDO frameworks. The Sardinian provinces of Sassari and Nuoro maintain traditional pastoral cheesemaking clusters threatened by generational skill transfer gaps.
Sheep Milk Cheese Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the sheep milk cheese market. Savencia Fromage & Dairy leverages continental distribution infrastructure to sustain volume leadership across European retail channels, while mid-sized producers collapse capital-intensity gaps through shared dairy infrastructure. Three archetypes dominate: heritage-brand regionalists with PDO-anchored positioning, vertically integrated farmstead operations with captive flock supply, and import-specialist distributors serving North American premium channels. Competitive moves concentrate on direct-to-consumer channel bypass and aging infrastructure technology licensing.
Among integrated European leaders, Savencia Fromage & Dairy occupies the scale-driven position exemplifying continental distribution reach, while Wensleydale Creamery represents heritage-brand regionalism through limited-batch production and premium shelf placement. Bellwether Farms anchors the farmstead archetype with in-house flock management and direct-to-consumer penetration in North American markets. These three entities collectively illustrate how vertical integration, heritage positioning, and channel control differentiate competitive standing across distinct geographic and price-tier vectors.
| Leading Market Players |
|---|
| Nordic Creamery |
| Quality Cheese Inc. |
| Valbreso Cheese |
| Eurial |
| Savencia Fromage & Dairy |
| Wensleydale Creamery |
| Bellwether Farms |
| Lacteos Segarra |
| Kirwee Farmers |
| Others |
Pricing and Supply Chain Analysis
Organic feed certification replacing conventional grain sourcing is redrawing procurement geography toward approved Mediterranean fodder suppliers while compressing margins across premium and standard tiers. This input substitution simultaneously elevates EFSA compliance costs and restricts pricing flexibility for producers locked into legacy supply contracts.
Pricing Analysis
Aging cellar service contracts and extended cave-storage agreements drive lifetime value capture for artisan producers. Three-tier pricing structure across PDO-certified premium, industrial standard, and private-label economy levels stratifies the market. Pricing pressure stems from organic feed cost inflation filtering through EFSA-mandated certification requirements. Foodservice buyers in Barcelona and Athens clusters exhibit highest price sensitivity, while direct-to-consumer subscription channels in London and Paris absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Container availability constraints on Mediterranean-Atlantic trade lanes are elevating landed costs for Aveyron and La Mancha exporters serving North American distribution. Raw milk supply concentrates in Spain, Greece, and France, with seasonal lactation windows compressing year-round availability. Production draws from organic-certified fodder, Penicillium roqueforti cultures, and cave-aged infrastructure. Single-source vulnerability runs through restricted Combalou cave access for Roquefort production. Distribution runs through urban deli procurement platforms and direct-to-consumer subscription channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Traditional flock-to-fork cheesemaking expertise in Basque and Sardinian production clusters faces generational attrition, creating scarcity premiums for producers that secure skill succession pipelines.
For Market Incumbents: Compound heritage-brand positioning through PDO-anchored origin verification and controlled cave-aging infrastructure licensing. Defend against climate-adapted pasture policy disruptions by securing multi-region flock contracts. Prioritize EFSA-mandated digital traceability investment to filter smaller competitors from export eligibility. For New Entrants and Emerging Players: Subscription-based cheese club fulfillment gaps in secondary European cities offer white-space entry points. Target Copenhagen and Stockholm urban clusters where restaurant groups source directly from creameries. Pursue climate-controlled cave replication technology licensing to bypass geographic PDO restrictions. For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-sized Mediterranean producers that adopted shared dairy infrastructure but lack direct-to-consumer channel control. Five-to-ten year viability hinges on securing aging cellar capacity and flock management expertise. Watch EFSA microbiological standard harmonization progress as inflection indicator for cross-border scalability.| Strategic Initiative | Industry Significance |
|---|---|
| PDO Certification Investment | EFSA origin-verification mandates create defensive moats against commodity imports in Madrid retail. |
| Climate-Controlled Cave Replication | Terroir-independent production technology unlocks non-traditional geographies without Combalou cave restrictions. |
| Direct-to-Consumer Channel Launch | Subscription cheese clubs in London and Paris bypass traditional retail markups for full margin capture. |
| Shared Dairy Infrastructure Partnership | Mid-sized producers collapse capital-intensity gaps through cooperative aging and pressing facilities. |
| Digital Flock Traceability Implementation | RFID and blockchain infrastructure satisfies EFSA mandates while filtering smallholder competitors from export markets. |
Research Methodology
A spread of perspectives from creamery operations directors, specialty retail category buyers, EFSA regulatory affairs specialists, and Mediterranean fodder suppliers converged on the working assumptions shaping this analysis. Primary fieldwork combined with secondary validation from EU PDO registry filings, EFSA microbiological standard documentation, national food safety authority enforcement records, and Mediterranean dairy trade customs data. Bottom-up producer capacity estimates triangulated against top-down retail channel absorption metrics.
Segmentation dimensions modeled include product type, texture profile, aging protocol, flavor category, and packaging format across the projection horizon. CAGRs were derived through regression analysis of historical volume trajectories and elasticity-adjusted price evolution. Forecast inputs incorporated climate-adapted pasture policy scenarios and EFSA traceability mandate implementation timelines.
Underlying assumptions cover sustained PDO framework enforcement and Mediterranean feed certification stability, with deviation risk concentrated in raw-milk regulatory friction and generational skill transfer gaps. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Japan Casein Market
Dairy Products
Low-Lactose Dairy Foods Market
Dairy Products
Asia-Pacific Flavored Milk Market
Dairy Products
Kefir Market
Dairy Products
Lactose and Derivative Market
Dairy Products
US Cheese Market
Dairy Products
Spicy Dairy Products Market
Dairy Products
Global Reduced Fat Butter Market
Dairy Products
Cheese Shreds Market
Dairy Products
Parmesan Cheese Market
Dairy Products
Citrus Yogurt Market
Dairy Products
Global Milk Protein Market
Dairy Products
Germany Dairy Market
Dairy Products
Non-GMO Yogurt Market
Dairy Products
A2 Milk Market
Dairy Products
Low-Fat Sour Cream Market