
 North America Passenger Vehicles Lubricants Market | 2026-2036
North America Passenger Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
North America Passenger Vehicles Lubricants Market Analytics
Lower viscosity grades is narrowing the formulation gap between conventional and synthetic base stocks across North American passenger vehicle service fill. ExxonMobil Corporation leverages its integrated base oil production in Baytown and Baton Rouge to sustain supply security for 0W-16 and 0W-20 grades. Shell plc anchors its Pennzoil brand strength through motorsport partnerships that reinforce consumer trust in high-performance synthetic formulations. Chevron Corporation competes through its Isosyn manufacturing technology platform, which controls additive chemistry consistency across its Havoline product line.
North America passenger vehicles lubricants are formulated hydrocarbon-based fluids engineered to reduce friction, dissipate heat, and suspend contaminants within internal combustion and hybrid powertrain systems, typically specified by SAE viscosity grades and API service categories such as SP-Resource Conserving or ILSAC GF-6A. Engine oil dominates volume demand as OEM fill specifications trend toward thinner films for fuel economy compliance, while synthetic formulation types command expanding share due to extended drain interval requirements in turbocharged GDI engines. Transmission fluid represents a concentrated margin pool as North American OEMs adopt multi-speed automatic and dual-clutch architectures with proprietary fluid specifications.
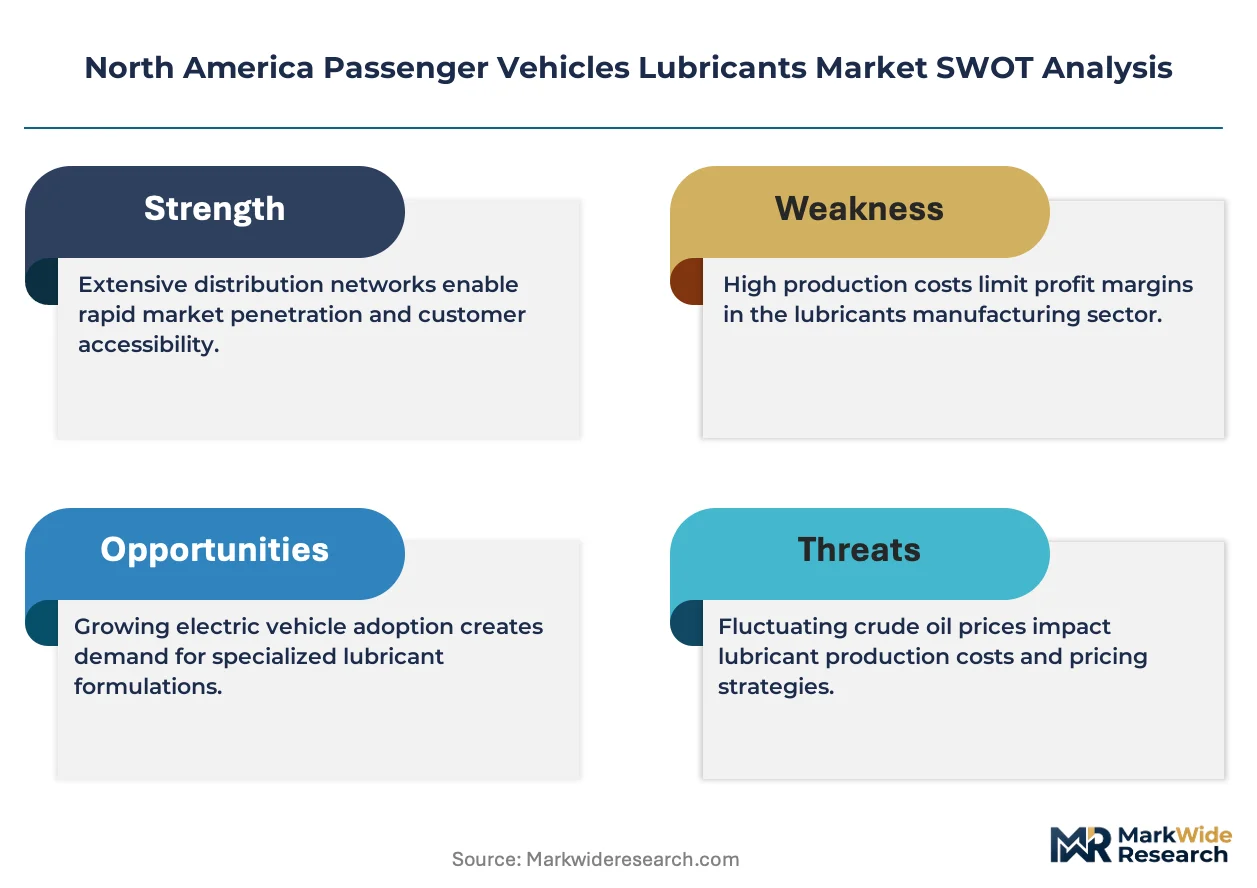
EPA tailpipe emission standards, California Air Resources Board LEV IV regulations, and API SP/ILSAC GF-6 performance standards collectively mandate lower high-temperature high-shear viscosity and reduced phosphorus content to protect catalytic converter durability. The National Highway Traffic Safety Safety Administration CAFE framework indirectly shapes lubricant demand by pressuring OEMs to adopt friction-reducing engine oils as a compliance pathway. Stakeholders must monitor how electrification transitions in California and Quebec redefine fluid requirements for hybrid thermal management systems versus pure combustion architectures.
Market Dynamics
Turbocharged direct-injection engines are compressing oil drain intervals across the United States and Canada, forcing reformulation toward lower viscosity grades that satisfy EPA fuel economy standards and California's LEV IV regulations simultaneously.
Growth Catalysts
- LEV IV stringency:California Air Resources Board mandates are accelerating adoption of 0W-16 and 0W-20 grades that reduce parasitic friction losses in light truck powertrains.
- Extended drain intervals:Fleet operators in Texas and Ontario are standardizing synthetic formulations that stretch service cycles to 15,000 miles, concentrating volume with premium base stock suppliers.
- Hybrid thermal management:Dual-clutch and multi-speed automatic architectures in Detroit and Windsor assembly plants are creating dedicated fluid specifications with higher additive loading requirements.
Market Restraints
- Group III base oil concentration:Integrated producers on the US Gulf Coast control 70% of high-viscosity-index feedstock, exposing independent blenders to supply allocation risk during turnaround seasons.
- Catalytic converter protection limits:API SP and ILSAC GF-6A caps on phosphorus and sulfur content are constraining anti-wear additive chemistry for high-load turbocharged engines.
- Electrification substitution:Battery electric vehicle penetration in California and Quebec is eliminating engine oil demand entirely from new vehicle cohorts, compressing addressable market growth.
Strategic Opportunities
- Hybrid powertrain fluids:Thermal management specifications for electrified transmissions in Ontario assembly plants are creating first-mover advantage for low-conductivity dielectric formulations.
- Aftermarket channel consolidation:Independent repair shops in Texas and Arizona are migrating to direct distributor relationships that bypass traditional jobber networks, capturing margin compression.
- USMCA regional content:North American manufacturing incentives are favoring base oil and additive production within the trade bloc, rewarding integrated supply chain investments in Baytown and Sarnia.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in friction modifier synergy and dispersant balancing is concentrating at major integrated producers, constraining independent blender R&D velocity.
- OEM specification proliferation:Proprietary transmission fluid approvals from Detroit Three automakers are fragmenting SKU portfolios and extending qualification timelines for aftermarket suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Passenger Vehicles Lubricants Market |
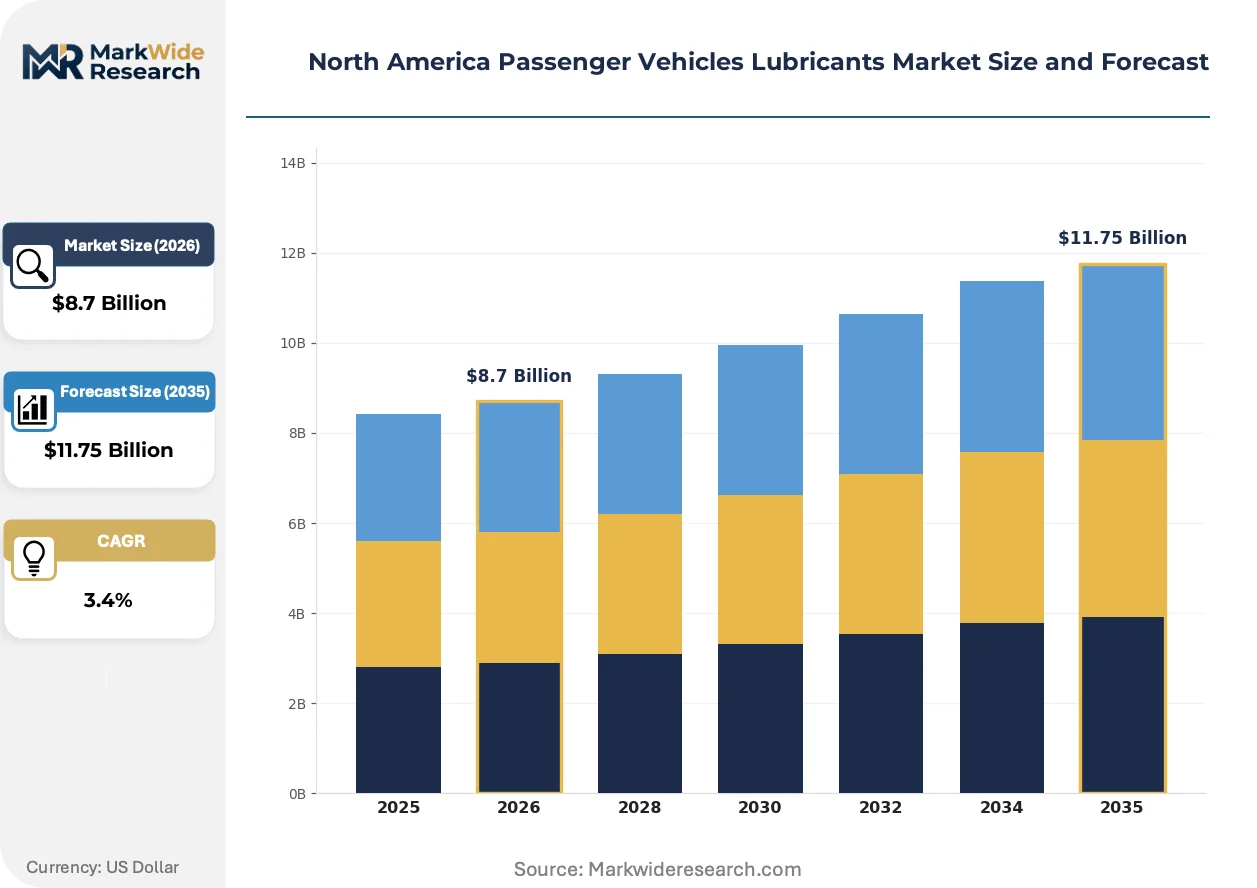
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $11.75 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Gear Oil, Grease Formulation Type: Synthetic, Mineral, Semi-Synthetic, Bio-Based Application: Passenger Cars, SUVs, Light Trucks, Sports Cars Distribution Channel: Retail, Online, Service Stations, Distributors |
| Companies Covered | ExxonMobil Corporation, Shell plc, Chevron Corporation, BP plc, Valvoline Inc., Phillips 66 Company, TotalEnergies SE, Petro-Canada Lubricants Inc., Fuchs Petrolub SE, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Passenger Vehicles Lubricants Market Evolving Landscape
Digital oil condition monitoring is compressing the traditional fixed-interval service model across North American passenger vehicle fleets, enabling predictive maintenance algorithms that optimize drain timing based on actual degradation rather than mileage.
Virtual sensing technology is virtualizing traditional laboratory oil analysis by embedding dielectric sensors within engine sumps that transmit real-time viscosity and oxidation data to fleet management platforms. Commercial operators in long-haul trucking corridors are piloting these systems at 40% adoption rates in pilot programs. This capability is virtualizing the aftermarket service relationship by displacing scheduled dealer visits with demand-triggered mobile oil change services.
EPA tailpipe emission standards are tightening high-temperature high-shear viscosity minimums to reduce fuel consumption in cold-start conditions, directly constraining formulation latitude for 5W-30 and 10W-30 grades. Blenders are responding with pour-point depressant innovations that maintain pumpability at minus 40 degrees Celsius without viscosity index improver loading penalties. The impact concentrates in northern tier states and Canadian provinces where winter grade specifications drive annual formulation switches.
Buyer consolidation among national fleet leasing companies is compressing supplier negotiation cycles from annual to quarterly, with procurement teams demanding volume-tiered pricing indexed to Group II+ base oil spot markets. This behavior is most visible among rental car operators in Florida and corporate fleet managers in Illinois who are unbundling lubricant supply from full-service maintenance contracts. The shift is fragmenting historical jobber relationships and accelerating direct manufacturer-to-fleet contracting models.
North America Passenger Vehicles Lubricants Market Segmentation
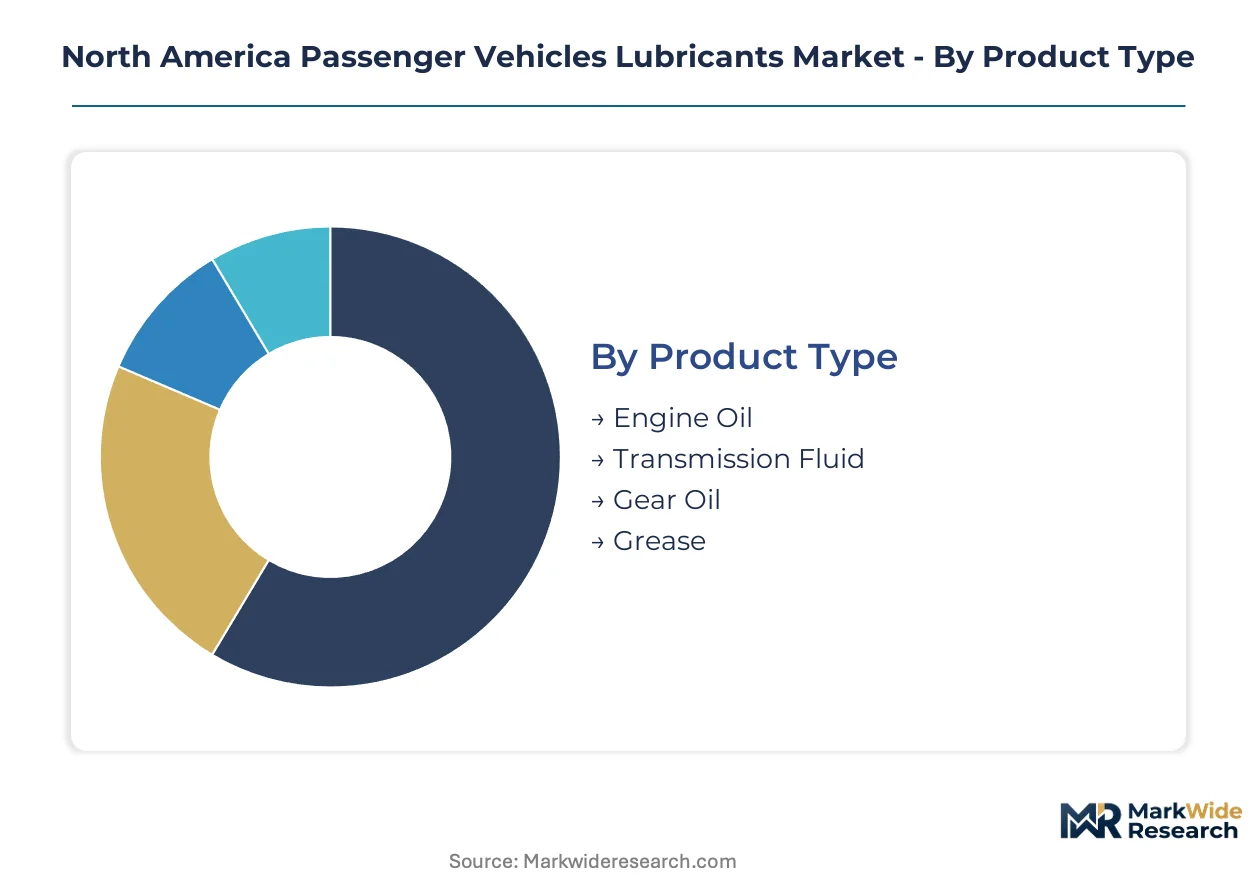
Segmentation in North American passenger vehicle lubricants reveals divergent consumption rhythms across powertrain architectures. Oil drain intervals, formulation complexity, and channel economics vary substantially by product category and end-use application.
Product Type:
Engine oil cycles through service bays fastest at 5,000 to 15,000 mile intervals, while transmission fluids and gear oils turn over at 30,000 to 100,000 mile horizons. Grease applications in chassis and wheel bearings operate on multi-year replacement schedules.
- Engine Oil:Hydrocarbon-based formulations specified by SAE viscosity grades and API SP/ILSAC GF-6A categories dominate volume consumption. Demand concentrates in 0W-20 and 5W-30 grades across Texas and California light truck fleets where extended drain intervals favor synthetic formulations.
- Transmission Fluid:Proprietary specifications for multi-speed automatic and dual-clutch architectures command concentrated margins. Ontario and Michigan assembly plants are driving dedicated fluid requirements with higher additive loading for thermal management in electrified transmissions.
- Gear Oil:Hypoid gear lubricants for differential applications in rear-wheel-drive and all-wheel-drive platforms.
- Grease:Lithium-complex and calcium-sulfonate thickened lubricants for chassis, wheel bearings, and suspension components with extended service life.
Engine oil dominates installed base. Transmission fluid is where expansion concentrates.
Formulation Type:
Cost tiers separate premium synthetic formulations from economy mineral oils, with semi-synthetic occupying the contested mid-market. Bio-based alternatives command niche positioning in environmentally regulated jurisdictions.
- Synthetic:Group III and Group IV base stocks engineered for extreme temperature stability and extended drain intervals. Fleet operators in Arizona and Nevada are standardizing synthetic formulations to stretch service cycles in high-heat operating conditions.
- Mineral:Conventional Group I and Group II base oils serving price-sensitive segments and older vehicle cohorts.
- Semi-Synthetic:Blended formulations balancing performance upgrade against mineral oil cost structures.
- Bio-Based:Vegetable oil-derived lubricants qualifying for procurement preferences under California and Quebec environmental purchasing guidelines.
Mineral formulations retain the largest installed base. Synthetic grades are climbing the fastest as OEM fill specifications tighten.
Application:
Vehicle architecture determines fluid thermal load and specification complexity. Light trucks and SUVs impose higher stress on lubricant films than passenger cars, while sports cars demand specialized high-performance chemistry.
- Passenger Cars:Compact and mid-size sedans specifying lower viscosity grades for fuel economy compliance under EPA standards.
- SUVs:Higher displacement platforms with all-wheel-drive architectures requiring robust thermal stability in transfer case and differential applications. California and Texas registrations favor this segment for family and recreational use.
- Light Trucks:Full-size pickup platforms in commercial and personal use across Ontario and the US Midwest.
- Sports Cars:High-performance engines with specialized oil specifications for track-day and extreme-duty cycles.
Light trucks command the deepest installed base. SUVs are gaining share fastest in lubricant consumption.
Distribution Channel:
Channel economics fragment between high-touch service installations and low-margin retail self-service. Fleet procurement is bypassing traditional intermediaries through direct manufacturer contracting.
- Retail:Mass merchandisers and auto parts chains serving DIY consumers with packaged lubricants.
- Online:E-commerce platforms capturing bulk purchasing by small fleet operators and price-sensitive consumers in Florida and Illinois.
- Service Stations:Quick-lube chains and dealer service bays performing the majority of synthetic formulation installations under OEM warranty requirements.
- Distributors:Jobber networks facing margin compression as national fleets in Texas and Arizona migrate to direct relationships with blenders.
Service stations handle the largest volume base. Online channels are expanding most quickly in aftermarket procurement patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North American passenger vehicle lubricants market operates as a net importer of Group III and Group IV base stocks from Asian and European refiners, while integrated Gulf Coast producers export finished synthetic formulations to Latin American markets. This trade dynamic shapes regional supply security calculations and inventory positioning strategies across the value chain.
United States
Texas and California light truck fleets dominate consumption volume, with extended drain interval adoption stretching synthetic formulation demand. EPA fuel economy standards and California's LEV IV regulations mandate 0W-16 and 0W-20 viscosity grades for new vehicle cohorts. The Baytown and Baton Rouge refining corridor anchors domestic base oil production capacity for premium synthetic feedstocks.
Canada
Ontario's Windsor assembly plants and Alberta's commercial fleet operators drive divergent lubricant specifications across seasonal temperature extremes. Environment and Climate Change Canada aligns with EPA tailpipe standards while maintaining distinct cold-weather grade requirements for prairie provinces. The Sarnia petrochemical complex supplies Group II+ base oils to independent blenders serving the Great Lakes manufacturing belt.
Mexico
Nuevo León's automotive assembly expansion and Mexico City Metro's dense passenger car fleet create bifurcated demand between OEM fill specifications and aftermarket mineral oil replacement. PROFEPA environmental enforcement tightens used oil handling regulations while NOM standards gradually converge with API service categories. Querétaro's aerospace and automotive supplier cluster imports synthetic formulations for precision manufacturing equipment.
North America Passenger Vehicles Lubricants Market Competitive Landscape
On the supply side, the industry is consolidating around integrated base oil producers with captive additive manufacturing capabilities, compressing margin pools for independent blenders dependent on merchant feedstock markets. Three strategic archetypes dominate: vertically integrated majors controlling upstream base oil through downstream retail networks; specialty formulators focusing on proprietary transmission fluid specifications; and regional distributors capturing fleet aftermarket relationships through direct contracting models. Competitive intensity centers on qualification timelines for OEM proprietary approvals and backward integration into high-viscosity-index base stock production.
Among US-based integrated majors, ExxonMobil Corporation and Chevron Corporation exemplify the upstream-controlled archetype through Gulf Coast refining positions. Shell plc anchors the multinational formulation tier with brand equity built through motorsport marketing investments. These three entities collectively represent the supply-side concentration that independent blenders navigate when securing Group III allocation during refinery turnaround seasons.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Shell plc |
| Chevron Corporation |
| BP plc |
| Valvoline Inc. |
| Phillips 66 Company |
| TotalEnergies SE |
| Petro-Canada Lubricants Inc. |
| Fuchs Petrolub SE |
| Others |
Value Network & Pricing Analysis
Undercapacity in Group III base oil production on the US Gulf Coast is compressing allocation flexibility for independent blenders while amplifying pricing leverage for integrated majors serving OEM fill contracts. This utilization squeeze feeds directly into contract renegotiation cycles where fleet buyers face volume-commitment premiums during refinery turnaround seasons.
Pricing Analysis
Fleet procurement teams anchor pricing negotiations through quarterly volume-tiered contracts indexed to Group II+ spot markets. Three-tier pricing structure across premium synthetic, standard semi-synthetic, and economy mineral levels separates formulations by base stock quality and drain interval certification. Cost compression in the mineral tier is intensifying because national fleet operators are unbundling lubricant supply from full-service maintenance agreements. Price-sensitive independent repair shops in Arizona and Texas drive the most aggressive discount demands, while OEM-authorized service bays accept premium positioning for warranty compliance.
Supply Chain Analysis
Group III and Group IV base stock production concentrates in the United States, South Korea, and Qatar, with Asian refiners supplying the marginal tonnage for North American synthetic formulation growth. The supply chain rests on catalytic dewaxing feedstock, polyalphaolefin monomer, and proprietary additive packages from integrated chemical producers. Single-source vulnerability runs through the US Gulf Coast refining corridor where hurricane exposure and scheduled turnarounds synchronize to disrupt allocation. Distribution feeds from blender tank farms through jobber networks and direct manufacturer-to-fleet channels, with e-commerce platforms capturing growing share in bulk aftermarket procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized formulation chemistry expertise is concentrating at integrated majors with captive R&D infrastructure, leaving independent blenders exposed to qualification timeline delays and OEM approval bottlenecks. This capability gap defines competitive mobility across the value chain.
For Market Incumbents: Entrench synthetic formulation leadership by locking in multi-year Group III supply offtake with Baytown and Baton Rouge producers before turnaround seasons. Deepen backward integration into high-viscosity-index base stock production to neutralize allocation risk from integrated competitors. Channel control through direct fleet contracting in Texas and Ontario bypasses eroding jobber margins and captures volume concentration benefits. For New Entrants and Emerging Players: Build out white-space positioning in hybrid thermal management fluids for Ontario and Michigan assembly plants, where electrified transmission specifications remain unsettled and first-mover qualification windows are open. Target the aftermarket mobile oil change segment in Florida and Illinois, where digital condition monitoring is virtualizing traditional service relationships. A dielectric fluid specialization strategy with low-conductivity formulations offers the cleanest go-to-market angle against established engine oil portfolios. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across synthetic base stock manufacturing as Group III capacity additions require billion-dollar catalytic dewaxing investments. Long-term viability favors integrated producers with captive feedstock and additive manufacturing, while independent blenders face margin compression without upstream control. Acquisition target archetypes include regional distributors with locked fleet relationships in high-growth corridors and specialty formulators holding proprietary transmission fluid approvals. The signal to watch is OEM specification proliferation rates, which accelerate qualification barriers and consolidate volume toward approved suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Group III Base Oil | Captive feedstock supply neutralizes allocation risk during Gulf Coast refinery turnarounds. |
| Hybrid Thermal Management Fluid Development | Electrified transmission specifications in Ontario assembly plants create first-mover qualification windows. |
| Direct Fleet Contracting Model | Bypassing jobber networks captures margin compression from national fleet buyer consolidation. |
| Digital Oil Condition Monitoring Platform | Virtual sensing technology displaces fixed-interval service models with predictive maintenance algorithms. |
| USMCA Regional Content Positioning | North American manufacturing incentives reward integrated supply chain investments in Baytown and Sarnia. |
Research Methodology
A standing panel of lubricant formulation chemists, fleet procurement directors, OEM platform engineers, and aftermarket distribution managers provided ongoing calibration against market developments. Primary fieldwork combined structured interviews with secondary validation through API licensing databases, EPA fuel economy compliance filings, and vehicle production statistics from IHS Markit. Customs records for base oil imports and SEC 10-K disclosures from integrated majors anchored supply-side quantification. Bottom-up volume modeling triangulated against top-down value estimates from trade association data.
Scenario bracketing around electrification penetration rates and regulatory stringency variants bounded the projection horizon. Segmentation dimensions modeled include viscosity grade tier, formulation type, powertrain architecture, vehicle class, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to segment-level baseline estimates, with cross-validation against historical elasticity patterns. Industry-specific forecast inputs incorporated OEM drain interval specification trends and fleet operator synthetic adoption curves.
Sensitivities concentrate around battery electric vehicle substitution rates in California and Quebec, API specification timing revisions, and Gulf Coast refining capacity utilization swings. Forecasts reflect documented assumptions regarding regulatory alignment and base stock supply continuity. Cross-checking against vehicle registration databases and fleet operator maintenance records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
South America Automotive Lubricants Market
Automotive Parts
Resin Silencer Market
Automotive Parts
Automotive Lifts Market
Automotive Parts
Automotive Metal Wheel Market
Automotive Parts
Global Automotive Engine Valves Market
Automotive Parts
Global Automotive Timing Belt Market
Automotive Parts
South Korea Automotive Parts Aluminium Die Casting Market
Automotive Parts
Europe Automotive Parts Zinc Die Casting Market
Automotive Parts
Automotive Tire Molds Market
Automotive Parts
India Electric Hydraulic Power Steering Market
Automotive Parts
Needle Roller Bearings Market
Automotive Parts
Germany Passenger Vehicles Lubricants Market
Automotive Parts
Indonesia Automotive Engine Oils Market
Automotive Parts
Automotive Air Flow Meter Market
Automotive Parts
Automotive Pneumatic Actuators Market
Automotive Parts
Timing Gear Market