
 Automotive Spring Market | 2026-2036
Automotive Spring Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Spring Market Intelligence
The European Union's End-of-Life Vehicles Directive is pivoting the industry's material selection calculus toward greater recyclability. Thyssenkrupp leverages its vast manufacturing scale to supply both traditional steel and advanced composite springs. Mubea specializes in lightweight chassis components, including innovative composite leaf springs. NHK Spring dominates the Asian market through its extensive product portfolio for passenger and commercial vehicles.
Automotive springs are components designed to absorb and store energy, supporting a vehicle's chassis and isolating the body from road shocks. These components, often manufactured from high-tensile spring steel, are engineered to precise spring rates to manage vehicle handling. Coil springs remain the dominant product type within the passenger vehicles application, valued for their compact design. The material segment shows steel holding the largest share, while composite materials represent the fastest-growing category due to lightweighting.
The US Environmental Protection Agency (EPA) and the European Union's Green Deal indirectly influence spring design through vehicle-level emissions and weight reduction targets. In China, GB standards dictate material quality and performance testing for all automotive components, ensuring market access. Supplier success depends on navigating the divergent material requirements between internal combustion engine vehicles and the expanding electric vehicle fleet.
Market Dynamics
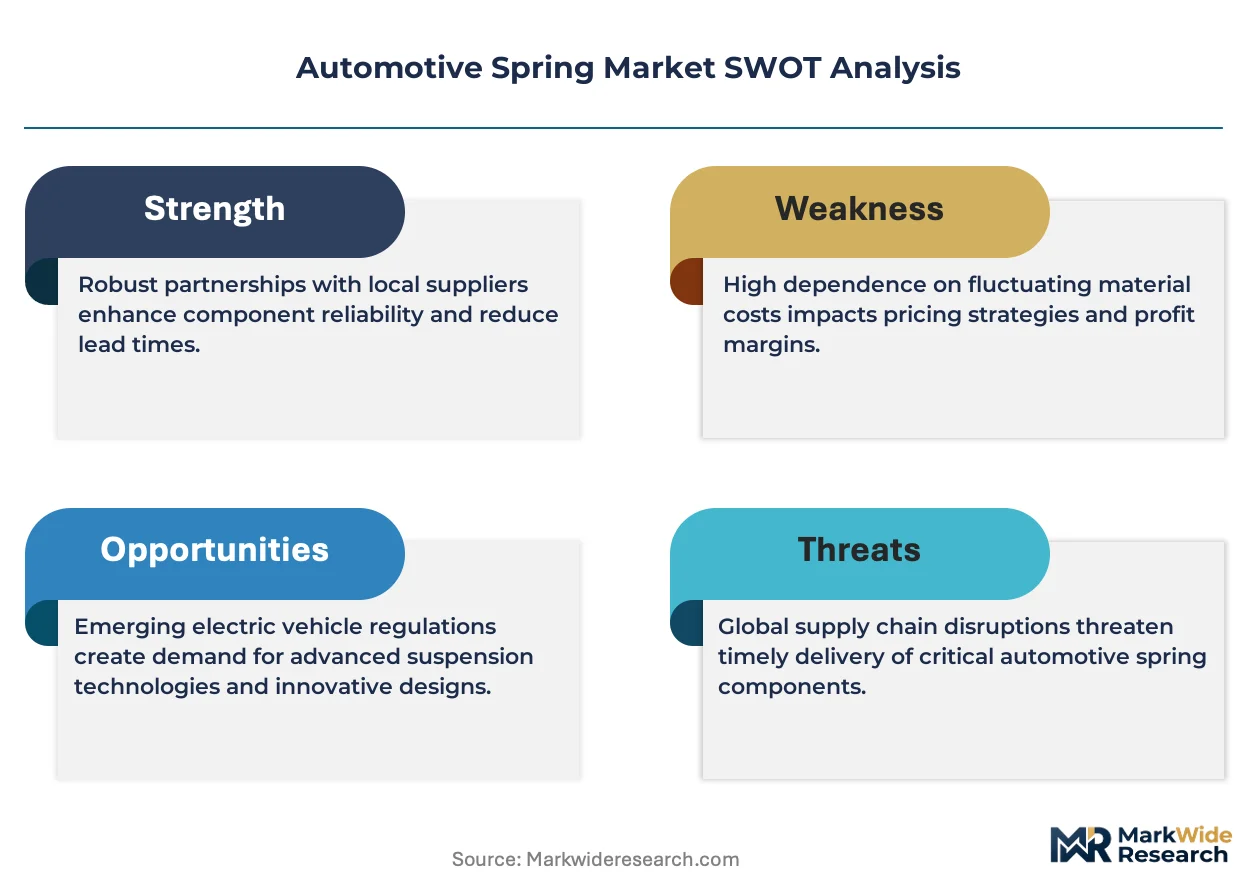
The automotive spring market is shaped by the fundamental tension between the need for lightweight components in electric vehicles and the cost-sensitive, high-volume demands of the legacy internal combustion engine vehicle sector.
Growth Catalysts
- Electric Vehicle Adoption:The need to offset heavy battery packs in EVs drives demand for lightweight springs to improve vehicle range and handling.
- Stringent Emission Standards:Global regulations on fuel economy mandate vehicle weight reduction, creating a pull for lighter composite and advanced steel springs.
- Recyclability Directives:Europe's End-of-Life Vehicles Directive compels automakers to select components made from easily recoverable materials.
Market Restraints
- Steel Price Volatility:Fluctuations in high-tensile spring steel costs create pricing instability and margin pressure for manufacturers of conventional springs.
- High Cost of Composites:Composite spring manufacturing remains significantly more expensive than steel, limiting use to premium applications and slowing mass adoption.
- Retooling Investment Barriers:The substantial capital needed to retool production lines for new materials like composites creates a significant barrier to entry.
Strategic Opportunities
- Advanced Suspension Systems:Active suspension development creates demand for specialized springs with unique performance characteristics and sensor integration capabilities.
- Low-Cost Composite Innovation:Research into lower-cost, recyclable composites and automated manufacturing processes could unlock mass-market adoption.
- EV Aftermarket Components:A replacement market is emerging for springs designed for the unique weight and wear patterns of electric vehicles.
Industry Challenges
- Navigating Divergent Standards:Suppliers face complexity designing products that meet conflicting global requirements, such as China's GB standards and Europe's recyclability rules.
- Composite Production Expertise:A shortage of engineers skilled in high-volume composite manufacturing for automotive use limits the ability to scale production of lightweight springs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Spring Market |
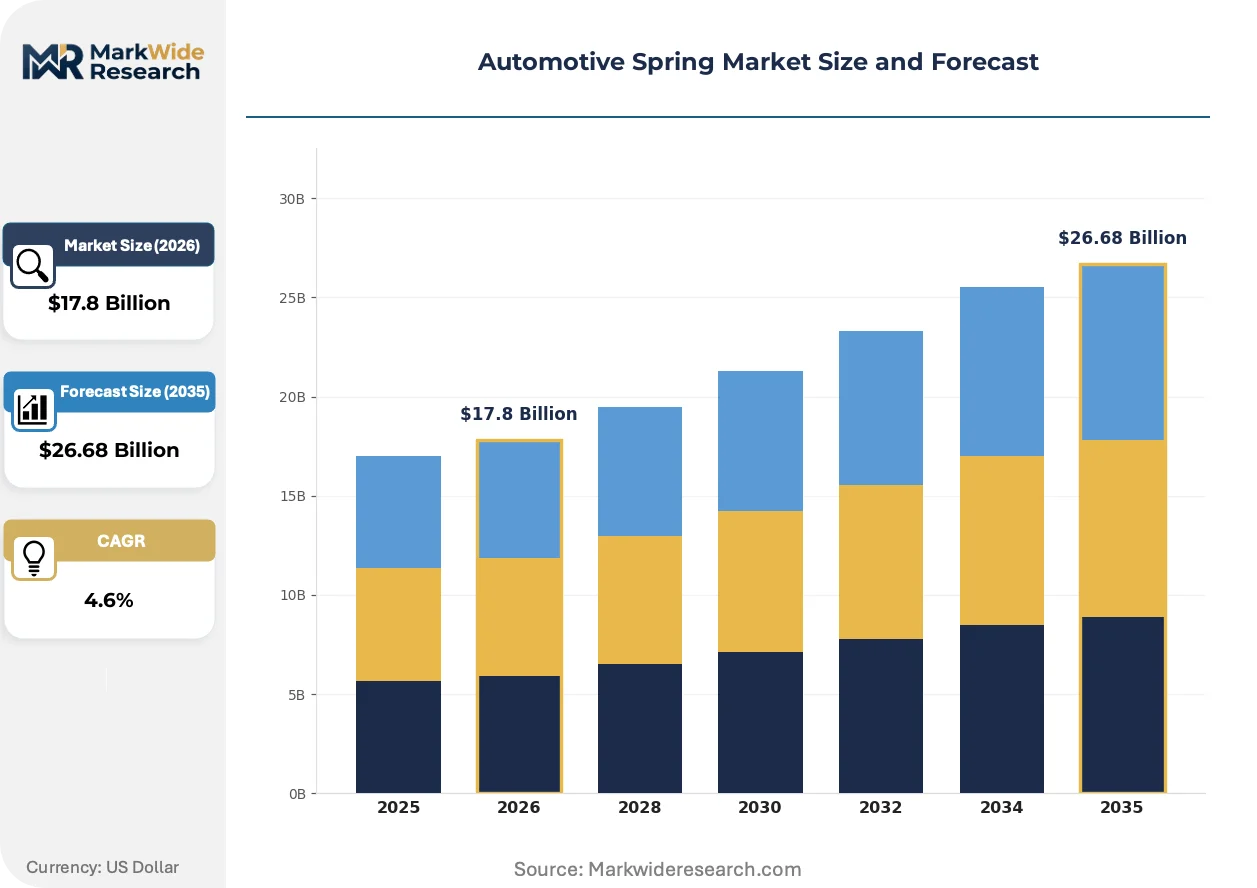
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $26.68 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coil Springs, Leaf Springs, Air Springs, Hydraulic Springs Application: Passenger Vehicles, Commercial Vehicles, Motorcycles, Heavy Machinery Material: Steel, Composite, Aluminum, Rubber Distribution Channel: Online Retail, Automotive Parts Stores, Direct Sales, Distributors |
| Companies Covered | Lesjofors, Hendrickson, Thyssenkrupp, Chuo Spring, NHK Spring, Schaeffler, Mubea, Rassini, Eibach, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Spring Market Strategic Shifts & Innovations
Material science advancements are converging with new vehicle architectures, forcing spring manufacturers to balance the conflicting priorities of extreme lightweighting for electric vehicles and cost efficiency for internal combustion engine models.
Multi-material springs combine elements like high-strength steel with composite over-wraps to optimize performance characteristics within a single component. Premium EV and performance vehicle manufacturers are adopting these designs to balance durability, weight, and specific handling responses. This approach is unifying previously separate design philosophies for load management and lightweighting into a single, integrated component strategy that addresses multiple engineering goals simultaneously.
Vehicle-level emissions and weight reduction targets, such as those within the US EPA's standards and the European Green Deal, are indirectly shaping spring design. These regulations compel automakers to pursue every opportunity for lightweighting, increasing pressure on component suppliers to innovate away from traditional, heavier materials. The passenger vehicle segment, especially for battery-electric models where weight directly impacts range, is most affected and is accelerating the adoption of lighter spring materials.
Automakers are standardizing chassis components across multiple vehicle models through the use of modular platform strategies. This disrupts the traditional model of bespoke spring design for each vehicle, favoring suppliers who can deliver a range of spring rates from a common component architecture. This trend is most visible in the global operations of large automotive groups, particularly for their expanding electric vehicle lineups built on shared platforms.
Automotive Spring Market Segmentation
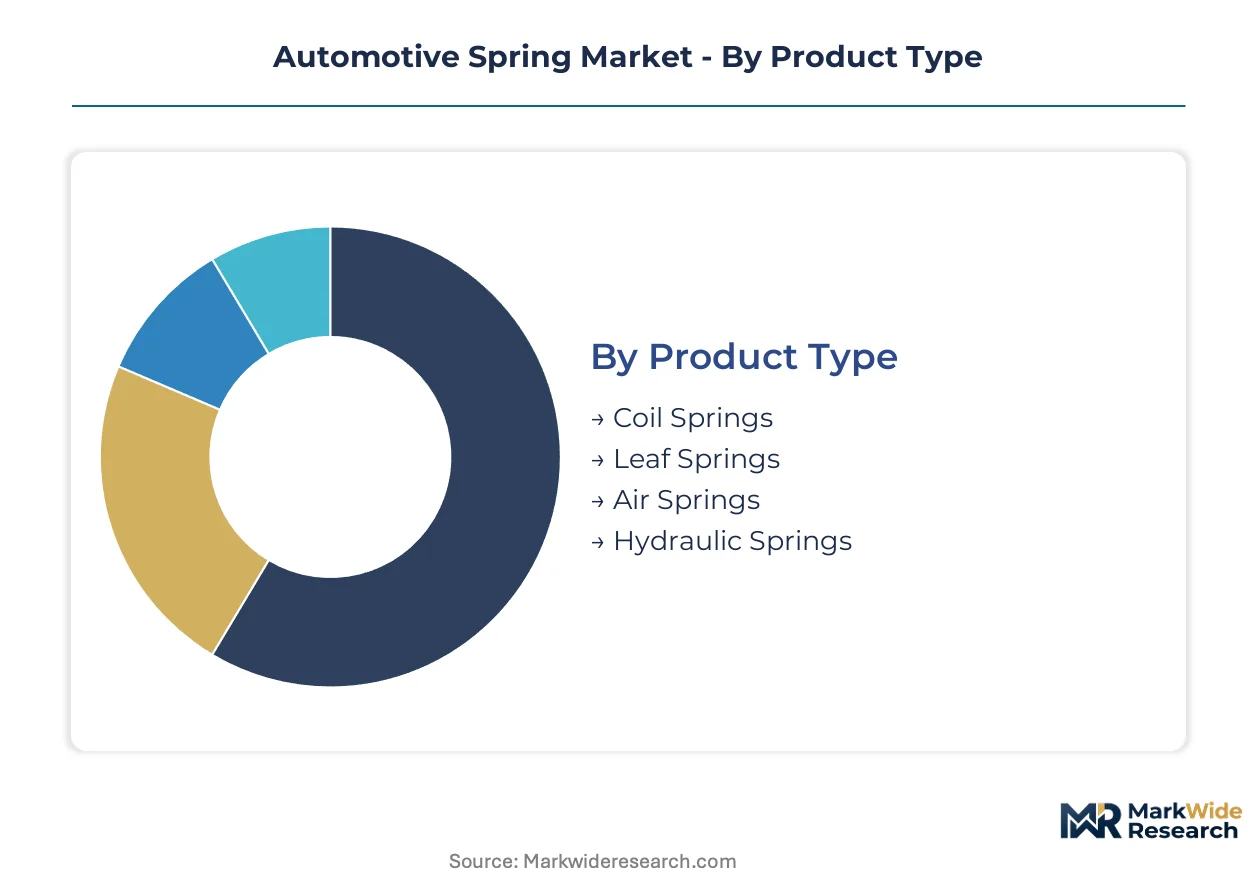
The automotive spring market's segmentation reveals the diverse engineering and commercial requirements across vehicle types and material innovations. Understanding these distinct segments allows manufacturers to tailor product development and sales strategies effectively. Each category reflects varying performance needs, cost sensitivities, and supply chain dynamics.
Product Type:
Buyers in this category differentiate based on the specific load management, damping characteristics, and space requirements of their vehicle designs.
- Coil Springs:Helical springs absorb kinetic energy through compression, supporting vehicle weight and isolating the chassis from road irregularities. Passenger vehicles drive significant demand for these compact designs, optimizing packaging space and ride comfort across various models.
- Air Springs:Air-filled bellows provide a variable spring rate, automatically adjusting to changes in load and road conditions for enhanced ride quality. Premium electric vehicles increasingly adopt air springs to effectively manage heavy battery packs and integrate with sophisticated adaptive suspension systems.
- Leaf Springs:Multi-layered or single composite strips manage vertical loads and provide basic damping, commonly found in commercial vehicles.
- Hydraulic Springs:Fluid-filled cylinders offer adjustable damping and load-leveling functions, often integrated into advanced suspension systems.
Coil springs lead volumes today; air springs are gaining share fastest.
Application:
End-use application requirements drive distinct spring specifications, influencing material choice, durability, and performance characteristics for different vehicle types.
- Passenger Vehicles:Springs support the vehicle chassis, isolating occupants from road shocks and contributing to handling stability. Electric vehicle adoption significantly boosts demand for lightweight springs in this segment, improving range and overall vehicle dynamics.
- Commercial Vehicles:Springs manage heavy payloads and provide robust stability for trucks, buses, and vans under demanding operational conditions. Stringent safety regulations and the sustained movement of freight across continents maintain consistent demand for durable, high-capacity springs.
- Motorcycles:Springs provide essential suspension for two-wheeled vehicle stability, handling, and rider comfort across diverse terrains.
- Heavy Machinery:Robust springs absorb extreme shocks and vibrations in construction, agricultural, and mining equipment, ensuring operational resilience.
Passenger vehicles constitute the largest end-use segment, while commercial vehicles demonstrate consistent procurement.
Material:
Material properties dictate a spring's weight, strength, fatigue resistance, and cost, directly impacting vehicle performance and manufacturing expenses.
- Steel:High-tensile steel alloys offer excellent strength, durability, and cost-effectiveness, making them the traditional choice for spring manufacturing. Legacy internal combustion engine vehicles predominantly utilize steel springs, driven by cost-sensitive, high-volume production models.
- Composite:Advanced fiber-reinforced polymers provide significant weight reduction and allow for tailored stiffness properties, crucial for modern vehicle design. Electric vehicle manufacturers increasingly specify composite springs to offset heavy battery weight and enhance vehicle range and efficiency.
- Aluminum:Lightweight metal alloys offer moderate weight savings for specific spring designs where overall mass reduction is a priority.
- Rubber:Elastomeric compounds provide vibration isolation and supplementary damping in auxiliary spring applications, enhancing ride comfort.
Steel maintains its market dominance, but composites show the steepest expansion trajectory.
Distribution Channel:
Customer procurement preferences and the nature of the sale (OEM vs. aftermarket) define the primary routes through which automotive springs reach end-users.
- Direct Sales:Manufacturers sell springs directly to original equipment manufacturers (OEMs) for integration into new vehicle assembly lines. Long-term contracts and stringent quality assurance processes characterize this channel, ensuring integrated supply for global automakers.
- Automotive Parts Stores:Brick-and-mortar retail outlets supply replacement springs to consumers and independent repair shops for vehicle maintenance and repair. The aftermarket segment sustains demand through these stores, driven by vehicle aging and routine component replacement cycles.
- Online Retail:E-commerce platforms facilitate direct-to-consumer sales for both replacement and performance-oriented springs, offering convenience and broad product selection.
- Distributors:Wholesalers and intermediaries supply springs to smaller repair shops, garages, and niche vehicle builders, providing logistical support.
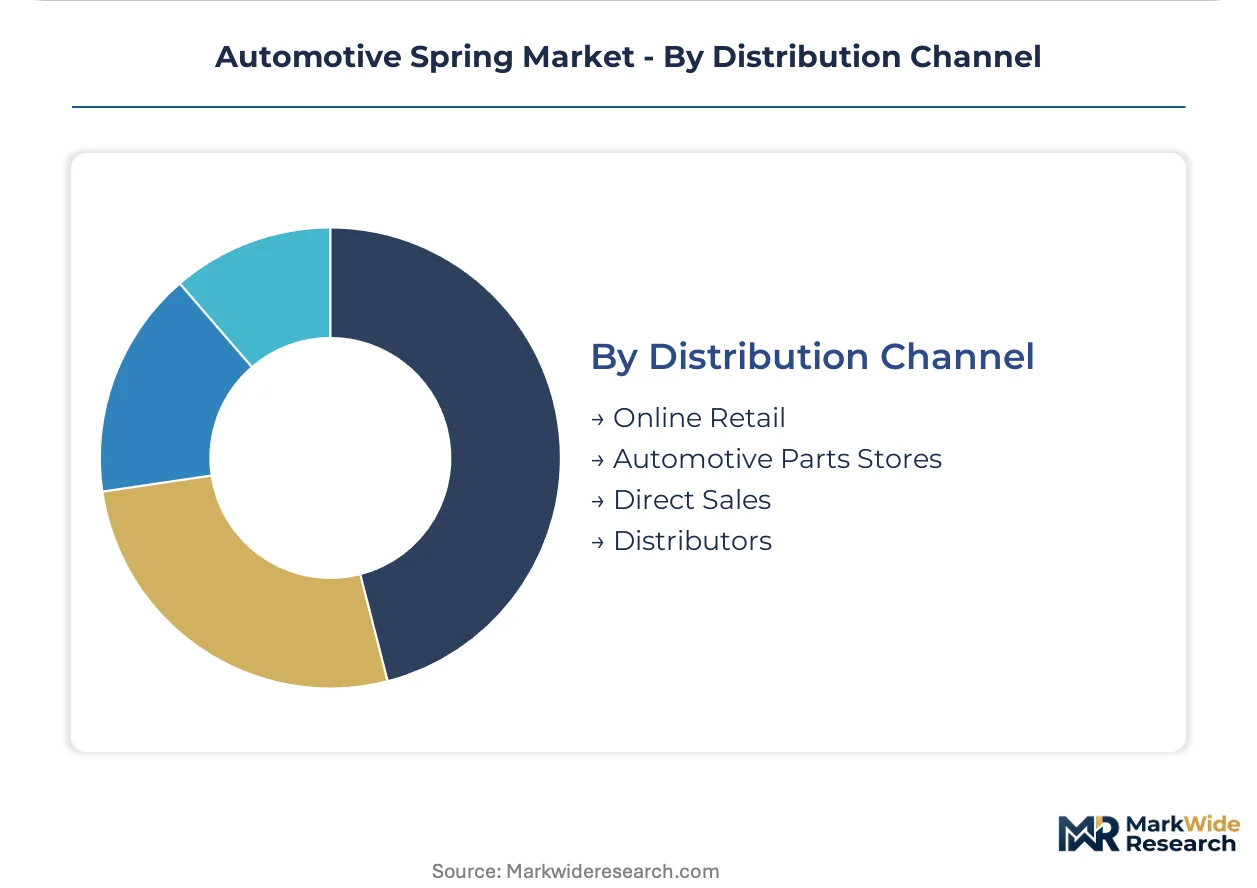
Direct sales routes remain critical for original equipment manufacturers, while automotive parts stores cater to the aftermarket.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The automotive spring industry historically scaled alongside the mass production of vehicles in Germany and the United States. Today, demand patterns are shifting globally, driven by stringent emissions targets and the expanding electric vehicle sector. Manufacturing centers are increasingly concentrated in key Asian markets.
China
China's robust electric vehicle adoption and extensive commercial vehicle production fuel significant demand for diverse springs. The country's GB standards dictate material quality and performance testing for all automotive components. Manufacturing clusters in the Yangtze River Delta region focus on high-volume spring production for both domestic and international automakers.
Germany
German premium automotive manufacturers drive demand for advanced spring solutions, including sophisticated multi-material designs. The European Union's Green Deal influences spring design through vehicle-level emissions and weight reduction targets. Automotive engineering hubs in Baden-Württemberg specialize in developing high-performance springs for luxury and electric vehicle applications.
United States
The United States market sees strong demand from its expanding electric vehicle sector and continued production of light trucks and SUVs. US Environmental Protection Agency (EPA) standards indirectly shape spring design through vehicle-level emissions and weight reduction goals. Detroit's automotive cluster remains central for spring suppliers, focusing on innovative solutions for new vehicle platforms.
Japan
Japanese automakers require high-precision springs for their globally exported passenger vehicles and advanced material adoption. Japan Industrial Standards (JIS) ensure rigorous quality and performance benchmarks for all automotive components. The Chubu region, particularly around Nagoya, hosts numerous specialized spring manufacturers serving major automotive original equipment manufacturers.
India
India's rapidly expanding vehicle production, including a significant two-wheeler market, creates consistent demand for cost-effective springs. The country's Production-Linked Incentive (PLI) scheme encourages domestic manufacturing of automotive components. Chennai, a major automotive manufacturing hub, attracts spring suppliers establishing local production facilities.
Automotive Spring Market Key Industry Players
The competitive structure tilts toward large, diversified manufacturers, complemented by specialized innovators. Several global players leverage extensive manufacturing scale to serve both traditional and advanced material needs. Market participants engage in strategic partnerships to co-develop new spring technologies and pursue capacity expansion for lightweight composite production. Portfolio diversification into advanced suspension systems also represents a key competitive move.
Within the diversified manufacturing segment, Germany-based Thyssenkrupp AG exemplifies a player with vast manufacturing scale, serving a broad spectrum of automotive spring requirements. NHK Spring Co., Ltd., a Japan-based entity, occupies a strong position across Asian markets due to its extensive product portfolio for various vehicle types. Another Germany-based firm, Mubea GmbH, represents a specialist archetype, focusing on lightweight chassis components and innovative composite leaf springs for modern vehicles.
| Leading Market Players |
|---|
| Lesjofors |
| Hendrickson |
| Thyssenkrupp |
| Chuo Spring |
| NHK Spring |
| Schaeffler |
| Mubea |
| Rassini |
| Eibach |
| Others |
Cost & Logistics Intelligence
The transition to lightweight composite materials in automotive spring production simultaneously reshapes cost economics and supply concentration. This shift demands new manufacturing processes and specialized raw material sourcing, influencing the final pricing of components and the geographic distribution of production capabilities.
Pricing Analysis
Bundled engineering services and component supply define pricing for original equipment manufacturers, while aftermarket sales follow a transactional model. Price differentiation stems from material quality grade, such as advanced composites versus high-tensile steel, and the level of customization required for specific vehicle platforms. Pricing pressure stems from the volatility of high-tensile spring steel costs, impacting traditional spring manufacturers. Original equipment manufacturers exhibit lower price sensitivity for mission-critical, lightweight composite springs, while the aftermarket segment remains highly price-sensitive for standard steel replacements.
Supply Chain Analysis
Reverse-logistics flows for end-of-life springs are gaining importance, driven by European Union recyclability directives for materials like steel and composites. Geographic supply concentration centers in China for high-volume production, Germany for advanced engineering, and Japan for precision manufacturing. The supply chain relies heavily on high-tensile spring steel and advanced fiber-reinforced polymers. Commodity price volatility for steel represents a significant structural risk for manufacturers. Distribution runs through direct sales channels to original equipment manufacturers and automotive parts stores for the aftermarket.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Automotive Spring Market presents a late-cycle quality story, driven by the demand-shift toward premium specifications for electric vehicle suspension systems.
For Market Incumbents: To counter the scarcity of composite production expertise and the cost-sensitive legacy internal combustion engine market, incumbents should invest in advanced material science R&D. Capacity expansion for composite manufacturing lines in strategic locations like China will also reinforce market position. Strategic partnerships with material science firms can accelerate the development of lower-cost, recyclable composites.
For New Entrants and Emerging Players: Price-point gaps exist between premium and economy tiers, particularly for specialized electric vehicle applications. New entrants should target the emerging electric vehicle aftermarket for specialized, lightweight springs designed for battery weight. A go-to-market angle focusing on online retail and specialized distributors can effectively reach performance-oriented electric vehicle owners. Innovation in low-cost composite manufacturing processes represents a significant white-space opportunity.
For Investors and Strategic Acquirers: Valuations sit cheapest among traditional steel spring manufacturers with limited composite capabilities. The long-term viability of the market is anchored by the global transition to electric vehicles, ensuring sustained demand for specialized, lightweight components. Acquisition targets should include specialists in high-volume composite manufacturing or integrated advanced suspension system developers. The commercialization of automated, low-cost composite production methods is a critical signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Composites | Increases supply of lightweight springs for electric vehicle platforms, addressing a critical market need. |
| Green Manufacturing Transition | Aligns production with European Union recyclability directives, enhancing material selection calculus. |
| Joint Venture in Material Science | Accelerates development of low-cost, high-performance composite materials for mass market adoption. |
| Product Launch: Multi-Material Springs | Offers optimized performance characteristics for premium electric vehicles, balancing durability and weight. |
| Distribution Channel Expansion: EV Aftermarket | Captures replacement demand for specialized springs designed for the unique wear patterns of electric vehicles. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary insights with robust secondary validation. Industry stakeholders including OEM procurement leads, Tier 1 R&D engineers, aftermarket distributors, and material scientists provided critical perspectives. Secondary data sources encompassed vehicle production databases, international trade statistics, patent filings for new materials, and regulatory reports from the US EPA and European Union.
The forecast framework anchored the projection horizon to historical reference periods, building an analytical model that disaggregates market value and volume. Segmentation dimensions modeled included product type, application, material, distribution channel, and regional production clusters. Compound annual growth rates were derived from an assessment of historical trends and projected future demand drivers. Forecast inputs integrated electric vehicle adoption rates and raw material cost trends.
Caveats apply where geopolitical shifts, raw material supply disruptions, or unexpected technological breakthroughs could materially shift the outlook. Forecasts reflect assumptions regarding economic stability and regulatory continuity across the analysis window. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Latin America Electric Power Steering Market
Automotive Parts
Motor Bearings Market
Automotive Parts
Automotive Oil Pressure Switch Market
Automotive Parts
Philippines Automotive Engine Oils Market
Automotive Parts
Europe Motorcycle Parts and Accessories Market
Automotive Parts
Undercarriage Systems Market
Automotive Parts
Global Automotive Closure Market
Automotive Parts
Automotive Steel Market
Automotive Parts
Insert Drive for Torque Wrench Market
Automotive Parts
Automotive Steering System Market
Automotive Parts
UK Automotive Parts Aluminium Die Casting Market
Automotive Parts
Bearing Steel Balls for New Energy Vehicles Market
Automotive Parts
Automotive Hydraulic Filter System Market
Automotive Parts
France Automotive Hydraulic Actuators Market
Automotive Parts
Motorcycle Catalyst Market
Automotive Parts
Vietnam Passenger Vehicles Lubricants Market