
 Automotive Hinges Market | 2026-2036
Automotive Hinges Market Size, Share, and Industry Trends Forecast 2026-2036
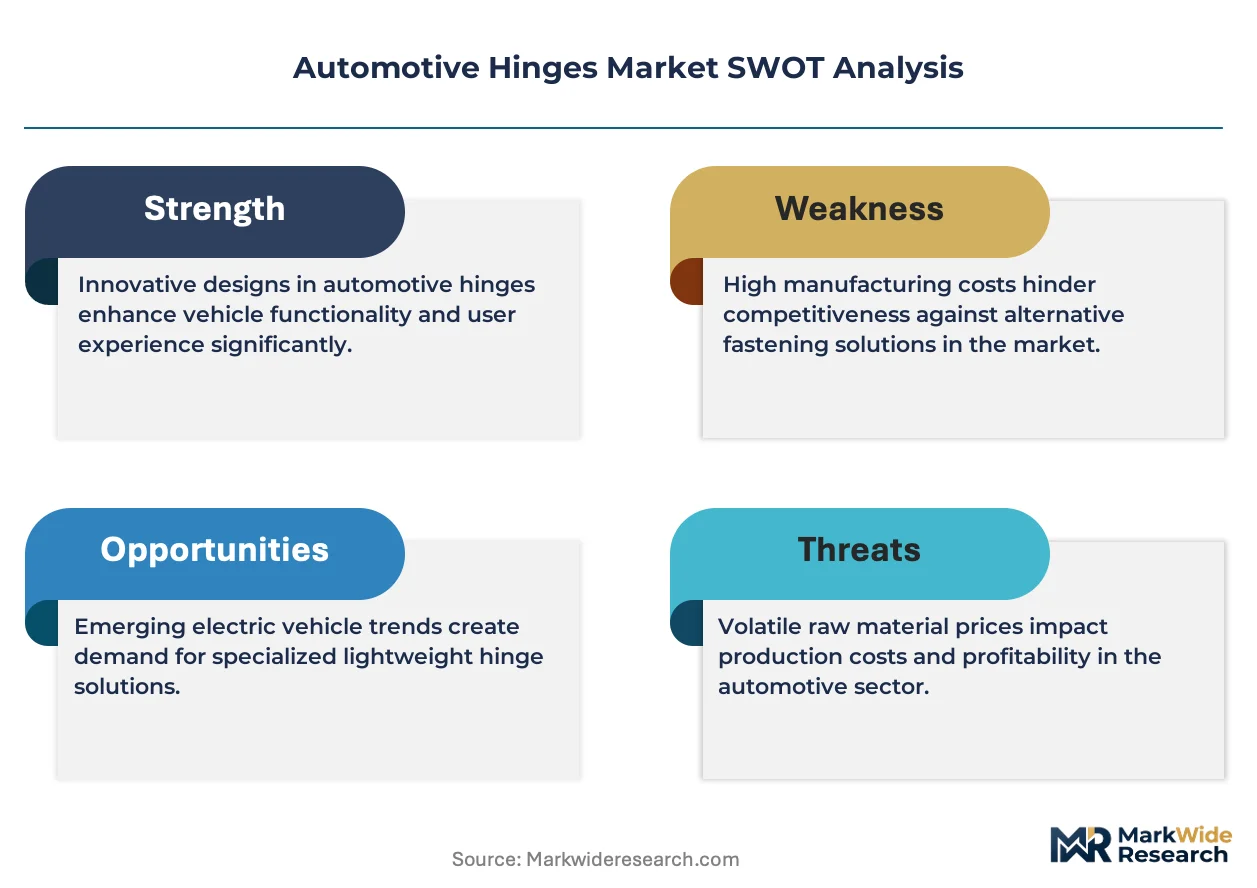
Automotive Hinges Market Analysis
IATF 16949 qualification is redrawing supplier eligibility across the automotive closure hardware sector, forcing tier-two stampers to upgrade quality systems or exit the value chain. Multimatic Inc leverages its integrated stamping and assembly footprint to anchor North American programs for light-truck tailgate hinges. Edscha Holding GmbH sustains decades of European OEM relationships through specialized door-hinge engineering for premium sedans. Magna International Inc dominates global volume by operating multi-material hinge lines that span steel, aluminum, and composite variants.
Automotive hinges are mechanical articulation devices that connect movable body panels to vehicle structures, typically fabricated from stamped steel or extruded aluminum with specified fatigue-life ratings exceeding 100,000 open-close cycles to ensure durability across a vehicle's service life. Their primary purpose is to enable controlled motion of doors, hoods, trunks, and tailgates while maintaining precise gap alignment and crash-energy management. Door hinges and tailgate hinges carry the largest share of OEM contract value due to their load-bearing requirements and integration with electronic latching systems. Aluminum material grades represent the fastest-expanding segment as electric vehicle platforms pursue mass reduction to extend driving range. Hood hinges for passenger cars remain a mature, price-competitive category where margin pools have shifted toward integrated sensor-mounting features.
NHTSA Federal Motor Vehicle Safety Standards govern hinge retention strength and secondary-latch performance in the United States, while E-Mark certification under United Nations Economic Commission for Europe regulations dictates durability testing protocols for European type approval. China's GB/T standards and MIIT administrative rules add localized corrosion-resistance and recycling-content requirements that shape supplier qualification timelines. Stakeholders must monitor how evolving pedestrian-protection regulations and autonomous-vehicle sensor integration requirements will redefine hinge load paths and material specifications in next-generation body architectures.
Market Dynamics
The transition to electric vehicle platforms is compressing traditional hinge design cycles while simultaneously demanding multi-material architectures that reconcile mass reduction with crash-performance retention.
Growth Catalysts
- EV Platform Weight Targets:Electric vehicle manufacturers are mandating aluminum-grade hinges to offset battery pack mass, creating specification upgrades across sedan and SUV body closures.
- E-Mark Durability Protocols:United Nations Economic Commission for Europe regulations are extending cycle-testing requirements, forcing hinge suppliers to engineer fatigue-resistant articulation mechanisms.
- Stuttgart Supplier Corridor:Germany's automotive engineering cluster around Stuttgart and Wolfsburg is concentrating R&D investment in integrated sensor-mounting hinge designs for premium vehicle programs.
Market Restraints
- Aluminum Price Volatility:Primary aluminum input costs fluctuate with energy pricing, compressing margins on lightweight hinge contracts indexed to metal exchanges.
- Stamping Capacity Concentration:Tier-two metal forming capacity clusters in China's industrial zones, creating single-source vulnerability for European and North American OEM qualification timelines.
- Steel Substitution Ceiling:High-strength steel retains cost advantage in full-size truck and commercial vehicle segments, limiting aluminum penetration in load-bearing tailgate applications.
Strategic Opportunities
- Autonomous Sensor Integration:LiDAR and camera mounting requirements are creating hinge-design white space for articulation mechanisms with embedded wiring channels and vibration damping.
- Pedestrian Protection Mandates:European Union pedestrian-impact regulations are driving demand for active hood hinge systems that deploy pyrotechnic lift mechanisms during collision events.
- Direct OEM Contracting:Door-hinge suppliers are bypassing traditional tier-one module integrators to capture specification control and margin from German and Japanese OEM engineering centers.
Industry Challenges
- IATF 16949 Transition Costs:Tier-two stampers face capital-intensive quality system overhauls to maintain supplier eligibility, with audit failure rates highest among single-plant operations.
- Multi-Material Welding Expertise:Aluminum-steel hybrid hinge production requires friction-stir welding capabilities that remain scarce in legacy stamping facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Hinges Market |
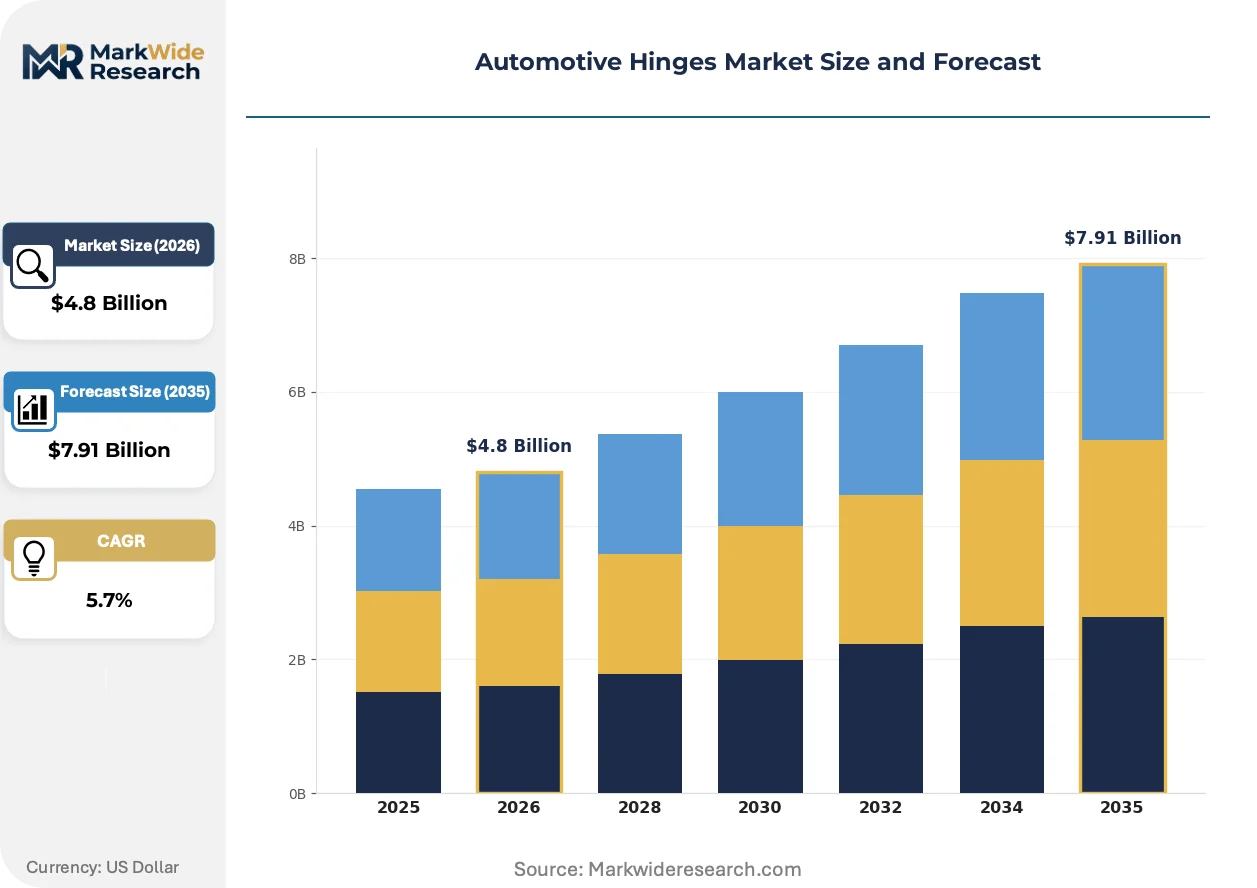
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hood Hinges, Trunk Hinges, Door Hinges, Tailgate Hinges Material: Steel, Aluminum, Plastic, Composite Vehicle Type: Passenger Cars, Commercial Vehicles, Motorcycles, Electric Vehicles Installation Type: OEM, Aftermarket, Custom, Replacement |
| Companies Covered | Multimatic Inc, Edscha Holding GmbH, Magna International Inc, ER Wagner, Brano Group, Aisin Corporation, Dura Automotive Systems LLC, Midlake Products & Mfg. Company Inc., Gestamp Automoción, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Hinges Market Emerging Trajectories
Active safety regulations and electric vehicle packaging constraints are forcing hinge architectures to absorb functions previously handled by separate body-structure components.
Aluminum extrusion hinge designs are bifurcating the market between mass-optimized EV platforms and cost-sensitive internal combustion segments. Premium electric vehicle programs specify hollow-box aluminum extrusions with integrated wire routing, while conventional vehicle lines retain stamped steel for price positioning. This material split is compressing supplier margins in the steel-dominated mid-market while enabling premium pricing for certified aluminum architectures.
REACH chemical compliance and EU Green Deal carbon-border adjustments are tightening material provenance requirements for European type approval. Suppliers must now document recycled content percentages and supply-chain emissions for aluminum hinge batches. German OEMs are responding by qualifying domestic and Nordic primary aluminum sources ahead of 2026 regulatory phase-ins.
Fleet procurement departments are consolidating hinge specifications across vehicle nameplates to compress supplier management overhead. This buying-pattern compression favors multi-program suppliers with IATF 16949 certification and cross-platform tooling flexibility. The consolidation is most visible in North American light-truck segments where single hinge designs now span multiple model years and brand badges.
Automotive Hinges Market Segmentation
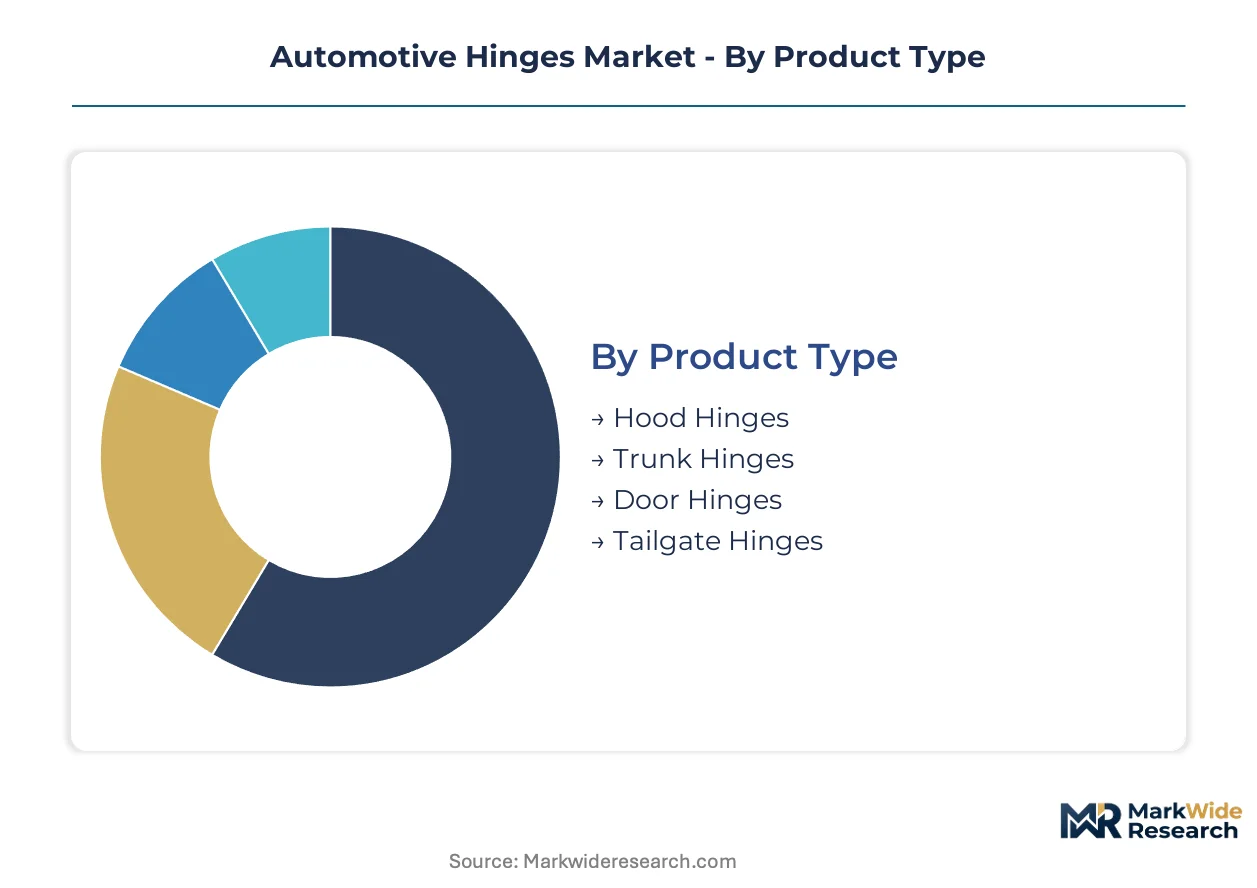
Automotive hinge procurement splits across four dimensions that determine specification authority and margin capture. Product type defines load-bearing requirements and integration complexity. Material selection increasingly separates electric vehicle programs from internal combustion architectures. Vehicle type dictates durability protocols and regulatory testing regimes. Installation type governs whether suppliers contract directly with OEM engineering centers or distribute through aftermarket channels.
Product Type:
Door hinges face the most acute substitution pressure as integrated electronic latching systems reduce standalone mechanical component value.
- Door Hinges:These multi-axis articulation mechanisms manage vertical and lateral loads while maintaining precise panel gaps across temperature cycles. German premium sedan programs concentrate specification authority here, with Stuttgart engineering centers mandating integrated sensor mounting provisions. Fatigue-life requirements exceeding 100,000 cycles dominate contract negotiations.
- Tailgate Hinges:Load-bearing designs for pickup trucks and SUVs must retain structural integrity under cantilevered cargo loads. North American light-truck programs anchor demand, with Multimatic anchoring assembly contracts through integrated stamping and welding footprints. Secondary-latch retention under NHTSA load protocols remains the critical qualification hurdle.
- Hood Hinges:Pedestrian-protection regulations are forcing active lift mechanisms into these previously passive components. European type approval under E-Mark protocols now requires pyrotechnic deployment capability.
- Trunk Hinges:Compact passenger car programs specify these for space-efficient rear closure systems. Cost positioning limits material specification upgrades in this category.
Door hinges anchor the volume base while tailgate hinges gain share at the steepest rate driven by light-truck segment expansion.
Material:
Cost tier stratification increasingly separates certified aluminum architectures from commodity steel specifications.
- Aluminum:Hollow-box extrusion designs with integrated wire routing channels dominate EV platform procurement. German OEMs are qualifying Nordic primary aluminum sources ahead of EU Green Deal carbon-border adjustments. REACH compliance documentation now accompanies every batch.
- Steel:High-strength stamped grades retain cost advantage in full-size truck and commercial vehicle segments. China's industrial zones concentrate tier-two stamping capacity for this material tier.
- Composite:Glass-fiber reinforced polymers appear in limited motorsport and hypercar applications where extreme mass reduction justifies unit cost premiums.
- Plastic:Interior compartment hinges and non-structural applications specify these for cost minimization in emerging market vehicle programs.
Steel maintains the installed base while aluminum climbs the fastest on EV platform penetration.
Vehicle Type:
Application-specific durability requirements fragment specification standards across mobility categories.
- Electric Vehicles:Battery pack mass offsets demand aluminum-grade hinges across all closure types. Stuttgart and Wolfsburg engineering clusters concentrate R&D investment for integrated sensor-mounting designs.
- Passenger Cars:Mature specification standards dominate this volume segment, with margin pools shifting toward electronic integration features rather than mechanical articulation.
- Commercial Vehicles:Cycle-count requirements exceed passenger car standards by factors of three to five. Fleet procurement departments are consolidating specifications across nameplates to compress supplier management overhead.
- Motorcycles:Exposed hinge designs require enhanced corrosion resistance under GB/T standards for Chinese domestic market approval.
Passenger cars carry the volume base while electric vehicles expand most quickly on platform proliferation.
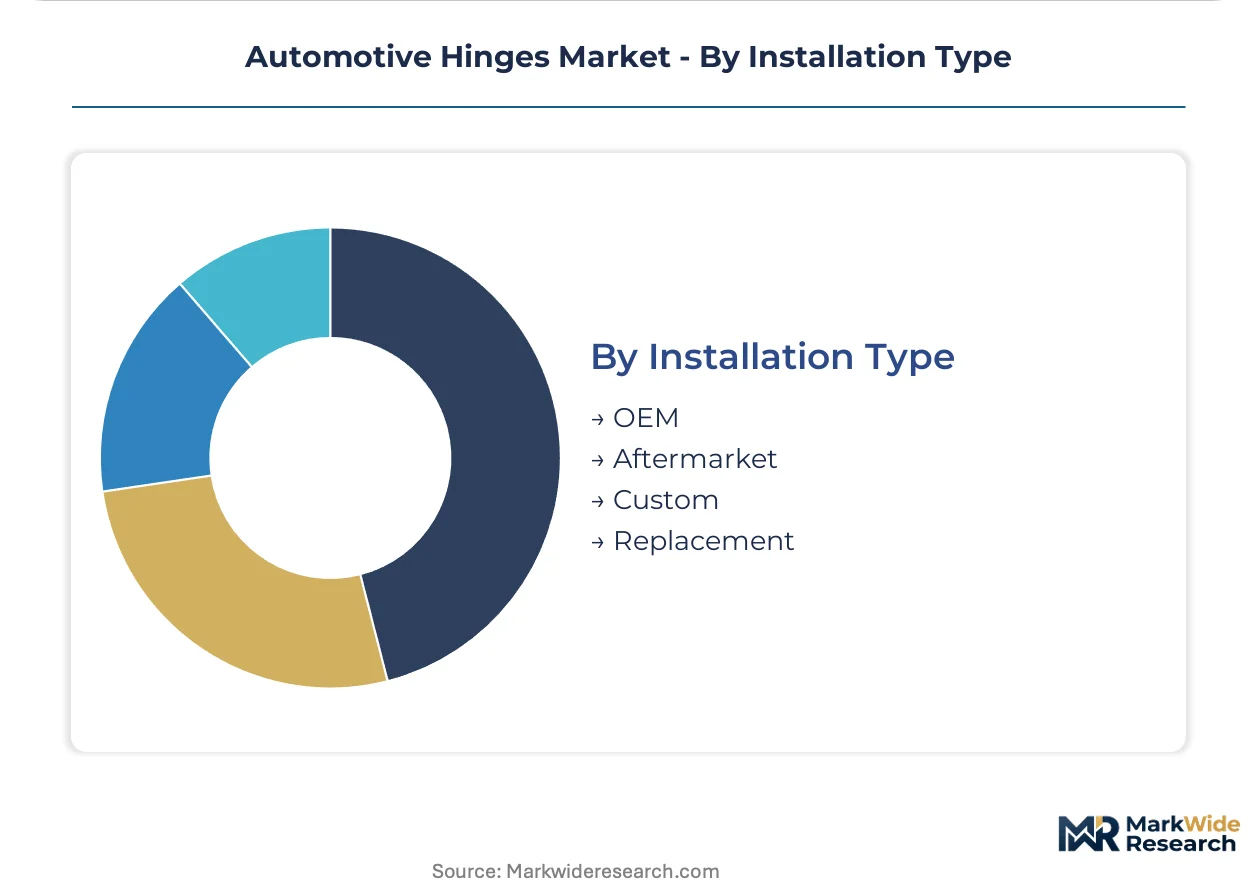
Installation Type:
Customer type determines whether suppliers capture specification control or compete as price-takers in fragmented distribution channels.
- OEM:Direct contracting with vehicle manufacturer engineering centers enables margin capture and specification influence. IATF 16949 certification is mandatory for eligibility.
- Aftermarket:Distributor relationships and inventory velocity dominate competitive positioning. Price transparency compresses margins versus OEM channels.
- Replacement:Insurance-funded collision repair generates demand matched to original specifications. Documentation of recycled content percentages is becoming standard.
- Custom:Low-volume specialty vehicle builders and restomod workshops specify these for non-standard body architectures.
OEM installation anchors the value base while aftermarket channels expand on vehicle parc age extension.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government incentives for electric vehicle adoption are reshaping procurement patterns across major automotive manufacturing hubs, with regulatory tightening on closure-system durability accelerating supplier qualification timelines in key markets.
United States
Light-truck tailgate hinge demand anchors North American volume as Detroit Three OEMs consolidate specifications across nameplates. NHTSA Federal Motor Vehicle Safety Standards govern retention strength and secondary-latch performance for type approval. Michigan's supplier corridor around Detroit concentrates stamping and assembly capacity for full-size pickup programs.
Germany
Premium sedan door-hinge engineering commands specification authority through Stuttgart engineering centers mandating integrated sensor provisions. E-Mark certification under United Nations Economic Commission for Europe regulations extends cycle-testing requirements beyond prior thresholds. The Wolfsburg-Stuttgart corridor concentrates R&D investment in aluminum extrusion designs for electric vehicle platforms.
China
Domestic EV platform proliferation drives aluminum-grade hinge procurement to offset battery pack mass. MIIT administrative rules and GB/T standards impose localized corrosion-resistance and recycling-content requirements on suppliers. Yangtze River Delta industrial zones cluster tier-two stamping capacity serving both domestic OEMs and export qualification timelines.
Japan
Keiretsu procurement structures favor long-term supplier relationships for precision door-hinge articulation mechanisms. METI industrial policy and JIS standards shape quality system expectations for export-oriented production. Kansai manufacturing clusters around Osaka maintain specialized fatigue-testing capabilities for premium vehicle programs.
South Korea
Hyundai-Kia Group platform consolidation creates volume concentration for multi-material hinge architectures. MFDS automotive component oversight and KSA quality certification align with export market requirements. Seoul Capital Area suppliers are upgrading friction-stir welding capabilities for aluminum-steel hybrid production.
Automotive Hinges Market Vendor Landscape
Listed leaders compete with private specialists across capital access and engineering agility dimensions. Tier-one module integrators retain specification influence on high-volume programs while tier-two stampers face IATF 16949 transition pressures. Three archetypes dominate: integrated stamping-assembly operators, specialized door-hinge engineering houses, and multi-material volume producers. M&A activity concentrates among European precision engineering assets, while capacity expansion focuses on aluminum extrusion lines in German and Chinese industrial zones.
Among North American-integrated operators, Multimatic Inc exemplifies the stamping-assembly archetype through its captive production footprint. Edscha Holding GmbH represents the European specialist tier with decades of OEM relationship continuity. Magna International Inc anchors the multi-material volume position with certified lines spanning steel, aluminum, and composite variants.
| Leading Market Players |
|---|
| Multimatic Inc |
| Edscha Holding GmbH |
| Magna International Inc |
| ER Wagner |
| Brano Group |
| Aisin Corporation |
| Dura Automotive Systems LLC |
| Midlake Products & Mfg. Company Inc. |
| Gestamp Automoción |
| Others |
Supply Flow & Price Mechanics
IATF 16949 certification gates supplier eligibility and price differentiation simultaneously, forcing tier-two stampers to absorb quality-system costs while OEMs extract premium positioning for certified aluminum architectures. Buyers face compressed lead times and material-indexed contracts that transmit aluminum price volatility directly into component costs.
Pricing Analysis
Certification level creates the primary spread between IATF-qualified premium suppliers and uncertified commodity stampers. Three-tier pricing structure across premium certified, standard qualified, and economy unverified levels tracks material grade and fatigue-cycle guarantees. Pricing pressure stems from aluminum spot-market volatility indexed to energy costs. Fleet procurement departments exhibit highest price sensitivity in full-size truck segments where steel retains cost advantage.
Supply Chain Analysis
Just-in-time delivery dominates OEM assembly plant relationships while strategic aluminum stockpiles buffer tier-one suppliers against LME price swings. Raw material supply concentrates in China's Yangtze River Delta for steel stamping, Germany's Stuttgart corridor for precision aluminum extrusion, and South Korea's Seoul Capital Area for friction-stir welding capacity. Production draws from primary aluminum smelters in Nordic regions and high-strength steel mills in East Asia. Single-source vulnerability clusters in Chinese tier-two stamping capacity. Distribution runs through tier-one module integrators to OEM engineering centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of friction-stir welding expertise and IATF 16949-certified aluminum extrusion capacity constrains supply expansion, concentrating margin capture among incumbent multi-material producers. Qualified engineering talent and certified production assets represent the binding bottlenecks.
For Market Incumbents: Secure backward integration into aluminum extrusion capacity to capture margin pools migrating from steel-dominated mid-market segments. Defend specification authority by embedding sensor-mounting provisions into door-hinge designs before autonomous-vehicle platforms finalize architectures. Add friction-stir welding lines in German or South Korean industrial zones to maintain qualification timelines against Chinese cost competition. For New Entrants and Emerging Players: Lead with active hood hinge systems for European OEMs facing E-Mark pedestrian-protection mandates, where pyrotechnic deployment mechanisms create specification white space. Target aftermarket replacement channels for aging light-truck parc in North America, where insurance-funded collision repair lacks price transparency. Position around recycled-content documentation capabilities ahead of EU Green Deal carbon-border adjustments. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European precision engineering specialists holding decades of Stuttgart OEM relationships. Five-to-ten year viability hinges on successful aluminum-grade transition and sensor-integration R&D conversion. Watch for IATF 16949 audit failure rates among single-plant tier-two stampers as inflection signal for consolidation opportunity.| Strategic Initiative | Industry Significance |
|---|---|
| Friction-Stir Welding Capacity Addition | Enables aluminum-steel hybrid hinge production for EV platform qualification under E-Mark protocols. |
| Active Hood Hinge System Development | Captures European OEM procurement for pedestrian-protection compliance with pyrotechnic deployment mechanisms. |
| Recycled Content Documentation Infrastructure | Qualifies suppliers for EU Green Deal carbon-border adjustments ahead of Nordic aluminum sourcing mandates. |
| Sensor-Mounting Integration Engineering | Positions hinge designs for autonomous-vehicle LiDAR and camera packaging requirements in Stuttgart engineering centers. |
| Tier-Two Stamping Consolidation | Absorbs IATF 16949 transition costs across multi-plant footprints to defend supplier eligibility. |
Methodological Framework
Initial hypotheses were tested against primary input from OEM platform engineers, tier-one supplier procurement directors, aftermarket distribution managers, and IATF certification auditors, then refined against vehicle production databases, customs trade records, SEC filings from listed automotive suppliers, and E-Mark type approval documentation. Bottom-up segment sizing triangulated with top-down market reconstruction.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects. The analytical framework models vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. CAGRs derive from segment-level build-up validated against macro vehicle production forecasts. Aluminum price elasticity and IATF certification penetration curves inform scenario boundaries.
The analysis sits within stated boundaries; outcomes outside sustained EV platform proliferation or aluminum cost stability would require recalibration. Forecasts reflect documented assumptions on regulatory phase-in timing and OEM platform consolidation patterns. Revision becomes warranted when IATF 16949 audit failure rates or EU carbon-border adjustment stringency crosses thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Steering Knuckle Market
Automotive Parts
Automotive Electric Drive Axle Market
Automotive Parts
Automotive Grease Market
Automotive Parts
Automotive Lifts Market
Automotive Parts
Automotive Fuel Delivery System Market
Automotive Parts
Global Automotive Selective Catalytic Reduction System Market
Automotive Parts
Automotive Metal Wheel Market
Automotive Parts
South America Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Parts Die Casting Market
Automotive Parts
Europe Automotive Lubricants Market
Automotive Parts
Global Automotive Motor Oil Market
Automotive Parts
Mexico Automotive Parts Die Casting Market
Automotive Parts
Clutch Pedal Kit Market
Automotive Parts
Gear Box and Gear Motors Market
Automotive Parts
Automotive Disc Brake Market
Automotive Parts
Electric Parking Brake Actuator Components Market