
 Automotive Oil Seals Market | 2026-2036
Automotive Oil Seals Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Oil Seals Market Outlook
Aftermarket service revenue is fragmenting across multiple channel layers as OEMs tighten captive parts programs and independent distributors fight for shelf space. Freudenberg Sealing Technologies leverages its vertically integrated rubber compounding network to control raw material pathways. SKF Group anchors its position through bearing-seal integration that locks in specification authority with vehicle assemblers. NOK Corporation specializes in compact seal geometries for Asian transmission architectures.
An automotive oil seal is an annular sealing device installed at rotating or reciprocating interfaces to retain lubricants and exclude contaminants, typically manufactured from nitrile rubber, fluorocarbon, or polytetrafluoroethylene compounds via compression or injection molding with metal case bonding. Radial oil seals dominate engine and transmission installations where shaft retention against pressurized oil galleries remains critical. Mechanical seals face displacement in lower-pressure auxiliary systems as spiral wound configurations gain traction in high-temperature turbocharger interfaces. Polyacrylate and polyurethane material grades command premium positioning in power steering and axle applications where chemical resistance to synthetic lubricants determines replacement cycles.
FDA and EPA frameworks in the United States impose material composition limits on seal elastomers exposed to fuel vapor recovery systems, while REACH and RoHS in Europe restrict phthalate plasticizers and heavy metal stabilizers in rubber formulations. China's GB standards and MIIT vehicle certification protocols mandate seal durability testing under thermal cycling regimes for domestic powertrain platforms. Stakeholders must track regulatory divergence between fluorocarbon approval pathways in North America and Europe versus China's accelerating domestic elastomer substitution mandates.
Market Dynamics
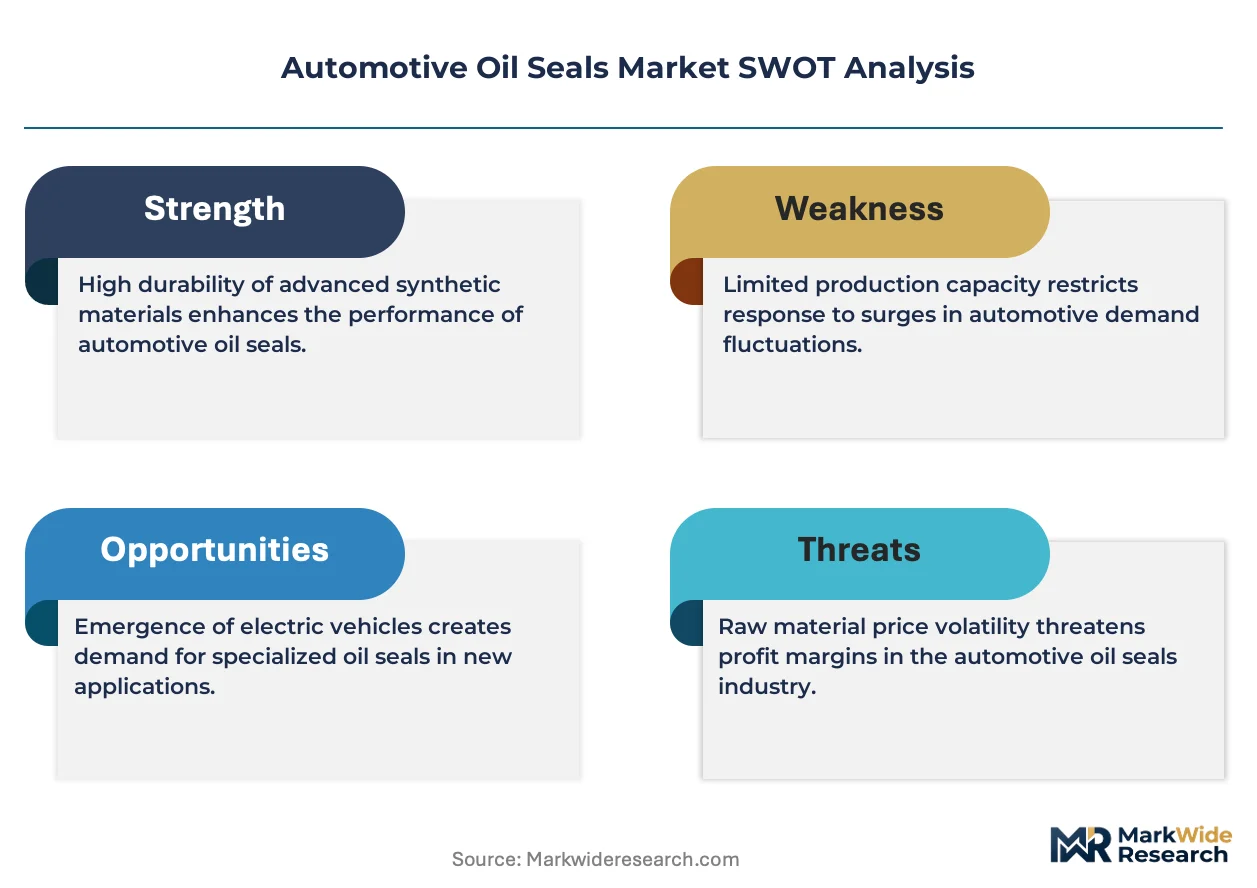
Electric vehicle powertrain architectures are eliminating traditional wet-sump sealing points while creating new thermal management sealing requirements that favor fluorocarbon compounds over nitrile rubber formulations. This shift is fragmenting incumbent supply relationships as OEMs requalify seal specifications for integrated e-axle modules.
Growth Catalysts
- China's NMPA vehicle safety standards:Thermal cycling durability mandates for domestic powertrain platforms are accelerating fluorocarbon seal validation programs among Tier-1 suppliers serving Yangtze River Delta assemblers.
- Turbocharger spiral wound configurations:High-temperature boost interfaces are displacing mechanical seals with advanced winding geometries that demand specialized elastomer compounding expertise.
- Synthetic lubricant chemistry:Polyurethane and polyacrylate material grades are capturing specification authority in power steering and axle applications where chemical resistance extends replacement intervals.
Market Restraints
- Fluorocarbon feedstock concentration:Specialty elastomer precursors rely on concentrated Asian chemical processing capacity, exposing seal manufacturers to input volatility and supply rationing during contract renegotiations.
- REACH phthalate restrictions:European rubber formulation compliance is forcing reformulation of legacy plasticizer systems, extending product development timelines and raising compound qualification costs.
- Solid-state bearing integration:Magnetic levitation and dry-running bearing technologies are eliminating radial seal requirements in select auxiliary pump applications.
Strategic Opportunities
- India's PLI scheme for auto components:Domestic manufacturing incentives are attracting fluorocarbon compounding investments to serve emerging EV assembly clusters around Chennai and Pune.
- Thermal interface materials convergence:Battery module sealing and cooling plate gasketing are merging specification requirements, creating cross-selling opportunities for seal manufacturers with polymer thermal conductivity expertise.
- Direct-to-fleet digital channels:Commercial vehicle operators are bypassing traditional distribution tiers through platform-based procurement, enabling margin capture for seal producers with logistics integration capabilities.
Industry Challenges
- Fluorocarbon compounding talent scarcity:Specialized polymer chemistry expertise for high-performance elastomer development is concentrating at a handful of European and Japanese compounders, constraining in-house capability building.
- Multi-standard certification complexity:Simultaneous compliance with EPA fuel vapor recovery requirements, REACH substance restrictions, and China's GB thermal cycling protocols is extending product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Oil Seals Market |
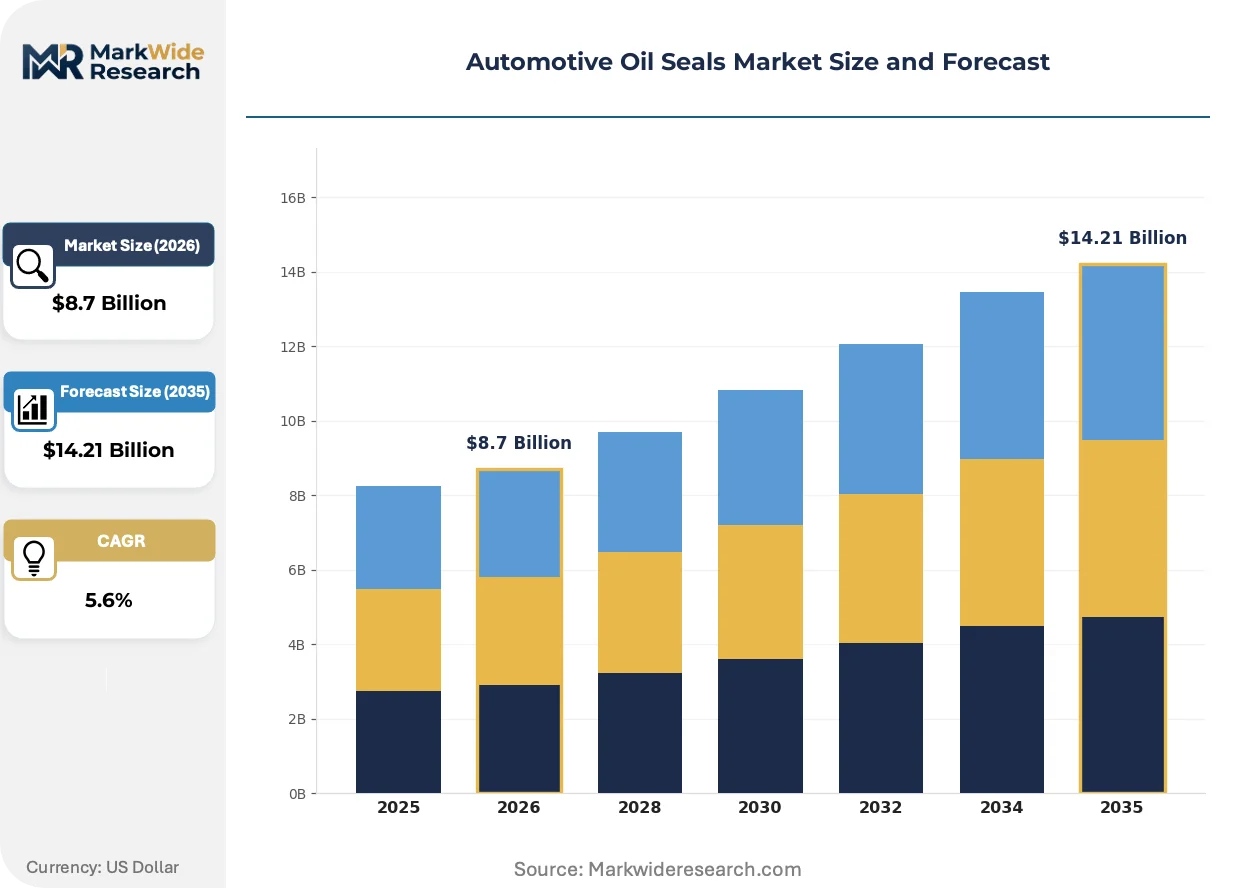
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radial Oil Seals, Mechanical Seals, Spiral Wound Seals, Face Seals Material: Rubber, Polyacrylate, Polyurethane, Metal Application: Engine Components, Transmission Systems, Power Steering, Axles End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Freudenberg Sealing Technologies, Parker Hannifin, NOK Corporation, Hutchinson, SKF Group, ElringKlinger AG, Dana, Trelleborg, Federal Mogul, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Oil Seals Market Strategic Shifts
Digital twin-based seal performance simulation is compressing physical prototyping cycles while predictive maintenance integration is shifting replacement revenue from calendar-based to condition-triggered service intervals. Material science advances and regulatory chemistry restrictions are jointly reshaping formulation roadmaps.
Multi-physics simulation platforms are virtualizing seal lip design optimization by modeling elastomer deformation, thermal expansion, and lubricant film thickness simultaneously before tool steel is cut. Major transmission manufacturers in Germany and Japan are adopting these tools for integrated e-axle seal development. The technology is virtualizing traditional iterative prototyping programs that previously consumed six to nine months of validation runway.
REACH F-Gas Regulation restrictions on perfluorinated compounds are forcing seal manufacturers to reformulate high-temperature grades using hydrogenated nitrile and terpolymer alternatives. The industrial consequence is a bifurcation between legacy fluorocarbon approvals for existing vehicle platforms and next-generation compound development for new EV architectures. European powertrain engineering centers are most affected, with Stuttgart and Munich supplier corridors accelerating domestic elastomer substitution programs to maintain specification authority.
Fleet operators are consolidating aftermarket procurement through integrated vehicle lifecycle management platforms that aggregate seal demand across mixed ICE and electric vehicle populations. Traditional independent distributors are losing shelf space to captive parts programs and direct manufacturer relationships. North American commercial vehicle operators are most visible in this shift, with large logistics providers negotiating multi-year supply agreements that bundle seal replacement with predictive maintenance data services.
Automotive Oil Seals Market Segmentation
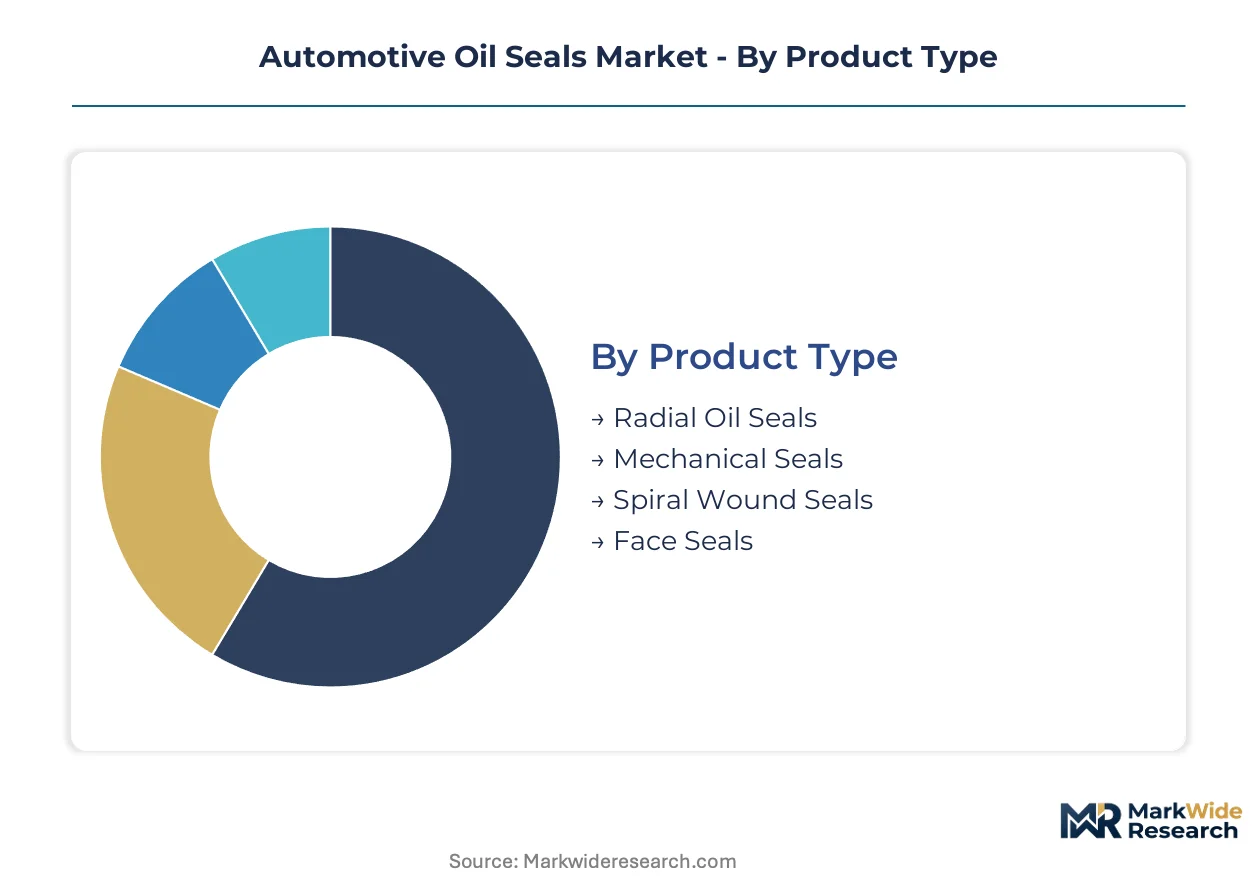
Seal specification authority fragments across product architectures, material chemistries, and procurement channels. Each segmentation dimension reveals distinct competitive moats and requalification barriers that determine supplier retention.
Product Type:
Powertrain architecture diversity spans from legacy wet-sump engines to integrated e-axle modules, each demanding specialized sealing geometries and pressure-handling capabilities.
- Radial Oil Seals:These annular elastomer-metal bonded devices retain pressurized lubricants against rotating shafts in crankcase and transmission interfaces. Demand concentrates in Germany's Stuttgart supplier corridor where precision machining tolerances for integrated e-axle modules are redefining lip design specifications. REACH F-Gas Regulation restrictions are forcing simultaneous validation of hydrogenated nitrile alternatives alongside legacy fluorocarbon grades.
- Mechanical Seals:Multi-component assemblies employing rotating and stationary faces achieve zero-leakage performance in coolant pumps and auxiliary systems. China's Yangtze River Delta automotive cluster is absorbing the highest volume as domestic OEMs localize Tier-1 supply relationships. Solid-state bearing integration in select auxiliary applications is displacing traditional mechanical seal specifications.
- Spiral Wound Seals:Metal-wound configurations with elastomer filler strips withstand extreme thermal cycling in turbocharger boost interfaces.
- Face Seals:Axial-contact designs seal perpendicular surfaces in limited-access gearbox compartments and differential housings.
Established volume favors radial oil seals; emerging adoption favors spiral wound configurations.
Material:
Compound selection determines thermal ceiling, chemical resistance, and replacement interval economics across powertrain duty cycles.
- Rubber:Nitrile and hydrogenated nitrile formulations dominate cost-sensitive high-volume applications where moderate thermal limits align with service intervals. China's MIIT vehicle certification protocols are accelerating domestic elastomer substitution programs to reduce fluorocarbon import dependency.
- Polyacrylate:This specialty elastomer withstands synthetic lubricant attack in power steering systems where extended drain intervals command premium positioning. Germany's powertrain engineering centers are specifying polyacrylate grades most aggressively as REACH phthalate restrictions eliminate legacy plasticizer systems.
- Polyurethane:Abrasion-resistant compounds serve axle and driveline interfaces exposed to contamination and shock loading.
- Metal:Case materials and winding substrates provide structural rigidity and thermal conductivity in high-pressure turbocharger applications.
Cost tier separation places rubber compounds in standard-duty platforms; specification authority concentrates in polyacrylate for synthetic lubricant environments.
Application:
Thermal load intensity and lubricant chemistry vary dramatically across powertrain subsystems, fragmenting compound qualification pathways.
- Engine Components:Crankshaft and camshaft seals face the most severe thermal cycling combined with crankcase pressure pulsation. China's NMPA vehicle safety standards mandate durability testing that favors fluorocarbon validation programs among Yangtze River Delta suppliers.
- Transmission Systems:Multi-speed automatic and dual-clutch architectures require seals that maintain lip contact across wide RPM ranges and fluid viscosity swings. Japan's transmission manufacturers are driving compact seal geometry specifications for Asian vehicle architectures.
- Power Steering:Rack-and-pinion and electric assist systems demand chemical resistance to phosphate ester and synthetic hydrocarbon fluids.
- Axles:Differential and hub seals contend with hypoid gear oil chemistry and external contamination from road debris.
Thermal stress concentration favors engine component specifications; electric vehicle transition favors transmission system redesign cycles.
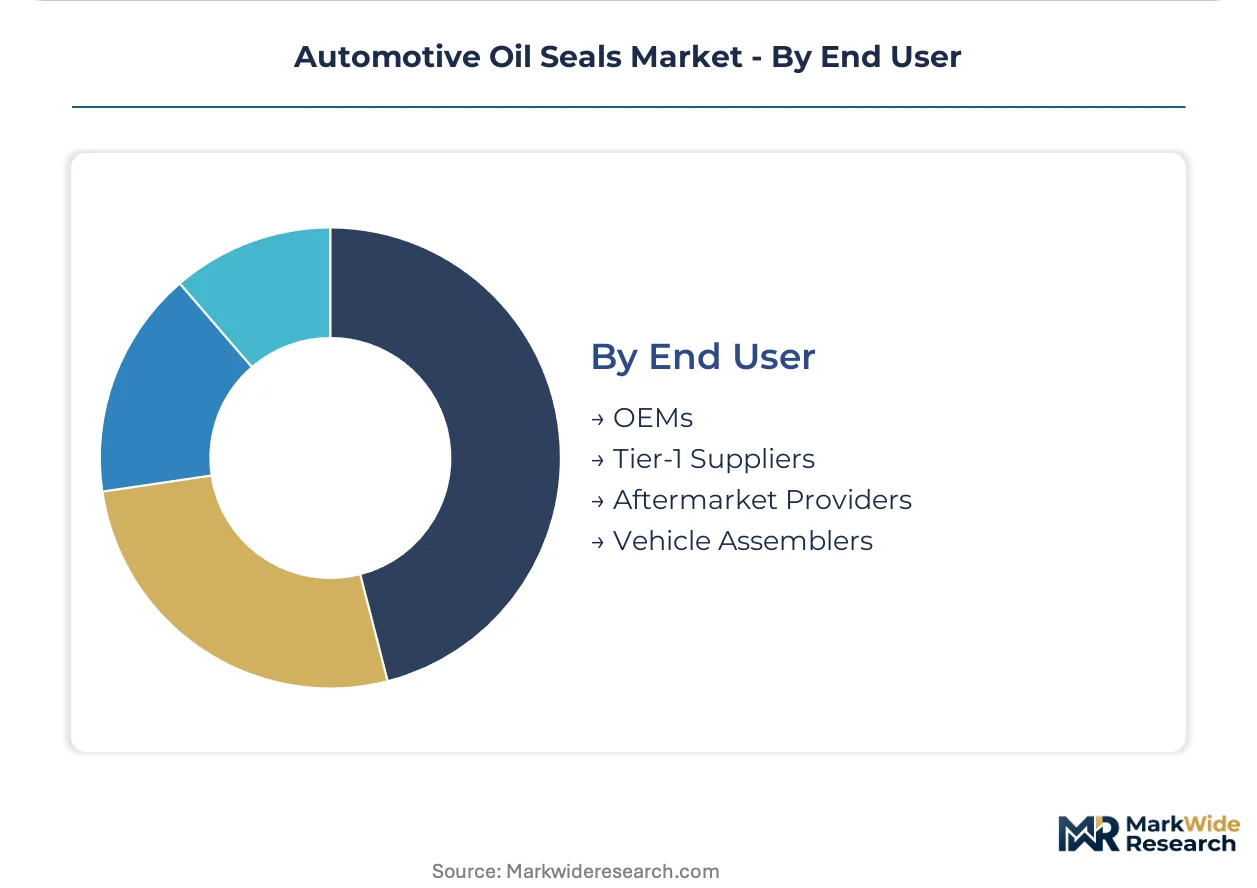
End User:
Procurement authority and technical specification control distribute unevenly across the automotive value chain, determining margin capture and relationship durability.
- OEMs:Vehicle brand owners retain final specification approval and captive parts program control for warranty coverage. North American commercial fleet operators are consolidating procurement through direct manufacturer relationships that bypass traditional distribution tiers.
- Tier-1 Suppliers:Integrated module manufacturers aggregate seal demand within transmission, axle, and thermal management assemblies. Freudenberg Sealing Technologies leverages backward integration into rubber compounding to secure specification authority with these customers.
- Aftermarket Providers:Independent distributors and jobbers serve vehicle service intervals outside warranty periods.
- Vehicle Assemblers:Contract manufacturing partners and joint venture production facilities execute final powertrain installation.
Specification control favors OEMs; margin compression concentrates in aftermarket providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across geographies. Fleet operators in North America negotiate multi-year supply agreements that compress margins, while China's state-backed OEMs prioritize qualification speed over unit cost, creating tiered procurement behavior.
China
Yangtze River Delta assemblers drive fluorocarbon seal validation for integrated e-axle modules. MIIT vehicle certification protocols mandate thermal cycling durability testing that accelerates domestic elastomer substitution programs. Shanghai and Suzhou supplier corridors concentrate Tier-1 compounding investments serving BYD and NIO production ramps.
Germany
Stuttgart's precision engineering ecosystem redefines lip design tolerances for next-generation transmission architectures. REACH F-Gas Regulation restrictions force simultaneous validation of hydrogenated nitrile alternatives alongside legacy fluorocarbon grades. Munich engineering centers accelerate domestic elastomer substitution to maintain specification authority with BMW and Mercedes-Benz powertrain divisions.
United States
Commercial fleet operators consolidate procurement through platform-based lifecycle management systems that bypass traditional distribution tiers. EPA fuel vapor recovery requirements impose material composition limits on seal elastomers exposed to evaporative emission control systems. Michigan and Ohio manufacturing corridors anchor bearing-seal integration programs serving Detroit Three thermal management specifications.
India
Chennai and Pune EV assembly clusters attract fluorocarbon compounding investments under the PLI scheme for auto components. BIS standards alignment with global thermal cycling protocols accelerates qualification timelines for export-oriented suppliers. Tamil Nadu's supplier parks concentrate seal manufacturing capacity serving Hyundai-Kia and Tata Motors electric platforms.
Japan
Transmission manufacturers in Aichi and Shizuoka prefectures specify compact seal geometries for Asian vehicle architectures. METI industrial standards coordinate domestic elastomer development with automotive OEM roadmaps. Nagoya supplier networks specialize in high-volume radial seal production for Toyota and Honda hybrid powertrain programs.
Automotive Oil Seals Market Competitive Environment
Vertically integrated compounders and bearing-integrated specialists split the market between material-control and specification-lock strategies. The vendor base concentrates around three archetypes: rubber compounders with backward integration into raw material pathways, bearing manufacturers leveraging seal integration for design authority, and focused seal specialists optimizing compact geometries for regional transmission architectures. Competitive moves center on captive supply chain construction and predictive maintenance data service bundling.
Among the vertically integrated compounders, Freudenberg Sealing Technologies exemplifies the material-control archetype through its rubber compounding network. SKF Group occupies the bearing-integration position, while NOK Corporation represents the compact-geometry specialization for Asian market requirements. These three anchors illustrate the strategic divergence between upstream raw material control, downstream specification authority, and regional application focus.
| Leading Market Players |
|---|
| Freudenberg Sealing Technologies |
| Parker Hannifin |
| NOK Corporation |
| Hutchinson |
| SKF Group |
| ElringKlinger AG |
| Dana |
| Trelleborg |
| Federal Mogul |
| Others |
Value Chain & Pricing Dynamics
Fluorocarbon feedstock concentration in Asian chemical processing corridors determines both tier spreads between nitrile and fluorocarbon grades and the geographic shape of compounding investments. OEM captive parts programs and REACH phthalate compliance costs feed back into supplier decisions on backward integration versus outsourcing.
Pricing Analysis
Aftermarket service revenue from extended replacement intervals drives lifetime value capture for seal manufacturers. Three-tier pricing structure across premium fluorocarbon, standard hydrogenated nitrile, and economy nitrile rubber levels stratifies by thermal performance certification and synthetic lubricant compatibility. Cost compression in the economy tier intensifies because China's MIIT domestic substitution mandates accelerate local nitrile production. Fleet operators in North America exhibit highest price sensitivity through consolidated multi-year procurement platforms, while German OEMs prioritize qualification speed over unit cost.
Supply Chain Analysis
Export-control regimes on fluorinated compound precursors limit technology flows from European and Japanese compounders to emerging Asian facilities. Raw material supply concentrates in China for nitrile rubber feedstocks, Germany for specialty fluorocarbon elastomers, and Japan for hydrogenated nitrile grades. Component dependencies span metal case stamping from German precision tooling suppliers, elastomer bonding adhesives from South Korean chemical firms, and PTFE filler materials from Chinese processors. Single-source vulnerability in fluorocarbon precursor supply exposes seal manufacturers to input rationing during contract renegotiations. Distribution runs through Tier-1 module assemblers who aggregate seal demand within integrated e-axle and transmission assemblies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where battery module sealing and cooling plate gasketing specifications are converging, forcing interoperability between thermal management and powertrain engineering teams.
For Market Incumbents: Insulate specification authority by accelerating in-house fluorocarbon compounding capability before talent scarcity concentrates expertise further at European and Japanese specialists. Secure backward integration into rubber formulation to control raw material pathways against REACH F-Gas reformulation mandates. Defend against solid-state bearing displacement by embedding predictive maintenance data services that lock in replacement revenue.
For New Entrants and Emerging Players: India's PLI-subsidized auto component corridors around Chennai and Pune represent the most penetrable entry point for fluorocarbon compounding investments serving Hyundai-Kia and Tata Motors electric platforms. Direct-to-fleet digital procurement channels for North American commercial vehicle operators offer bypass opportunities around entrenched distribution tiers. A thermal interface materials convergence play—merging battery sealing with cooling plate expertise—provides the clearest go-to-market angle against established seal specialists.
For Investors and Strategic Acquirers: REACH F-Gas Regulation restrictions on perfluorinated compounds reshape the acquisition landscape toward hydrogenated nitrile and terpolymer alternative developers. Long-term viability favors compounders with dual-track validation capabilities spanning legacy fluorocarbon approvals and next-generation elastomer substitution programs. Watch for Tier-1 supplier requalification timelines as the signal indicating which formulation platforms will capture specification authority in integrated e-axle modules.
| Strategic Initiative | Industry Significance |
|---|---|
| Fluorocarbon Compounding Capacity Expansion | Captures specification authority with Yangtze River Delta assemblers qualifying integrated e-axle seals. |
| Hydrogenated Nitrile Substitution Program | Maintains European market access under REACH F-Gas restrictions while serving BMW and Mercedes-Benz powertrain divisions. |
| Predictive Maintenance Data Partnership | Locks in aftermarket revenue from North American fleet operators consolidating procurement through lifecycle platforms. |
| Thermal Interface Materials Convergence | Cross-sells battery module sealing into cooling plate gasketing for emerging EV thermal management architectures. |
| Direct-to-Fleet Digital Channel Buildout | Bypasses independent distributor margin compression by capturing commercial vehicle operator procurement directly. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distribution heads, and fluorocarbon compounding technical leads. Secondary validation drew from vehicle production databases, IHS Markit registration data, MIIT certification filings, and REACH substance restriction notifications. Bottom-up seal demand modeling triangulated against top-down powertrain production forecasts to reconcile unit volume projections.
Calibration against historical thermal cycling test outcomes and qualification timeline records anchored growth trajectory assumptions across the projection horizon. Segmentation dimensions spanned propulsion architecture, seal product type, material chemistry grade, OEM tier positioning, and regional production cluster. CAGRs were derived from elasticity-adjusted adoption curves for electric vehicle thermal management sealing versus declining internal combustion wet-sump applications. Forecast inputs included NMPA durability mandate compliance costs and synthetic lubricant chemistry evolution timelines.
Practitioners should monitor fluorocarbon precursor supply rationing events and domestic elastomer substitution program acceleration for early signals of input cost volatility. Forecasts reflect assumptions about regulatory divergence persistence and EV platform standardization rates. Material shifts in solid-state bearing adoption or REACH F-Gas enforcement stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Center and Drag Link Market
Automotive Parts
Europe Automotive Parts Zinc Die Casting Market
Automotive Parts
Latin America Electric Power Steering Market
Automotive Parts
France Automotive Parts Aluminium Die Casting Market
Automotive Parts
Rammer Market
Automotive Parts
Global Automotive Cooler Market
Automotive Parts
Passenger Car Wiper Blade Market
Automotive Parts
Turkey Passenger Vehicles Lubricants Market
Automotive Parts
North America Automotive Parts Magnesium Die Casting Market
Automotive Parts
Apron Bus Market
Automotive Parts
Wiper Systems Market
Automotive Parts
Global Automotive Ignition Market
Automotive Parts
Air Filter Cartridges Market
Automotive Parts
Russia Automotive Actuators Market
Automotive Parts
Engine Fogging Oil Market
Automotive Parts
Aluminum Parts Gravity Die Casting Market