
 Automotive Forging Market | 2026-2036
Automotive Forging Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Forging Market Analysis
Asset-light leasing arrangements for forging presses and shared-die programs is tilting competitive dynamics toward mid-tier suppliers who previously faced capital barriers. Bharat Forge Limited leverages its integrated steel-to-component pipeline to sustain cost leadership in crankshaft supply. Thyssenkrupp AG anchors European demand through its captive heat-treatment and machining network. Precision Castparts Corp. differentiates via aerospace-grade process discipline applied to automotive turbine wheels and structural forgings.
Automotive forging produces high-strength metal components through compressive deformation at temperatures typically exceeding 1,000 degrees Celsius, yielding grain structures that withstand cyclic fatigue in powertrain and chassis assemblies. Steel dominates material selection for crankshafts and gears where tensile requirements exceed 800 MPa, while aluminum gains share in electric vehicle knuckles seeking unsprung mass reduction. Passenger vehicles absorb the majority of forged volume, though electric vehicle applications represent the fastest-expanding margin pool as OEMs redesign subframes around battery packaging constraints.
EPA tailpipe rules and Euro 7 emissions limits compel automakers to source lighter forged substitutes for cast iron, directly shaping procurement specifications at American Axle & Manufacturing and NTN Corporation. NHTSA crashworthiness standards elevate forging penetration in steering columns and suspension knuckles where failure modes must remain ductile. Stakeholders must monitor how China's MIIT new-energy vehicle subsidy thresholds and India's BIS automotive steel grades recalibrate export competitiveness for forge shops serving multinational OEM platforms.
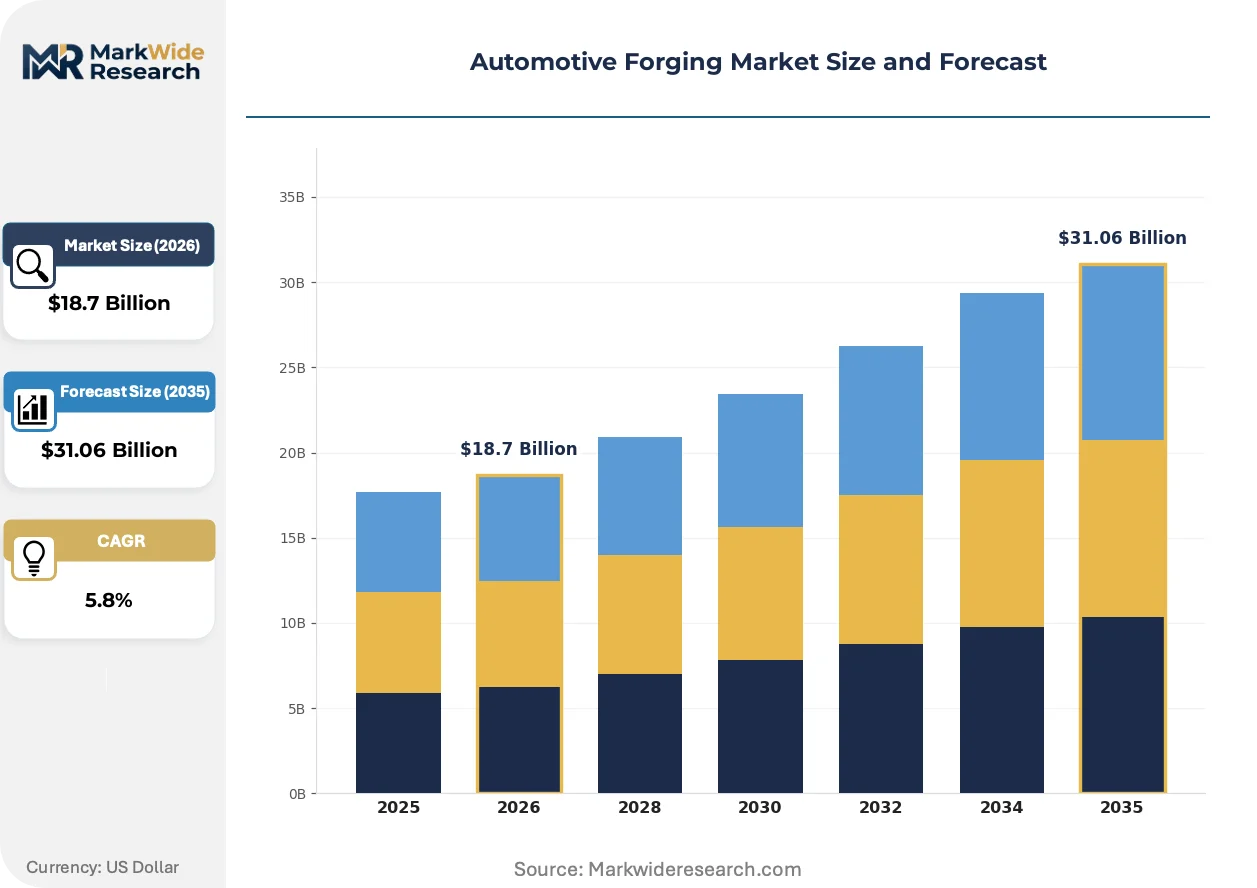
Market Dynamics
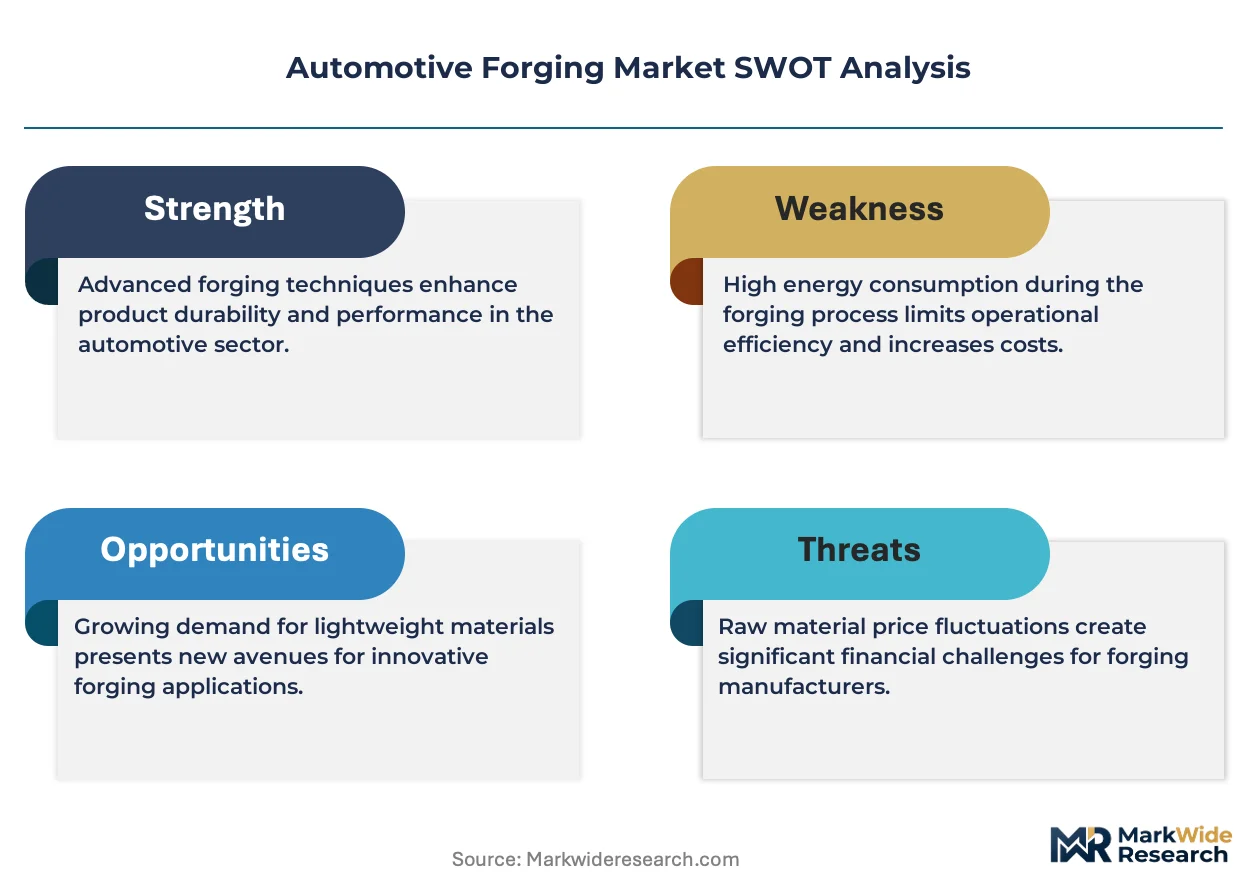
Electric vehicle platform architectures are forcing a fundamental redesign of forged component specifications, as battery packaging constraints demand lighter unsprung mass and redesigned subframe geometries that legacy steel forging processes cannot economically deliver.
Growth Catalysts
- EPA Tier 3 and Euro 7 emissions frameworks:Tailpipe limits compel automakers to substitute forged aluminum for cast iron in powertrain and chassis applications, directly expanding addressable component volume.
- Closed-die precision forging:Advances in die design and thermal management enable net-shape production of complex electric vehicle knuckles, reducing machining waste and cycle times.
- Germany, Japan, and the United States:Dense clusters of tier-1 suppliers and captive heat-treatment infrastructure concentrate procurement decisions and accelerate specification standardization across OEM platforms.
Market Restraints
- Scrap steel and primary aluminum price volatility:Input cost swings compress forging margins and complicate long-term contract pricing with automotive OEMs.
- Supply concentration in German and Japanese equipment builders:Dependence on a limited supplier base for large mechanical and hydraulic forging presses creates capex planning risk and extended lead times.
- Titanium and carbon fiber reinforced polymer substitution:High-performance electric vehicle segments increasingly specify non-ferrous materials for extreme weight targets beyond aluminum forging capability.
Strategic Opportunities
- India's PLI scheme for automotive components:Production-linked incentives attract forging capacity expansion to serve export demand from European and Japanese OEMs.
- Integrated steel-to-component pipelines:Captive melt shops and rolling mills enable mid-tier suppliers to control alloy chemistry and reduce purchased input exposure.
- Shared-die programs and press leasing:Asset-light arrangements lower capital barriers for regional forge shops seeking entry into electric vehicle supply chains.
Industry Challenges
- Die design and thermal simulation expertise:Shortage of engineers proficient in finite element modeling for multi-stage forging sequences limits process optimization and defect reduction.
- IATF 16949 and OEM-specific quality certifications:Protracted audit timelines and customer-specific addenda delay new supplier qualification for critical safety components.
- Legacy ERP and MES integration:Forge shops struggle to connect shop-floor data collection with enterprise planning systems for real-time die wear tracking and predictive maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Forging Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Knuckles, Steering Columns, Crankshafts, Gears Application: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Performance Vehicles Material: Steel, Aluminum, Titanium, Alloys Manufacturing Stage: Initial Production, Mass Production, Custom Production, Post-Processing |
| Companies Covered | Aichi Steel Corporation, CIE Automotive, Bharat Forge Limited, Scot Forge, NTN Corporation, Thyssenkrupp AG, Precision Castparts Corp., Zetwerk, American Axle & Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Forging Market Emerging Trajectories
Isothermal and near-isothermal forging processes are penetrating automotive applications previously reserved for aerospace, as thermal uniformity requirements tighten for complex aluminum structural components.
Isothermal forging maintains die and workpiece at uniform elevated temperatures throughout deformation, eliminating thermal gradients that cause cracking in thin-walled aluminum sections. Tier-1 suppliers serving premium electric vehicle platforms are adopting these cells for control arm and knuckle production. Conventional hammer and mechanical press forging is rendering obsolete for components requiring wall thickness below four millimeters or draft angles under three degrees.
REACH authorization requirements for hexavalent chromium surface treatments are compelling forge shops to convert to trivalent chrome and zirconium-based passivation chemistries. The substitution increases pretreatment line capital cost but eliminates downstream liability for OEMs exporting into European markets. Heat-treated steel forgings for chassis applications face the most acute compliance pressure, with German and French suppliers already completing line conversions.
Automotive OEM procurement organizations are consolidating supplier panels and mandating direct electronic data interchange for die wear metrics and lot traceability. Tier-1 forging suppliers must now embed sensors and connectivity modules into dies and presses to maintain preferred supplier status. This transformation is most advanced in Japanese keiretsu supply structures, where real-time production data sharing has become a contractual requirement for new platform awards.
Automotive Forging Market Segmentation
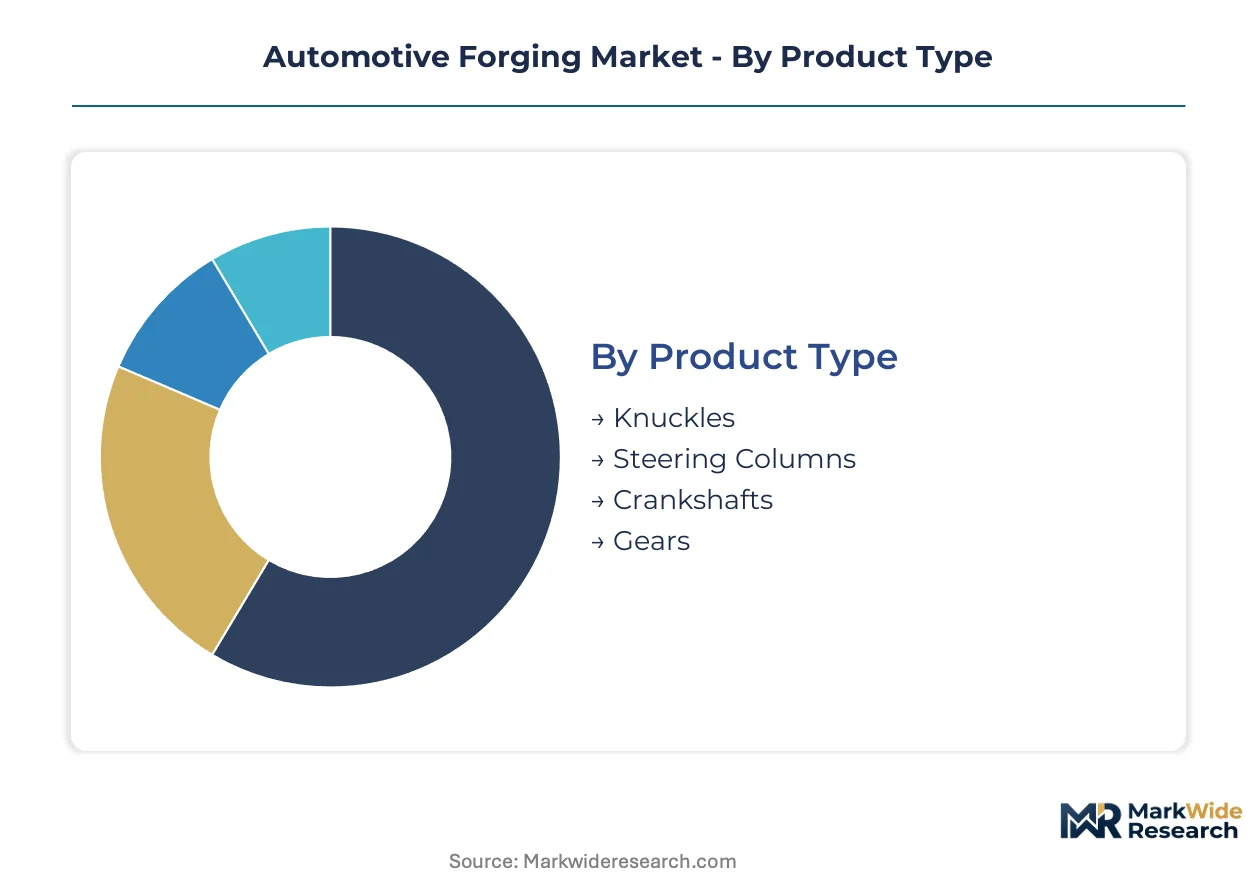
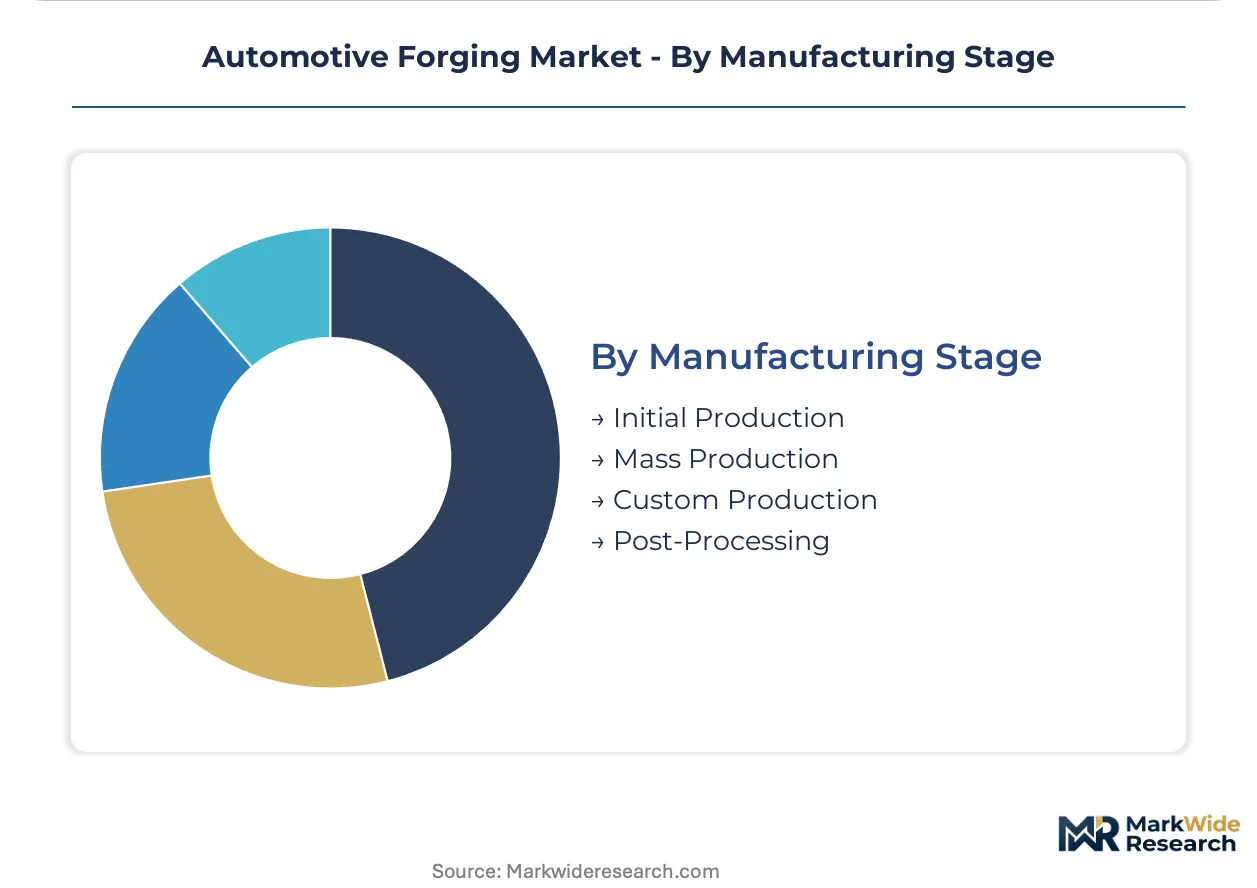
Automotive forging segmentation reveals how material specifications and manufacturing stages align with divergent OEM procurement strategies. Component geometry, thermal processing requirements, and platform-specific load cases determine supplier qualification pathways across passenger, commercial, and electric vehicle programs.
Product Type:
Cost tier separation across forged automotive components reflects machining intensity, die complexity, and safety-critical certification requirements.
- Crankshafts:These rotating assemblies demand micro-alloyed steel grades with tensile strength exceeding 800 MPa and surface induction hardening for bearing journals. Procurement concentrates at Bharat Forge and Thyssenkrupp AG facilities serving European and Japanese OEM powertrain platforms where fatigue resistance under cyclic torsional loading is non-negotiable.
- Knuckles:Suspension corner modules in aluminum alloys enable unsprung mass reduction critical to electric vehicle range targets. Detroit Three and German premium OEMs now specify closed-die forged 6061-T6 variants with integrated ball joint bores, displacing multi-piece welded fabrications.
- Steering Columns:Tubular steel forgings with collapsible deformation zones meet NHTSA crashworthiness mandates for occupant protection.
- Gears:Net-shape forged ring gears and pinions reduce machining stock in high-volume transmission programs.
Crankshafts command the established base. The steepest expansion runs through knuckles.
Application:
Application segmentation tracks how platform electrification and regulatory tailpipe limits are redistributing forging demand across vehicle categories.
- Electric Vehicles:Battery packaging constraints and range optimization drive specification of hollow aluminum subframe members and integrated motor mounts. Tesla, BYD, and Volkswagen Group platforms now source forged structural nodes previously cast or stamped, with die thermal management becoming the critical process control point.
- Passenger Vehicles:High-volume internal combustion programs sustain demand for steel crankshafts, connecting rods, and transmission gears. Japanese keiretsu supply structures maintain preferred supplier panels with captive heat-treatment and just-in-sequence delivery to assembly plants in Toyota City and Maryville, Tennessee.
- Commercial Vehicles:Heavy-duty diesel and emerging hydrogen fuel cell powertrains require forged camshafts and axle shafts with enhanced section modulus.
- Performance Vehicles:Titanium connecting rods and inconel exhaust valves serve motorsport-derived road car programs with extreme specific power targets.
Passenger vehicles anchor current volume. Electric vehicle applications are expanding most quickly.
Material:
Material selection balances specific strength, formability limits, and scrap value recovery in closed-loop manufacturing systems.
- Steel:Micro-alloyed and boron grades dominate powertrain forgings where cost-per-unit-strength metrics favor ferrous metallurgy. German and Japanese OEMs specify vacuum-degassed billets with sulfur below 0.015% for crankshaft fatigue life consistency.
- Aluminum:6xxx and 7xxx series alloys penetrate chassis and structural applications where density reduction offsets raw material premium. EPA Tier 3 compliance pressure accelerates substitution for cast iron in steering knuckles and control arms.
- Titanium:Ti-6Al-4V forgings serve connecting rod and valve applications in high-revving performance engines.
- Alloys:Nickel-based superalloys and magnesium variants address niche thermal and electromagnetic shielding requirements.
Steel retains the volume base. Aluminum alloys are gaining share fastest.
Manufacturing Stage:
Manufacturing stage segmentation distinguishes between prototype validation, scale production, and aftermarket service requirements.
- Mass Production:Automated closed-die forging cells with 10,000-ton hydraulic presses and robotic die lubrication achieve cycle times below 12 seconds for high-volume knuckle programs. German equipment builders supply the majority of press installations to tier-1 suppliers in Stuttgart, Aichi Prefecture, and Detroit.
- Initial Production:Soft-tooling and rapid die modification capabilities support platform launch phases where design changes remain probable. Suppliers with integrated machining and CMM inspection reduce iteration lead times for OEM validation builds.
- Custom Production:Small-batch forging for motorsport, aftermarket performance, and heritage vehicle restoration programs.
- Post-Processing:Shot peening, thermal spray coating, and precision machining operations that convert raw forgings to net-shape components.
Mass production commands the established base. The steepest expansion runs through initial production as electric vehicle platform launches accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive forging procurement concentrates at OEM engineering centers and tier-1 supplier clusters where heat-treatment infrastructure and die-making capabilities co-locate. Dense supplier networks in Germany, Japan, and the United States shape specification standards that cascade to secondary sourcing regions.
Germany
Stuttgart and Munich anchor European demand for precision steel crankshafts and aluminum chassis components serving BMW, Mercedes-Benz, and Volkswagen Group platforms. Euro 7 emissions limits under ECHA oversight compel forged aluminum substitution for cast iron steering knuckles. The Baden-Württemberg and Bavaria industrial corridors host captive heat-treatment networks that compress supplier qualification timelines.
Japan
Aichi Prefecture and Toyota City sustain keiretsu supply structures where just-in-sequence forging delivery feeds final assembly plants. METI industrial standards govern micro-alloyed steel specifications for powertrain durability. Chubu region suppliers cluster around Nagoya with integrated die-making and robotic forging cell capabilities that serve Toyota, Honda, and Nissan platforms.
United States
Detroit Three procurement organizations in Michigan and Ohio specify closed-die aluminum forgings for electric vehicle subframe redesigns. EPA Tier 3 tailpipe rules accelerate lightweighting mandates that reshape supplier panels at American Axle & Manufacturing. The Southeast manufacturing corridor from Tennessee to Alabama attracts forging capacity to serve transplant OEM assembly plants.
India
Maharashtra and Tamil Nadu forge clusters leverage PLI scheme incentives to capture export demand from European and Japanese OEMs. BIS automotive steel grades recalibrate alloy chemistry requirements for crankshaft suppliers serving multinational platforms. Pune and Chennai industrial zones concentrate mid-tier suppliers adopting shared-die programs to lower capital barriers.
China
MIIT new-energy vehicle subsidy thresholds reshape procurement specifications for battery electric platform structural forgings. Yangtze River Delta suppliers in Shanghai and Jiangsu Province serve Tesla, BYD, and Volkswagen Group joint ventures with aluminum knuckle and motor mount production. Local equipment builders supply mechanical forging presses that reduce dependence on German and Japanese machinery imports.
Automotive Forging Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered supply strata where captive heat-treatment networks confer qualification advantages. The vendor base organizes around three archetypes: integrated steel-to-component pipelines, precision aerospace-grade disciplinarians, and asset-light regional specialists leveraging shared-die programs. Consolidation pressure runs through mid-tier suppliers seeking scale to meet OEM electronic data interchange mandates. Dominant competitive moves include backward integration into captive melt shops and strategic partnerships for die design expertise.
Among integrated pipeline operators, Bharat Forge Limited and Thyssenkrupp AG exemplify cost-control architectures that span alloy chemistry to final machining. Precision Castparts Corp. occupies a position translating aerospace process discipline into automotive turbine wheel and structural forging applications. These three entities anchor distinct competitive vectors—volume-scale ferrous powertrain, European captive network density, and transferred aerospace-grade thermal management—without overlapping segment positioning.
| Leading Market Players |
|---|
| Aichi Steel Corporation |
| CIE Automotive |
| Bharat Forge Limited |
| Scot Forge |
| NTN Corporation |
| Thyssenkrupp AG |
| Precision Castparts Corp. |
| Zetwerk |
| American Axle & Manufacturing |
| Others |
Supply Flow & Price Mechanics
Overcapacity in European forging press installations is compressing utilization rates below break-even thresholds, forcing German and Japanese equipment suppliers to extend payment terms and accept asset-light leasing structures that transfer pricing power downstream to OEM procurement organizations.
Pricing Analysis
Cost-plus contracts indexed to LME aluminum and scrap steel benchmarks dominate long-term supply agreements between tier-1 forgers and Detroit Three OEMs. Price differentiation separates aerospace-grade thermal management certifications from standard automotive IATF 16949 tiers, with premium cells commanding 15-20 point spreads. Cost compression in aluminum knuckle programs is intensifying because Chinese equipment builders are undercutting German press pricing by 30 points. Fleet procurement officers at commercial vehicle OEMs exhibit highest price sensitivity, while German premium EV platforms prioritize die thermal uniformity over unit cost.
Supply Chain Analysis
Export control regimes restricting large hydraulic forging press technology from Germany and Japan to Chinese state-owned enterprises are fragmenting equipment sourcing channels and extending lead times for Yangtze River Delta suppliers. Geographic supply concentration centers on Germany, Japan, and the United States for precision die-making and heat-treatment infrastructure. Raw material flows draw from Russian vacuum-degassed billet suppliers, Australian primary aluminum smelters, and Chinese rare earth alloying agents. Single-source vulnerability runs through German equipment builders Schuler and Lasco for 10,000-ton press installations. Distribution runs through captive just-in-sequence networks feeding Toyota City, Stuttgart, and Detroit assembly corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive forging sits in early-cycle expansion as electric vehicle platform launches accelerate specification of hollow aluminum subframe members previously cast or stamped, with die thermal management becoming the critical qualification threshold for new supplier entry.
For Market Incumbents: Build captive heat-treatment network density as the primary moat against mid-tier suppliers adopting shared-die programs. Thyssenkrupp AG and Bharat Forge Limited should deepen backward integration into vacuum-degassed billet supply to offset scrap steel volatility. IATF 16949 certification investments with OEM-specific addenda create switching costs that titanium connecting rod substitutes cannot easily replicate. For New Entrants and Emerging Players: India's PLI scheme corridors in Maharashtra and Tamil Nadu represent the most penetrable entry point for regional forge shops seeking export qualification with European and Japanese OEMs. Shared-die programs with German equipment lessors lower capital barriers for electric vehicle knuckle production. Go-to-market execution should target tier-2 supplier status on Volkswagen Group MEB platform programs before pursuing Detroit Three validation. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across asset-light regional specialists leveraging press leasing and shared-die arrangements, compressing returns for traditional integrated pipeline operators. Long-term viability over a 5-10 year window favors acquisition targets with captive melt shops and rolling mills controlling alloy chemistry. The signal to watch is MIIT subsidy threshold adjustments that would recalibrate Chinese domestic demand for aluminum structural forgings and redirect export volume toward European and Japanese OEM platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vacuum-Degassed Billet Supply | Bharat Forge Limited and Thyssenkrupp AG control alloy chemistry and reduce scrap steel price exposure. |
| Isothermal Forging Cell Deployment | Tier-1 suppliers serving Tesla and Volkswagen Group platforms achieve net-shape production of thin-walled aluminum knuckles. |
| Shared-Die Program Expansion | Mid-tier Indian suppliers in Pune and Chennai lower capital barriers for electric vehicle supply chain entry. |
| Trivalent Chrome Conversion | German and French suppliers eliminate downstream REACH liability for OEMs exporting into European markets. |
| Real-Time Die Wear Sensor Integration | Japanese keiretsu suppliers meet contractual EDI mandates for lot traceability and predictive maintenance. |
Methodological Framework
Operator-level perspectives from tier-1 supplier procurement directors, OEM platform engineers, heat-treatment facility managers, and German equipment builder sales executives anchored the qualitative base. Secondary validation drew from EPA Tier 3 regulatory filings, ECHA REACH authorization databases, MIIT new-energy vehicle subsidy disclosures, and IHS Markit vehicle production data. Bottom-up volume estimates triangulated against top-down OEM platform content-per-vehicle assumptions across the analysis window.
Scenario-bracketing framed volume and value outputs across conservative, baseline, and accelerated electric vehicle penetration trajectories. Segmentation dimensions modeled included material grade, vehicle propulsion architecture, manufacturing stage, and regional production cluster. CAGRs were derived from slope analysis of year-over-year segment growth rates. Industry-specific forecast inputs incorporated die thermal management adoption curves and Euro 7 compliance timelines for aluminum substitution mandates.
Practitioners should monitor scrap steel and primary aluminum price volatility, MIIT subsidy threshold recalibrations, and German equipment export license approvals for early signals of forecast deviation. Material shifts in titanium and carbon fiber reinforced polymer substitution rates for high-performance electric vehicle segments would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
United States Automotive Glass Market
Automotive Parts
France Automotive Parts Aluminium Die Casting Market
Automotive Parts
Automotive Trailing Arm Bushing Market
Automotive Parts
Automotive Fuel Nozzle Market
Automotive Parts
Automotive Fuel Rail Market
Automotive Parts
Automotive Evaporators and Blowers Market
Automotive Parts
North America Automotive Airfilters Market
Automotive Parts
Italy Automotive Parts Zinc Die Casting Market
Automotive Parts
Qatar Passenger Vehicles Lubricants Market
Automotive Parts
Friction Pads Market
Automotive Parts
United States Ceramic Ball Bearings Market
Automotive Parts
Automotive Piston Pin Market
Automotive Parts
Automotive Performance Parts Market
Automotive Parts
South America Gear Market
Automotive Parts
Malaysia Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Exhaust System Market