
 Hydraulic Lash Adjuster Market | 2026-2036
Hydraulic Lash Adjuster Market Size, Share, and Industry Trends Forecast 2026-2036
Hydraulic Lash Adjuster Market Analysis
China is reshaping regional supply dynamics through expanded precision machining capacity for valvetrain components. Schaeffler Technologies AG & Co. leverages its integrated bearing and adjuster portfolio to dominate European OEM supply chains. Tenneco sustains competitive positioning through exhaust and valvetrain system bundling that reduces customer procurement complexity. Young Shin Automotive anchors East Asian aftermarket distribution with specialized adjuster rebuild kits for legacy engine architectures.
A hydraulic lash adjuster is a self-contained, oil-pressure-actuated device that maintains zero valve clearance in internal combustion engine valvetrains, typically incorporating a plunger, check ball, and precision-machined cylinder bore with tolerances below five microns to ensure consistent hydraulic response across operating temperatures. Its primary purpose is eliminating mechanical valve lash, reducing noise, and enabling variable valve timing systems that improve fuel economy and emissions performance. The hydraulic product type commands the dominant share of OEM specifications due to its self-compensating operation under thermal expansion cycles, while electronic adjusters represent the fastest-growing category as automakers integrate cam phasing with cylinder deactivation strategies. The automotive application segment occupies the core margin pool, though aerospace turbine adjuster demand is accelerating as geared turbofan architectures require more precise blade pitch control mechanisms.
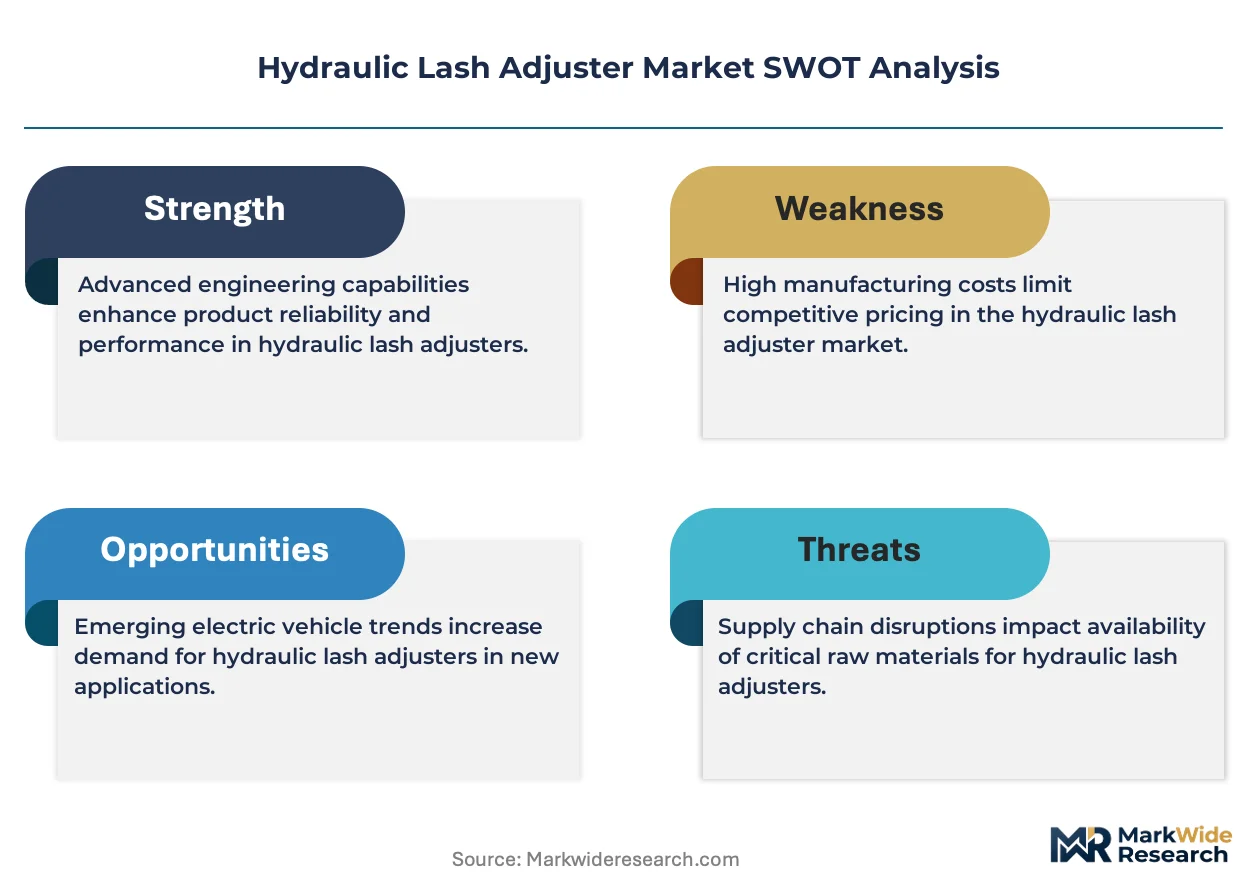
EPA tailpipe standards and Euro 7 emissions frameworks are forcing tighter valve timing tolerances that only precision hydraulic adjusters can sustain across full engine life cycles. China's MIIT fuel consumption regulations and NMPA automotive component certification requirements are creating parallel compliance pathways that favor suppliers with dual-standard testing capabilities. Stakeholders must monitor how solid-state valvetrain architectures and camless engine prototypes displace traditional hydraulic systems in next-generation powertrain portfolios.
Market Dynamics
Precision tolerance requirements under tightening tailpipe emissions frameworks are forcing automakers to upgrade valvetrain architectures, compressing supplier qualification cycles and concentrating procurement among vertically integrated component specialists capable of sub-five-micron machining consistency.
Growth Catalysts
- EPA Tier 3 compliance mandates:Tighter NOx and particulate thresholds compel OEMs to specify hydraulic lash adjusters that maintain zero valve clearance across thermal cycles, eliminating combustion inefficiencies from mechanical lash variation.
- Overhead camshaft engine proliferation:Passenger vehicle powertrain architectures in North American OEM portfolios are standardizing hydraulic self-adjusting mechanisms to support variable valve timing integration.
- Precision machining cluster concentration:German supplier networks serving premium engine platforms leverage captive metrology capabilities to meet Euro 7 valve timing tolerances that conventional mechanical adjusters cannot sustain.
Market Restraints
- Specialized alloy input volatility:Hardened plunger cylinders require vacuum-melted bearing steels subject to aerospace and medical device demand competition, compressing margin stability for mid-tier adjuster manufacturers.
- Single-source check ball supply risk:Ceramic ball fabrication for high-pressure sealing concentrates among Japanese and German precision ceramic houses, creating vulnerability to regional logistics disruptions.
- Solid-state valvetrain substitution trajectory:Electromagnetic and electrohydraulic camless prototypes under development at several powertrain research consortia threaten long-term displacement of hydraulic architectures in next-generation engines.
Strategic Opportunities
- MIIT fuel consumption pathways:China's dual-standard testing requirements favor suppliers with parallel EPA and NMPA certification capabilities, opening procurement access to domestic OEMs previously served by captive joint-venture suppliers.
- Aerospace turbine blade pitch control:Geared turbofan architectures require precision adjusters for variable stator vane actuation, extending addressable market beyond automotive into commercial aviation propulsion systems.
- Aftermarket rebuild kit channel expansion:Legacy overhead cam engines reaching second and third ownership cycles create demand for specialized adjuster refurbishment components distributed through independent service networks.
Industry Challenges
- Sub-micron metrology talent scarcity:Cylindrical grinding and honing operations require operators trained in air-gauge measurement protocols that aging workforce demographics and limited vocational pipeline output cannot replenish.
- Dual-certification timeline compression:Simultaneous EPA and MIIT validation protocols demand parallel durability testing fleets that strain capital allocation for tier-two suppliers without captive proving ground access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydraulic Lash Adjuster Market |
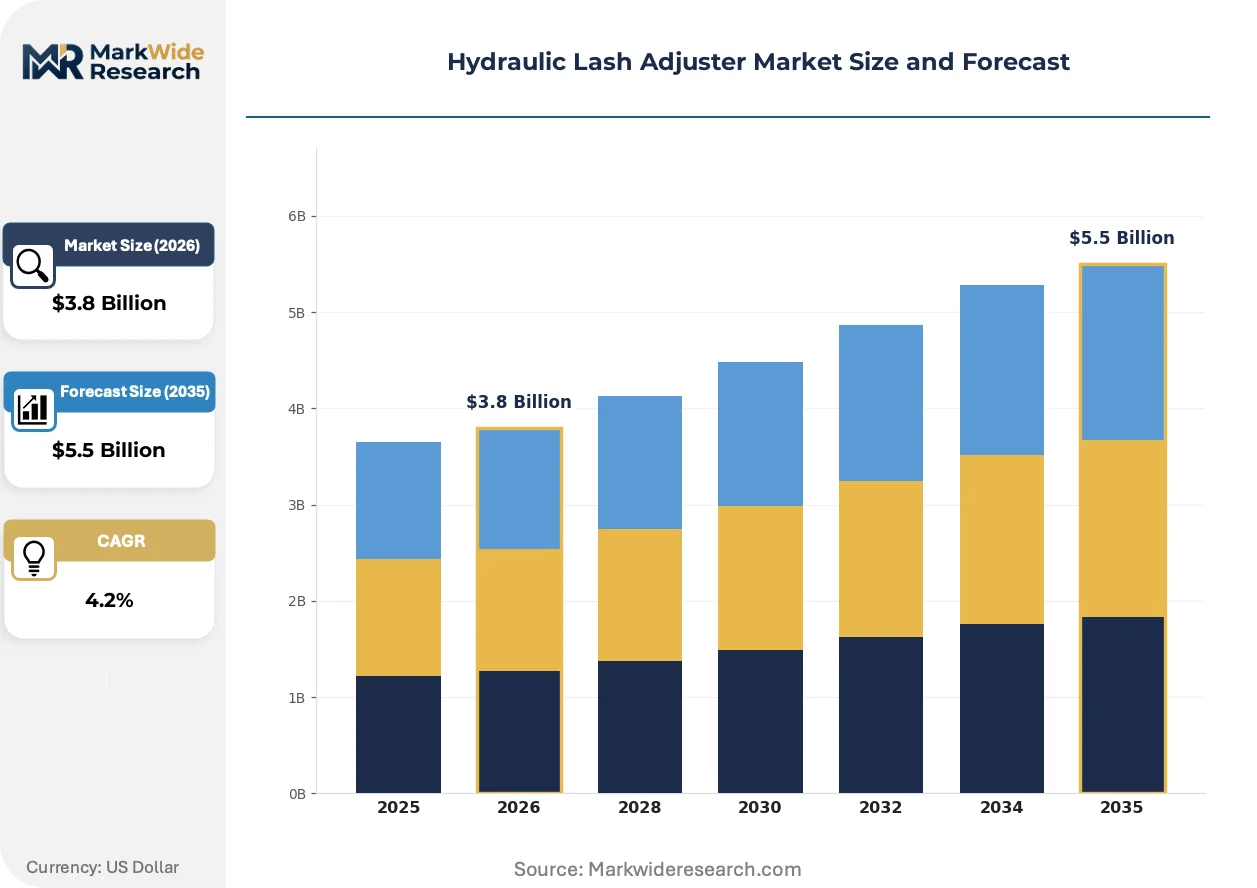
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical, Electronic, Hydraulic, Pneumatic Application: Automotive, Aerospace, Marine, Industrial Equipment Component: Valves, Cylinders, Pumps, Actuators End User: OEMs, Aftermarket Providers, Manufacturing Plants, Engineering Firms |
| Companies Covered | GT Technologies, Tenneco, Schaeffler Technologies AG & Co., Young Shin Automotive, BLE Products, Eaton, LuK GmbH & Co. KG, COMP Cams, OTICS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydraulic Lash Adjuster Market Emerging Trajectories
Valvetrain component manufacturing is converging with precision electronics and closed-loop control systems, compressing the traditional boundary between mechanical actuation and software-defined engine management.
Smart adjuster architectures with embedded pressure and temperature sensors are digitizing condition monitoring capabilities previously requiring external diagnostic equipment. Powertrain engineers at premium OEMs are specifying these intelligent variants for cylinder deactivation strategies that demand real-time lash verification. The technology is digitizing supplier value propositions from commodity hardware toward integrated mechatronic subsystems with recurring calibration service revenue.
REACH substance restrictions on hexavalent chromium plating processes are forcing conversion to trivalent alternatives or physical vapor deposition coatings for plunger wear surfaces. European suppliers face accelerated qualification timelines as surface treatment modifications trigger re-validation of million-cycle durability data. The regulatory pressure concentrates most intensely on German and Czech manufacturing clusters serving domestic OEM valvetrain programs.
Fleet procurement managers are consolidating supplier relationships around bundled exhaust and valvetrain system sourcing that reduces transaction overhead and aligns warranty accountability. This concentration behavior displaces standalone adjuster vendors lacking integrated emissions component portfolios. The pattern manifests most visibly in North American heavy-duty truck engine procurement, where vertical integration between turbocharger, EGR, and valvetrain suppliers determines contract awards.
Hydraulic Lash Adjuster Market Segmentation
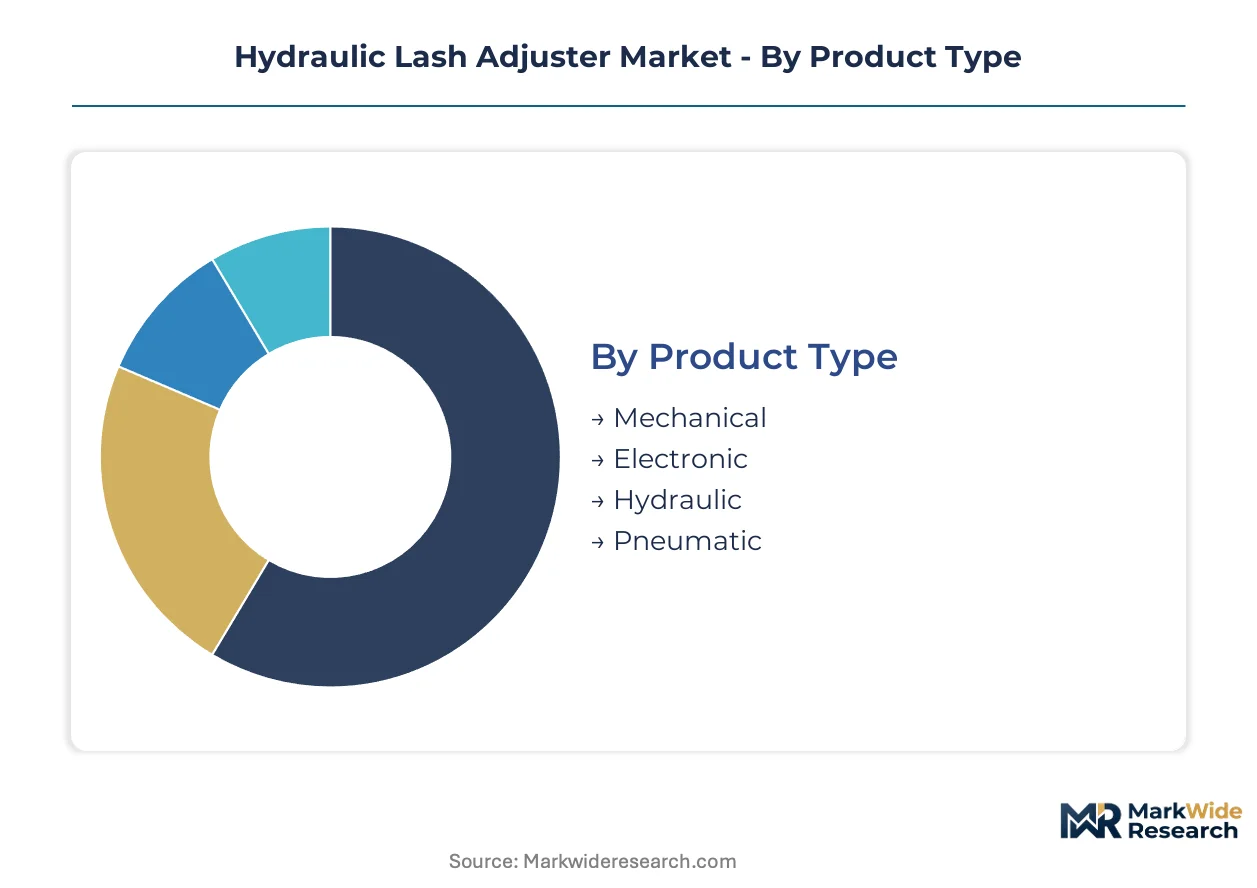
Valvetrain component procurement splits sharply between legacy mechanical architectures and precision electronic systems, with each segment demanding distinct supplier capabilities in machining tolerance, sensor integration, and thermal durability testing.
Product Type:
Mature hydraulic mechanisms dominate current OEM specifications, while emerging electronic variants capture development budgets for next-generation powertrains.
- Hydraulic:Self-contained oil-pressure actuation with plunger-check ball assemblies maintains zero valve clearance across thermal expansion cycles. Passenger vehicle OEMs in Germany and the United States specify these for overhead camshaft engines requiring Euro 7 and EPA Tier 3 compliance. Demand concentrates where variable valve timing integration requires consistent lash compensation through million-cycle durability.
- Electronic:Embedded position sensors and closed-loop control enable real-time lash verification for cylinder deactivation strategies. Powertrain engineers at premium automakers are specifying these intelligent variants, with procurement expanding fastest where mechatronic subsystem bundling reduces warranty accountability fragmentation.
- Mechanical:Solid adjusters with threaded or shim-based clearance setting persist in cost-sensitive small-engine applications and legacy industrial equipment rebuilds.
- Pneumatic:Compressed-air actuation serves specialized high-speed racing valvetrains and prototype camless engine research platforms.
Hydraulic variants handle the majority of throughput; electronic adjusters are expanding most quickly on share.
Application:
Volume concentration tilts toward mass-production automotive, while margin expansion follows aerospace precision requirements.
- Automotive:Passenger cars, light trucks, and heavy-duty commercial vehicles constitute the core demand pool. North American OEM procurement of hydraulic self-adjusting mechanisms is standardizing for variable valve timing integration, while Chinese domestic brands under MIIT fuel consumption regulations drive dual-standard certification requirements.
- Aerospace:Geared turbofan architectures require precision adjusters for variable stator vane actuation in blade pitch control systems. Commercial aviation propulsion programs at airframe manufacturers in France and the United States are qualifying sub-five-micron tolerance components for extended service intervals.
- Marine:Diesel and gas marine engines utilize hardened plunger assemblies for salt-air corrosion resistance in commercial shipping and recreational craft powertrains.
- Industrial Equipment:Stationary generators, compressor engines, and agricultural machinery specify mechanical or hydraulic adjusters based on duty cycle severity and maintenance accessibility constraints.
Automotive applications absorb the dominant share of unit volume; aerospace represents the steepest expansion trajectory on margin contribution.
Component:
Precision machining intensity varies by subsystem, with cylindrical grinding operations concentrating supplier qualification barriers.
- Cylinders:Vacuum-melted bearing steel plunger bores with sub-five-micron tolerances constitute the critical wear surface. German and Czech manufacturing clusters leverage captive metrology capabilities for Euro 7 re-validation timelines.
- Valves:Check ball sealing interfaces determine high-pressure hydraulic response consistency. Ceramic ball fabrication concentrates among Japanese and German precision ceramic houses, creating single-source supply risk.
- Pumps:Internal oil pressure generation mechanisms integrate with engine lubrication systems for self-compensating operation.
- Actuators:Mechanical force transmission elements convert hydraulic pressure to valve stem contact force.
Cylinders command the dominant share of precision machining investment; valves face the tightest supply concentration constraints.
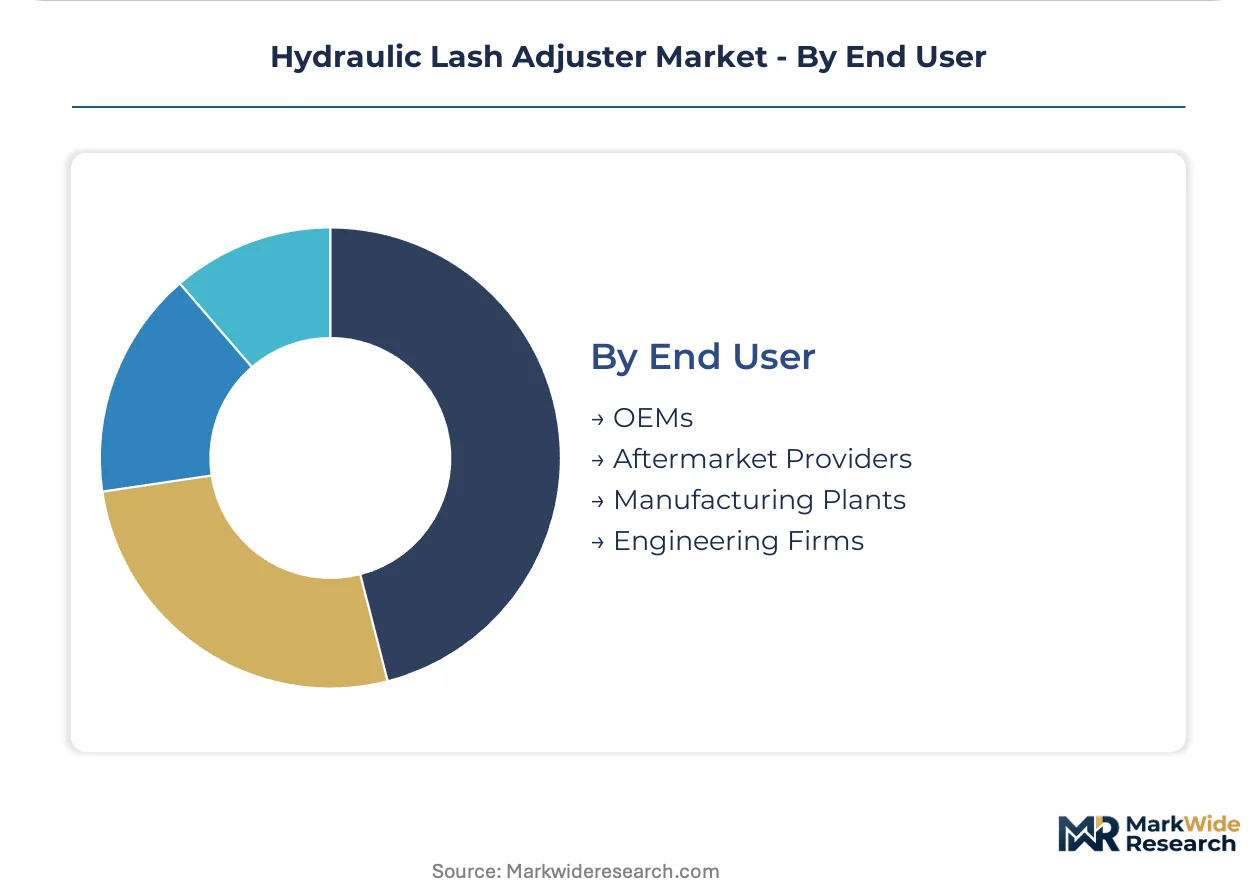
End User:
Procurement authority splits between captive OEM engineering organizations and fragmented aftermarket service networks.
- OEMs:Original equipment manufacturers specify adjuster architectures during powertrain development, locking in supplier relationships through platform life cycles. Bundled exhaust and valvetrain system sourcing is consolidating procurement among vertically integrated component specialists.
- Aftermarket Providers:Independent distributors and specialized rebuild shops serve legacy overhead cam engines reaching second and third ownership cycles. Young Shin Automotive anchors East Asian distribution with adjuster refurbishment kits.
- Manufacturing Plants:Tier-one and tier-two engine assembly facilities procure adjuster subassemblies for line-fit integration.
- Engineering Firms:Powertrain research consortia and prototype development shops source specialized variants for camless engine and solid-state valvetrain investigations.
OEMs direct the majority of specification authority; aftermarket providers are gaining share fastest as legacy fleet aging accelerates rebuild demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision machining clusters for valvetrain components concentrate in Germany, China, Japan, and the United States, with each jurisdiction enforcing distinct emissions and fuel efficiency frameworks that reshape supplier qualification requirements.
Germany
Schaeffler and LuK maintain dense supplier networks serving premium engine platforms from manufacturing bases in Bavaria and Baden-Württemberg. Euro 7 standards from the European Commission mandate sub-five-micron valve timing tolerances that hydraulic adjusters must sustain across full engine life cycles. Stuttgart-area metrology facilities provide captive air-gauge measurement protocols for cylindrical grinding operations.
China
Domestic OEMs under MIIT fuel consumption regulations are expanding procurement of precision-machined adjusters for overhead camshaft engines. NMPA automotive component certification requirements create parallel compliance pathways favoring suppliers with dual-standard testing capabilities. Yangtze River Delta machining clusters are scaling vacuum-melted bearing steel processing for plunger cylinder production.
United States
Passenger vehicle OEMs are standardizing hydraulic self-adjusting mechanisms to support variable valve timing integration in light truck and SUV powertrains. EPA Tier 3 tailpipe standards compel zero valve clearance specifications that eliminate combustion inefficiencies from mechanical lash variation. Detroit-area engine assembly facilities consolidate bundled exhaust and valvetrain system sourcing.
Japan
Ceramic ball fabrication for high-pressure sealing interfaces concentrates among precision ceramic houses serving both automotive and aerospace turbine applications. METI industrial standards govern surface treatment processes for plunger wear surfaces in legacy and next-generation engine architectures. Nagoya-area supplier networks support variable stator vane actuation systems for geared turbofan programs.
South Korea
Domestic automakers are qualifying hydraulic adjusters for cylinder deactivation strategies under national fuel economy targets. MFDS automotive component quality frameworks align with parallel EPA and Euro validation protocols for export-oriented engine production. Busan-Ulsan manufacturing corridors integrate valvetrain subassembly operations with captive engine foundry capacity.
Hydraulic Lash Adjuster Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream on precision machining and materials science. The supplier base stratifies between vertically integrated emissions system bundlers and standalone adjuster manufacturers lacking portfolio breadth. Three archetypes dominate: integrated valvetrain-exhaust platform suppliers, precision bearing and adjuster portfolio owners, and aftermarket-focused rebuild kit distributors. Competitive moves concentrate on dual-certification capability expansion and bundled system sourcing consolidation.
Among Germany-based integrated suppliers, Schaeffler Technologies AG & Co. and LuK GmbH & Co. KG occupy positions exemplifying the precision bearing-adjuster portfolio archetype, while Young Shin Automotive represents the aftermarket rebuild kit specialization tier. Tenneco sits within the platform integrator category, illustrating how exhaust and valvetrain system bundling reduces customer procurement complexity. These three named entities anchor the competitive structure without exhausting the full supplier landscape.
| Leading Market Players |
|---|
| GT Technologies |
| Tenneco |
| Schaeffler Technologies AG & Co. |
| Young Shin Automotive |
| BLE Products |
| Eaton |
| LuK GmbH & Co. KG |
| COMP Cams |
| OTICS |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Delta machining cluster's vacuum-melted bearing steel capacity expansion is compressing procurement costs for mid-tier hydraulic adjuster manufacturers while concentrating pricing power among German and Japanese precision ceramic houses serving premium OEM specifications.
Pricing Analysis
EPA Tier 3 and Euro 7 tailpipe standards dictate the pricing tier structure across the hydraulic lash adjuster market. Three-tier pricing structure across premium, standard, and economy levels separates sub-five-micron tolerance components with dual-certification capabilities from single-standard mechanical adjusters. Price differentiation hinges on certification grade and volume scale, with bundled exhaust-valvetrain system sourcing commanding premium positioning. Cost compression in the standard tier is intensifying because Chinese domestic OEMs under MIIT fuel consumption regulations are expanding procurement of locally-machined alternatives. Fleet procurement managers at heavy-duty truck engine manufacturers exhibit the highest price sensitivity, while premium passenger vehicle OEMs prioritize zero-lash consistency over unit cost.
Supply Chain Analysis
Extended payment terms from German and Japanese OEMs are straining working capital for tier-two adjuster manufacturers lacking supply-chain finance facilities. Vacuum-melted bearing steel plunger bores draw from German, Czech, and Chinese machining clusters, while ceramic check ball fabrication rests on Japanese and German precision ceramic houses. Single-source vulnerability concentrates in high-pressure sealing interfaces, where regional logistics disruptions threaten production continuity. Distribution runs through bundled emissions system integrators consolidating procurement accountability in North American heavy-duty engine programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as solid-state valvetrain prototypes and electronic adjuster architectures create parallel specification pathways, splitting procurement authority between legacy hydraulic specialists and emerging mechatronic subsystem integrators.
For Market Incumbents: Pre-empt displacement from electromagnetic camless prototypes by deepening captive metrology capabilities for smart adjuster architectures with embedded pressure and temperature sensors. Consolidate backward integration into vacuum-melted bearing steel processing to insulate margin stability from aerospace and medical device demand competition. Lock in bundled exhaust-valvetrain system contracts with North American heavy-duty OEMs before standalone adjuster vendors regain procurement access. For New Entrants and Emerging Players: Establish a beachhead in aerospace turbine blade pitch control applications for geared turbofan architectures, where sub-five-micron tolerance requirements exceed incumbent automotive-focused capabilities. Target aftermarket rebuild kit distribution for legacy overhead cam engines reaching second and third ownership cycles in East Asian independent service networks. Lead with specialized adjuster refurbishment components rather than competing head-to-head on million-cycle OEM durability specifications. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with captive valvetrain divisions lacking standalone scale or dual-certification testing capabilities. Long-term viability in this market rests on positioning for cylinder deactivation strategy integration and camless engine transition hedging. Monitor qualification timelines for trivalent chromium plating alternatives under REACH substance restrictions as the inflection indicator for surface treatment technology winners.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Testing Capacity Expansion | Parallel EPA and MIIT validation protocols open procurement access to Chinese domestic OEMs previously served by joint-venture suppliers. |
| Smart Adjuster Sensor Integration | Embedded pressure and temperature sensors digitize supplier value propositions toward recurring calibration service revenue streams. |
| Aerospace Turbine Qualification | Geared turbofan variable stator vane actuation extends addressable market beyond automotive into commercial aviation propulsion systems. |
| Aftermarket Rebuild Kit Channel Development | Legacy overhead cam engines reaching second and third ownership cycles create demand for specialized adjuster refurbishment components. |
| Trivalent Chromium Surface Treatment Conversion | REACH substance restrictions on hexavalent chromium plating force accelerated re-validation of million-cycle durability data. |
Methodological Framework
A spread of perspectives from OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distribution specialists, and precision machining operators converged on the working assumptions underpinning this analysis. Primary field engagement combined with secondary validation from EPA certification databases, MIIT fuel consumption disclosure filings, Euro 7 regulatory impact assessments, and aerospace turbine program qualification records anchored the evidence base. Bottom-up segmentation modeling and top-down macroeconomic cross-checks ensured triangulation across independent analytical pathways.
Demand-supply-balance framing structured the forecast architecture across the analysis window, with segmentation dimensions spanning product type, application, component subsystem, and end-user procurement authority. Vehicle production databases, engine platform content specifications, and regional emissions compliance timelines fed the analytical model. CAGRs were derived from iterative reconciliation between historical trajectory analysis and forward-looking regulatory implementation schedules.
Sensitivities concentrate around solid-state valvetrain technology maturation timelines, ceramic ball supply disruption scenarios, and REACH substance restriction enforcement intensity. Forecasts reflect documented assumptions regarding EPA Tier 3 and Euro 7 implementation consistency, MIIT fuel consumption pathway stability, and aerospace turbine program ramp schedules. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Philippines Passenger Vehicles Lubricants Market
Automotive Parts
Russia Automotive Actuators Market
Automotive Parts
Automotive Parts Die Casting Market
Automotive Parts
Asia-Pacific Electric Power Steering Market
Automotive Parts
Automotive Fuel Supply System Market
Automotive Parts
Electromagnetic Clutch System Market
Automotive Parts
Automotive Engine Oil Coolers Market
Automotive Parts
Automotive Oil Pressure Switch Market
Automotive Parts
Automotive AHSS Market
Automotive Parts
Air Suspension Systems Market
Automotive Parts
North America Very Narrow Aisle Trucks (VNA Truck) Market
Automotive Parts
Automotive Air Flow Meter Market
Automotive Parts
United Kingdom Passenger Vehicles Lubricants Market
Automotive Parts
South Korea Automotive Parts Zinc Die Casting Market
Automotive Parts
Italy Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Roller Bearing Market