
 Global Passenger Cars Market | 2026-2036
Global Passenger Cars Market Size, Share, and Industry Trends Forecast 2026-2036
Global Passenger Cars Market Foresight
Lithium-ion battery chemistry is rebalancing passenger car product economics as nickel and cobalt compositions yield to iron-phosphate formulations. Toyota Motor Corporation leverages its solid-state battery R&D pipeline to sustain technology leadership in next-generation powertrains. BYD anchors its competitive position through backward integration into blade battery cell production. Tesla differentiates via software-defined vehicle architectures that control over-the-air feature monetization.
Passenger cars are enclosed motor vehicles designed to transport passengers, typically featuring unibody or body-on-frame construction, crumple zones engineered to absorb collision energy, and powertrains ranging from internal combustion engines to battery-electric drivetrains with energy densities exceeding 250 watt-hours per kilogram. Their primary commercial purpose is personal mobility and fleet transportation across urban, suburban, and intercity corridors. SUVs now occupy the dominant revenue position across product type segments as ride height and cabin versatility align with family buyer preferences in North America and Asia-Pacific markets. Electric drivetrains within fuel type segments are recording the fastest volume expansion, though hybrid architectures retain margin strength where charging infrastructure remains sparse. Individual buyers within customer type segments still generate the largest absolute transaction flow, yet fleet owners are consolidating procurement volumes and extracting steeper fleet discounts.
The US EPA tailpipe emission standards and the EU F-Gas Regulation on mobile air conditioning refrigerants are tightening compliance thresholds for vehicle manufacturers across multiple geographies. China's MIIT new energy vehicle credit mandate and India's BIS automotive safety standards are further fragmenting homologation requirements for multinational platforms. California's CARB zero-emission vehicle program and Germany's KBA type-approval protocols add state-level and national-layer complexity to market access. Stakeholders must monitor how battery passport traceability requirements under the EU CSRD reshape supplier qualification and carbon accounting obligations.
Market Dynamics
The transition from nickel-cobalt to lithium iron phosphate battery chemistry is compressing powertrain cost structures and redrawing competitive boundaries across vehicle segments. This shift is forcing incumbent automakers to retool cell sourcing strategies while enabling new entrants to undercut established pricing tiers.
Growth Catalysts
- China's MIIT NEV Credit Mandate:Fleet operators accelerate electrified procurement to avoid compliance penalties, expanding volume commitments for battery-electric platforms.
- Iron-Phosphate Battery Chemistry:Lower raw material costs and improved thermal stability reduce pack pricing, widening addressable market penetration in mass-market segments.
- Yangtze River Delta Manufacturing Corridor:Concentrated cell production and vehicle assembly infrastructure compress logistics costs and supplier qualification timelines.
Market Restraints
- Critical Mineral Supply Concentration:Refined lithium and cobalt processing capacity clusters in specific jurisdictions, exposing automakers to geopolitical supply disruptions.
- Charging Infrastructure Gaps:Sparse fast-charging networks in secondary cities and rural corridors limit pure-electric viability for intercity fleet operators.
- EU F-Gas Refrigerant Regulation:Mobile air conditioning system redesign requirements add homologation costs and extend development cycles for climate-controlled vehicle variants.
Strategic Opportunities
- India's BIS Automotive Safety Standards:Localized crash-test and ADAS compliance frameworks create first-mover advantages for platforms engineered to emerging market specifications.
- Software-Defined Vehicle Architectures:Over-the-air feature monetization transforms one-time sales into recurring revenue streams, particularly in premium segments.
- Fleet Consolidation Patterns:Ride-hailing and corporate mobility providers aggregate procurement volumes, enabling direct manufacturer relationships that bypass traditional dealer networks.
Industry Challenges
- Battery Passport Traceability:EU CSRD carbon accounting and supply chain disclosure requirements demand granular cell-level documentation that most tier-two suppliers cannot yet provide.
- Homologation Fragmentation:Divergent type-approval protocols across the US EPA, Germany's KBA, and China's MIIT force platform variants that dilute scale economies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Passenger Cars Market |
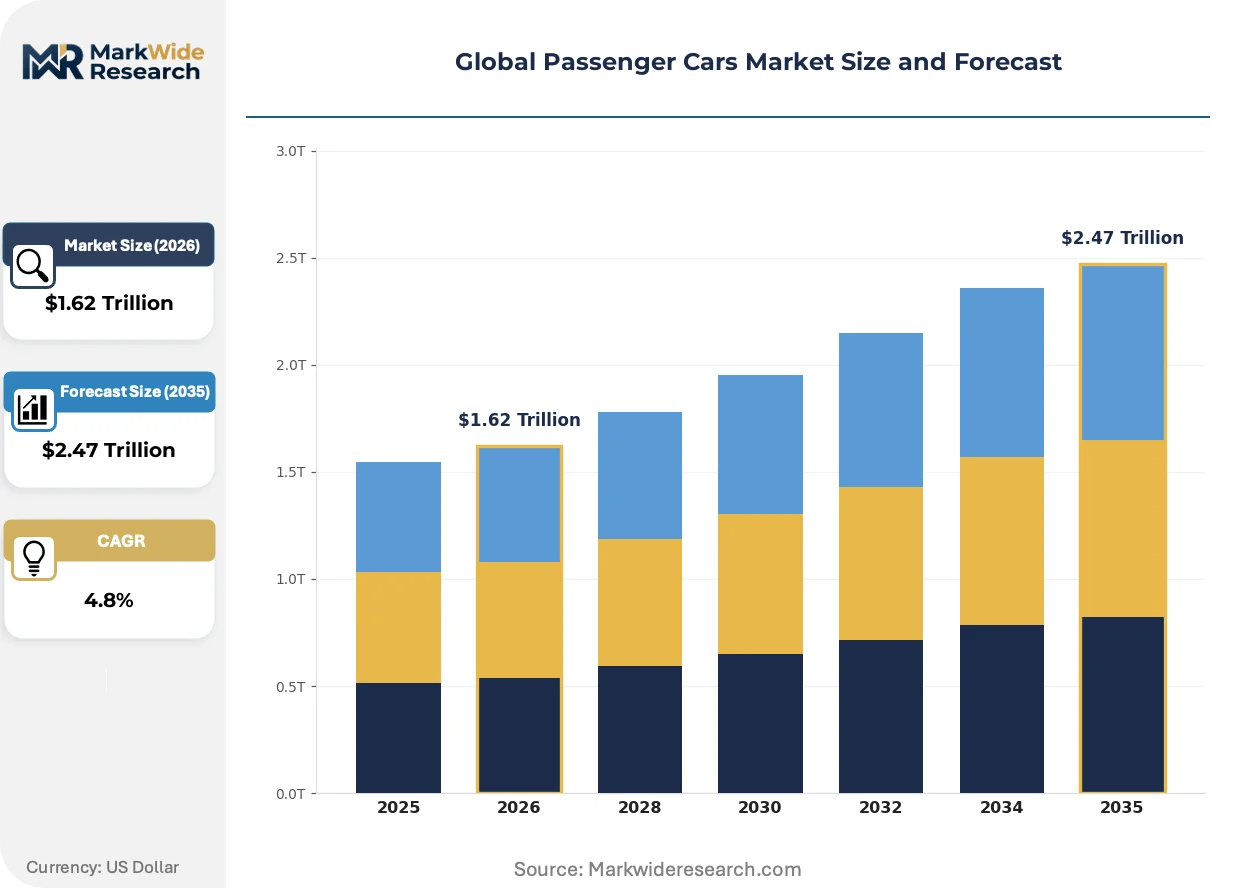
| Market Size in 2026 | $1.62 Trillion |
| Market Size in 2035 | $2.47 Trillion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sedan, SUV, Hatchback, Coupe Fuel Type: Petrol, Diesel, Electric, Hybrid Customer Type: Individual Buyers, Fleet Owners, Car Rentals, Corporate Purchases Sales Channel: Direct Sales, Dealerships, Online Platforms, Auctions |
| Companies Covered | Volkswagen Group, Stellantis, Toyota Motor Corporation, Honda Motor, General Motors, Tesla, Hyundai Motor Company, BMW Group, BYD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Passenger Cars Market Shifts & Advancements
Solid-state battery development and software-centric vehicle architectures are converging to redefine product differentiation beyond traditional powertrain specifications. These forces are compressing hardware commoditization timelines while elevating data and service monetization as primary value levers.
Solid-state electrolyte technology promises energy densities exceeding conventional lithium-ion architectures while eliminating thermal runaway risks. Toyota Motor Corporation and several Korean cell manufacturers have accelerated pilot production timelines for automotive-grade formats. This breakthrough is rewriting the competitive calculus for next-generation powertrain investments, compressing the window for incumbent liquid-electrolyte capacity to recover capital costs.
The EU CSRD and associated battery passport regulations now mandate supply chain traceability from mine to module. Vehicle manufacturers must document carbon intensity and human rights compliance across tier-three raw material suppliers. European fleet operators and export-oriented Chinese producers face the steepest compliance burdens, driving accelerated supplier consolidation and vertical integration into cell production.
Fleet procurement teams now negotiate total cost of ownership contracts that bundle vehicle lease, energy, maintenance, and residual value guarantees into single per-kilometer rates. This model is displacing traditional capital purchase and separate service arrangements, particularly among European corporate mobility providers and North American last-mile delivery operators. Germany and the Netherlands exhibit the fastest contract structure transitions, with Asian markets trailing by approximately two development cycles.
Global Passenger Cars Market Segmentation
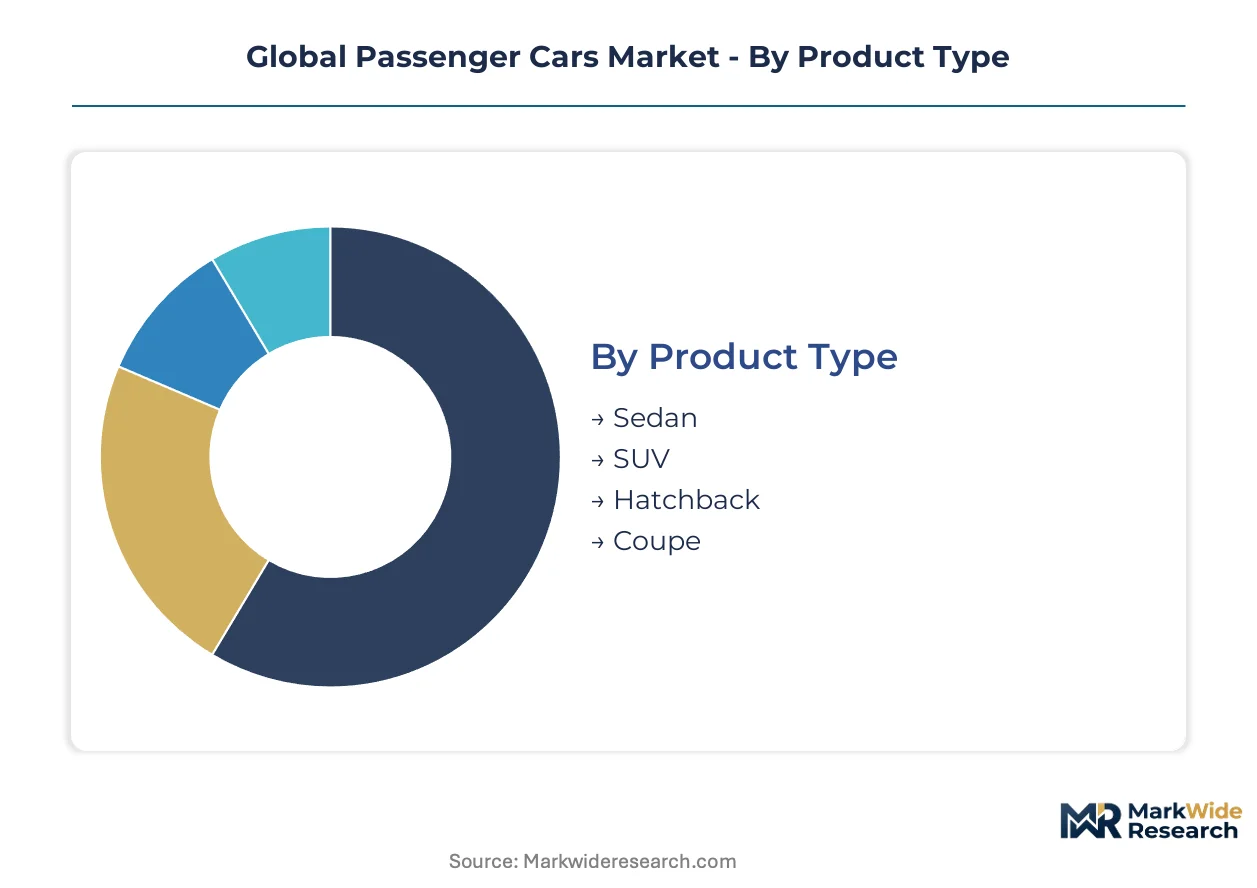
Passenger car procurement decisions fragment across vehicle architecture, energy source, ownership model, and purchase pathway. Each segmentation axis carries distinct margin profiles, regulatory exposure, and supplier power dynamics that reshape competitive positioning.
Product Type:
Buyers prioritize cabin versatility against parking constraints and fuel economy trade-offs when selecting body architecture.
- SUV:Elevated ride height and flexible interior packaging command family buyer preference across suburban North America and China's tier-one cities. Revenue concentration tracks toward mid-size crossovers as electrified platforms reduce fuel economy penalties historically associated with larger footprints.
- Sedan:Three-box designs with dedicated cargo compartments retain fleet procurement dominance where aerodynamic efficiency and rear-seat legroom outweigh cargo flexibility. China's MIIT NEV credit mandate accelerates battery-electric sedan deployment among state-affiliated fleet operators.
- Hatchback:Compact two-box architectures optimize urban parking density in European city centers and Japanese metropolitan corridors. Toyota and Volkswagen maintain platform engineering investments for this segment despite shrinking North American presence.
- Coupe:Two-door fixed-roof configurations target enthusiast demographics with performance-tuned chassis dynamics. Low-volume production sustains primarily through premium badge positioning rather than standalone profitability.
Volume sits with SUV; growth tilts toward electrified sedan platforms in regulated fleet channels.
Fuel Type:
Total cost of ownership calculations now incorporate carbon compliance credits, energy price volatility, and residual value depreciation curves.
- Electric:Battery-electric drivetrains with lithium iron phosphate cell chemistry achieve cost parity in mass-market segments across China's Yangtze River Delta manufacturing corridor. Sparse fast-charging infrastructure in secondary cities and rural corridors constrains intercity viability.
- Hybrid:Parallel and series-parallel architectures retain margin strength where charging networks remain underdeveloped. Toyota's dual-motor hybrid systems dominate fleet procurement in Southeast Asian markets with unreliable grid infrastructure.
- Petrol:Spark-ignition internal combustion engines face compressed development timelines under EU CO2 fleet standards and China's dual carbon policy goals. Brazil's ANP biofuel blending mandates sustain flex-fuel petrol demand in Latin American markets.
- Diesel:Compression-ignition powertrains concentrate in European long-haul fleet applications where torque density and thermal efficiency outweigh NOx aftertreatment costs. Germany's KBA type-approval protocols tightened post-Dieselgate compliance burdens.
Hybrid architectures retain current volume leadership; electric drivetrains gain share fastest where charging infrastructure and NEV credits align.
Customer Type:
Procurement scale and contract structure determine manufacturer pricing power and service bundling opportunities.
- Individual Buyers:Single-unit transactions generate largest absolute transaction flow through dealership networks and direct manufacturer platforms. Financing arrangements and extended warranty attachments drive dealer profitability.
- Fleet Owners:Ride-hailing operators and corporate mobility providers aggregate procurement volumes, extracting steeper discounts and negotiating total cost of ownership contracts with residual value guarantees. Uber and Lyft procurement teams in North America bypass traditional dealer markups.
- Car Rentals:Short-term fleet operators prioritize depreciation-resistant segments and standardized maintenance protocols. Hertz and Avis fleet renewal cycles accelerate toward battery-electric platforms in European urban locations with congestion charge exemptions.
- Corporate Purchases:Employee benefit vehicle programs and executive fleet allocations emphasize brand positioning and CO2 reporting compliance. Germany's CSRD disclosure requirements elevate supply chain carbon accounting in procurement specifications.
Individual transactions dominate absolute volume; fleet consolidation patterns expand most quickly in European corporate mobility markets.
Sales Channel:
Channel economics reflect inventory carrying costs, customer acquisition expenditure, and regulatory franchise protections.
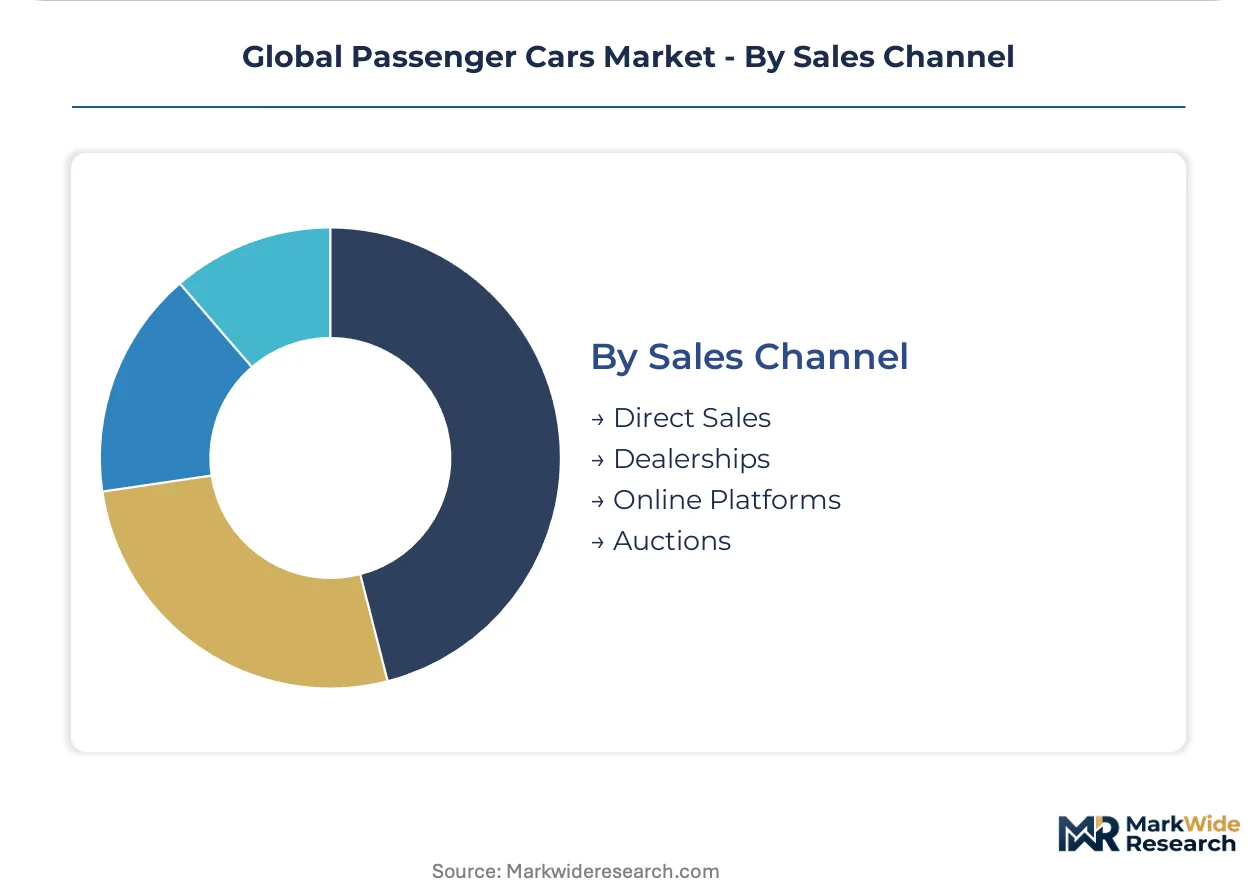
- Dealerships:Franchise networks with localized inventory and service capacity retain dominance in North American markets where state-level dealer protection laws constrain direct manufacturer sales. Margin compression from price transparency tools pressures F&I product attachment rates.
- Direct Sales:Manufacturer-owned retail and online configurators eliminate intermediary markups, enabling dynamic pricing and over-the-air feature monetization. Tesla's direct model circumvents traditional dealer networks in markets without franchise protection statutes.
- Online Platforms:Digital marketplaces aggregate new and used inventory across multiple brands, reducing search costs for comparison shoppers. Carvana and Vroom operational models face profitability challenges from logistics-intensive home delivery commitments.
- Auctions:Wholesale channels dispose of fleet returns, lease residuals, and trade-in inventory toward secondary retail operators. Manheim and ADESA transaction volumes indicate used vehicle supply elasticity and pricing sentiment.
Dealership networks anchor current transaction volume; direct sales channels climb the fastest where regulatory barriers permit manufacturer-controlled distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta and Germany's Baden-Württemberg corridor concentrate the highest-volume passenger car demand clusters worldwide. Fleet procurement contracts in these regions increasingly bundle electrification mandates with residual value guarantees. Regulatory fragmentation across national type-approval regimes forces platform variants that dilute manufacturing scale economies.
China
State-affiliated fleet operators accelerate battery-electric sedan procurement under MIIT NEV credit mandates. The country's dual carbon policy goals compress ICE development timelines for domestic manufacturers. Shanghai and the broader Yangtze River Delta anchor cell production and vehicle assembly infrastructure that compresses supplier qualification timelines.
Germany
Corporate mobility providers negotiate total cost of ownership contracts with carbon accounting disclosure requirements under CSRD rules. The KBA type-approval protocols add national-layer complexity to platform homologation for export-oriented producers. Stuttgart and Baden-Württemberg concentrate premium OEM headquarters and tier-one supplier engineering centers.
United States
Suburban family buyers in Texas and the Southeast prioritize SUV ride height and cabin versatility against parking constraints. EPA tailpipe emission standards tighten compliance thresholds for powertrain development cycles. Detroit and the Midwest manufacturing belt retain final assembly capacity even as battery cell investments shift toward the South.
India
First-time car buyers in Maharashtra and Gujarat drive compact hatchback volume where urban parking density constrains footprint. BIS automotive safety standards create localized crash-test compliance frameworks for multinational platform entry. Tamil Nadu's Sriperumbudur corridor concentrates foreign OEM joint venture assembly operations serving domestic and export markets.
Japan
Commercial fleet operators in Kanto and Kansai regions retain hybrid procurement dominance where charging infrastructure remains underdeveloped. METI industrial policy supports solid-state battery R&D timelines for next-generation powertrain transitions. Toyota City and the Chubu manufacturing belt anchor captive hybrid system production and supplier keiretsu networks.
Global Passenger Cars Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated OEMs commanding premium pricing power while assembly partners capture volume in emerging markets. The vendor base concentrates around five global groups with full-stack powertrain capabilities, though Chinese battery-electric specialists disrupt traditional tiering. Strategic archetypes include legacy conglomerates with multi-brand portfolios, pure-play EV scale operators, and state-backed national champions. Dominant competitive moves encompass backward integration into cell production and software-defined vehicle architecture licensing.
Among the legacy conglomerate tier, Volkswagen Group and Stellantis exemplify multi-brand portfolio strategies that span mass-market and premium positioning. Toyota Motor Corporation occupies a distinct archetype as a hybrid technology incumbent accelerating solid-state battery transitions. Tesla represents the pure-play EV scale operator with direct distribution models that circumvent traditional dealer networks. BYD anchors the state-backed national champion category with captive blade battery cell production integrated through the Yangtze River Delta supply base.
| Leading Market Players |
|---|
| Volkswagen Group |
| Stellantis |
| Toyota Motor Corporation |
| Honda Motor |
| General Motors |
| Tesla |
| Hyundai Motor Company |
| BMW Group |
| BYD |
| Others |
Supply & Pricing Matrix
Sovereign-backed battery producers across China's Yangtze River Delta and state-affiliated OEMs in Germany's Baden-Württemberg corridor command pricing discipline through captive cell supply and fleet procurement aggregation. Their ownership structures compress supplier margins while elevating residual value guarantees as competitive weapons.
Pricing Analysis
Volume concentration in mass-market SUVs and battery-electric sedans compresses per-unit margins, while premium software-defined vehicles sustain pricing power through over-the-air feature monetization. Three-tier pricing structure across premium, standard, and economy levels differentiates primarily by powertrain architecture and ADAS certification grade. Cost compression in iron-phosphate battery packs is intensifying because of nickel and cobalt substitution, eroding legacy nickel-cobalt chemistry premiums. Fleet owners exhibit highest price sensitivity through total cost of ownership negotiations, whereas individual buyers in premium segments show lowest sensitivity to sticker price variations.
Supply Chain Analysis
Ocean freight and overland rail costs from Chinese cell plants to European assembly plants constitute a growing share of landed pack costs, reshaping regional production decisions. Refined lithium processing capacity concentrates in China, Chile, and Australia, while cathode active material production clusters in China, South Korea, and Japan. The passenger car supply chain draws from cobalt feedstock originating in the Democratic Republic of Congo and Indonesia's nickel laterite deposits. Single-source vulnerability in semiconductor-grade lithium hydroxide refining exposes automakers to export license disruptions. Distribution runs through tiered franchise dealer networks in North America, direct manufacturer platforms in China, and hybrid agency models in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Refined lithium conversion capacity and automotive-grade semiconductor foundry output lag vehicle assembly expansion, propping powertrain pricing through the analysis window.
For Market Incumbents: Anchor hybrid technology margins in Southeast Asian markets where charging infrastructure gaps persist, while accelerating solid-state battery R&D timelines to outflank iron-phosphate cost leaders. Consolidate supplier qualification processes under EU CSRD battery passport requirements to exclude tier-two competitors lacking carbon traceability systems. Prioritize backward integration into cathode active material production in Indonesia or Chile to secure nickel and lithium hydroxide offtake. For New Entrants and Emerging Players: Fleet management platforms and corporate mobility aggregators offer the fastest channel to bypass entrenched dealer networks and capture recurring revenue through per-kilometer service contracts. Target India's compact hatchback segment where BIS crash-test localization creates compliance barriers for slow-moving incumbents. Pursue white-label manufacturing partnerships with contract assemblers in Thailand or Vietnam to avoid capital-intensive greenfield investments. For Investors and Strategic Acquirers: Distressed-cycle entries favor pure-play EV scale operators with direct sales infrastructure in China and software-defined vehicle architecture licensing revenue. Long-term viability hinges on cell chemistry flexibility and over-the-air monetization capability rather than manufacturing scale alone. Monitor EU battery passport compliance rates among tier-two suppliers as the inflection indicator for supplier consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Iron-phosphate cell offtake contracts with CATL or BYD secure cost parity in mass-market segments. |
| Software-Defined Vehicle Investment | Over-the-air feature architectures transform Tesla and premium Chinese OEMs into recurring revenue platforms. |
| Geographic Manufacturing Footprint | Yangtze River Delta assembly proximity to cell plants compresses logistics costs for export-oriented producers. |
| Charging Infrastructure Partnership | Fast-charging network alliances with State Grid or Ionity unlock fleet procurement in intercity corridors. |
| Platform Standardization | Modular skateboard architectures across SUV and sedan variants dilute homologation costs under fragmented KBA and MIIT rules. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by structured interviews with OEM platform engineers, tier-one supplier procurement leads, fleet operator sustainability officers, and dealership operations managers. Primary fieldwork covered vehicle production databases, IHS Markit registration data, MIIT NEV credit disclosures, and EU type-approval documentation. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Granularity-level modeling deployed vehicle class, propulsion architecture, and regional production cluster as primary segmentation dimensions, with secondary splits by customer type and sales channel. CAGRs derived from regression analysis of historical production volumes against regulatory mandate trajectories and infrastructure buildout schedules. Forecast inputs incorporated lithium carbonate price volatility indices, charging station deployment curves, and carbon credit market liquidity assumptions.
Several conditions sit outside the modeled scope, including abrupt geopolitical trade restrictions on critical mineral exports, breakthrough solid-state battery commercialization timelines, and autonomous vehicle regulatory frameworks. Forecasts reflect assumptions about policy continuity and technology cost curves that may shift with regulatory elections or raw material discovery. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passenger Vehicles
Microcars Market
Passenger Vehicles
China Luxury Car Market
Passenger Vehicles
Automotive Passenger Vehicle Sensor Market
Passenger Vehicles
Wheelchair Accessible Vehicle Market
Passenger Vehicles
Train Seat Market
Passenger Vehicles
Global Luxury SUV Market
Passenger Vehicles
Solar Passenger Car Market
Passenger Vehicles
Small Suvs Market
Passenger Vehicles
Sports Utility Vehicles (Suvs) Market
Passenger Vehicles
Electric Sports Car Market
Passenger Vehicles
Asia Pacific Luxury Cars Market
Passenger Vehicles
India Luxury Car Market
Passenger Vehicles
Three-Wheeler Vehicle Market
Passenger Vehicles
Indonesia Passenger Car Market
Passenger Vehicles
Luxury Car Market
Passenger Vehicles
Medium Cars Market