
 Indonesia Commercial Vehicles Lubricants Market | 2026-2036
Indonesia Commercial Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Commercial Vehicles Lubricants Market Foresight
Synthetic base stocks is expanding its share in heavy-duty formulations as mineral Group I economics erode under longer OEM drain specifications. PT Pertamina leverages its captive refinery output to anchor mid-tier fleet supply contracts across Kalimantan. Chevron Corporation sustains premium positioning through OEM co-development programs with Japanese truck assemblers. Royal Dutch Shell Plc differentiates via digital oil-analysis subscriptions that lock workshop loyalty in Jakarta's dense service corridors.
Indonesia commercial vehicles lubricants are formulated blends of base oils and performance additives engineered to manage friction, thermal stability, and soot dispersion in diesel engines operating under tropical loads and extended idle cycles. These products typically carry SAE viscosity grades of 15W-40 or 10W-30 and must resist oxidation under high-sulphur fuel combustion common in archipelago logistics. Engine Oil commands the dominant value pool given high consumption rates in inter-island trucking, while Grease gathers momentum from mining and construction equipment servicing in Papua and Sulawesi. Fleet Operators represent the fastest-growing end-user channel as centralized procurement displaces fragmented workshop buying.
BIS-equivalent national standards and Indonesia's Ministry of Energy and Mineral Resources biofuel blending rules shape product certification pathways and additive reformulation cycles. The country's environmental regulator enforces waste-oil handling protocols that concentrate licensed collection in major port cities. Stakeholders must monitor how B50 biodiesel progression alters total base number depletion rates and forces earlier drain intervals versus synthetic extended-life claims.
Market Dynamics
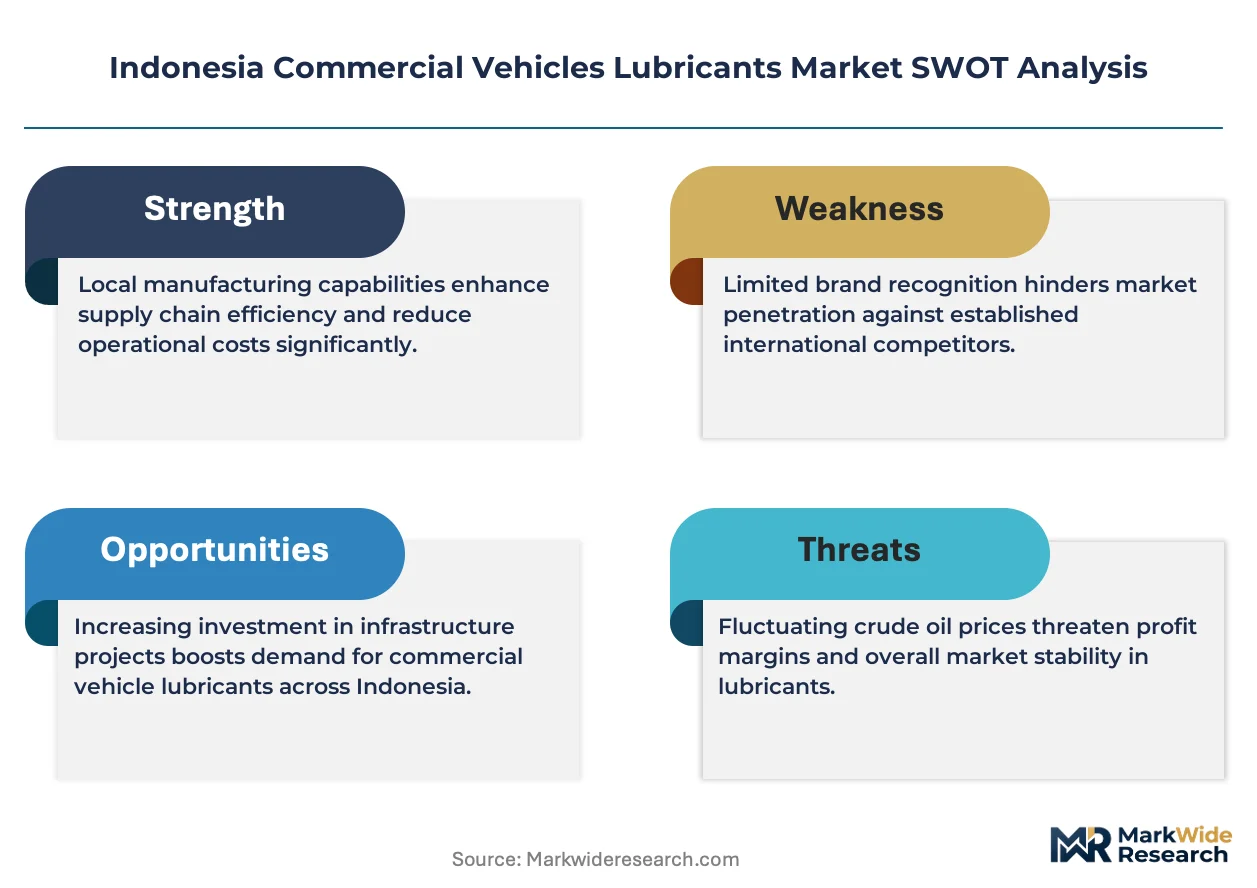
Indonesia's B40 biodiesel mandate is the dominant structural force reshaping commercial vehicle lubricant demand, forcing additive reformulation to counter accelerated oxidation and deposit buildup from palm-based fuel combustion across heavy-duty fleets.
Growth Catalysts
- Ministry of Energy and Mineral Resources biofuel blending rules:The B40 mandate and anticipated B50 progression create sustained demand for high-TBN (total base number) formulations that neutralize acidic byproducts from fatty acid methyl ester combustion.
- Fleet operator consolidation:Centralized procurement by logistics groups across Java and Sumatra displaces fragmented workshop purchasing, driving volume commitments to certified lubricant suppliers.
- Synthetic base stock adoption:OEM drain interval extensions to 80,000 kilometers in Euro-III compliant trucks pull demand toward Group II/III formulations that resist thermal breakdown under tropical idle cycles.
Market Restraints
- Group I base oil supply concentration:Domestic refinery output limitations force blenders to import API Group II/III stocks, exposing margins to Singapore hub pricing volatility and currency fluctuation.
- Used lubricant collection infrastructure gaps:Licensed waste-oil handling protocols concentrate in Jakarta, Surabaya, and Makassar, leaving Kalimantan and Papua with informal disposal channels that constrain circular economy participation.
- High-sulphur diesel persistence:Inter-island bunkering quality inconsistencies above 500 ppm sulphur accelerate lubricant acidification, compressing effective service life below synthetic product claims.
Strategic Opportunities
- Papua and Sulawesi mining corridors:Construction and extractive equipment servicing in eastern Indonesia remains underserved by technical field services, creating white space for mobile oil-analysis and bulk delivery systems.
- Digital fleet management integration:Telematics-enabled oil condition monitoring allows predictive drain scheduling, opening subscription revenue models tied to vehicle uptime guarantees rather than per-liter sales.
- PLI scheme alignment:Indonesia's Production Linked Incentive framework for manufacturing investment supports domestic blending capacity expansion to capture import substitution value in mid-tier fleet segments.
Industry Challenges
- Tribology specialist scarcity:Formulation chemists with palm-biodiesel combustion expertise remain concentrated in Singapore and Kuala Lumpur, constraining local R&D velocity for Pertamina and independent blenders.
- BIS-equivalent certification timelines:National standard harmonization with evolving OEM specifications creates 12-18 month product approval cycles that lag behind Japanese and European truck platform introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Commercial Vehicles Lubricants Market |
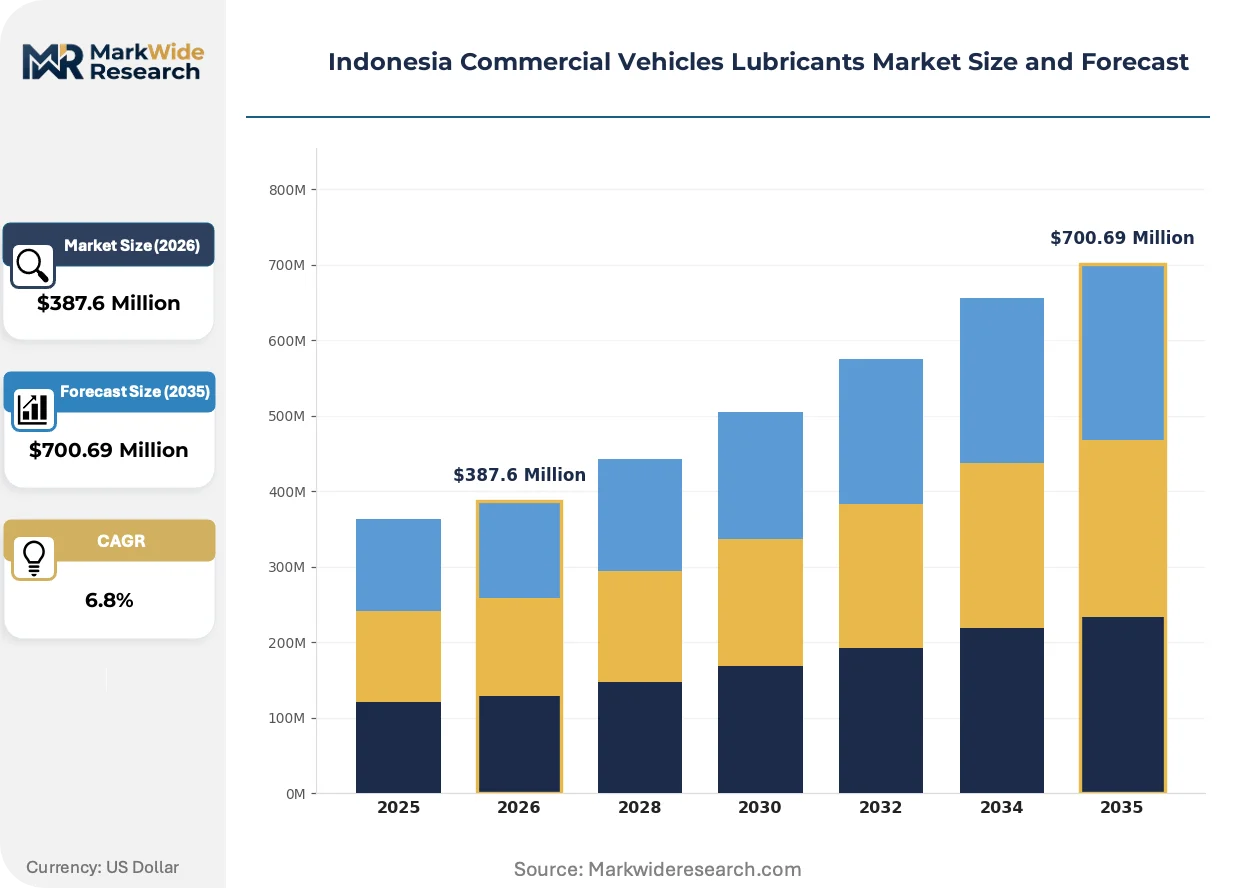
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Gear Oil, Grease End User: Trucking Companies, Fleet Operators, OEMs, Workshops Application: Heavy-Duty Trucks, Light-Duty Vehicles, Bus Services, Delivery Vans Distribution Channel: Retail Stores, E-Commerce, Direct Sales, Wholesale |
| Companies Covered | PT Wiraswasta Gemilang Indonesia (Evalube), Chevron Corporation, PT Pertamina, TotalEnergies, FUCHS, BP PLC (Castrol), Royal Dutch Shell Plc, Idemitsu Kosan Co Ltd, ExxonMobil Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Commercial Vehicles Lubricants Market Shifts & Advancements
Reformulation chemistry is pivoting toward oxidation-resistant additive systems as biodiesel blending ratios climb, while digital service models reshape how lubricant value is captured and delivered to dispersed archipelago fleets.
Polyalkylene glycol (PAG) synthetic base stocks are electrifying heavy-duty diesel formulations by delivering superior thermal stability and soot-handling capacity compared to mineral alternatives. Mining contractors in Kalimantan and coal-hauling fleets in South Sumatra are adopting PAG-enhanced 10W-40 grades for extended drain intervals in high-load, high-humidity conditions. This technology is electrifying competitive positioning by enabling lubricant suppliers to displace incumbent mineral-oil relationships through total cost of ownership guarantees rather than per-liter pricing.
Indonesia's Ministry of Energy and Mineral Resources biofuel blending progression from B40 toward B50 mandates is forcing step-change additive package redesigns. The regulation's 2025-2035 trajectory requires lubricant formulators to double detergent-dispersant concentrations to manage increased combustion-chamber deposits and fuel dilution. Engine oil suppliers serving Java's dense trucking corridors are responding with accelerated field-testing protocols to validate drain interval claims under elevated biodiesel content.
Fleet procurement centralization is consolidating purchasing authority into logistics group headquarters, displacing traditional distributor-led workshop relationships. Large trucking operators in Jakarta and Surabaya are unbundling lubricant supply from mechanical service contracts, negotiating direct volume agreements with blenders for island-wide bulk delivery. This pattern is most visible in containerized inter-island shipping, where fuel and lubricant procurement have merged under single fleet management platforms to optimize working capital across archipelago operations.
Indonesia Commercial Vehicles Lubricants Market Segmentation
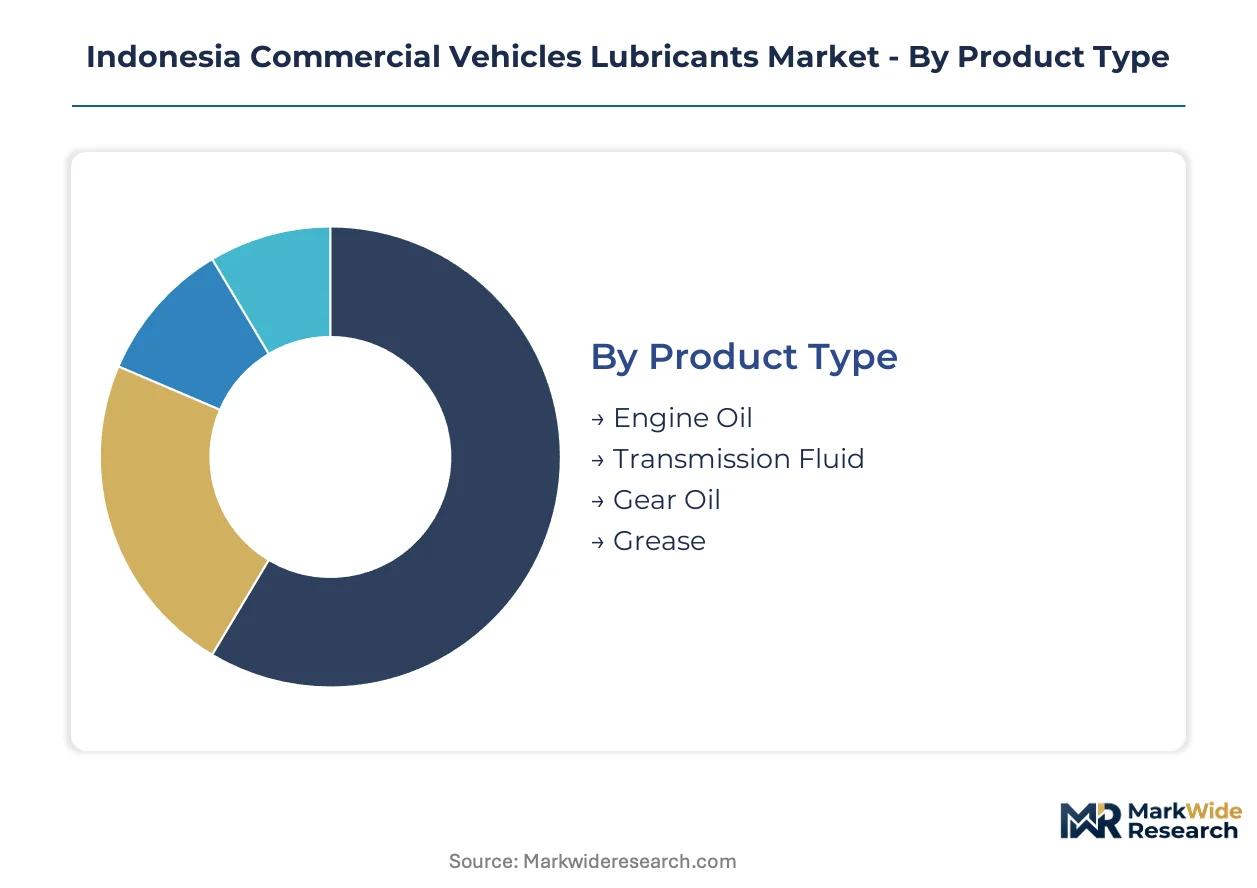
Segmentation in Indonesia's commercial vehicle lubricants market reveals how certification requirements, procurement centralization, and biodiesel compatibility reshape supplier strategies across distinct customer and application profiles.
Product Type:
Certification pathways from Indonesia's Ministry of Energy and Mineral Resources and BIS-equivalent standards impose divergent testing burdens across product categories, with engine oils facing the most stringent oxidation stability validation under B40 mandates.
- Engine Oil:Formulated blends of base oils and detergent-dispersant additives engineered to manage soot dispersion and thermal breakdown in diesel engines operating under tropical loads. Demand concentrates in inter-island trucking corridors across Java and Sumatra where fleet operators extend drain intervals to offset biodiesel-induced degradation. PT Pertamina and international blenders compete through high-TBN formulations that neutralize acidic byproducts from palm-based fuel combustion.
- Grease:Thickened lubricant systems combining base oils with metallic soap or complex thickener structures to seal contaminants and sustain boundary lubrication under shock loading. Mining contractors in Papua and Sulawesi drive specification requirements for extreme-pressure grades in construction and extractive equipment servicing, where centralized procurement is displacing fragmented workshop buying.
- Transmission Fluid:Specialized formulations managing friction characteristics and heat dissipation in automated manual and conventional transmissions.
- Gear Oil:Extreme-pressure lubricants protecting differentials and final drives in heavy-axle configurations under sustained torque loading.
Leading the category by volume: Engine Oil. Growing fastest: Grease.
End User:
Cost tier stratification separates premium synthetic adopters from mineral-oil purchasers, with procurement scale and technical service requirements determining margin capture across customer types.
- Fleet Operators:Centralized logistics groups with island-wide vehicle portfolios negotiating direct volume agreements for bulk delivery and predictive maintenance integration. These stakeholders pull demand toward Group II/III synthetic formulations as OEM drain specifications extend, displacing traditional distributor relationships in Jakarta and Surabaya.
- Trucking Companies:Inter-island freight operators managing fuel and lubricant procurement under unified fleet management platforms to optimize working capital across archipelago operations. B40 biodiesel mandates force accelerated additive reformulation cycles to counter combustion-chamber deposits in high-sulphur fuel environments.
- OEMs:Japanese and European truck assemblers specifying factory-fill lubricants through co-development programs with certified blenders.
- Workshops:Fragmented service points in secondary cities dependent on distributor-led supply relationships and per-liter pricing models.
Volume concentrates with Fleet Operators. Steepest expansion trajectory: Fleet Operators.
Application:
Application-specific duty cycles determine formulation specifications, with high-idle tropical operations and extended haul distances creating divergent thermal and oxidation stress profiles.
- Heavy-Duty Trucks:Euro-III compliant diesel platforms operating 80,000-kilometer drain intervals under combined high-load and high-humidity conditions. Coal-hauling fleets in South Sumatra and containerized shipping operators across Java adopt PAG-enhanced 10W-40 grades through total cost of ownership guarantees rather than per-liter pricing.
- Bus Services:Urban and inter-city passenger transport with stop-start duty cycles accelerating lubricant fuel dilution and acidification. Operators in Jakarta's dense service corridors prioritize oxidation-resistant additive packages as B50 biodiesel progression looms.
- Light-Duty Vehicles:Commercial pickups and small trucks in last-mile distribution with shorter drain intervals and price-sensitive procurement.
- Delivery Vans:E-commerce logistics fleets with high-frequency, low-distance cycles driving rapid lubricant degradation.
Heavy-Duty Trucks anchor application demand. Bus Services gain share fastest.
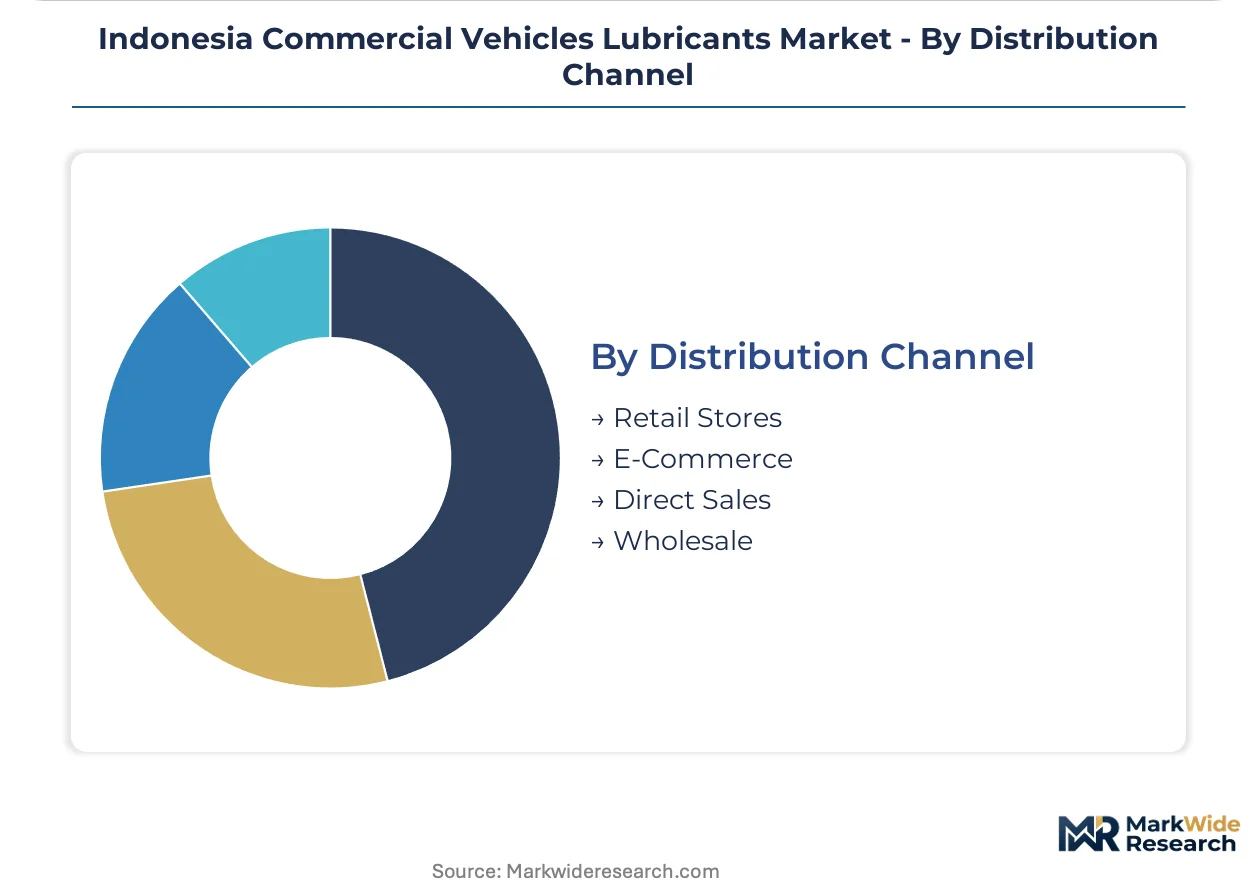
Distribution Channel:
Channel economics reflect geographic fragmentation across Indonesia's archipelago, with infrastructure concentration in western islands forcing adaptive logistics strategies for eastern market penetration.
- Direct Sales:Volume contracts between blenders and consolidated fleet operators for island-wide bulk delivery with integrated oil-analysis subscriptions. Chevron Corporation and Royal Dutch Shell Plc leverage digital service models to lock workshop loyalty through telematics-enabled condition monitoring.
- Wholesale:Distributor networks supplying fragmented workshops in Kalimantan and secondary cities where licensed waste-oil handling infrastructure remains concentrated in Jakarta, Surabaya, and Makassar.
- Retail Stores:Branded service stations and automotive parts counters serving owner-operator truckers and small fleet maintenance.
- E-Commerce:Emerging platform-based procurement for standardized grades in urban centers with reliable logistics coverage.
Direct Sales commands value concentration. E-Commerce expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's commercial vehicle lubricant demand concentrates in Java and Sumatra where inter-island trucking corridors generate the heaviest fleet consumption. Eastern provinces present service infrastructure gaps that constrain synthetic product penetration despite mining-driven equipment needs.
Java
Jakarta's dense logistics corridors drive centralized fleet procurement toward Group II/III synthetic formulations with predictive oil-analysis subscriptions. Indonesia's Ministry of Energy and Mineral Resources enforces B40 biodiesel blending rules that force additive reformulation cycles. Surabaya's containerized shipping operators negotiate direct volume agreements for island-wide bulk delivery.
Sumatra
Coal-hauling fleets in South Sumatra adopt PAG-enhanced 10W-40 grades through total cost of ownership guarantees rather than per-liter pricing. BIS-equivalent national standards impose oxidation stability validation burdens on engine oil suppliers. Palembang's trucking operators extend drain intervals to offset biodiesel-induced degradation under high-sulphur fuel conditions.
Kalimantan
Mining contractors in East Kalimantan drive specification requirements for extreme-pressure grease grades in construction and extractive equipment servicing. Licensed waste-oil handling protocols concentrate in Jakarta and Surabaya, leaving this region with informal disposal channels. Samarinda's heavy-equipment workshops remain dependent on distributor-led supply relationships.
Sulawesi
Nickel mining operations in Central Sulawesi generate demand for technical field services that remain underserved by mobile oil-analysis systems. Indonesia's environmental regulator enforces waste-oil handling protocols that constrain circular economy participation in eastern provinces. Makassar functions as the sole licensed collection hub for this region's commercial vehicle lubricant waste streams.
Papua
Remote mining corridors in Papua create white space for bulk delivery systems and predictive maintenance integration. High-sulphur diesel persistence above 500 ppm sulphur accelerates lubricant acidification in this region. Jayapura's logistics operators face compressed effective service life below synthetic product claims due to fuel quality inconsistencies.
Indonesia Commercial Vehicles Lubricants Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with state-affiliated energy companies anchoring mid-tier fleet supply through captive refinery output. International oil majors sustain premium positioning via OEM co-development programs and digital service subscriptions. Three archetypes dominate: vertically integrated national oil companies, multinational lubricant blenders with technical service networks, and regional independent distributors serving fragmented workshop channels. Competitive intensity centers on additive package reformulation velocity for biodiesel compatibility and predictive maintenance platform deployment.
Among Indonesia-based suppliers, PT Pertamina occupies a position exemplifying captive refinery leverage for domestic blending capacity. Chevron Corporation and Royal Dutch Shell Plc represent the multinational archetype, anchoring premium-tier positioning through telematics-enabled condition monitoring and workshop loyalty programs in Jakarta's dense service corridors. These three entities illustrate how competitive advantage in this market depends on combining formulation chemistry capabilities with digital fleet management integration.
| Leading Market Players |
|---|
| PT Wiraswasta Gemilang Indonesia (Evalube) |
| Chevron Corporation |
| PT Pertamina |
| TotalEnergies |
| FUCHS |
| BP PLC (Castrol) |
| Royal Dutch Shell Plc |
| Idemitsu Kosan Co Ltd |
| ExxonMobil Corporation |
| Others |
Supply & Pricing Matrix
Group II and Group III base oil import costs from Singapore refineries cascade through three distinct pricing tiers, compressing margins for mid-tier blenders serving Java's fleet operators while anchoring premium positioning for suppliers with captive additive formulation capabilities.
Pricing Analysis
Volume commitments from consolidated fleet operators trade at thin margins against per-liter spot sales to fragmented workshops. Three-tier pricing structure across premium synthetic, mid-tier hydrocracked, and economy mineral grades reflects certification tier and bulk delivery scale. Pricing pressure stems from biodiesel-induced drain interval compression that undermines synthetic extended-life claims. Owner-operator truckers in secondary cities exhibit highest price sensitivity; Jakarta-based logistics groups with predictive maintenance contracts show lowest.
Supply Chain Analysis
Specialized tribology chemists concentrate in Singapore and Kuala Lumpur, constraining local formulation velocity for Indonesian blenders. API Group II/III base stocks flow from Singapore, South Korea, and Thailand; detergent-dispersant additive packages originate from US and European chemical majors. Single-source vulnerability runs through Singapore hub pricing for base oil imports. Distribution runs through direct bulk delivery contracts with fleet operators, bypassing traditional wholesale channels in concentrated procurement corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into captive base oil supply and forward integration into predictive maintenance platforms constitute the dual vertical-integration race reshaping competitive position in this market.
For Market Incumbents: To counter biodiesel-induced drain interval compression, anchor market position through accelerated oxidation stability field-testing protocols and direct bulk delivery infrastructure expansion into Kalimantan mining corridors. Certification investment in BIS-equivalent standards ahead of B50 progression locks out reformulation-lagged competitors. For New Entrants and Emerging Players: Mobile oil-analysis subscriptions for Papua and Sulawesi mining contractors represent the most penetrable white-space target. Technical field service gaps in eastern Indonesia enable subscription revenue models tied to equipment uptime guarantees rather than per-liter sales, bypassing entrenched distributor relationships. For Investors and Strategic Acquirers: B50 mandate progression announcements from Indonesia's Ministry of Energy and Mineral Resources are the leading indicator that additive reformulation capabilities will command acquisition premiums. Long-term viability over the next decade hinges on chemistry assets with palm-biodiesel combustion expertise. Acquisition targets should display field-testing infrastructure and fleet telematics integration; watch for B50 timeline acceleration as the primary inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Supply | Captive Group II/III refinery output from Pertamina insulates margin volatility from Singapore hub pricing. |
| Predictive Maintenance Platform Deployment | Telematics-enabled oil condition monitoring locks workshop loyalty through uptime guarantee contracts in Jakarta. |
| B50 Additive Reformulation Acceleration | Doubled detergent-dispersant concentrations validated under palm-biodiesel combustion secure drain interval claims. |
| Eastern Indonesia Field Service Expansion | Mobile oil-analysis systems in Papua and Sulawesi capture mining contractor procurement centralization. |
| Waste Oil Collection Infrastructure Buildout | Licensed handling protocols beyond Jakarta, Surabaya, and Makassar enable circular economy participation. |
Research Methodology
Independent corroboration across lubricant blender supply managers, fleet procurement directors, and mining contractor maintenance heads underwrites the qualitative findings in this analysis. Primary interviews with additive package formulators, base oil traders, and workshop service managers combined with secondary validation from Indonesia's Ministry of Energy and Mineral Resources biofuel blending directives, BIS-equivalent certification databases, and Singapore refinery output disclosures. Bottom-up volume triangulation against top-down market sizing anchored the segment-level outputs.
Rate-of-change decomposition across product type, end-user procurement scale, application duty cycle, and regional logistics infrastructure shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include base oil grade tier, fleet operator consolidation status, biodiesel blend ratio exposure, and archipelago distribution complexity. CAGRs derived from elasticity-adjusted demand curves incorporating OEM drain specification progression and B40-to-B50 mandate trajectory. Industry-specific inputs encompassed oxidation stability test data and telematics penetration rates in commercial vehicle fleets.
Revisions become necessary when biodiesel blend ratio acceleration exceeds modeled timelines, base oil import tariff structures shift, or synthetic formulation cost parity with mineral alternatives materializes faster than projected. Forecasts reflect documented assumptions about fleet operator procurement centralization velocity and additive package reformulation cycle durations. A small set of named triggers warrants ongoing watch: B50 mandate implementation timing, Singapore hub base oil pricing volatility, and eastern Indonesia logistics infrastructure development.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Mexico Automotive Parts Zinc Die Casting Market
Automotive Parts
Italy Automotive Hydraulic Actuators Market
Automotive Parts
Connecting Rods Market
Automotive Parts
Automotive Spring Market
Automotive Parts
Automotive Thermal Systems Market
Automotive Parts
Commercial Vehicles LED Bar Lights Market
Automotive Parts
Automobile Muffler Market
Automotive Parts
Gasoline Direct Injection Market
Automotive Parts
Lug Wrench Market
Automotive Parts
Japan Automotive Hydraulic Actuators Market
Automotive Parts
Automotive Brake Friction Products Market
Automotive Parts
Drum Brake Market
Automotive Parts
Latin America Automotive Parts Magnesium Die Casting Market
Automotive Parts
Automotive Viscosity Index Improvers Market
Automotive Parts
Spare Wheel Carrier Market
Automotive Parts
Wiper Systems Market