
 Electric Vehicle Aluminum Die Casting Parts Market | 2026-2036
Electric Vehicle Aluminum Die Casting Parts Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Aluminum Die Casting Parts Market Insights
Software-defined thermal management is shifting how aluminum die casting suppliers contract with automakers, moving from component sales to performance-guarantee subscriptions. Nemak leverages its integrated casting-machining footprint to anchor long-term battery enclosure supply agreements with European OEMs. Ryobi Limited sustains competitive differentiation through high-pressure die casting specialization for structural EV frames in East Asian production networks. Georg Fischer dominates precision vacuum die casting for cooling circuit components, where tolerances directly impact battery thermal efficiency.
Electric vehicle aluminum die casting parts are aluminum alloy components formed by injecting molten metal into steel molds under pressures ranging from 1,000 to 20,000 psi, achieving wall thicknesses below 2.5 millimeters with tensile strengths exceeding 300 MPa. These parts serve primarily to reduce vehicle mass while maintaining crashworthiness and thermal conductivity in electrified powertrains. Structural components occupy the largest volume share as OEMs consolidate multi-part assemblies into single castings for battery trays and body-in-white nodes. High-pressure die casting leads technology adoption due to cycle speed and dimensional repeatability at mass production scale. Battery enclosures represent the fastest-growing application segment, driven by integrated thermal-fluidic designs that combine structural support with active cooling channels.
The EPA tailpipe emission standards and NHTSA corporate average fuel economy rules in the United States compel automakers to lightweight vehicle structures, directly expanding aluminum die casting procurement. China's MIIT new energy vehicle mandates and GB standards for battery safety enforce minimum thermal management performance, specifying aluminum alloy grades and casting integrity for enclosure applications. Stakeholders must monitor how solid-state battery form factors alter enclosure geometries and whether regional carbon border adjustments reshape foundry energy sourcing decisions.
Market Dynamics
Software-defined thermal management architectures are forcing aluminum die casting suppliers to restructure commercial relationships, converting one-time component sales into recurring performance-guarantee subscriptions tied to battery thermal efficiency metrics.
Growth Catalysts
- China's MIIT NEV mandates:Minimum thermal management performance requirements under GB standards are specifying aluminum alloy grades and casting integrity for battery enclosure procurement.
- High-pressure die casting cycle speeds:Dimensional repeatability at mass production scale is accelerating adoption for structural EV components requiring wall thicknesses below 2.5 millimeters.
- Yangtze River Delta cluster concentration:Die casting foundries co-locating with battery assembly plants are reducing logistics costs and enabling just-in-time thermal management component delivery.
Market Restraints
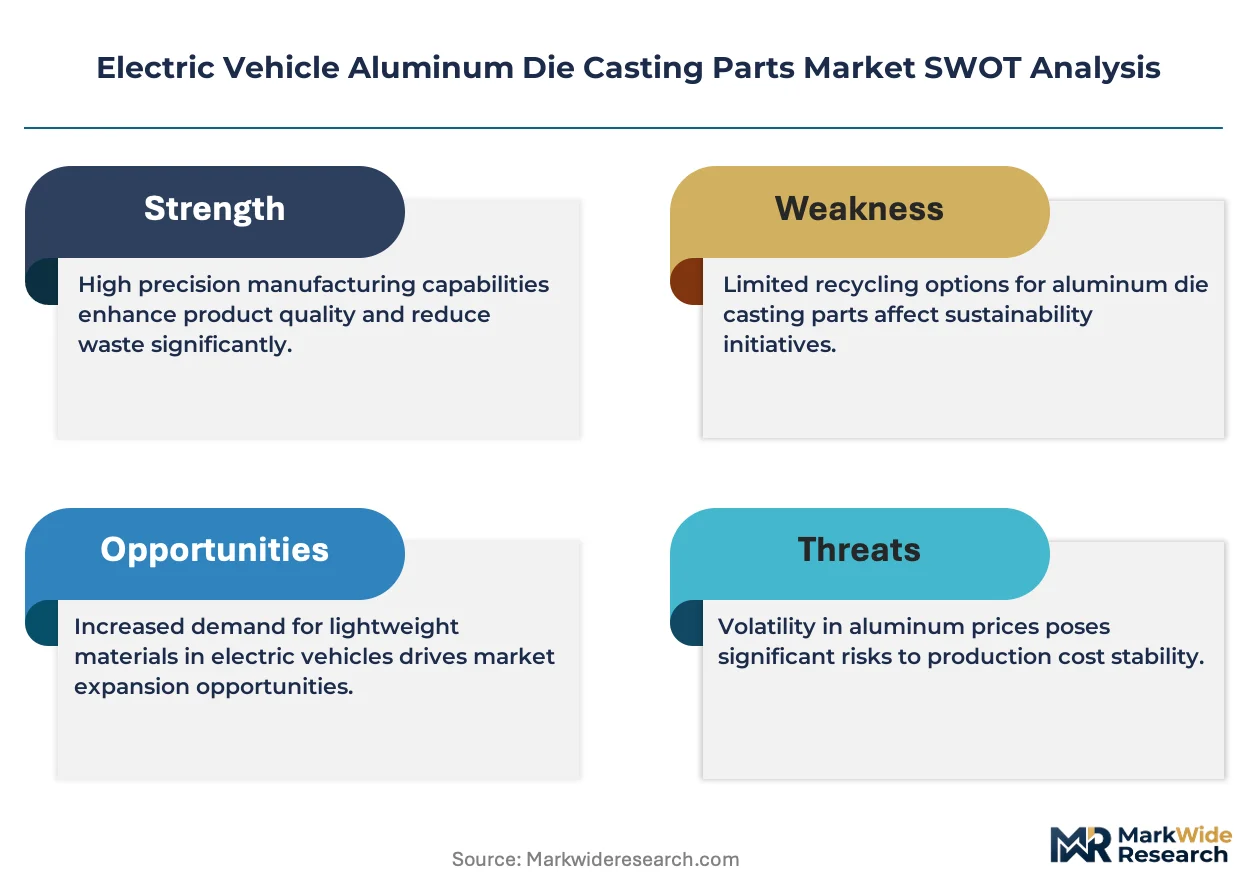
- Primary aluminum price volatility:Energy-intensive smelting operations expose foundries to input cost swings that compress margin buffers on fixed-price OEM contracts.
- Equipment supplier oligopoly:High-pressure die casting machine production concentrates among German and Japanese capital goods manufacturers, creating capex bottlenecks for capacity expansion.
- EU F-Gas Regulation compliance:Thermal management system refrigerant restrictions are complicating cooling channel designs and extending validation timelines for European-bound enclosures.
Strategic Opportunities
- India's PLI scheme for automotive:Production-linked incentives for advanced chemistry cell manufacturing are attracting battery assembly investment that will localize die casting demand.
- Solid-state battery form factor divergence:Next-generation cell architectures requiring redesigned enclosure geometries create first-mover advantages for foundries with rapid tooling capabilities.
- Carbon border adjustment mechanisms:Regional embodied carbon tariffs are incentivizing foundry energy sourcing shifts that can be monetized through premium low-carbon aluminum positioning.
Industry Challenges
- Multi-physics simulation talent scarcity:Integrated thermal-structural-fluidic design for battery enclosures requires computational engineers with rare cross-domain expertise.
- Tooling lead time compression:OEM platform acceleration cycles are demanding die cast mold delivery in 12-14 weeks versus historical 20-week baselines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Aluminum Die Casting Parts Market |
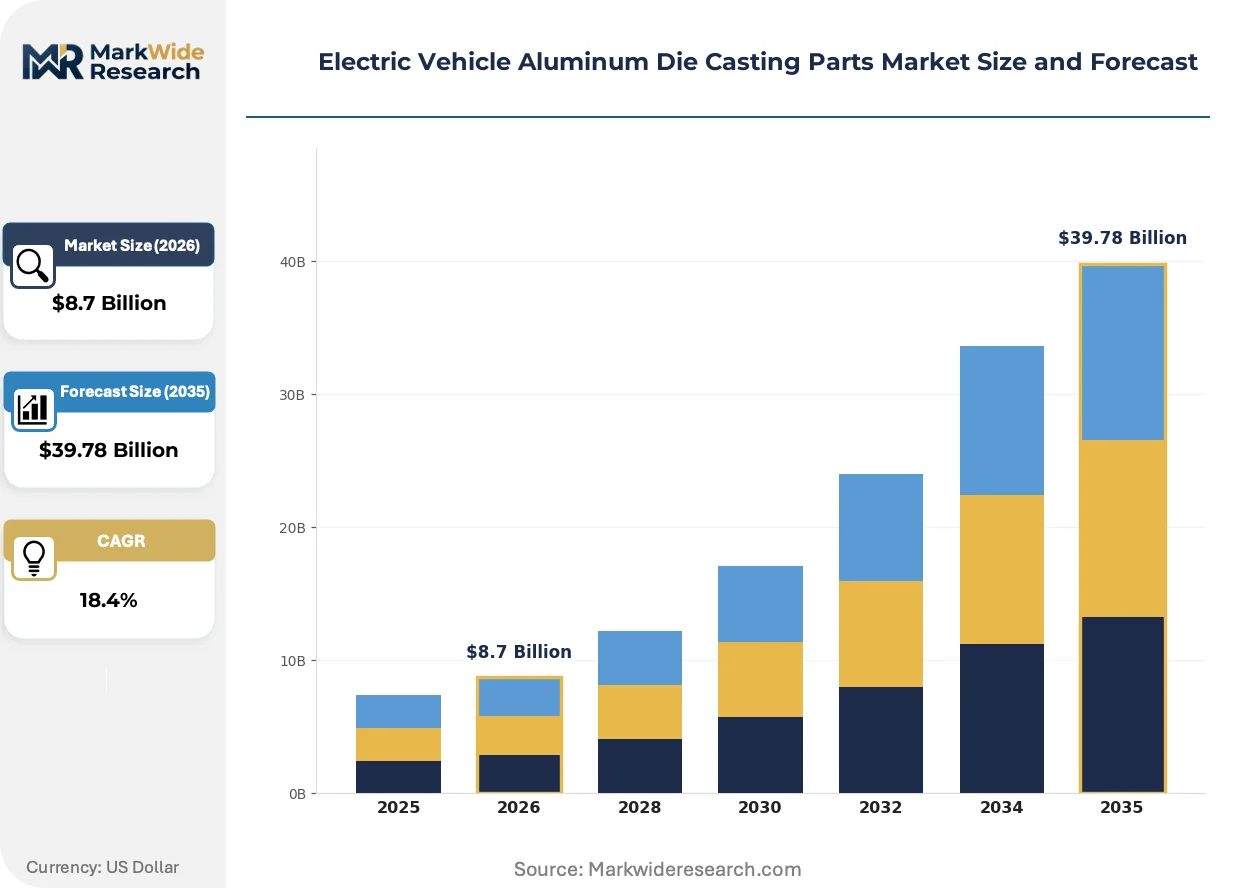
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Structural Components, Chassis Parts, Engine Blocks, Transmission Housings End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Technology: High-Pressure Die Casting, Low-Pressure Die Casting, Vacuum Die Casting, Gravity Die Casting Application: Battery Enclosures, Heat Exchangers, Cooling Systems, Structural Frames |
| Companies Covered | Nemak, Ryobi Limited, Linamar Corporation, Martinrea International, Pace Industries, Dynacast, Aludyne, Ahresty Corporation, Georg Fischer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Aluminum Die Casting Parts Market Trends and Innovations
Active thermal management integration is blurring the boundary between structural and functional components, requiring die casters to master conjugate heat transfer engineering alongside metallurgical process control.
Large-scale integrated die casting is rewriting how battery enclosures are manufactured. Tesla's gigacasting approach consolidates seventy-plus stamped and welded parts into single aluminum castings. European and Chinese OEMs are replicating this at varying paces. The technology is compressing assembly line footprint requirements and eliminating joint corrosion pathways in thermal-fluidic circuits.
The EU F-Gas Regulation is tightening refrigerant restrictions for battery thermal management systems. Automakers must redesign cooling channel geometries to accommodate lower-GWP alternatives with different thermodynamic properties. Battery enclosure suppliers serving European markets are responding with vacuum die casting process refinements that maintain leak-tight integrity at thinner wall sections.
Buyer consolidation among EV OEMs is concentrating procurement leverage with ten major platforms now accounting for the majority of battery enclosure volume. Tier-1 suppliers are responding by embedding foundry operations within OEM manufacturing campuses. This geographic pattern is most visible in China's Jiangsu and Zhejiang provinces, where battery-dedicated die casting joint ventures are proliferating.
Electric Vehicle Aluminum Die Casting Parts Market Segmentation
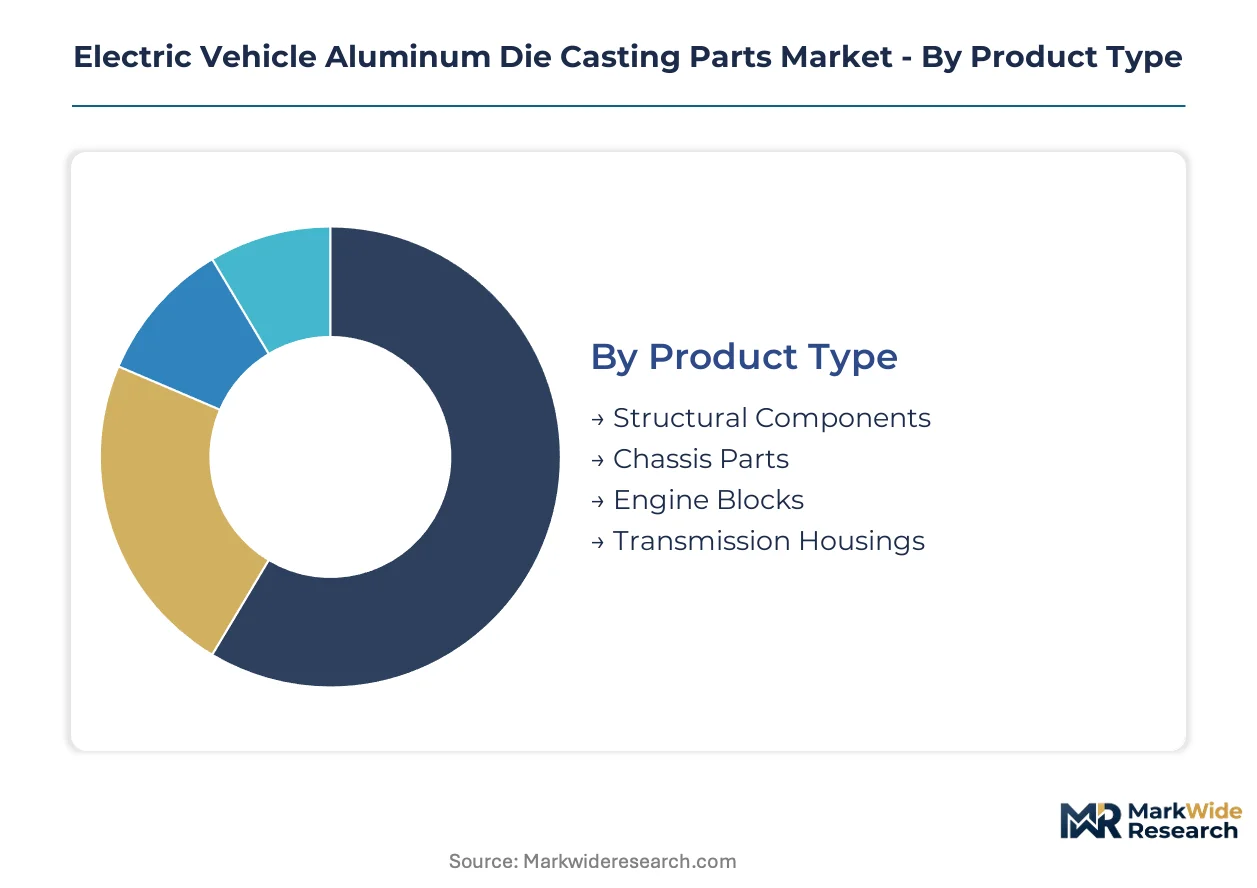
Segmentation in the Electric Vehicle Aluminum Die Casting Parts Market reveals how integration depth varies across product architectures. Some segments operate as standalone bolt-on components while others embed directly into platform-level thermal and structural systems.
Product Type:
Standalone structural members contrast with chassis assemblies that integrate multiple functions into single castings. Integration depth determines tooling complexity and OEM contract duration.
- Structural Components:Consolidated aluminum castings replacing multi-part welded assemblies in battery trays and body nodes. Demand concentrates in Tesla's gigacasting supply chain and Chinese OEM platform programs pursuing single-piece rear floor structures.
- Chassis Parts:Control arms, knuckles, and subframe elements requiring fatigue resistance above 150 MPa. European premium EV architectures specify these for mass reduction without sacrificing crash performance.
- Engine Blocks:Declining relevance in pure battery-electric platforms; persistent demand from range-extender and plug-in hybrid programs in Germany and Japan.
- Transmission Housings:Reduced gearbox complexity in EVs shifts casting requirements toward e-axle and reducer housings with integrated motor mounts.
Volume placements concentrate in Structural Components; the faster expansion belongs to Chassis Parts as multi-link rear suspensions proliferate across C-segment and above EV platforms.
End User:
Customer type segmentation tracks how procurement authority distributes between vehicle manufacturers and their supply chain intermediaries. Direct OEM relationships favor foundries with design-for-manufacturing capabilities.
- OEMs:Direct procurement of battery enclosures and large structural castings. BYD and NIO operate captive die casting facilities in Jiangsu province to control thermal management integration.
- Tier-1 Suppliers:Intermediate aggregators sourcing machined castings for brake systems, steering, and HVAC modules. Margin pressure intensifies as OEMs consolidate supplier bases.
- Aftermarket Providers:Replacement chassis components and collision repair parts; limited volume due to aluminum repair complexity and OEM parts certification requirements.
- Vehicle Assemblers:Contract manufacturers and joint-venture production facilities with localized die casting partnerships.
Procurement authority is shifting toward OEMs for high-integration castings; Tier-1 Suppliers retain volume leadership in modular subassemblies.
Technology:
Process selection balances cycle speed against porosity control and dimensional precision. Vacuum and high-pressure methods dominate where leak-tight integrity matters for thermal-fluidic circuits.
- High-Pressure Die Casting:Cycle times under 90 seconds enable mass production of thin-wall structural components. The Yangtze River Delta cluster hosts the densest concentration of 4,000-tonne-plus machines serving battery enclosure programs.
- Vacuum Die Casting:Reduced gas porosity achieves heat treatability and weldability for crash-critical nodes. European OEMs specify this for front-end structures requiring post-cast T7 heat treatment.
- Low-Pressure Die Casting:Slower fill rates suit thick-section transmission housings and motor mounts where internal soundness outweighs cycle speed.
- Gravity Die Casting:Permanent mold casting for prototype volumes and aftermarket production; minimal automation limits scale economics.
Equipment deployment tilts toward High-Pressure Die Casting; Vacuum Die Casting is climbing fastest as heat-treatable alloy adoption spreads.
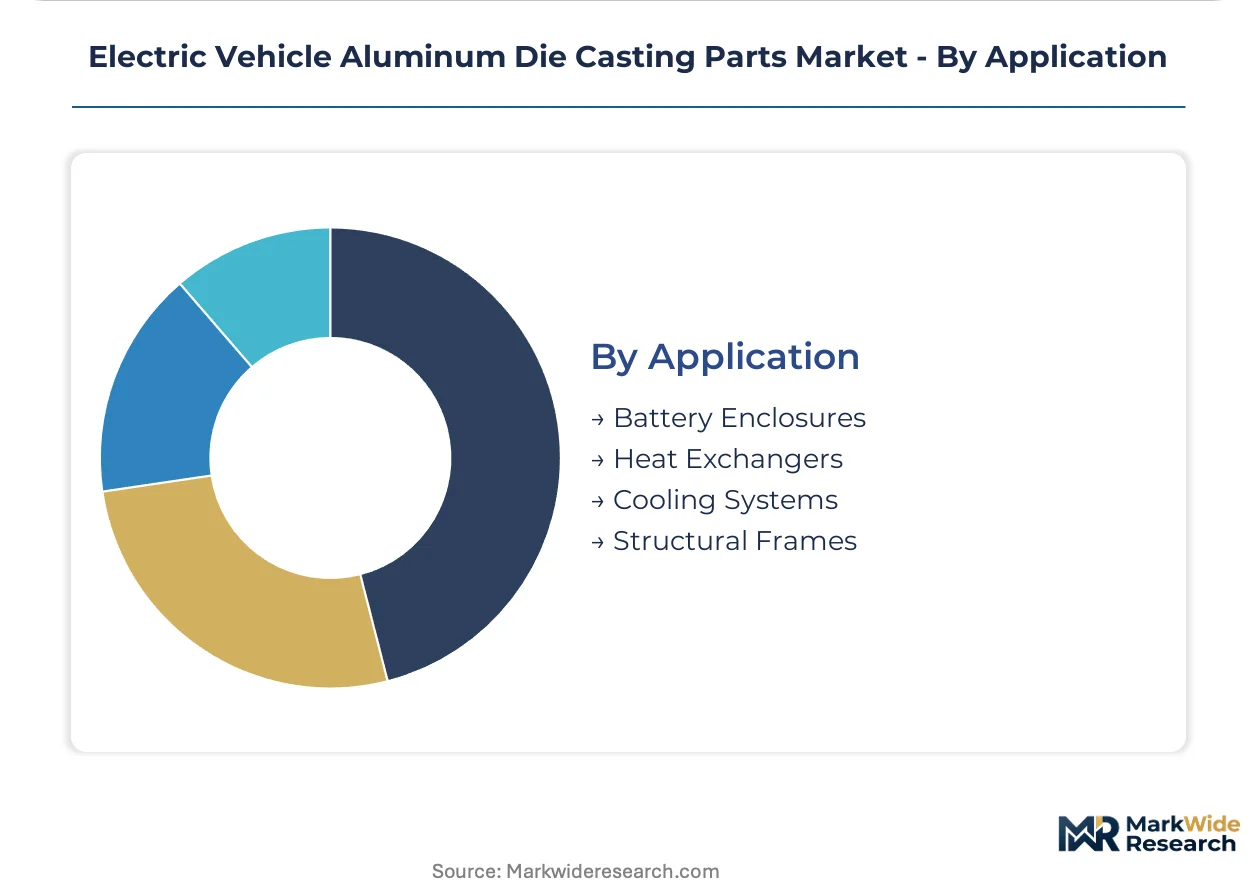
Application:
Functional segmentation distinguishes thermal management components from load-bearing structures. Active cooling integration is blurring this boundary in next-generation battery architectures.
- Battery Enclosures:Combined structural and thermal functions with integrated cooling channels. China's GB standards for battery safety mandate specific aluminum grades and casting integrity levels for these applications.
- Heat Exchangers:Thin-wall castings with extended surface geometries for refrigerant and coolant circuits. EU F-Gas Regulation compliance is driving redesign for lower-GWP working fluids.
- Cooling Systems:Pump housings, manifolds, and valve bodies requiring pressure-tight integrity. Japanese suppliers specialize in precision vacuum casting for these fluid-handling components.
- Structural Frames:Megacasting rear underbodies and front compartments consolidating dozens of stamped parts. Tesla's Austin and Berlin facilities anchor this segment's process development.
Production volume clusters in Structural Frames; Battery Enclosures are expanding most quickly as cell-to-pack architectures proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China produces the majority of EV aluminum die casting components while European and North American markets absorb premium-grade output for luxury platforms. This production-consumption divide shapes regional investment patterns and regulatory compliance requirements.
China
MIIT NEV mandates and GB battery safety standards specify aluminum alloy grades for thermal management enclosures. The Yangtze River Delta cluster in Jiangsu and Zhejiang provinces hosts die casting joint ventures co-located with CATL and BYD battery assembly plants. Foundries here operate 4,000-tonne-plus high-pressure machines for gigacasting-scale production.
Germany
Premium OEM platforms from BMW, Mercedes-Benz, and Volkswagen drive demand for vacuum die cast heat-treatable alloys in crash-critical nodes. KBA type-approval requirements and EU F-Gas Regulation refrigerant restrictions complicate cooling channel validation timelines. Bavaria and Baden-Württemberg concentrate precision foundries supplying thermal-fluidic components for European-bound EVs.
United States
EPA tailpipe standards and NHTSA CAFE rules compel lightweighting across Detroit Three and Tesla lineups. Texas and Michigan anchor competing production philosophies: Austin hosts Tesla's gigacasting consolidation while Detroit maintains traditional multi-supplier chassis sourcing. The Inflation Reduction Act domestic content provisions influence aluminum procurement decisions.
Japan
METI carbon neutrality roadmaps and JIS standards govern alloy selection for export-bound components. Toyota and Nissan thermal management specifications drive vacuum die casting specialization for pump housings and manifolds. Aichi Prefecture's Nagoya industrial corridor maintains precision casting capacity for hybrid and range-extender programs.
India
PLI scheme incentives for advanced chemistry cell manufacturing are attracting battery assembly investment to Tamil Nadu and Gujarat. BIS automotive standards and state-level EV policies create foundational demand for localized die casting capacity. Chennai and Ahmedabad industrial zones are emerging as preferred locations for foundry joint ventures serving Maruti Suzuki and Tata Motors platforms.
Electric Vehicle Aluminum Die Casting Parts Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the EV aluminum die casting landscape. The market structure tilts toward consolidation at the high-integration end while fragmenting among commodity chassis suppliers. Three archetypes dominate: integrated casting-machining operators, high-pressure specialists, and precision vacuum die casters. Capacity expansion and captive supply arrangements represent the dominant competitive moves as OEMs seek supply security.
Among integrated operators, Nemak and Ryobi Limited exemplify the casting-machining archetype with end-to-end process control. Georg Fischer occupies a position within the precision vacuum tier where thermal-fluidic component tolerances determine battery efficiency. These three companies anchor distinct competitive vectors: scale consolidation, East Asian production network density, and European premium-tier positioning.
| Leading Market Players |
|---|
| Nemak |
| Ryobi Limited |
| Linamar Corporation |
| Martinrea International |
| Pace Industries |
| Dynacast |
| Aludyne |
| Ahresty Corporation |
| Georg Fischer |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up specialists now control substantial die casting capacity across North American automotive supply chains, compressing supplier margins through aggressive working-capital management while simultaneously extracting pricing premiums from OEMs desperate for thermal management component security. This ownership pattern concentrates bargaining power with consolidated buyers and distorts traditional foundry economics toward short-term EBITDA optimization.
Pricing Analysis
Margin tightening in vacuum die cast battery enclosures traces to OEM platform acceleration cycles demanding 12-14 week mold delivery versus historical 20-week baselines. Three-tier pricing structure across premium, standard, and economy levels separates heat-treatable alloy grades certified to GB standards from commodity Al-Si-Mg alternatives. Cost-down pressure on high-pressure structural castings accelerates because Chinese foundries in the Yangtze River Delta cluster absorb primary aluminum volatility through captive smelter relationships. Tier-1 suppliers exhibit highest price sensitivity due to fixed-price OEM contracts with minimal pass-through clauses; OEM direct procurement shows lowest sensitivity where thermal performance guarantees justify premium positioning.
Supply Chain Analysis
Freight cost arbitrage between Chinese export ports and European inland destinations now exceeds 8% of landed component value for vacuum die cast heat exchangers, forcing logistics network reconfiguration. Supply concentrates in China, Germany, and Mexico for high-volume automotive programs. Raw material dependencies draw from primary aluminum smelters in Quebec, Emirates, and Yunnan province, plus German and Japanese capital equipment manufacturers for 4,000-tonne-plus machines. Single-source vulnerability concentrates in high-pressure die casting machine supply, where two equipment builders control global capacity expansion. Distribution runs through OEM campus-embedded foundry joint ventures in Jiangsu and Zhejiang provinces, bypassing traditional Tier-1 aggregation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EV aluminum die casting sector sits at a technology-transition inflection where large-scale integrated die casting displaces multi-part stamped and welded assemblies. Gigacasting consolidation rewrites capital intensity requirements and tooling amortization economics.
For Market Incumbents: Anticipate solid-state battery form factor divergence by reserving rapid tooling capability capacity and pre-positioning heat-treatable alloy expertise for crash-critical node applications. Defensive consolidation through captive foundry joint ventures with CATL and BYD in Jiangsu province secures thermal management integration access. Vertical integration into precision machining operations preserves margin capture against Tier-1 supplier disintermediation.
For New Entrants and Emerging Players: Vacuum die casting specialization for cooling circuit components offers technology-first wedge positioning against high-pressure commodity competition. White-space targets concentrate in India's Tamil Nadu and Gujarat industrial zones where PLI scheme battery assembly investment precedes localized die casting capacity. Penetrable segment: precision pump housings and manifolds for Japanese OEM hybrid programs requiring JIS-certified alloys. Go-to-market angle: embedded engineering partnerships with Aichi Prefecture Nagoya corridor thermal management specialists.
For Investors and Strategic Acquirers: Distressed-cycle entries favor precision vacuum die casters with European premium OEM qualifications in Bavaria and Baden-Württemberg, where KBA type-approval timelines create moats against rapid replication. Long-term viability hinges on 5-10 year thermal management architecture lock-in as software-defined battery systems proliferate. Acquisition target archetype: mid-scale foundries with T7 heat treatment capability and existing EU F-Gas Regulation validation documentation. Signal to watch: OEM gigacasting platform adoption rates accelerating mold tooling demand beyond German and Japanese equipment builder capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Gigacasting Platform Adoption | Tesla's consolidation of seventy-plus parts into single castings compresses assembly footprints across OEM replication programs. |
| Vacuum Die Casting Capacity Expansion | European OEM heat-treatable alloy specifications for crash-critical nodes outstrip qualified foundry supply. |
| Campus-Embedded Foundry Joint Ventures | BYD and NIO captive facilities in Jiangsu province eliminate logistics costs for just-in-time battery enclosure delivery. |
| Rapid Tooling Capability Investment | 12-14 week mold delivery requirements reward foundries with in-house die design and CNC machining integration. |
| Low-Carbon Aluminum Sourcing Certification | Regional carbon border adjustment mechanisms monetize Quebec and Yunnan hydro-powered smelter positioning. |
Research Methodology
Multi-period observation of high-pressure die casting machine deployment rates, primary aluminum price volatility patterns, and OEM platform consolidation timelines anchored the trend analysis, supplemented by interviews with foundry operations directors, OEM platform engineers, Tier-1 supplier procurement leads, and thermal management system architects. Secondary validation drew from MIIT NEV production filings, Yangtze River Delta industrial zone investment disclosures, German KBA type-approval databases, and SEC 10-K equipment supplier filings. Bottom-up capacity modeling triangulated against top-down OEM procurement budget analysis.
The input-output matrix framed die casting output as a function of machine-hour availability, alloy feedstock cost structures, and OEM platform lifecycle positioning across the projection horizon. Segmentation dimensions modeled encompassed product integration depth, process technology selection, thermal management functional embedding, and regional regulatory compliance tier. CAGRs derived from compound growth pathing of battery enclosure unit volumes against aluminum content per vehicle trajectories. Industry-specific forecast inputs included solid-state battery commercialization timelines and EU F-Gas Regulation refrigerant transition schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden primary aluminum price spikes or German equipment builder delivery delays. Outputs reflect documented assumptions regarding OEM platform acceleration cycle maintenance and carbon border adjustment mechanism implementation scope. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Indonesia Commercial Vehicles Lubricants Market
Automotive Parts
Automotive Wiper System Market
Automotive Parts
Europe Automotive Parts Zinc Die Casting Market
Automotive Parts
Vehicle Transfer Case Market
Automotive Parts
Indonesia Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Tire Molds Market
Automotive Parts
Canada Automotive Parts Die Casting Market
Automotive Parts
Bulgaria Automotive Lubricants Market
Automotive Parts
Tire Tread Cutting Machines Market
Automotive Parts
Automotive Steel Market
Automotive Parts
Power Liftgate Market
Automotive Parts
Mexico Automotive Parts Die Casting Market
Automotive Parts
Nigeria Automotive Engine Oils Market
Automotive Parts
Automotive Suspension System Market
Automotive Parts
Automotive Trailing Arm Market
Automotive Parts
Mexico Automotive Actuators Market