
 Wiper Systems Market | 2026-2036
Wiper Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Wiper Systems Market Intelligence
ISO 9001/IATF 16949 qualification cycles is unwinding supplier eligibility across the wiper systems value chain, favoring manufacturers with certified quality management systems. Robert Bosch GmbH leverages its captive motor production in Germany to sustain margin control across the integrated wiper module segment. Valeo S.A. anchors its position through adaptive rain-sensing technology leadership, while Denso Corporation competes aggressively in the conventional wiper arm and blade aftermarket through dense OEM service networks.
Wiper systems encompass electromechanical assemblies combining drive motors, linkage mechanisms, and blade carriers engineered to clear precipitation from vehicle glazing surfaces, typically operating at sweep frequencies between 30 and 65 cycles per minute depending on speed settings. These systems serve the essential safety function of maintaining operator visibility under adverse weather conditions across all motorized ground transport categories. Electric wiper products dominate installed value owing to universal fitment in passenger and commercial vehicles, while rain-sensing adaptive technology represents the fastest-expanding margin pool as automakers bundle sensor-driven automation into premium trim configurations. The aftermarket channel for replacement blades and complete assemblies sustains higher volume velocity than OEM fitment due to wear-driven replacement cycles averaging twelve to twenty-four months in high-precipitation climates.
The US NHTSA Federal Motor Vehicle Safety Standard 104 mandates minimum swept areas and operating speeds for windshield clearing systems, directly shaping product design validation requirements for suppliers accessing North American vehicle platforms. ECE Regulation 48 in Europe and Japan's JIS D 5703 standard impose comparable visibility performance thresholds, creating a harmonized but jurisdictionally certified compliance landscape for multinational component manufacturers. Stakeholders must monitor evolving automated driving visibility standards that will likely mandate redundant sensor cleaning integration alongside traditional glazing clearance functions.
Market Dynamics
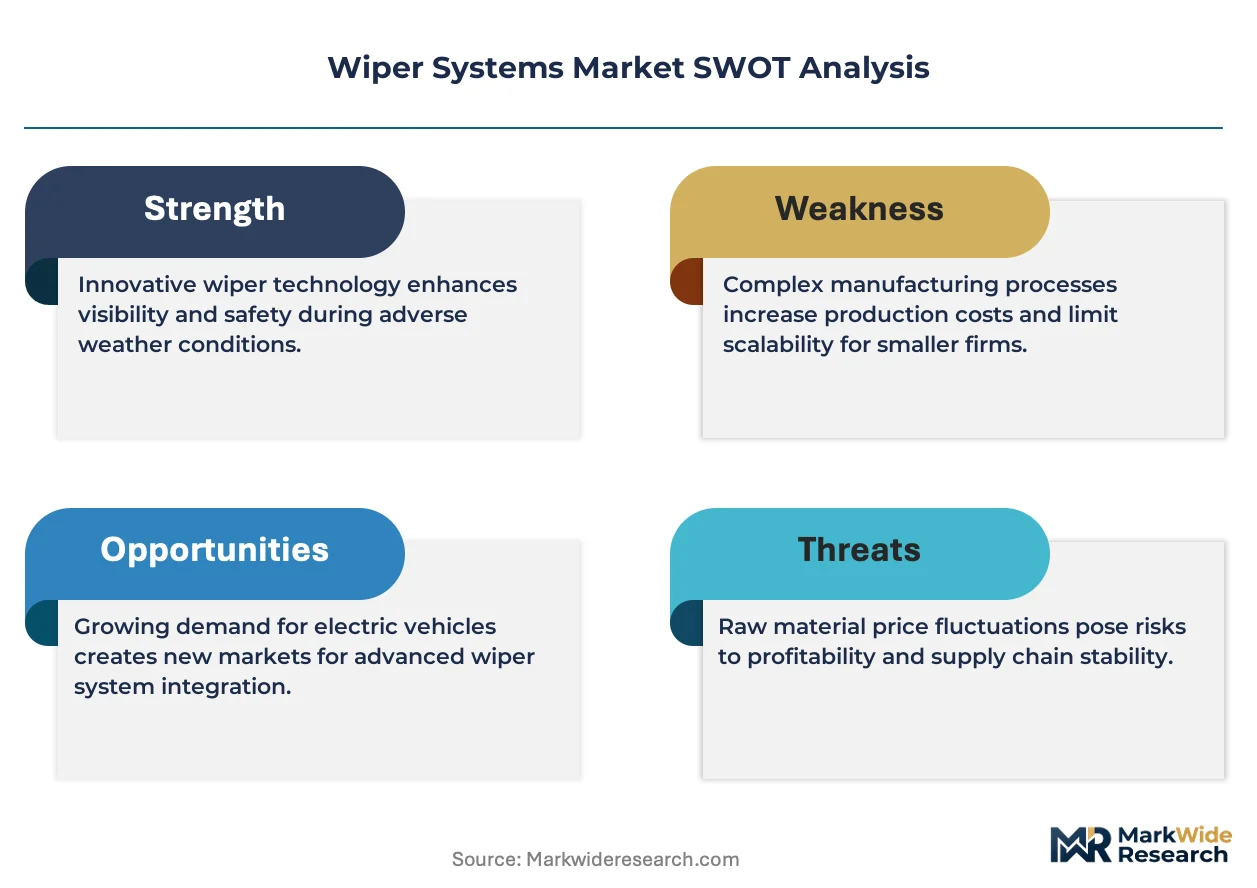
ISO 9001/IATF 16949 qualification cycles are compressing supplier eligibility across the wiper systems value chain, favoring manufacturers with certified quality management systems and forcing consolidation among uncertified component producers.
Growth Catalysts
- ANVISA visibility protocols:Brazil's stricter safety mandates for commercial vehicle fleets are accelerating wiper replacement schedules and expanding aftermarket service intervals.
- Rain-sensing module adoption:Premium passenger vehicle assembly corridors in Germany are capturing disproportionate demand share for integrated sensor-driven automation.
- Electrification of drive systems:Brushless DC motor architectures are replacing conventional brushed designs across OEM platforms, improving durability and reducing electromagnetic interference.
Market Restraints
- Raw material volatility:Natural rubber and steel pricing fluctuations directly compress blade and linkage margin structures for tier-two suppliers.
- Supply concentration risk:Captive motor production in Germany creates dependency on single-source electromechanical component flows.
- Technical limitation:Conventional wiper arm designs face performance ceilings in extreme cold climates below minus twenty degrees Celsius.
Strategic Opportunities
- Sensor cleaning convergence:Automated driving visibility standards are mandating redundant LiDAR and camera cleaning integration alongside traditional glazing functions.
- Aftermarket channel expansion:Dense OEM service networks in Japan enable direct-to-fleet replacement programs bypassing traditional distributor tiers.
- India commercial vehicle penetration:BIS certification requirements are creating first-mover advantage windows for qualified wiper system suppliers in heavy truck fitment.
Industry Challenges
- Certification timeline compression:IATF 16949 audit cycles now require eighteen-month revalidation windows, straining quality engineering bandwidth.
- Legacy integration complexity:Adaptive rain-sensing modules must interface with decade-old vehicle network architectures lacking standardized CAN bus protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wiper Systems Market |
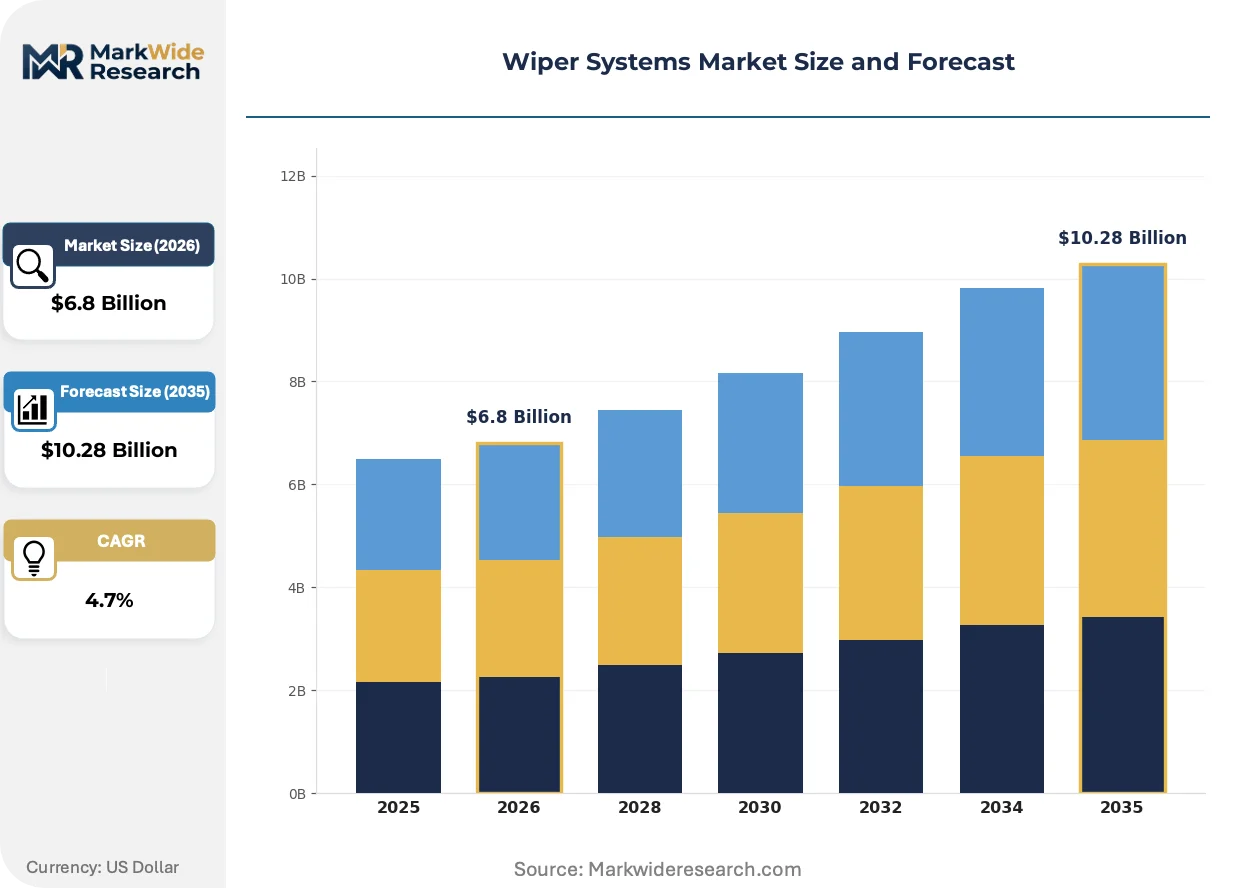
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Wipers, Pneumatic Wipers, Manual Wipers, Hybrid Wipers End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Technology: Conventional, Adaptive, Automatic Rain Sensing, Integrated Application: Passenger Vehicles, Commercial Vehicles, Off-Road Vehicles, Motorcycles |
| Companies Covered | Robert Bosch GmbH, Valeo S.A., Denso Corporation, Mitsuba Corporation, HELLA GmbH & Co. KGaA, Trico Products, ASMO Co., Ltd., Magneti Marelli S.p.A., DOGA SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wiper Systems Market Strategic Shifts & Innovations
Product architectures are diverging as electromechanical sophistication separates premium integrated modules from commodity blade replacements, reshaping competitive positioning across OEM and aftermarket channels.
Silicone-based blade compounds are fragmenting traditional rubber-dominated aftermarket segments. Fleet operators in high-UV climates are adopting extended-life silicone formulations at accelerated replacement cycles. This material shift is fragmenting supplier tiers between compound specialists and conventional rubber processors.
ECE Regulation 48 visibility performance thresholds are harmonizing with emerging automated driving sensor cleaning mandates across European assembly platforms. Suppliers must now validate swept area compliance simultaneously with optical sensor clearance protocols. Germany's KBA type-approval processes are experiencing backlog pressures from dual-certification submission volumes.
Fleet procurement teams are unbundling blade replacement from scheduled maintenance contracts. Commercial vehicle operators in Brazil now source wiper components through direct B2B platforms rather than dealer-integrated service packages. This disintermediation is most visible among long-haul trucking fleets operating under ANVISA-mandated visibility audit regimes.
Wiper Systems Market Segmentation
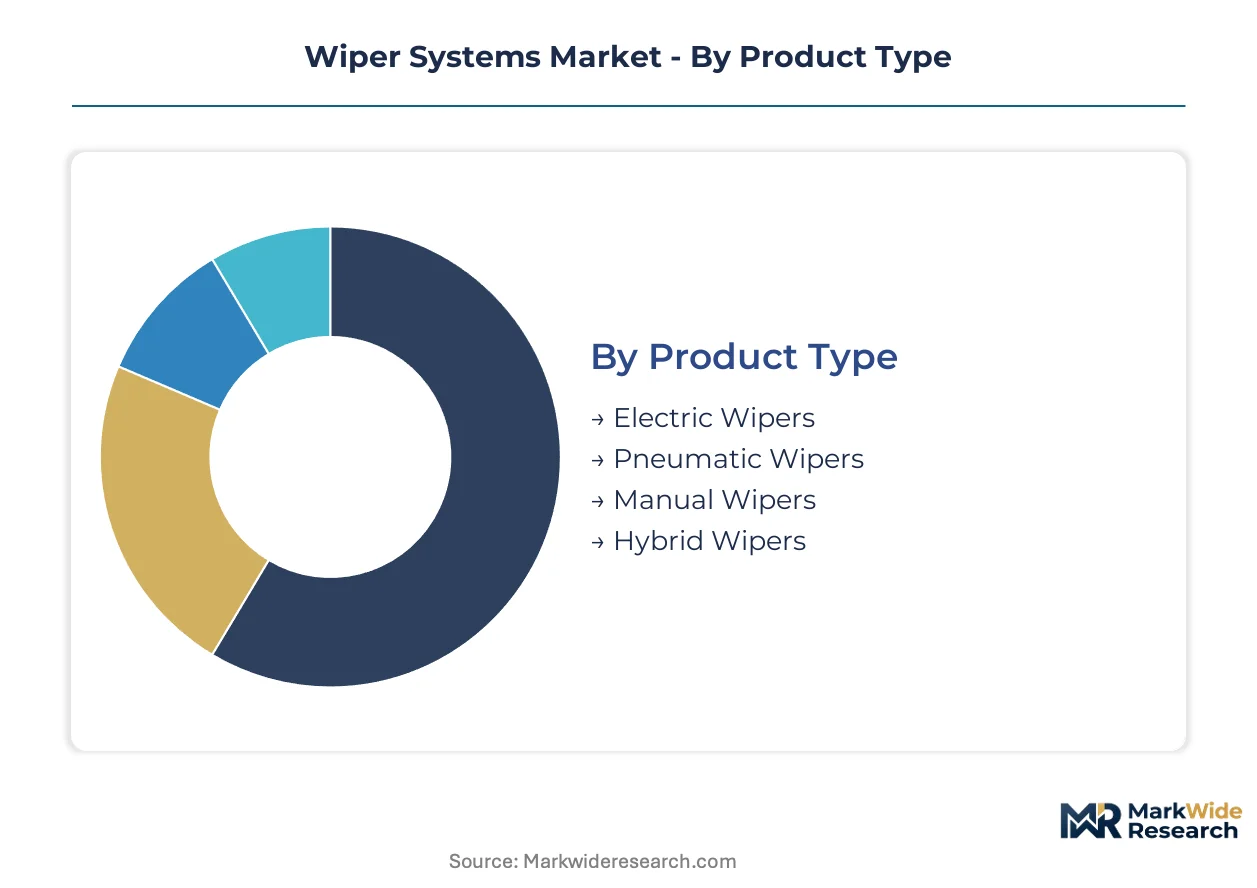
Wiper system architectures fragment across four intersecting dimensions that reshape procurement patterns and margin structures. Product type determines electromechanical complexity and service interval economics. Technology tier separates commodity replacement cycles from sensor-integrated premium fitment.
Product Type:
Electric wiper configurations dominate domestic assembly corridors in Germany and Japan, while pneumatic designs concentrate in heavy-duty export platforms serving Brazilian and Indian commercial fleets.
- Electric Wipers:Brushless DC motor assemblies with integrated control modules sweep at calibrated frequencies between 30 and 65 cycles per minute. Passenger vehicle OEMs in Germany's premium assembly corridor specify these for rain-sensor compatibility and electromagnetic interference suppression. The ANVISA-mandated visibility audits across Brazilian commercial fleets are compressing replacement cycles for conventional electric armatures.
- Pneumatic Wipers:Compressed-air drive mechanisms engineered for heavy-truck applications where electrical system redundancy is critical. Indian heavy-duty truck assemblers specify pneumatic systems for BIS-certified platforms operating in high-dust corridors. Raw material volatility in natural rubber and steel supply chains directly compresses margin structures for tier-two pneumatic component suppliers.
- Manual Wipers:Hand-operated lever mechanisms retain fitment in low-cost motorcycle and agricultural equipment segments.
- Hybrid Wipers:Dual-mode electropneumatic architectures serving specialized off-road military and mining vehicle platforms.
Electric wiper systems command the established base. The steepest expansion runs through pneumatic configurations in heavy-duty commercial applications.
End User:
Procurement authority concentrates differently across volume tiers, with OEM direct sourcing favoring certified tier-one integrators while aftermarket channels fragment across distributor hierarchies.
- OEMs:Original equipment manufacturers specify complete wiper modules through IATF 16949-qualified tier-one suppliers. Germany's KBA type-approval processes validate swept area compliance for direct vehicle platform integration. Certification timeline compression is straining quality engineering bandwidth for eighteen-month IATF revalidation cycles.
- Aftermarket Providers:Independent distributors and service networks sustain higher volume velocity than OEM fitment due to wear-driven replacement cycles. Fleet operators in Brazil now source blades through direct B2B platforms rather than dealer-integrated service packages under ANVISA audit regimes.
- Vehicle Assemblers:Contract manufacturers and kit assembly operations in emerging markets procure sub-assemblies for localized fitment.
- Tier-1 Suppliers:System integrators combining motor, linkage, and blade carrier technologies for OEM platform delivery.
Aftermarket providers capture the volume base. OEM direct sourcing maintains the steepest technology climb.
Technology:
Cost-to-performance stratification separates legacy mechanical systems from sensor-integrated automation, with adaptive architectures commanding premium positioning in European premium vehicle assembly.
- Conventional:Fixed-speed electromechanical systems with manual operator control retain dominance in economy passenger and commercial vehicle segments. Conventional arm designs face performance ceilings below minus twenty degrees Celsius in Scandinavian and Canadian cold-climate corridors.
- Adaptive:Variable-speed response systems adjusting sweep frequency to precipitation intensity without full sensor integration. Japanese OEM service networks deploy adaptive modules across mid-tier passenger platforms.
- Automatic Rain Sensing:Optical sensor-driven modules eliminating manual operator intervention. Germany's premium passenger vehicle assembly corridor captures disproportionate demand share for integrated sensor-driven automation. Legacy integration complexity forces these modules to interface with decade-old vehicle network architectures lacking standardized CAN bus protocols.
- Integrated:Multi-function assemblies combining wiper, washer, and sensor cleaning for automated driving visibility compliance. ECE Regulation 48 harmonization with sensor cleaning mandates is creating dual-certification submission backlogs at Germany's KBA.
Conventional technology commands the installed base. Automatic rain sensing delivers the steepest margin expansion.
Application:
Vehicle category determines swept area specifications, operating duty cycles, and regulatory compliance thresholds across distinct safety regimes.
- Passenger Vehicles:Light-duty applications with standardized swept area requirements under NHTSA FMVSS 104 in the US and ECE Regulation 48 in Europe. Rain-sensing integrated modules are capturing disproportionate demand share in Germany's premium passenger vehicle assembly corridor.
- Commercial Vehicles:Heavy-duty platforms with extended sweep armatures and pneumatic backup systems. Brazilian fleet operators are expanding wiper replacement schedules amid stricter ANVISA visibility safety protocols.
- Off-Road Vehicles:Mining, construction, and agricultural equipment requiring sealed electromechanical housings for dust and vibration resistance.
- Motorcycles:Compact single-blade configurations with minimal sweep arcs, predominantly manual or basic electric drive.
Passenger vehicles command the unit volume base. Commercial vehicle applications are climbing fastest on regulatory replacement mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet procurement teams in Brazil and assembly engineers in Germany represent the dominant buyer archetypes, with regulatory pressure and premium vehicle production driving distinct procurement patterns across high-volume corridors.
Germany
Premium passenger vehicle assemblers specify rain-sensing integrated modules at disproportionate rates. KBA type-approval processes validate swept area compliance alongside emerging sensor cleaning mandates. Stuttgart and Munich anchor the premium assembly corridor where adaptive automation bundles command premium positioning.
Brazil
Commercial fleet operators expand wiper replacement schedules under stricter visibility protocols. ANVISA mandates compress aftermarket service intervals for long-haul trucking fleets. São Paulo and Rio Grande do Sul concentrate heavy-truck assembly where direct B2B procurement platforms disintermediate traditional dealer networks.
United States
NHTSA Federal Motor Vehicle Safety Standard 104 shapes design validation requirements for North American vehicle platforms. Brushless DC motor architectures displace conventional brushed designs across OEM platforms. Detroit and the Southeast manufacturing belt concentrate electromechanical module production for domestic light-duty fitment.
Japan
OEM service networks enable dense aftermarket penetration through direct-to-fleet replacement programs. JIS D 5703 standards impose visibility performance thresholds comparable to European harmonized requirements. Nagoya and Osaka anchor mid-tier passenger platforms where adaptive modules deploy without full sensor integration.
India
Heavy-duty truck assemblers specify pneumatic wiper systems for BIS-certified platforms operating in high-dust corridors. Commercial vehicle penetration creates first-mover advantage windows for qualified suppliers. Maharashtra and Gujarat concentrate heavy-truck fitment where compressed-air drive mechanisms ensure electrical system redundancy.
Wiper Systems Market Key Industry Players
Player mix skews toward diversified automotive component conglomerates with captive electromechanical capabilities. Tier-one integrators dominate OEM direct sourcing through IATF 16949 qualification, while tier-two component suppliers face consolidation pressure from certification timeline compression. Two strategic archetypes define competitive positioning: integrated module specialists leveraging sensor-driven automation, and aftermarket volume players optimizing replacement cycle economics. M&A activity concentrates on quality system acquisition, while geographic expansion targets emerging market certification windows.
Among diversified automotive suppliers, Robert Bosch GmbH and Valeo S.A. exemplify the integrated module archetype, with Denso Corporation occupying a position in dense aftermarket service networks. Bosch represents German-based electromechanical conglomeration with captive motor production. Valeo anchors French adaptive technology positioning through rain-sensing leadership. Denso sits within Japanese OEM-integrated supply structures. These three entities collectively illustrate the geographic and capability stratification shaping tier-one procurement authority.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Valeo S.A. |
| Denso Corporation |
| Mitsuba Corporation |
| HELLA GmbH & Co. KGaA |
| Trico Products |
| ASMO Co., Ltd. |
| Magneti Marelli S.p.A. |
| DOGA SA |
| Others |
Cost & Logistics Intelligence
Sixty-day motor inventory cycles at Stuttgart assembly plants concentrate pricing leverage among German electromechanical suppliers, compressing margin negotiation space for tier-two blade manufacturers in Brazil and India. This lead-time asymmetry rewards captive motor producers with cost-plus contract security while fragmenting replacement blade pricing across spot-market rubber sourcing.
Pricing Analysis
Cost-plus contracts with natural rubber indexation dominate OEM supply agreements, locking in margin protection for compound specialists while exposing tier-two processors to commodity volatility. Price differentiation rests on IATF 16949 certification grade and after-sales bundling intensity. Cost compression in conventional armature segments is intensifying because Brazilian fleet operators disintermediate dealer networks. Aftermarket distributors exhibit highest price sensitivity; premium sensor-integrated module buyers show lowest.
Supply Chain Analysis
Strait of Malacca transit underwrites Southeast Asian rubber flows to European compounders, creating logistics vulnerability for blade manufacturers. Supply concentrates in Germany for brushless DC motors, China for stamped steel linkages, and Thailand for natural rubber feedstock. Raw material dependencies span natural rubber, cold-rolled steel, and rare-earth motor magnets. Single-source vulnerability runs through German captive motor production. Distribution runs through OEM tier-one integrators for original fitment and independent distributors for aftermarket replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from sensor-cleaning convergence threatening standalone wiper module relevance. Defense requires repositioning around integrated visibility systems rather than discrete electromechanical components.
For Market Incumbents: Shield core motor production through backward integration into rare-earth magnet sourcing. Lock in IATF 16949 revalidation ahead of eighteen-month audit windows to freeze out uncertified competitors. The priority lever sits with sensor-cleaning R&D partnerships that preempt pure-play LiDAR washer entrants from capturing automated driving visibility budgets.
For New Entrants and Emerging Players: Anchor in Indian heavy-duty pneumatic fitment where BIS certification windows remain open and electrical redundancy requirements favor compressed-air architectures. White-space targets include direct-to-fleet B2B platforms in Brazilian long-haul trucking and silicone blade compound specialization for high-UV climates. Go-to-market angle: unbundle blade replacement from scheduled maintenance contracts.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because certification timeline compression will force tier-two exits and concentrate procurement authority among IATF-qualified integrators. Acquisition target archetype: mid-cap silicone compounders with fleet distribution relationships. Signal to watch: KBA dual-certification backlog duration as proxy for integrated module demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Magnet Supply | Captive motor producers in Germany secure margin control against commodity volatility. |
| Sensor-Cleaning Convergence R&D Partnership | Integrated module specialists preempt pure-play LiDAR washer entrants from visibility budgets. |
| Direct-to-Fleet B2B Platform Launch | Brazilian commercial operators bypass dealer networks under ANVISA audit regimes. |
| Silicone Compound Specialization | Extended-life formulations capture fleet replacement cycles in high-UV corridors. |
| IATF 16949 Certification Pre-Emption | Early revalidation locks out uncertified competitors from OEM sourcing pools. |
Research Approach
Cross-validation between Tier 1 supplier procurement interviews and vehicle production database triangulation anchors the qualitative findings in this study. Primary fieldwork encompassed OEM platform engineers, aftermarket distributor operations heads, fleet procurement managers, and IATF audit specialists. Secondary sources span NHTSA FMVSS 104 filings, KBA type-approval registries, ANVISA commercial vehicle safety directives, and customs trade records for rubber and steel inputs. Bottom-up segmentation modeling and top-down market sizing were reconciled across analysis approaches.
Sensitivity analysis around raw material price bands and regulatory implementation timelines stress-tested projection robustness. The analytical framework disaggregates volume and value across product type, technology tier, end-user channel, and regional production cluster throughout the forecast period. CAGRs were derived from fitted trend extrapolation against historical replacement cycle data. Industry-specific inputs include ANVISA audit compliance rates and rain-sensor bundle penetration in German premium assembly.
Decision-makers should treat outputs as directional under stable regulatory implementation assumptions; material deviation in ANVISA enforcement intensity or automated driving standard timelines would warrant model refresh. Practitioners should keep alternative scenarios live as sensor-cleaning mandate harmonization and rare-earth supply chain reconfiguration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Vietnam Commercial Vehicles Lubricants Market
Automotive Parts
Passenger Car Motor Oil Market
Automotive Parts
Automotive Fuel Rail Market
Automotive Parts
Global Automotive Brake Hose Market
Automotive Parts
Tire Vulcanizer Market
Automotive Parts
Mobile Emission Catalysts Market
Automotive Parts
Automotive Differential Housing Market
Automotive Parts
Indonesia Automotive Engine Oils Market
Automotive Parts
Automotive Electric HVAC Compressor Market
Automotive Parts
Cabin Air Filter Housing Replacement Parts Market
Automotive Parts
US Automotive Parts Magnesium Die Casting Market
Automotive Parts
South America Automotive Engine Oils Market
Automotive Parts
Heavy Duty Engines Market
Automotive Parts
Global Automotive Plain Carbon ERW Tubes Market
Automotive Parts
Brazil Automotive Hydraulic Actuators Market
Automotive Parts
South America Passenger Vehicles Lubricants Market