
 Treasury Management Market | 2026-2036
Treasury Management Market Size, Share, and Industry Trends Forecast 2026-2036
Treasury Management Market Intelligence
Multi-source vendor strategies is rebalancing how corporate treasuries procure liquidity and risk management infrastructure. FIS Global anchors its position through deep ERP integration capabilities across Fortune 500 accounts. Kyriba leverages cloud-native architecture to compete in mid-market segments previously served by on-premises installations. Bloomberg Treasury dominates real-time market data feeds that underpin foreign exchange and investment management workflows.
Treasury management encompasses the strategic oversight of corporate liquidity, financial risk, and capital allocation through integrated software platforms that automate cash positioning, hedging execution, and regulatory reporting. Core systems typically process multi-currency cash flows across SWIFT, ACH, and real-time payment rails while maintaining audit trails for SOX and Basel compliance. Cloud-based deployment now leads new installations as corporate IT departments prioritize API-first architectures that connect treasury workstations with ERP and banking systems. Within solution offerings, cash management and liquidity management sustain the largest revenue pools, while risk management registers the fastest expansion as interest rate volatility drives hedging automation demand.
The US Federal Reserve's instant payment infrastructure, alongside SEC disclosure requirements for liquidity risk, shapes how vendors architect real-time reporting modules. In Europe, the EU AI Act and GDPR constrain how machine learning models flag fraud or optimize working capital, forcing explainable algorithm design into product roadmaps. Stakeholders must weigh data sovereignty commitments against the interoperability gains of multi-bank API networks.
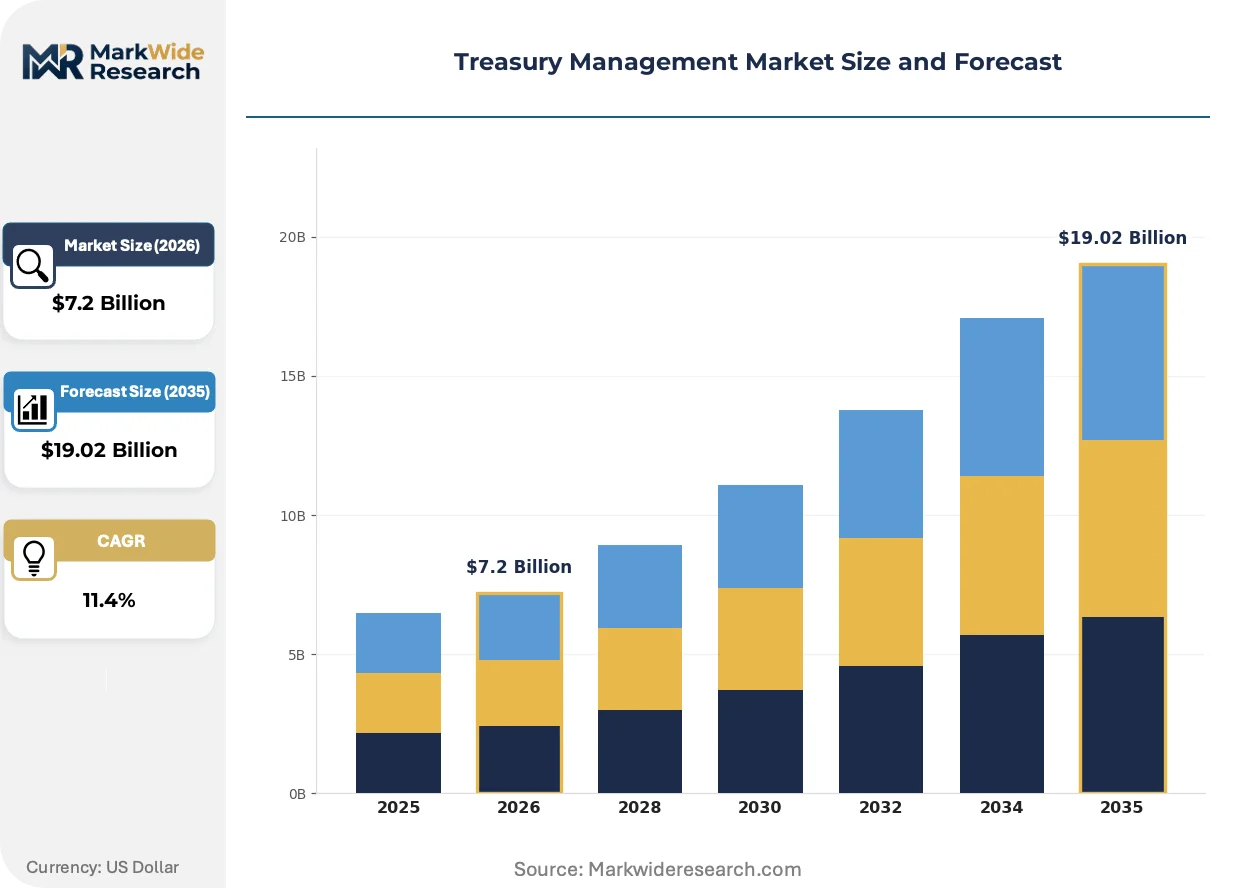
Market Dynamics
Cloud-native treasury platforms are electrifying competitive positioning by compressing deployment cycles from eighteen months to six weeks, forcing incumbent vendors to re-architect legacy stacks or cede mid-market accounts to API-first challengers.
Growth Catalysts
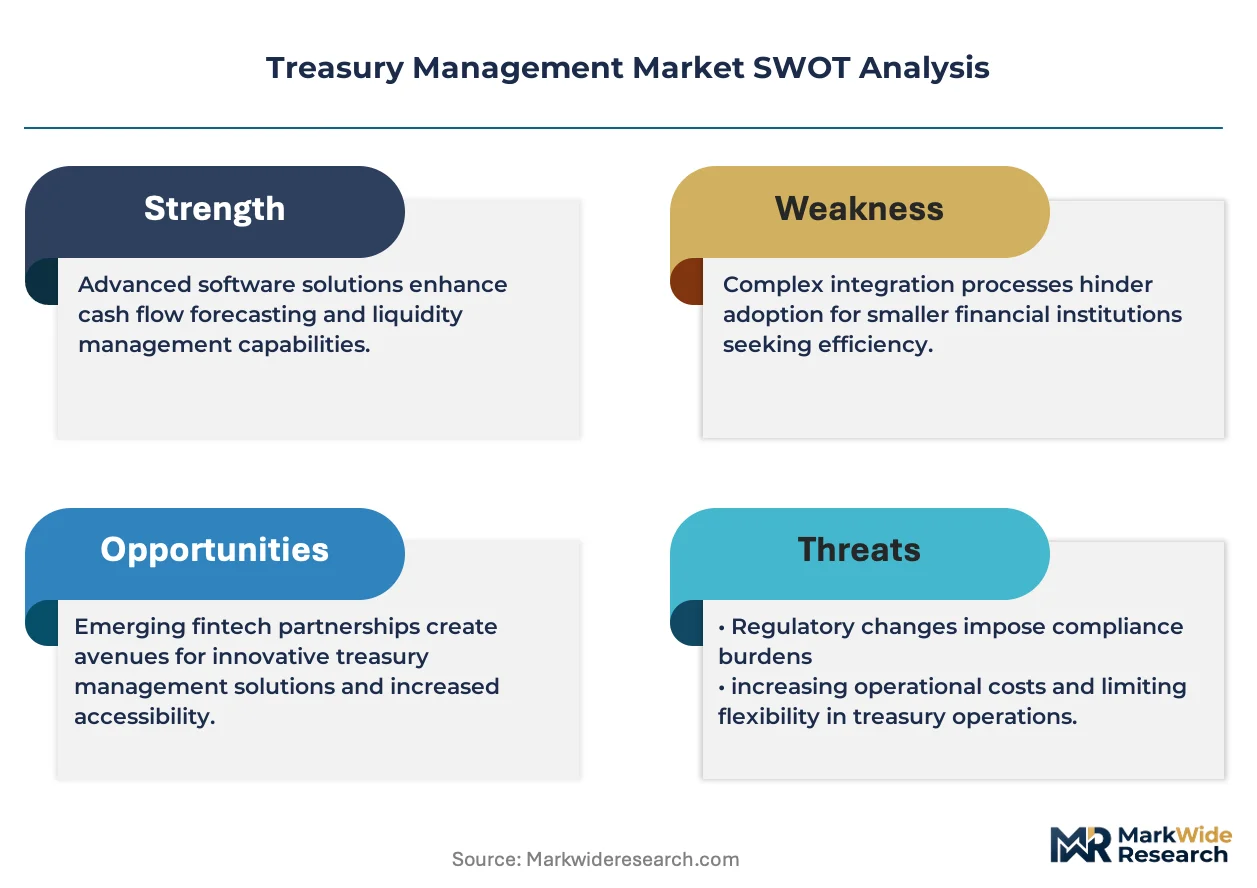
- Instant payment infrastructure:The US Federal Reserve's FedNow rail enables real-time cash positioning, compelling treasuries to replace batch-processed systems with streaming liquidity dashboards.
- Interest rate volatility:Hedging automation demand from healthcare and technology corporations accelerates adoption of AI-driven risk management modules.
- GDPR and EU AI Act:European compliance mandates for algorithmic transparency and data residency are reshaping vendor selection criteria toward explainable machine learning architectures.
Market Restraints
- Legacy ERP integration costs:SAP and Oracle system migrations consume 40-60% of implementation budgets, delaying cloud transitions for Fortune 500 accounts.
- SWIFT network concentration:Dependency on Belgian messaging infrastructure creates geopolitical exposure and operational single-point-of-failure risk.
- Talent scarcity in quantitative finance:Shortage of professionals combining treasury operations expertise with Python and API engineering skills constrains platform customization.
Strategic Opportunities
- Embedded finance convergence:Treasury APIs integrating with procurement and supply chain platforms unlock working capital optimization for manufacturing verticals.
- India's digital rupee infrastructure:RBI's central bank digital currency pilot creates first-mover advantage for real-time liquidity management in emerging market treasury operations.
- CSRD sustainability reporting:EU corporate sustainability disclosure rules mandate granular cash flow transparency, expanding demand for carbon-adjusted treasury analytics.
Industry Challenges
- Multi-bank API fragmentation:Lack of standardized data formats across JPMorgan, Citi, and BNP Paribas connectivity layers forces redundant integration engineering.
- SOX compliance timeline compression:Accelerated audit trail requirements for algorithmic trading decisions strain documentation workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Treasury Management Market |
| Market Size in 2026 | $7.2 Billion |
| Market Size in 2035 | $19.02 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Hosted, Private Cloud Solution Offering: Cash Management, Risk Management, Payment Processing, Compliance Management, Liquidity Management, Investment Management Application: Cash Forecasting, Debt Management, Fraud Detection, Working Capital Optimization, Foreign Exchange Management, Capital Planning End User: Financial Institutions, Corporate Treasury Departments, Government Agencies, Non-Profit Organizations, Asset Management Firms |
| Companies Covered | FIS Global, Kosh AI, Cobase, HighRadius, Brex, GTreasury, Kyriba, Bloomberg Treasury, ION Treasury, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Treasury Management Market Strategic Shifts & Innovations
Generative AI is compressing the analyst-to-automation ratio in treasury operations, while open banking mandates and embedded finance architectures are dissolving traditional boundaries between corporate treasury, procurement, and supplier finance functions.
Real-time cash forecasting engines powered by machine learning are electrifying liquidity optimization by ingesting ERP, banking, and market data streams to project positions within 2% accuracy across 90-day horizons. Mid-market healthcare and technology treasuries are adopting these tools fastest, replacing spreadsheet-based weekly forecasts. The structural consequence is collapsing headcount in treasury operations centers while elevating strategic finance roles.
The EU AI Act's risk-based classification system is forcing explainability into fraud detection and working capital algorithms deployed across European operations. Vendors must now document decision trees and maintain human-in-the-loop overrides for high-risk automated transactions. Treasury platforms serving multinational corporations are responding by segregating European data processing and embedding audit logging that satisfies both GDPR and upcoming SEC climate disclosure rules.
Subscription-based pricing for treasury workstations is displacing perpetual license models as corporate buyers prioritize operational expenditure treatment and faster vendor switching. Mid-market enterprises in the United States are driving this shift, demanding month-to-month contracts with usage-based scaling. Channel partners and systems integrators are restructuring compensation around customer lifetime value rather than upfront implementation fees.
Treasury Management Market Segmentation
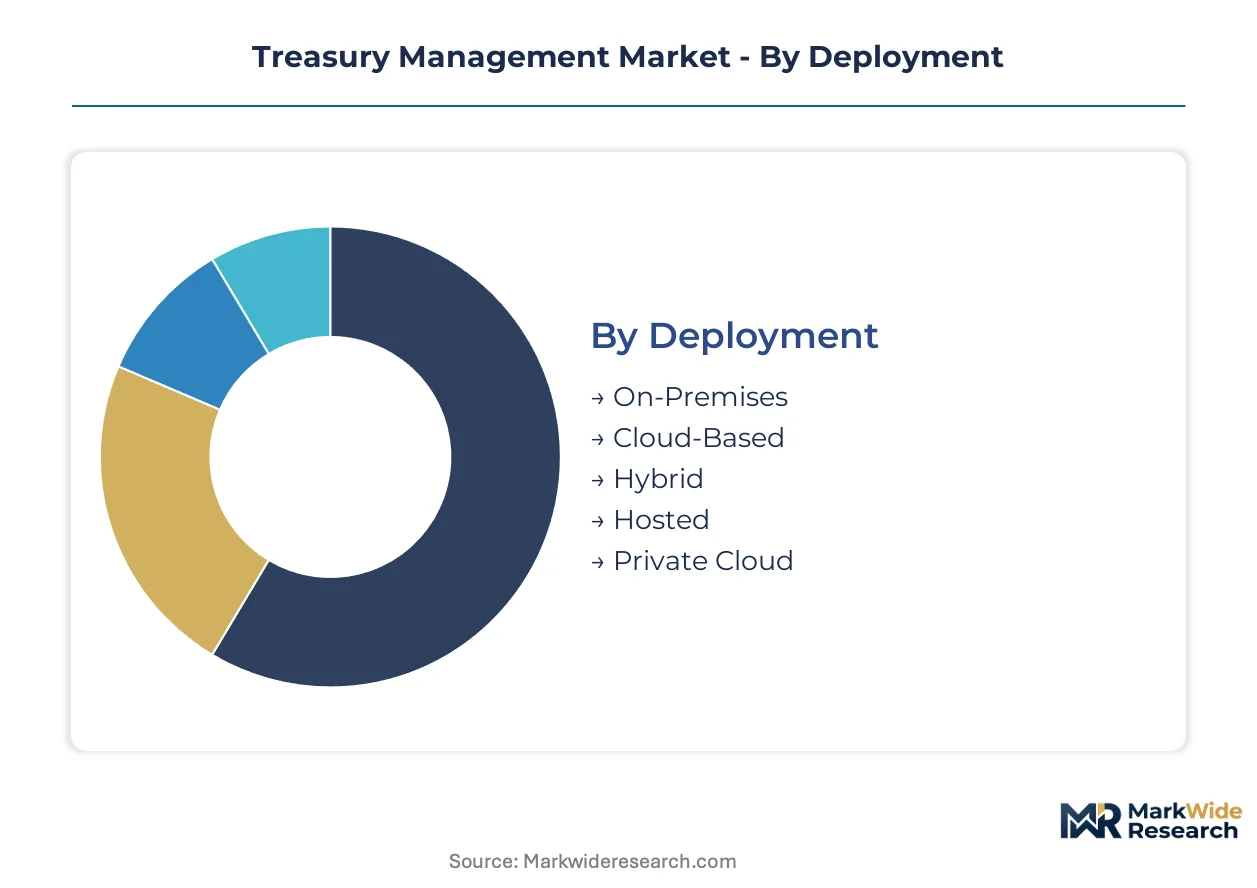
Treasury management platforms serve fundamentally different buyer archetypes across deployment models, functional modules, and organizational maturity levels. Segmentation reveals where cloud-native architectures displace legacy installations and which compliance workflows command premium pricing.
Deployment:
Enterprise IT departments select deployment architectures based on data residency requirements, ERP integration complexity, and capital expenditure preferences.
- Cloud-Based:Multi-tenant SaaS architectures compress implementation timelines through API-first connectivity with banking networks and ERP systems. Mid-market technology and healthcare corporations in the United States are migrating fastest, driven by FedNow real-time payment adoption and subscription pricing preferences.
- On-Premises:Legacy installations persist among Fortune 500 accounts with complex SAP and Oracle ecosystem dependencies. These deployments consume substantial implementation budgets for SWIFT gateway configuration and SOX-compliant audit infrastructure.
- Hybrid:Split architectures segregate sensitive payment authorization workflows on-premises while leveraging cloud analytics for cash forecasting. European multinational corporations favor this model to satisfy GDPR data residency mandates without sacrificing machine learning capabilities.
- Hosted:Single-tenant managed services deliver dedicated infrastructure without internal data center overhead. Asset management firms with specialized compliance requirements select this path for regulatory examination readiness.
- Private Cloud:Dedicated cloud environments within hyperscaler facilities address data sovereignty concerns for government agencies and financial institutions subject to national banking regulator oversight.
Cloud-Based deployments lead volumes today; Hybrid architectures are gaining share fastest among European regulated entities.
Solution Offering:
Functional module selection correlates with treasury organizational maturity and exposure to interest rate volatility.
- Cash Management:Core modules automate multi-currency position reporting, bank reconciliation, and liquidity pooling across dispersed accounts. Corporate treasury departments in manufacturing verticals prioritize these capabilities for working capital visibility.
- Risk Management:Hedging automation platforms integrate derivative execution, counterparty exposure monitoring, and hedge accounting documentation. Healthcare and technology corporations facing interest rate volatility are expanding adoption fastest.
- Payment Processing:Payment factory modules consolidate disbursement workflows across ACH, wire, and real-time rails. Financial institutions embed these capabilities for corporate banking clients.
- Compliance Management:Regulatory reporting engines automate SOX documentation, Basel liquidity calculations, and CSRD sustainability disclosures. European operations mandate these modules for EU AI Act algorithmic transparency requirements.
- Liquidity Management:Cash concentration and notional pooling tools optimize trapped cash across jurisdictional boundaries. Multinational corporations with emerging market subsidiaries deploy these for India digital rupee and similar CBDC preparation.
- Investment Management:Portfolio accounting and money market fund execution modules serve asset management firms and large corporate treasuries with substantial short-term investment programs.
Cash Management sustains the largest revenue pool; Risk Management is expanding most quickly as hedging automation demand accelerates.
Application:
Workflow automation priorities diverge between defensive risk mitigation and offensive capital efficiency objectives.
- Cash Forecasting:Machine learning engines ingest ERP, banking, and market data streams to project liquidity positions within narrow accuracy bands. Mid-market healthcare treasuries are replacing spreadsheet-based weekly forecasts with these tools.
- Debt Management:Capital structure optimization modules track covenant compliance, interest rate swap effectiveness, and refinancing timelines. Corporate treasury departments with leveraged balance sheets depend on these for SEC disclosure preparation.
- Fraud Detection:Behavioral analytics and anomaly detection flag suspicious payment instructions before execution. EU AI Act explainability requirements are reshaping algorithm design toward documented decision trees.
- Working Capital Optimization:Supply chain finance and dynamic discounting tools integrate procurement data with treasury liquidity. Manufacturing verticals deploy these for embedded finance convergence.
- Foreign Exchange Management:Exposure netting, forward execution, and hedge accounting modules address currency volatility for multinational operations.
- Capital Planning:Strategic allocation tools model dividend capacity, share repurchase capacity, and M&A funding availability.
Cash Forecasting dominates current deployment; Working Capital Optimization shows the steepest expansion trajectory as procurement-treasury boundaries dissolve.
End User:
Organizational type determines regulatory burden, transaction complexity, and vendor relationship dynamics.
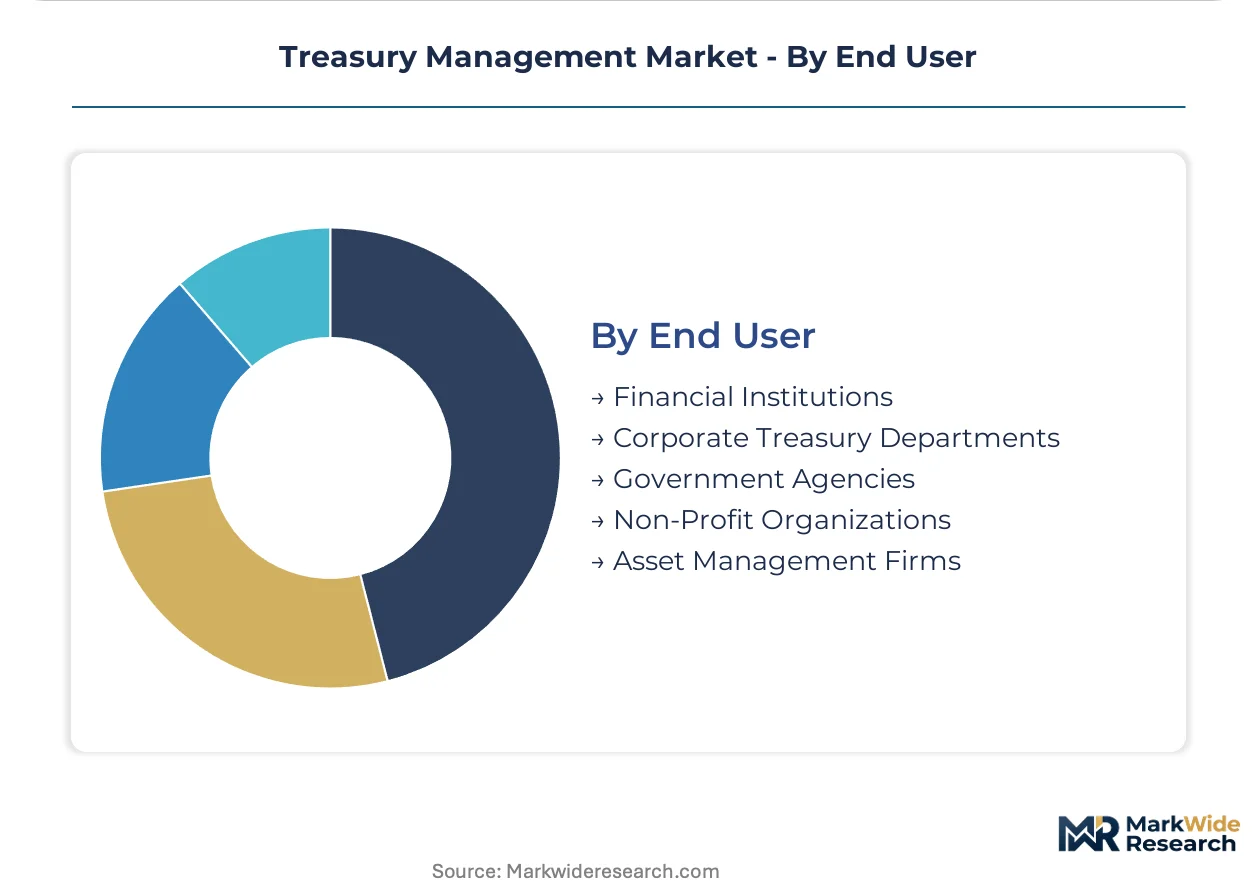
- Corporate Treasury Departments:Mid-market and large enterprise finance functions seeking ERP integration and real-time bank connectivity represent the core demand pool for cloud-native platforms.
- Financial Institutions:Banks and credit unions require treasury infrastructure for their own liquidity management and for white-labeled corporate banking services.
- Government Agencies:Public sector treasuries prioritize data sovereignty, audit transparency, and compliance with federal procurement regulations.
- Non-Profit Organizations:Endowment management and grant compliance workflows drive specialized requirements for restricted fund tracking.
- Asset Management Firms:Investment advisors and fund managers need portfolio-level cash positioning integrated with trading and settlement systems.
Corporate Treasury Departments anchor current demand; Financial Institutions are climbing the fastest as embedded finance partnerships proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New York City's financial services corridor anchors treasury management platform deployment, with corporate headquarters density driving real-time liquidity infrastructure demand across North America and Europe.
United States
Technology and healthcare corporations in Silicon Valley and Boston are modernizing legacy ERP integrations at the fastest pace. The Federal Reserve's FedNow instant payment infrastructure compels treasury departments to replace batch-processed systems with streaming dashboards. Chicago's derivatives trading ecosystem supports sophisticated hedging automation module adoption.
Germany
Industrial manufacturing conglomerates in the Ruhr region and Bavaria prioritize working capital optimization tools integrated with procurement systems. The EU AI Act's algorithmic transparency mandates reshape vendor selection toward explainable machine learning architectures. Frankfurt's banking hub concentration accelerates multi-bank API connectivity standardization efforts.
United Kingdom
Asset management firms in the City of London drive investment management module demand for portfolio-level cash positioning. The Financial Conduct Authority's operational resilience requirements pressure treasuries toward cloud-native disaster recovery architectures. Edinburgh's fund administration cluster adopts subscription-based treasury workstation pricing fastest.
India
Mid-market enterprises in Mumbai and Bangalore accelerate cloud-native platform adoption as the Reserve Bank of India's digital rupee pilot creates first-mover opportunity. SEBI's disclosure requirements for liquidity risk reshape reporting module specifications. Hyderabad's technology corridor hosts emerging fintech partnerships embedding treasury APIs into supply chain finance.
Singapore
Multinational corporate regional headquarters drive liquidity management demand for cross-border cash concentration across Southeast Asian subsidiaries. The Monetary Authority of Singapore's digital payment infrastructure mandates accelerate real-time payment rail integration. The Marina Bay financial district concentrates vendor R&D investment for Asia-Pacific localization.
Treasury Management Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue embedded finance convergence and API-first architectures. The vendor base stratifies across three maturity tiers: legacy ERP-integrated incumbents, cloud-native challengers, and specialized risk management boutiques. Dominant competitive moves include strategic partnerships with banking networks and geographic expansion through regulatory localization.
Within the cloud-native tier, Kyriba and HighRadius exemplify mid-market-focused architectures compressing deployment timelines. FIS Global anchors the ERP-integrated incumbent category through Fortune 500 ecosystem penetration. Bloomberg Treasury occupies the real-time data feed specialization vector, underpinning foreign exchange workflow automation for multinational operations.
| Leading Market Players |
|---|
| FIS Global |
| Kosh AI |
| Cobase |
| HighRadius |
| Brex |
| GTreasury |
| Kyriba |
| Bloomberg Treasury |
| ION Treasury |
| Others |
Cost & Logistics Intelligence
Python-proficient quantitative finance specialists concentrated in London and New York command compensation premiums that widen spreads between premium-tier SaaS subscriptions and economy-tier perpetual licenses. Labor-cost differentials between these financial centers and emerging talent pools in Bangalore and Warsaw directly feed into vendor pricing architectures.
Pricing Analysis
Input-cost pass-through from cloud infrastructure providers and specialized engineering talent drives subscription pricing for treasury platforms. Three-tier pricing structure across premium, standard, and economy levels separates Fortune 500 ERP-integrated deployments from mid-market API-first solutions and basic cash management modules. Price differentiation rests on customization depth and FedNow real-time rail certification. Margins are tightening due to hyperscaler compute cost inflation. Mid-market healthcare treasuries exhibit highest price sensitivity; asset management firms with compliance examination requirements show least.
Supply Chain Analysis
Freight costs for specialized hardware security modules and on-premises server shipments from Taiwan and Germany add geographic premiums to hybrid deployment pricing. Software development centers in India, Poland, and the United States anchor cloud-native platform engineering. Raw material dependencies include cryptographic processors, SWIFT gateway appliances, and hyperscaler compute capacity. Single-source vulnerability concentrates in Belgian SWIFT messaging infrastructure. Distribution runs through direct enterprise sales teams, systems integrator partnerships, and banking channel referrals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Treasury management functions as a stable compounder anchored by persistent regulatory complexity that mandates continuous platform investment regardless of interest rate cycles.
For Market Incumbents: Deepen ERP ecosystem integration moats around SAP and Oracle installations to defend against API-first challengers compressing deployment timelines. Acquire specialized risk management boutiques to fill AI-driven hedging automation gaps. Prioritize EU AI Act compliance documentation as a competitive differentiator in European account retention. For New Entrants and Emerging Players: CSRD in Europe opens a window for carbon-adjusted treasury analytics targeting manufacturing conglomerates in the Ruhr region. India's digital rupee infrastructure creates first-mover opportunity for real-time liquidity management modules. Procurement-treasury convergence in supply chain finance represents the most penetrable white space. Pursue embedded finance partnerships with manufacturing ERP vendors as primary go-to-market angle. For Investors and Strategic Acquirers: Private equity firms with fintech portfolios are the most active acquirer in this space, driving valuation multiples for cloud-native platforms with mid-market recurring revenue bases. Five-to-ten year viability frames around subscription revenue retention and cross-sell velocity into risk management modules. Target acquisition archetype: API-first challengers with FedNow certification and healthcare vertical penetration. Watch for FedNow adoption inflection above fifty percent of corporate treasury departments as signal of platform consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first connectivity with SAP and Oracle ecosystems defends incumbent accounts against cloud-native displacement. |
| Regulatory Localization | EU AI Act explainability documentation opens European public sector procurement channels previously closed to black-box algorithms. |
| Strategic Partnership | Banking network alliances with JPMorgan and BNP Paribas standardize multi-bank API connectivity for mutual clients. |
| Acquisition of Specialist Firm | Machine learning cash forecasting boutiques add predictive capabilities that compress analyst-to-automation ratios. |
| Geographic Expansion | India digital rupee pilot preparation captures emerging market treasury operations migrating from spreadsheet-based systems. |
Research Approach
Direct dialogue with treasury operations directors, ERP integration specialists, banking API product managers, and compliance officers grounded qualitative findings in operational reality. Secondary validation drew from SEC disclosure filings for liquidity risk, SWIFT network traffic reports, and FedNow adoption statistics published by the Federal Reserve. Bottom-up account-level sizing and top-down market aggregation triangulated volume estimates.
Segmentation outputs across deployment architecture, solution module, and organizational maturity dimensioned the analytical framework. CAGRs derived from logistic adoption curves fitted to cloud migration patterns and real-time payment infrastructure rollouts. Interest rate volatility indices and corporate capital expenditure surveys fed scenario-weighted projections across the modeling period.
Revisions become necessary when central bank digital currency timelines accelerate, major ERP vendors release native treasury modules, or geopolitical fragmentation disrupts SWIFT network reliability. Forecasts reflect documented assumptions about technology adoption elasticities and regulatory enforcement intensity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Europe B2B Legal Services Market
Financial Services
ATM Management Service Market
Financial Services
Online Sports Betting Market
Financial Services
India Trade Finance Market
Financial Services
Germany E-Brokerage Market
Financial Services
Global Trust and Corporate Service Market
Financial Services
Global Treasury Management System (TMS) Market
Financial Services
Middle East Financial Consulting Software Market
Financial Services
Mobile Notary Public Market
Financial Services
Power Bank Sharing Services Market
Financial Services
Debt Collection Software and Service Market
Financial Services
Solar Powered ATM Market
Financial Services
Virtual Account Management Software Market
Financial Services
China Supply Chain Financing Market
Financial Services
E-KYC Market
Financial Services
South Korea Factoring Services Market