
 Debt Collection Software and Service Market | 2026-2036
Debt Collection Software and Service Market Size, Share, and Industry Trends Forecast 2026-2036
Debt Collection Software and Service Market Insights
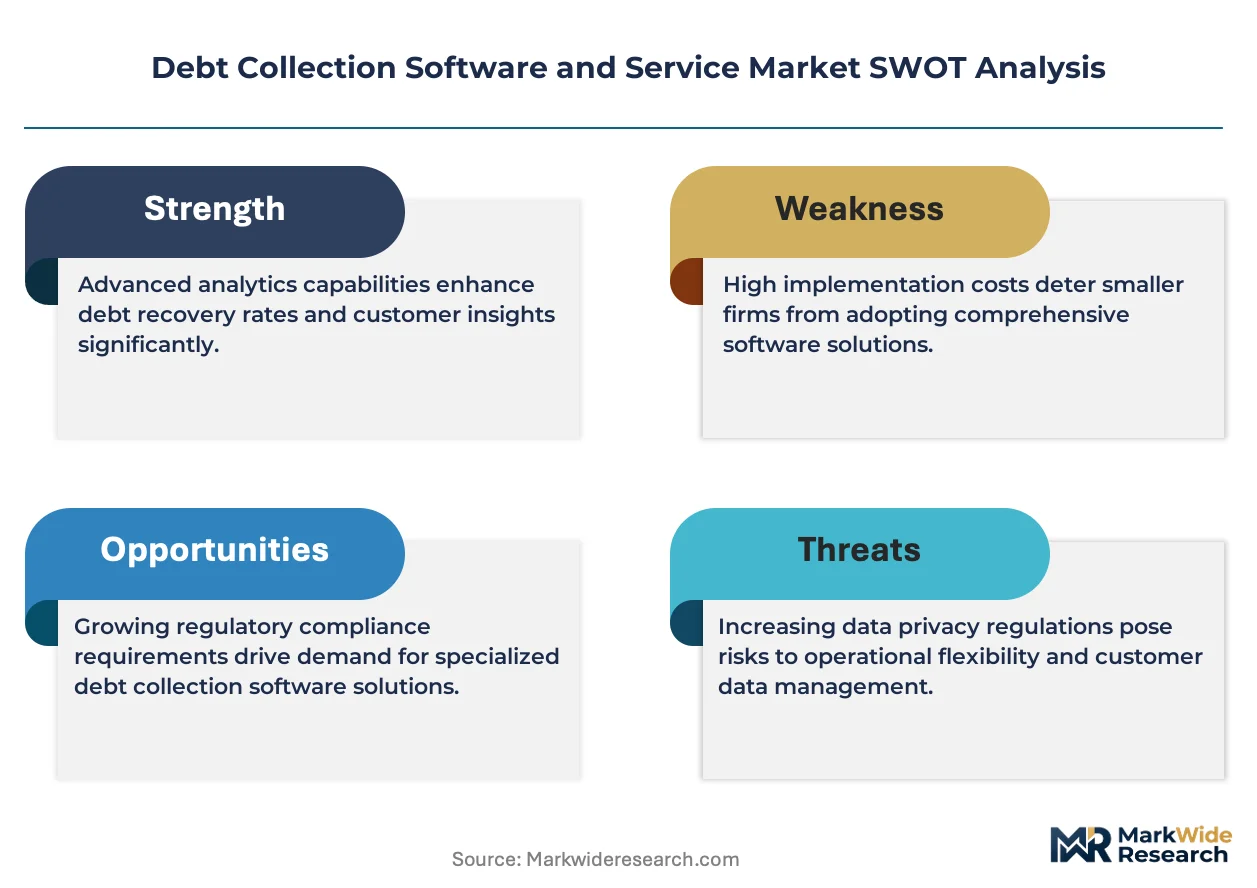
Subscription-based service models is shifting how debt collection vendors monetize their platforms, replacing perpetual licenses with recurring revenue structures. Fair Isaac Corporation leverages its FICO analytics heritage to anchor enterprise risk-scoring workflows within collection cycles. Experian plc competes through integrated credit-data pipelines that feed real-time into recovery decision engines. TransUnion LLC differentiates via identity-verification layers that reduce skip-tracing friction for agency clients.
Debt collection software and services comprise digital platforms and outsourced recovery operations that automate borrower outreach, payment arrangement, and compliance documentation across delinquent accounts. These systems typically process batch portfolio uploads through API-connected dialer and communication modules, scoring accounts by propensity-to-pay algorithms before routing to human agents or self-service portals. Cloud-based deployment leads solution architecture as banks prioritize elastic infrastructure over fixed on-premise capacity, while skip tracing and customer communication platforms capture disproportionate R&D investment due to regulatory pressure on contact frequency and channel consent. Accounts receivable management retains the largest revenue pool among solution types, though payment processing integrations are gaining traction as creditors embed settlement links directly within digital borrower portals.
The Consumer Financial Protection Bureau enforces Regulation F contact rules that limit call frequency and mandate disclosure formats, directly shaping software feature roadmaps for US vendors. State attorneys general in California and New York supplement federal standards with stricter licensing and bonding requirements that raise barriers for service providers. The Federal Trade Commission monitors third-party debt collector communications for deceptive practice claims, pushing vendors toward audit-trail automation and recorded-consent architectures. Stakeholders must weigh compliance automation spend against portfolio recovery rates as regulatory density intensifies across jurisdictions.
Market Dynamics
Cloud migration is compressing deployment cycles for debt collection platforms as financial institutions abandon fixed-capacity data centers for elastic infrastructure that scales with portfolio volatility.
Growth Catalysts
- Regulation F compliance automation:The Consumer Financial Protection Bureau's contact frequency limits are forcing banks to adopt software with built-in call-capping and disclosure formatting, creating mandatory upgrade cycles.
- Skip-tracing AI:Machine learning models trained on alternative data streams are reducing time-to-locate for delinquent borrowers, cutting recovery costs for third-party agencies.
- India:The Reserve Bank of India's tightened non-performing asset recognition norms are pushing domestic lenders toward outsourced recovery operations and digital collection platforms.
Market Restraints
- Input cost volatility:Cloud compute and API connectivity costs from hyperscale providers are squeezing margins for mid-tier software vendors serving regional credit unions.
- Regulatory fragmentation:California's Rosenthal Fair Debt Collection Practices Act imposes stricter licensing than federal standards, raising compliance overhead for multi-state service providers.
- Technical limitation:Legacy core banking systems lacking open API architectures block real-time data feeds into modern collection workflows, delaying implementation timelines.
Strategic Opportunities
- Embedded finance integration:Convergence of payment processing APIs with collection portals enables settlement links within borrower-facing apps, reducing friction in recovery cycles.
- Brazil:ANVISA's expanding oversight of healthcare debt creates demand for specialized compliance modules in medical receivables management.
- Outcome-based pricing:Contingency fee structures tied to recovery rates are displacing flat subscription models, aligning vendor incentives with creditor outcomes.
Industry Challenges
- Compliance engineering talent:Shortage of developers versed in both consumer protection law and scalable system architecture is extending product roadmaps for regulatory features.
- Legacy system integration:Mainframe-based loan servicing platforms at major banks require custom middleware development, inflating implementation costs and failure rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Debt Collection Software and Service Market |
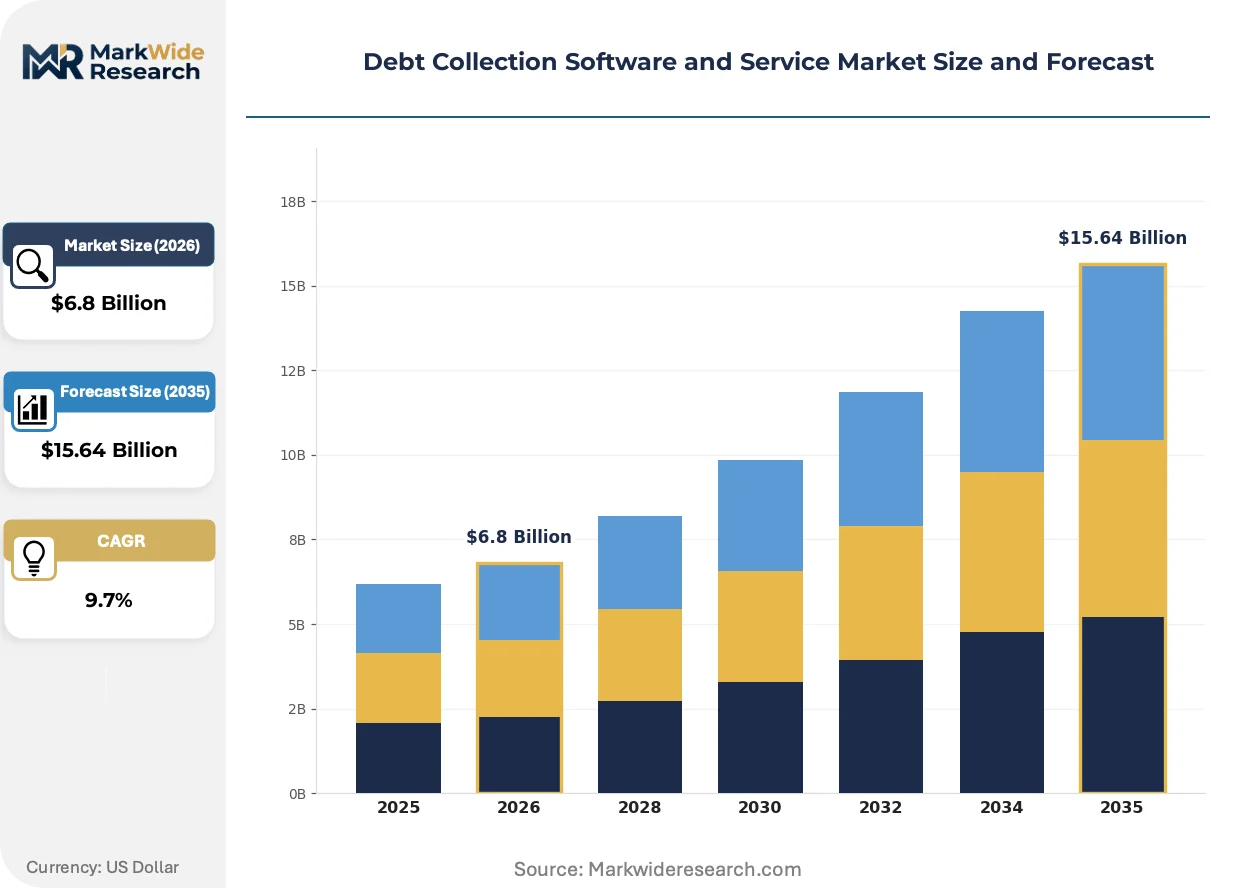
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.64 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, SaaS Solutions Solution Type: Accounts Receivable Management, Skip Tracing, Dialer Systems, Payment Processing, Customer Communication Platforms End User Industry: Telecommunications Providers, Financial Institutions, Utility Service Providers, Educational Institutions, Government Agencies Service Model: Contingency-Based, Fixed-Fee, Subscription-Based, Hybrid Engagements |
| Companies Covered | Fair Isaac Corporation, Experian plc, TransUnion LLC, Equifax Inc., FIS, Fiserv, Inc., CGI, Inc., C&R Software, Prodigal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Debt Collection Software and Service Market Trends and Innovations
Artificial intelligence is restructuring how collection platforms prioritize accounts, moving from static scoring models toward dynamic behavioral prediction that adapts to individual borrower responses.
Conversational AI is electrifying borrower engagement protocols across North American banking networks. Natural language processing engines now handle payment negotiations through voice and chat interfaces, reducing agent headcount requirements. Major credit card issuers are deploying these systems for early-stage delinquencies, compressing cost-per-contact metrics while maintaining regulatory consent documentation.
The European Union's AI Act is imposing risk-classification requirements on automated decision systems used in credit and collections. High-risk algorithmic scoring tools must demonstrate human oversight and bias auditing before deployment. German and French debt purchasers are restructuring their machine learning pipelines to accommodate these conformity assessments, delaying feature rollouts.
Self-service portal adoption is accelerating among millennial and Gen Z borrowers who prefer digital negotiation over phone contact. Mobile-optimized payment arrangement interfaces with embedded document upload are displacing traditional call-center workflows for accounts under ninety days delinquent. This behavioral shift is most pronounced in United States urban markets where smartphone penetration exceeds branch access.
Debt Collection Software and Service Market Segmentation
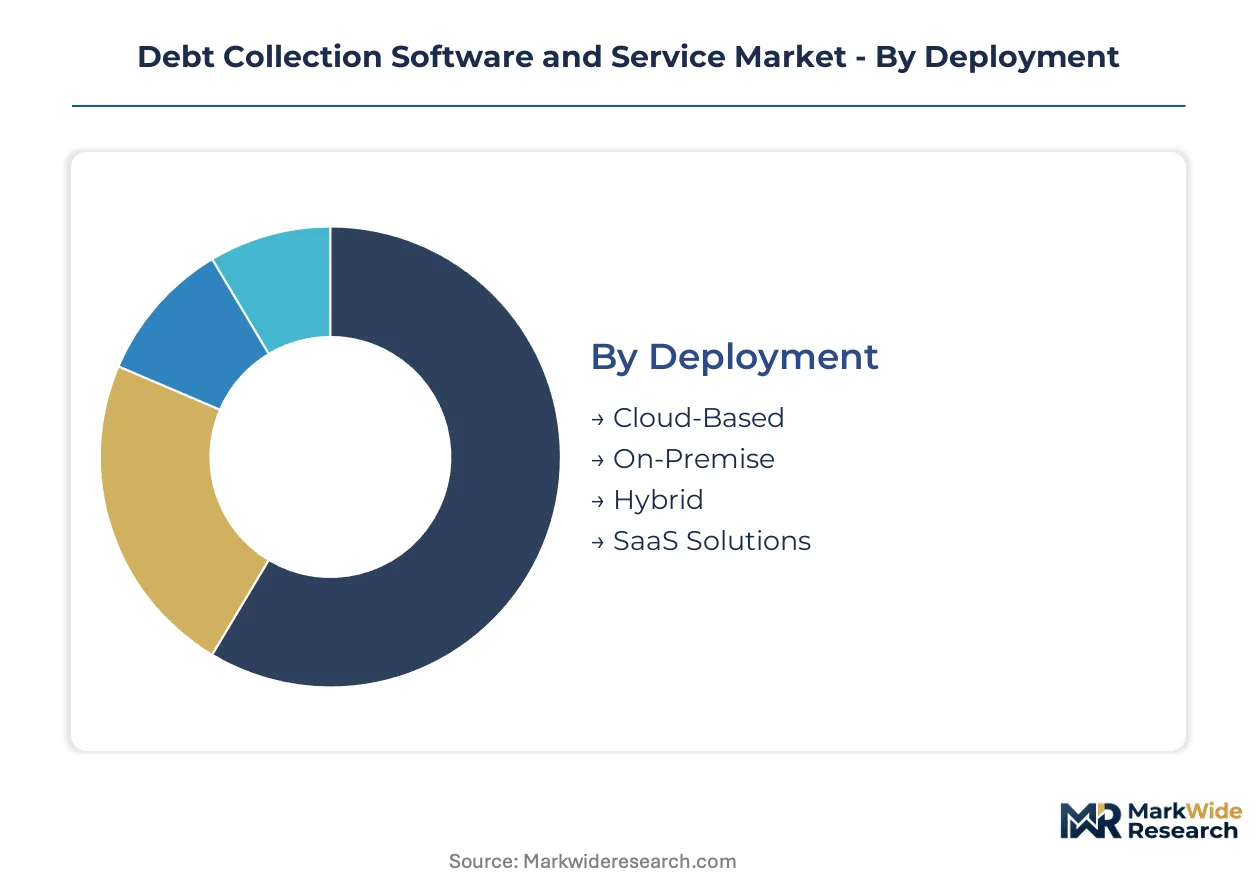
Segmentation in debt collection software and services reveals how procurement priorities diverge across infrastructure preferences, regulatory exposure, and recovery economics. Buyers select deployment architectures and service models based on portfolio volatility, compliance burden, and internal IT maturity rather than feature checklists alone.
Deployment:
Elastic capacity requirements drive infrastructure decisions as portfolio volumes fluctuate with economic cycles and seasonal delinquency patterns.
- Cloud-Based:Elastic infrastructure scales compute and storage with portfolio volatility, eliminating fixed data center commitments. Financial institutions in the United States prioritize this model to satisfy FFIEC guidance on business continuity and data redundancy without capital expenditure.
- On-Premise:Dedicated hardware installations maintain full data sovereignty and direct control over borrower records. European banks under GDPR's data-localization pressures retain on-premise stacks for sensitive credit files, accepting higher fixed costs for compliance certainty.
- Hybrid:Split architectures isolate core borrower data on-premise while pushing communication workloads to cloud dialer platforms. Regional credit unions adopt this compromise to balance regulatory caution with operational flexibility.
- SaaS Solutions:Fully managed software subscriptions transfer infrastructure and update responsibility to vendors. Third-party collection agencies favor this model to accelerate deployment timelines and convert capital expenses to operational budgets.
Cloud-Based leads on scale; SaaS Solutions leads on momentum.
Solution Type:
Functional specialization determines R&D allocation as vendors compete on workflow depth rather than platform breadth.
- Accounts Receivable Management:Comprehensive platforms orchestrate the full recovery lifecycle from initial delinquency flagging through settlement documentation. These systems command the largest revenue pool as they integrate scoring, workflow routing, and compliance audit trails into unified dashboards.
- Skip Tracing:Locator services aggregate alternative data streams—utility records, employment databases, digital footprints—to find displaced borrowers. Machine learning models trained on these datasets are compressing time-to-locate metrics for agencies serving unsecured credit portfolios.
- Dialer Systems:Automated outbound calling infrastructure manages contact cadence within Regulation F frequency limits. TCPA compliance features including consent verification and call-time restrictions dominate vendor differentiation in United States deployments.
- Payment Processing:Embedded settlement engines enable real-time fund capture through borrower-facing portals. Demand concentrates where creditors seek to reduce friction between negotiation agreement and actual fund transfer.
- Customer Communication Platforms:Omnichannel messaging systems coordinate email, SMS, and chat outreach with centralized consent management. These tools are gaining traction among issuers targeting millennial and Gen Z borrowers who prefer digital channels over voice contact.
Accounts Receivable Management leads on scale; Customer Communication Platforms leads on momentum.
End User Industry:
Regulatory density and recovery economics shape industry-specific feature requirements and vendor selection criteria.
- Financial Institutions:Banks, credit unions, and card issuers operate under strict CFPB oversight with mandatory call recording and disclosure formatting. These buyers demand audit-trail automation and integration with core banking systems.
- Telecommunications Providers:Wireless and cable carriers manage high-volume, low-balance delinquencies with compressed recovery windows. Speed-to-contact and self-service portal adoption outrank sophisticated scoring for this segment.
- Utility Service Providers:Electric, gas, and water utilities face state-level shutoff moratoria and seasonal payment patterns. Specialized modules handle payment arrangement scheduling around regulatory protection periods.
- Educational Institutions:Universities and student loan servicers navigate FERPA privacy constraints alongside debt collection rules. Segment-specific compliance features restrict data sharing with third-party agencies.
- Government Agencies:Federal, state, and municipal tax authorities impose unique procedural requirements including administrative wage garnishment workflows. Vendors serving this segment invest heavily in public-sector procurement certification processes.
Financial Institutions leads on scale; Government Agencies leads on momentum.
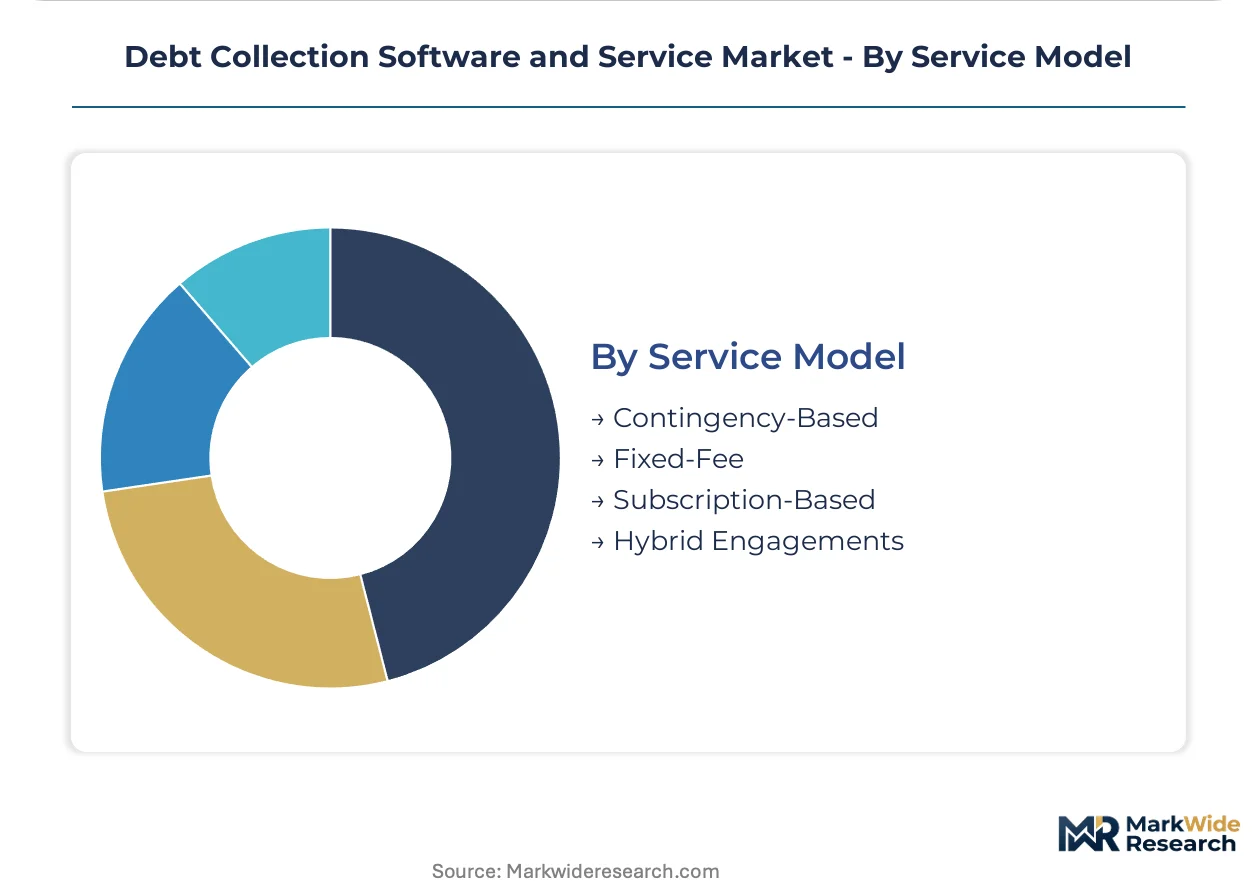
Service Model:
Fee structure alignment determines vendor-creditor incentive compatibility and contract negotiation dynamics.
- Contingency-Based:Recovery fees calculated as percentage of collected amounts transfer performance risk to service providers. Third-party agencies favor this model to align compensation with creditor outcomes, though it compresses margins during low-recovery economic environments.
- Fixed-Fee:Predetermined charges per account or campaign provide cost certainty for creditors with predictable portfolio volumes. Large issuers with in-house collection infrastructure use fixed-fee arrangements for overflow capacity during peak delinquency periods.
- Subscription-Based:Recurring platform access fees replace perpetual licenses with predictable operational expenditure. Software vendors are migrating toward this structure to improve revenue visibility and customer lifetime value metrics.
- Hybrid Engagements:Blended structures combine base subscription fees with performance incentives tied to recovery rates. These arrangements are expanding among mid-tier creditors seeking to balance cost control with vendor accountability.
Contingency-Based leads on scale; Hybrid Engagements leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States deploys cloud-native collection platforms at scale while Germany maintains stricter data-localization requirements that favor hybrid architectures. India's regulatory push on non-performing assets is accelerating outsourced recovery adoption. Brazil's specialized compliance needs in healthcare receivables are creating niche demand.
United States
Financial institutions dominate procurement as card issuers and regional banks replace legacy dialer systems with AI-powered communication platforms. The Consumer Financial Protection Bureau enforces Regulation F contact frequency limits that mandate built-in call-capping features. New York and California clusters concentrate vendor development activity as state attorneys general impose supplemental licensing requirements.
Germany
Debt purchasers restructure machine learning pipelines to accommodate the EU AI Act's risk-classification requirements for automated decision systems. GDPR data-localization pressures retain on-premise stacks for sensitive credit files at major banking groups. Frankfurt's financial services hub hosts compliance-engineering talent pools that extend product roadmaps for conformity assessments.
India
Domestic lenders outsource recovery operations as the Reserve Bank of India tightens non-performing asset recognition norms. The central bank's regulatory pressure pushes mid-tier banks toward digital collection platforms with embedded payment arrangements. Mumbai and Bangalore clusters concentrate fintech development activity for regional language communication modules.
Brazil
Healthcare receivables management demands specialized compliance modules as ANVISA expands oversight of medical debt collection practices. The national health regulator's procedural requirements shape software feature roadmaps for hospital billing systems. São Paulo's financial technology corridor anchors vendor investment in Portuguese-language conversational AI interfaces.
United Kingdom
Buy-now-pay-later providers drive demand for early-stage delinquency workflows as unsecured credit volumes expand. The Financial Conduct Authority's consumer duty rules mandate fair treatment protocols that reshape contact strategies. London's fintech concentration supports real-time credit-data integration with collection decision engines.
Debt Collection Software and Service Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with credit bureaus and core banking vendors commanding enterprise accounts while vertical SaaS providers capture mid-market share. The vendor landscape organizes around three archetypes: data-centric incumbents with credit-information heritage, full-service technology conglomerates with payment processing breadth, and agile specialists with AI-native architectures. Consolidation activity concentrates among data analytics providers seeking to anchor risk-scoring workflows within collection cycles. Strategic partnerships between communication-platform vendors and compliance-automation specialists are accelerating feature integration timelines.
Within the data-centric tier, Fair Isaac Corporation and Experian plc exemplify archetypes that leverage analytics heritage to anchor enterprise workflows. TransUnion LLC occupies a position emphasizing identity-verification layers that reduce operational friction. These three entities represent how credit-information incumbents are restructuring collection software around proprietary data pipelines rather than standalone workflow tools.
| Leading Market Players |
|---|
| Fair Isaac Corporation |
| Experian plc |
| TransUnion LLC |
| Equifax Inc. |
| FIS |
| Fiserv, Inc. |
| CGI, Inc. |
| C&R Software |
| Prodigal |
| Others |
Pricing and Supply Chain Analysis
Regional credit union procurement concentration anchors pricing power for mid-tier SaaS vendors, forcing subscription models toward outcome-based hybrids as buyers demand recovery-rate accountability.
Pricing Analysis
Capacity additions in India's fintech corridors are reshaping price floors for communication-platform modules. Subscription tiers stratify across enterprise, mid-market, and agency levels, with differentiation driven by API call volumes and compliance-automation depth. Cost compression in dialer infrastructure stems from hyperscale cloud provider competition. Third-party collection agencies exhibit highest price sensitivity; card issuers with in-house scoring engines show lowest.
Supply Chain Analysis
Cloud compute supply rests on hyperscale infrastructure concentrated in the United States, Ireland, and Singapore. Software development draws from Indian engineering talent pools and Eastern European compliance-coding specialists. Single-source vulnerability concentrates in AI model training data licensed from credit bureaus. Distribution runs through direct vendor sales teams serving enterprise banks and channel partners reaching regional agencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as regulatory compliance mandates create recurring upgrade cycles that lock in vendor relationships across economic conditions.
For Market Incumbents: Anticipate margin erosion from AI-native challengers by embedding conversational intelligence deeper into core workflows. Consolidate position through acquisition of specialized compliance-automation firms. Prioritize certification investment in EU AI Act conformity to defend European banking relationships against restructuring pipelines. For New Entrants and Emerging Players: Municipal utility billing systems represent an underserved buyer archetype with specialized regulatory protection-period workflows. Target Brazil's healthcare receivables segment where ANVISA oversight creates compliance-module demand unmatched by generic platforms. Lead with Portuguese-language conversational AI as the go-to-market wedge. For Investors and Strategic Acquirers: Credit bureaus with data-pipeline integration capabilities are the most active acquirer in this space. Five-to-ten year viability hinges on regulatory automation moats rather than raw recovery-rate performance. Watch CFPB enforcement intensity as the signal indicating mandatory upgrade cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first architecture enables embedded finance settlement links within borrower portals. |
| Regulatory Compliance Automation | Built-in Regulation F call-capping differentiates vendors for US financial institutions. |
| Acquisition of Specialist Firm | Skip-tracing AI providers add machine learning pipelines to legacy scoring engines. |
| Geographic Expansion | Regional language modules capture India's RBI-mandated digital collection shift. |
| Strategic Partnership | Communication-platform vendors ally with compliance-automation specialists to accelerate feature roadmaps. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with collection operations directors, compliance officers at card issuers, SaaS procurement leads, and third-party agency executives triangulate against CFPB enforcement records, FFIEC guidance documents, SEC filings from listed vendors, and trade data from debt purchasing associations. Bottom-up account-level modeling and top-down market sizing cross-validate projections.
Granularity extends to deployment architecture, solution type, end-user industry, and service model dimensions across the analysis window. CAGRs derive from segment-level growth rate reconciliation with macroeconomic delinquency forecasts. Inputs include regulatory timeline assumptions for EU AI Act implementation and RBI non-performing asset recognition phase-ins.
Inputs from cloud infrastructure providers and credit bureau data licensors were available through the study window; gaps in privately held agency financials introduce uncertainty bands around third-party services market sizing. Forecasts reflect documented assumptions about regulatory enforcement intensity and legacy system replacement rates. A small set of triggers—CFPB rulemaking, EU AI Act conformity deadlines, and central bank NPA policy shifts—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Global Executive Search (Headhunting) Market
Financial Services
Banknote Counters Market
Financial Services
Online Sports Betting Market
Financial Services
Financial Services Software Market
Financial Services
South Korea Factoring Services Market
Financial Services
Africa Lottery Market
Financial Services
CFD Trading Affiliate Programs Market
Financial Services
Reconciliation Software Market
Financial Services
Factoring Services Market
Financial Services
Multivendor ATM Software Market
Financial Services
Canada Credit Cards Market
Financial Services
Banking Cloud Services Market
Financial Services
UK Islamic Finance Market
Financial Services
North America B2B Legal Services Market
Financial Services
China Trade Finance Market
Financial Services
United Kingdom E-Brokerage Market