
 ATM Management Service Market | 2026-2036
ATM Management Service Market Size, Share, and Industry Trends Forecast 2026-2036
ATM Management Service Market Insights
The ATM management service tier is consolidating around two distinct performance bands. NCR Atleos Corporation leverages its global hardware installed base to bundle monitoring and cash logistics into multi-year contracts. Diebold Nixdorf Incorporated anchors its position through software-defined ATM architectures that reduce on-site service frequency. Euronet Worldwide Inc competes by controlling proprietary switching networks that lower transaction costs for independent deployers.
ATM management services encompass the remote and on-site oversight of automated teller machine fleets, including cash forecasting algorithms that optimize replenishment cycles to sub-24-hour resolution and predictive diagnostics that flag component failures before terminal downtime. Cash replenishment commands the largest revenue share due to armored transport and vault cash custody requirements, while cloud-based deployment models are expanding fastest as retail banks shed on-premise server obligations. Independent ATM deployers represent a concentrated margin pool because they lack captive service organizations and outsource full lifecycle management.
The US Federal Reserve's cash access policies, the EU's PSD2 strong-customer-authentication mandates, and India's RBI guidelines on ATM uptime thresholds collectively determine service level benchmarks and liability frameworks across jurisdictions. The US OCC examines third-party risk management in bank-fintech outsourcing arrangements, tightening vendor oversight. Stakeholders must monitor how central bank digital currency pilots reshape cash velocity and ATM transaction economics.
Market Dynamics
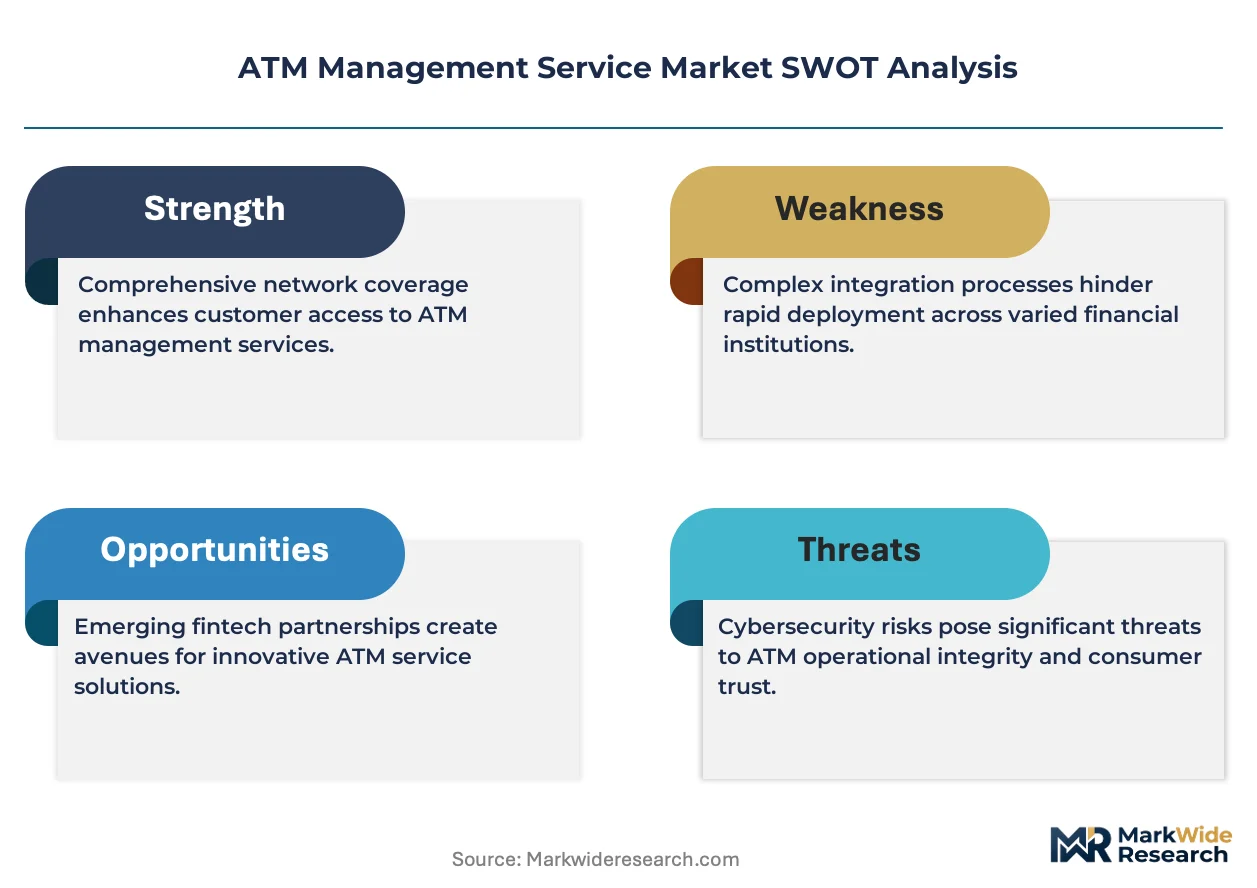
Retail banks are dismantling captive ATM service organizations and transferring fleet oversight to specialized providers, converting fixed infrastructure burdens into variable operating expenditures while demanding guaranteed uptime thresholds.
Growth Catalysts
- India's PLI scheme for fintech infrastructure:Production-linked incentives accelerate ATM network modernization across rural districts, expanding addressable fleet volumes for management providers.
- EU PSD2 strong-customer-authentication mandates:Terminal software upgrade requirements force banks to outsource complex compliance engineering to service specialists.
- Cloud-native monitoring architectures:Predictive diagnostics platforms reduce on-site service frequency and extend hardware lifecycles, lowering total cost of ownership.
Market Restraints
- Armored transport cost volatility:Fuel price fluctuations and driver shortages inflate cash replenishment expenses, compressing margins on the largest revenue line.
- Component supply concentration in East Asian foundries:ATM hardware manufacturers depend on concentrated semiconductor and display panel suppliers, exposing service networks to extended spare parts lead times.
- Central bank digital currency substitution:Pilot programs in multiple jurisdictions reduce cash velocity and transaction volumes at physical terminals.
Strategic Opportunities
- Rural financial inclusion programs in India:Unbanked population access initiatives expand ATM deployment into previously unserved districts with full lifecycle outsourcing requirements.
- Real-time payment integration:ISO 20022 messaging standards enable service providers to bundle transaction switching with terminal management, capturing interchange revenue streams.
- Independent ATM deployer consolidation:Fragmented non-bank operators lack scale for captive service organizations and represent concentrated demand for bundled management contracts.
Industry Challenges
- Cybersecurity certification complexity:PCI DSS compliance and regional data residency requirements extend onboarding timelines for new service deployments.
- Legacy core banking integration:Proprietary host-to-host protocols require custom middleware development, inflating implementation costs and technical risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ATM Management Service Market |
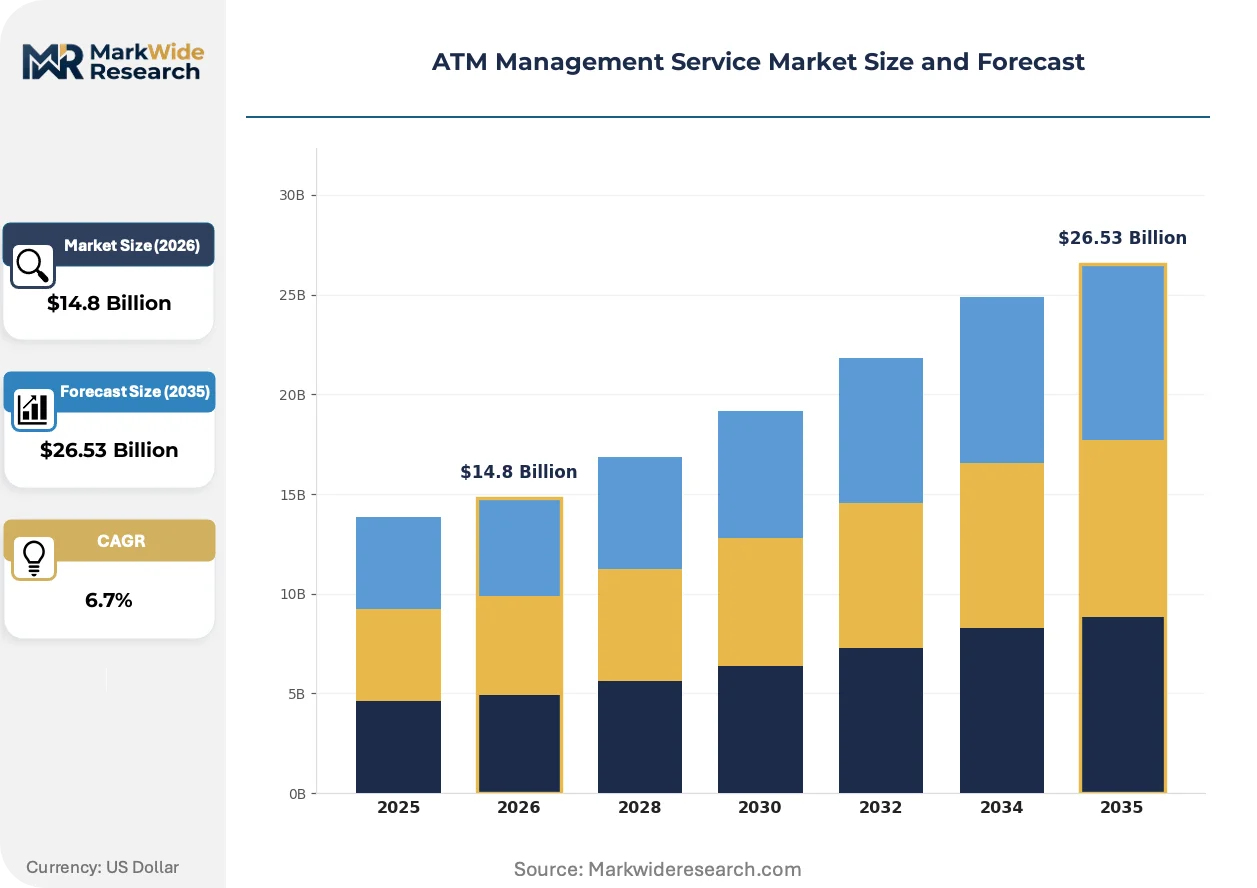
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cash Replenishment, ATM Monitoring, Maintenance & Repair, Software Management, Security Services Deployment Model: On-Premise, Cloud-Based, Hybrid, Managed Services End User: Retail Banks, Credit Unions, Payment Processors, Independent ATM Deployers, FinTech Providers Distribution Channel: Direct Sales, Channel Partners, Online Platforms, Third-Party Vendors |
| Companies Covered | NCR Atleos Corporation, Diebold Nixdorf Incorporated, Euronet Worldwide Inc, AGS Transact Technologies Ltd, CMS Info Systems Ltd, Fiserv Inc, Cardtronics, Hitachi Payment Services Pvt Ltd, Financial Software and Systems Pvt Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ATM Management Service Market Trends and Innovations
Software-defined architectures are displacing hardware-centric service models, enabling remote configuration management and predictive intervention that reduces physical site visits.
AI-driven cash forecasting algorithms analyze transaction patterns, seasonal cycles, and local events to optimize replenishment schedules. Tier-1 retail banks in North America and Western Europe deploy these systems to minimize vault cash holdings. The technology is consolidating cash logistics operations around fewer, larger regional cash centers.
The EU's Digital Operational Resilience Act imposes stringent third-party risk management obligations on financial institutions outsourcing critical functions. Service providers must demonstrate redundant infrastructure, incident reporting capabilities, and penetration testing regimes. ATM management contracts in EU member states now embed DORA compliance as a standard term.
Independent ATM deployers are unbundling service components and selecting best-of-breed providers for hardware maintenance, cash logistics, and transaction processing separately. This procurement fragmentation pressures bundled service incumbents to justify premium pricing through demonstrable uptime performance. The pattern is most pronounced in the United Kingdom and Australia where IAD market share exceeds thirty percent of terminal installed base.
ATM Management Service Market Segmentation
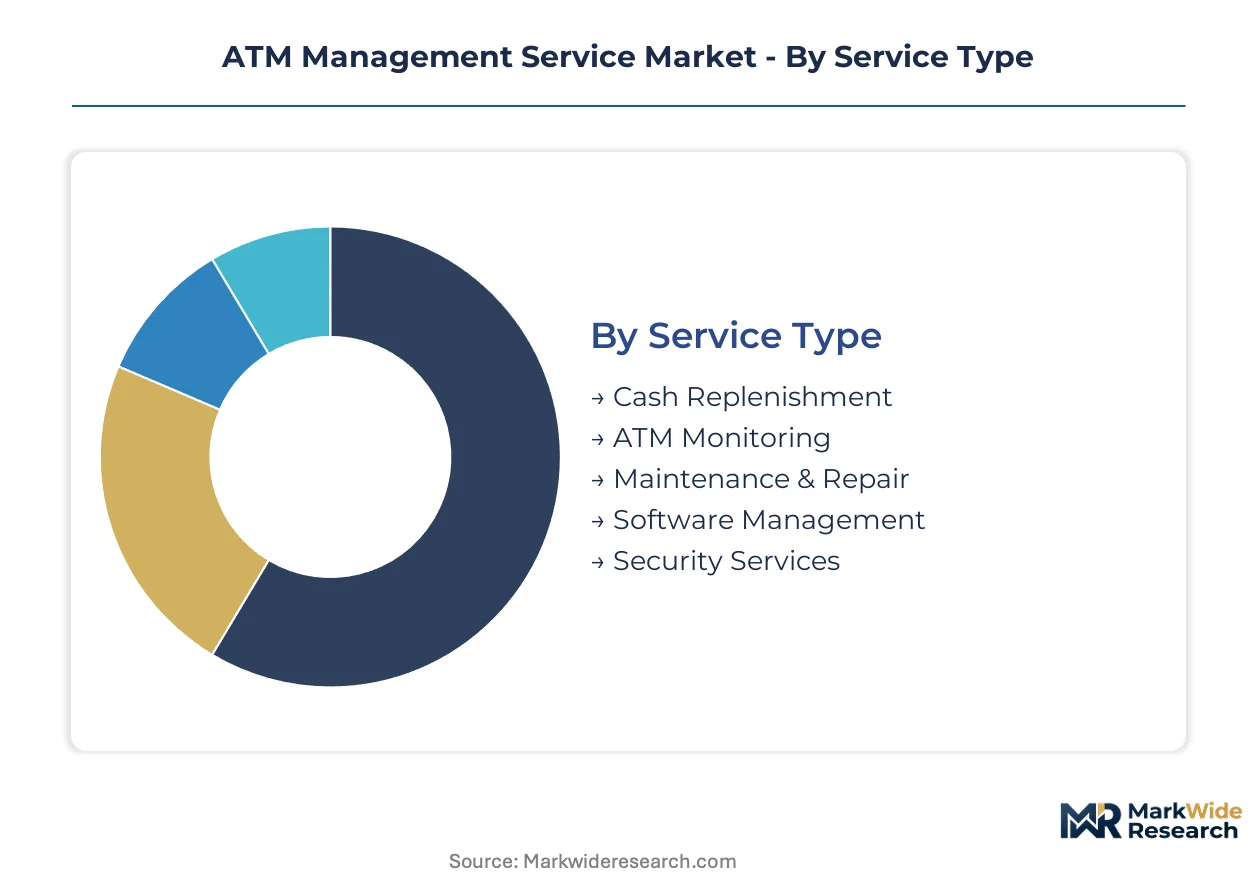
Service procurement in ATM management diverges sharply by buyer sophistication. Large retail banks prioritize bundled uptime guarantees, while independent deployers unbundle components to minimize fixed costs. Understanding these decision hierarchies reveals where margin concentrates and which technologies reshape contract structures.
Service Type:
Cost tier determines outsourcing depth—high-frequency physical services command premium pricing, while remote capabilities enable margin compression through scale.
- Cash Replenishment:Armored transport and vault custody operations dominate revenue pools due to fuel-linked cost volatility and specialized security licensing. Indian rural inclusion programs and EU cash access mandates sustain demand concentration despite digital payment expansion.
- ATM Monitoring:Predictive diagnostics platforms analyze transaction velocity, component temperature, and cash depletion curves to trigger preemptive intervention. Cloud-native architectures reduce on-site service frequency for North American and Western European retail banks.
- Maintenance & Repair:Field technician dispatch for hardware failures and preventive component replacement.
- Software Management:Terminal firmware updates, security patch deployment, and compliance configuration.
- Security Services:Physical surveillance integration, fraud detection algorithms, and PCI DSS certification maintenance.
Volume sits with Cash Replenishment; growth tilts toward ATM Monitoring.
Deployment Model:
Application criticality shapes infrastructure choice—transaction switching demands low-latency edge presence, while analytics workloads migrate to centralized cloud.
- Cloud-Based:Centralized monitoring dashboards and AI-driven cash forecasting eliminate on-premise server obligations. Retail banks in Germany and France accelerate migration under EU Digital Operational Resilience Act data residency requirements.
- Managed Services:Full lifecycle outsourcing converts fixed infrastructure to variable expenditure with guaranteed SLA structures. Independent ATM deployers in the United Kingdom and Australia favor this model due to absence of captive service organizations.
- On-Premise:Legacy core banking protocol integration retains localized control over sensitive transaction data.
- Hybrid:Split architectures maintain edge transaction processing while centralizing analytics and compliance reporting.
Revenue concentrates in Managed Services; Cloud-Based deployment is expanding most quickly.
End User:
Customer type dictates contract complexity—regulated banks demand redundant infrastructure certification, while agile entrants prioritize speed-to-deployment.
- Retail Banks:Tier-1 institutions mandate 99.5% uptime guarantees, redundant switching paths, and DORA-compliant third-party risk documentation. US OCC examination guidelines tighten vendor oversight for these relationships.
- Independent ATM Deployers:Fragmented non-bank operators lack scale for captive service organizations and represent concentrated demand for unbundled procurement. Australian and UK IAD market share exceeding thirty percent of terminal base drives specialized provider ecosystems.
- Credit Unions:Cooperative financial institutions with limited IT staffing outsource full terminal lifecycle management.
- Payment Processors:Transaction switching specialists require ATM fleet interoperability for network reach expansion.
- FinTech Providers:Digital-first entrants leverage ATM infrastructure for physical cash access without building service capabilities.
Contract value concentrates with Retail Banks; Independent ATM Deployers are gaining share fastest.
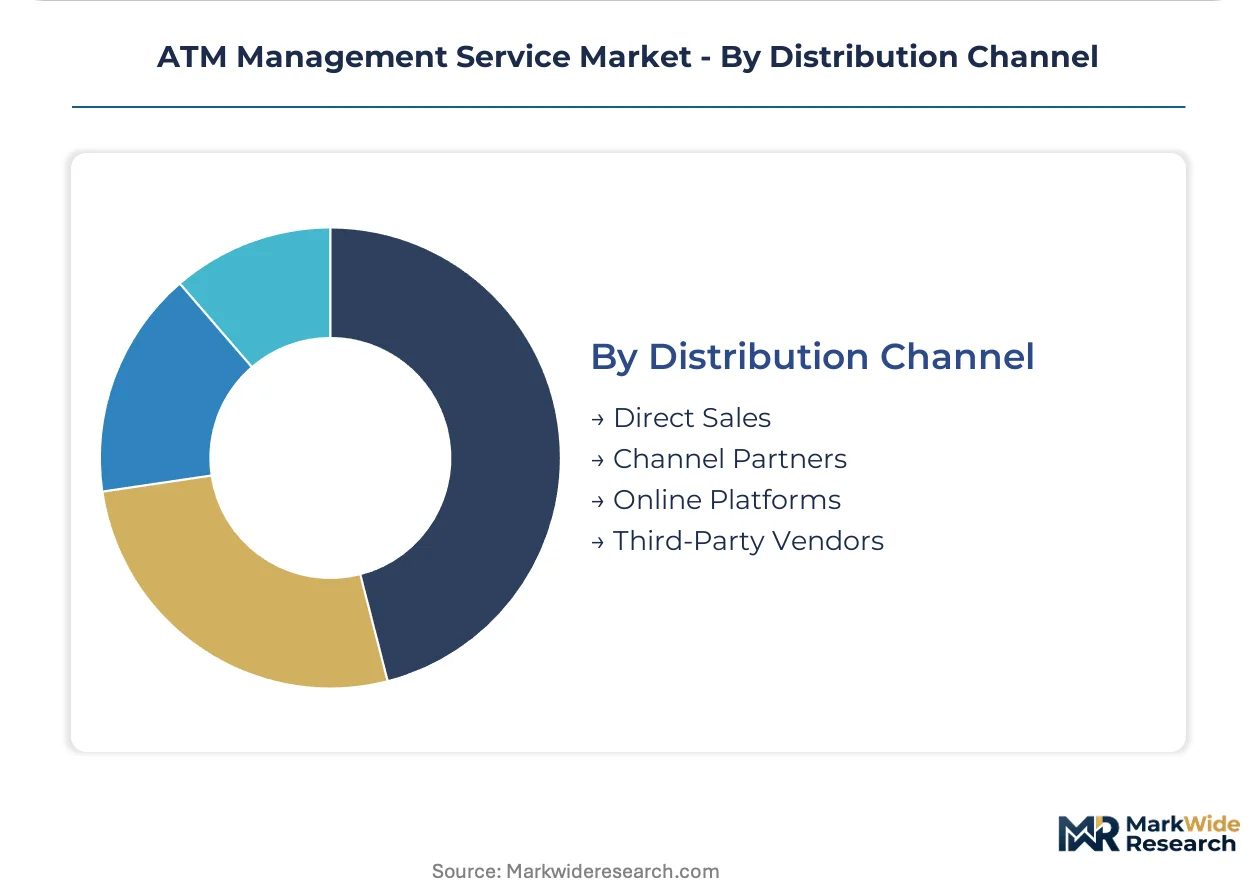
Distribution Channel:
Geography and buyer maturity determine route-to-market—direct relationships dominate complex regulated sales, while channels extend reach to fragmented deployers.
- Direct Sales:Enterprise account teams negotiate multi-year bundled contracts with custom SLA terms. Major retail banks in the United States and Germany prefer this channel for cybersecurity certification complexity.
- Channel Partners:Regional systems integrators and value-added resellers extend coverage to mid-tier credit unions and emerging market banks. Indian fintech infrastructure PLI scheme beneficiaries frequently procure through local partners.
- Online Platforms:Self-service procurement portals for standardized monitoring and software management subscriptions.
- Third-Party Vendors:Hardware manufacturers bundle service contracts with new terminal deployments.
Revenue sits with Direct Sales; Channel Partners show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai's financial district anchors ATM management service demand through concentrated banking headquarters and fintech infrastructure clusters that drive outsourced fleet operations across South Asia.
United States
Retail bank consolidation and branch network optimization accelerate third-party ATM outsourcing across Texas and Florida corridors. The OCC's third-party risk management examinations tighten vendor oversight requirements for multi-year service contracts. Chicago and Atlanta host concentrated cash logistics operations serving regional bank fleets.
Germany
Sparkassen and cooperative banking networks modernize ATM infrastructure under cloud-native deployment mandates. The EU's Digital Operational Resilience Act imposes stringent third-party risk documentation requirements on outsourced critical functions. Frankfurt's financial cluster drives demand for redundant switching infrastructure and compliance-engineered service tiers.
India
Rural financial inclusion programs and the RBI's ATM uptime threshold guidelines expand addressable fleet volumes across Maharashtra and Karnataka states. The PLI scheme for fintech infrastructure accelerates network modernization in previously unserved districts. Bangalore and Mumbai anchor service provider ecosystems for independent ATM deployer consolidation.
United Kingdom
Independent ATM deployers exceeding thirty percent terminal market share drive unbundled procurement patterns across England and Scotland. The Financial Conduct Authority's operational resilience expectations shape service level negotiations for non-bank operators. London concentrates transaction switching specialists and cash logistics coordination hubs.
Australia
Fragmented independent deployer networks lacking captive service organizations outsource full lifecycle management across New South Wales and Victoria. APRA's outsourcing prudential standards govern risk allocation in bank-fintech arrangements. Sydney and Melbourne host specialized provider ecosystems serving unbundled procurement demand.
ATM Management Service Market Competitive Landscape
Premium-margin players sit above commodity-margin players across bundled service capability and compliance certification depth. The vendor base stratifies between hardware-origin incumbents with installed base leverage and software-native entrants with predictive analytics specialization. Three archetypes dominate: global hardware bundlers, switching network controllers, and regional cash logistics specialists. Competitive moves concentrate on multi-year contract renewal cycles and cloud-native platform migrations that reduce on-site service frequency.
Within the hardware-bundler archetype, NCR Atleos Corporation and Diebold Nixdorf Incorporated exemplify global incumbents leveraging installed base scale. Euronet Worldwide Inc occupies a position among switching network specialists. These three represent divergent strategic anchors—hardware bundling, software-defined architectures, and proprietary transaction infrastructure—each commanding distinct margin tiers based on customer sophistication and contract complexity.
| Leading Market Players |
|---|
| NCR Atleos Corporation |
| Diebold Nixdorf Incorporated |
| Euronet Worldwide Inc |
| AGS Transact Technologies Ltd |
| CMS Info Systems Ltd |
| Fiserv Inc |
| Cardtronics |
| Hitachi Payment Services Pvt Ltd |
| Financial Software and Systems Pvt Ltd |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up cash logistics specialists have consolidated regional armored transport networks across the United States and Western Europe, converting fragmented local operators into national platforms that exercise pricing discipline through route density advantages and fuel surcharge pass-through mechanisms.
Pricing Analysis
Uptime-guarantee contracts anchor value-based pricing structures that tie service fees to terminal availability thresholds rather than discrete maintenance events. Three-tier pricing structure across premium, standard, and economy levels separates Tier-1 retail banks demanding redundant infrastructure certification from independent deployers selecting unbundled components. Pricing pressure stems from armored transport cost volatility driven by fuel price fluctuations and driver shortages, compressing margins on cash replenishment services. Independent ATM deployers exhibit highest price sensitivity due to absence of captive service organizations and thin transaction economics, while retail banks prioritize uptime performance over unit cost minimization.
Supply Chain Analysis
PCI DSS certification and regional data residency requirements gate supplier qualification, extending onboarding timelines for new service deployments and concentrating vendor relationships among incumbent specialists with established compliance infrastructure. Component sourcing draws from semiconductor foundries in Taiwan and South Korea, display panel manufacturers in China, and precision mechanical suppliers in Germany. Single-source vulnerability in East Asian semiconductor supply exposes service networks to extended spare parts lead times. Distribution runs through direct enterprise sales teams for regulated banking clients and regional channel partners extending coverage to fragmented independent deployer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified armored transport capacity constraints in rural India and driver shortage bottlenecks across North American logistics networks prop pricing power for established providers with secured fleet access.
For Market Incumbents: Lock in multi-year contract renewals with Tier-1 retail banks before EU DORA compliance deadlines accelerate vendor consolidation. Extend hardware lifecycle management capabilities through predictive diagnostics platform investments that reduce competitor differentiation on uptime performance. Central bank digital currency pilots threaten cash velocity and transaction volumes, making software-defined service bundling essential for revenue retention. For New Entrants and Emerging Players: Launch via cloud-native monitoring subscriptions targeting mid-tier credit unions in the United States and cooperative banking networks in Germany lacking internal IT staffing for terminal lifecycle management. India's PLI scheme beneficiaries in Maharashtra and Karnataka states represent the most penetrable geography due to rural inclusion program acceleration and absence of established service provider density. Emphasize ISO 20022 real-time payment integration capabilities as the primary go-to-market wedge against hardware-origin incumbents. For Investors and Strategic Acquirers: RBI ATM uptime threshold enforcement actions against non-compliant operators are the leading indicator that regulatory compliance capabilities will drive acquisition premiums for certified service providers. The five-to-ten-year viability window favors providers with demonstrated DORA compliance documentation and redundant switching infrastructure. Target acquisition profiles should emphasize regional cash logistics specialists with dense route networks in supply-constrained corridors.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Reduces on-site service frequency for North American and Western European retail banks through predictive intervention capabilities. |
| Real-Time Payment Integration | Captures interchange revenue streams via ISO 20022 messaging standards bundled with terminal management services. |
| Rural Network Expansion | Addresses ATM deployment requirements in India's previously unserved districts under financial inclusion programs. |
| Compliance Certification Investment | Accelerates EU DORA onboarding timelines and differentiates service tiers for regulated banking relationships. |
| Cash Logistics Consolidation | Builds route density advantages that offset fuel price volatility through armored transport network scale. |
Research Methodology
SEC filings from NCR Atleos Corporation and Diebold Nixdorf Incorporated, RBI circulars on ATM infrastructure guidelines, and EU Digital Operational Resilience Act regulatory texts formed the secondary backbone for market sizing and competitive positioning analysis. Primary interviews with ATM fleet operations directors at Tier-1 retail banks, cash logistics procurement managers at independent deployers, and compliance officers at service provider organizations validated secondary data points and informed contract structure assumptions. Bottom-up triangulation across terminal installed base estimates and top-down verification against aggregate service revenue disclosures ensured cross-validation of market value calculations.
Historical trendline analysis of ATM transaction volumes, cash replenishment frequencies, and outsourcing penetration rates established baseline growth trajectories across the projection horizon. The analytical framework modeled segmentation dimensions including service type, deployment model, end-user category, and geographic regulatory cluster. CAGRs were derived through regression analysis of historical outsourcing adoption curves and forward projection of rural financial inclusion program deployment targets. Industry-specific forecast inputs incorporated RBI uptime threshold enforcement patterns and EU PSD2 strong-customer-authentication compliance timelines.
Central bank digital currency pilot expansion, armored transport labor market disruptions, and semiconductor supply chain normalization are the dominant revision risks to modeled forecasts. A model refresh is warranted upon material change in cash velocity trends or regulatory enforcement intensity across priority jurisdictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Saas Escrow Services Market
Financial Services
LAMEA Financial Services Software Market
Financial Services
Commercial Debt Collection Software Market
Financial Services
Factoring Services Market
Financial Services
Pawn Shop Market
Financial Services
Asia-Pacific Factoring Services Market
Financial Services
Financial Services Operational Risk Management Solution Market
Financial Services
Smart Finance Services Market
Financial Services
Qatar Analysis of Key Sectors and Investment Opportunities Market
Financial Services
North America Management Consulting Services Market
Financial Services
Healthcare Finance Solutions Market
Financial Services
Canada Credit Cards Market
Financial Services
Digital Account Opening Market
Financial Services
Europe Factoring Services Market
Financial Services
Europe B2B Legal Services Market
Financial Services
South Korea Trade Finance Market