
 Global Treasury Management System (TMS) Market | 2026-2036
Global Treasury Management System (TMS) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Treasury Management System (TMS) Market Foresight
ISO 20022 certification is bifurcating the competitive landscape between legacy message-format vendors and modern API-native platforms. Oracle leverages its database-centric architecture to anchor enterprise-scale deployments across Fortune 500 treasuries. Kyriba differentiates through cloud-native connectivity to bank APIs across multiple jurisdictions. SAP sustains its installed-base advantage by embedding treasury modules within broader ERP ecosystems.
A treasury management system constitutes an integrated software platform that automates cash positioning, liquidity forecasting, payment execution, and financial risk hedging through real-time bank connectivity and multi-entity consolidation engines. Cloud-based deployment is displacing on-premises installations as banks accelerate API-first connectivity standards. Cash management and liquidity management solutions capture the deepest margin pools, while risk management modules are expanding fastest among energy firms and telecommunications providers navigating commodity and currency volatility.
The European Banking Authority enforces ISO 20022 migration timelines that reshape product roadmaps for vendors serving EU-domiciled clients. The US Federal Reserve's FedNow instant payment infrastructure and India's RBI-mandated real-time gross settlement expansions are creating parallel certification requirements. Compliance management functionality is becoming non-negotiable as Basel III liquidity coverage ratios and regional data residency rules tighten. Stakeholders must evaluate whether their current platforms can absorb forthcoming central bank digital currency interfaces without core architecture replacement.
Market Dynamics
ISO 20022 migration mandates are compressing replacement cycles across the Global Treasury Management System (TMS) Market, forcing banks and corporates to retire legacy SWIFT MT formats while real-time payment infrastructure investments demand API-native architectures.
Growth Catalysts
- Real-time payment infrastructure:FedNow in the United States and India's RBI-mandated RTGS expansions are compelling treasury departments to upgrade connectivity protocols. Financial institutions in New York and Mumbai are prioritizing instant settlement capabilities.
- Cloud migration mandates:European Banking Authority guidelines on operational resilience are accelerating displacement of on-premises installations. Frankfurt and London-based banks are consolidating multi-entity cash positions through hosted platforms.
- Liquidity coverage requirements:Basel III regulations are driving demand for intraday cash visibility tools. Energy trading desks and telecommunications treasury operations require real-time liquidity forecasting to meet regulatory thresholds.
Market Restraints
- Implementation cost concentration:Multi-year deployment timelines for enterprise-scale TMS installations strain capital allocation. Fortune 500 treasuries face seven-figure integration expenditures before achieving operational breakeven.
- Bank connectivity fragmentation:Proprietary API standards across jurisdictions create interoperability friction. Corporates operating in Brazil, Japan, and Switzerland must maintain multiple connectivity protocols.
- Data residency compliance:China's cybersecurity law and Russia's data localization requirements restrict cloud deployment options. Multinational treasuries must architect region-specific instances rather than unified global platforms.
Strategic Opportunities
- Central bank digital currency interfaces:Pilot programs by the European Central Bank and Bank of England are creating first-mover advantages for vendors with programmable payment architectures. Treasury platforms capable of CBDC wallet integration will capture replacement demand.
- Embedded finance convergence:API marketplaces are enabling non-bank platforms to offer treasury services. Logistics and e-commerce marketplaces in Singapore and the Netherlands are white-labeling cash management tools for supplier networks.
- Carbon accounting integration:EU Corporate Sustainability Reporting Directive requirements are expanding treasury scope into emissions-linked financial planning. Sustainability-linked derivatives and green liquidity pools represent new margin opportunities.
Industry Challenges
- ISO 20022 expertise scarcity:Message format translation and rich data field mapping require specialized technical skills that outpace available talent pools. Implementation partners in Chicago and Frankfurt command premium rates.
- Legacy ERP entanglement:Decades-old general ledger architectures resist real-time API connectivity. SAP and Oracle environments require extensive middleware development before achieving bank-direct integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Treasury Management System (TMS) Market |
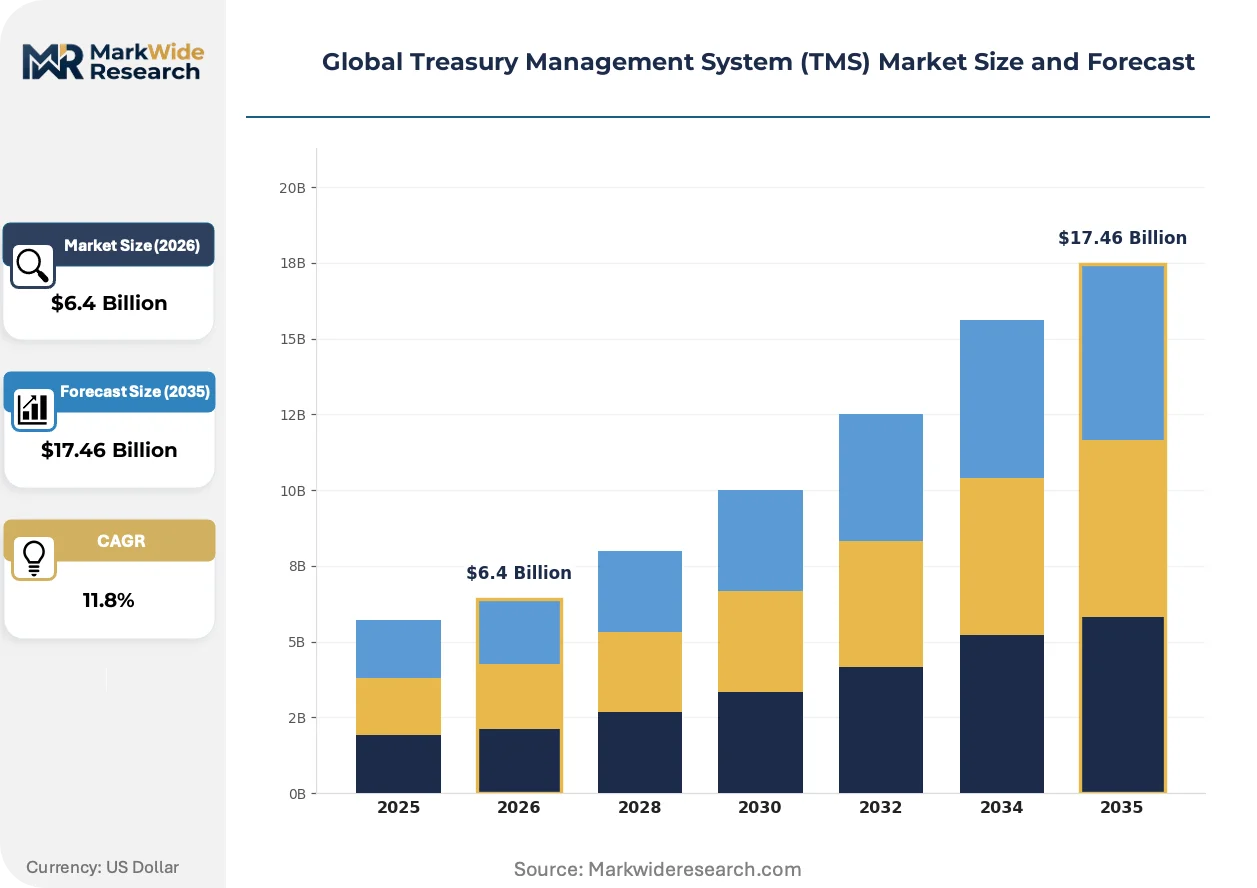
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $17.46 Billion |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Hosted Solution Type: Cash Management, Risk Management, Payment Processing, Compliance Management, Liquidity Management Organization Size: Small Enterprises, Medium Enterprises, Large Corporations, Multinational Companies End User Industry: Banking Institutions, Nonprofit Entities, Government Agencies, Energy Firms, Telecommunications Providers |
| Companies Covered | Oracle, SAP, Kyriba, Finastra, GTreasury, Taulia, Sopra Banking Software, ACI Worldwide, Broadridge Financial Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Treasury Management System (TMS) Market Shifts & Advancements
API-first connectivity standards are fragmenting competitive moats between established treasury vendors and fintech challengers, while regulatory mandates on payment timing and data formats compress technology refresh cycles.
Artificial intelligence is bifurcating cash forecasting methodologies across the Global Treasury Management System (TMS) Market. Machine learning models now ingest alternative data streams including supply chain signals and macroeconomic indicators to predict liquidity positions. Multinational corporates in consumer goods and pharmaceuticals are deploying these tools to reduce working capital buffers. The technology is bifurcating vendor capabilities between predictive analytics leaders and rules-based legacy providers.
REACH chemical substance regulations and the EU AI Act are imposing algorithmic transparency requirements on automated treasury decisions. European treasuries must now document machine learning model logic for liquidity optimization and hedging recommendations. Vendors serving EU-domiciled clients are engineering explainable AI modules to satisfy audit requirements. German and French banking supervisors are conducting targeted examinations of black-box risk management systems.
Treasury centralization patterns are rotating toward captive finance structures in high-interest-rate environments. Corporates are consolidating regional cash pools into fewer physical locations to maximize yield on overnight balances. Singapore and Luxembourg have captured disproportionate share of these relocations due to favorable tax treaties and clearing infrastructure. Energy and commodity trading firms are leading this geographic consolidation to optimize collateral management.
Global Treasury Management System (TMS) Market Segmentation

Treasury management system procurement patterns diverge sharply across deployment architectures, solution portfolios, and organizational scale. Vendors must architect pricing and implementation models that align with the technical debt tolerance and regulatory complexity of each segment cluster.
Deployment:
Margin pools concentrate in recurring subscription revenue from cloud-native architectures, while professional services attach rates remain elevated for hybrid transition engagements.
- On-Premises:Legacy installations persist in defense contractors and critical infrastructure operators where air-gapped security mandates override cloud economics. Frankfurt and Zurich-based banks maintain these configurations to satisfy data sovereignty requirements enforced by national regulators.
- Cloud-Based:Multi-tenant SaaS platforms dominate new procurement among mid-market corporates seeking rapid bank API onboarding without capital expenditure. Singaporean fintech hubs and Amsterdam trade finance centers are displacing on-premises footprints fastest.
- Hybrid:Split architectures partition sensitive cash positioning data on-premises while routing payment execution through cloud gateways. Japanese automotive treasury operations and Australian mining firms favor this model to balance latency requirements with regulatory audit trails.
- Hosted:Single-tenant private cloud deployments serve sovereign wealth funds and public pension managers requiring dedicated infrastructure without operational overhead. Oslo and Abu Dhabi financial centers represent concentrated demand.
On-Premises holds installed capacity. Cloud-Based is rotating up the share rankings.
Solution Type:
Cash and liquidity modules generate the deepest recurring revenue streams, while compliance functionality commands premium pricing from Basel III-constrained institutions.
- Cash Management:Real-time cash positioning and multi-bank aggregation form the core transactional layer. New York and London multinational treasuries demand intraday visibility across 50-plus currency accounts to optimize overnight balances.
- Liquidity Management:Forecasting engines and notional pooling structures enable regulatory ratio compliance. Energy trading desks in Houston and commodity houses in Geneva deploy these tools to meet liquidity coverage thresholds.
- Risk Management:Currency hedging and interest rate exposure analytics expand fastest among telecommunications providers navigating emerging market volatility. Brazilian and South African operators represent concentrated procurement.
- Payment Processing:ISO 20022-native execution modules displace legacy wire platforms. Indian and US institutions upgrading to real-time infrastructure drive replacement cycles.
- Compliance Management:Regulatory reporting automation and audit trail preservation attract premium pricing. EU-domiciled banks under ECB supervision prioritize these capabilities for CSRD alignment.
Cash Management anchors vendor revenue. Liquidity Management is climbing the fastest among regulated institutions.
Organization Size:
Implementation complexity and customization requirements scale non-linearly with entity count and geographic dispersion.
- Large Corporations:Domestic-focused enterprises with centralized treasury functions seek modular platforms without excessive integration overhead. German Mittelstand manufacturers and Canadian resource firms represent core demand.
- Multinational Companies:Complex entity structures across 20-plus jurisdictions require multi-ERP consolidation and jurisdictional tax optimization. US technology conglomerates and Swiss pharmaceutical groups maintain the most sophisticated deployments.
- Medium Enterprises:Growth-stage companies prioritize rapid deployment over customization. Nordic and Benelux mid-caps favor pre-configured templates with limited bank connectivity requirements.
- Small Enterprises:Basic cash visibility and payment execution suffice for single-currency operations. UK professional services firms and Australian agricultural exporters populate this segment.
Multinational Companies consume the highest per-seat licensing. Medium Enterprises are gaining share fastest as cloud economics democratize access.
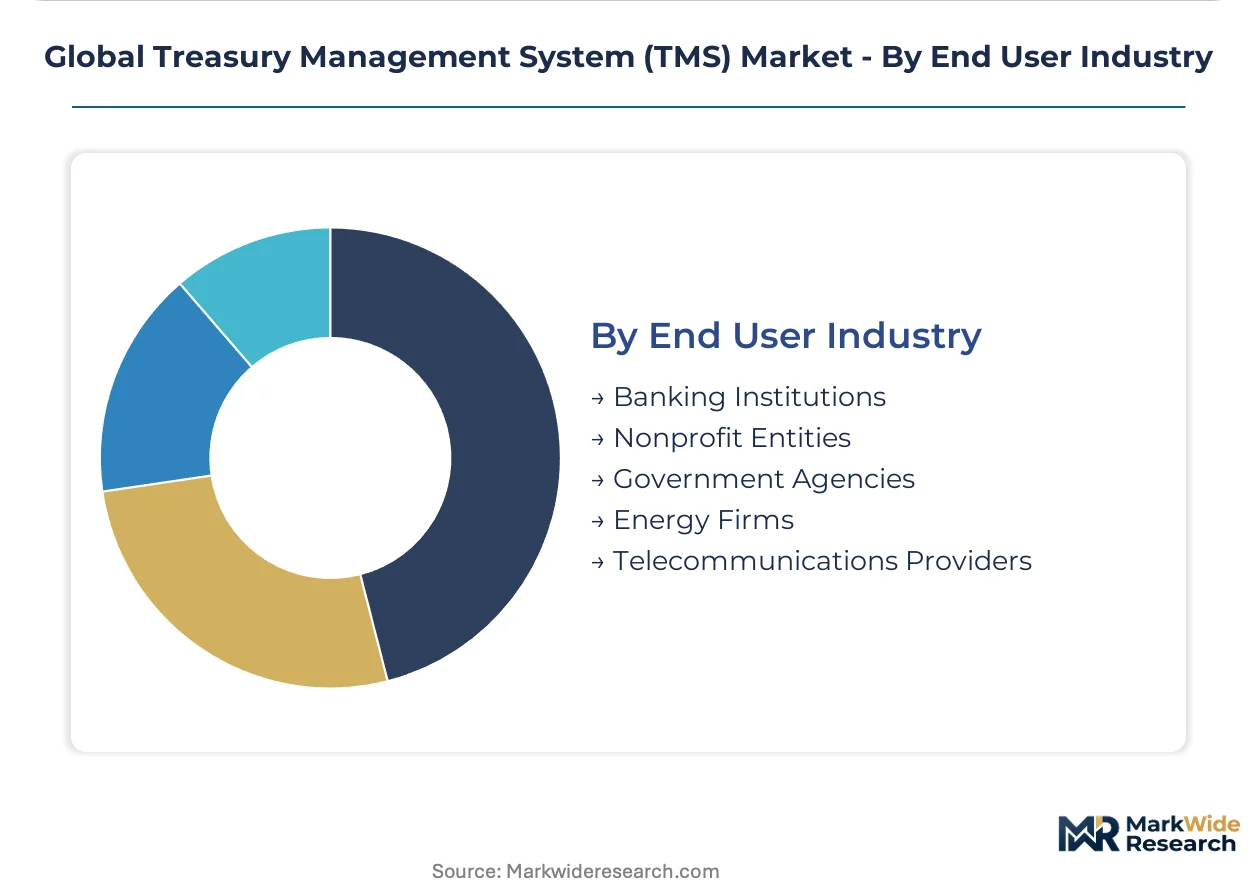
End User Industry:
Banking institutions generate volume through white-label distribution, while energy and telecommunications verticals drive specialized risk module development.
- Banking Institutions:Corporate banking divisions deploy TMS platforms as client-facing cash management services. Spanish and Italian universal banks are expanding API marketplaces for SME treasury outsourcing.
- Energy Firms:Commodity trading desks require real-time collateral management and multi-currency hedging. Singapore and Geneva trading hubs concentrate procurement of specialized risk modules.
- Telecommunications Providers:Emerging market revenue exposure drives currency volatility management priorities. Mexican and Indonesian operators are expanding hedging program sophistication.
- Government Agencies:Sovereign treasury departments prioritize payment security and audit transparency. Scandinavian and Gulf state public finance ministries lead public sector adoption.
- Nonprofit Entities:Grant-funded organizations seek donor-restricted cash tracking and multi-currency pool management. International development NGOs headquartered in Washington DC and Geneva represent specialized demand.
Banking Institutions hold institutionalized procurement channels. Energy Firms are rotating up the share rankings through commodity volatility cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Multinational corporate treasury departments concentrate procurement decisions in financial centers where real-time payment infrastructure and regulatory clarity converge. Banking supervisors in major economies are compressing technology refresh timelines through ISO 20022 mandates. Vendor sales cycles track directly to these jurisdictional compliance deadlines.
United States
The Federal Reserve's FedNow instant payment network is forcing treasury departments to abandon batch-processing architectures. SEC liquidity disclosure rules for registered investment advisers are expanding demand for intraday cash visibility tools. New York and Chicago financial centers host the densest concentrations of Fortune 500 treasury operations upgrading connectivity protocols.
Germany
BaFin operational resilience guidelines are accelerating displacement of on-premises treasury installations among Mittelstand exporters. The Bundesbank's TARGET2 migration to ISO 20022 is creating hard deadlines for corporate connectivity upgrades. Frankfurt's banking cluster concentrates vendor implementation resources and specialized consulting capacity.
United Kingdom
The Bank of England's real-time gross settlement modernization is driving replacement of legacy SWIFT MT infrastructure. FCA rules on operational continuity are mandating cloud-resilient treasury architectures for systemically important institutions. London's Square Mile and Canary Wharf districts maintain Europe's deepest pool of multinational treasury talent.
Singapore
MAS guidelines on cloud risk management are legitimizing SaaS treasury deployments for regional headquarters operations. The country's real-time payment infrastructure (PayNow) is integrating with cross-border ASEAN settlement schemes. Marina Bay and Raffles Place financial districts are capturing treasury centralization flows from commodity trading firms relocating from Geneva.
India
RBI-mandated RTGS expansion and UPI interoperability requirements are compelling domestic banks to modernize corporate cash management platforms. SEBI's liquidity stress testing mandates for non-banking financial companies are expanding addressable market for forecasting modules. Mumbai's Bandra-Kurla Complex and Delhi's Gurugram corridor concentrate fintech vendor development centers serving this upgrade cycle.
Global Treasury Management System (TMS) Market Competitive Landscape
Player mix skews toward enterprise software incumbents with database-centric architectures and cloud-native challengers with API-first connectivity stacks. Consolidation pressure intensifies as ISO 20022 certification costs favor scaled R&D budgets over point solutions. Three archetypes dominate: ERP-embedded treasury modules, standalone cloud platforms, and bank-originated white-label services. Competitive moves center on middleware partnerships with regional banks and vertical specialization for commodity trading workflows.
Within the ERP-embedded tier, Oracle and SAP occupy positions anchoring enterprise-scale deployments through existing database relationships and general ledger integration paths. Kyriba exemplifies the cloud-native challenger archetype, representing vendors that built API connectivity into core architecture rather than retrofitting legacy message formats. Finastra sits within the bank-technology intersection, reflecting institutions that originated as banking infrastructure providers before extending into corporate treasury software.
| Leading Market Players |
|---|
| Oracle |
| SAP |
| Kyriba |
| Finastra |
| GTreasury |
| Taulia |
| Sopra Banking Software |
| ACI Worldwide |
| Broadridge Financial Solutions |
| Others |
Supply & Pricing Matrix
Capacity utilization at cloud infrastructure providers in the United States and Europe anchors pricing floors for TMS deployments, as multi-tenant SaaS platforms achieve margin leverage that on-premises vendors cannot replicate. This scale concentration compresses implementation cost curves while elevating subscription renewal rates across mid-market segments.
Pricing Analysis
Cost-plus contracts with CPI indexation dominate enterprise TMS procurement, particularly among Fortune 500 treasuries negotiating multi-year agreements. Three-tier pricing structure across premium, standard, and economy levels separates API-native platforms from legacy middleware-dependent installations. Pricing pressure stems from open-source treasury tool proliferation and fintech challengers offering modular point solutions. Medium enterprises exhibit highest price sensitivity due to constrained capital allocation, while sovereign wealth funds demonstrate lowest sensitivity given regulatory compliance imperatives.
Supply Chain Analysis
Strategic stockpiling of implementation talent in Frankfurt and Singapore contrasts with just-in-time contractor deployment for North American upgrades. Software development concentrates in India, Ireland, and Poland, with cloud infrastructure provisioning anchored in the United States, Germany, and Singapore. Critical dependencies include banking API middleware, ISO 20022 message libraries, and regulatory compliance engines. Single-source vulnerability pervades specialized ISO 20022 expertise pools. Distribution runs through direct vendor sales organizations supplemented by Big Four consulting partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 20022 implementation expertise scarcity constrains vendor delivery capacity, creating asymmetric returns for firms that secured specialized talent ahead of regulatory deadlines. This capability gap separates execution-ready platforms from backlog-constrained competitors.
For Market Incumbents: Consolidate ISO 20022-certified implementation partners through exclusive contracting arrangements to lock out challengers. Acquire cloud-native connectivity specialists in Singapore and Amsterdam to neutralize API-first entrant threats. Prioritize vertical integration into bank API middleware development to reduce third-party dependency. For New Entrants and Emerging Players: Anchor in mid-market manufacturing verticals in the Benelux and Nordic regions where ERP-embedded incumbents leave service gaps. Target carbon accounting integration modules for EU Corporate Sustainability Reporting Directive compliance as the most penetrable white-space. Pursue white-label distribution through Spanish and Italian universal banks expanding SME treasury outsourcing. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors cloud-native platforms with pre-built CBDC wallet architectures over legacy message-format vendors facing replacement cycles. Long-term viability hinges on programmable payment infrastructure readiness. Target acquisition archetypes: API-first treasury specialists with multi-jurisdiction bank connectivity. Watch European Central Bank digital euro pilot program expansion as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 20022 Certification Acceleration | European Banking Authority deadlines in Frankfurt and BaFin guidelines compress vendor product roadmaps. |
| Cloud-Native Architecture Migration | MAS guidelines in Singapore legitimize SaaS deployments for regional treasury headquarters operations. |
| CBDC Interface Development | Bank of England and European Central Bank pilot programs create first-mover platform advantages. |
| Embedded Finance Partnership | API marketplaces in the Netherlands and Singapore enable non-bank treasury service distribution. |
| Carbon Accounting Integration | EU Corporate Sustainability Reporting Directive expands treasury scope into emissions-linked financial planning. |
Research Methodology
A spread of perspectives from treasury operations directors, bank API integration specialists, regulatory compliance officers, and fintech platform engineers converged on the working assumptions. Primary interviews combined with secondary validation from SEC 10-K filings, ECB supervisory disclosures, MAS regulatory circulars, and SWIFT ISO 20022 migration reports. Bottom-up deployment counts and top-down enterprise software spending estimates underwent cross-triangulation.
Segmentation dimensions modeled span deployment architecture, solution type, organization size, and end-user industry across the analysis window. Deployment splits tracked cloud-native versus on-premises versus hybrid configurations. Solution type captured cash management, liquidity management, risk management, payment processing, and compliance management modules. Organization size stratified multinational companies, large corporations, medium enterprises, and small enterprises. CAGR derivation rested on replacement cycle analysis tied to ISO 20022 mandate timelines and real-time payment infrastructure investments.
Decision-makers should treat outputs as directional under stable regulatory deadline assumptions and constant cloud infrastructure cost curves; material deviation would warrant model refresh. Forecasts incorporate Basel III liquidity coverage ratio enforcement intensity and central bank digital currency pilot program expansion as variable inputs. Revision becomes warranted when FedNow adoption velocity or ECB digital euro timeline crosses materiality thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Australia Online Gambling Market
Financial Services
Broker Affiliate Programs Market
Financial Services
E-Invoicing Market
Financial Services
Qatar Analysis of Key Sectors and Investment Opportunities Market
Financial Services
Reconciliation Software Market
Financial Services
Europe B2B Legal Services Market
Financial Services
Factoring Services Market
Financial Services
Germany E-Brokerage Market
Financial Services
Solar Powered ATM Market
Financial Services
North America Management Consulting Services Market
Financial Services
China Financial Services Software Market
Financial Services
Africa Factoring Services Market
Financial Services
Account Aggregators Market
Financial Services
UK Islamic Finance Market
Financial Services
White Glove Services Market
Financial Services
Southeast Asia E-Invoicing Market