
 Solar Powered ATM Market | 2026-2036
Solar Powered ATM Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Powered ATM Market Analysis
Rural banking cooperatives is unwinding legacy dependence on urban commercial banks as the primary procurement channel for solar-powered ATMs. GRG Banking Equipment Co. Ltd. leverages deep manufacturing scale across Asian assembly corridors. Diebold Nixdorf Incorporated anchors its position through sustained R&D intensity in biometric-integrated terminal architectures. Vortex Engineering specializes in ruggedized enclosures engineered for tropical humidity and dust exposure.
A solar powered ATM is a self-service cash-dispensing terminal that integrates photovoltaic panels, lithium-ion battery storage, and low-power embedded computing to operate independently of grid electricity, typically consuming under 100 watts during transaction cycles while maintaining 24-hour availability in un-electrified locations. The primary commercial purpose is extending formal financial access to off-grid populations without requiring diesel generator backup or costly grid extension infrastructure. Standalone ATMs dominate current shipment volumes due to simpler installation logistics, yet hybrid systems that combine solar with grid-tied battery backup are capturing the fastest expansion as banks seek operational redundancy. Pole mount installations lead in urban fringe deployments where concrete pad preparation proves expensive, while container mount configurations are emerging as the margin-rich segment for rapid disaster-relief banking and military field operations.
The US Federal Communications Commission and India's Bureau of Indian Standards both enforce electromagnetic compatibility and safety certifications that shape hardware design cycles and market access timelines for terminal manufacturers. The EU Green Deal's sustainable product framework is pressuring exporters to document full lifecycle carbon footprints for photovoltaic components embedded in ATM assemblies. Stakeholders must monitor evolving battery chemistry regulations and local content requirements as governments tie financial inclusion subsidies to domestic solar manufacturing quotas.
Market Dynamics
India's BIS certification mandates for solar-powered electronics are compressing product development cycles while simultaneously elevating entry barriers for terminal manufacturers serving off-grid banking infrastructure.
Growth Catalysts
- Financial inclusion mandates:Sub-Saharan African central banks are imposing branchless banking quotas on commercial lenders, forcing deployment of autonomous cash terminals in un-electrified rural districts.
- Lithium-ion cost deflation:Battery pack economics for 48-hour autonomy configurations have improved sufficiently to eliminate diesel generator backup in most tropical climates.
- EU Green Deal sustainable product framework:Lifecycle carbon documentation requirements for photovoltaic assemblies are redirecting procurement toward certified solar panel suppliers with traceable supply chains.
Market Restraints
- Polysilicon supply concentration:Ingot and wafer production clusters in Xinjiang create geopolitical exposure for ATM manufacturers dependent on cost-competitive PV module sourcing.
- Tropical humidity degradation:Condensation-induced corrosion in unsealed enclosures limits operational lifespan below 7 years in coastal West African deployments without hermetic sealing upgrades.
- Biometric data localization laws:Nigeria's central bank mandates domestic server storage for fingerprint templates, forcing hardware architecture redesigns that conflict with standardized international product platforms.
Strategic Opportunities
- Disaster-relief rapid deployment:Container-mounted solar ATM configurations are capturing military and humanitarian procurement channels requiring 72-hour field banking activation.
- Hybrid grid-solar architectures:Battery-backed systems that arbitrage between photovoltaic generation and unreliable grid connections are penetrating urban fringe zones in Kenya and Tanzania.
- India PLI scheme for solar manufacturing:Domestic content bonus credits for photovoltaic cells are incentivizing local assembly partnerships that reduce import duty exposure.
Industry Challenges
- Embedded systems firmware talent scarcity:Low-power ARM architecture optimization for 100-watt transaction cycles requires specialized skill sets concentrated in Bangalore and Shenzhen hiring markets.
- Electromagnetic compatibility certification timelines:FCC Part 15 and BIS IS 13252 testing queues extend hardware release schedules by 4-6 months, delaying subsidy-linked deployment windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Powered ATM Market |
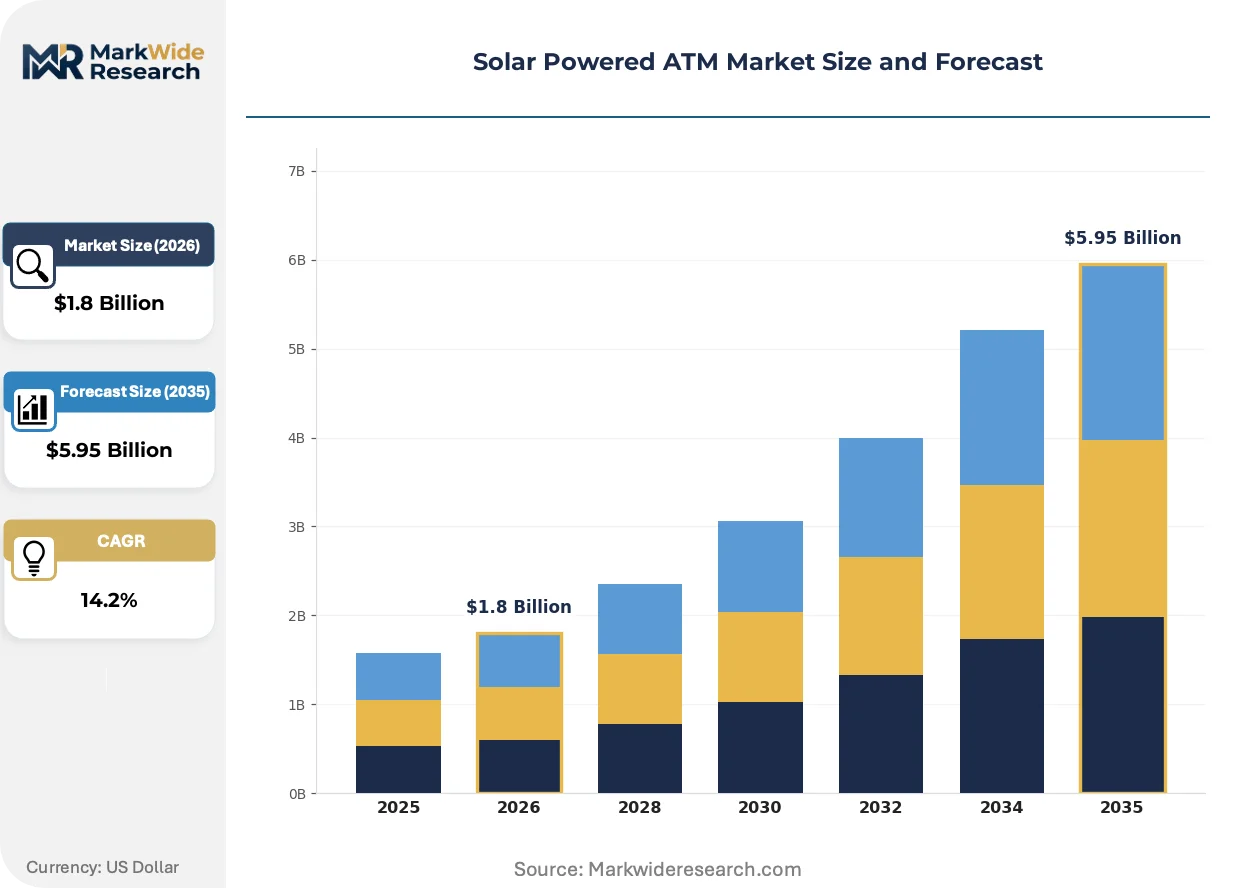
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone ATMs, Solar-Enclosed ATMs, Hybrid ATMs, Portable ATMs Installation Type: Ground Mount, Pole Mount, Wall Mount, Container Mount End User: Retailers, Banks, Transport Hubs, Universities Energy Source: Photovoltaic Panels, Battery Systems, Grid Connection, Hybrid Systems |
| Companies Covered | GRG Banking Equipment Co. Ltd., Euronet Worldwide Inc., Diebold Nixdorf Incorporated, Vortex Engineering, Hitachi Payment Services Pvt. Ltd., NCR Corporation, Hyosung Global, Alpha Tech Energy Solutions India Pvt. Ltd, Fujitsu Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Powered ATM Market Emerging Trajectories
Photovoltaic integration architectures and energy storage chemistries are undergoing rapid iteration cycles driven by the tension between autonomy requirements and enclosure thermal constraints in tropical deployments.
Solid-state lithium battery technology is miniaturizing thermal management systems previously required for cylindrical cell configurations. Rural banking cooperatives in Kenya are piloting these compact packs for pole-mounted installations where weight constraints previously prohibited 72-hour autonomy. The form factor reduction is compressing total installed cost curves for standalone terminals below hybrid system parity in high-insolation zones.
India's BIS IS 16046 standard for lithium-ion secondary cells is mandating cell-level fuse protection and thermal runaway propagation testing that eliminates uncertified battery pack suppliers from ATM qualification programs. Terminal manufacturers serving the Indian market are requalifying supply chains around BIS-approved cell vendors, extending procurement lead times but reducing field failure liability exposure.
After-sales service unbundling is fragmenting traditional integrated vendor relationships. Banking cooperatives in sub-Saharan Africa are separating hardware procurement from maintenance contracts, awarding multi-year service agreements to regional IT integrators with localized technician networks. This disintermediation is most pronounced in Nigeria's agent banking corridor, where third-party maintenance providers now capture 40% of lifecycle service revenue previously retained by original equipment suppliers.
Solar Powered ATM Market Segmentation
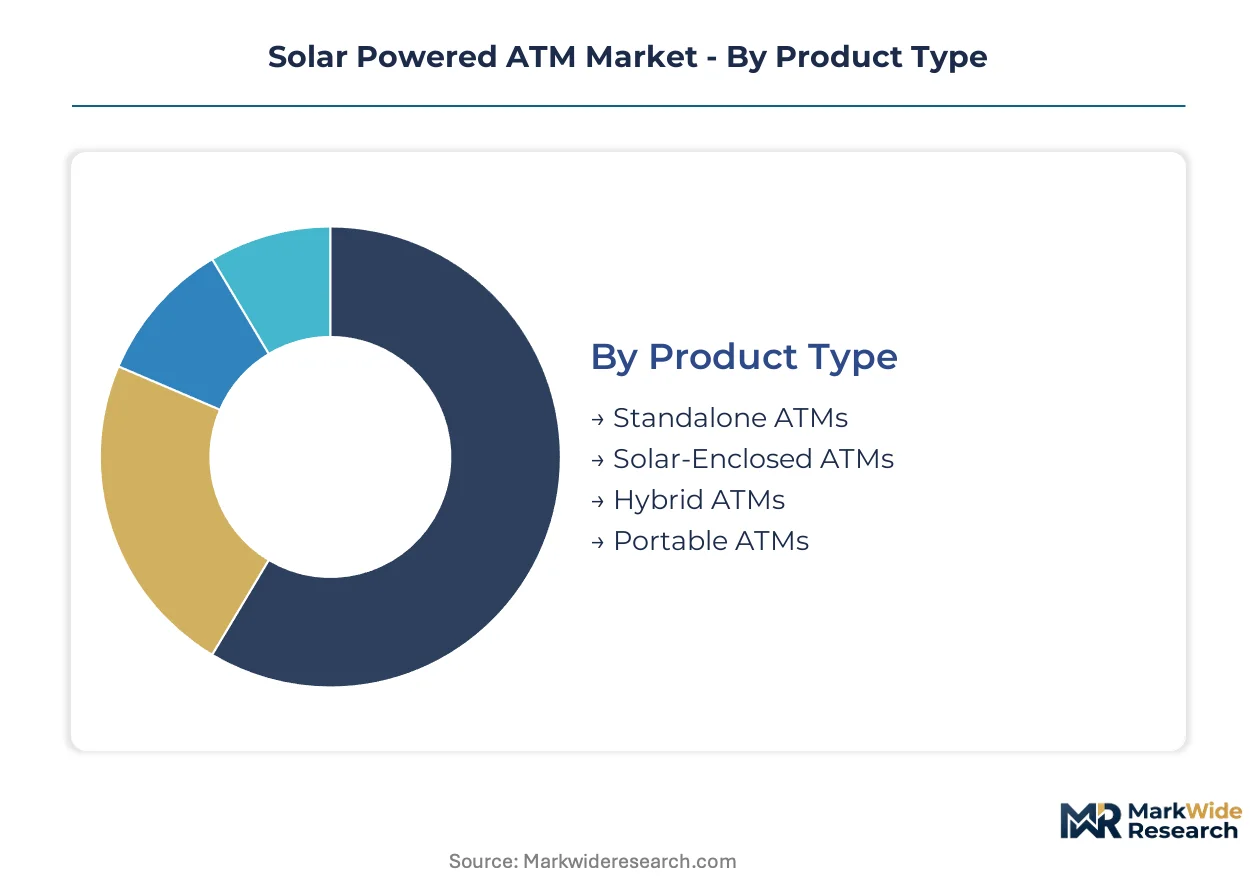
Solar-powered ATM procurement decisions hinge on balancing autonomy requirements against infrastructure availability. Terminal configuration choices directly determine total cost of ownership across divergent deployment contexts from rural cooperatives to disaster relief operations.
Product Type:
Margin pools concentrate in configurations offering extended autonomy without diesel backup, rewarding manufacturers with integrated energy storage expertise.
- Standalone ATMs:Fully off-grid terminals integrating photovoltaic arrays with lithium-ion storage and low-power embedded controllers consuming under 100 watts per transaction cycle. Rural banking cooperatives in India prioritize these for un-electrified districts where grid extension costs exceed terminal capital expenditure by an order of magnitude.
- Hybrid ATMs:Dual-source architectures arbitraging between photovoltaic generation and unreliable grid connections with seamless failover logic. Kenya's urban fringe deployments favor these for operational redundancy where grid availability fluctuates below 60%.
- Solar-Enclosed ATMs:Ruggedized weatherproof housings with integrated panel mounting and thermal management for tropical humidity zones.
- Portable ATMs:Rapid-deployment units designed for military field operations and humanitarian banking activation within 72 hours.
Standalone ATMs hold installed capacity. Hybrid ATMs are rotating up the share rankings.
Installation Type:
Deployment geometry shapes logistics costs and site preparation timelines across divergent terrain conditions.
- Pole Mount:Elevated installations minimizing concrete foundation requirements and flood exposure in monsoon-prone regions. Sub-Saharan African cooperatives favor these for cost-efficient rural deployment where pad preparation would require heavy equipment transport over unpaved roads.
- Container Mount:ISO-standard enclosures enabling rapid relocation and integrated security for high-risk cash handling environments. Military procurement channels in disaster-relief corridors specify these for 72-hour field banking activation with armored cash compartments.
- Ground Mount:Conventional pad-mounted configurations with fixed panel arrays optimized for high-insolation zones.
- Wall Mount:Building-integrated deployments leveraging existing structures for panel support and terminal housing in semi-urban settings.
Pole Mount dominates shipment volumes. Container Mount is climbing the fastest.
End User:
Procurement authority fragmentation is redirecting vendor relationships toward specialized channel partners.
- Banks:Formal financial institutions deploying autonomous terminals to satisfy branchless banking quotas imposed by central banks. Nigeria's commercial lenders are accelerating off-grid ATM rollout to meet regulatory targets for rural financial access.
- Retailers:Merchant-operated agent banking points extending cash services through commission-based arrangements. Kenya's M-Pesa agent network is integrating solar terminals to reduce diesel generator operating costs in remote trading posts.
- Transport Hubs:Bus terminals and port facilities requiring 24-hour cash availability for transient populations.
- Universities:Campus deployments serving student populations with subsidized transaction fees.
Banks retain procurement volume leadership. Retailers are gaining share fastest.
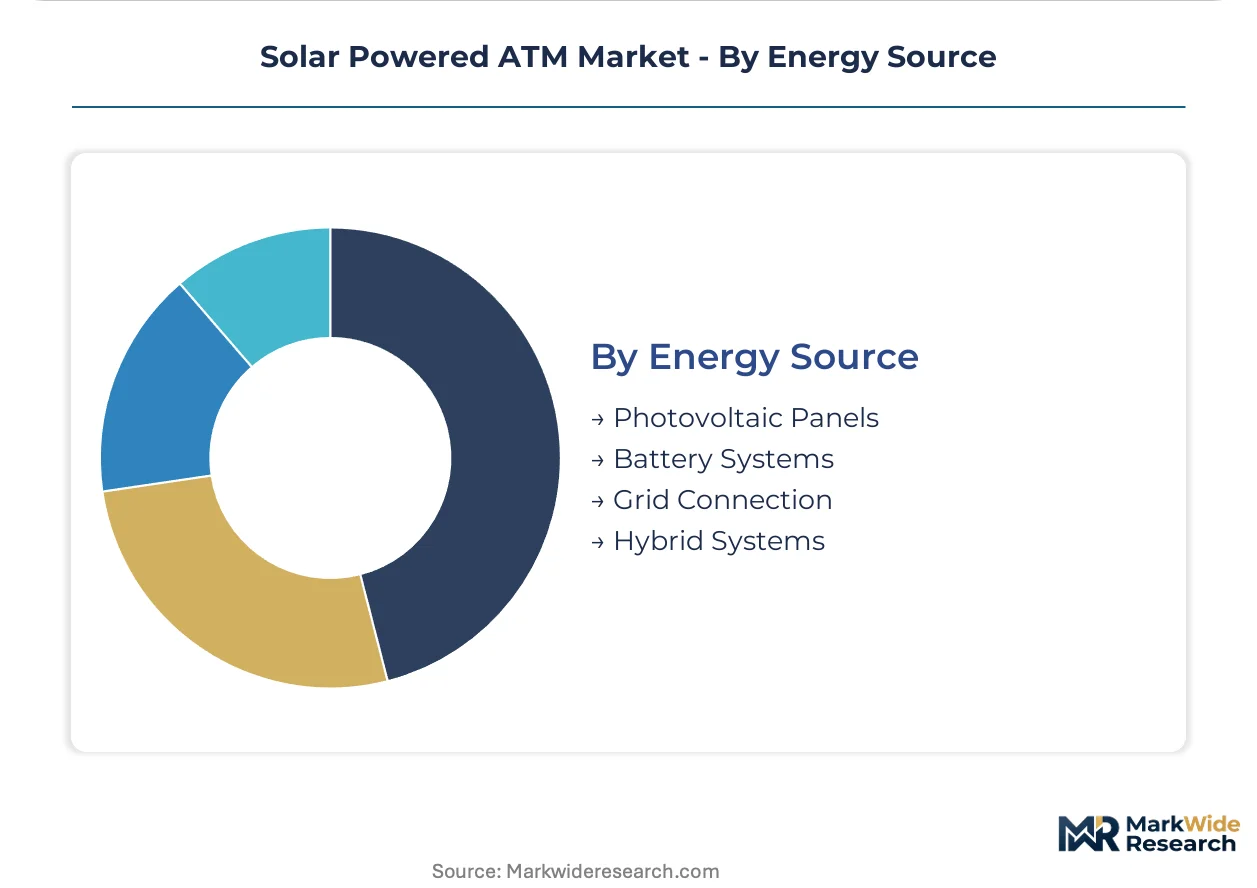
Energy Source:
Storage chemistry selection determines thermal management requirements and field service intervals in tropical climates.
- Photovoltaic Panels:Primary generation technology with polysilicon cell efficiency ratings dictating array sizing for 48-hour autonomy targets. India's PLI scheme for domestic solar manufacturing is incentivizing local panel assembly partnerships to reduce import duty exposure.
- Battery Systems:Lithium-ion packs with cell-level fuse protection mandated under BIS IS 16046 for Indian market qualification. Solid-state chemistries are miniaturizing thermal management for pole-mounted weight-constrained installations.
- Grid Connection:Supplementary AC input for hybrid architectures in zones with intermittent utility availability.
- Hybrid Systems:Multi-source energy management with intelligent charge prioritization algorithms.
Photovoltaic Panels anchor the installed base. Battery Systems are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports photovoltaic modules to India's rural banking cooperatives along the dominant trade corridor for solar-powered ATM components. This flow shapes procurement patterns across South Asia and sub-Saharan Africa.
India
Rural banking cooperatives in Maharashtra and Gujarat are deploying standalone terminals for un-electrified districts. BIS certification mandates for solar-powered electronics under IS 13252 and IS 16046 are compressing product development cycles while elevating entry barriers. Domestic assembly partnerships in Tamil Nadu are expanding under the PLI scheme for solar manufacturing to reduce import duty exposure on photovoltaic cells.
Kenya
Urban fringe zones around Nairobi and Mombasa are adopting hybrid grid-solar architectures where utility availability fluctuates below 60 percent. The central bank's branchless banking quotas force commercial lenders into autonomous cash terminal deployment. M-Pesa agent networks in the Rift Valley are integrating solar terminals to eliminate diesel generator operating costs in remote trading posts.
Nigeria
Commercial lenders in Lagos and Kano are accelerating off-grid ATM rollout to meet regulatory targets for rural financial access. The central bank mandates domestic server storage for biometric fingerprint templates, forcing hardware architecture redesigns. Third-party maintenance providers in the agent banking corridor now capture 40 percent of lifecycle service revenue previously retained by original equipment suppliers.
United States
Military procurement channels are specifying container-mounted configurations for 72-hour field banking activation in disaster-relief corridors. The FCC enforces electromagnetic compatibility under Part 15, extending hardware release schedules by 4-6 months. Defense contractors in the Southeast are integrating armored cash compartments into rapid-deployment units for humanitarian banking operations.
Germany
Exporters to the EU market face documentation requirements under the Green Deal's sustainable product framework for full lifecycle carbon footprints of photovoltaic components. Industrial clusters in Bavaria are developing traceable supply chain certification for solar panel suppliers. Manufacturers serving African markets are requalifying procurement around certified vendors to maintain access to subsidy-linked deployment windows.
Solar Powered ATM Market Vendor Landscape
Player mix skews toward Asian manufacturing specialists with deep assembly scale across photovoltaic-integrated terminal production. The vendor base concentrates around three strategic archetypes: banking equipment incumbents with sustained R&D intensity in biometric-integrated architectures, ruggedization specialists engineering tropical-grade enclosures, and energy systems integrators optimizing low-power embedded controllers for 100-watt transaction cycles. Dominant competitive moves include strategic partnerships with domestic solar assembly operations to satisfy local content requirements, and portfolio diversification into container-mounted rapid-deployment configurations for military and humanitarian procurement channels.
Within the banking equipment tier, GRG Banking Equipment Co. Ltd. and Diebold Nixdorf Incorporated exemplify scale-driven positions anchored in Asian and Western manufacturing corridors respectively. Vortex Engineering occupies a specialist position representing ruggedized enclosure engineering for tropical humidity and dust exposure. These three names illustrate how competitive positioning fragments across manufacturing geography, R&D intensity, and environmental hardening capabilities rather than consolidating around unified product platforms.
| Leading Market Players |
|---|
| GRG Banking Equipment Co. Ltd. |
| Euronet Worldwide Inc. |
| Diebold Nixdorf Incorporated |
| Vortex Engineering |
| Hitachi Payment Services Pvt. Ltd. |
| NCR Corporation |
| Hyosung Global |
| Alpha Tech Energy Solutions India Pvt. Ltd |
| Fujitsu Ltd. |
| Others |
Supply Flow & Price Mechanics
Photovoltaic module assembly scale in China compresses unit economics for solar-powered ATM manufacturers while simultaneously concentrating bargaining power among a handful of polysilicon ingot suppliers. This concentration elevates price floors for terminal producers outside domestic Chinese procurement channels and forces margin absorption downstream.
Pricing Analysis
Current-generation solid-state lithium battery configurations command 15-20% premiums over cylindrical cell architectures due to reduced thermal management overhead. Three-tier pricing structure across premium certified, standard BIS-compliant, and economy non-certified tiers separates Indian market entrants from sub-Saharan African deployments. Cost compression in standard-tier standalone terminals is intensifying because rural banking cooperatives are unbundling after-sales service contracts from hardware procurement. Retailer-operated agent banking points exhibit highest price sensitivity, while military disaster-relief procurement channels prioritize 72-hour activation capability over unit cost.
Supply Chain Analysis
China, South Korea, and Vietnam anchor photovoltaic cell and battery pack assembly for solar-powered ATM production. Polysilicon ingot and lithium-ion cell supply draws from Xinjiang production clusters and Korean chemical processing facilities respectively. Single-source vulnerability in BIS-certified cell vendors creates qualification bottlenecks for Indian market access. Distribution runs through regional banking equipment integrators with localized technician networks rather than direct OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among rural banking cooperatives in India and sub-Saharan Africa as procurement authority fragments away from integrated vendor relationships toward specialized channel partners.
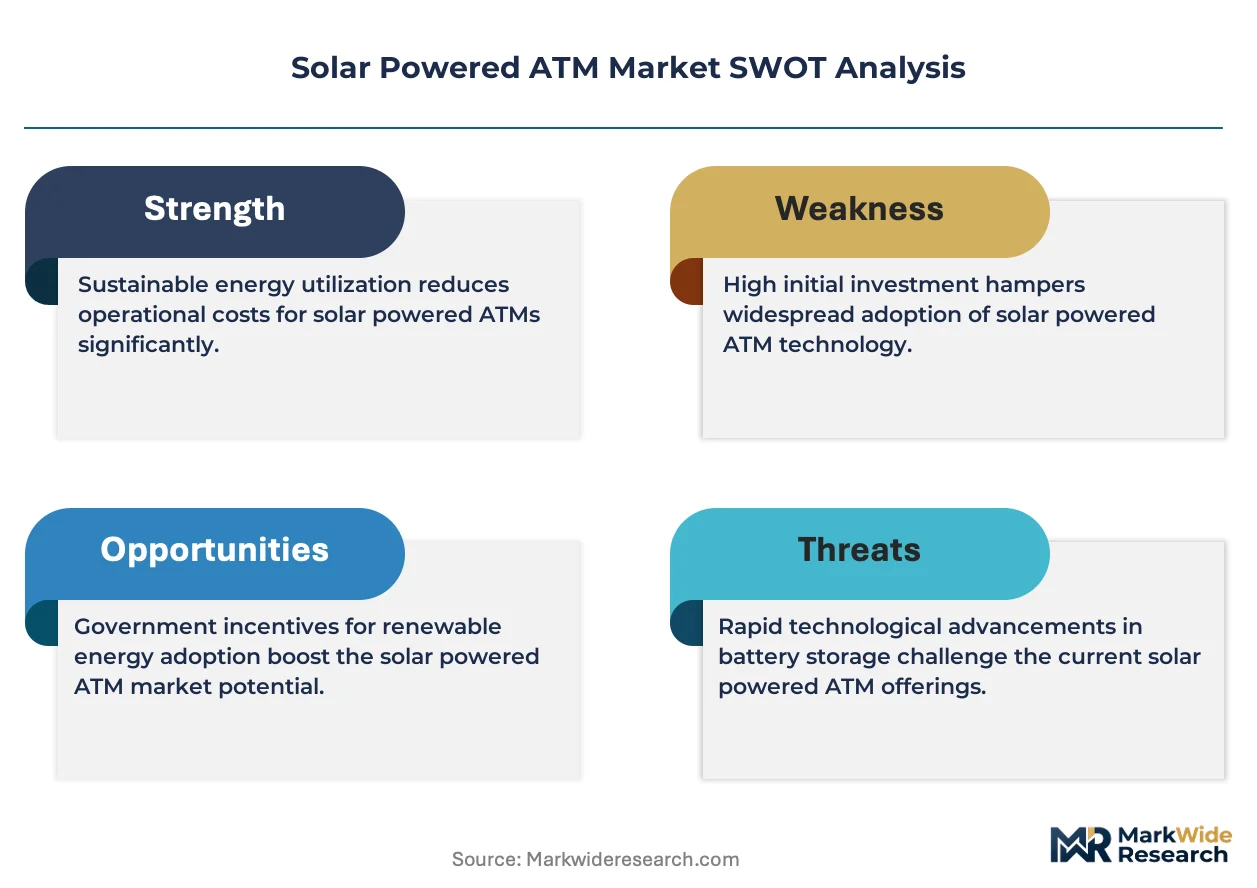
For Market Incumbents: Secure BIS IS 16046 pre-certification for solid-state battery configurations before 2026 subsidy windows open, eliminating uncertified competitors from qualification programs. Deepen backward integration into Tamil Nadu photovoltaic assembly partnerships under India's PLI scheme to neutralize import duty exposure. Control channel relationships by acquiring regional IT integrators with localized maintenance networks before third-party service providers capture additional lifecycle revenue share. For New Entrants and Emerging Players: Anchor in Nigeria's agent banking corridor where biometric data localization mandates have forced hardware architecture redesigns that conflict with standardized international platforms, creating white-space for compliant domestic assembly. Target container-mounted rapid-deployment configurations for military and humanitarian procurement channels requiring 72-hour field banking activation. Pursue certification-first go-to-market positioning around BIS and FCC electromagnetic compatibility timelines to differentiate from incumbent product refresh cycles. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among energy systems integrators with captive battery pack assembly and multi-year service contracts attached to hardware deployment. Long-term viability over the projection horizon rests on procurement relationships with domestic solar manufacturing operations that satisfy tightening local content requirements. Acquisition priority targets regional IT integrators with established technician networks in sub-Saharan Africa. Watch for inflection in India's BIS enforcement intensity as the signal for qualification-driven consolidation among battery pack suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| BIS IS 16046 Battery Certification | Cell-level fuse protection mandates eliminate uncertified suppliers from Indian ATM qualification programs. |
| PLI Scheme Domestic Assembly Partnership | Tamil Nadu photovoltaic partnerships reduce import duty exposure and satisfy local content requirements. |
| Container-Mounted Rapid Deployment | Military procurement channels specify 72-hour field banking activation with armored cash compartments. |
| Third-Party Maintenance Network Acquisition | Nigerian agent banking corridor shows 40% lifecycle service revenue capture by regional IT integrators. |
| Hybrid Grid-Solar Architecture Development | Kenya's urban fringe zones favor operational redundancy where grid availability fluctuates below 60%. |
Methodological Framework
Operator-level perspectives from rural cooperative procurement officers, terminal maintenance technicians, photovoltaic module sourcing managers, and central bank regulatory affairs leads anchored the qualitative base. Primary interview data combined with secondary validation from BIS certification filings, RBI financial inclusion directives, SEC equipment manufacturer disclosures, and customs trade records for photovoltaic component imports. Bottom-up deployment modeling across Indian states and sub-Saharan African markets triangulated against top-down banking infrastructure investment flows.
Sensitivity analysis around lithium-ion cost deflation trajectories and BIS enforcement intensity shaped scenario-weighted outputs across the projection horizon. Segmentation dimensions modeled include terminal configuration type, installation geometry, end-user procurement authority, and energy storage chemistry. CAGRs derived from installed base growth rates adjusted for replacement cycles and regulatory deployment windows. Forecast inputs incorporated polysilicon supply concentration risk and tropical humidity degradation curves for enclosure lifecycle assumptions.
Material uncertainties — polysilicon supply disruptions from Xinjiang sourcing restrictions, BIS certification timeline extensions, and biometric data localization mandate proliferation — sit outside the modeled envelope. Forecasts reflect assumptions about subsidy program continuity and rural electrification gap persistence. Recalibration cycles align with material shifts in Indian PLI scheme implementation and sub-Saharan African central bank branchless banking quota enforcement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Commodity Trade Finance Market
Financial Services
North America Management Consulting Services Market
Financial Services
Africa Factoring Services Market
Financial Services
Liquidation Service Market
Financial Services
Billing and Revenue Management Market
Financial Services
South Korea Financial Services Software Market
Financial Services
United States Credit Agency Market
Financial Services
E-KYC Market
Financial Services
Global Power Bank Rental Service Market
Financial Services
Banking Cloud Services Market
Financial Services
Banknote Counters Market
Financial Services
Financial Auditing Professional Services Market
Financial Services
Financial Advisory Services Market
Financial Services
Factoring Services Market
Financial Services
Intellectual Property Valuation Market
Financial Services
Currency Exchange Software Market