
 Buy Now Pay Later Platform Market | 2026-2036
Buy Now Pay Later Platform Market Size, Share, and Industry Trends Forecast 2026-2036
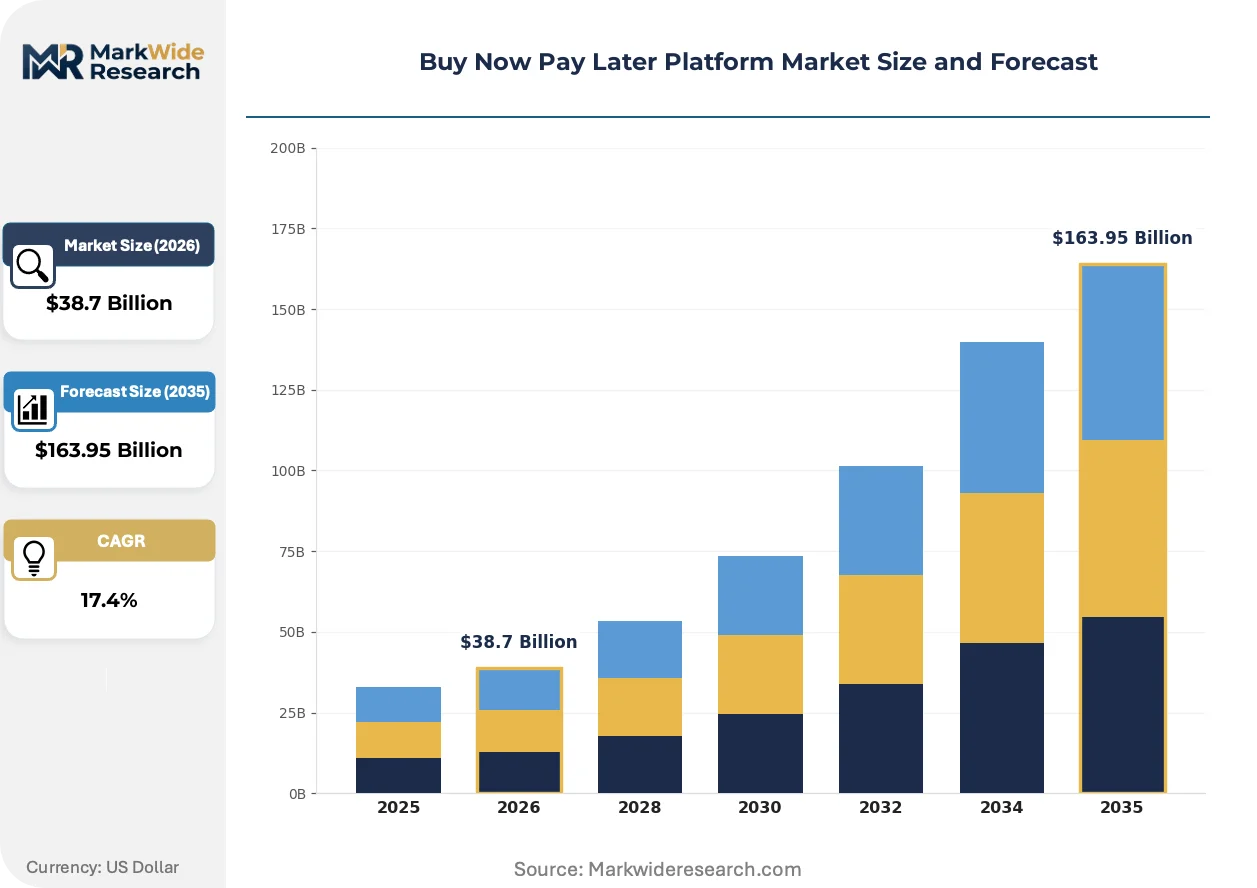
Buy Now Pay Later Platform Market Outlook
Millennial dominance in Buy Now Pay Later adoption is collapsing as Gen Z consumers flood into installment payment tools for online fashion and electronics. Klarna leverages its embedded checkout network across European and North American retail sites to sustain merchant lock-in. Affirm anchors the high-ticket vertical through partnerships with furniture and electronics retailers. Afterpay competes in the Asia-Pacific corridor through localized brand positioning and influencer-driven acquisition.
A Buy Now Pay Later Platform is a digital credit infrastructure that splits consumer purchases into scheduled payments, typically integrating via REST APIs and tokenized payment rails at merchant checkout points. Its commercial purpose is to reduce cart abandonment while transferring credit risk from retailers to specialized lenders. Installment payment services now lead service-type revenue pools because merchants subsidize interest-free periods to drive conversion. E-commerce integration dominates the integration-level landscape as checkout-embedded APIs replace redirect-based flows. Gen Z within the customer-type dimension represents the fastest-growing acquisition cohort due to thin-file credit profiles and mobile-native purchasing habits.
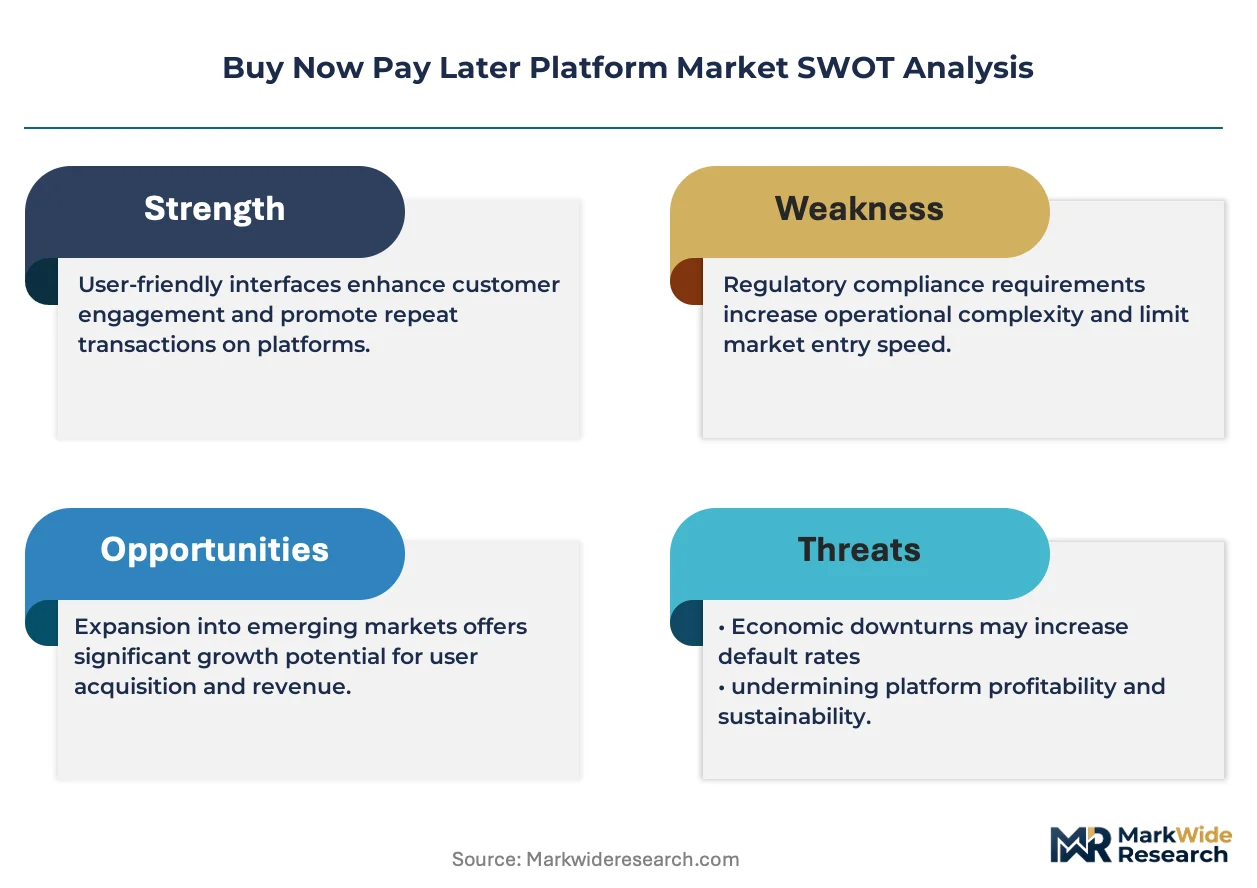
The Consumer Financial Protection Bureau in the United States, the Financial Conduct Authority in the United Kingdom, and the Australian Securities and Investments Commission are each constructing sector-specific disclosure and affordability frameworks that reshape product design and limit automatic credit-line expansion. These regulators increasingly mandate standardized cost disclosures and hardship protocols, forcing platforms to reengineer underwriting engines and merchant pricing models. Stakeholders must monitor which jurisdiction first mandates income-verification requirements, as this will trigger cascading compliance redesigns across multi-market operators.
Market Dynamics
Open banking API proliferation is compressing underwriting cycles from days to milliseconds, forcing platforms to rebuild risk engines around real-time data streams rather than traditional credit bureau pulls. This technical shift is redrawing competitive moats.
Growth Catalysts
- Regulatory Disclosure Mandates:The Consumer Financial Protection Bureau's standardized cost disclosure requirements in the United States are forcing product transparency that builds consumer trust and reduces comparison friction.
- Gen Z Fashion Commerce:Thin-file younger consumers in online apparel and electronics are adopting installment tools at checkout points for discretionary purchases under five hundred dollars.
- Real-Time Scoring Algorithms:Machine learning models analyzing transaction-level banking data are expanding approval rates for previously unscorable applicants.
Market Restraints
- Credit Loss Concentration:Macroeconomic stress in discretionary retail verticals is elevating default rates among subprime cohorts and compressing lender margins.
- Merchant Subsidy Burden:Interest-free period financing requires retailers to absorb discount fees, creating resistance in low-margin grocery and essentials categories.
- Regulatory Fragmentation:Divergent state-level lending license requirements across the United States multiply compliance costs for multi-jurisdiction operators.
Strategic Opportunities
- Healthcare Services Penetration:Elective medical and dental procedures in the United States represent an underexploited vertical with predictable payment streams and lower default correlation.
- Embedded B2B Trade Credit:Small business invoice financing integrated into procurement platforms offers higher ticket sizes and stickier merchant relationships.
- Hardship Protocol Incentives:Australian Securities and Investments Commission guidelines rewarding responsible lending practices create regulatory arbitrage for compliant operators.
Industry Challenges
- Legacy Core Banking Integration:Middleware development for real-time settlement with established payment networks demands specialized engineering talent and extended deployment timelines.
- Affordability Assessment Complexity:Income verification without payroll data access requires partnerships with account aggregation providers and creates data latency in approval flows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Buy Now Pay Later Platform Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $163.95 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Customer Type: Millennials, Gen Z, Credit Seekers, E-commerce Shoppers Service Type: Direct Payment, Installment Payment, Deferred Payment, Interest-Free Payment Industry Vertical: Retail, Travel, Consumer Electronics, Fashion Integration Level: API Integration, In-store Integration, E-commerce Integration, Mobile App Integration |
| Companies Covered | Klarna, Affirm, Afterpay, PayPal, Zip, Sezzle, Tabby, Tamara, Openpay, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Buy Now Pay Later Platform Market Strategic Shifts
Checkout-embedded financing is fragmenting into specialized vertical stacks. Platforms are abandoning horizontal marketplaces in favor of purpose-built underwriting models tied to specific purchase categories and risk profiles.
AI-powered risk decisioning is bifurcating the competitive landscape. Advanced platforms deploy neural networks analyzing thousands of behavioral signals to price risk dynamically. Traditional operators relying on FICO scores and static rulesets are retreating toward prime-only segments. This technological divergence is compressing margins for mid-tier players caught between automation investment requirements and legacy infrastructure debt.
The Financial Conduct Authority in the United Kingdom is mandating pre-contractual affordability assessments with specific debt-to-income thresholds. Lenders must now verify sufficient disposable income before extending credit, regardless of automated approval scores. High-frequency, low-ticket fashion purchases face the strictest scrutiny, pushing platforms to redesign checkout flows with explicit cooling-off periods.
Subscription bundling is displacing standalone installment offerings at merchant checkout. Retailers in the United States are negotiating all-in-one payment partnerships combining loyalty programs, installment options, and stored-value wallets. This consolidation reduces merchant willingness to maintain multiple lender integrations, concentrating volume with full-stack providers capable of unified commerce experiences.
Buy Now Pay Later Platform Market Segmentation
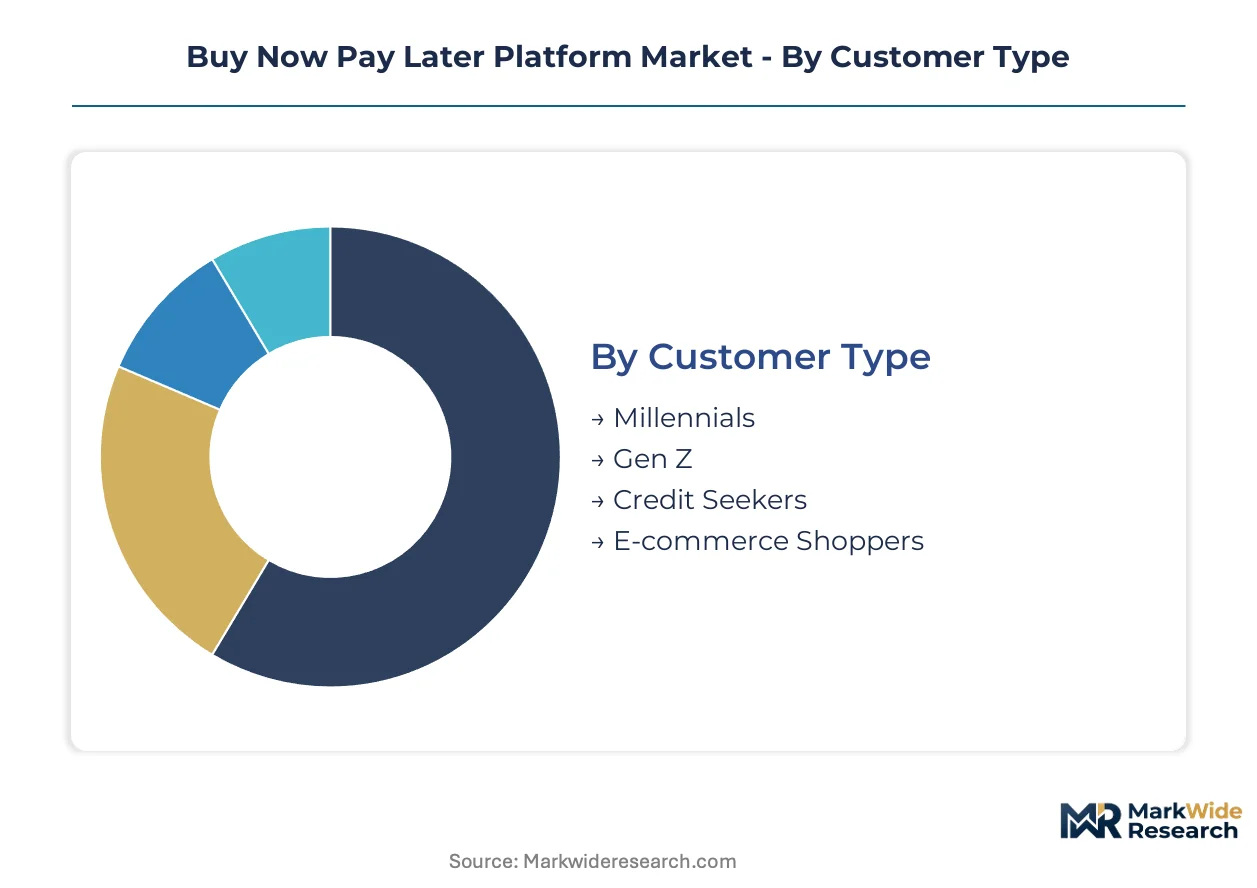
Segmentation in the Buy Now Pay Later Platform Market reveals divergent margin profiles across customer cohorts and integration architectures. Platforms optimize underwriting engines and merchant pricing models differently for each segment, creating distinct competitive battlegrounds.
Customer Type:
Margin pools concentrate in thin-file segments where risk-based pricing commands premium merchant fees.
- Millennials:Established credit histories enable lower-friction approvals for mid-ticket discretionary purchases. Demand clusters in United States furniture and home improvement verticals where platforms like Affirm anchor merchant partnerships.
- Gen Z:Mobile-native purchasing habits and limited credit files require real-time bank data integration for approval decisions. United Kingdom and Australian regulators scrutinize this cohort most heavily for affordability compliance.
- Credit Seekers:Subprime applicants drive higher default correlation but attract specialized lenders with alternative data models.
- E-commerce Shoppers:Checkout-embedded convenience reduces comparison shopping, locking in repeat usage patterns.
Millennials hold installed capacity. Gen Z is rotating up the share rankings.
Service Type:
Merchant subsidy structures determine which payment structures generate sustainable unit economics.
- Installment Payment:Scheduled payment splits dominate revenue pools as retailers absorb discount fees to drive conversion. United States fashion and electronics merchants subsidize interest-free periods most aggressively.
- Interest-Free Payment:Zero-APR periods require precise loss-rate forecasting against merchant fee income. Australian Securities and Investments Commission disclosure mandates reshape product design for this structure.
- Direct Payment:Immediate settlement with deferred billing carries lower credit risk but thinner margins.
- Deferred Payment:Pay-later options without installment scheduling attract regulatory scrutiny for hidden cost structures.
Installment Payment holds installed capacity. Interest-Free Payment is rotating up the share rankings.
Industry Vertical:
Default correlation varies sharply across purchase categories, segmenting risk appetite among specialized lenders.
- Fashion:High-frequency, low-ticket apparel purchases face strictest affordability scrutiny from United Kingdom Financial Conduct Authority. Gen Z concentration in this vertical demands enhanced cooling-off period protocols.
- Consumer Electronics:Predictable depreciation curves and warranty coverage reduce loss severity on defaulted obligations. United States retailers negotiate volume-based merchant fee tiers for smartphone and laptop financing.
- Retail:General merchandise spans diverse risk profiles requiring dynamic underwriting adjustments.
- Travel:Booking value volatility and cancellation risk create unique exposure patterns for deferred payment products.
Consumer Electronics holds installed capacity. Fashion is rotating up the share rankings.
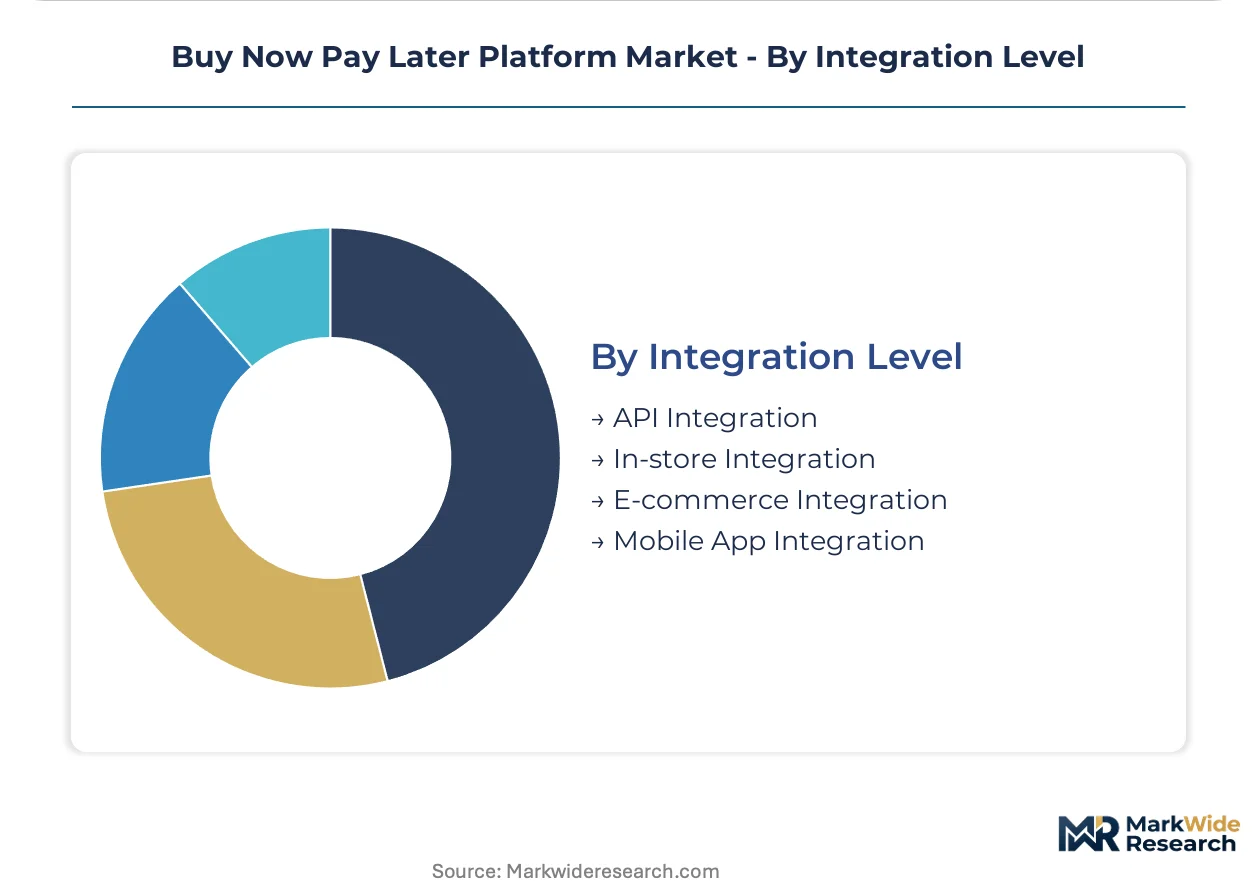
Integration Level:
Technical architecture choices determine merchant switching costs and platform defensibility.
- E-commerce Integration:Checkout-embedded APIs displace redirect-based flows as the dominant deployment mode. REST API tokenization at merchant checkout points reduces cart abandonment most effectively.
- API Integration:Direct technical integration enables real-time decisioning and customized user experiences. Open banking data streams require specialized engineering talent for millisecond underwriting cycles.
- Mobile App Integration:Native SDK deployment captures in-app purchase volume but fragments across iOS and Android ecosystems.
- In-store Integration:Point-of-sale terminal compatibility demands legacy payment network middleware development.
E-commerce Integration holds installed capacity. API Integration is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Younger buyers with thin credit files dominate adoption patterns across mature digital economies. United States, United Kingdom, and Australia concentrate the highest transaction volumes. Regulatory divergence is reshaping product design in each jurisdiction.
United States
Gen Z consumers in online fashion and electronics drive checkout-embedded financing volume. The Consumer Financial Protection Bureau mandates standardized cost disclosures that force platforms to reengineer underwriting engines. Los Angeles and New York City merchant clusters subsidize interest-free periods most aggressively for discretionary purchases under five hundred dollars.
United Kingdom
Millennial furniture and home improvement buyers anchor mid-ticket installment demand. The Financial Conduct Authority requires pre-contractual affordability assessments with specific debt-to-income thresholds. London fintech corridors concentrate engineering talent for real-time bank data integration and millisecond approval cycles.
Australia
High-frequency, low-ticket apparel purchases face strictest regulatory scrutiny for Gen Z affordability compliance. The Australian Securities and Investments Commission guidelines reward responsible lending practices with operational clarity. Sydney and Melbourne retail networks deploy enhanced cooling-off period protocols at fashion merchant checkouts.
Germany
Open banking API proliferation compresses underwriting cycles for thin-file applicants in consumer electronics. The country's national financial regulator constructs sector-specific disclosure frameworks that reshape merchant pricing models. Berlin and Munich technology clusters specialize in REST API tokenization for embedded checkout networks.
Canada
E-commerce integration displaces redirect-based flows as dominant deployment mode for installment services. Provincial-level lending license requirements multiply compliance costs for cross-border operators. Toronto and Vancouver merchant partnerships concentrate on subscription bundling combining loyalty programs with deferred payment options.
Buy Now Pay Later Platform Market Competitive Environment
Player mix skews toward vertically integrated platform operators with embedded checkout networks. Three to five dominant operators control merchant relationships in major Western markets. Strategic archetypes include full-stack providers, specialized high-ticket lenders, and regional influencer-driven acquirers. Competitive moves concentrate on API infrastructure expansion and regulatory compliance redesign.
Within the full-stack tier, Klarna and Affirm exemplify divergent geographic and vertical specializations. Afterpay occupies a position in Asia-Pacific corridor development through localized positioning. These three anchors represent the spectrum from European merchant lock-in to United States high-ticket partnerships to Asia-Pacific influencer acquisition.
| Leading Market Players |
|---|
| Klarna |
| Affirm |
| Afterpay |
| PayPal |
| Zip |
| Sezzle |
| Tabby |
| Tamara |
| Openpay |
| Others |
Value Chain & Pricing Dynamics
Millisecond underwriting latency requirements compress API integration deployment cycles to 45-60 days, concentrating pricing power with platforms possessing pre-built REST tokenization stacks and merchant network density. This lead-time compression rewards operators with embedded checkout infrastructure while squeezing margins for redirect-dependent providers.
Pricing Analysis
Legacy ruleset pricing versus AI-powered neural pricing versus open-bank-data dynamic pricing stratifies platform economics across three distinct capability tiers. Merchant discount fees constitute the dominant pricing model, with interest-free period subsidies absorbed by retailers to drive conversion. Price differentiation hinges on risk-based merchant fees and real-time data integration depth. Cost compression in thin-file underwriting is intensifying because open banking API proliferation commoditizes basic approval engines. Subprime-focused lenders exhibit highest price sensitivity due to default correlation pressures, while prime-tier platforms command premium positioning through superior loss rates.
Supply Chain Analysis
Container availability constraints on Asia-Pacific trade lanes elevate inbound logistics costs for hardware-dependent point-of-sale terminal deployments. Engineering talent concentrates in the United States, the United Kingdom, and Germany for millisecond risk engine development. Core infrastructure draws from cloud compute providers, open banking data aggregators, and tokenized payment rail operators. Single-source vulnerability rests on concentrated merchant checkout platform dependencies. Distribution runs through direct API integration partnerships rather than channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform fragmentation creates specialized vertical opportunities as checkout-embedded financing splinters into category-specific underwriting stacks. Gen Z fashion commerce demands distinct affordability protocols from healthcare elective procedures.
For Market Incumbents: Compound merchant lock-in through exclusive checkout-embedded API partnerships with top-quartile e-commerce retailers. Deepen underwriting moats by acquiring specialized bank data aggregation capabilities. Neobank entrants threaten direct lending relationships. Vertical integration into real-time credit scoring infrastructure anchors defensible positioning. For New Entrants and Emerging Players: Australian Securities and Investments Commission hardship protocol certification fast-tracks regulatory credibility for compliant operators. Healthcare services penetration offers white-space expansion with predictable payment streams and lower default correlation. Embedded B2B trade credit integrated into procurement platforms represents the most penetrable segment. Go-to-market through vertical SaaS partnerships enables rapid merchant acquisition without direct sales infrastructure. For Investors and Strategic Acquirers: Carve-out targets emerge from legacy financial institutions spinning off undercapitalized installment lending units. Five-to-ten-year viability hinges on AI-powered risk decisioning differentiation versus FICO-dependent legacy operators. Acquire platforms with demonstrated open banking integration and millisecond approval capabilities. Watch for income-verification mandate triggers as inflection indicators requiring cascading compliance redesigns.| Strategic Initiative | Industry Significance |
|---|---|
| API Infrastructure Expansion | REST tokenization at merchant checkout points reduces cart abandonment and raises switching costs. |
| Vertical Underwriting Specialization | Purpose-built risk models for healthcare or B2B trade credit capture premium merchant fees. |
| Regulatory Compliance Redesign | Pre-contractual affordability assessments satisfy Financial Conduct Authority debt-to-income mandates. |
| Open Banking Data Integration | Real-time transaction analysis expands approval rates for thin-file Gen Z applicants. |
| Subscription Bundling Partnerships | Unified loyalty-installment-wallet offerings concentrate volume with full-stack providers. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, merchant partnership disclosures, and open banking API documentation. The research program combined structured interviews with chief technology officers, risk management leads, merchant acquisition directors, and regulatory compliance officers at platform operators and retail partners. Secondary validation drew from Consumer Financial Protection Bureau rulemaking records, Financial Conduct Authority consultation papers, Australian Securities and Investments Commission licensing data, and trade association underwriting benchmark reports. Bottom-up transaction volume modeling and top-down market sizing triangulated demand estimates.
Segmentation dimensions modeled span customer type, service structure, industry vertical, and integration architecture across the projection horizon. The analytical framework disaggregates revenue pools by merchant subsidy structures and risk-based pricing tiers. CAGRs were derived from trend extrapolation of checkout-embedded financing penetration rates and Gen Z cohort expansion patterns. Forecast inputs incorporate open banking API adoption curves and real-time scoring algorithm deployment timelines.
Underlying assumptions cover sustained e-commerce growth, stable merchant discount fee structures, and incremental regulatory harmonization, with deviation risk concentrated in macroeconomic stress elevating subprime default rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Europe Payment Gateways Market
Payments
United Kingdom Real Time Payments Market
Payments
United Kingdom Payment Gateway Market
Payments
Singapore Payments Market
Payments
Global Real-Time Payments Market
Payments
Sweden Mobile Payments Market
Payments
India Payment Gateway Market
Payments
Spain Payment Gateway Market
Payments
Blockchain Payments Software Market
Payments
Middle East Gift Card and Incentive Card Market
Payments
Malta POS Terminal Market
Payments
Cloud Billing Market
Payments
Slovakia POS Terminal Market
Payments
Recurring Payments Market
Payments
Norway Mobile Payments Market
Payments
Wireless POS Terminals Market