
 China Enterprise Risk Management Market | 2026-2036
China Enterprise Risk Management Market Size, Share, and Industry Trends Forecast 2026-2036
China Enterprise Risk Management Market Intelligence
Buyer concentration among China's state-owned banking groups is restructuring procurement patterns for enterprise risk management platforms. Diligent leverages its governance technology heritage to compete for board-level risk oversight contracts at major financial institutions. Protiviti anchors its position through specialized consulting delivery tied to SOX-like internal control frameworks adapted for Chinese capital markets. Allianz extends its risk analytics capabilities to serve insurance-sector clients navigating the country's evolving solvency regulatory regime.
China enterprise risk management encompasses integrated software frameworks and advisory methodologies that identify, quantify, monitor, and mitigate threats to organizational value, typically incorporating real-time data ingestion, scenario modeling engines, and automated control testing against predefined risk appetite thresholds. The discipline serves primarily to protect capital adequacy, ensure regulatory compliance, and preserve operational continuity across complex, multi-entity corporate structures. Cloud-based deployment is accelerating fastest among mid-tier joint-stock banks seeking to bypass heavy infrastructure capital outlays, while on-premises solutions still dominate at policy banks and sovereign wealth funds where data localization requirements are most stringent. Compliance management solutions command concentrated vendor attention because China's layered regulatory environment—spanning PBOC, CBIRC, and CSRC mandates—generates recurring implementation and upgrade cycles.
SAMR's data governance rules, combined with PBOC's fintech supervision guidelines and the Cybersecurity Administration's cross-border transfer security assessments, collectively elevate compliance spending thresholds for domestic and foreign-invested enterprises alike. These frameworks force platform vendors to embed localized audit trails, encryption standards, and reporting formats directly into product architecture. Stakeholders must weigh the pace of regulatory harmonization against the fragmentation of provincial enforcement practices when allocating product development resources across China's risk management technology landscape.
Market Dynamics
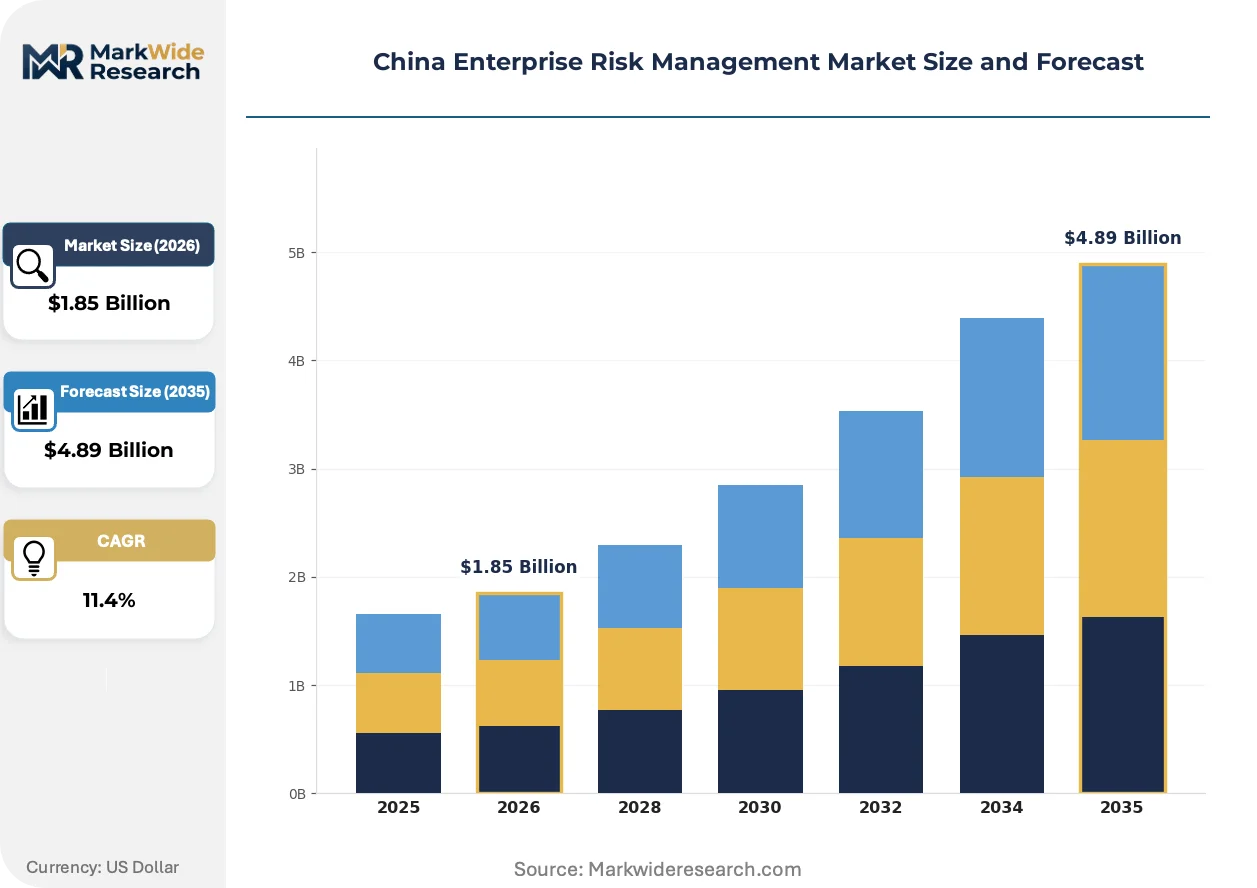
China's layered regulatory environment—spanning PBOC fintech supervision guidelines, SAMR data governance rules, and CSRC solvency mandates—is compressing procurement cycles for integrated risk platforms while elevating compliance spending thresholds across state-owned banking groups.
Growth Catalysts
- Data Security Law compliance mandates:Cross-border transfer security assessments under the Cybersecurity Administration are forcing platform upgrades at foreign-invested enterprises, creating recurring implementation cycles for localized audit trail architectures.
- Joint-stock banks:Mid-tier financial institutions in Shanghai and Shenzhen are bypassing heavy infrastructure capital outlays through cloud-based deployment models, accelerating platform adoption outside the policy bank tier.
- Real-time data ingestion:Streaming analytics engines now process transaction-level risk signals within sub-second windows, enabling dynamic capital adequacy monitoring that static batch systems cannot replicate.
Market Restraints
- Data localization hardware costs:On-premises infrastructure requirements at sovereign wealth funds and policy banks demand specialized encryption appliances, inflating total cost of ownership relative to offshore alternatives.
- Provincial enforcement fragmentation:Divergent interpretation of CBIRC circulars across eastern coastal versus interior provinces complicates single-platform standardization for national banking groups.
- Open-source analytics stacks:Apache Spark and Flink deployments in fintech subsidiaries present functional substitutes for vendor-proprietary scenario modeling engines, capping pricing power at the mid-market tier.
Strategic Opportunities
- Western province expansion:Chongqing and Chengdu banking clusters currently rely on fragmented point solutions, presenting whitespace for integrated platform consolidation as regional asset scale crosses critical thresholds.
- Carbon risk quantification:Dual carbon goals under MEE frameworks are creating demand for climate stress-testing modules that overlay traditional credit risk engines with emissions-linked default probability models.
- API-first distribution:Embedded risk-as-a-service offerings through cloud marketplaces are opening channel access to securities firms and asset managers previously served only through direct enterprise sales.
Industry Challenges
- Quantitative risk modeling talent:Shortage of professionals fluent in both stochastic calculus and Chinese regulatory reporting formats slows implementation timelines for advanced scenario engines.
- Legacy core banking integration:COBOL-era transaction systems at established state-owned institutions require costly middleware layers to feed real-time data streams into modern risk platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Enterprise Risk Management Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Offering: Risk Assessment, Compliance Management, Incident Management, Audit Management, Business Continuity Deployment Mode: Cloud-Based, On-Premises, Hybrid, Private Cloud Application Area: Operational Risk, Financial Risk, Strategic Risk, Reputation Risk, Credit Risk, Market Risk End User Industry: Manufacturing, Telecommunications, Banking, Insurance, Energy, Government |
| Companies Covered | Asanify, Hays China, Diligent, ManpowerGroup China, Korn Ferry China, Allianz, Randstad China, FESCO Adecco, Protiviti, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Enterprise Risk Management Market Strategic Shifts & Innovations
Artificial intelligence inference pipelines are reshaping how Chinese financial institutions detect anomalous transaction patterns, compressing detection latency from hours to milliseconds while forcing architectural choices between edge and cloud deployment.
Graph neural networks for counterparty risk mapping are consolidating previously siloed credit, market, and operational risk data into unified entity relationship models. Twelve joint-stock banks have piloted these systems for interbank exposure monitoring since 2024. The technology is consolidating vendor competitive positions around integrated data fabric capabilities rather than standalone analytical modules.
SAMR's 2024 data classification rules mandate granular labeling of personal and important data before cross-border transfer, compelling platform vendors to embed automated classification engines directly into data ingestion pipelines. Insurance conglomerates with multinational operations face the steepest compliance burden, driving preference for platforms with pre-configured regulatory reporting templates.
Centralized procurement by parent holding companies is displacing subsidiary-level vendor selection across state-owned banking groups. Board-level risk committees now mandate enterprise-wide platform standardization, compressing the vendor shortlist from dozens to three or four approved suppliers. This concentration is most visible at headquarters in Beijing and Shanghai, where procurement authority has shifted from IT departments to chief risk officer functions.
China Enterprise Risk Management Market Segmentation
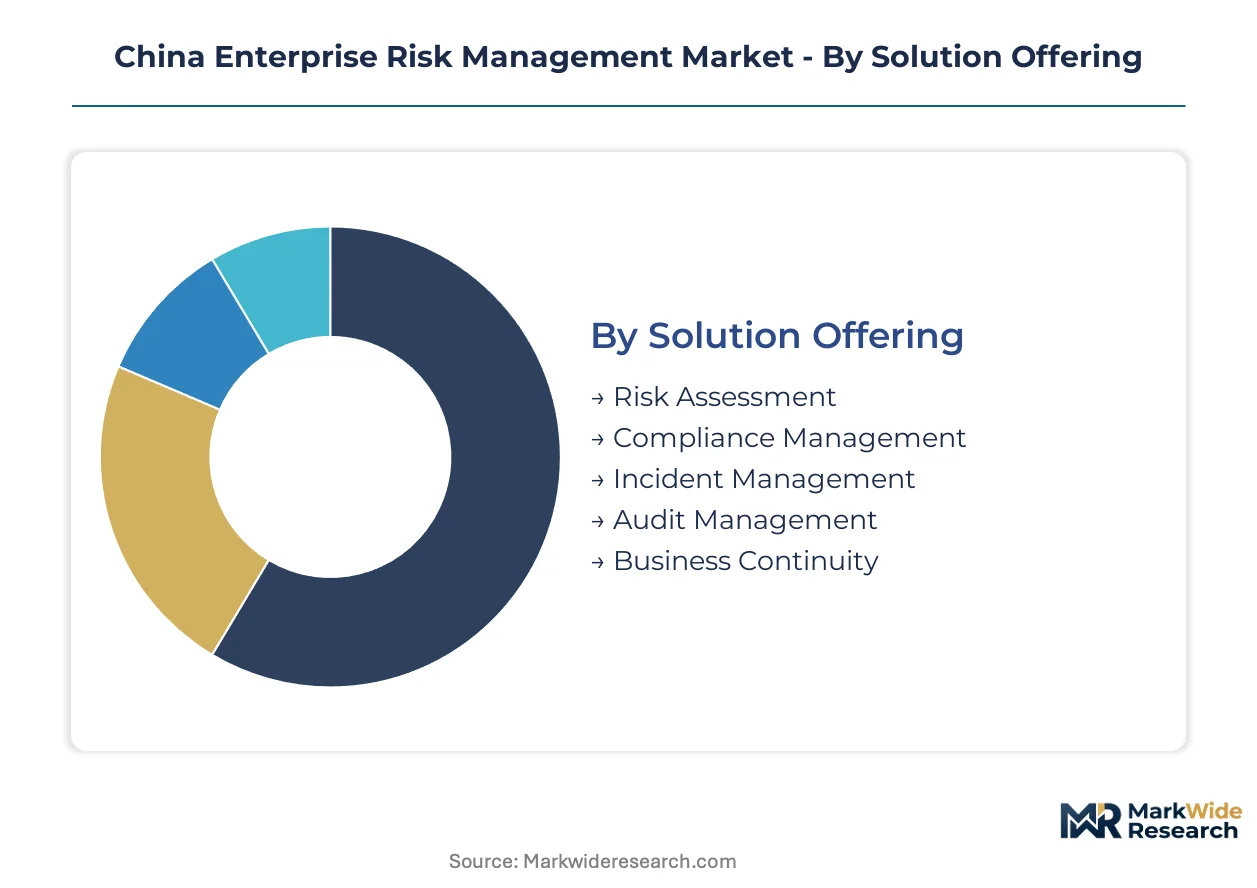
China's enterprise risk management market fragments across solution architectures, infrastructure models, risk categories, and sector-specific compliance regimes. Each segmentation axis carries distinct regulatory certification burdens that reshape vendor competitive positioning and procurement timelines.
Solution Offering:
Certification requirements under SAMR data governance rules and CSRC solvency mandates vary sharply across solution types, with compliance modules demanding the most extensive localization testing.
- Compliance Management:Platforms embed automated classification engines for personal and important data labeling per SAMR's cross-border transfer rules. State-owned banking groups in Beijing and Shanghai drive concentrated procurement as board-level risk committees mandate enterprise-wide standardization.
- Risk Assessment:Stochastic modeling engines process transaction-level signals within sub-second windows for dynamic capital adequacy monitoring. Mid-tier joint-stock banks bypass heavy infrastructure outlays through cloud deployment, accelerating adoption outside the policy bank tier.
- Incident Management:Real-time alerting systems integrate with PBOC fintech supervision dashboards for regulatory reporting automation.
- Audit Management:Localized audit trail architectures support SOX-like internal control frameworks adapted for Chinese capital markets.
- Business Continuity:Scenario modeling engines overlay traditional credit risk with climate stress-testing modules under MEE dual carbon frameworks.
Leading the category by volume: Compliance Management. Growing fastest: Risk Assessment.
Deployment Mode:
Infrastructure capital intensity and data localization stringency create sharp cost tier differentiation across deployment architectures.
- Cloud-Based:Mid-tier financial institutions in Shanghai and Shenzhen accelerate adoption to bypass on-premises hardware expenditure. Streaming analytics capabilities match real-time regulatory reporting demands without dedicated encryption appliance procurement.
- On-Premises:Sovereign wealth funds and policy banks absorb specialized encryption hardware costs to satisfy stringent data localization mandates. Total cost of ownership runs substantially above offshore alternatives due to appliance procurement and facility hardening.
- Hybrid:Split architectures segregate sensitive core banking data on-premises while pushing analytics workloads to cloud environments.
- Private Cloud:Dedicated infrastructure deployments serve insurance conglomerates with multinational operations facing steep cross-border compliance burdens.
Volume concentration: On-Premises. Steepest expansion trajectory: Cloud-Based.
Application Area:
Regulatory mandate intensity and quantitative modeling sophistication requirements segment application areas by implementation complexity and talent scarcity constraints.
- Financial Risk:Integrated platforms consolidate credit, market, and liquidity risk engines for consolidated capital adequacy reporting to PBOC and CBIRC. Graph neural networks for counterparty risk mapping piloted at twelve joint-stock banks since 2024 unify previously siloed data streams.
- Operational Risk:AI inference pipelines compress anomalous transaction detection latency from hours to milliseconds. Architectural choices between edge and cloud deployment force vendor technology roadmaps.
- Credit Risk:Traditional scoring models augmented with alternative data ingestion from fintech subsidiaries.
- Market Risk:Real-time position monitoring against stress scenarios mandated by CSRC trading book regulations.
- Strategic Risk:Scenario planning modules for geopolitical and supply chain disruption quantification.
- Reputation Risk:Social media sentiment analytics integrated with early warning systems for brand protection.
Dominant by revenue: Financial Risk. Gaining share fastest: Operational Risk.
End User Industry:
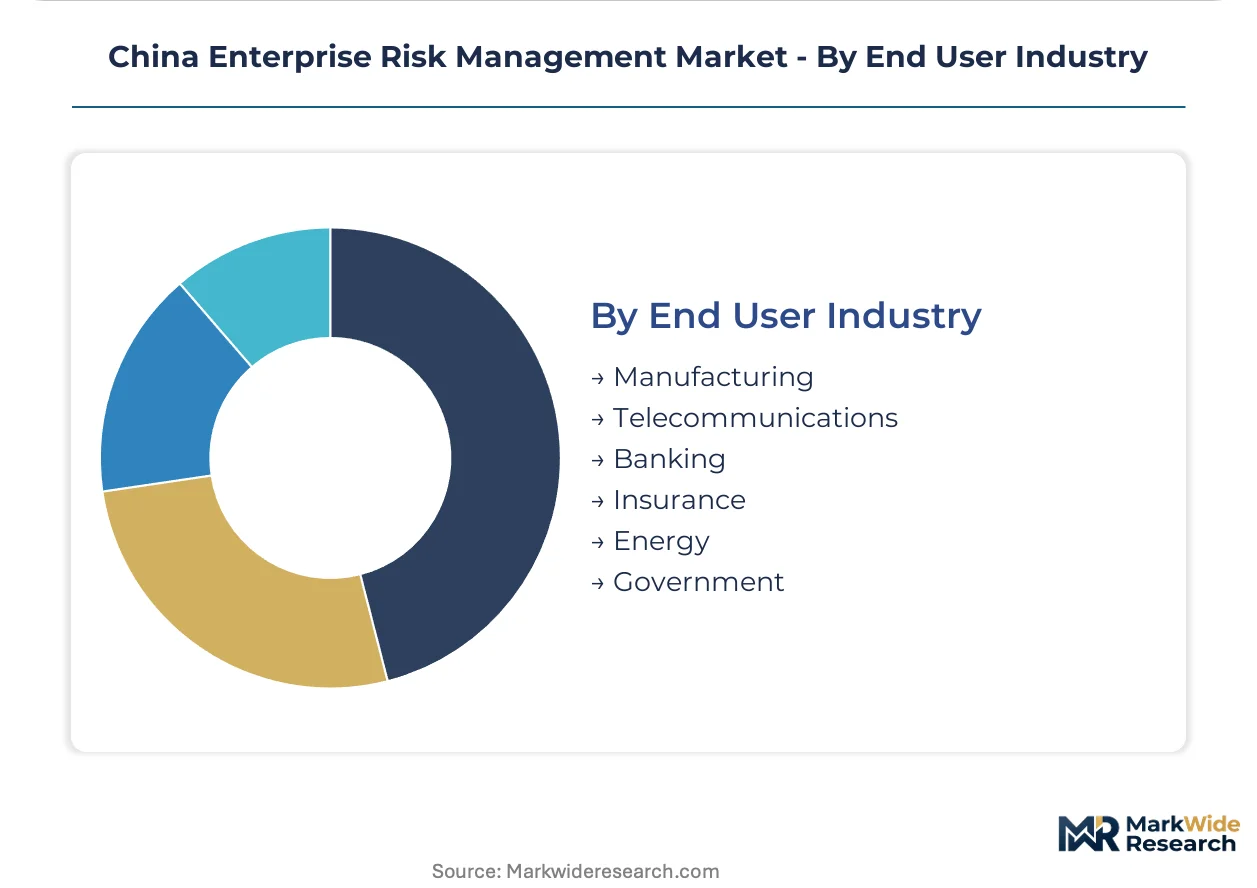
Sector-specific regulatory density and asset scale thresholds concentrate demand among financial services while creating whitespace in western provincial clusters.
- Banking:State-owned commercial banks anchor procurement volume through centralized holding company mandates. Board-level risk committees compress vendor shortlists from dozens to three or four approved suppliers, restructuring competitive dynamics.
- Insurance:Solvency regulatory regime evolution under CBIRC drives demand for climate risk quantification modules. Conglomerates with multinational operations prefer platforms with pre-configured regulatory reporting templates for cross-border data governance compliance.
- Energy:Dual carbon goals under MEE frameworks create demand for emissions-linked default probability models overlaying traditional credit engines.
- Government:Provincial enforcement fragmentation of CBIRC circulars complicates single-platform standardization for national deployments.
- Manufacturing:Supply chain risk visibility tools gain traction as export-oriented firms navigate geopolitical uncertainty.
- Telecommunications:Cybersecurity Law compliance mandates drive platform upgrades for cross-border transfer security assessments.
Revenue concentration: Banking. Expanding most quickly: Insurance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data sovereignty requirements and financial sector concentration anchor demand geography across China's provincial banking clusters. Eastern coastal infrastructure density contrasts with emerging western provincial scale thresholds.
Beijing-Tianjin-Hebei
Policy banks and sovereign wealth funds dominate procurement volume. SAMR data governance rules mandate localized audit trail architectures. The capital's risk technology procurement authority has shifted from IT departments to chief risk officer functions.
Yangtze River Delta
Shanghai joint-stock banks accelerate cloud-based deployment to bypass heavy infrastructure capital outlays. PBOC fintech supervision guidelines compress platform upgrade cycles. Twelve financial institutions pilot graph neural networks for counterparty risk mapping.
Pearl River Delta
Shenzhen's fintech subsidiaries deploy open-source analytics stacks as functional substitutes for vendor-proprietary engines. CSRC solvency mandates drive real-time position monitoring requirements. Guangdong insurance conglomerates seek pre-configured regulatory reporting templates.
Sichuan-Chongqing
Regional banking clusters currently rely on fragmented point solutions. CBIRC circular enforcement interpretation diverges from eastern coastal provinces. Chongqing's asset scale crosses thresholds for integrated platform consolidation.
Shandong Peninsula
Manufacturing supply chain risk visibility tools gain traction among export-oriented firms. MEE dual carbon frameworks create demand for climate stress-testing modules. Qingdao and Jinan financial institutions evaluate emissions-linked default probability models.
China Enterprise Risk Management Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue embedded risk-as-a-service distribution through cloud marketplaces. Procurement concentration among state-owned banking groups compresses vendor shortlists from dozens to three or four approved suppliers. Three archetypes dominate: governance technology heritage players, specialized consulting delivery firms, and insurance-rooted risk analytics providers. Competitive moves center on API-first platform architectures and carbon risk quantification module development.
Within the governance technology tier, Diligent occupies a position serving board-level risk oversight contracts at major financial institutions. Protiviti exemplifies the consulting-anchored archetype through specialized delivery tied to SOX-like internal control frameworks. Allianz represents the insurance-sector vector, extending risk analytics capabilities to clients navigating evolving solvency regulatory regimes.
| Leading Market Players |
|---|
| Asanify |
| Hays China |
| Diligent |
| ManpowerGroup China |
| Korn Ferry China |
| Allianz |
| Randstad China |
| FESCO Adecco |
| Protiviti |
| Others |
Cost & Logistics Intelligence
Specialized encryption appliance procurement costs cascade through deployment tiers, compressing margins at policy banks while cloud-based alternatives absorb hardware expenditure through subscription models. SAMR certification requirements and PBOC fintech supervision mandates further stratify pricing across compliance management modules versus risk assessment engines.
Pricing Analysis
Warranty and service bundling separates premium-tier vendors offering embedded regulatory reporting templates from unbundled alternatives requiring separate implementation contracts. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and customization depth. Pricing pressure stems from open-source analytics stacks in fintech subsidiaries capping vendor pricing power. Mid-tier joint-stock banks exhibit highest price sensitivity; sovereign wealth funds demonstrate lowest due to data localization mandates.
Supply Chain Analysis
Certification gating under SAMR data governance rules and CSRC solvency mandates restricts vendor qualification to firms with localized audit trail architectures. Supply concentrates in China for encryption hardware, the United States for stochastic modeling engines, and Singapore for cloud infrastructure. Component dependencies include specialized encryption appliances, streaming analytics processors, and regulatory reporting template libraries. Single-source vulnerability runs through domestic encryption hardware suppliers. Distribution runs through direct enterprise sales to state-owned banking groups and API-first cloud marketplace channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized quantitative risk modeling talent scarcity props pricing for implementation services, creating supply-constrained conditions across platform deployment cycles.
For Market Incumbents: Lock in board-level risk committee relationships at Beijing and Shanghai headquarters before centralized procurement compresses vendor shortlists further. Defend against open-source analytics substitution by embedding proprietary graph neural network capabilities for counterparty risk mapping. Prioritize certification investment under evolving SAMR data classification rules to maintain approved supplier status. For New Entrants and Emerging Players: Cloud marketplace operators present channel access to securities firms and asset managers previously served only through direct enterprise sales. Target western provincial banking clusters in Chongqing and Chengdu relying on fragmented point solutions. Pursue API-first risk-as-a-service distribution to bypass incumbent sales organization scale advantages. For Investors and Strategic Acquirers: Distressed-cycle entries favor compliance management specialists with pre-configured regulatory reporting templates in eastern coastal provinces. Long-term viability hinges on carbon risk quantification module development under MEE dual carbon frameworks. Monitor CBIRC circular enforcement harmonization across provincial boundaries as inflection indicator for platform standardization demand.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Risk Module Development | Climate stress-testing capabilities align with MEE dual carbon mandates at energy-sector clients. |
| API-First Platform Architecture | Embedded risk-as-a-service distribution opens channel access to securities firms through cloud marketplaces. |
| Graph Neural Network Integration | Counterparty risk mapping pilots at twelve joint-stock banks since 2024 consolidate siloed data streams. |
| SAMR Certification Investment | Automated data classification engines satisfy cross-border transfer rules for insurance conglomerates. |
| Western Province Expansion | Chongqing and Chengdu banking clusters cross asset thresholds for integrated platform consolidation. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Chief risk officers, IT procurement leads at state-owned banks, platform engineers, and SAMR compliance specialists formed the primary interview base. PBOC fintech supervision guidelines, CBIRC circulars, CSRC solvency mandates, and Cybersecurity Administration assessments provided regulatory validation. Bottom-up deployment mode segmentation triangulated against top-down financial services demand estimates.
Data-stream reconciliation across solution offering, deployment architecture, and end-user industry dimensions generated volume and value outputs. Modeled segments encompassed compliance management, risk assessment, and incident management solutions alongside cloud-based and on-premises deployment patterns. CAGRs derived from regulatory mandate intensity curves and joint-stock bank technology expenditure trajectories. Capital adequacy reporting requirements and real-time data ingestion capability gaps served as industry-specific forecast inputs.
Caveats apply where PBOC fintech supervision guideline revisions or SAMR data classification rule updates could materially shift the outlook. Forecasts reflect assumptions regarding regulatory harmonization pace and provincial enforcement consistency. A model refresh is warranted upon material change in CBIRC circular interpretation alignment across eastern coastal versus interior provinces.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Risk Management and Compliance
Operations Advisory Service Market
Risk Management and Compliance
Corporate Investigation Services Market
Risk Management and Compliance
Southeast Asia Credit and Risk Management Market
Risk Management and Compliance
Risk-Based Monitoring Software Market
Risk Management and Compliance
Anti-Money Laundering (AML) Market
Risk Management and Compliance
BFSI Crisis Management Market
Risk Management and Compliance
Disclosure Management Market
Risk Management and Compliance
Artificial Intelligence and Regtech Market
Risk Management and Compliance
Global Financial Crime and Fraud Management Solutions Market
Risk Management and Compliance
UK Anti Money Laundering Solutions Market
Risk Management and Compliance
Europe Sustainable Finance Market
Risk Management and Compliance
Asia-Pacific Operational Risk Management Consulting Services in Manufacturing Market
Risk Management and Compliance
Legal Advisory Service Market
Risk Management and Compliance
Europe Strategic Consulting Services Market
Risk Management and Compliance
Global Energy Trading and Risk Management (ETRM) Market
Risk Management and Compliance
Global Backstop Netting Systems Market