
 Germany E-Brokerage Market | 2026-2036
Germany E-Brokerage Market Size, Share, and Industry Trends Forecast 2026-2036
Germany E-Brokerage Market Insights
API-first architecture is reconfiguring how German e-brokerage platforms deliver real-time execution and portfolio analytics. Trade Republic GmbH leverages its proprietary clearing infrastructure to offer commission-free equity trades. flatexDEGIRO AG anchors its competitive position through scale advantages across multiple European clearing venues. Scalable Capital Broker GmbH differentiates via its hybrid robo-advisory engine that blends automated allocation with selective direct indexing.
Germany e-brokerage denotes digitally native securities execution and custody services operating through internet-connected interfaces, typically requiring sub-second order routing to regulated trading venues and T+2 settlement compliance via central counterparty clearing. The primary commercial purpose is disintermediating traditional branch-based wealth management through self-service portfolio construction and reduced fee structures. Discount brokers and online trading platforms command the dominant transaction volume pools as price-sensitive retail migration accelerates from incumbent banks. Robo-advisors represent the fastest-expanding segment as algorithmic portfolio construction lowers minimum investment thresholds for mass-affluent clients. Mobile trading apps are displacing web-based platforms as the primary acquisition channel among investors under forty.
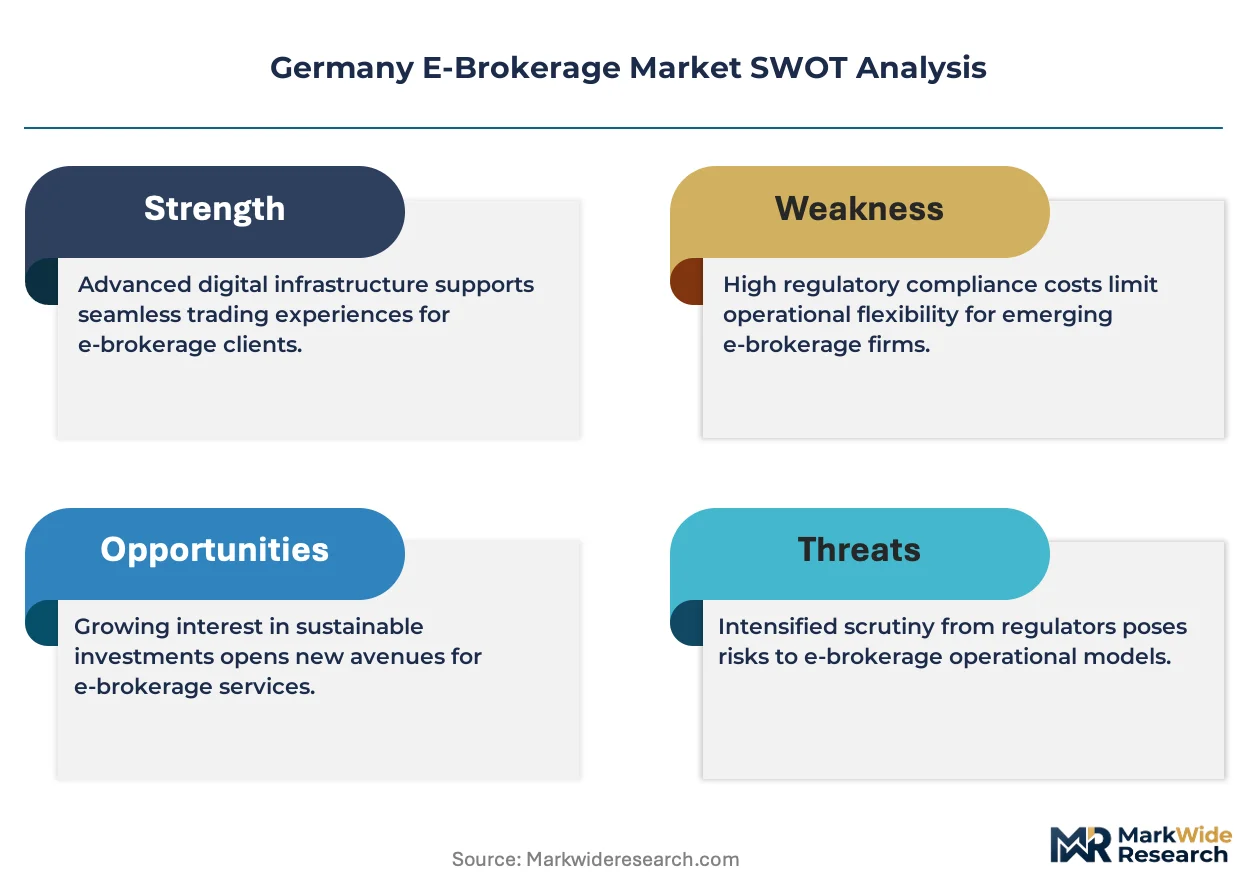
BaFin supervises platform licensing under the German Banking Act and enforces MiFID II best-execution reporting standards, while the ECB's TARGET2-Securities framework shapes post-trade settlement infrastructure requirements. These regulatory layers elevate capital and compliance barriers for new entrants while mandating transparent fee disclosure that compresses revenue per trade. Stakeholders must monitor the interplay between BaFin's forthcoming digital asset custody classifications and the EU's DLT pilot regime for tokenized securities settlement.
Market Dynamics
BaFin's digital securities custody framework is compressing platform economics while MiFID II best-execution mandates force infrastructure upgrades that smaller operators cannot absorb.
Growth Catalysts
- MiFID II transparency mandates:Fee disclosure requirements accelerate retail migration from incumbent banks toward self-directed platforms.
- Mobile-first onboarding:Sub-ten-minute KYC completion via video identification expands investor acquisition in Bavaria and Baden-Württemberg.
- Fractional share trading:Micro-investment thresholds below one euro unlock mass-affluent participation previously excluded from equity markets.
Market Restraints
- Clearing infrastructure concentration:Dependence on TARGET2-Securities and EuroCCP creates single-point-of-failure exposure for settlement continuity.
- BaFin licensing capital requirements:Minimum regulatory capital thresholds for Kreditinstitut licenses exceed twenty-five million euros, blocking de novo entry.
- Negative interest rate legacy:Sustained sub-zero deposit rates eroded net interest margin buffers that subsidized commission-free trading.
Strategic Opportunities
- Tokenized securities under DLT pilot regime:EU distributed ledger experimentation permits T+0 settlement pilots that bypass traditional clearing layers.
- ESG direct indexing:Automated portfolio construction with security-level sustainability screens addresses regulatory disclosure requirements under CSRD.
- White-label B2B infrastructure:Licensed platforms extend proprietary clearing and custody stacks to regional banks seeking digital transformation without capital deployment.
Industry Challenges
- MiFID II best-execution audit trails:Sub-second order routing documentation across fragmented liquidity venues demands specialized compliance engineering talent scarce in Frankfurt and Berlin.
- Core banking system integration:Incumbent custodians' legacy COBOL stacks resist API connectivity, prolonging onboarding timelines for multi-bank aggregation features.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany E-Brokerage Market |
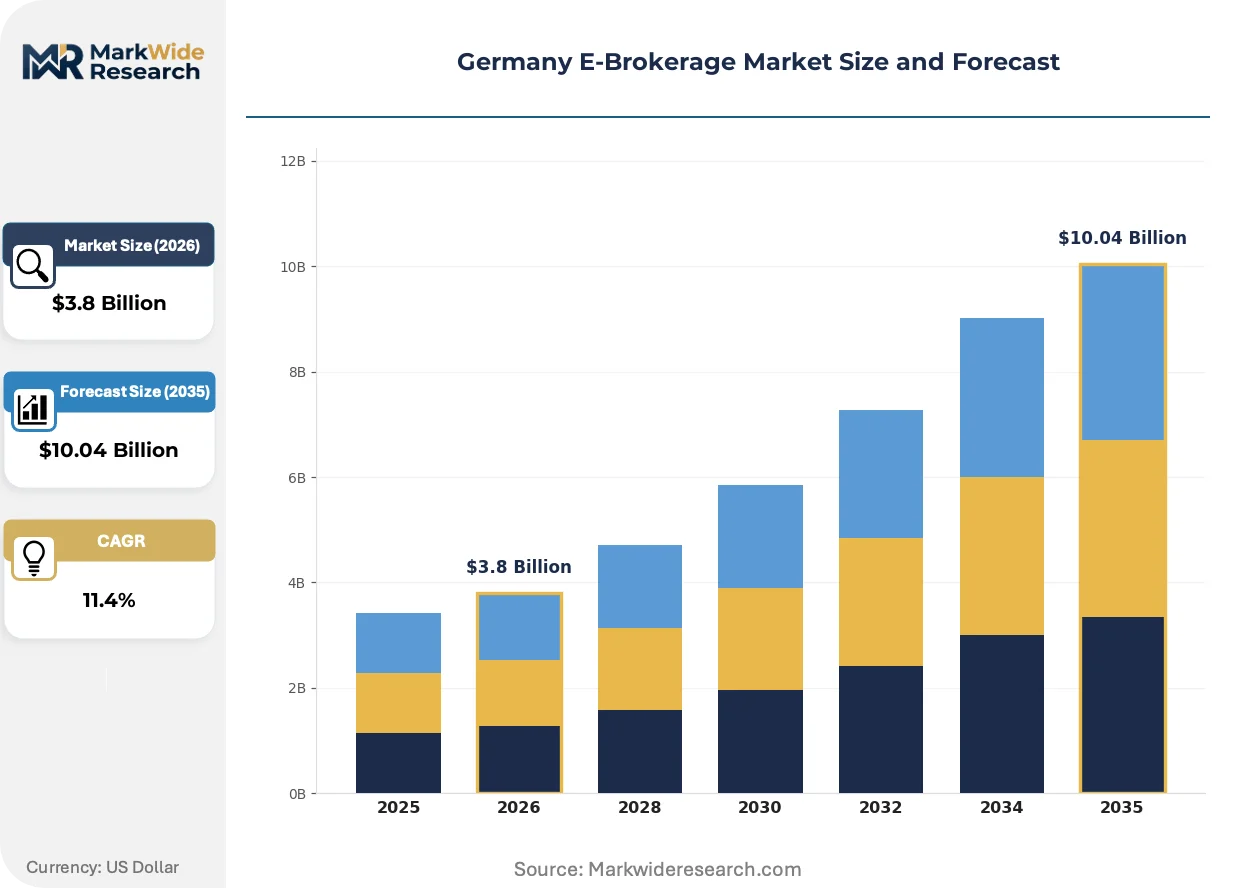
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Discount Brokers, Full-Service Brokers, Robo-Advisors, Online Trading Platforms Customer Type: Retail Investors, Institutional Investors, High-Net-Worth Individuals, Day Traders Technology: Mobile Trading Apps, Web-Based Platforms, Algorithmic Trading Software, Blockchain Integration Offering: Equities, ETFs, Options, Forex |
| Companies Covered | Trade Republic GmbH, flatexDEGIRO AG, Scalable Capital Broker GmbH, finanzen.net ZERO, Smartbroker Plus, Comdirect Bank AG, ING Direct Depot, Consorsbank, Interactive Brokers, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany E-Brokerage Market Trends and Innovations
Execution infrastructure is fragmenting across proprietary matching engines while regulatory technology automates compliance workflows previously staffed by human analysts.
Algorithmic order routing is migrating from centralized exchange connectivity toward smart order routers that scan dark pools and systematic internalizers simultaneously. Tier-one platforms deploy machine learning models that predict venue liquidity twenty milliseconds ahead of order submission. This compression of execution latency is migrating from institutional-only access toward retail-facing applications, narrowing the historical gap between professional and self-directed trader performance.
BaFin's forthcoming digital asset custody classification under the German Banking Act creates licensing clarity for tokenized security custody. The regulation mandates segregation of crypto-assets from traditional securities books, forcing infrastructure bifurcation. Platforms serving both asset classes must duplicate custody architectures, elevating operational complexity most acutely for mid-scale operators in Hamburg and Stuttgart.
Self-directed investors under forty demonstrate preference for consolidated financial apps over standalone brokerage interfaces. Banking super-apps from N26 and similar fintechs embed securities execution alongside payments and savings, capturing primary customer relationships. This unbundling of brokerage from banking is most visible in Berlin and Munich, where mobile-native users reject separate login credentials for investment activity.
Germany E-Brokerage Market Segmentation
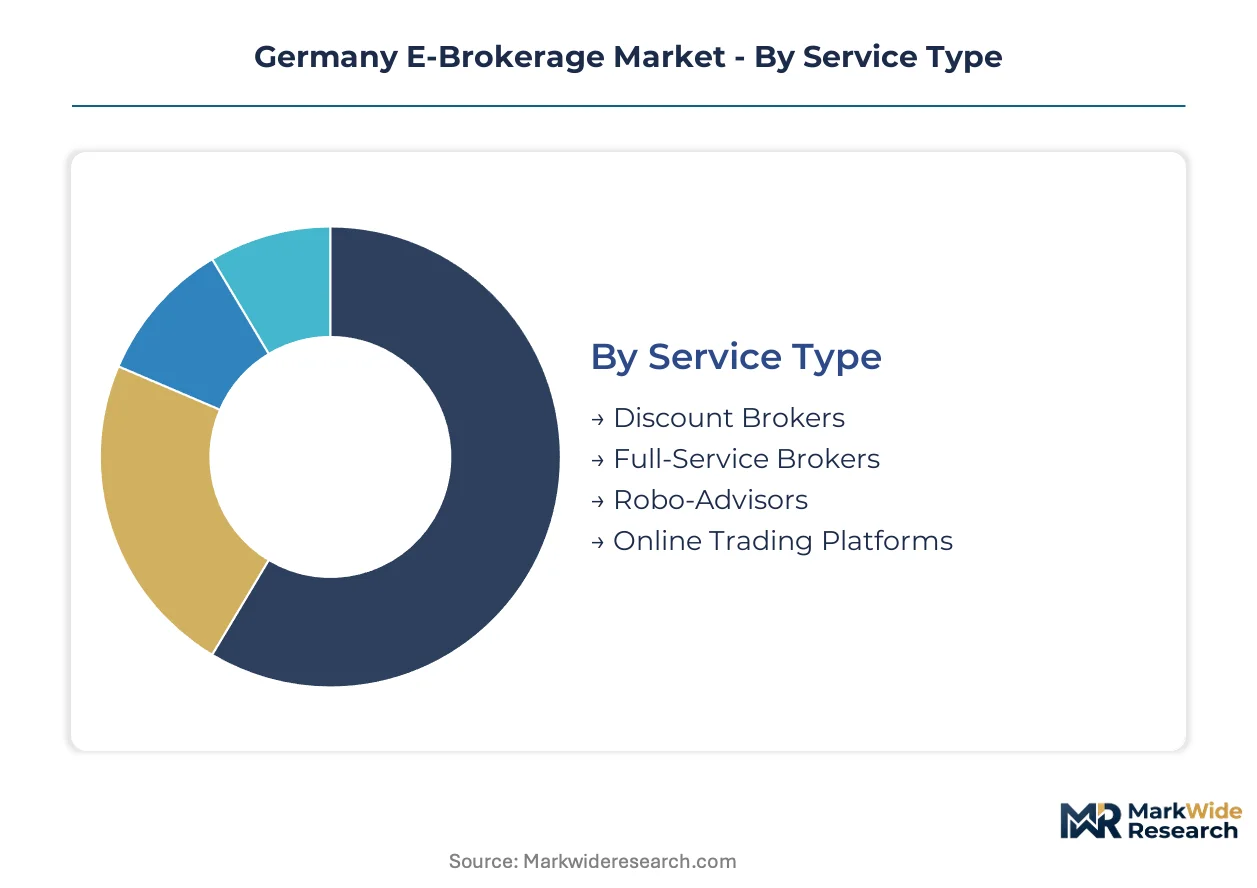
E-brokerage platforms in Germany serve divergent investor profiles with distinct service architectures, fee sensitivities, and regulatory compliance burdens. Segment boundaries increasingly blur as hybrid models emerge, yet operational DNA and capital requirements still cluster around four fundamental service types, four customer archetypes, four technology delivery modes, and four core asset classes.
Service Type:
Cost tier determines platform infrastructure investment and regulatory capital intensity.
- Discount Brokers:Execution-only services strip advisory layers to minimize per-trade fees. Demand concentrates among self-directed retail investors in Frankfurt and Munich where BaFin's fee disclosure mandates accelerate migration from incumbent bank channels.
- Robo-Advisors:Algorithmic portfolio construction automates rebalancing and tax-loss harvesting. Adoption climbs fastest in Berlin and Hamburg among mass-affluent clients seeking ESG-aligned direct indexing without human advisor costs.
- Full-Service Brokers:Hybrid digital-human advisory models retain higher-touch wealth planning. Client concentration persists in Baden-Württemberg among business owners requiring succession and liquidity event structuring.
- Online Trading Platforms:Multi-asset execution interfaces target active traders with derivatives access. Bavarian day traders drive volume through proprietary APIs connecting to systematic internalizers.
Established volume favors discount brokers; emerging adoption favors robo-advisors.
Customer Type:
Trading frequency and asset scale dictate platform monetization mechanics and KYC depth.
- Retail Investors:Mass-market participants with portfolios below institutional thresholds. Concentration surges in metropolitan hubs where mobile-first onboarding via video identification compresses acquisition costs.
- Day Traders:High-velocity participants executing multiple intraday positions. Demand clusters around algorithmic execution tools with sub-millisecond latency to Frankfurt-based matching engines.
- High-Net-Worth Individuals:Affluent clients requiring bespoke custody and reporting. Preference shifts toward white-label B2B infrastructure from licensed platforms rather than building proprietary stacks.
- Institutional Investors:Asset managers and corporates with block-order requirements. MiFID II best-execution audit trails mandate specialized compliance engineering talent scarce in Berlin.
Transaction economics favor day traders; lifetime value concentration favors high-net-worth individuals.
Technology:
Delivery modality shapes customer acquisition cost and retention durability across age cohorts.
- Mobile Trading Apps:Native iOS and Android interfaces dominate investor acquisition under forty. Berlin and Munich users reject separate login credentials, driving banking super-app embedding of securities execution.
- Web-Based Platforms:Browser-accessible interfaces retain preference among investors over fifty. Legacy COBOL integration challenges prolong onboarding for multi-bank aggregation features.
- Algorithmic Trading Software:API connectivity and smart order routers scan fragmented liquidity venues. Machine learning models predicting venue liquidity twenty milliseconds ahead narrow professional-retail performance gaps.
- Blockchain Integration:DLT pilot regime infrastructure enables T+0 settlement pilots bypassing traditional clearing layers. BaFin's digital asset custody classification forces custody architecture bifurcation for platforms serving both traditional and tokenized securities.
Acquisition momentum favors mobile trading apps; infrastructure differentiation favors algorithmic trading software.
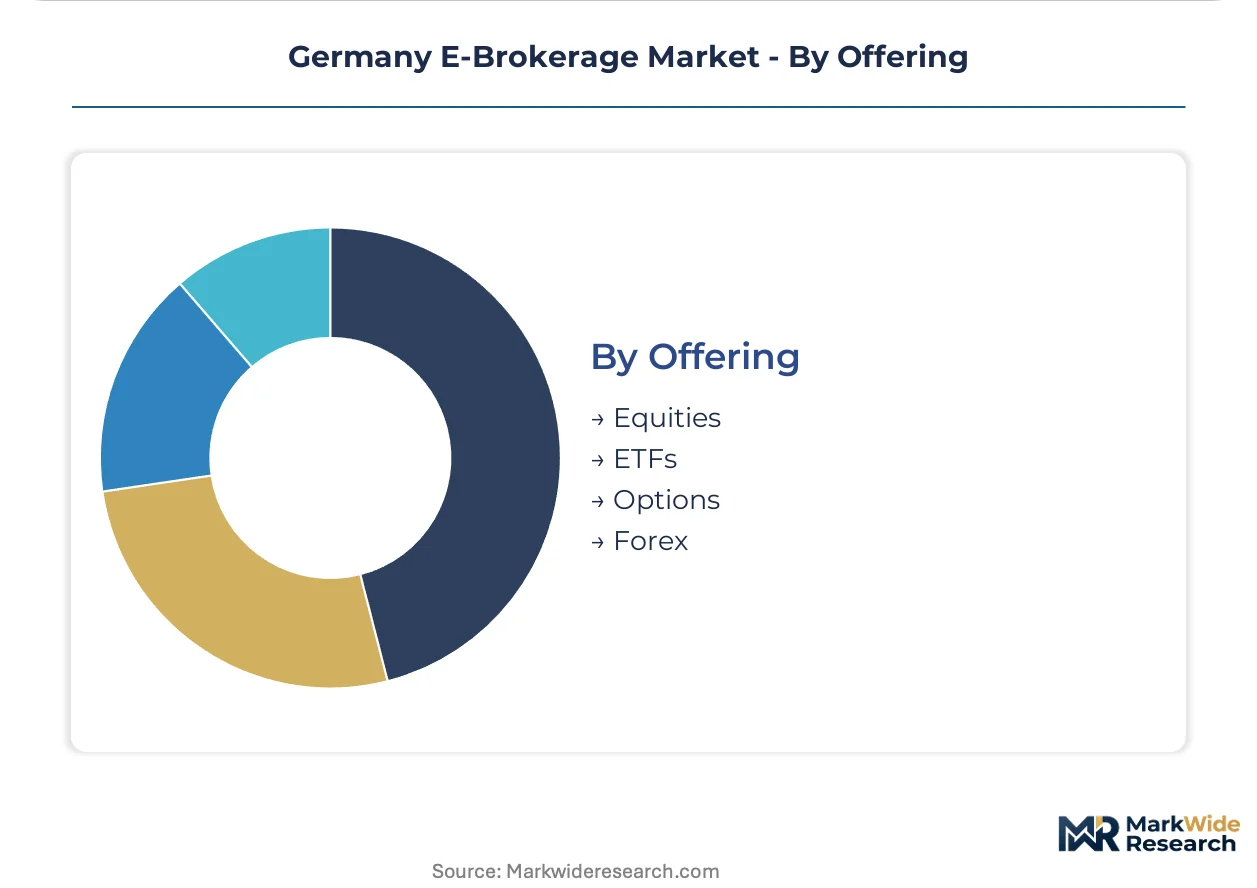
Offering:
Asset class mix determines clearing venue relationships and regulatory reporting obligations.
- ETFs:Exchange-traded funds dominate passive allocation flows. Fractional share trading below one euro thresholds unlocks mass-affluent participation previously excluded from equity markets.
- Equities:Single-stock execution remains volume anchor for commission-free platforms. Proprietary clearing infrastructure enables zero-commission models subsidized by securities lending and payment for order flow.
- Options:Derivatives contracts require enhanced risk disclosure and suitability frameworks. Regulatory complexity elevates compliance barriers for smaller operators in Hamburg and Stuttgart.
- Forex:Currency pair trading demands 24-hour liquidity access and multi-currency custody. TARGET2-Securities settlement concentration creates single-point-of-failure exposure for cross-border euro clearing.
Volume concentration favors equities; margin expansion favors options.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German e-brokerage platforms export execution technology and white-label infrastructure to neighboring European markets, with Austria, Switzerland, and the Netherlands serving as primary demand corridors for cross-border digital custody services.
Bavaria
Mobile-first investor acquisition accelerates through sub-ten-minute video identification workflows. BaFin's digital securities custody framework elevates compliance engineering requirements for Munich-based platform operators. The Munich-Stockstadt corridor concentrates proprietary clearing infrastructure development for commission-free equity execution.
Baden-Württemberg
Mass-affluent demand for ESG-aligned direct indexing drives robo-advisory adoption among Stuttgart's automotive industry professionals. MiFID II best-execution audit trail mandates force infrastructure upgrades for regional wealth management digitization. The Stuttgart-Tübingen cluster hosts hybrid digital-human advisory platforms targeting business owner succession planning.
North Rhine-Westphalia
Institutional block-order execution demand from Düsseldorf's asset management sector elevates compliance talent competition. The ECB's TARGET2-Securities settlement framework shapes post-trade infrastructure requirements for Cologne-based clearing operations. The Rhine-Ruhr metropolitan region concentrates API connectivity development for multi-bank aggregation features.
Hesse
Frankfurt's status as TARGET2-Securities settlement hub attracts smart order router deployment for sub-millisecond latency execution. BaFin's Kreditinstitut licensing capital thresholds exceeding twenty-five million euros block de novo entry for Frankfurt fintech ventures. The Frankfurt-Mainz corridor anchors machine learning model development for venue liquidity prediction.
Berlin-Brandenburg
Banking super-app embedding of securities execution captures primary customer relationships among mobile-native users under forty. The EU's DLT pilot regime for tokenized securities settlement permits T+0 settlement pilots bypassing traditional clearing layers. The Berlin startup ecosystem concentrates fractional share trading platform development for micro-investment thresholds below one euro.
Germany E-Brokerage Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. Tier-one operators leverage proprietary clearing infrastructure and scale advantages across multiple European venues. Tier-two platforms differentiate through hybrid robo-advisory engines and automated portfolio construction. Tier-three white-label providers extend custody stacks to regional banks seeking digital transformation without capital deployment. Consolidation pressure intensifies as MiFID II compliance costs and BaFin licensing requirements compress economics for sub-scale operators.
Within the mobile-native tier, Trade Republic GmbH exemplifies commission-free execution models subsidized through securities lending and payment for order flow. flatexDEGIRO AG occupies a position representing scale-driven consolidation across European clearing venues. Scalable Capital Broker GmbH anchors the hybrid advisory segment, blending automated allocation with selective direct indexing capabilities. These three archetypes illustrate the strategic divergence between infrastructure-heavy clearing operators, volume-scaled execution platforms, and algorithmic wealth management specialists competing for German retail investor relationships.
| Leading Market Players |
|---|
| Trade Republic GmbH |
| flatexDEGIRO AG |
| Scalable Capital Broker GmbH |
| finanzen.net ZERO |
| Smartbroker Plus |
| Comdirect Bank AG |
| ING Direct Depot |
| Consorsbank |
| Interactive Brokers |
| Others |
Pricing and Supply Chain Analysis
Proprietary clearing infrastructure concentration among Frankfurt and Munich operators anchors margin capture downstream, with commission-free retail execution subsidized through securities lending and payment-for-order-flow arrangements that shift revenue extraction from explicit fees to implicit spread capture.
Pricing Analysis
Current-generation mobile-native platforms deploy zero-commission models against prior-generation web-based brokers charging per-trade fees, while next-generation hybrid robo-advisory engines test subscription-based wealth management pricing. Three-tier pricing structure across premium direct-indexing, standard automated allocation, and economy execution-only levels stratifies by advisory depth and customization intensity. Pricing pressure stems from MiFID II fee disclosure mandates accelerating retail migration toward transparent cost structures. Day traders exhibit highest price sensitivity to per-transaction costs, while high-net-worth individuals prioritize custody reliability over fee minimization.
Supply Chain Analysis
Upstream feedstock for execution infrastructure draws from Netherlands-based EuroCCP clearing services, German TARGET2-Securities settlement rails, and proprietary matching engines hosted in Frankfurt data centers. Critical dependencies include sub-millisecond connectivity fiber, cloud compute capacity for machine learning order routing, and API middleware for banking system integration. Single-point-of-failure exposure concentrates in TARGET2-Securities settlement continuity. Distribution runs through mobile app stores, embedded banking super-apps, and white-label B2B infrastructure licensing to regional banks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German e-brokerage operates as a defensive-moat market where BaFin's twenty-five-million-euro Kreditinstitut licensing threshold creates regulatory entrenchment that protects scaled incumbents from de novo competition.
For Market Incumbents: Pre-empt regulatory technology automation by deploying machine learning compliance engines that reduce MiFID II best-execution audit trail costs below smaller rivals' break-even thresholds. Consolidate proprietary clearing infrastructure through targeted acquisition of regional white-label custody providers, neutralizing emerging fintech threats before they achieve scale economies.
For New Entrants and Emerging Players: Geographic underpenetration in Hamburg and Stuttgart's mid-scale operator segment offers white-space entry for algorithmic execution specialists with differentiated smart order router technology. Target mass-affluent robo-advisory demand in Baden-Württemberg's automotive professional cohort through ESG direct-indexing positioning that incumbent banks cannot replicate without legacy system overhaul.
For Investors and Strategic Acquirers: Capital is best deployed toward hybrid robo-advisory platforms with proven automated allocation engines and selective direct-indexing capabilities that command premium valuation multiples through recurring revenue visibility. Monitor BaFin's forthcoming digital asset custody classification as inflection signal for tokenized securities infrastructure plays.
| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Clearing Infrastructure Development | EuroCCP and TARGET2-Securities bypass capabilities enable commission-free retail execution models. |
| Machine Learning Compliance Automation | MiFID II best-execution audit trail cost compression below sub-scale rival break-even thresholds. |
| ESG Direct-Indexing Engine Deployment | CSRD disclosure requirements drive mass-affluent demand for security-level sustainability screening. |
| White-Label B2B Infrastructure Licensing | Regional banks seek digital transformation without twenty-five-million-euro capital deployment. |
| DLT Pilot Regime Tokenized Settlement | T+0 settlement pilots bypass traditional clearing layers for next-generation custody architecture. |
Research Methodology
Cross-validation between executive interviews at licensed Kreditinstitut operators and secondary analysis of BaFin regulatory filings anchors the qualitative findings. Primary fieldwork encompassed platform engineering leads, compliance officers, wealth management digitization heads at regional banks, and securities lending desk managers. Secondary sources included MiFID II transparency database extracts, TARGET2-Securities operational statistics, ECB payment system reports, and EU DLT pilot regime documentation. Bottom-up transaction volume modeling triangulated against top-down addressable market sizing.
Calibration against historical platform user acquisition curves and clearing infrastructure investment cycles shaped projection reliability. Segmentation dimensions spanned service type, customer archetype, technology delivery mode, and core asset class, with additional modeling of regional adoption intensity across German federal states. CAGRs derived from trend extrapolation of mobile-first onboarding velocity and robo-advisory asset accumulation rates, cross-checked against securities lending revenue sustainability and payment-for-order-flow regulatory exposure.
The forecast holds incumbent behavior within observed patterns; aggressive moves by unlicensed fintechs or accelerated MiFID III disclosure requirements would shift outcomes substantially. Cross-checking against ECB TARGET2-Securities volume benchmarks and BaFin enforcement action frequencies is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Mobile Notary Public Market
Financial Services
Canada Credit Cards Market
Financial Services
United States Payroll Services Market
Financial Services
Online Investment Platform Market
Financial Services
Legal Management Consulting Service Market
Financial Services
Global Business Management Consulting Service Market
Financial Services
Financial Services Application Market
Financial Services
Currency Management Market
Financial Services
Global Financial Consulting Software Market
Financial Services
Foreign Exchange Services Market
Financial Services
Power Bank Sharing Services Market
Financial Services
Peer-To-Peer (P2P) Market
Financial Services
Reverse Factoring Market
Financial Services
Solar Powered ATM Market
Financial Services
Cash Flow Market
Financial Services
Reconciliation Software Market