
 Europe B2B Legal Services Market | 2026-2036
Europe B2B Legal Services Market Size, Share, and Industry Trends Forecast 2026-2036
Europe B2B Legal Services Market Insights
Generative AI contract analysis is reconfiguring how European law firms structure their associate-to-partner workflows and client delivery timelines. Clifford Chance LLP leverages proprietary machine-learning tools to accelerate due diligence execution across cross-border M&A mandates. Freshfields Bruckhaus Deringer LLP anchors its competitive stance through deep sector specialization in financial regulatory matters. Linklaters LLP dominates London-Frankfurt corridor work by sustaining integrated teams across both jurisdictions.
Europe B2B legal services encompass advisory, transactional, and dispute-resolution counsel delivered to corporate and institutional clients rather than individuals, typically governed by national bar associations and EU-wide professional conduct directives that mandate independence, confidentiality, and competence standards. Corporate law and intellectual property segments carry the deepest margin pools due to recurring advisory relationships and premium rate structures on patent prosecution and portfolio management. The subscription delivery model is gaining traction among SMEs seeking predictable legal spend, while project-based engagements retain dominance for large enterprises managing episodic litigation or restructuring events.
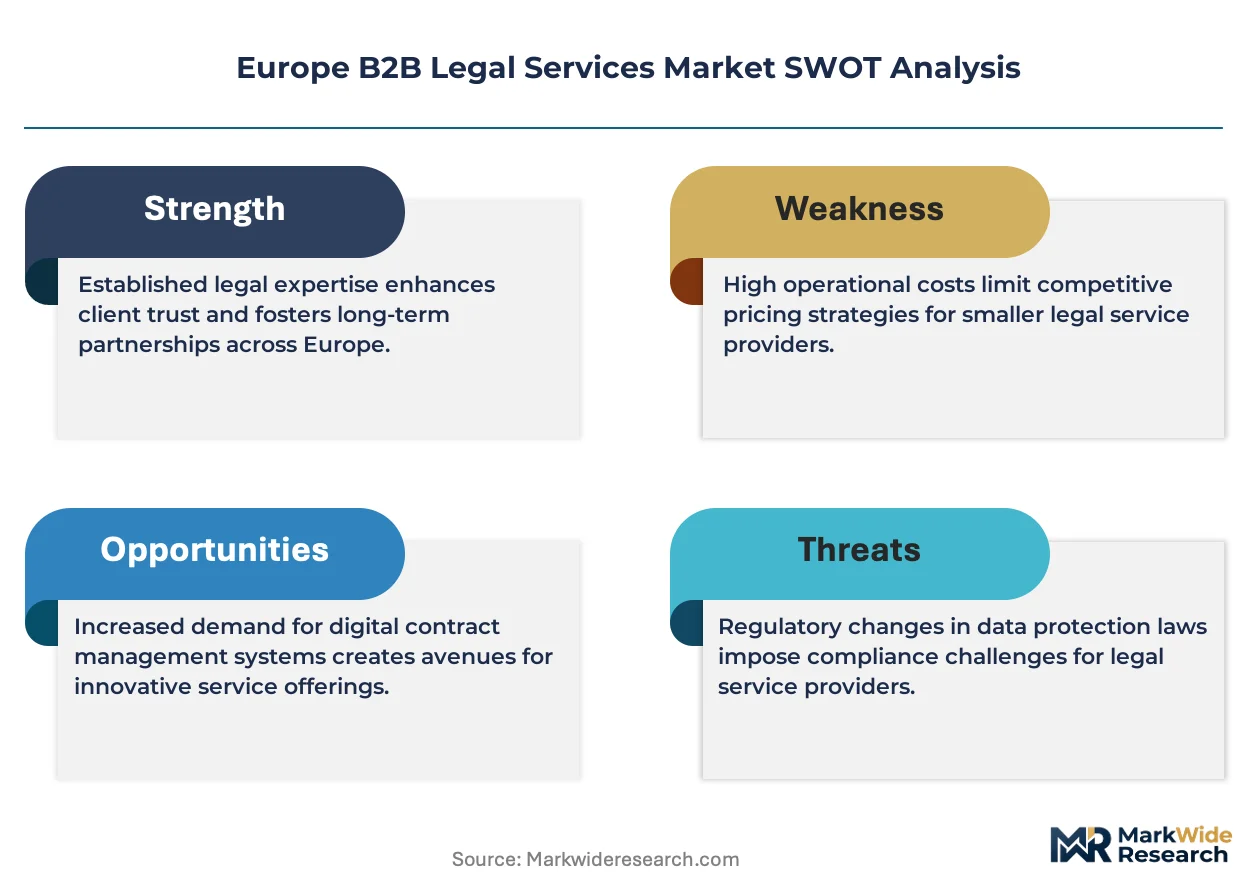
The EU AI Act and GDPR compliance obligations are reshaping demand for specialized technology and data privacy counsel across all client tiers, with EBA guidelines on digital operational resilience adding further complexity for financial services verticals. National bar regulators in France, Germany, and the Netherlands impose strict multidisciplinary practice restrictions that limit how accounting and consulting firms can bundle legal advisory with adjacent services. Stakeholders must monitor how the EU Green Deal's expanding disclosure mandates create new advisory categories around climate litigation risk and sustainability-linked contract structuring.
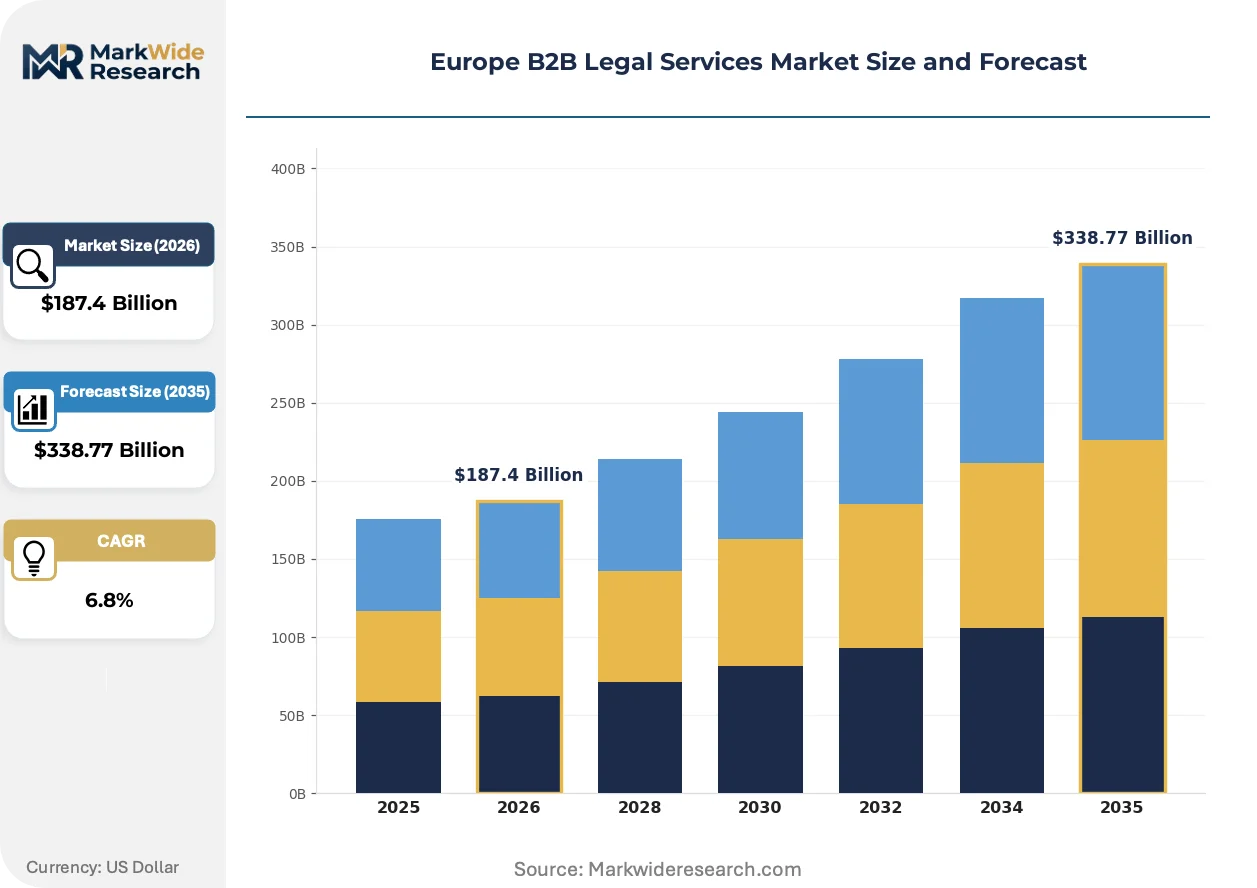
Market Dynamics
The EU AI Act's risk-tier classification system is compressing procurement timelines for specialized regulatory counsel as enterprises race to achieve compliance deadlines ahead of enforcement phases.
Growth Catalysts
- EU AI Act enforcement:The regulation's high-risk system mandates trigger enterprise demand for algorithmic impact assessments and conformity documentation across financial services and healthcare verticals.
- Germany's corporate law concentration:Frankfurt and Munich host the continent's densest clusters of cross-border M&A activity, sustaining premium advisory rates for transactional work.
- Subscription pricing adoption:SME buyers increasingly favor predictable monthly retainers over hourly billing, expanding addressable client bases beyond traditional enterprise accounts.
Market Restraints
- Multidisciplinary practice restrictions:French, German, and Dutch bar associations prohibit accounting firms from bundling legal advisory with audit or tax services, capping market entry by Big Four competitors.
- Associate talent scarcity:Technology and data privacy specializations command salary premiums that compress partner margin pools at mid-tier firms.
- GDPR litigation volume saturation:Standardized penalty frameworks have reduced variance in enforcement outcomes, dampening demand for novel defense strategies.
Strategic Opportunities
- CSRD disclosure mandates:The Corporate Sustainability Reporting Directive creates advisory white space around climate litigation risk assessment and supply chain due diligence documentation.
- Netherlands arbitration hub expansion:The Hague's institutional infrastructure attracts Asia-Pacific commercial disputes, diversifying revenue beyond European corporate mandates.
- Generative AI contract generation:Convergence of large language models with clause libraries enables productized legal templates for standardized commercial agreements.
Industry Challenges
- EBA digital operational resilience compliance:Financial services clients demand integrated cyber-incident response planning that stretches traditional advisory capabilities into IT security domains.
- Cross-border privilege fragmentation:Inconsistent confidentiality protections between English common law and continental civil law jurisdictions complicate multi-jurisdictional investigation management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe B2B Legal Services Market |
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Corporate Law, Intellectual Property, Employment Law, Litigation Client Type: Startups, SMEs, Large Enterprises, Government Agencies Delivery Model: On-site Services, Remote Consultation, Subscription Model, Project-based Industry Vertical: Technology, Healthcare, Finance, Retail |
| Companies Covered | Clifford Chance LLP, Freshfields Bruckhaus Deringer LLP, Linklaters LLP, Allen & Overy LLP, Slaughter and May, Hogan Lovells, Norton Rose Fulbright, DLA Piper, Baker McKenzie, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe B2B Legal Services Market Trends and Innovations
Generative AI tools are compressing document review timelines while regulatory complexity expands the scope of mandatory specialized counsel across European jurisdictions.
Natural language processing contract analysis is hybridizing due diligence workflows at major law firms, automating clause extraction and risk flagging in cross-border M&A. Private equity sponsors and strategic acquirers now expect 40-60% faster turnaround on target company document reviews. This compression is reallocating associate hours toward negotiation strategy and regulatory clearance rather than mechanical review tasks.
The EU AI Act's risk-based classification system is forcing enterprises to maintain auditable documentation trails for high-risk automated decision systems. Technology vendors and deployers must establish conformity assessment procedures before market entry. Financial services and healthcare sectors face the steepest compliance burdens, with many firms establishing dedicated AI governance committees staffed by hybrid legal-technical personnel.
General counsel departments are unbundling after-the-event litigation support from ongoing advisory relationships, creating separate procurement streams for disputes versus transactional work. Large enterprises now maintain panels of specialized boutiques alongside full-service relationships. This bifurcation is most advanced in the United Kingdom and Netherlands, where in-house legal teams have achieved sufficient scale to manage multi-vendor coordination.
Europe B2B Legal Services Market Segmentation
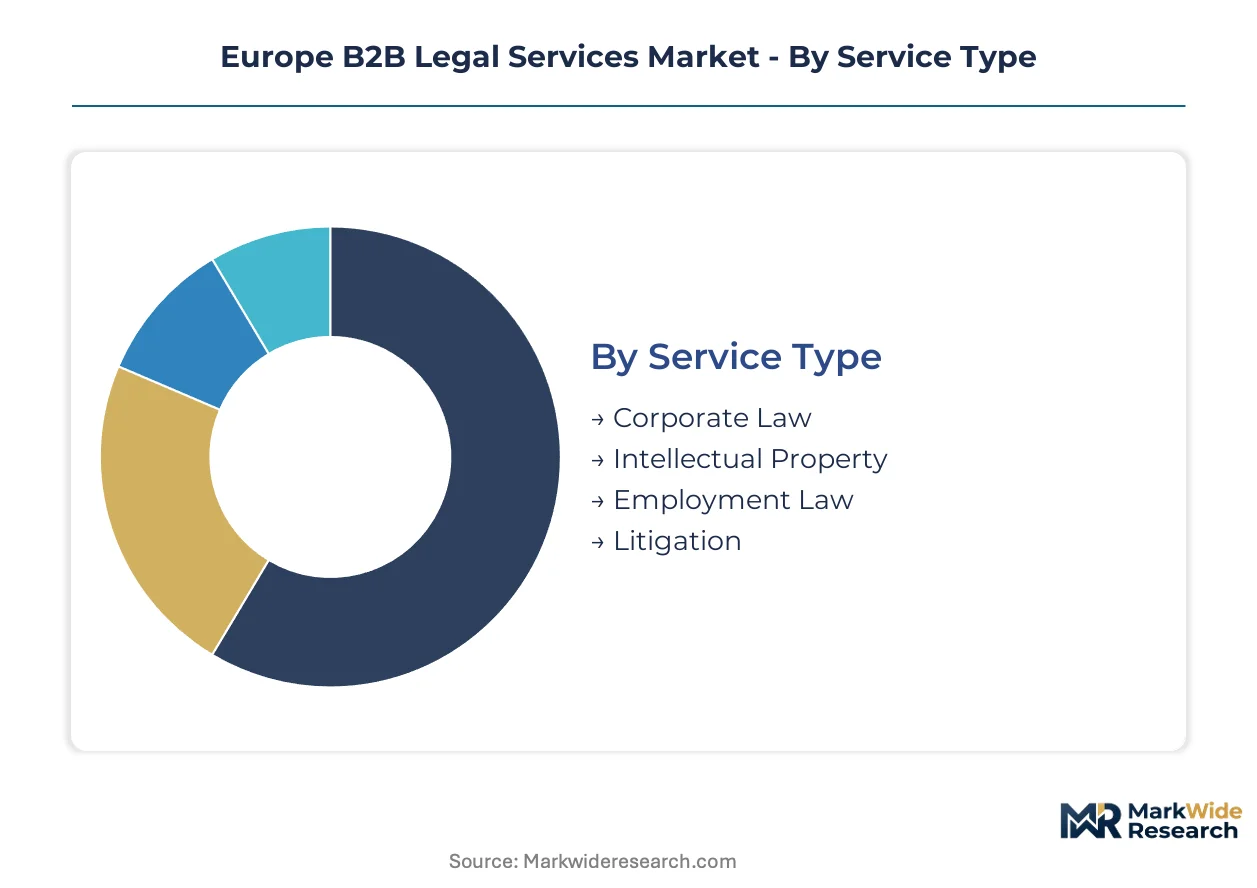
Segmentation in European B2B legal services reveals how procurement patterns diverge across client sophistication tiers and regulatory exposure levels. Service mix and delivery mechanisms shift materially between Frankfurt banking mandates and Amsterdam startup ecosystems.
Service Type:
Corporate law and intellectual property dominate fee generation, while employment and litigation segments respond to cyclical enforcement intensity.
- Corporate Law:Cross-border M&A, capital markets, and restructuring mandates anchor partner-level billing rates. Frankfurt and London banking corridors sustain the deepest transaction pipelines, with EU AI Act compliance layering new advisory scope onto traditional deal work.
- Intellectual Property:Patent prosecution, portfolio management, and licensing negotiations command premium retainers due to technical specialization barriers. Munich and Eindhoven clusters drive demand from semiconductor and automotive R&D operations.
- Employment Law:Collective bargaining, executive compensation, and works council negotiations serve industrial manufacturing concentrations.
- Litigation:Commercial disputes, regulatory enforcement defense, and arbitration support concentrate in London, Paris, and The Hague institutional venues.
Established volume favors Corporate Law; emerging adoption favors Intellectual Property.
Client Type:
Procurement sophistication scales with legal spend predictability and panel management capabilities.
- Large Enterprises:Dedicated general counsel departments unbundle transactional, regulatory, and disputes work across multiple firm relationships. German automotive and French luxury conglomerates maintain the most structured procurement frameworks.
- SMEs:Subscription retainers and fixed-fee commercial templates replace hourly billing unpredictability. Netherlands and UK mid-market buyers show strongest appetite for productized legal services.
- Startups:Venture-backed technology firms prioritize speed and founder-friendly terms over comprehensive coverage.
- Government Agencies:EU institution mandates and national procurement frameworks emphasize cost transparency and geographic diversity requirements.
Revenue concentration sits with Large Enterprises; fastest expansion trajectory belongs to SMEs.
Delivery Model:
Channel selection reflects matter complexity, confidentiality requirements, and client geographic dispersion.
- Project-based:Episodic litigation, M&A transactions, and regulatory investigations sustain traditional hourly and success-fee structures. Complex mandates retain preference for partner-led, site-embedded teams.
- Subscription Model:Monthly retainers covering compliance monitoring, contract templates, and routine advisory democratize access beyond enterprise tier. UK and Dutch markets lead penetration.
- On-site Services:Seconded lawyers and embedded counsel arrangements serve intensive regulatory or restructuring periods.
- Remote Consultation:Video-enabled advisory and document collaboration platforms compress response times for standardized queries.
Margin stability favors Subscription Model; premium realization favors Project-based.
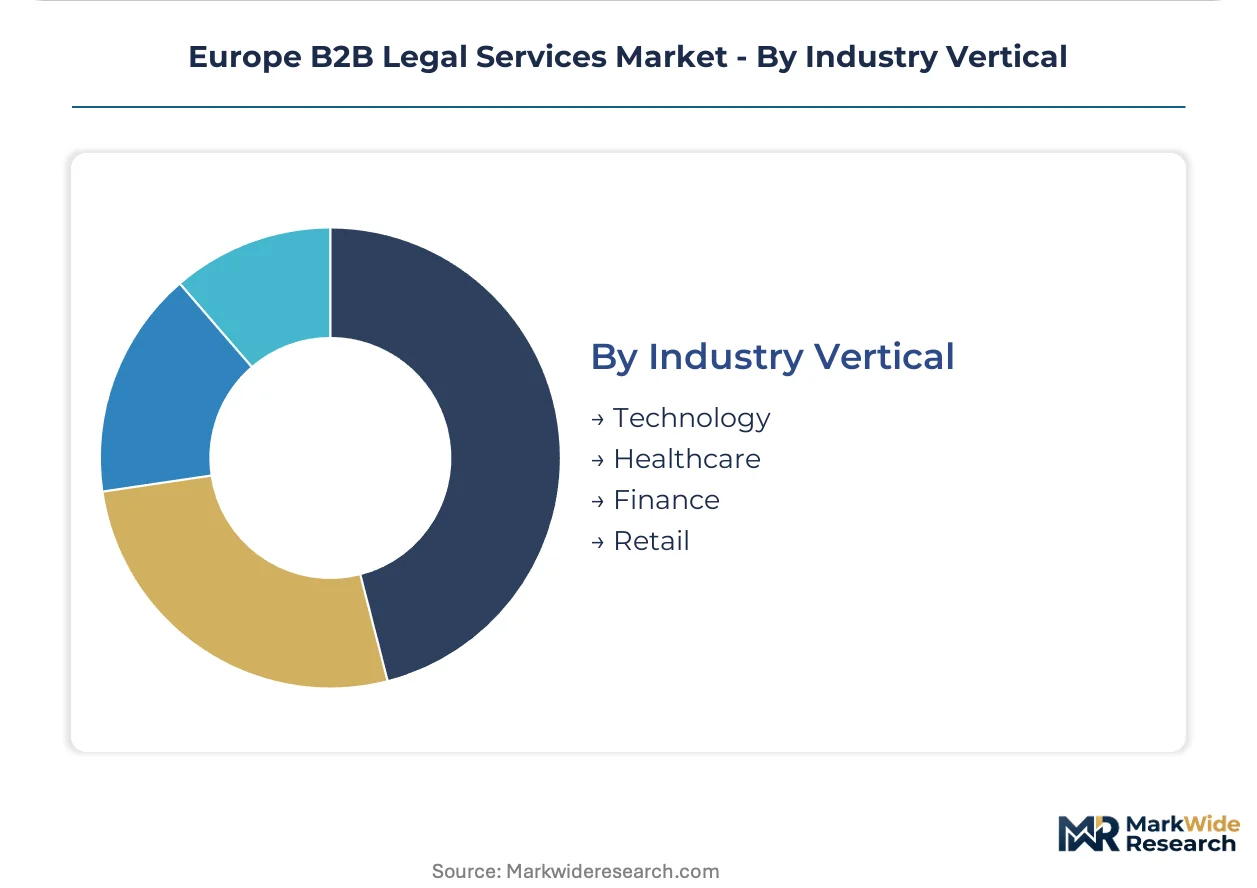
Industry Vertical:
Sector specialization determines counsel selection as regulatory fragmentation deepens.
- Finance:EBA digital operational resilience guidelines and EU AI Act high-risk system mandates drive integrated regulatory-technical advisory demand. Frankfurt, London, and Luxembourg host densest banking and asset management advisory relationships.
- Technology:Data privacy, platform liability, and AI governance requirements concentrate demand in Dublin, Amsterdam, and Berlin startup ecosystems.
- Healthcare:EMA regulatory pathways, clinical trial contracting, and medical device M&A sustain specialized practices.
- Retail:Supply chain due diligence, consumer protection, and sustainability disclosure obligations expand advisory scope under CSRD implementation.
Fee intensity favors Finance; regulatory velocity favors Technology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Financial services procurement teams and corporate legal departments concentrate advisory demand in jurisdictions with dense regulatory infrastructure and cross-border transaction volume. National bar frameworks and EU-wide directives shape where specialized counsel clusters.
Germany
Frankfurt's banking corridor and Munich's industrial headquarters generate sustained demand for M&A and regulatory compliance mandates. The German Federal Bar Association enforces strict multidisciplinary practice restrictions that protect pure-play law firms from accounting firm competition. Bavaria's automotive and semiconductor R&D clusters drive patent prosecution volume through Munich's dense IP practitioner networks.
United Kingdom
London's position as a disputes resolution hub attracts international arbitration and commercial litigation from Asia-Pacific and Middle Eastern parties. The Solicitors Regulation Authority maintains professional conduct standards that facilitate cross-border privilege recognition with common law jurisdictions. The City of London's concentration of private equity sponsors sustains premium transactional advisory rates.
France
Paris hosts the continent's deepest pool of luxury conglomerate and state-owned enterprise legal spend. The French National Bar Council prohibits accounting networks from offering legal advisory alongside audit services. Île-de-France's pharmaceutical and aerospace headquarters generate specialized regulatory counsel demand for EMA pathway navigation.
Netherlands
Amsterdam's technology startup ecosystem and The Hague's arbitration institutions create bifurcated demand for productized SME services and high-stakes commercial disputes. The Netherlands Bar Association permits limited multidisciplinary arrangements that attract alternative legal service providers. Randstad's distribution and logistics headquarters expand supply chain due diligence mandates under CSRD implementation.
Switzerland
Geneva and Zurich private banking centers sustain wealth management and cross-border structuring advisory at premium rate levels. Swissmedic and FINMA regulatory frameworks require specialized compliance counsel for pharmaceutical and financial services verticals. The country's bilateral treaty network with the EU creates distinctive advisory demand around market access and regulatory equivalence.
Europe B2B Legal Services Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions defined by geographic coverage and sector depth. The European B2B legal services market exhibits concentrated partnership structures at the premium tier, with fragmented mid-market competition from national and regional boutiques. Two dominant archetypes emerge: full-service international firms with integrated cross-border capabilities, and sector-specialist boutiques with deep regulatory expertise in single verticals. Competitive moves center on lateral partner recruitment for technology and ESG capabilities, and technology licensing arrangements for contract automation platforms.
Among UK-based full-service partnerships, Clifford Chance LLP, Freshfields Bruckhaus Deringer LLP, and Linklaters LLP occupy positions that exemplify the integrated international archetype. These firms anchor their competitive stance through sustained investment in cross-jurisdictional team structures and proprietary technology platforms. Their market presence reflects the concentration of financial services and cross-border transactional demand in London-Frankfurt corridor work.
| Leading Market Players |
|---|
| Clifford Chance LLP |
| Freshfields Bruckhaus Deringer LLP |
| Linklaters LLP |
| Allen & Overy LLP |
| Slaughter and May |
| Hogan Lovells |
| Norton Rose Fulbright |
| DLA Piper |
| Baker McKenzie |
| Others |
Pricing and Supply Chain Analysis
EU AI Act compliance deadlines function as a regulatory chokepoint that compresses procurement timelines for specialized counsel while simultaneously widening rate spreads between premium-tier international firms and mid-market national competitors. This deadline pressure forces enterprises to accept accelerated billing structures for algorithmic impact assessments and conformity documentation, reshaping how legal services are priced and delivered across the continent.
Pricing Analysis
Cost-plus contracts indexed to associate salary benchmarks dominate project-based engagements for cross-border M&A and regulatory mandates. Three-tier pricing structure across premium, standard, and economy levels separates Magic Circle partnerships from national full-service firms and productized legal template providers. Price differentiation hinges on partner-to-associate leverage ratios and sector certification depth, with financial services specialization commanding substantial premiums. Cost compression in mid-tier hourly rates is intensifying because technology-enabled contract automation commoditizes standardized document review. SME buyers exhibit the highest price sensitivity, while large enterprise general counsel departments prioritize outcome predictability over unit cost minimization.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities have proliferated among corporate legal departments seeking to optimize working capital across multi-vendor panel arrangements. Talent supply concentrates in the United Kingdom, Germany, and the Netherlands, where bar admission pathways and language capabilities sustain the deepest pools of cross-border practitioners. Raw material dependencies include LLM licensing fees, document management infrastructure, and regulatory intelligence subscriptions. Single-source vulnerability sits with specialized technology and data privacy associates whose salary premiums compress partner margins. Distribution runs through direct partner relationships for premium mandates, while alternative legal service providers capture standardized workflow segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe B2B legal services market is entering a cyclical recovery phase as deferred M&A pipelines reactivate and EU AI Act implementation creates sustained compliance advisory demand. Transaction velocity in Frankfurt and London corridors provides the cyclical driver justifying this framing.
For Market Incumbents: Entrench competitive position by accelerating lateral partner recruitment in AI governance and CSRD advisory capabilities before compliance deadlines harden client relationships. Deepen proprietary technology investments in contract automation platforms that embed switching costs. The threat of Big Four consulting networks exploiting regulatory arbitrage in jurisdictions with relaxed multidisciplinary practice restrictions demands preemptive capability consolidation.
For New Entrants and Emerging Players: Southern European SME markets remain substantially underpenetrated by subscription legal service models that have achieved scale in the United Kingdom and Netherlands. Productized compliance monitoring for CSRD disclosure mandates offers the most penetrable white space, given limited incumbent specialization in climate litigation risk assessment. A founder-friendly fixed-fee structure targeting venture-backed technology startups in Amsterdam and Berlin provides the optimal go-to-market angle.
For Investors and Strategic Acquirers: Boutique firms with concentrated EMA regulatory expertise or specialized AI governance practices represent the highest-value acquisition target archetype for platform roll-up strategies. Long-term viability rests on regulatory complexity deepening faster than technology commoditization advances across the advisory stack. The signal to monitor is enforcement intensity under the EU AI Act's high-risk system classification, which would validate premium pricing power for specialized compliance counsel.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Governance Capability Buildout | EU AI Act high-risk system mandates create dedicated advisory revenue streams across financial services and healthcare verticals. |
| CSRD Disclosure Practice Launch | Corporate Sustainability Reporting Directive implementation expands climate litigation risk assessment and supply chain due diligence mandates. |
| Technology Platform Licensing | Proprietary contract automation tools embed client switching costs while compressing associate hours on mechanical review tasks. |
| Netherlands Arbitration Hub Expansion | The Hague's institutional infrastructure attracts Asia-Pacific commercial disputes, diversifying revenue beyond European corporate mandates. |
| Subscription Model Penetration | Predictable monthly retainers democratize legal access to SME buyers beyond traditional enterprise account relationships. |
Research Methodology
Cross-validation between primary stakeholder interviews and secondary regulatory filings anchors the qualitative findings in documented enforcement patterns and procurement behaviors. The analysis draws from conversations with general counsel at German automotive and French luxury conglomerates, managing partners at UK-based international firms, and legal procurement officers at major financial institutions. Secondary validation incorporates EU AI Act implementation guidance, EBA digital operational resilience guidelines, and national bar association disciplinary records. Bottom-up segmentation modeling and top-down macroeconomic overlay triangulation ensure methodological rigor.
Calibration against historical transaction volumes and regulatory enforcement intensity informs the projection framework across the analysis window. Segmentation dimensions include service type, client sophistication tier, delivery model, and industry vertical exposure to EU AI Act compliance burdens. CAGRs derive from trend extrapolation moderated by saturation effects in GDPR litigation and technology-enabled commoditization of standardized advisory work. Forecast inputs incorporate lateral hiring patterns at major firms and panel unbundling trends among large enterprise legal departments.
Macroeconomic conditions sit as an overlay; deviation in interest rate trajectories and cross-border M&A financing availability would shift the trajectory of transactional advisory demand. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and technology adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Global Treasury Software Market
Financial Services
Multivendor ATM Software Market
Financial Services
Global Business Management Consulting Service Market
Financial Services
Middle Office Outsourcing Market
Financial Services
Power Bank Sharing Services Market
Financial Services
Australia Online Gambling Market
Financial Services
Europe E-Brokerages Market
Financial Services
Global Power Bank Rental Service Market
Financial Services
US Healthcare Finance Solutions Market
Financial Services
Mobile Notary Service Market
Financial Services
Europe Financial Advisory Services Market
Financial Services
Contract for Difference Broker Market
Financial Services
Banking Cloud Services Market
Financial Services
Intellectual Property Valuation Market
Financial Services
Australia Online Trading Platform Market
Financial Services
Global Executive Search (Headhunting) Market