
 North America Venture Capital Investment Market | 2026-2036
North America Venture Capital Investment Market Size, Share, and Industry Trends Forecast 2026-2036
North America Venture Capital Investment Market Insights
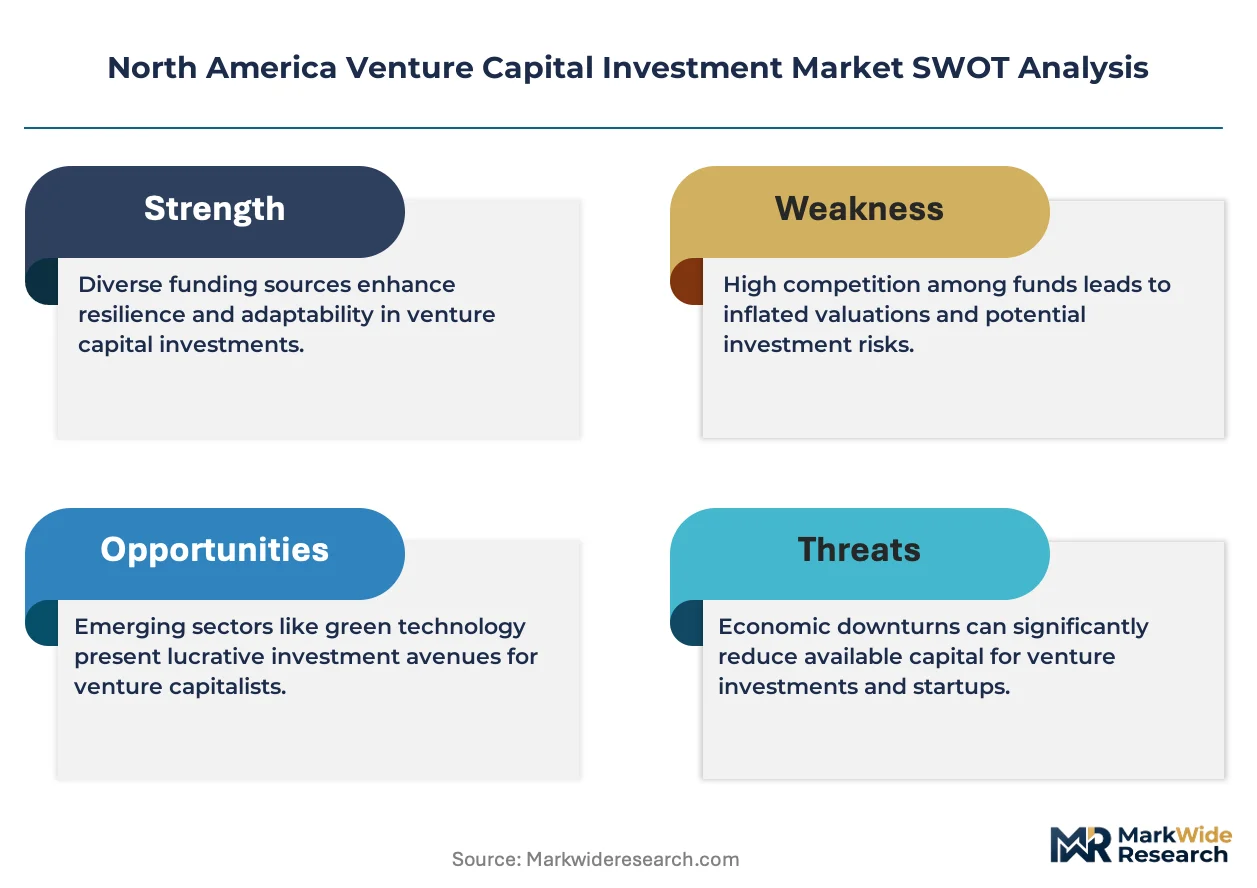
Platform licensing revenue from portfolio analytics tools is reshaping how venture firms monetize intellectual property beyond carried interest. Andreessen Horowitz leverages its media and research divisions to deepen founder relationships and reduce deal sourcing friction. Sequoia Capital anchors its competitive position through a concentrated, high-conviction portfolio construction that sustains premium access to breakout rounds. Greylock Partners differentiates through embedded technical recruiting services that reduce portfolio company execution risk.
North America venture capital investment denotes the structured deployment of risk capital into privately held companies across seed through pre-IPO stages, typically via limited partnership vehicles with ten-year horizons and 2/20 fee structures. The asset class functions as primary growth financing for firms too early or too volatile for public market access, with returns driven by power-law distributions among a small subset of outperformers. Technology sector allocations dominate deployment volume, though healthcare venture has matured into a distinct margin pool with longer holding periods and regulatory-driven due diligence requirements. By investor type, institutional limited partners supply the bulk of committed capital, yet family offices represent the fastest-growing LP category as they seek illiquidity premiums outside public equities. Early-stage investing captures the highest multiple on invested capital when successful, while growth-stage rounds absorb the greatest absolute dollar flows as firms scale toward liquidity events.
The SEC oversees disclosure requirements and accredited investor definitions that gate retail participation, while FINRA regulates broker-dealer activity in secondary transactions and fund placements. State-level blue sky laws in California and New York impose additional registration burdens that shape fund domicile decisions and marketing restrictions. IRS rules on qualified small business stock treatment influence holding-period behavior and exit timing for portfolio companies. Stakeholders must monitor how proposed changes to carried interest taxation and antitrust enforcement priorities could alter fund economics and platform consolidation strategies.
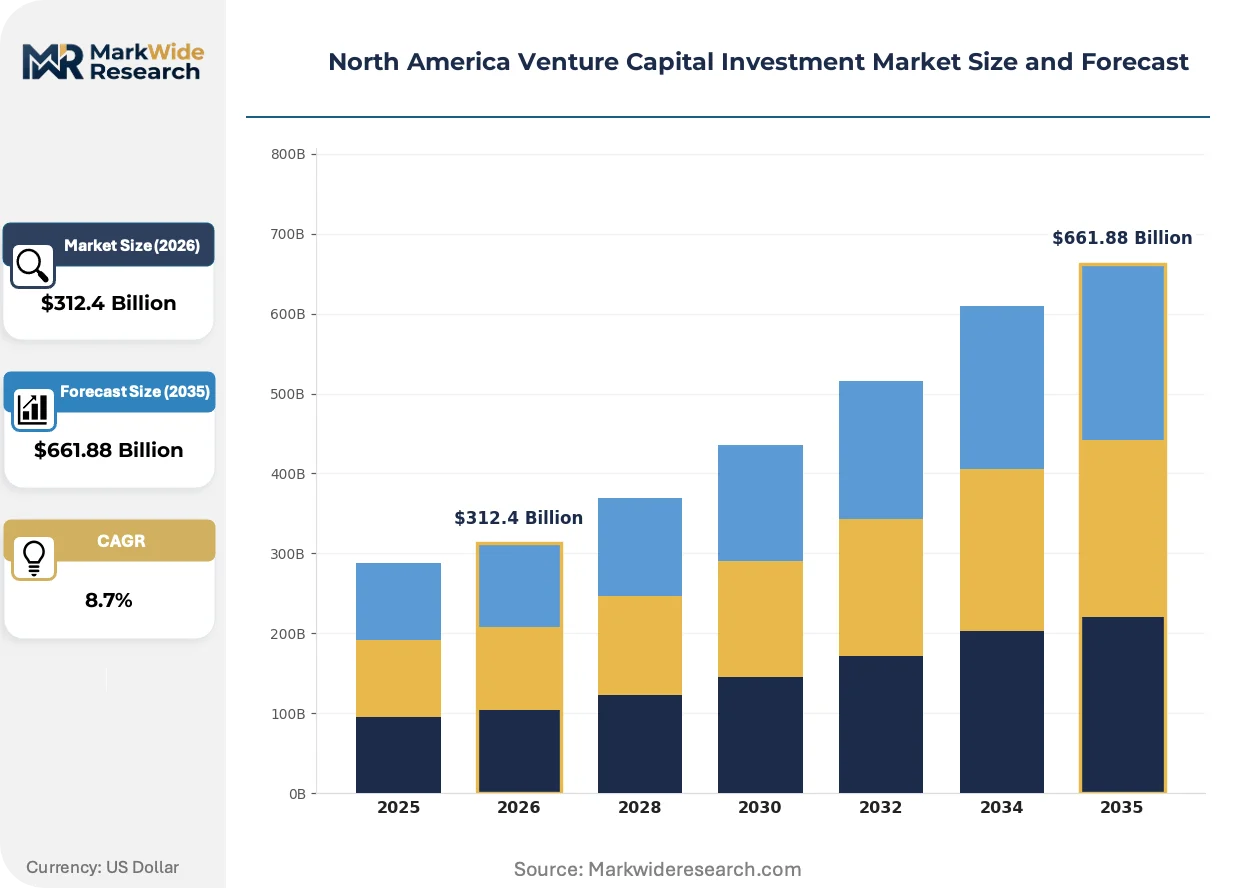
Market Dynamics
Capital deployment velocity in North American venture markets is decoupling from traditional LP fundraising cycles as evergreen fund structures and rolling close vehicles compress deployment timelines and extend manager track record windows.
Growth Catalysts
- Regulation D Expansion:The SEC's broadened accredited investor definitions under 2020 amendments have unlocked family office and high-net-worth individual capital pools previously excluded from private fund access.
- Enterprise Software Demand:Cloud infrastructure spend from Fortune 500 procurement committees is accelerating Series B through D round sizes for vertical SaaS applications in construction, logistics, and healthcare administration.
- Texas-Florida Migration:Founders exiting San Francisco and New York metro areas for Austin, Miami, and Dallas are compressing portfolio company burn rates by 30-40 percent while maintaining coastal talent network access.
Market Restraints
- LP Concentration Risk:Endowment and public pension fund allocations to venture have plateaued near 15 percent of alternatives portfolios, capping fresh capital inflows from traditional institutional sources.
- Carried Interest Taxation Uncertainty:Proposed federal legislation treating carried interest as ordinary income rather than capital gains threatens the 2/20 compensation model underpinning fund economics.
- Secondary Market Illiquidity:Limited partner stakes in 2017-2019 vintage funds trade at 30-50 percent discounts to NAV due to extended holding periods and sparse exit activity.
Strategic Opportunities
- Climate Tech Mandates:Inflation Reduction Act tax credits and loan guarantee programs are channeling institutional capital into clean energy venture vehicles targeting grid-scale storage and industrial decarbonization.
- Healthcare AI Convergence:FDA breakthrough device designation pathways and HIPAA-compliant infrastructure tooling are creating regulatory clarity for clinical decision support and diagnostic imaging startups.
- Embedded Finance:Banking-as-a-service APIs and state-level fintech sandboxes in Wyoming and South Dakota are enabling vertical software platforms to capture payment and lending margin pools.
Industry Challenges
- Technical Talent Scarcity:Machine learning engineering and infrastructure platform roles command 40-60 percent compensation premiums over general software development, straining portfolio company hiring velocity.
- Valuation Reset Friction:Down-round financing mechanics and anti-dilution provision triggers from 2021 peak valuations are consuming legal bandwidth and founder equity at unprecedented rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Venture Capital Investment Market |
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $661.88 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Investment Stage: Seed, Early Stage, Growth Stage, Late Stage Investor Type: Institutional Investors, Angel Investors, Corporations, Family Offices Sector: Technology, Healthcare, Consumer Products, Fintech Funding Size: Micro, Small, Medium, Large |
| Companies Covered | Andreessen Horowitz, General Catalyst, Sequoia Capital, Accel, New Enterprise Associates, Khosla Ventures, Bessemer Venture Partners, Greylock Partners, Lightspeed Venture Partners, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Venture Capital Investment Market Trends and Innovations
Artificial intelligence tooling is compressing due diligence timelines and reshaping how venture firms source, evaluate, and support portfolio companies across the investment lifecycle.
Generative AI co-pilots for financial modeling and market sizing are hybridizing traditional associate-driven research workflows at early-stage firms. Seed and Series A investors in San Francisco and New York are deploying these tools to screen 3-4x more opportunities per partner without expanding headcount. The technology is compressing initial pitch-to-term-sheet cycles from six weeks to under ten days for software categories with sufficient training data.
SEC disclosure modernization rules and state-level blue sky harmonization efforts are reducing cross-border fundraising friction for multi-state fund vehicles. The industrial consequence is a migration of fund domicile selection from Delaware-centric structures toward Wyoming and South Dakota jurisdictions offering streamlined regulatory frameworks. Emerging managers targeting regional LP bases are responding by establishing feeder vehicles optimized for state-specific tax treatment and investor accreditation verification.
Founder preferences for transparent compensation benchmarking and equity liquidity pathways are displacing opaque legacy practices at established venture firms. Talent marketplaces and secondary transaction platforms are replacing informal founder network introductions as the primary channel for executive recruiting and early employee liquidity. This behavioral shift is most visible in Austin and Miami ecosystems where transplanted coastal operators demand institutional-grade HR infrastructure from seed-stage backers.
North America Venture Capital Investment Market Segmentation
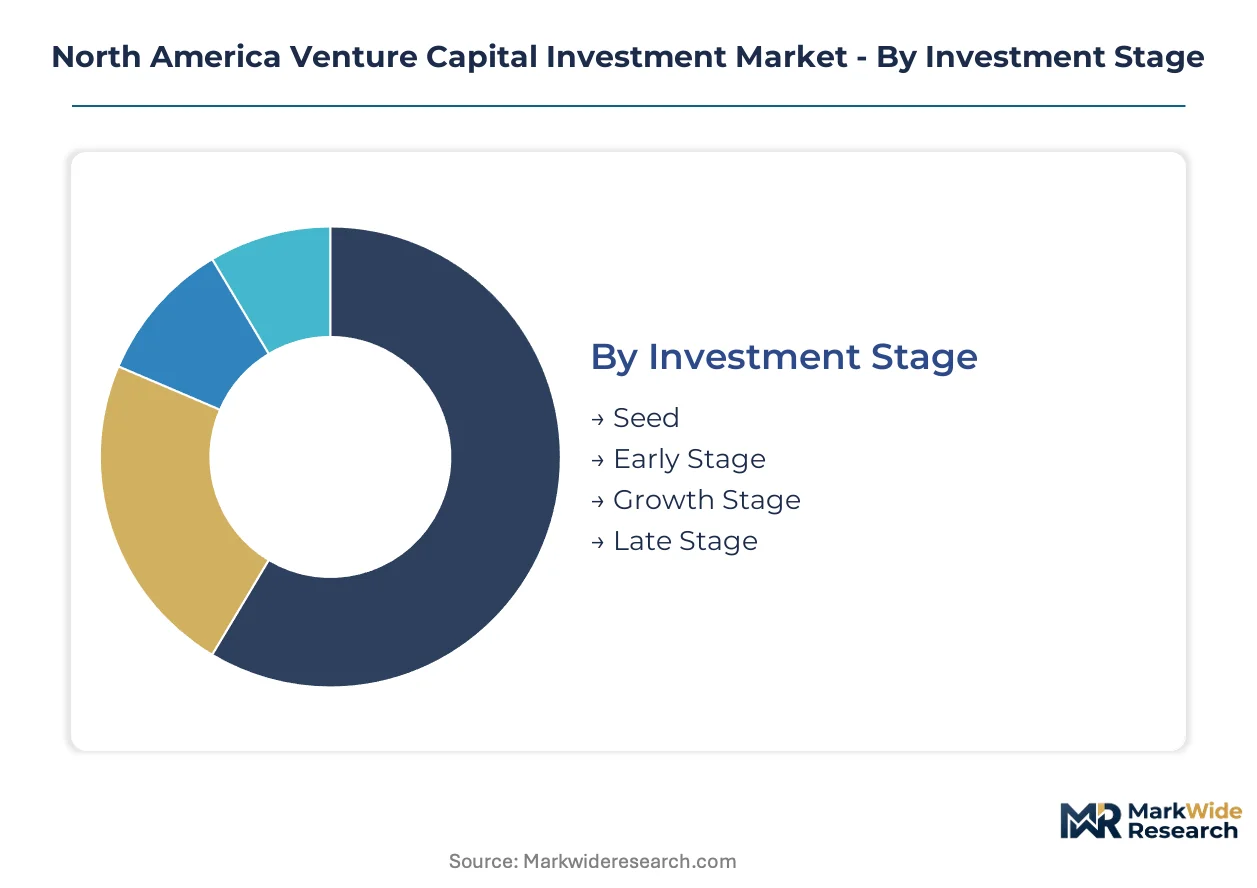
Segmentation in venture capital investment reveals how capital deployment patterns, risk-return profiles, and LP preferences vary across structural dimensions. Understanding these divisions enables firms to optimize fund construction, target specific LP bases, and align portfolio strategy with market opportunity sets.
Investment Stage:
After-sales-service intensity peaks at growth and late stages, where portfolio companies require intensive operational support, executive recruiting, and secondary transaction facilitation to prepare for exit events.
- Seed:Initial capital injections of $500K to $2M validate product-market fit and build founding teams. Demand concentrates in Austin and Miami as coastal transplants seek lower burn-rate environments with maintained network access.
- Early Stage:Series A and B rounds scaling customer acquisition and engineering headcount. Texas and Florida ecosystems absorb the fastest deployment velocity as founders exit high-cost metros for 30-40 percent operating cost reductions.
- Growth Stage:Expansion capital for revenue scaling and geographic market entry.
- Late Stage:Pre-IPO financing and secondary liquidity for early employees and investors.
By volume, Growth Stage leads. By growth pace, Seed is climbing the fastest as micro-funds proliferate and solo capitalists deploy at unprecedented velocity.
Investor Type:
Cost tier stratification separates institutional LPs committing $50M+ per fund from family offices deploying $1-5M tickets through feeder vehicles and sidecar structures.
- Institutional Investors:Endowments, public pension funds, and insurance companies supplying committed capital through ten-year limited partnership vehicles. Yale and Stanford endowments anchor the largest fund closes, though allocations have plateaued near 15 percent of alternatives portfolios.
- Angel Investors:High-net-worth individuals deploying personal capital at seed stage. California and New York metro areas retain the densest angel networks despite founder migration trends.
- Corporations:Strategic venture arms seeking technology access and acquisition optionality.
- Family Offices:The fastest-expanding LP category as wealth managers seek illiquidity premiums outside public equities.
By volume, Institutional Investors lead. By growth pace, Family Offices are expanding most quickly under SEC Regulation D accredited investor expansion.
Sector:
Application-driven segmentation aligns fund mandates with LP thematic priorities and regulatory tailwinds shaping exit pathway clarity.
- Technology:Enterprise software, infrastructure tooling, and artificial intelligence platforms capturing the dominant share of deployed capital. Cloud procurement committees at Fortune 500 firms accelerate Series B through D round sizes for vertical SaaS applications.
- Healthcare:Biotech, medical devices, and digital health with longer holding periods and FDA-driven due diligence requirements. FDA breakthrough device designation pathways create regulatory clarity for clinical decision support startups.
- Consumer Products:Direct-to-commerce brands and physical goods with capital-intensive inventory cycles.
- Fintech:Banking-as-a-service APIs and embedded finance platforms leveraging Wyoming and South Dakota regulatory sandboxes.
By volume, Technology leads. By growth pace, Healthcare is gaining share fastest as AI convergence accelerates diagnostic imaging and clinical workflow automation.
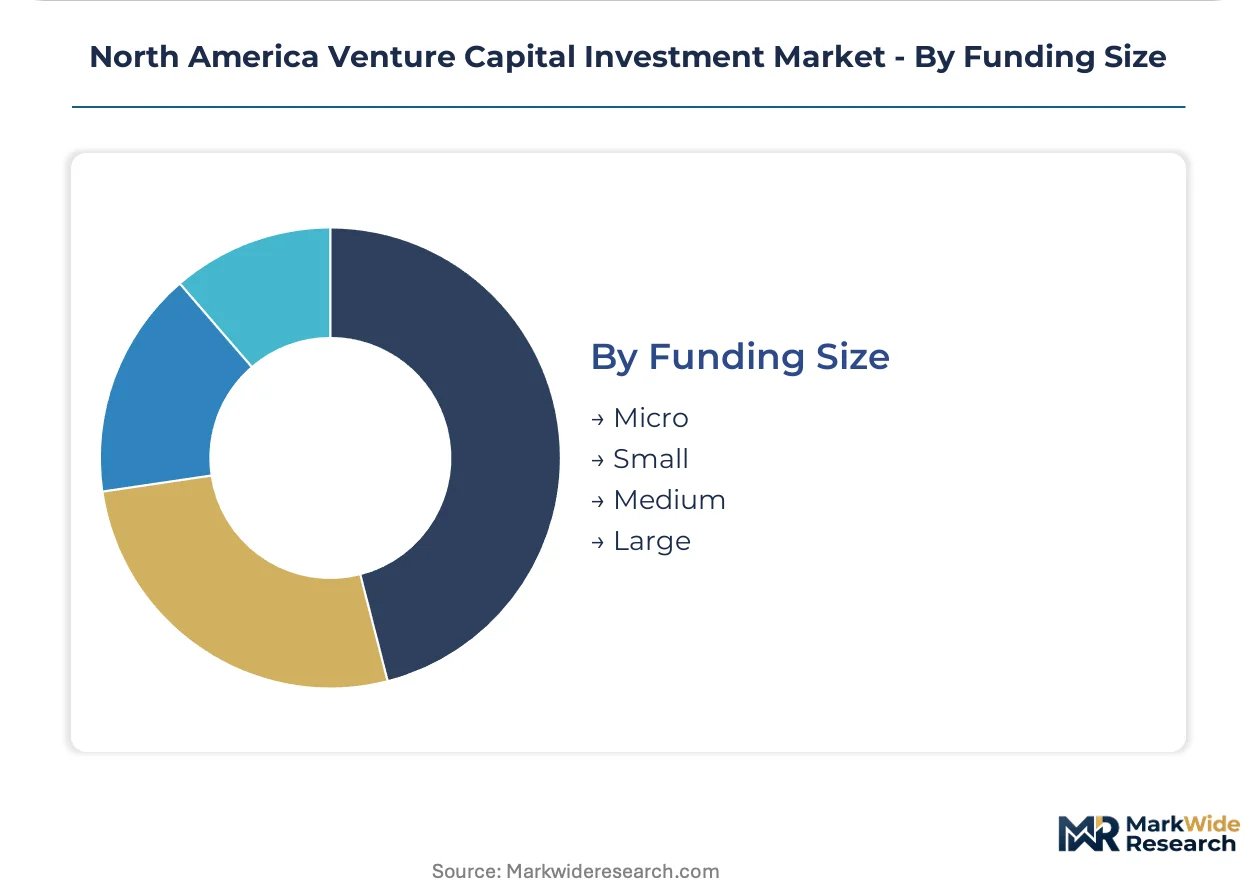
Funding Size:
Volume concentration determines fund economics, with large rounds absorbing the greatest absolute dollar flows while micro rounds generate the highest multiple on invested capital when successful.
- Micro:Sub-$1M checks from pre-seed and angel syndicates. Solo capitalists and rolling fund vehicles compress fundraising timelines to under 30 days for software categories with proven founder-market fit.
- Small:$1-10M rounds led by seed-focused firms with concentrated portfolio construction. Austin and Miami ecosystems show elevated small-round velocity as transplanted operators demand institutional-grade backing at earlier stages.
- Medium:$10-50M growth capital for Series B and C expansion.
- Large:$50M+ growth and late-stage rounds scaling toward liquidity events.
By volume, Large leads. By growth pace, Micro is climbing the fastest as evergreen fund structures and rolling close vehicles democratize access to early-stage deal flow.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States buyers demonstrate the lowest price sensitivity to management fees given scale advantages and track record premiums, while Canadian and Mexican LPs negotiate harder on carry structures and co-investment rights. Demand elasticity varies sharply across the three markets.
United States
SEC Regulation D amendments have unlocked family office capital pools previously excluded from private fund access. The Inflation Reduction Act channels institutional commitments into climate tech vehicles targeting grid-scale storage. Austin and Miami absorb the fastest deployment velocity as founders exit San Francisco and New York for 30-40 percent burn-rate reductions.
Canada
Ontario and Quebec pension funds anchor venture allocations though commitments have plateaued near 15 percent of alternatives portfolios. Health Canada regulatory clarity for digital therapeutics creates demand for healthcare AI convergence plays. Toronto-Waterloo corridor concentrates technical talent scarcity mitigation through university pipeline partnerships.
Mexico
Fintech sandbox frameworks in Mexico City enable embedded finance platform scaling with reduced regulatory friction. Central bank digital currency pilots stimulate demand for banking-as-a-service infrastructure. Monterrey and Guadalajara industrial clusters attract cross-border Series A deployment from US-based seed funds seeking lower valuation entry points.
North America Venture Capital Investment Market Competitive Landscape
Capability concentration sits with established multi-stage platforms; scale advantage sits with sector-focused specialists and emerging regional players. The market structures around three tiers: concentrated legacy franchises with media and research divisions, mid-size firms with embedded technical recruiting services, and solo capitalists with rolling fund vehicles. Strategic archetypes include platform builders monetizing intellectual property beyond carried interest, conviction-driven portfolio constructors sustaining premium round access, and operational specialists reducing execution risk through talent marketplaces. Dominant competitive moves encompass fund domicile migration to Wyoming and South Dakota for streamlined regulatory frameworks, and evergreen structures compressing deployment timelines.
Within the platform builder tier, Andreessen Horowitz and Sequoia Capital exemplify divergent approaches to founder relationship depth and portfolio construction discipline. Greylock Partners occupies a position among operational specialists leveraging technical recruiting differentiation. Bessemer Venture Partners and Accel represent scale-driven franchises with sector concentration in enterprise software and fintech respectively.
| Leading Market Players |
|---|
| Andreessen Horowitz |
| General Catalyst |
| Sequoia Capital |
| Accel |
| New Enterprise Associates |
| Khosla Ventures |
| Bessemer Venture Partners |
| Greylock Partners |
| Lightspeed Venture Partners |
| Others |
Pricing and Supply Chain Analysis
Delaware-domiciled fund administrators and Cayman Islands legal counsel anchor the upstream service layer, concentrating margin capture with specialized law firms and fund formation agents before capital reaches portfolio companies. This geographic concentration of fund infrastructure services shapes downstream pricing power across management fee tiers and carried interest structures.
Pricing Analysis
Platform services revenue from portfolio analytics and technical recruiting tools drives lifetime value beyond traditional 2/20 fund economics. Pricing stratifies across premium multi-stage platforms with embedded media divisions, mid-tier specialists offering operational support, and emerging managers competing on fee compression. Pricing pressure stems from LP demands for fee transparency and co-investment rights as family offices negotiate harder on carry structures. Institutional endowments demonstrate lowest price sensitivity given scale advantages, while emerging managers face acute sensitivity from first-time family office LPs.
Supply Chain Analysis
Upstream capital formation draws from Delaware and Wyoming fund domiciles, New York and California LP concentration, and Texas-Florida founder migration corridors. The supply chain rests on limited partnership agreements, regulatory compliance infrastructure, and portfolio company governance frameworks. Single-source vulnerability sits with concentrated prime broker relationships for late-stage secondary transactions. Distribution runs through feeder vehicles, sidecar structures, and direct LP commitments to fund managers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of technical operating partners with genuine company-building experience defines competitive advantage in this market, separating platforms that deliver execution support from those merely deploying capital.
For Market Incumbents: Entrench founder relationships through embedded recruiting and secondary liquidity services before emerging managers replicate operational toolkits. Deepen platform moats by acquiring specialized technical talent marketplaces. Defend against fee compression threats from rolling fund vehicles by demonstrating measurable portfolio company velocity improvements. For New Entrants and Emerging Players: Build out regional presence in Austin and Miami where transplanted coastal operators demand institutional-grade infrastructure at seed stage. Target healthcare AI convergence and climate tech mandates as most penetrable thematic segments. Lead with transparent compensation benchmarking and equity liquidity pathways as differentiated go-to-market positioning. For Investors and Strategic Acquirers: Secondary-cycle assets sit with 2017-2019 vintage funds trading at structural discounts to NAV due to extended holding periods. Long-term viability hinges on manager track record through multiple macro cycles rather than single vintage performance. Monitor LP allocation decisions at public pension funds as inflection indicator for fresh capital inflows.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Services Expansion | Andreessen Horowitz demonstrates how media and research divisions deepen founder relationships and reduce sourcing friction. |
| Regional Fund Domicile Migration | Wyoming and South Dakota streamlined regulatory frameworks attract emerging managers seeking state-specific tax optimization. |
| Evergreen Fund Structure Adoption | Rolling close vehicles compress deployment timelines and extend manager track record windows beyond traditional ten-year horizons. |
| Technical Recruiting Integration | Greylock Partners leverages embedded talent services to reduce portfolio company execution risk and differentiation. |
| Climate Tech Mandate Targeting | Inflation Reduction Act tax credits channel institutional commitments into clean energy vehicles with regulatory tailwind clarity. |
Research Methodology
A spread of perspectives from fund general partners, limited partner portfolio managers, fund formation attorneys, and portfolio company founders converged on the working assumptions shaping this analysis. Primary interviews with these stakeholders combined with secondary validation from SEC filings, FINRA regulatory notices, state blue sky law databases, and venture capital performance benchmarks. Bottom-up deal flow analysis and top-down LP allocation modeling triangulated market size estimates.
Demand-supply balance across capital deployment velocity and LP commitment pacing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include investment stage, investor type, sector concentration, and funding size tier. CAGRs derived from historical deployment patterns, vintage fund performance distributions, and structural shifts in fund vehicle design. Forecast inputs incorporated SEC accredited investor expansion effects and founder geographic migration patterns.
The forecast holds incumbent behavior within observed patterns; aggressive fee compression moves by solo capitalists with rolling fund vehicles would shift outcomes beyond projected ranges. Cross-checking against Cambridge Associates and Preqin venture performance benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Venture Capital
Impact Investing Market
Venture Capital
Europe Venture Capital Market
Venture Capital
US Venture Capital Investment Market
Venture Capital
Venture Capital Investment Market
Venture Capital
Asia Pacific Venture Capital Market
Venture Capital
Asia-Pacific Venture Capital Investment Market
Venture Capital
Business Incubator Market
Venture Capital
LAMEA Venture Capital Investment Market
Venture Capital
Angel Funds Market
Venture Capital
United States Venture Capital Market
Venture Capital
Crowdfunding Market
Venture Capital
Middle East and Africa Venture Capital Market
Venture Capital
North America Venture Capital Market
Venture Capital
Equity Crowdfunding Market
Venture Capital
Micro VC Funds Market
Venture Capital
Global Art Crowdfunding Market