
 Europe Governance, Risk and Compliance Platform Market | 2026-2036
Europe Governance, Risk and Compliance Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Governance, Risk and Compliance Platform Market Intelligence
Subscription-based compliance monitoring is hardening into the core revenue model for European GRC vendors. SAP SE leverages its embedded ERP footprint to bundle risk analytics directly into financial workflows. Wolters Kluwer sustains dominance in regulatory content through continuous updates spanning EU member state variations. MetricStream anchors its position in cloud-native audit orchestration for mid-market financial institutions.
Europe Governance, Risk and Compliance Platform denotes integrated software environments that consolidate policy libraries, control testing engines, and incident ticketing into unified workflow architectures, typically deployed via REST APIs and SAML-based identity federation to satisfy cross-border data residency requirements. Cloud-based delivery leads technology adoption as banks migrate from fragmented on-premise spreadsheets to centralized SaaS control towers, while hybrid configurations persist among German manufacturers balancing legacy SCADA integration with modern risk dashboards. Application-level demand concentrates in compliance management modules where real-time regulatory change feeds from EBA and ECB guidance documents reduce manual interpretation overhead.
EU AI Act enforcement through national competent authorities and EBA guidelines on ICT risk management are reshaping product certification requirements for platform vendors seeking bank procurement approval. GDPR Article 32 technical measures and DORA's third-party risk registers create overlapping compliance obligations that drive consolidation toward multi-tenant architectures. Stakeholders must weigh whether to build captive compliance engines or absorb vendor roadmaps that promise pre-certified control mappings against evolving supervisory expectations.
Market Dynamics
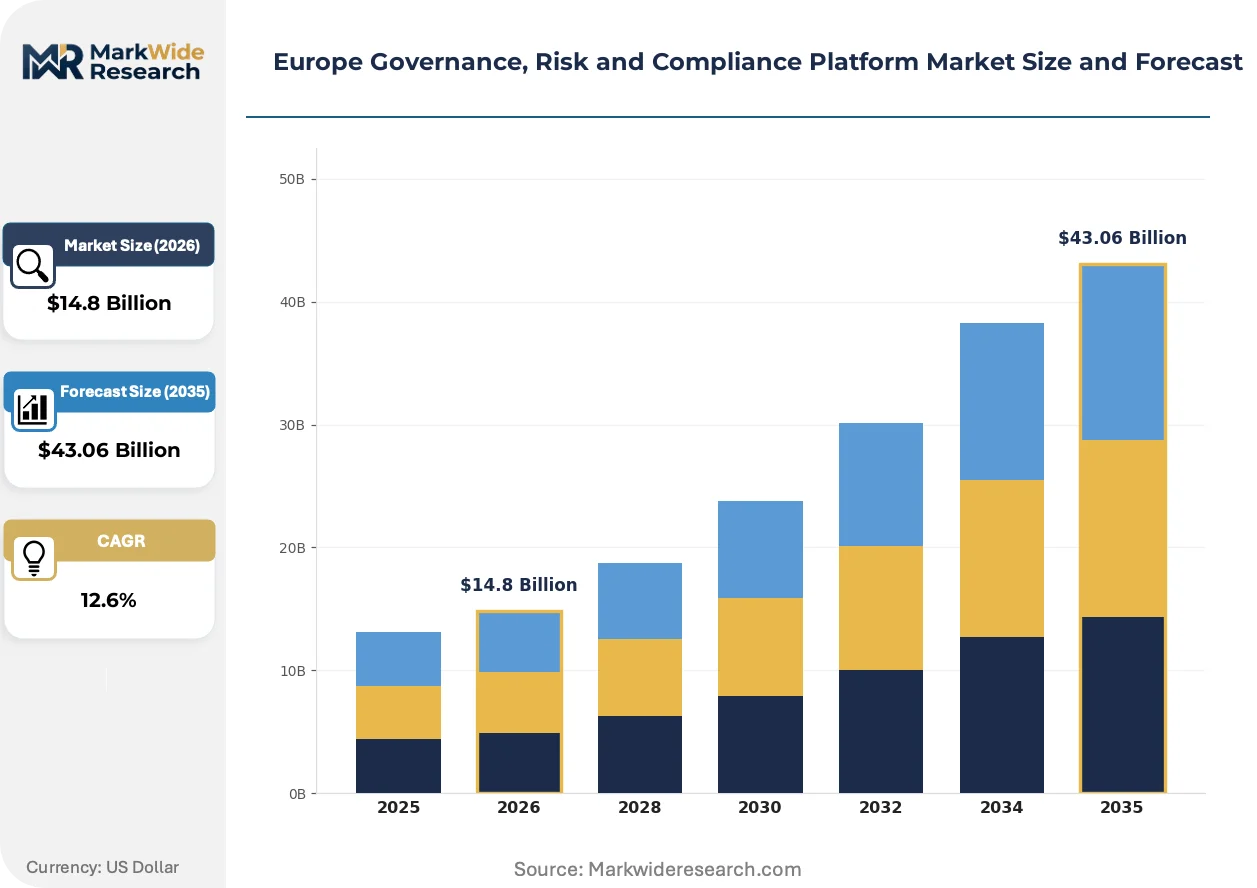
EU AI Act enforcement and DORA implementation timelines are compressing procurement cycles, forcing banks to replace fragmented compliance spreadsheets with unified SaaS control towers that embed real-time regulatory feeds directly into financial workflows.
Growth Catalysts
- EBA ICT Risk Guidelines:European Banking Authority mandates on operational resilience are compelling institutions to automate control testing and incident reporting through integrated GRC platforms.
- Cloud-native audit orchestration:Mid-market financial institutions in Germany and France are migrating from on-premise legacy systems to multi-tenant SaaS architectures for cross-border data residency compliance.
- Netherlands granular timelines:Dutch national regulators have issued specific DORA compliance deadlines that accelerate platform procurement among Amsterdam-headquartered banking groups.
Market Restraints
- SCADA integration friction:German manufacturers face prohibitive retrofit costs when connecting legacy industrial control systems to modern risk dashboards.
- GDPR Article 32 technical measures:Overlapping data protection obligations create architectural complexity that extends implementation timelines and inflates professional services spend.
- Regulatory content fragmentation:Vendors must maintain parallel update streams for 27 EU member state variations, straining content engineering resources.
Strategic Opportunities
- Polish and Romanian banking sectors:These markets show underpenetrated GRC adoption relative to Western European peers, presenting first-mover expansion potential.
- Third-party risk registers:DORA's vendor oversight requirements create demand for automated supplier assessment modules that integrate with procurement systems.
- AI governance tooling:Convergence of machine learning explainability frameworks with traditional risk engines opens new product categories for algorithmic audit trails.
Industry Challenges
- SAML-based identity federation expertise:Shortage of engineers skilled in cross-border authentication protocols delays enterprise deployments.
- Pre-certified control mapping:Vendors must maintain continuous alignment with evolving ECB and EBA supervisory expectations, requiring dedicated regulatory affairs functions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Governance, Risk and Compliance Platform Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $43.06 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consulting, Implementation, Support, Training Technology: Cloud-based, On-premise, Hybrid, Mobile End User: Financial Services, Healthcare, Manufacturing, Retail Application: Compliance Management, Risk Assessment, Audit Management, Policy Management |
| Companies Covered | SAP SE, Wolters Kluwer, MetricStream, Ideagen, SureCloud, Swiss GRC AG, Oxial, GlobalSuite Solutions, Acuity Risk Management, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Governance, Risk and Compliance Platform Market Strategic Shifts & Innovations
European GRC platforms are embedding real-time regulatory intelligence directly into operational workflows, collapsing the lag between supervisory guidance issuance and control implementation.
Continuous control monitoring engines are converging with ERP financial workflows to enable automated policy-to-payment traceability. Large German banking groups are deploying these integrations at scale across treasury and procurement functions. This convergence is compressing the traditional audit cycle from quarterly to near-real-time assurance.
EU AI Act enforcement through national competent authorities is mandating algorithmic risk documentation for high-stakes financial decisions. Institutions must maintain technical logs of model training data, performance metrics, and human oversight protocols. Dutch and French regulators have issued the first compliance deadlines, pushing banks to procure certified governance modules before penalties activate.
Subscription-based compliance monitoring is displacing perpetual license models across mid-market financial institutions. Chief risk officers now prefer operational expenditure structures that bundle content updates with platform access. This shift is most visible in Benelux banking clusters where procurement teams prioritize vendor roadmaps over in-house development.
Europe Governance, Risk and Compliance Platform Market Segmentation
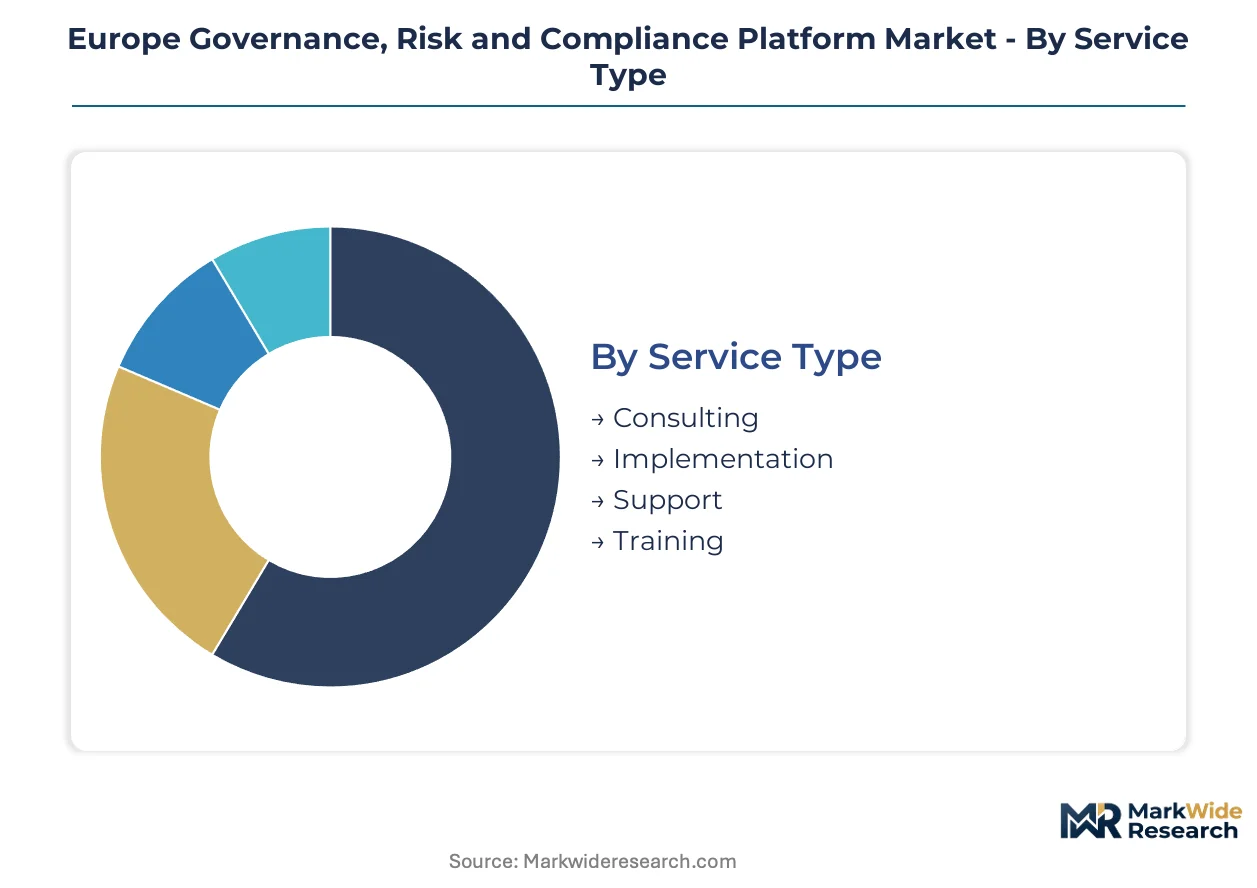
Platform procurement across European banking and manufacturing sectors fragments across service layers, deployment architectures, and functional modules. Procurement teams weigh upgrade cycles against DORA and EU AI Act deadlines when selecting configuration combinations. Segmentation clarity enables vendors to align pre-certified control mappings with specific buyer risk profiles.
Service Type:
Replacement cycles for legacy compliance infrastructure are compressing advisory and deployment timelines simultaneously.
- Consulting:Regulatory interpretation services bridge gaps between EBA guidance issuance and internal policy translation. Demand concentrates among Amsterdam and Frankfurt banking clusters facing compressed DORA implementation windows.
- Implementation:System integration projects encompass SAML federation configuration, ERP connector deployment, and multi-tenant data residency setup. German manufacturers prioritize hybrid SCADA integrations that preserve legacy control investments while enabling modern risk dashboards.
- Support:Continuous update streams maintain alignment with ECB supervisory expectations and 27 member state regulatory variations.
- Training:Certification programs address shortages in cross-border identity federation expertise and algorithmic audit documentation protocols.
Volume placements concentrate in Implementation; the faster expansion belongs to Consulting.
Technology:
Cost tier differentiation separates centralized SaaS control towers from capital-intensive on-premise retention.
- Cloud-based:Multi-tenant architectures enable real-time regulatory feed ingestion and automated control testing. Mid-market financial institutions in France and the Netherlands are migrating from fragmented spreadsheets to unified SaaS environments.
- On-premise:Captive infrastructure persists among German banking groups with stringent data sovereignty requirements and legacy mainframe dependencies.
- Hybrid:Split deployments balance GDPR Article 32 technical measures against cloud scalability, particularly in cross-border treasury operations.
- Mobile:Responsive audit interfaces extend policy-to-payment traceability to field personnel and executive review workflows.
Revenue concentration sits with Cloud-based deployments; Hybrid configurations are climbing the fastest as manufacturers phase transition timelines.
End User:
Application maturity varies sharply across sector-specific regulatory exposure profiles.
- Financial Services:Banking groups automate regulatory reporting under EBA ICT Risk Guidelines and EU AI Act algorithmic documentation mandates. Dutch and French regulators have issued the first compliance deadlines.
- Healthcare:GDPR Article 32 technical measures and patient data governance requirements drive platform adoption for clinical trial documentation and pharmacovigilance workflows.
- Manufacturing:German industrial clusters face SCADA integration friction when retrofitting legacy control systems to modern risk dashboards.
- Retail:Supply chain transparency modules address ESG disclosure requirements and third-party vendor oversight under DORA.
Procurement volume dominates Financial Services; Retail is expanding most quickly as ESG compliance deadlines approach.
Application:
Customer type segmentation separates integrated platform buyers from point-solution adopters.
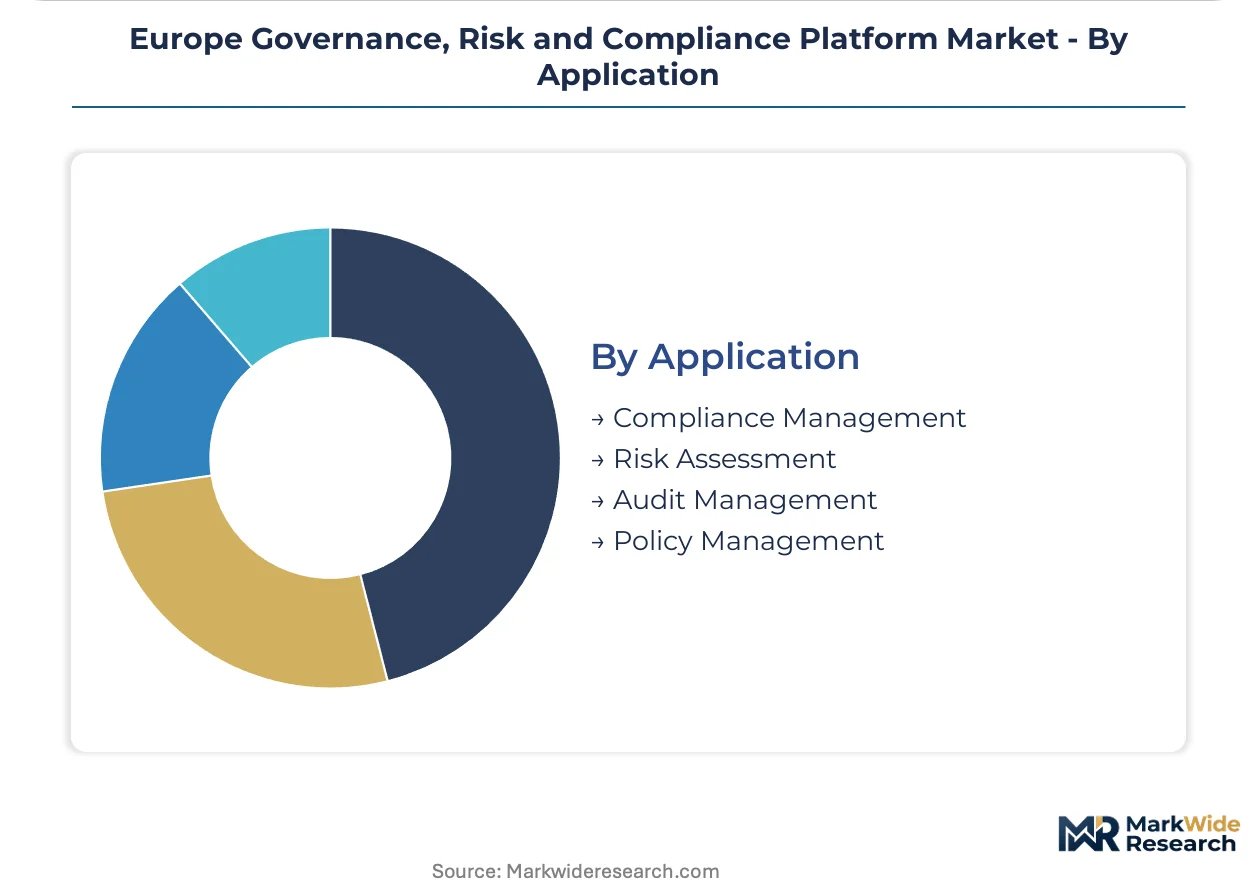
- Compliance Management:Real-time regulatory change feeds from EBA and ECB guidance documents reduce manual interpretation overhead. Chief risk officers in Benelux banking clusters prefer subscription bundles combining content updates with platform access.
- Risk Assessment:Continuous control monitoring engines converge with ERP financial workflows to enable automated policy-to-payment traceability across treasury functions.
- Audit Management:Cloud-native orchestration compresses traditional audit cycles from quarterly to near-real-time assurance for mid-market institutions.
- Policy Management:Centralized policy libraries with version control and attestation tracking satisfy supervisory documentation requirements.
Deployment scale favors Compliance Management; Risk Assessment modules are gaining share fastest as AI governance tooling converges with traditional engines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform production concentrates among Dutch and German software vendors, while consumption spreads across banking clusters in Amsterdam, Frankfurt, and Paris responding to DORA and EU AI Act deadlines.
Germany
BaFin supervisory mandates and DORA implementation timelines compress procurement cycles for Frankfurt banking groups. The EU AI Act algorithmic documentation requirements force institutions to upgrade legacy risk infrastructure. Bavarian industrial manufacturers face SCADA integration friction when connecting legacy control systems to modern risk dashboards.
France
ACPR enforcement of EBA ICT Risk Guidelines drives automation of control testing among Paris-headquartered banking groups. The EU AI Act mandates technical logs for high-stakes financial decisions through national competent authorities. Île-de-France financial clusters procure certified governance modules ahead of penalty activation dates.
Netherlands
DNB granular compliance timelines accelerate platform adoption among Amsterdam banking headquarters. DORA third-party risk registers create demand for automated supplier assessment modules. Dutch regulators issued the first EU AI Act deadlines, pushing institutions toward subscription-based compliance monitoring.
United Kingdom
FCA operational resilience expectations and post-Brexit regulatory divergence shape procurement patterns for London financial institutions. PRA supervisory statements on ICT risk management drive cloud-native audit orchestration adoption. The UK-EU regulatory border creates hybrid architecture demand for cross-border treasury operations.
Switzerland
FINMA guidance on operational risk and third-party outsourcing compels Zurich and Geneva private banks to consolidate fragmented compliance spreadsheets. Swiss GRC vendors leverage neutrality advantages for EU-facing institutions. The country's data sovereignty requirements sustain hybrid deployment preferences among wealth managers.
Europe Governance, Risk and Compliance Platform Market Key Industry Players
Top-tier vendors anchor the integrated platform segment, while specialized content providers and cloud-native specialists occupy distinct competitive tiers. The vendor base clusters around three strategic archetypes: ERP-embedded risk analytics bundlers, regulatory content aggregators maintaining parallel update streams, and audit orchestration specialists. Consolidation pressure intensifies as DORA and EU AI Act deadlines force procurement teams toward pre-certified control mappings. Dominant competitive moves include strategic partnerships for SAML federation expertise and portfolio diversification into AI governance tooling.
Within the ERP-embedded tier, SAP SE leverages its existing financial workflow footprint to bundle risk analytics directly into procurement and treasury functions. Wolters Kluwer occupies a position as the regulatory content archetype, sustaining market presence through continuous update engineering across EU member state variations. MetricStream exemplifies the cloud-native audit orchestration specialist, anchoring its competitive position among mid-market financial institutions migrating from fragmented on-premise systems.
| Leading Market Players |
|---|
| SAP SE |
| Wolters Kluwer |
| MetricStream |
| Ideagen |
| SureCloud |
| Swiss GRC AG |
| Oxial |
| GlobalSuite Solutions |
| Acuity Risk Management |
| Others |
Cost & Logistics Intelligence
Frankfurt and Amsterdam banking clusters concentrate procurement authority for enterprise GRC platforms, locking in subscription-based SaaS pricing as the dominant commercial model across European financial institutions.
Pricing Analysis
Margin tightening in mid-market deployments reflects compressed DORA implementation timelines forcing accelerated procurement decisions. Three-tier pricing structure across premium, standard, and economy levels differentiates by integration complexity and regulatory content bundle depth. Cost-down pressure on standard-tier subscriptions accelerates because Polish and Romanian banking sectors negotiate volume discounts for first-mover deployments. Tier 1 financial institutions in Germany and France show lowest price sensitivity, prioritizing pre-certified control mappings over license economics.
Supply Chain Analysis
GDPR Article 32 technical measures and national data residency rules reshape sourcing toward EU-based cloud infrastructure providers. Platform engineering concentrates in Germany, the Netherlands, and Ireland where hyperscaler regions satisfy cross-border data governance requirements. Development pipelines draw from specialized SAML federation expertise pools, regulatory content engineering functions, and ERP integration specialists. Single-source vulnerability sits with concentrated regulatory affairs talent capable of maintaining parallel update streams across 27 member state variations. Distribution runs through direct enterprise sales teams supplemented by systems integrator partnerships for hybrid SCADA deployments.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Governance, Risk and Compliance Platform Market functions as a cost-of-compliance story where DORA's third-party risk register mandates create a barrier-to-entry moat for vendors with pre-certified ECB and EBA control mappings.
For Market Incumbents: Acquire specialized SAML federation engineering teams to address deployment bottlenecks delaying enterprise implementations. Consolidate regulatory content engineering capabilities to defend against Wolters Kluwer's continuous update dominance across EU member state variations. Expand hybrid deployment expertise to capture German manufacturer retrofit cycles for legacy SCADA integration. For New Entrants and Emerging Players: EU AI Act enforcement in France and the Netherlands opens a window for algorithmic audit trail modules targeting banking groups facing first-mover compliance deadlines. Polish and Romanian banking sectors present the most penetrable geography given underpenetrated GRC adoption relative to Western European peers. Lead with cloud-native audit orchestration positioned against fragmented on-premise spreadsheet environments in mid-market institutions. For Investors and Strategic Acquirers: The window for entry favors cloud-native specialists with proven multi-tenant architectures and existing EBA ICT Risk Guidelines certifications. Long-term viability rests on vendor ability to maintain continuous alignment with evolving ECB supervisory expectations through dedicated regulatory affairs functions. Watch for DORA penalty activation dates as inflection indicators accelerating replacement cycles for non-compliant legacy infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Content Engineering Expansion | Continuous update streams across 27 EU member state variations defend Wolters Kluwer's market position. |
| ERP Integration Partnership | SAP SE leverages embedded financial workflow footprint to bundle risk analytics directly into procurement functions. |
| Cloud-Native Audit Orchestration | MetricStream anchors mid-market position as German and French institutions migrate from fragmented on-premise systems. |
| AI Governance Module Certification | Algorithmic audit trail capabilities address EU AI Act technical documentation mandates for high-stakes financial decisions. |
| Hybrid SCADA Deployment Capability | German manufacturer retrofit demand bridges legacy industrial control investments with modern risk dashboards. |
Research Approach
Document review covered EBA ICT Risk Guidelines, ECB supervisory expectations, and DORA implementation timelines, complemented by interviews with chief risk officers, regulatory affairs directors, IT procurement officers, and systems integration specialists. Secondary validation drew from EU official journals, national competent authority guidance documents, and vendor certification disclosures. Bottom-up deployment estimates triangulated against top-down market sizing across service type, technology, and end user dimensions.
Segment-level outputs across the projection horizon reflect modeled adoption curves for compliance management, risk assessment, audit management, and policy management modules. Deployment architecture segmentation captured cloud-based, on-premise, hybrid, and mobile delivery modes. CAGRs derived from regression analysis against regulatory deadline compression and banking sector IT spend patterns, with cross-validation against historical ERP migration cycles and SaaS transition benchmarks in European financial services.
The model assumes a particular technology adoption path; alternative pathways for hybrid SCADA integration would alter the outlook for German manufacturing segments. Forecasts reflect assumptions regarding DORA penalty enforcement consistency and EU AI Act national competent authority coordination. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Risk Management and Compliance
Pre Trade Risk Management Solution Market
Risk Management and Compliance
North America BFSI Biometrics Market
Risk Management and Compliance
United States Governance, Risk and Compliance Platform Market
Risk Management and Compliance
Europe Strategy Consulting Market
Risk Management and Compliance
Global Management Decision Market
Risk Management and Compliance
Europe Sustainable Finance Market
Risk Management and Compliance
Global Energy Trading and Risk Management (ETRM) Market
Risk Management and Compliance
Treasury and Risk Management Market
Risk Management and Compliance
AI in Fraud Management Market
Risk Management and Compliance
Europe BFSI Biometrics Market
Risk Management and Compliance
Certificates Market
Risk Management and Compliance
Southeast Asia Credit and Risk Management Market
Risk Management and Compliance
Anti-Money Laundering (AML) Market
Risk Management and Compliance
Quality Warranty Management Market
Risk Management and Compliance
United States Strategic Consulting Services Market
Risk Management and Compliance
Employee Benefits Strategy and Consulting Market