
 Global Investment Management Software Market | 2026-2036
Global Investment Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Investment Management Software Market Outlook
SEC cybersecurity disclosure rules and the EU Digital Operational Resilience Act is consolidating the cost-of-entry calculus for new software vendors. BlackRock leverages its proprietary Aladdin platform to anchor institutional workflows across asset classes. SS&C Technologies Holdings sustains scale through captive servicing of hedge fund administration and back-office automation. SimCorp specializes in integrated front-to-back investment management systems for complex multi-asset portfolios.
Investment management software encompasses applications that automate portfolio construction, risk analytics, order execution, and regulatory reporting through real-time data feeds and algorithmic engines, typically integrating with market data providers and custodial networks via FIX protocol or API architectures. Cloud-based deployment is displacing legacy on-premise installations as asset managers prioritize elastic compute capacity and faster implementation cycles. Portfolio management solutions dominate current revenue pools, while compliance management modules capture expanding margin as jurisdictional reporting obligations multiply across the United States, Europe, and Asia-Pacific.
The SEC, FCA, and Monetary Authority of Singapore each enforce distinct reporting cadences and data granularity standards that shape product roadmaps and client retention strategies for platform vendors. EBA stress-testing guidelines and IOSCO principles for financial market infrastructures further constrain architecture choices around resilience and audit trails. Stakeholders must weigh jurisdictional coverage breadth against modular deployment flexibility when selecting platforms.
Market Dynamics
Cloud migration is compressing implementation timelines for asset managers while MiFID II and SEC disclosure mandates force parallel infrastructure upgrades. Vendors must now deliver elastic compute capacity alongside embedded compliance engines or risk displacement.
Growth Catalysts
- SEC Cybersecurity Disclosure Rules:Mandated incident reporting and governance disclosures are compelling asset managers to replace legacy risk systems with automated surveillance platforms that embed audit trails natively.
- Wealth Management Digitalization:High-net-worth advisory practices in the United States and Singapore are abandoning spreadsheet-based portfolio construction for API-connected rebalancing engines that sync with custodial networks in real time.
- Alternative Asset Proliferation:Private equity and real asset allocations are surging among institutional investors, driving demand for software modules that handle illiquid position valuation and waterfall distribution calculations.
Market Restraints
- Data Localization Mandates:China's Personal Information Protection Law and Russia's data sovereignty requirements fragment cloud architectures, forcing vendors to maintain redundant infrastructure stacks that inflate operational overhead.
- Concentrated Custodial Dependencies:Three global custodian banks handle clearance for the majority of cross-border institutional flows, creating single-point-of-failure risk that constrains platform resilience guarantees.
- FIX Protocol Legacy Lock-in:Decades of order-routing infrastructure built on Financial Information eXchange standards create path dependency that slows API-native platform adoption among established asset managers.
Strategic Opportunities
- India's Mutual Fund Expansion:SEBI's systematic investment plan regulations and rising retail participation are creating whitespace for cloud-native portfolio administration platforms targeting the country's 40 million-plus SIP accounts.
- ESG Data Integration:EU CSRD disclosure requirements and TCFD alignment pressures are opening demand for software that automates carbon footprint attribution across multi-asset portfolios and private market holdings.
- Embedded Finance Convergence:Banking-as-a-Service APIs are enabling wealth tech startups to embed investment management functionality directly into consumer applications, bypassing traditional advisor channels.
Industry Challenges
- Quantitative Developer Scarcity:Asset managers competing for Python and Rust engineers capable of building low-latency risk engines face wage inflation that compresses platform development budgets.
- Multi-Jurisdictional Certification Lag:Vendors seeking to serve both SEC-registered advisers and FCA-authorized firms must maintain parallel compliance certifications that extend sales cycles by 8-14 months.
- Legacy System Integration Friction:Mainframe-based accounting engines at established custodians resist real-time API connectivity, forcing middleware layers that degrade data freshness and inflate implementation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Investment Management Software Market |
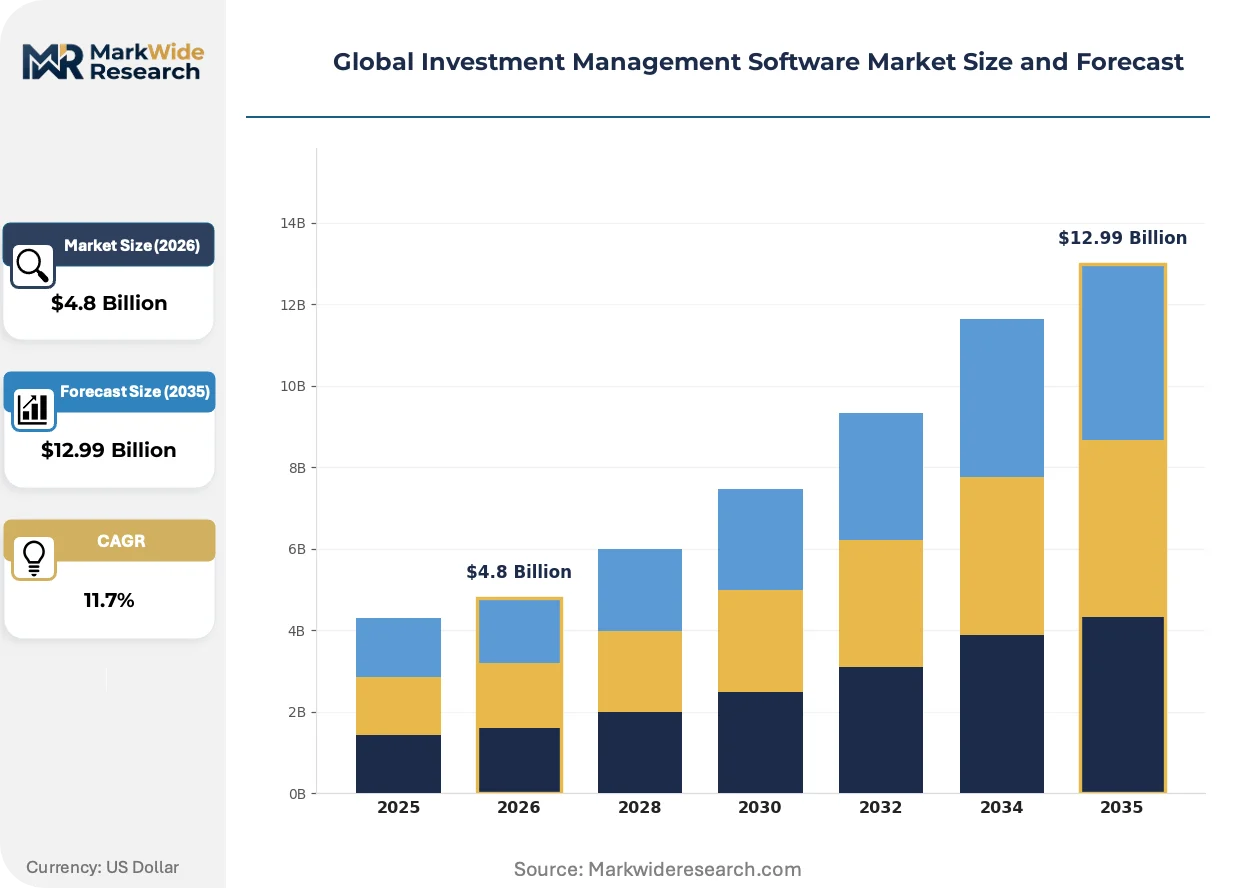
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Managed Service End User: Institutional Investors, Wealth Managers, Hedge Funds, Family Offices Solution: Portfolio Management, Risk Management, Trading System, Compliance Management Application: Asset Allocation, Performance Measurement, Regulatory Reporting, Investment Strategy |
| Companies Covered | BlackRock, SS&C Technologies Holdings, SimCorp, Charles River Development, Broadridge Financial Solutions, Fidelity National Information Services, Temenos, Murex, Envestnet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Investment Management Software Market Strategic Shifts
Generative AI is penetrating investment workflows while regulators accelerate operational resilience mandates. These forces are compressing vendor roadmaps and reshaping how asset managers evaluate platform partnerships.
Large language models are integrating into research synthesis and client communication workflows at hedge funds and family offices. Early adopters are deploying natural language interfaces for portfolio commentary generation and regulatory filing drafting. This capability is integrating previously siloed functions—research, compliance, and marketing—into unified content engines that reduce headcount intensity.
The EU Digital Operational Resilience Act is mandating ICT risk management frameworks, incident reporting protocols, and resilience testing for financial entities. Asset managers must now map third-party software dependencies and conduct penetration testing on vendor platforms. European-domiciled funds are prioritizing vendors with pre-certified DORA compliance modules, creating a bifurcation in procurement criteria between EU and non-EU buyers.
Subscription pricing models are displacing perpetual license structures across the middle-market asset management segment. Vendors are unbundling modules to capture smaller managers who previously deferred platform investments due to upfront capital requirements. This shift is most visible among emerging registered investment advisers in the United States, where monthly SaaS commitments now dominate new vendor relationships.
Global Investment Management Software Market Segmentation
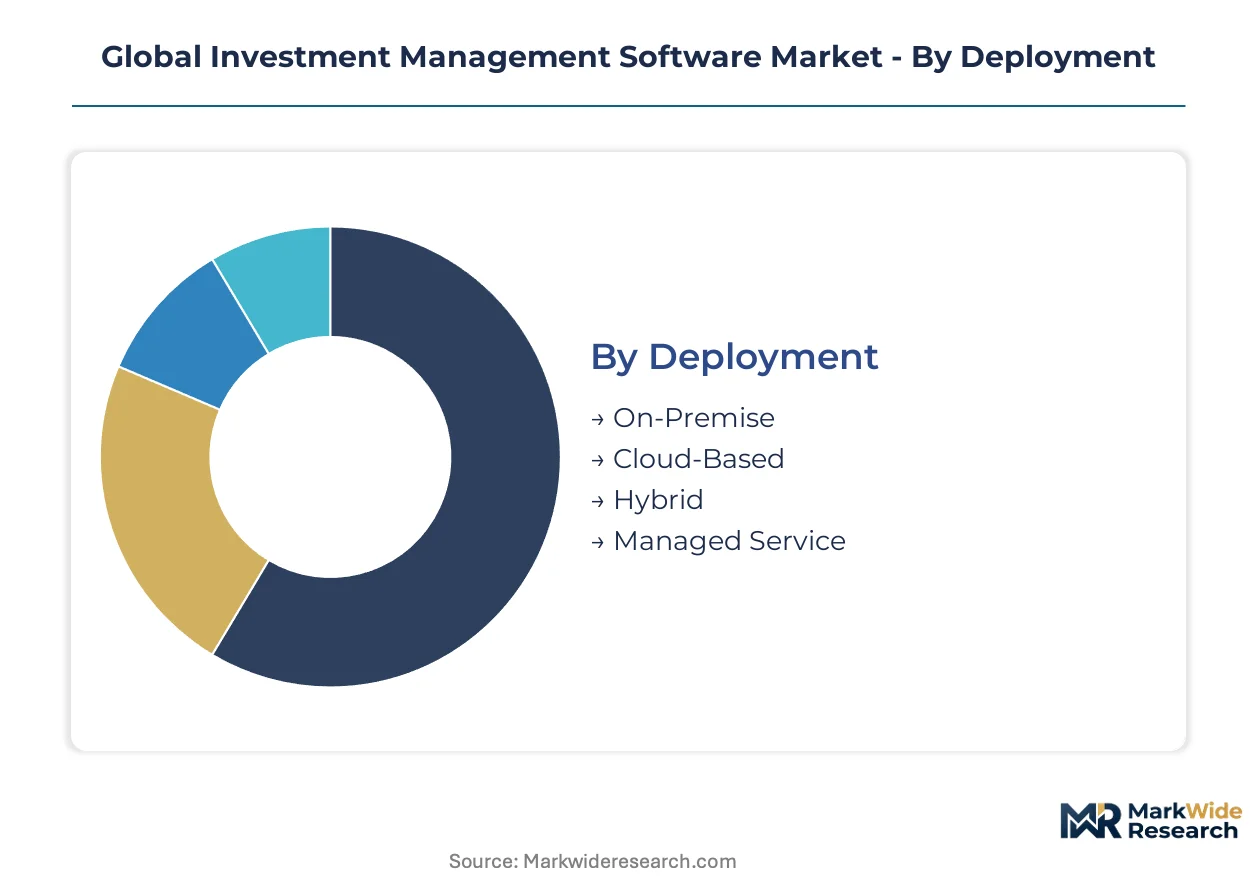
Investment management software vendors architect certification pathways around deployment modes and end-user profiles. Each segment carries distinct regulatory burdens that shape product roadmaps and client acquisition costs.
Deployment:
Cloud-based platforms require SOC 2 Type II and ISO 27001 certifications for institutional acceptance, while on-premise installations demand localized compliance attestations that vary by jurisdiction.
- On-Premise:Legacy infrastructure installed within client data centers maintains dominance among sovereign wealth funds and defense-sector asset managers with classified holdings. United States federal contractors and Saudi sovereign entities mandate air-gapped environments that preclude external connectivity, preserving demand despite higher total cost of ownership.
- Cloud-Based:Multi-tenant SaaS architectures deliver elastic compute for portfolio stress-testing and real-time rebalancing. Singaporean wealth managers and United Kingdom boutique advisors are migrating fastest, drawn by sub-90-day implementation cycles and consumption-based pricing that aligns costs with AUM fluctuations.
- Hybrid:Split architectures isolate sensitive data on-premise while routing analytics to cloud environments. German institutional investors leverage this model to satisfy Bundesbank operational resilience guidelines without sacrificing computational scale.
- Managed Service:Outsourced platform administration bundled with operational staff transfers operational risk to vendors. Japanese trust banks and Australian superannuation funds favor this model to circumvent internal technology hiring constraints.
Cloud-Based sits at the top of the volume ranking, with Managed Service climbing the fastest.
End User:
Regulatory complexity scales with AUM thresholds and cross-border activity, fragmenting vendor sales cycles across client types.
- Institutional Investors:Pension funds and insurance companies with multi-asset mandates require front-to-back integration across public and private markets. United States public sector retirement systems and Dutch pension giants drive demand for modules handling illiquid asset valuation and liability-driven investment workflows.
- Wealth Managers:High-net-worth advisory practices prioritize client-facing dashboards and automated rebalancing across taxable and tax-advantaged accounts. Swiss private banks and United States registered investment advisers are consolidating previously fragmented point solutions into unified platforms.
- Hedge Funds:Quantitative and event-driven strategies demand low-latency execution infrastructure and prime brokerage connectivity. Connecticut-based systematic managers and London macro funds invest heavily in custom risk engine development.
- Family Offices:Single and multi-family structures managing concentrated wealth seek consolidated reporting across direct investments, fund commitments, and philanthropic vehicles. Singapore and Dubai family offices are expanding fastest as regional wealth formation accelerates.
Institutional Investors commands the largest addressable base, while Family Offices expands most quickly.
Solution:
Margin profiles diverge sharply between commoditized portfolio administration and specialized compliance engines with jurisdictional lock-in.
- Portfolio Management:Core modules for position tracking, performance attribution, and rebalancing constitute the revenue foundation. Vendors compete on custody network connectivity, with differentiation narrowing to implementation speed and user interface design.
- Risk Management:Multi-asset risk analytics integrating market, credit, and liquidity exposures command premium pricing. United States asset managers facing SEC stress-testing mandates and European insurers under Solvency II drive replacement cycles.
- Trading System:Order management and execution platforms with smart order routing and transaction cost analysis. FIX protocol integration remains table stakes, while API-native architectures gain traction among systematic strategies.
- Compliance Management:Automated regulatory reporting and surveillance tools capture expanding margin as MiFID II, SEC, and Monetary Authority of Singapore disclosure requirements multiply. Pre-certified modules accelerate procurement decisions.
Portfolio Management generates the highest absolute revenue, with Compliance Management posting the steepest expansion trajectory.
Application:
Functional modules map to distinct workflow stages, with integration depth determining platform stickiness.
- Asset Allocation:Strategic and tactical allocation engines incorporating scenario analysis and liability matching. United States defined benefit pension funds and United Kingdom life insurers dominate demand for liability-driven investment capabilities.
- Performance Measurement:Attribution analysis and benchmark comparison tools with GIPS compliance certification. Institutional consultants and fund-of-funds rely on these modules for client reporting and competitive benchmarking.
- Regulatory Reporting:Automated generation of SEC Form PF, AIFMD Annex IV, and jurisdictional tax filings. European asset managers under CSRD and United States advisers facing Form ADV modernization drive replacement demand.
- Investment Strategy:Quantitative model development and backtesting environments with alternative data integration. Quantitative hedge funds and systematic family offices invest in specialized platforms with Python and R interoperability.
Asset Allocation leads in deployment volume, with Regulatory Reporting gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Quantitative developers cluster in financial hubs from New York to Singapore, anchoring regional software demand. Regulatory divergence across jurisdictions fragments vendor roadmaps. Cloud migration accelerates fastest where compliance mandates force infrastructure replacement.
United States
Asset managers in Boston and New York face SEC cybersecurity disclosure rules mandating automated governance surveillance. The Form ADV modernization program compels registered investment advisers to replace spreadsheet-based reporting. Connecticut hedge funds drive demand for low-latency execution infrastructure.
United Kingdom
Wealth managers in London and Edinburgh accelerate cloud adoption to meet FCA operational resilience deadlines. MiFID II transaction reporting obligations force boutique advisors to abandon legacy on-premise systems. The City of London concentration of family offices fuels demand for consolidated multi-asset reporting platforms.
Germany
Institutional investors in Frankfurt and Munich navigate Bundesbank operational resilience guidelines through hybrid deployment architectures. Solvency II stress-testing requirements drive insurers toward integrated risk analytics modules. Baden-Württemberg pension funds prioritize liability-driven investment workflow automation.
Singapore
Wealth management practices in the central business district migrate to cloud-native platforms under Monetary Authority of Singapore disclosure mandates. Rising family office formation creates demand for consolidated reporting across direct investments and philanthropic vehicles. Retail participation growth drives portfolio administration platform adoption.
India
Asset managers in Mumbai and Bengaluru respond to SEBI systematic investment plan regulations with cloud-native administration tools. The country's 40 million-plus SIP accounts create whitespace for elastic compute solutions. Hyderabad fintech clusters incubate API-connected rebalancing engines targeting retail advisory workflows.
Global Investment Management Software Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across deployment modes and end-user segments. The market exhibits tiered concentration where scale advantages in custody network connectivity separate leaders from challengers. Three strategic archetypes dominate: asset manager-owned platform operators, independent software vendors with captive servicing arms, and banking technology conglomerates with wealth management modules. Competitive moves center on compliance certification pre-positioning and unbundled SaaS pricing to capture emerging registered advisers.
Within the asset manager-owned platform tier, BlackRock exemplifies vertical integration into institutional workflows through proprietary infrastructure anchoring. SS&C Technologies Holdings occupies a position among captive servicing specialists bundling software with operational staff transfer. SimCorp represents focused pure-play positioning in integrated front-to-back systems for complex multi-asset mandates.
| Leading Market Players |
|---|
| BlackRock |
| SS&C Technologies Holdings |
| SimCorp |
| Charles River Development |
| Broadridge Financial Solutions |
| Fidelity National Information Services |
| Temenos |
| Murex |
| Envestnet |
| Others |
Value Chain & Pricing Dynamics
Cloud compute capacity costs cascade through SaaS subscription tiers as vendors balance elastic infrastructure spend against per-seat pricing elasticity for emerging registered investment advisers.
Pricing Analysis
The bundled-vs-unbundled service split now dominates vendor monetization strategies. Subscription SaaS-tiered pricing stratifies across premium, standard, and economy tiers based on custody network connectivity depth and compliance certification grade. Price differentiation hinges on ISO 27001 attestation status and real-time data feed integration. Pricing pressure stems from open-source risk engine alternatives compressing margins at the mid-market. Emerging registered investment advisers exhibit highest price sensitivity, while sovereign wealth funds with air-gapped requirements show lowest elasticity.
Supply Chain Analysis
Real-time market data feeds rest on three concentrated exchanges in the United States, the United Kingdom, and Singapore. Cloud infrastructure draws from hyperscaler regions in Virginia, Frankfurt, and Singapore. FIX protocol middleware and API gateway components anchor legacy integration layers. Single-source vulnerability concentrates around Bloomberg and Refinitiv terminals for reference data. Distribution runs through direct enterprise sales teams and systems integrator partnerships serving regional asset manager clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as regulatory disclosure mandates force recurring infrastructure replacement cycles across asset manager archetypes.
For Market Incumbents: Deepen vertical integration into custody network APIs to lock out modular challengers. Expand SOC 2 Type II certification coverage into emerging Asian wealth hubs before local vendors capture regulatory mindshare. Cloud-native entrants threaten mid-market share; counter with unbundled SaaS pricing to capture emerging registered investment advisers. For New Entrants and Emerging Players: SEC cybersecurity disclosure rules in the United States open a window for automated governance surveillance platforms targeting registered investment advisers with sub-$1 billion AUM. India's SEBI systematic investment plan regulations create whitespace for cloud-native portfolio administration. Embed directly into banking-as-a-service APIs to bypass traditional advisor channel capture. For Investors and Strategic Acquirers: Roll-up economics work for compliance-specialist vendors because jurisdictional certification requirements create sticky recurring revenue with low churn. Five-to-ten-year viability favors platforms with pre-certified DORA modules capturing European procurement bifurcation. Watch for Monetary Authority of Singapore disclosure mandate acceleration as inflection signal for Asia-Pacific platform consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidates fragmented point solutions into unified front-to-back workflows for multi-asset mandates. |
| Acquisition of Specialist Firm | Captures niche compliance modules with jurisdictional lock-in under MiFID II and SEC rules. |
| Geographic Expansion | Positions cloud-native architectures for India's 40 million-plus systematic investment plan accounts. |
| Strategic Partnership | Accelerates custody network connectivity through prime brokerage API alliances. |
| Product Launch | Deploys generative AI interfaces for regulatory filing automation and client commentary generation. |
Study Parameters
Multiple input streams — primary interviews with chief technology officers, compliance officers at asset managers, and integration specialists at custodian banks, plus secondary validation against SEC Form ADV filings, FCA operational resilience disclosures, and Monetary Authority of Singapore regulatory circulars — were reconciled through bottom-up and top-down triangulation.
Historical spend patterns were cross-referenced against panel input from platform vendors to anchor growth assumptions across the analysis window. Segmentation dimensions modeled include deployment architecture, organization AUM tier, vertical specialization, integration complexity, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted replacement cycle timing and cloud migration velocity curves specific to wealth management digitalization.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated generative AI disruption or prolonged quantitative developer scarcity. Forecasts reflect assumptions about regulatory implementation timelines and custody network API standardization. A small set of triggers — DORA enforcement severity, SEBI SIP account growth velocity, and FIX-to-API migration pace — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Asset Management
APAC Mutual Fund Market
Asset Management
Mutual Fund Assets Market
Asset Management
China Mutual Funds Market
Asset Management
Fund Management Software Market
Asset Management
Fixed Income Asset Management Market
Asset Management
Healthcare Asset Management Market
Asset Management
US Asset Management Market
Asset Management
US Healthcare Assets Management Market
Asset Management
Global Remote Asset Management Market
Asset Management
Global AI in Asset Management Market
Asset Management
Japan Asset Management Market
Asset Management
Canada Pension Fund Market
Asset Management
Fund Management Fee Market
Asset Management
US Pension Funds Market
Asset Management
Asset Management System Market
Asset Management
India AMC Industry Market