
 Middle East Financial Consulting Software Market | 2026-2036
Middle East Financial Consulting Software Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Financial Consulting Software Market Analytics
Multi-sourced vendor ecosystems is decoupling legacy dependence on single-stack providers across Middle Eastern financial institutions. Temenos AG sustains dominance in core banking integration layers through its regional implementation partnerships. Path Solutions specializes in Shariah-compliant module architecture, giving it defensible positioning in Islamic finance corridors. Oracle Financial Services Software leverages cloud-native risk engines to compete for tier-one bank mandates in Riyadh and Dubai.
Middle East Financial Consulting Software encompasses modular platforms that aggregate portfolio data, run Monte Carlo simulations, and generate regulatory filings across wealth management, risk assessment, compliance solutions, and performance reporting service types. These systems typically deploy via on-premise, cloud-based, hybrid, or private hosting configurations to serve financial institutions, corporates, SMEs, and high-net-worth individual client types with real-time analytics and automated reporting pipelines. Cloud-based deployment is capturing the fastest expansion as Gulf banks accelerate data center migration timelines under sovereign cloud directives. AI-driven analytics and predictive modeling technology segments command the deepest margin pools due to scarce quantitative talent and proprietary algorithm development costs.
SAMA, the UAE Central Bank, and the Qatar Financial Centre Regulatory Authority enforce cybersecurity frameworks and data residency rules that dictate vendor eligibility and architecture choices across the region. Compliance solutions modules absorb disproportionate R&D investment as institutions preempt audit scrutiny from these regulators. Stakeholders must weigh sovereign cloud mandates against the interoperability limitations of national data localization requirements.
Market Dynamics
Sovereign cloud mandates from SAMA and the UAE Central Bank are forcing Gulf financial institutions to re-architect procurement criteria around data residency compliance, decoupling vendor selection from legacy single-stack dependencies.
Growth Catalysts
- SAMA Cloud Security Directives:Saudi banks must migrate core systems to sovereign-approved data centers by 2026, creating mandatory refresh cycles for portfolio analytics infrastructure.
- Islamic Finance Module Expansion:Shariah-compliant wealth management platforms are capturing institutional mandates across Bahrain and Kuwait as sukuk issuance volumes climb.
- Quantitative Talent Scarcity:AI-driven risk engines are commanding premium positioning as Gulf banks compete for scarce data science expertise.
Market Restraints
- Data Localization Friction:Qatar Financial Centre Regulatory Authority residency rules limit interoperability with cross-border cloud architectures, raising integration costs.
- Implementation Cost Concentration:Tier-one bank mandates in Riyadh and Dubai absorb disproportionate vendor resources, squeezing mid-market service levels.
- Legacy Core Banking Lock-in:Temenos AG integration layers create switching costs that delay modular platform adoption.
Strategic Opportunities
- Oman SME Underpenetration:Corporate treasury automation remains nascent outside Saudi Arabia and UAE, offering first-mover positioning for cloud-native entrants.
- Hybrid Deployment Convergence:Private hosting configurations blending on-premise risk engines with cloud reporting layers are capturing regulatory-sensitive mandates.
- Central Bank Digital Transformation Incentives:UAE regulatory sandboxes are accelerating pilot approvals for predictive compliance modules.
Industry Challenges
- Quantitative Model Validation Bottlenecks:Monte Carlo simulation certification timelines stretch 14-18 months under SAMA audit protocols, compressing product release windows.
- Multi-Vendor Integration Complexity:Decoupled procurement from Path Solutions, Oracle Financial Services Software, and regional specialists requires bespoke API architecture that strains IT budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Financial Consulting Software Market |
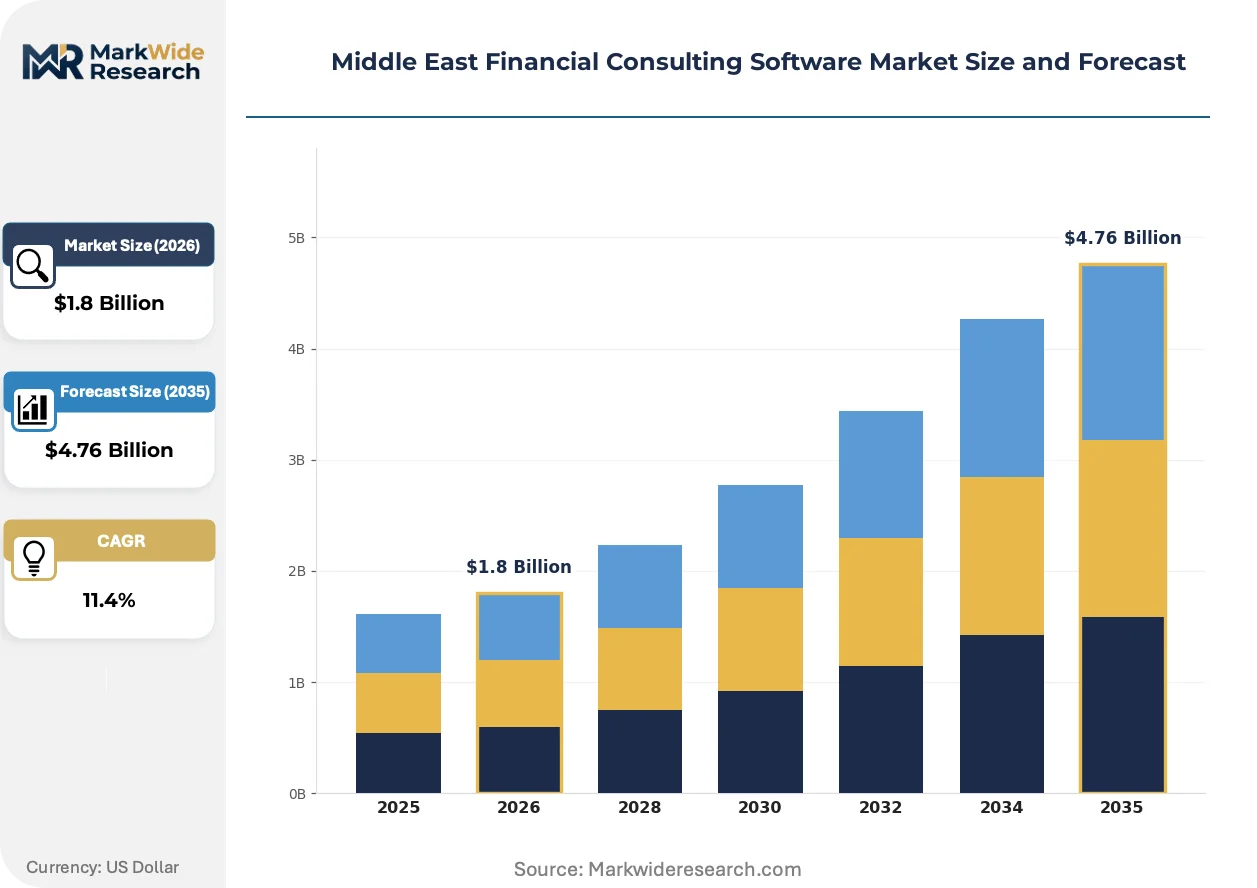
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Wealth Management, Risk Assessment, Compliance Solutions, Performance Reporting Deployment: On-Premise, Cloud-Based, Hybrid, Private Hosting Client Type: Financial Institutions, Corporates, SMEs, High-Net-Worth Individuals Technology: AI-Driven Analytics, Blockchain Solutions, Big Data Platforms, Predictive Modeling |
| Companies Covered | Temenos AG, FIS, Oracle Financial Services Software, SAP SE, Infosys Finacle, Finastra, Fiserv, Inc., Path Solutions, ICS Financial Systems, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Financial Consulting Software Market Evolving Landscape
Generative AI and sovereign cloud architectures are compressing traditional vendor hierarchies across Middle Eastern financial consulting software procurement, creating new competitive entry points for specialized module providers.
Cloud-native risk engines are overtaking on-premise legacy installations in tier-one Saudi and UAE bank RFPs. Chief risk officers at sovereign wealth funds now mandate API-first architecture that enables real-time portfolio rebalancing. This displacement is compressing implementation timelines from 24 months to under 12 months while elevating vendor qualification barriers.
SAMA's cybersecurity framework and the UAE Central Bank's operational resilience requirements are mandating continuous compliance monitoring rather than periodic audit cycles. Financial institutions must deploy automated regulatory filing pipelines that ingest transaction data in real time. Wealth management platforms in Dubai are responding by embedding compliance modules directly into portfolio analytics stacks.
Subscription pricing for AI-driven analytics is displacing perpetual license models across high-net-worth advisory segments. Family offices in Riyadh now demand outcome-based fee structures tied to portfolio performance benchmarks. This shift is most visible in Saudi Arabia, where sovereign wealth fund portfolio analytics modernization is setting procurement standards for private banking units.
Middle East Financial Consulting Software Market Segmentation
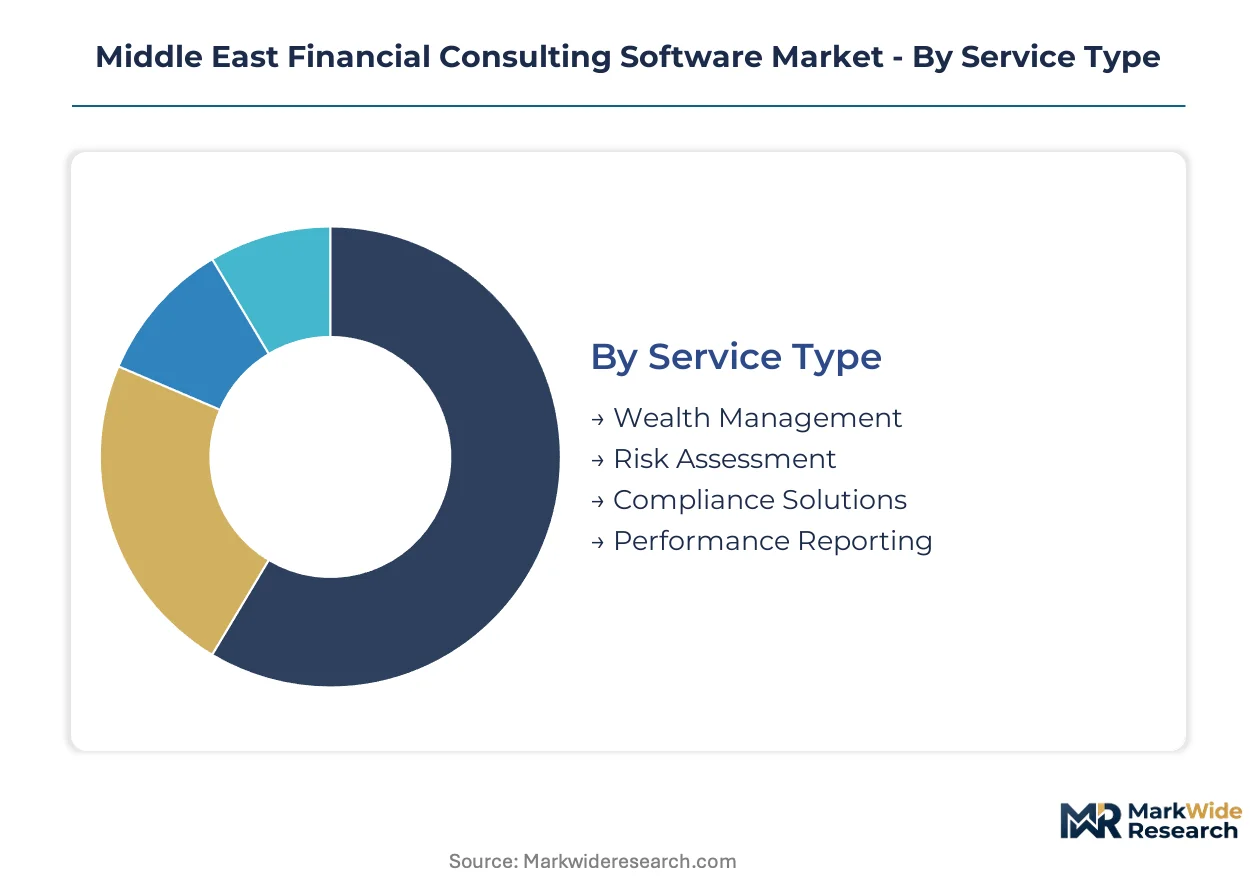
Segmentation across Middle East financial consulting software reveals how procurement patterns diverge between sovereign wealth funds demanding bespoke integration and mid-tier banks accepting standardized modules. Vendor strategy must calibrate across these divides to capture value.
Service Type:
Customization intensity varies sharply across this category, with regulatory-facing modules requiring bespoke configuration while reporting functions standardize more readily.
- Wealth Management:Platforms aggregate portfolio data across asset classes and generate client-facing performance dashboards. Saudi sovereign wealth funds and Dubai family offices are concentrating procurement here, driven by sukuk portfolio expansion and Shariah compliance requirements. SAMA mandates for real-time disclosure are accelerating refresh cycles.
- Risk Assessment:Monte Carlo simulation engines and stress-testing frameworks quantify exposure across credit, market, and operational risks. Tier-one banks in Riyadh and Dubai dominate demand, constrained by 14-18 month model validation timelines under SAMA audit protocols.
- Compliance Solutions:Automated regulatory filing pipelines ingest transaction data for real-time monitoring.
- Performance Reporting:Standardized modules generate periodic client statements and regulatory submissions.
Leading the category by volume: Wealth Management. Growing fastest: Compliance Solutions.
Deployment:
Cost tiering separates this category, with sovereign cloud mandates pushing premium configurations while budget-constrained entrants seek lighter alternatives.
- Cloud-Based:Native architectures enable elastic scaling and continuous compliance monitoring without capital-intensive infrastructure. UAE Central Bank digital transformation directives and SAMA cloud security mandates are concentrating Gulf bank procurement here, though data residency rules limit vendor pools.
- Hybrid:Configurations blend on-premise risk engines with cloud reporting layers for regulatory-sensitive workloads. Tier-one Saudi banks facing Monte Carlo certification bottlenecks are adopting this model to maintain audit trail control while accelerating analytics delivery.
- On-Premise:Legacy installations persist where data sovereignty concerns override cloud migration incentives.
- Private Hosting:Dedicated infrastructure meets Qatar Financial Centre Regulatory Authority residency requirements.
Cloud-Based commands the largest addressable spend. Hybrid deployments are expanding most quickly among tier-one mandates.
Client Type:
Application complexity stratifies this category, from institutional multi-entity consolidation to individual portfolio optimization.
- Financial Institutions:Core banking integration layers require modular platforms that aggregate disparate data sources across trading, lending, and treasury operations. Saudi and UAE banks absorb disproportionate vendor resources, squeezing implementation bandwidth for smaller clients.
- High-Net-Worth Individuals:Family offices in Riyadh and Dubai demand outcome-based fee structures tied to portfolio benchmarks. Subscription pricing for AI-driven analytics is displacing perpetual licenses here, with sovereign wealth fund procurement standards cascading to private banking units.
- Corporates:Treasury automation platforms manage liquidity and foreign exchange exposure.
- SMEs:Standardized cloud modules serve underpenetrated segments outside Saudi Arabia and UAE.
Financial Institutions generate the deepest revenue pools. High-Net-Worth Individuals are climbing fastest as advisory digitization accelerates.
Technology:
Margin concentration separates proprietary algorithm development from commoditized infrastructure layers.
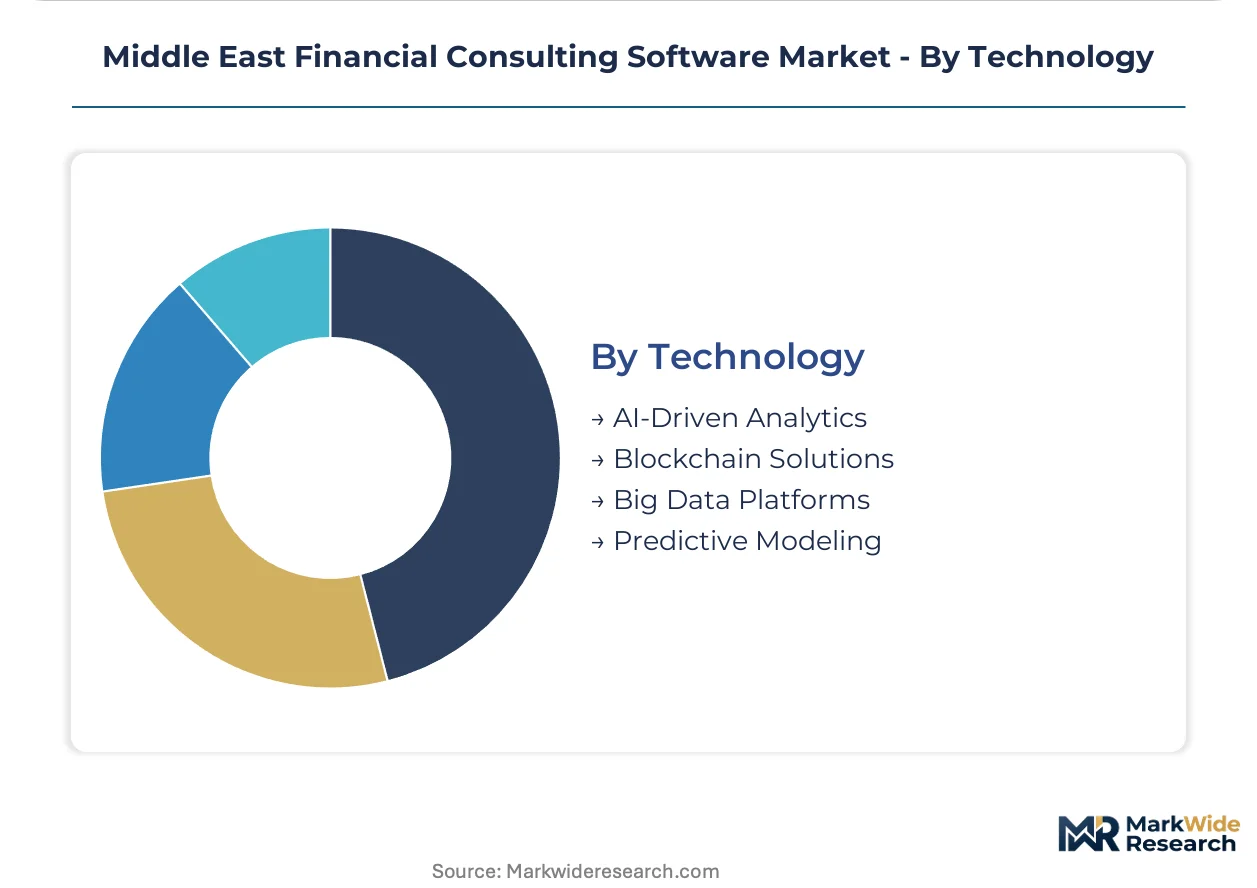
- AI-Driven Analytics:Predictive engines for portfolio rebalancing and risk quantification command premium positioning due to scarce quantitative talent across the Gulf. Chief risk officers at sovereign wealth funds now mandate API-first architecture enabling real-time decision support.
- Predictive Modeling:Statistical frameworks forecast default probabilities and market regime shifts. Gulf banks compete aggressively for data science expertise here, with development costs and certification timelines creating defensive moats for early movers.
- Blockchain Solutions:Distributed ledger applications target sukuk issuance and settlement automation.
- Big Data Platforms:Infrastructure layers ingest and normalize high-velocity transaction streams.
AI-Driven Analytics captures the steepest margin expansion. Predictive Modeling is gaining share fastest as regulatory stress-testing requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Crude oil revenues flowing through Gulf sovereign wealth funds anchor regional procurement capacity for financial consulting software. SAMA and the UAE Central Bank directives are redistributing vendor attention toward Riyadh and Dubai clusters. Data residency requirements are fragmenting cloud architecture decisions across national boundaries.
Saudi Arabia
Sovereign wealth fund portfolio modernization is driving demand for AI-driven analytics and Monte Carlo simulation engines. SAMA cloud security mandates require core system migration to sovereign-approved data centers by 2026. Riyadh-based tier-one banks are absorbing disproportionate vendor implementation resources, compressing service availability for mid-market institutions.
United Arab Emirates
Dubai family offices and private banking units are accelerating subscription pricing adoption for wealth management platforms. The UAE Central Bank's operational resilience requirements mandate continuous compliance monitoring through automated regulatory filing pipelines. Dubai International Financial Centre clusters are embedding compliance modules directly into portfolio analytics stacks.
Qatar
Qatar Financial Centre Regulatory Authority data residency rules are limiting interoperability with cross-border cloud architectures. The country's national financial regulator enforces strict cybersecurity frameworks that dictate vendor eligibility criteria. Doha-based institutions face elevated integration costs when connecting to regional cloud infrastructure.
Kuwait
Shariah-compliant wealth management platform demand is climbing alongside sukuk issuance volume expansion. The country's central bank is aligning with Gulf Cooperation Council regulatory harmonization initiatives for Islamic finance modules. Kuwait City financial institutions are prioritizing modular procurement decoupled from legacy single-stack dependencies.
Oman
Corporate treasury automation remains underpenetrated relative to Saudi Arabia and UAE market saturation. The country's national banking regulator is encouraging digital transformation incentives for SME-focused cloud-native entrants. Muscat and Salalah commercial clusters present first-mover positioning opportunities for standardized deployment configurations.
Middle East Financial Consulting Software Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors seek to decouple from legacy single-stack dependencies. The market exhibits tiered consolidation with global platform providers, regional specialists, and cloud-native challengers occupying distinct competitive bands. Three strategic archetypes have emerged: core banking integration specialists, Shariah-compliant module architects, and cloud-native risk engine developers. M&A activity and sovereign cloud certification partnerships represent the dominant competitive moves as vendors position for SAMA and UAE Central Bank procurement mandates.
Within the core banking integration tier, Temenos AG and Oracle Financial Services Software exemplify established positioning through regional implementation partnerships. Path Solutions occupies a specialized niche as a Shariah-compliant module architect serving Islamic finance corridors. Among diversified technology conglomerates, SAP SE and FIS represent scale-driven entries competing for tier-one bank mandates. These five companies anchor the competitive structure, with Temenos AG and Oracle Financial Services Software sitting within the premium integration layer, Path Solutions representing defensible specialization, and SAP SE alongside FIS exemplifying platform breadth strategies.
| Leading Market Players |
|---|
| Temenos AG |
| FIS |
| Oracle Financial Services Software |
| SAP SE |
| Infosys Finacle |
| Finastra |
| Fiserv, Inc. |
| Path Solutions |
| ICS Financial Systems |
| Others |
Value Network & Pricing Analysis
Cloud infrastructure cost indices cascading through Gulf financial institutions are compressing implementation margins for vendors while elevating sovereign-certified deployment premiums. SAMA data center migration mandates and UAE Central Bank operational resilience requirements are forcing procurement officers to reweight total-cost-of-ownership calculations toward compliance-bundled service tiers.
Pricing Analysis
Service-level bundling separates compliance-certified implementations from unbundled module licensing across Riyadh and Dubai procurement offices. Three-tier pricing structure across premium, standard, and economy levels reflects SAMA audit validation depth, API architecture complexity, and post-deployment support intensity. Price differentiation hinges on sovereign cloud certification status and quantitative model validation timelines. Pricing pressure stems from tier-one bank mandates absorbing disproportionate vendor resources, compressing mid-market service availability. Family offices in Dubai exhibit highest price sensitivity, while Saudi sovereign wealth funds prioritize outcome-based structures tied to portfolio performance benchmarks.
Supply Chain Analysis
Regional distribution centers in Dubai Internet City and Riyadh Digital City anchor hub-and-spoke deployment patterns for cloud-native risk engines. Software development concentrates in India, Ireland, and Singapore, with implementation partnerships localized across Saudi Arabia and the United Arab Emirates. Raw material dependencies include proprietary algorithm libraries, API middleware stacks, and Shariah compliance certification frameworks. Supply chain risk centers on single-source vulnerability for scarce quantitative talent pools. Distribution runs through systems integrator networks certified under SAMA and UAE Central Bank vendor eligibility criteria.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
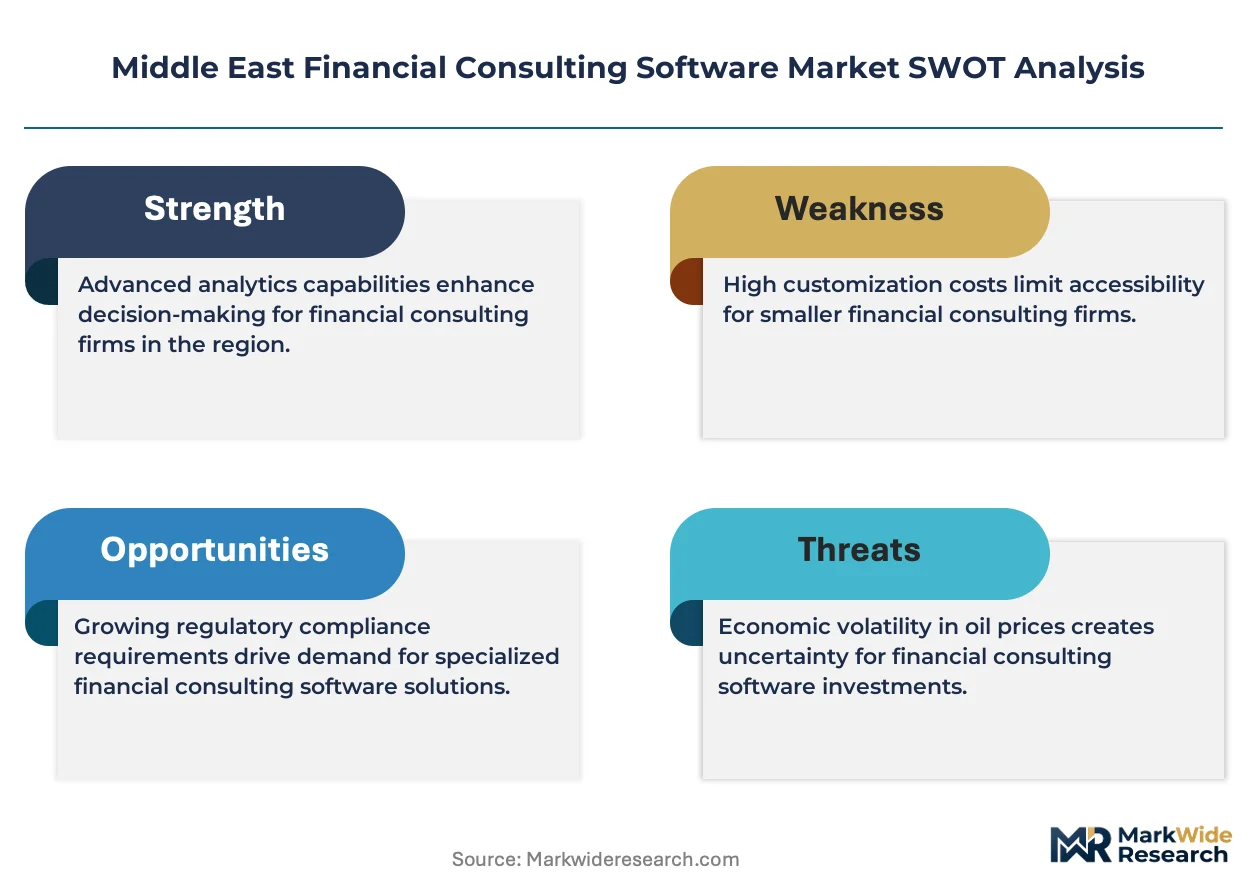
SAMA cloud security directives function as a cost-of-compliance moat, elevating vendor qualification barriers and consolidating procurement around sovereign-certified implementation partners. This regulatory scaffolding protects compliant incumbents while raising capital requirements for market entry.
For Market Incumbents: Deploy sovereign cloud certification partnerships as the primary defensive lever. Temenos AG and Oracle Financial Services Software should deepen regional implementation partnerships to capture mandatory refresh cycles. Path Solutions must accelerate Shariah-compliant module R&D to defend against cloud-native challengers targeting Islamic finance corridors. Threat vectors include API-first entrants displacing legacy integration layers and quantitative talent scarcity compressing development timelines. For New Entrants and Emerging Players: AI-driven predictive compliance modules offer technology-first positioning into underpenetrated Oman SME segments. White-space targets include corporate treasury automation outside Saudi Arabia and UAE saturation zones, plus hybrid deployment configurations for tier-one banks facing Monte Carlo certification bottlenecks. Most penetrable entry point: standardized cloud modules serving Muscat commercial clusters. Go-to-market angle should emphasize rapid implementation timelines under 12 months versus incumbent 24-month cycles. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized module architects with existing SAMA or UAE Central Bank certifications in Riyadh and Dubai corridors. Long-term viability over the analysis window rests on regulatory compliance durability rather than feature differentiation. Acquisition target archetype: cloud-native risk engine developers with sovereign-certified deployment track records. Signal to watch: central bank sandbox pilot approvals accelerating predictive compliance module commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification Partnership | SAMA and UAE Central Bank mandates elevate certified vendors above uncertified competitors in procurement cycles. |
| Shariah-Compliant Module Expansion | Sukuk issuance growth across Bahrain and Kuwait creates defensible positioning in Islamic finance corridors. |
| API-First Architecture Development | Chief risk officers at sovereign wealth funds now mandate real-time portfolio rebalancing capabilities. |
| Quantitative Talent Acquisition | Scarce data science expertise in the Gulf commands premium positioning for AI-driven analytics development. |
| Hybrid Deployment Configuration Launch | Regulatory-sensitive tier-one Saudi banks seek audit trail control combined with cloud analytics acceleration. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with chief technology officers, chief risk officers, IT procurement officers, and systems integration specialists across Riyadh, Dubai, and Doha financial clusters combined with SAMA policy documents, UAE Central Bank circulars, and Gulf Cooperation Council regulatory harmonization frameworks. Bottom-up deployment configuration modeling triangulated against top-down sovereign wealth fund procurement capacity estimates derived from crude revenue inflow projections.
Granularity-level modeling segmented the market across service type, deployment configuration, client tier, and technology stack dimensions. Value projections incorporated organization-size tiering, vertical adoption patterns, and regional regulatory cluster differentiation. CAGRs derived from fitted growth curves calibrated to historical procurement cycle timing and mandated migration deadlines. Forecast inputs included Monte Carlo simulation certification timeline distributions and quantitative talent availability constraints across Gulf labor markets.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated SAMA enforcement timelines or Qatar Financial Centre Regulatory Authority residency rule expansions. Outputs reflect documented assumptions regarding sovereign cloud mandate adherence rates and vendor certification pipeline velocities. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Direct Selling Market
Financial Services
Africa Factoring Services Market
Financial Services
Mobile Notary Public Market
Financial Services
Currency Management Market
Financial Services
White Glove Services Market
Financial Services
Germany Factoring Services Market
Financial Services
Power Bank Sharing Services Market
Financial Services
Global Treasury Software Market
Financial Services
Global Business Management Consulting Service Market
Financial Services
Source to Pay Market
Financial Services
Hyperinflation System Market
Financial Services
Intellectual Property Rights and Royalty Management Market
Financial Services
CFD Trading Affiliate Programs Market
Financial Services
Global Financial Consulting Software Market
Financial Services
North America Management Consulting Services Market
Financial Services
Cash Logistics Market