
 Global Trust and Corporate Service Market | 2026-2036
Global Trust and Corporate Service Market Size, Share, and Industry Trends Forecast 2026-2036
Global Trust and Corporate Service Market Outlook
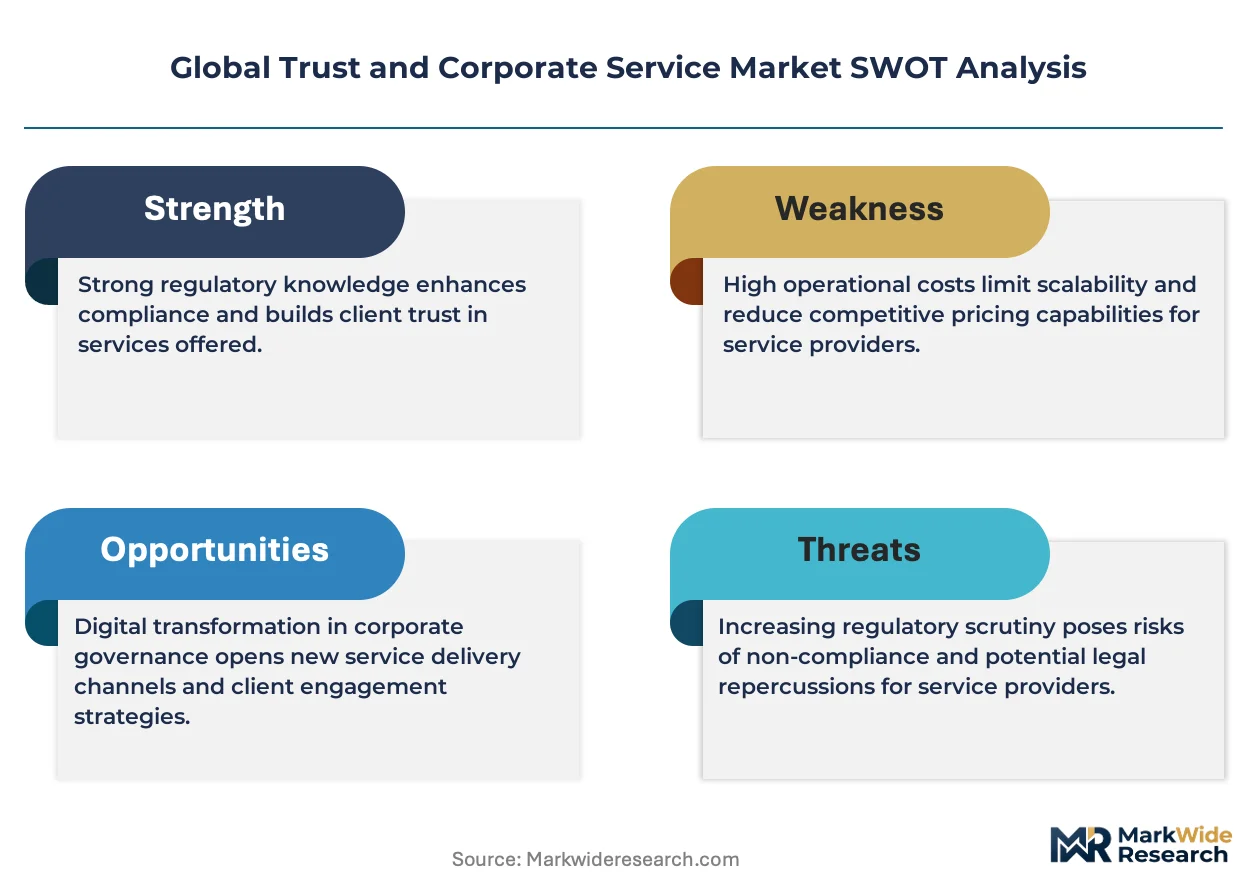
Buyer concentration among family offices and institutional allocators is expanding as wealth consolidates into fewer, larger pools. TMF Group leverages its jurisdictional licensing breadth to capture multi-country mandates from these consolidated buyers. Vistas anchors its position through technology-led service delivery across fund administration and corporate governance. IQ EQ Group Holdings differentiates via specialized capabilities in alternative asset servicing and private capital structures.
Trust and corporate service provision encompasses fiduciary administration, entity incorporation, statutory compliance management, and governance advisory delivered across multiple legal jurisdictions. These functions require specialized expertise in local company law, anti-money laundering protocols, and beneficial ownership registration systems that vary by territory. Trust administration and compliance services represent the most mature revenue pools, while governance advisory is accelerating as boards face intensified ESG disclosure obligations. The end-user base tilts toward corporates and family offices, where complexity of cross-border structuring generates recurring advisory demand.
The SEC, FCA, and Monetary Authority of Singapore each enforce evolving beneficial ownership and fund transparency rules that expand mandatory service scopes for providers. The EU's CSRD and OECD tax transparency frameworks are forcing multinational entities to augment internal governance with external fiduciary support. Stakeholders must monitor regulatory divergence between common law and civil law jurisdictions as structuring decisions increasingly hinge on compliance architecture rather than tax rate differentials alone.
Market Dynamics
Beneficial ownership registries and cross-border tax transparency frameworks are forcing trust and corporate service providers to rebuild compliance infrastructure around real-time data disclosure rather than static entity formation.
Growth Catalysts
- EU Corporate Sustainability Reporting Directive:Mandatory ESG disclosure obligations are expanding the advisory scope for governance and fiduciary service providers across European-domiciled structures.
- Family office consolidation:Wealth concentration into fewer, larger pools is generating multi-jurisdictional mandates requiring integrated trust administration and corporate governance capabilities.
- Fund structuring automation:Digital entity management platforms are compressing setup timelines for special purpose vehicles in Singapore, Switzerland, and the Cayman Islands.
Market Restraints
- Specialized talent scarcity:Qualified trust officers and jurisdictional compliance experts command premium compensation in Singapore and Switzerland, elevating operational cost structures.
- Regulatory fragmentation:Divergent beneficial ownership rules between common law and civil law jurisdictions create compliance architecture complexity that slows cross-border structuring decisions.
- Technology substitution risk:Blockchain-based entity registries and smart contract governance tools threaten traditional fiduciary administration revenue pools.
Strategic Opportunities
- India wealth management penetration:Underdeveloped outsourced governance infrastructure among Indian family offices presents first-mover expansion potential for established providers.
- Climate disclosure integration:The EU Green Deal and emerging carbon reporting mandates create advisory white space at the intersection of ESG compliance and fiduciary structuring.
- API-enabled service delivery:Open banking and regulatory data feed integration allow real-time compliance monitoring as a premium service tier.
Industry Challenges
- Beneficial ownership verification:Source of wealth documentation and politically exposed person screening requirements are extending client onboarding timelines and elevating liability exposure.
- Legacy system interoperability:Trust administration platforms built on jurisdiction-specific architectures resist seamless integration with global entity management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Trust and Corporate Service Market |
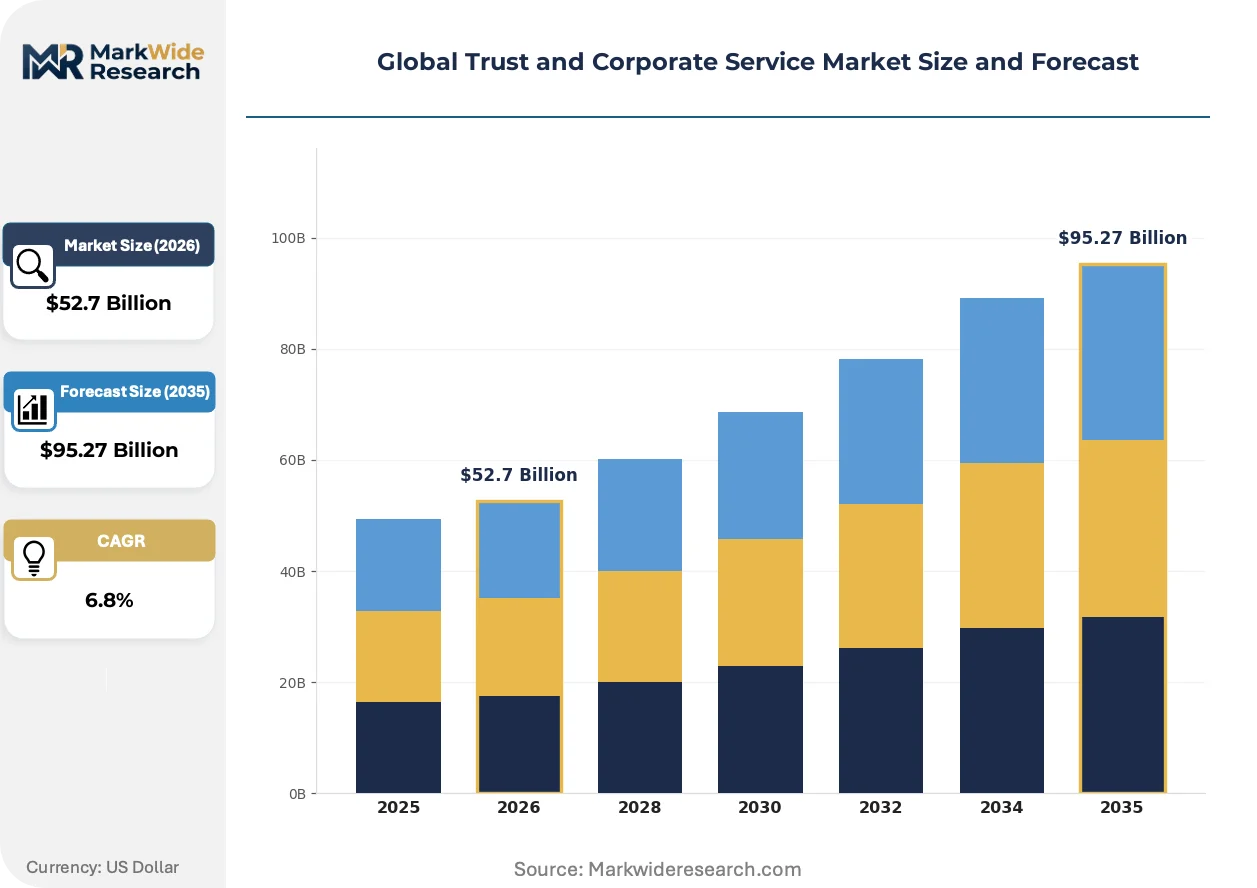
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $95.27 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Trust Administration, Company Formation, Compliance Services, Governance Advisory End User: Corporates, High Net Worth Individuals, Family Offices, Institutions Offering: Consulting, Asset Management, Marketing Solutions, Tax Services Distribution Channel: Direct Sales, Online Platforms, Third-Party Providers, Brokers |
| Companies Covered | Tricor Group, Apex Group Ltd., TMF Group, IQ EQ Group Holdings, Vistra, Wilmington Trust, JTC plc, Ocorian, Intertrust Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Trust and Corporate Service Market Strategic Shifts
Service delivery models are pivoting from episodic entity setup toward continuous compliance monitoring, driven by real-time regulatory data requirements and compressed disclosure timelines.
Entity management software is modularizing trust administration workflows into discrete compliance, governance, and reporting components. Family offices and institutional allocators in Singapore and Switzerland are adopting these platforms to consolidate multi-jurisdictional structures. This architecture is modularizing vendor relationships, allowing buyers to unbundle fiduciary services across specialized providers rather than relying on single-source relationships.
The OECD's Common Reporting Standard and country-by-country tax transparency frameworks are elevating data governance requirements for multinational entities. Service providers must now maintain audit-ready beneficial ownership records across multiple regulatory regimes. Fund administrators with exposure to EU-domiciled vehicles face the most acute compliance compression as CSRD and tax transparency obligations overlap.
Subscription-based fiduciary advisory is displacing traditional transaction-priced entity formation. Family offices in the Cayman Islands and Switzerland are contracting for ongoing governance oversight rather than per-structure setup fees. This shift is most visible among ultra-high-net-worth allocators managing more than ten cross-border entities.
Global Trust and Corporate Service Market Segmentation
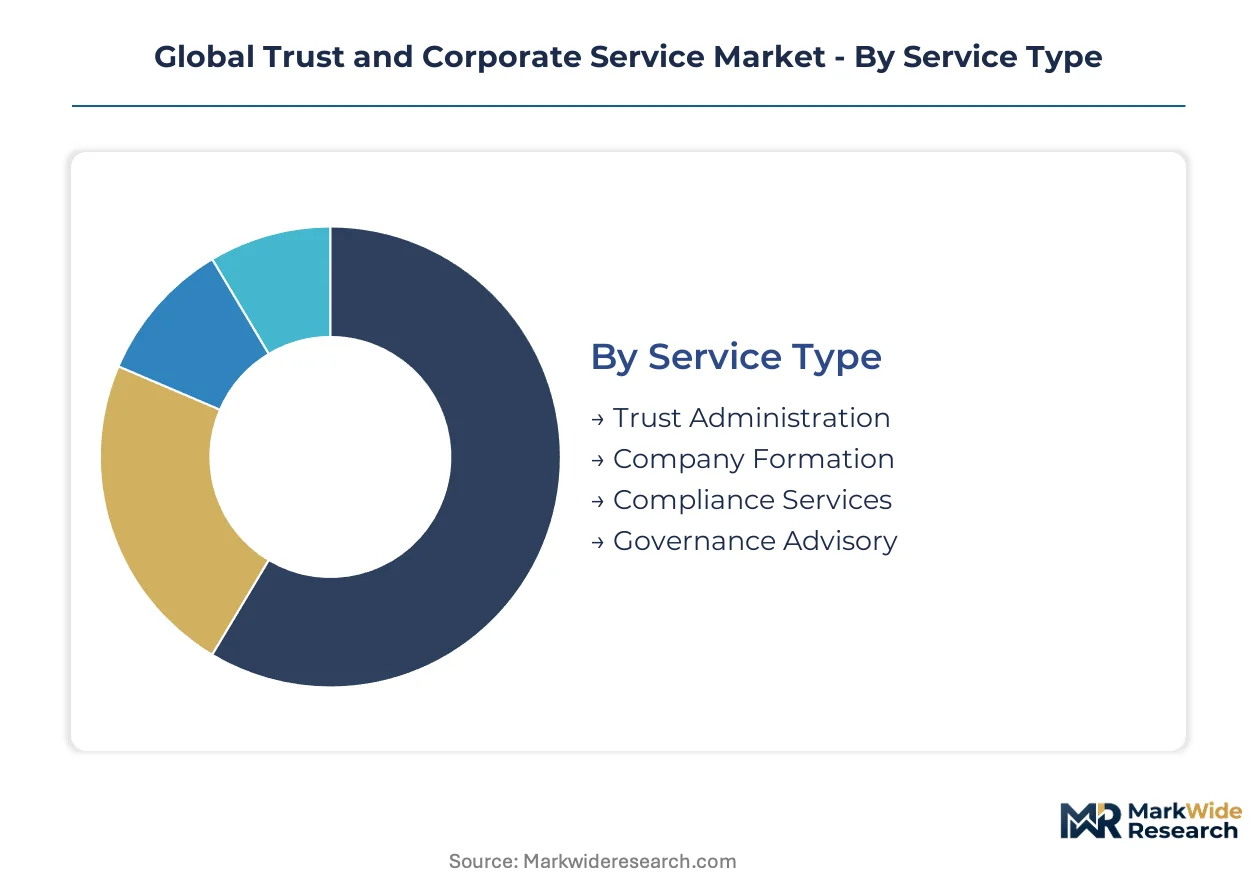
Segmentation in trust and corporate services reveals how buyer sophistication and regulatory exposure drive purchasing patterns. Providers must align service architecture with distinct risk profiles across fiduciary administration, entity management, and governance advisory functions.
Service Type:
Buyer differentiation hinges on recurring compliance burden versus episodic structuring needs.
- Trust Administration:Fiduciary oversight of settlor intentions, beneficiary distributions, and trustee liability management across multi-generational wealth structures. Demand concentrates among family offices in Switzerland and Singapore, where dynastic wealth preservation mandates drive long-term trustee relationships and succession planning complexity.
- Compliance Services:Statutory filing, beneficial ownership registration, and anti-money laundering monitoring across jurisdictional registries. European-domiciled entities facing CSRD and OECD transparency frameworks generate the steepest advisory demand as real-time disclosure obligations compress reporting timelines.
- Company Formation:Entity incorporation, registered office provision, and constitutional document drafting for special purpose vehicles.
- Governance Advisory:Board effectiveness review, ESG disclosure architecture, and director liability mitigation.
Trust Administration leads volumes today; Compliance Services is gaining share fastest.
End User:
Procurement authority varies by decision-making concentration and internal capability depth.
- Family Offices:Multi-jurisdictional entity clusters requiring integrated fiduciary administration and cross-border tax coordination. Singapore-based single-family offices with assets exceeding $500 million are outsourcing governance functions previously managed in-house as regulatory complexity outstrips internal expertise.
- Corporates:Subsidiary management, intercompany structuring, and transfer pricing documentation for multinational enterprises. US and EU headquartered multinationals facing simultaneous SEC, FCA, and CSRD obligations drive demand for consolidated entity management platforms.
- High Net Worth Individuals:Personal wealth structuring through trusts, foundations, and holding companies.
- Institutions:Pension funds, endowments, and sovereign wealth vehicles requiring independent director services and investment vehicle governance.
Corporates anchor current revenue; Family Offices are expanding most quickly.
Offering:
Margin profiles diverge sharply between advisory-driven and execution-oriented service lines.
- Tax Services:Cross-border structuring, substance planning, and treaty access optimization for multinational entities. Cayman Islands and Luxembourg domiciled funds require ongoing tax compliance as OECD pillar two implementation tightens effective rate planning.
- Consulting:Regulatory interpretation, restructuring advisory, and governance framework design for complex ownership structures.
- Asset Management:Investment oversight, custody coordination, and performance reporting for trust-held portfolios.
- Marketing Solutions:Investor relations, fund documentation, and subscription processing for capital-raising vehicles.
Tax Services dominates current margins; Consulting is climbing the fastest.
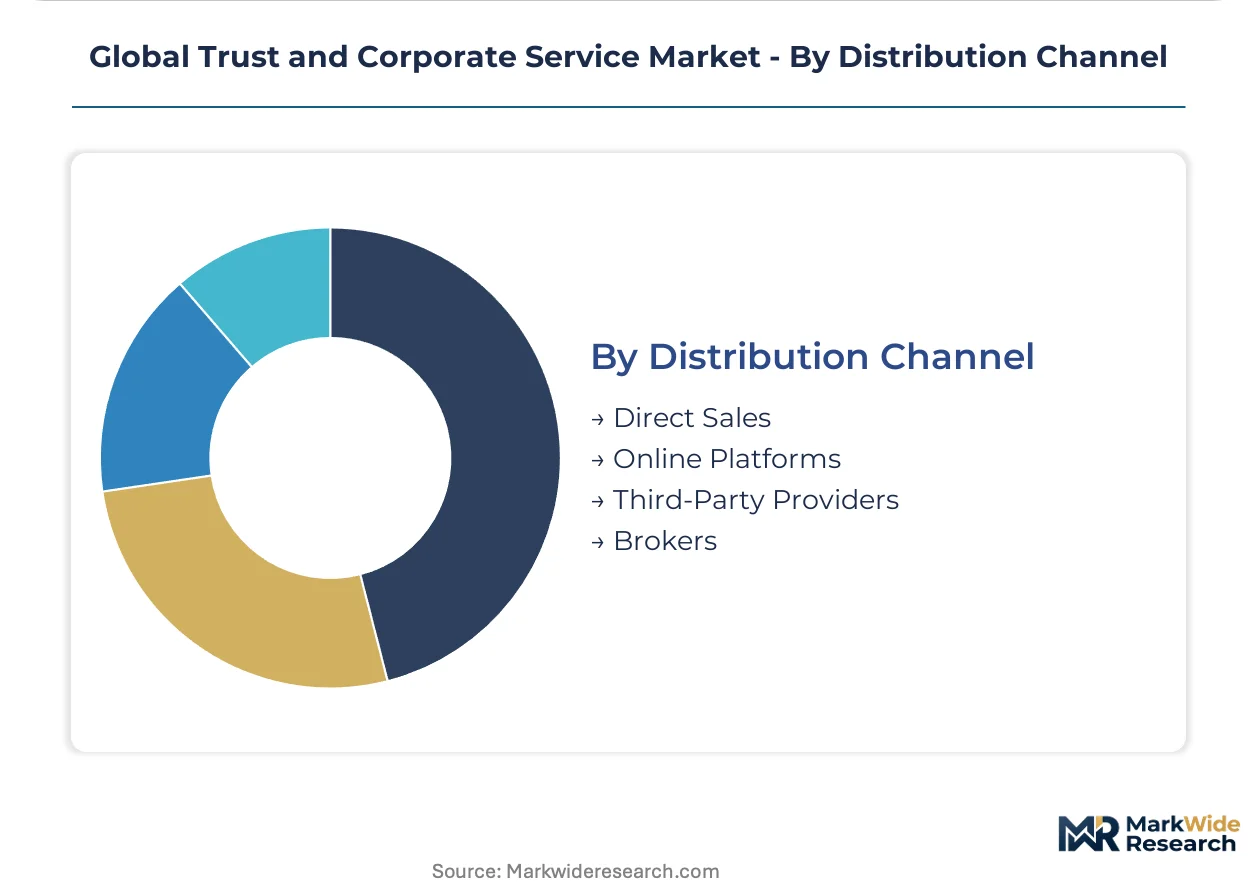
Distribution Channel:
Channel selection reflects buyer sophistication, relationship density, and urgency of jurisdictional access.
- Direct Sales:Dedicated relationship managers serving ultra-high-net-worth allocators and large family offices with bespoke fiduciary mandates. Swiss and Singapore providers invest heavily in direct coverage teams as consolidated wealth pools demand white-glove governance oversight.
- Third-Party Providers:Law firms, accounting networks, and private banks referring clients to specialized trust administrators. UK and US professional service networks generate substantial referral volume for Cayman Islands entity formation and trustee appointments.
- Online Platforms:Digital entity management portals for standardized company formation and compliance monitoring.
- Brokers:Intermediary arrangements for cross-selling fiduciary services alongside insurance or investment products.
Direct Sales captures premium pricing today; Third-Party Providers are expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore and Switzerland attract comparable volumes of special purpose vehicle formation, yet divergent regulatory philosophies shape service provider strategies in each jurisdiction. The United States maintains the deepest pool of institutional capital requiring fiduciary infrastructure. Demand concentrates where wealth preservation motives intersect with stable legal frameworks.
Singapore
Single-family offices exceeding $500 million in assets drive outsourced governance mandates as the Monetary Authority of Singapore tightens beneficial ownership disclosure timelines. The city-state's Variable Capital Company framework accelerates fund structuring for private capital vehicles. Marina Bay and Raffles Place host concentrated provider clusters serving Asia-Pacific wealth migration.
Switzerland
Dynastic wealth preservation across multi-generational structures sustains trustee relationship longevity in Zurich and Geneva. Swiss FINMA enforcement of anti-money laundering protocols elevates documentation burdens for family office clients. The Zug canton attracts crypto-asset fiduciaries seeking regulatory clarity for digital wealth structures.
Cayman Islands
Exempted company formation for private equity and hedge fund vehicles generates recurring compliance revenue pools. The jurisdiction's beneficial ownership registry alignment with OECD standards compresses setup timelines for cross-border investment structures. George Town maintains dominant service provider density across fund administration functions.
United States
SEC disclosure mandates for institutional allocators expand fiduciary advisory scopes beyond traditional trust administration. Delaware statutory trust structures attract domestic wealth preservation demand alongside cross-border Latin American capital flows. Wilmington and New York City anchor competing provider ecosystems serving distinct client risk profiles.
United Kingdom
FCA beneficial ownership rules and overlapping EU CSRD obligations for retained European structures elevate compliance complexity for multinational entities. London's legal and fiduciary service clusters adapt to post-Brexit regulatory divergence from EU frameworks. The City and Mayfair retain concentration of white-glove family office governance mandates.
Global Trust and Corporate Service Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across fiduciary administration and corporate governance functions. Market structure tilts toward consolidation as jurisdictional licensing breadth becomes a decisive bidding criterion for multi-country mandates. Three archetypes dominate: full-service administrators spanning 80+ jurisdictions, technology-enabled fund specialists, and boutique trustees serving single-asset-class niches. Competitive intensity manifests through M&A-driven geographic expansion and API-enabled service modularization that unbundles traditional bundled offerings.
Within the full-service administrator tier, TMF Group and Vistra occupy positions defined by jurisdictional coverage density rather than technology differentiation. IQ EQ Group Holdings and Apex Group Ltd. exemplify the alternative asset specialization vector, anchoring their market presence through private capital structuring expertise. JTC plc represents the mid-market consolidation play, sitting within an acquisition-driven expansion archetype that targets jurisdictional gap-filling. These four names illustrate how provider strategy fragments across coverage breadth, asset class focus, and scale-driven M&A execution.
| Leading Market Players |
|---|
| Tricor Group |
| Apex Group Ltd. |
| TMF Group |
| IQ EQ Group Holdings |
| Vistra |
| Wilmington Trust |
| JTC plc |
| Ocorian |
| Intertrust Group |
| Others |
Value Chain & Pricing Dynamics
Family offices exceeding $500 million in assets anchor pricing power for trust and corporate service providers, consolidating procurement around subscription-based fiduciary advisory rather than transactional entity formation fees. This buyer concentration enables premium pricing for integrated multi-jurisdictional mandates while compressing margins for standardized compliance services.
Pricing Analysis
Capacity additions in Singapore and Switzerland are reshaping price floors for trust administration as licensed providers expand jurisdictional coverage to capture consolidated family office mandates. Three-tier pricing structure across premium, standard, and economy levels differentiates by regulatory complexity and beneficiary distribution frequency. Cost compression in standardized compliance services is intensifying because digital entity management platforms automate statutory filing workflows. Single-family offices with internal governance capabilities exhibit the highest price sensitivity, while dynastic wealth structures with succession planning complexity accept premium trustee retainers.
Supply Chain Analysis
Refurbishment of legacy trust administration platforms and migration to cloud-based entity management systems constitute reverse-logistics flows as providers modernize jurisdiction-specific architectures. Supply concentrates in Singapore, Switzerland, and the Cayman Islands for fiduciary licensing and regulatory infrastructure. Raw material dependencies include jurisdictional legal expertise, anti-money laundering compliance technology, and beneficial ownership registry access. Single-source vulnerability to regulatory divergence between common law and civil law jurisdictions elevates operational risk. Distribution runs through direct relationship manager networks for premium mandates and third-party professional service referrals for standardized entity formation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where regulatory divergence between Singapore's Variable Capital Company framework and EU CSRD obligations creates cost differentials for cross-border structuring decisions.
For Market Incumbents: Anchor jurisdictional licensing breadth as the decisive bidding criterion for multi-country mandates from consolidated family offices. Defensive moves include API-enabled service modularization that unbundles traditional bundled offerings and acquisition-driven expansion to fill geographic gaps. Blockchain-based entity registries threaten traditional fiduciary administration revenue pools; vertical integration into regulatory technology platforms mitigates substitution risk. For New Entrants and Emerging Players: Digital-channel routes through online entity management portals offer the lowest customer acquisition cost for standardized company formation in underpenetrated segments. White-space targets include Indian family offices lacking outsourced governance infrastructure and climate disclosure integration at the intersection of ESG compliance and fiduciary structuring. The most penetrable segment is mid-market single-family offices with assets between $100 million and $500 million seeking subscription-based governance oversight. For Investors and Strategic Acquirers: Private equity firms specializing in professional services consolidation are the most active acquirer in this space, targeting mid-market trustees with jurisdictional gap-filling potential. Long-term viability hinges on providers' ability to pivot from episodic entity setup toward continuous compliance monitoring as regulatory disclosure timelines compress. Acquisition target archetype: technology-enabled fund administrators with alternative asset specialization and established API infrastructure. The signal to watch is regulatory harmonization versus divergence between OECD tax transparency frameworks and jurisdiction-specific beneficial ownership rules.| Strategic Initiative | Industry Significance |
|---|---|
| Jurisdictional Licensing Expansion | Monetary Authority of Singapore and Swiss FINMA approvals enable multi-country mandate capture from consolidated family offices. |
| Regulatory Technology Platform Integration | Real-time compliance monitoring as a premium service tier leverages open banking and regulatory data feed integration. |
| Climate Disclosure Advisory Capability | EU Green Deal and emerging carbon reporting mandates create advisory white space for ESG-integrated fiduciary structuring. |
| API-Enabled Service Modularization | Unbundling traditional bundled offerings allows buyers to distribute fiduciary services across specialized providers. |
| India Market Entry | Underdeveloped outsourced governance infrastructure among Indian family offices presents first-mover expansion potential. |
Study Parameters
Coverage spans Singapore, Switzerland, the Cayman Islands, the United States, and the United Kingdom, with primary inputs from each jurisdiction combining interviews with trust officers, family office governance heads, regulatory compliance directors, and fund administration executives with secondary validation. Secondary sources include SEC filings, FCA regulatory notices, Monetary Authority of Singapore circulars, OECD tax transparency framework documentation, and jurisdictional beneficial ownership registry disclosures. Bottom-up service line revenue triangulation against top-down market sizing ensures consistency across the analysis window.
Rate-of-change decomposition separates volume effects from price mix shifts across trust administration, compliance services, company formation, and governance advisory segments. Segmentation dimensions modeled include service type, end user archetype, offering category, and distribution channel complexity. CAGRs derive from regression analysis of historical licensing data and regulatory mandate expansion trajectories. Forecast inputs incorporate EU CSRD implementation timelines and OECD Pillar Two effective rate planning impacts on fund structuring demand.
The model assumes a particular technology adoption path; alternative pathways for blockchain-based entity registries and smart contract governance tools would alter the outlook. Forecasts reflect assumptions about regulatory harmonization versus continued divergence between common law and civil law jurisdictions. Practitioners should monitor beneficial ownership registry alignment with OECD standards and family office consolidation trajectories for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
UK Islamic Finance Market
Financial Services
Online Investment Platform Market
Financial Services
Germany E-Brokerage Market
Financial Services
Spain E-Brokerage Market
Financial Services
Southeast Asia E-Invoicing Market
Financial Services
Europe Factoring Services Market
Financial Services
Outsource Debt Collection Services Market
Financial Services
Global Alternative Data Market
Financial Services
Global Management Consulting Services Market
Financial Services
North America Financial Advisory Services Market
Financial Services
Islamic Finance Market
Financial Services
Intellectual Property Valuation Market
Financial Services
Back-Office Outsourcing in Financial Services Market
Financial Services
United Kingdom E-Brokerage Market
Financial Services
Intellectual Property Rights and Royalty Management Market
Financial Services
North America B2B Legal Services Market