
 Virtual Account Management Software Market | 2026-2036
Virtual Account Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Virtual Account Management Software Market Analysis
The virtual account management software market is restructuring around a sharp split between premium platforms with embedded AI-driven cash forecasting and commodity offerings limited to basic ledger virtualization. Oracle Corporation leverages its database heritage to anchor enterprise-grade deployments with real-time liquidity analytics across multicurrency hierarchies. SAP Fioneer competes through deep ERP integration that eliminates reconciliation latency between treasury and procurement systems. Intellect Design Arena specializes in modular architectures that let mid-tier banks deploy virtual account capabilities without core banking replacement.
Virtual account management software is a treasury technology platform that generates unlimited sub-ledgers linked to a single physical bank account, enabling granular cash position tracking through API-connected balance reporting and automated transaction tagging. Its primary commercial purpose is to eliminate physical account proliferation while preserving legal entity separation for regulatory and operational reporting. Cloud-based deployment leads adoption among corporations seeking rapid rollout without data center capital expenditure, while SaaS models capture the fastest expansion as regional banks white-label virtual account infrastructure from platform vendors. The service type dimension shows account reconciliation commanding the deepest margin pools due to its complexity and regulatory audit value, whereas user management has commoditized around standardized role-based access frameworks.
The EU's Digital Operational Resilience Act and GDPR impose strict data residency and incident reporting requirements that shape European vendor product roadmaps and customer procurement criteria. The US OCC and Federal Reserve guidance on operational risk management similarly influences how American banks evaluate third-party treasury platform providers. Stakeholders must monitor how ISO 20022 migration timelines reshape the interoperability requirements that virtual account platforms must satisfy to maintain bank connectivity.
Market Dynamics
Cloud migration mandates under the EU's Digital Operational Resilience Act are forcing wholesale replacement of legacy on-premises treasury infrastructure, compressing vendor selection cycles and elevating data residency requirements to primary procurement criteria.
Growth Catalysts
- API standardization:ISO 20022 migration timelines are accelerating bank-technology platform interoperability, reducing integration friction for corporate treasuries adopting virtual account hierarchies.
- Germany's regulatory environment:Bundesbank reporting standards and dense corporate banking infrastructure create favorable deployment conditions for virtual account structures at multinational manufacturers.
- Automated reconciliation:Machine learning-powered transaction tagging eliminates manual matching processes, driving adoption among treasury departments managing multicurrency operations.
Market Restraints
- Core banking replacement risk:Mid-tier banks face capital-intensive infrastructure decisions when virtual account deployment requires parallel core system modernization.
- Data residency compliance costs:GDPR and EU Digital Operational Resilience Act mandates impose strict localization requirements that inflate cloud deployment expenditures for cross-border operators.
- Talent scarcity in treasury technology:Shortage of professionals combining cash management expertise with API architecture skills constrains implementation velocity at regional banks.
Strategic Opportunities
- White-label SaaS models:Regional banks can deploy virtual account capabilities without proprietary development by licensing modular infrastructure from specialized platform vendors.
- AI-driven cash forecasting integration:Convergence of predictive analytics engines with virtual account ledgers creates premium pricing tiers for enterprise-grade deployments.
- India's digital payment infrastructure:RBI's real-time gross settlement expansion and corporate treasury modernization initiatives open underpenetrated demand for virtual account solutions.
Industry Challenges
- Legacy ERP integration complexity:Treasury departments face extended reconciliation latency when virtual account platforms lack native connectivity to established procurement systems.
- Multicurrency hierarchy standardization:Absence of unified protocols for cross-border virtual account structures forces custom development at each implementation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Virtual Account Management Software Market |
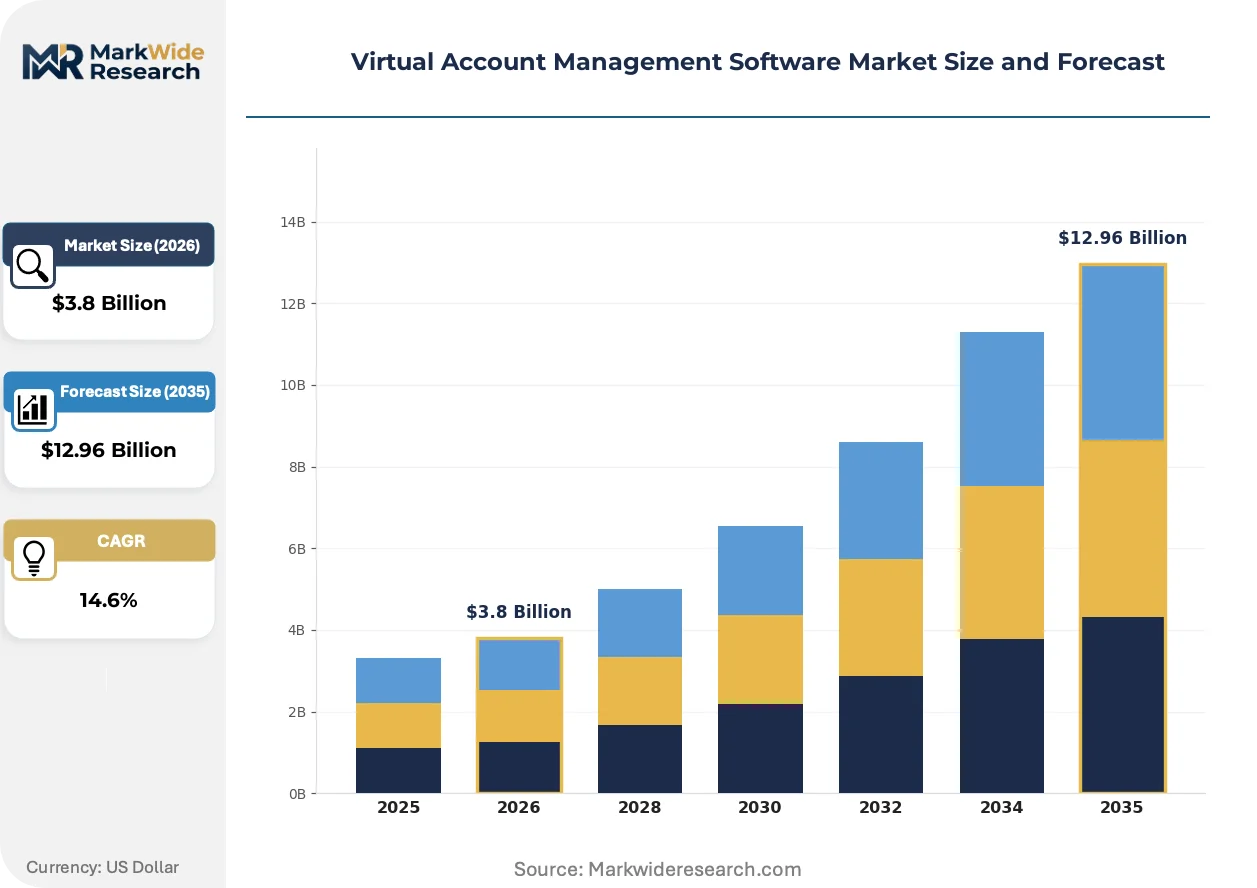
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, SaaS Customer Type: SMEs, Large Enterprises, Startups, Corporations Service Type: Account Reconciliation, User Management, Reporting, Analytics Industry Vertical: Banking, Retail, Telecommunications, Education |
| Companies Covered | Infosys Finacle, Montran, Oracle Corporation, Epicor Software Corporation, Tietoevry Banking, SAP Fioneer, Intellect Design Arena, Infor, Finastra, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Virtual Account Management Software Market Emerging Trajectories
Virtual account management software is restructuring around embedded intelligence and regulatory-driven architecture decisions, with vendor differentiation increasingly tied to forecasting depth rather than ledger virtualization alone.
Real-time liquidity analytics engines are converging with virtual account platforms to enable predictive cash positioning across dispersed legal entities. Multinational manufacturers operating complex supply chains are adopting these integrated stacks to compress working capital cycles. This convergence is displacing standalone treasury workstations that lack native AI capabilities.
The EU's Digital Operational Resilience Act imposes strict incident reporting and third-party risk management obligations on financial infrastructure providers. Vendors must now demonstrate continuous operational resilience certification to maintain bank partnerships. German corporate banks are responding by pre-qualifying only cloud-native platforms with embedded compliance tooling.
Subscription-based procurement models are displacing perpetual license structures as regional banks seek to minimize capital commitment to treasury infrastructure. Channel relationships with system integrators are shifting toward revenue-sharing arrangements that align implementation success with vendor economics. This transformation is most visible in the United Kingdom's mid-tier banking segment.
Virtual Account Management Software Market Segmentation
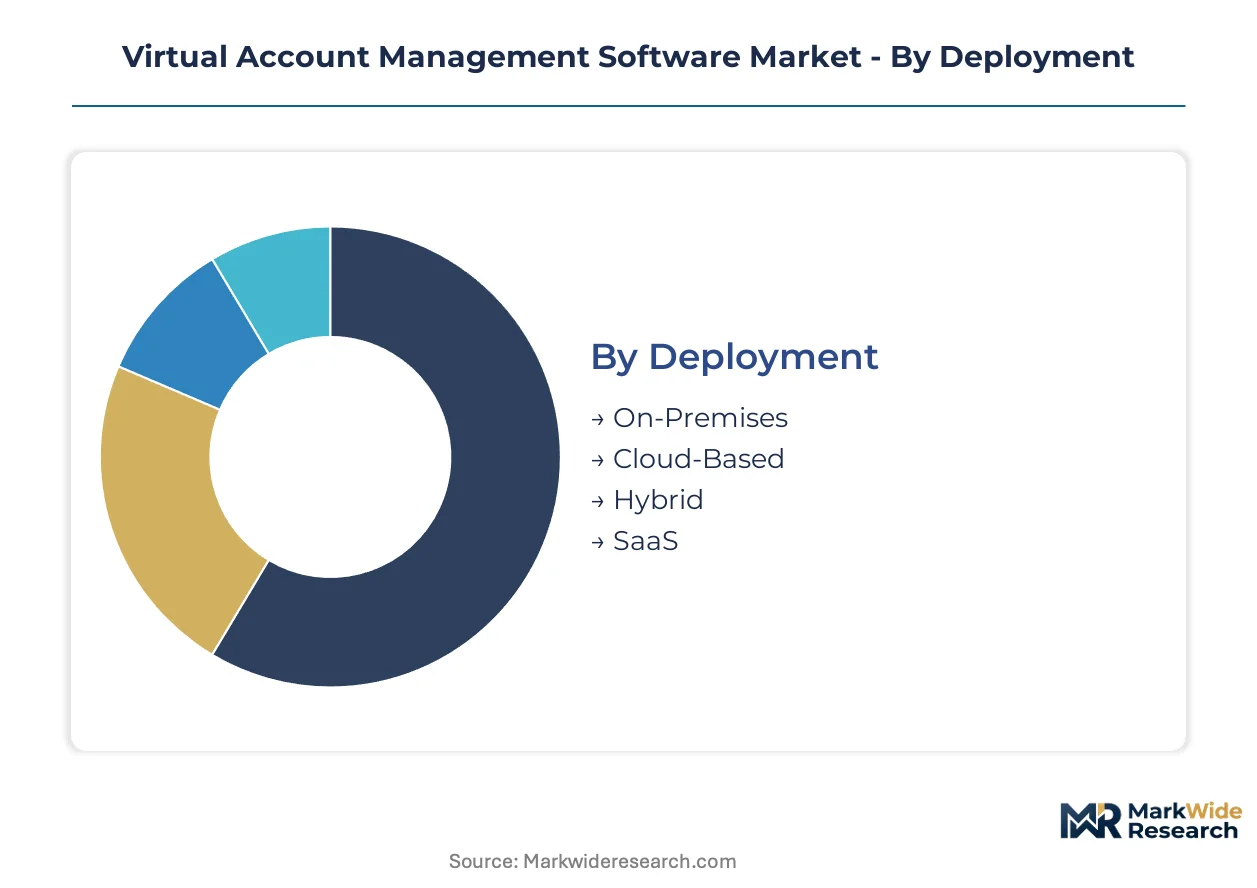
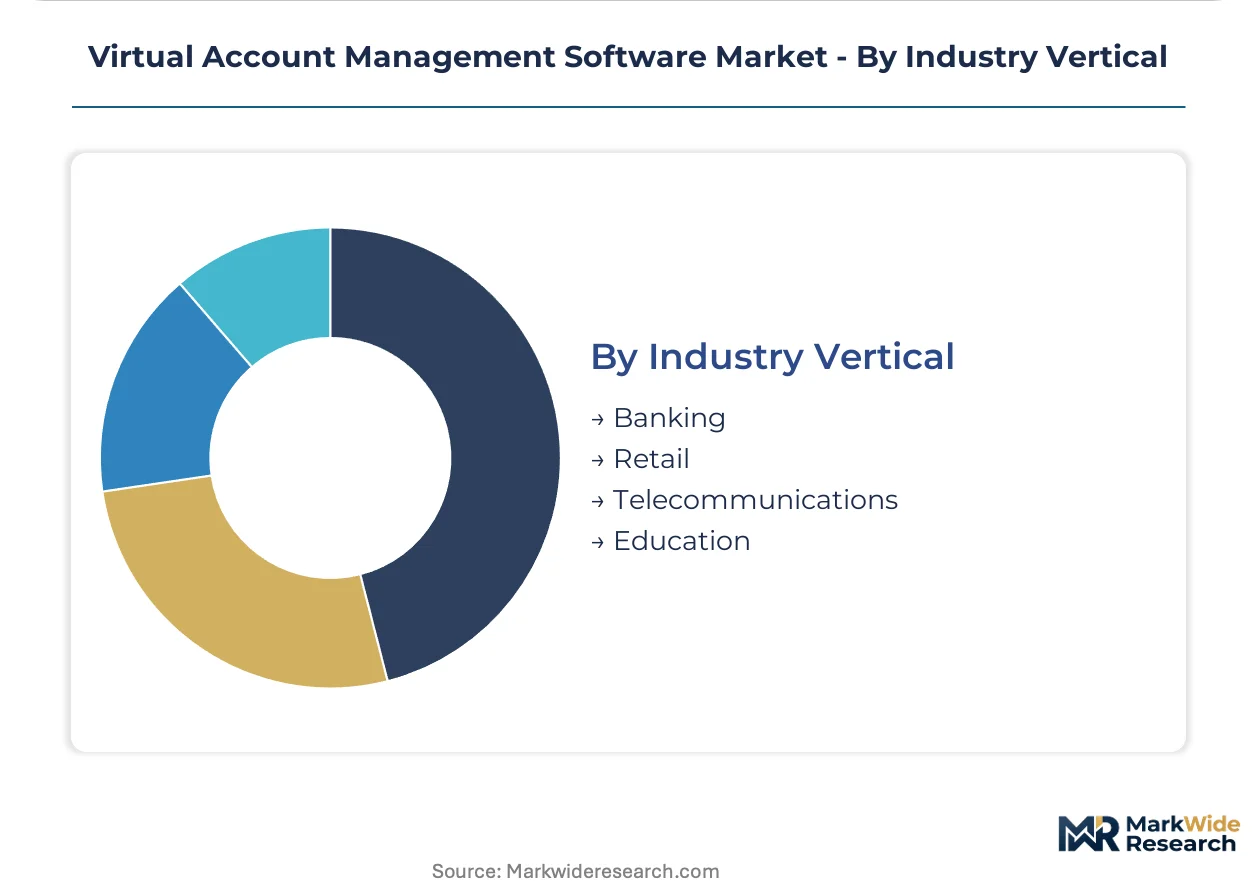
Virtual account management software vendors architect product roadmaps around four distinct segmentation axes. Deployment modality determines infrastructure capital requirements and regulatory compliance posture. Customer type shapes pricing tiers and implementation complexity. Service type governs margin depth and renewal economics. Industry vertical dictates integration priorities and sales channel strategy.
Deployment:
Deployment architecture functions as the primary procurement filter, separating buyers by risk tolerance, data sovereignty requirements, and capital availability.
- Cloud-Based:Multi-tenant architectures with regional data residency controls dominate procurement at multinational manufacturers seeking rapid rollout without data center expenditure. German corporate banks pre-qualify only cloud-native platforms with embedded EU Digital Operational Resilience Act compliance tooling.
- SaaS:Subscription licensing with API-first connectivity enables regional banks to white-label virtual account capabilities without proprietary development. Mid-tier institutions across India and Southeast Asia favor this model to minimize treasury infrastructure capital commitment.
- On-Premises:Single-tenant installations persist among defense contractors and government banking entities with air-gapped security mandates.
- Hybrid:Split configurations separating transaction processing from analytics workloads appeal to organizations navigating phased cloud migration.
Cloud-Based deployment leads on scale; SaaS leads on momentum.
Customer Type:
Organizational scale determines feature depth, support intensity, and contract value trajectories across the vendor base.
- Large Enterprises:Multinational manufacturers operating complex supply chains demand embedded AI-driven cash forecasting across multicurrency hierarchies. Procurement teams prioritize platforms with native ERP integration to eliminate reconciliation latency.
- Corporations:Treasury departments at mid-cap industrial groups seek modular architectures that preserve legacy system connectivity while enabling virtual account deployment.
- SMEs:Standardized configurations with pre-built bank connectors address limited IT resources and compressed implementation timelines.
- Startups:API-only offerings with per-transaction pricing align with variable cash flow patterns and minimal operational overhead requirements.
Large Enterprises anchor revenue concentration; Corporations represent the steepest expansion trajectory.
Service Type:
Functional module selection directly governs margin capture and customer lifetime value expansion opportunities.
- Account Reconciliation:Machine learning-powered transaction matching with audit trail documentation commands premium pricing due to regulatory compliance value and implementation complexity. Demand concentrates among treasury departments managing multicurrency operations across dispersed legal entities.
- Analytics:Predictive liquidity positioning engines integrating external market data streams create differentiation for enterprise-grade deployments. Convergence with virtual account ledgers displaces standalone treasury workstations lacking native AI capabilities.
- Reporting:Bundesbank-aligned regulatory templates and ISO 20022-formatted outputs satisfy mandated disclosure requirements for European banking clients.
- User Management:Role-based access frameworks with multi-factor authentication have commoditized around standardized identity provider integrations.
Account Reconciliation leads on margin; Analytics gains share fastest.
Industry Vertical:
Sector-specific operational patterns dictate integration priorities and compliance module requirements.
- Banking:Core banking system interoperability and white-label deployment capabilities dominate vendor selection criteria. Regional banks across Germany and the United Kingdom license modular infrastructure to compete with larger institutions.
- Retail:High-velocity transaction processing with real-time balance visibility supports omnichannel payment reconciliation and franchise network liquidity management.
- Telecommunications:Multi-jurisdictional revenue collection and partner settlement workflows require virtual account structures spanning emerging market operations.
- Education:Grant fund segregation and donor-restricted account tracking drive adoption at research universities with complex funding portfolios.
Banking leads on scale; Retail leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Deep concentrations of treasury technology professionals in Frankfurt, London, and Mumbai anchor regional demand clusters for virtual account infrastructure across three continents.
Germany
Corporate banking density and Bundesbank reporting standards drive adoption among multinational manufacturers. The EU Digital Operational Resilience Act mandates cloud migration timelines that compress vendor selection cycles. Frankfurt's financial district hosts concentrated deployments at automotive treasury centers modernizing liquidity infrastructure.
United States
Federal Reserve guidance on operational risk management shapes how American banks evaluate third-party treasury platforms. OCC supervision frameworks elevate data residency requirements for cross-border operators. New York's fintech corridor attracts SaaS vendors targeting regional bank white-label partnerships.
United Kingdom
Mid-tier banking segments favor subscription procurement models to minimize capital commitment. FCA operational resilience rules align with EU-equivalent third-party risk mandates. London's Square Mile concentrates system integrator relationships shifting toward revenue-sharing arrangements.
India
RBI real-time gross settlement expansion and corporate treasury modernization initiatives open underpenetrated demand. The central bank's payment infrastructure investments reduce integration friction for virtual account hierarchies. Mumbai's financial district anchors domestic vendor development serving Southeast Asian expansion.
Japan
METI industrial digitization programs accelerate replacement of legacy on-premises treasury systems. JIS standards and domestic data sovereignty preferences favor hybrid deployment architectures. Tokyo's corporate headquarters clusters drive demand for multicurrency hierarchy management across regional subsidiaries.
Virtual Account Management Software Market Vendor Landscape
Capital-heavy enterprise software producers compete with asset-light specialized platform vendors for treasury technology budgets. The vendor base separates into three tiers: database-anchored incumbents with ERP integration depth, modular specialists enabling bank white-label deployment, and cloud-native challengers with API-first architectures. Dominant competitive moves include strategic partnerships with system integrators and vertical integration into predictive analytics engines.
Within the database-anchored tier, Oracle Corporation represents enterprise-grade deployment archetypes with multicurrency liquidity analytics heritage. SAP Fioneer exemplifies ERP-native integration strategies that eliminate reconciliation latency between treasury and procurement systems. Intellect Design Arena occupies a specialized position serving mid-tier banks with modular architectures that avoid core banking replacement.
| Leading Market Players |
|---|
| Infosys Finacle |
| Montran |
| Oracle Corporation |
| Epicor Software Corporation |
| Tietoevry Banking |
| SAP Fioneer |
| Intellect Design Arena |
| Infor |
| Finastra |
| Others |
Supply Flow & Price Mechanics
Corporate treasury procurement mandates for ISO 20022-compliant API connectivity are forcing platform vendors to absorb integration development costs, compressing margins on standard-tier deployments while creating pricing power for AI-embedded premium offerings.
Pricing Analysis
Bundled service packaging dominates enterprise procurement, with AI-driven cash forecasting modules commanding substantial premiums over basic ledger virtualization. Price differentiation rests on ERP integration depth and regulatory compliance certification tiers. Pricing pressure stems from white-label SaaS competition among regional banks seeking minimal capital commitment. Mid-tier corporations exhibit highest price sensitivity, while multinational manufacturers prioritize forecasting accuracy over license cost.
Supply Chain Analysis
Single-source vulnerability sits with hyperscale cloud infrastructure providers in the United States, Germany, and India, where data residency requirements tether deployment geography to specific regional availability zones. Platform development draws from specialized API engineering talent pools, banking regulatory expertise, and machine learning research capabilities. Supply chain risk centers on talent scarcity constraining implementation velocity at regional banks. Distribution runs through system integrator partnerships and direct vendor-to-bank licensing channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in predictive analytics convergence, where automation of reconciliation processes reduces service delivery costs while enabling premium-tier pricing for forecasting capabilities.
For Market Incumbents: Deploy embedded AI forecasting modules to defend against cloud-native challengers with API-first architectures. Prioritize backward integration into data analytics engines to preserve differentiation as ledger virtualization commoditizes. Strengthen system integrator channel control through revenue-sharing arrangements that align implementation success with vendor economics.
For New Entrants and Emerging Players: Enter via India's underpenetrated corporate treasury modernization initiatives, where RBI payment infrastructure expansion reduces integration friction. Target mid-tier regional banks with modular white-label offerings that bypass core banking replacement requirements. Pursue SaaS licensing models to minimize customer capital commitment and accelerate procurement cycles.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized platform vendors possessing modular architectures and established bank partnerships. Long-term viability favors vendors bridging treasury and procurement system integration. Monitor ISO 20022 migration completion rates as an inflection indicator for interoperability-driven vendor consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native ERP connectivity eliminates reconciliation latency between treasury and procurement systems at multinational manufacturers. |
| Strategic Partnership | System integrator alliances with revenue-sharing terms align implementation success with vendor economics in the United Kingdom. |
| Geographic Expansion | India's RBI payment infrastructure investments open underpenetrated demand for virtual account hierarchies among corporate treasuries. |
| Product Launch | AI-driven cash forecasting modules displace standalone treasury workstations lacking predictive analytics capabilities. |
| Acquisition of Specialist Firm | Machine learning talent acquisition addresses capability scarcity constraining regional bank implementation velocity. |
Methodological Framework
Coverage spans Germany, the United States, the United Kingdom, India, and Japan, with primary inputs from each market obtained through structured interviews with corporate treasury directors, bank technology procurement officers, platform integration specialists, and regulatory compliance leads. Secondary validation drew from SEC filings, EU regulatory databases, Bundesbank reporting standards documentation, and RBI policy circulars. Bottom-up deployment estimates triangulated against top-down banking technology expenditure assessments.
Granularity-level modeling addressed deployment modality, organization scale, service type, and industry vertical dimensions across the projection horizon. CAGRs were derived from trend extrapolation of cloud migration timelines and API standardization adoption curves. Forecast inputs incorporated EU Digital Operational Resilience Act compliance deadlines and ISO 20022 migration schedules without assigning specific year markers.
Inputs from regulatory filings and vendor disclosures were available through the study window; gaps in privately held regional bank technology budgets introduce uncertainty bands around SaaS adoption trajectories. Forecasts reflect assumptions about cloud infrastructure cost curves and talent market expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Global Executive Search (Headhunting) Market
Financial Services
Australia Online Trading Platform Market
Financial Services
Qatar Analysis of Key Sectors and Investment Opportunities Market
Financial Services
Africa Factoring Services Market
Financial Services
Peer-To-Peer (P2P) Market
Financial Services
Middle East Financial Consulting Software Market
Financial Services
Financial Advisory Services Market
Financial Services
Financial Services Operational Risk Management Solution Market
Financial Services
Solar Powered ATM Market
Financial Services
South Korea Factoring Services Market
Financial Services
E-Invoicing Market
Financial Services
ATM Managed Services Market
Financial Services
Global Financial Consulting Software Market
Financial Services
Reverse Factoring Market
Financial Services
Back-Office Outsourcing in Financial Services Market
Financial Services
Silver Economy Market