
 Mobile Notary Public Market | 2026-2036
Mobile Notary Public Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Notary Public Market Foresight
Market Context
Independent notary networks across the United States are expanding their agent rosters to cover exurban and rural counties where traditional brick-and-mortar notary access remains sparse. DocuSign leverages its e-signature install base to bundle remote notarization workflows for enterprise clients. Notarize anchors its position through proprietary identity-proofing technology that satisfies multi-state RON requirements. First American Financial Corporation sustains channel control by integrating notary services directly into its title insurance closing operations.
Technical Definition and Segment Structure
Mobile notary public services encompass state-commissioned notarial acts performed outside fixed office locations, requiring seal impression, journal recordation, and signer identity verification under governing state laws. The service delivers legally authenticated document execution for real estate transactions, estate planning instruments, and commercial affidavits where in-person or remote witness presence carries jurisdictional weight. Loan signing commands the largest revenue pool within service type segmentation due to mortgage origination complexity and lender-specific closing instructions. E-notarization and video conferencing technologies represent the fastest-expanding delivery mode categories as state legislatures codify remote execution frameworks. Real estate agents and law firms concentrate margin capture within client type segmentation through recurring high-volume document workflows.
Regulatory Environment
Remote online notarization standards in the United States fragment across state legislatures, with the SECURE Notarization Act proposals at the federal level seeking uniform interstate recognition while individual states maintain distinct technology and recordkeeping mandates. The National Notary Association and state secretary of state offices shape training requirements, bond minimums, and journal retention rules that directly determine platform compliance costs and notary eligibility pools. Stakeholders must monitor state legislative calendars for RON expansion or restriction bills that could abruptly reconfigure addressable market geography and technology investment requirements.
Market Dynamics
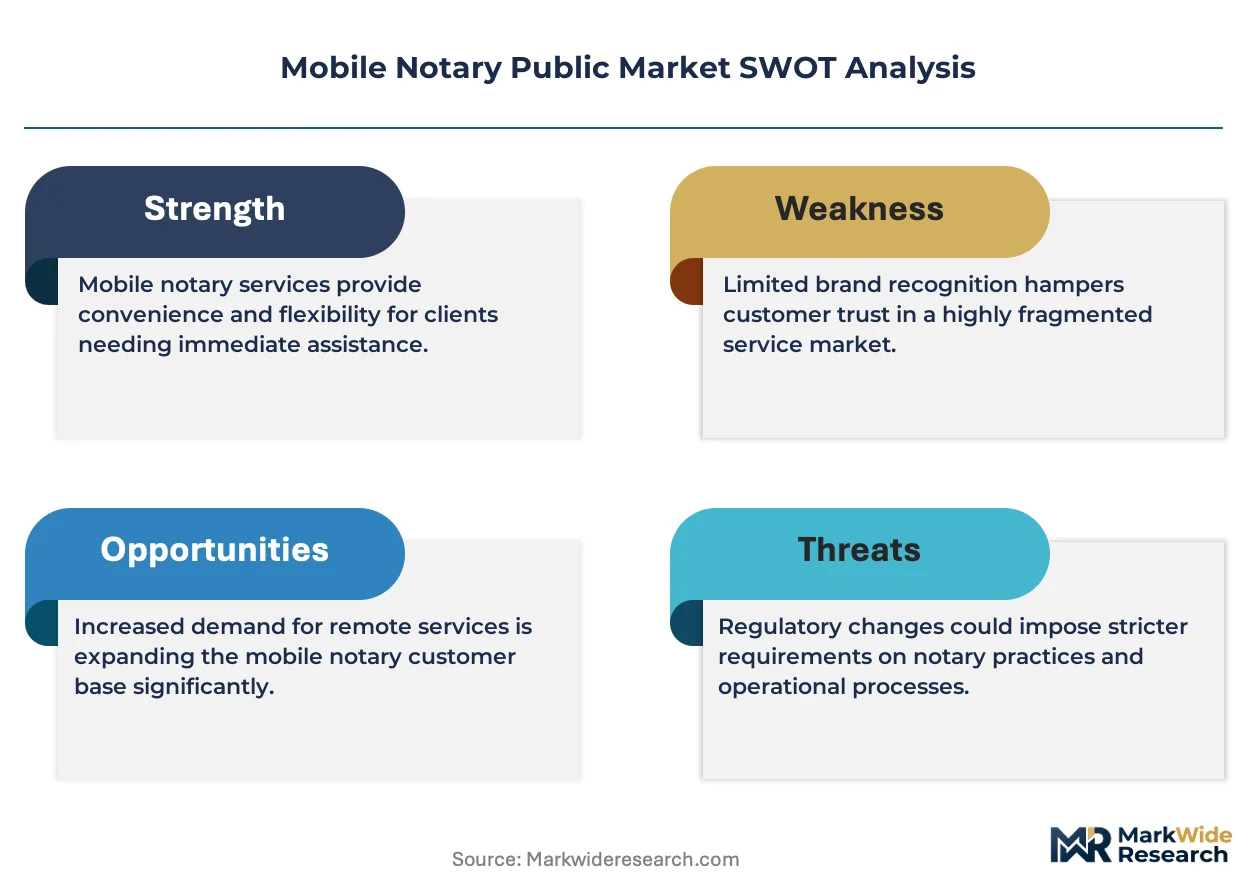
The Mobile Notary Public Market faces structural pressure from uneven state-level RON legislation, which fragments compliance requirements and forces platforms to maintain multiple technology stacks simultaneously.
Growth Catalysts
- Real estate transaction volume:Mortgage origination pipelines in Texas, Florida, and California generate sustained demand for loan signing services requiring notarial witness.
- Remote Online Notarization statutes:State legislatures codifying RON frameworks expand addressable geography beyond traditional brick-and-mortar coverage.
- Identity-proofing technology:Biometric verification and knowledge-based authentication enable multi-jurisdictional compliance without physical presence.
Market Restraints
- State-by-state regulatory fragmentation:The SECURE Notarization Act proposals remain stalled, perpetuating incompatible technology mandates across jurisdictions.
- Notary workforce concentration:Commissioned agent density skews toward urban corridors, leaving rural and exurban counties underserved.
- Wet-ink requirement persistence:Certain document categories, including some estate planning instruments, resist electronic execution under governing state laws.
Strategic Opportunities
- Rural county penetration:Independent notary networks can capture margin in underserved exurban markets where traditional access remains sparse.
- Enterprise workflow bundling:E-signature platforms integrating remote notarization capture recurring high-volume document processing from corporate legal departments.
- Title insurance channel integration:Direct embedding of notary services into closing operations creates captive demand streams.
Industry Challenges
- Multi-state compliance engineering:Platforms must architect systems satisfying divergent journal retention rules, bond minimums, and technology specifications.
- Commissioned agent recruitment:Training pipelines and background check timelines constrain workforce scaling in high-demand corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Notary Public Market |
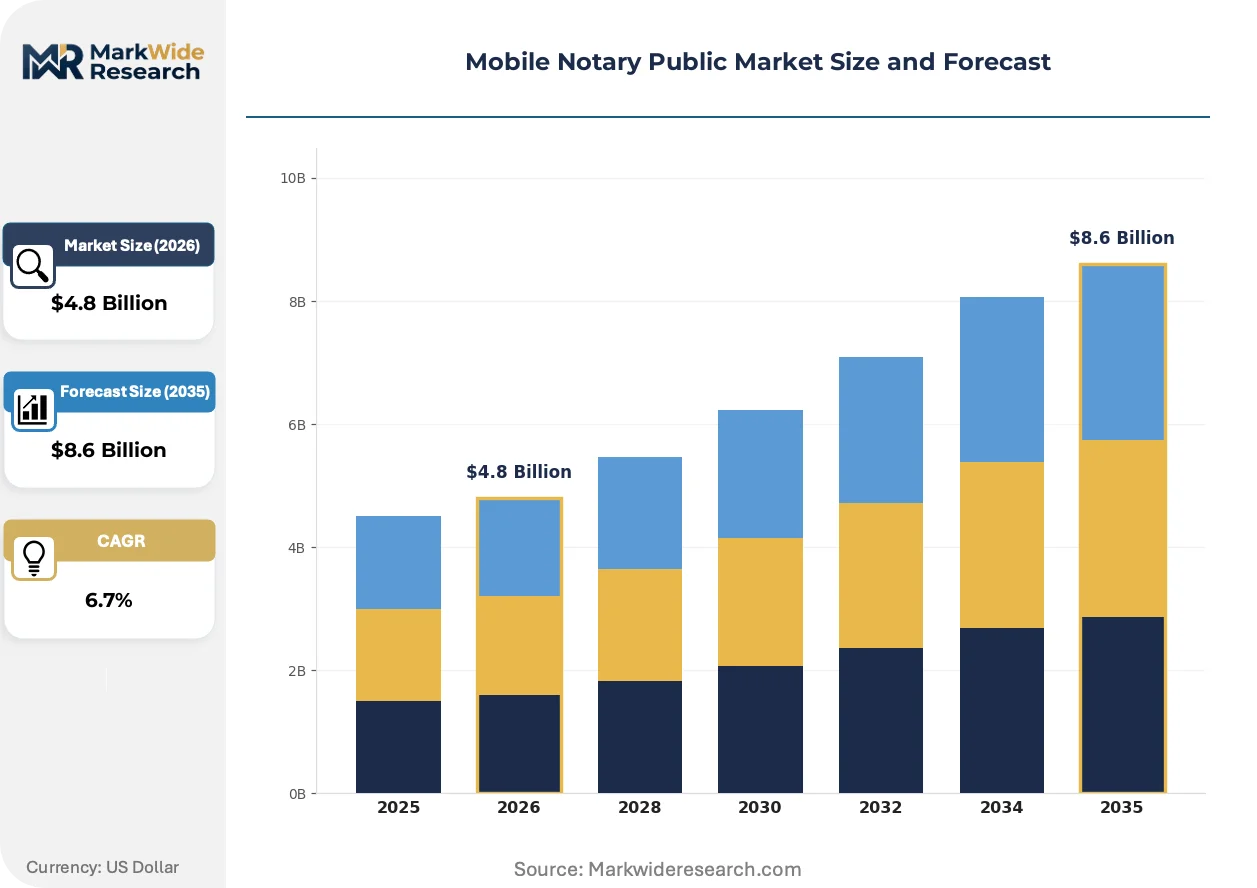
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: General Notary, Loan Signing, Apostille Services, Legal Documents Client Type: Individuals, Real Estate Agents, Law Firms, Businesses Technology: Mobile App, Web-Based Platform, E-Notarization, Video Conferencing Delivery Mode: In-Person, Online, Remote, On-Demand |
| Companies Covered | SignNow, 123Notary, NotaryCam, First American Financial Corporation, Notary Jane, DocuSign, Sunshine Signing, The Closing Exchange, Notarize, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Notary Public Market Shifts & Advancements
Technology convergence and regulatory codification are compressing execution timelines while redrawing competitive boundaries between traditional notary networks and platform-enabled providers.
Artificial intelligence-powered identity verification is automating the multi-factor authentication workflows required for RON compliance. Title insurers and mortgage lenders are adopting these systems fastest, replacing manual document review with algorithmic confidence scoring. This compression of verification time is automating cost structures that previously required human intervention at every step.
The SECURE Notarization Act proposals at the federal level are creating anticipatory investment patterns among platform providers. Stakeholders are pre-building interstate recognition capabilities despite legislative uncertainty. Mortgage origination platforms face the steepest adaptation costs as they reconfigure closing workflows around potential uniform standards.
Buyer preferences are consolidating around bundled service models that combine e-signature, notarization, and document storage. Law firms and real estate brokerages are displacing standalone notary relationships with integrated platform subscriptions. This consolidation is most visible in high-transaction-volume metropolitan areas where workflow efficiency commands premium pricing.
Mobile Notary Public Market Segmentation
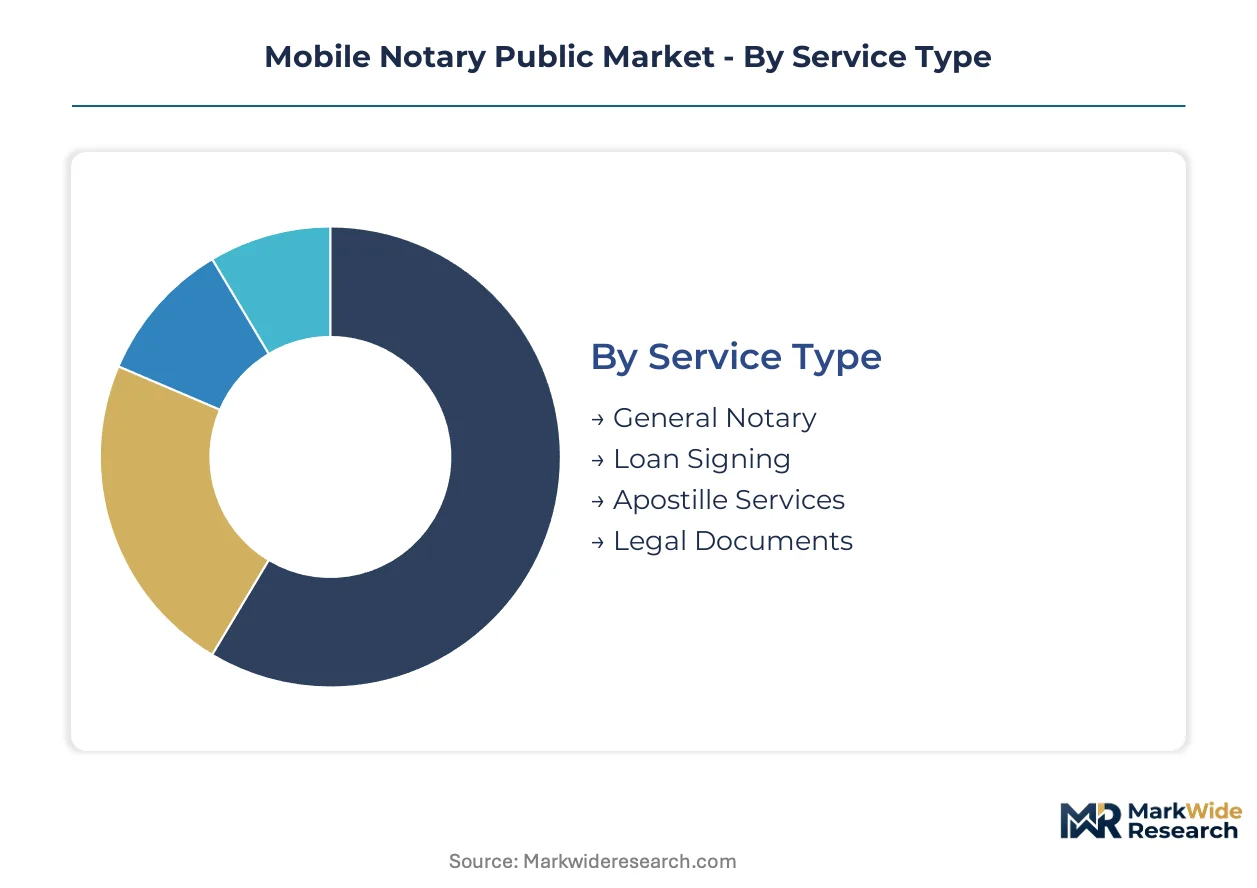
Mobile notary public services fragment across multiple operational dimensions, each commanding distinct margin profiles and compliance architectures. Understanding how service type, client base, technology stack, and delivery mode intersect reveals where platform investments concentrate and where independent operators retain defensible positions.
Service Type:
Supply concentration in loan signing services pulls commissioned agents toward mortgage corridor geographies, leaving general notary capacity thinly distributed elsewhere.
- General Notary:Routine acknowledgments and jurats for personal affidavits, vehicle transfers, and minor legal instruments. Demand clusters in urban centers where population density supports walk-up volume, though margins compress under platform pricing pressure.
- Loan Signing:Complex mortgage closing packages requiring specialized training in lender-specific instructions, escrow documentation, and title transfer protocols. Texas, Florida, and California absorb the majority of transaction volume as housing market velocity concentrates in these states.
- Apostille Services:Document authentication for international use under Hague Convention standards.
- Legal Documents:Estate planning instruments, power of attorney execution, and corporate formation filings.
Loan signing absorbs the bulk of installed capacity; apostille services are expanding most quickly as cross-border document authentication demand rises.
Client Type:
Margin structure varies sharply by client sophistication, with institutional purchasers extracting volume discounts that independent notaries cannot match.
- Individuals:One-time consumers seeking convenience for personal transactions. Price sensitivity runs high; mobile premiums of 50-100% over brick-and-mortar rates are accepted only when geographic access is severely constrained.
- Real Estate Agents:Recurring high-volume users embedding notary coordination into closing workflows. Commission structures incentivize agent-controlled notary selection, creating sticky relationships that platforms struggle to disintermediate.
- Law Firms:Corporate legal departments and estate practices requiring reliable execution capacity.
- Businesses:HR departments, procurement teams, and compliance functions with recurring notarization needs.
Real estate agents command the deepest relationship economics; law firms are climbing the fastest as remote execution capabilities expand their addressable notary pool.
Technology:
Technology investment patterns track state RON legislation density, with platforms overbuilding in permissive jurisdictions while maintaining legacy infrastructure elsewhere.
- Mobile App:GPS-enabled dispatch systems connecting signers with proximate commissioned agents. User experience differentiation centers on real-time availability visibility and automated scheduling.
- Web-Based Platform:Browser-accessible portals for document upload, session scheduling, and payment processing. Enterprise adoption concentrates where IT security policies restrict native application deployment.
- E-Notarization:Digital seal application and cryptographic document binding satisfying state electronic signature statutes.
- Video Conferencing:Synchronous audio-visual sessions enabling remote online notarization where permitted.
Mobile apps capture the greatest user acquisition investment; video conferencing infrastructure is scaling fastest as state legislatures codify RON frameworks.
Delivery Mode:
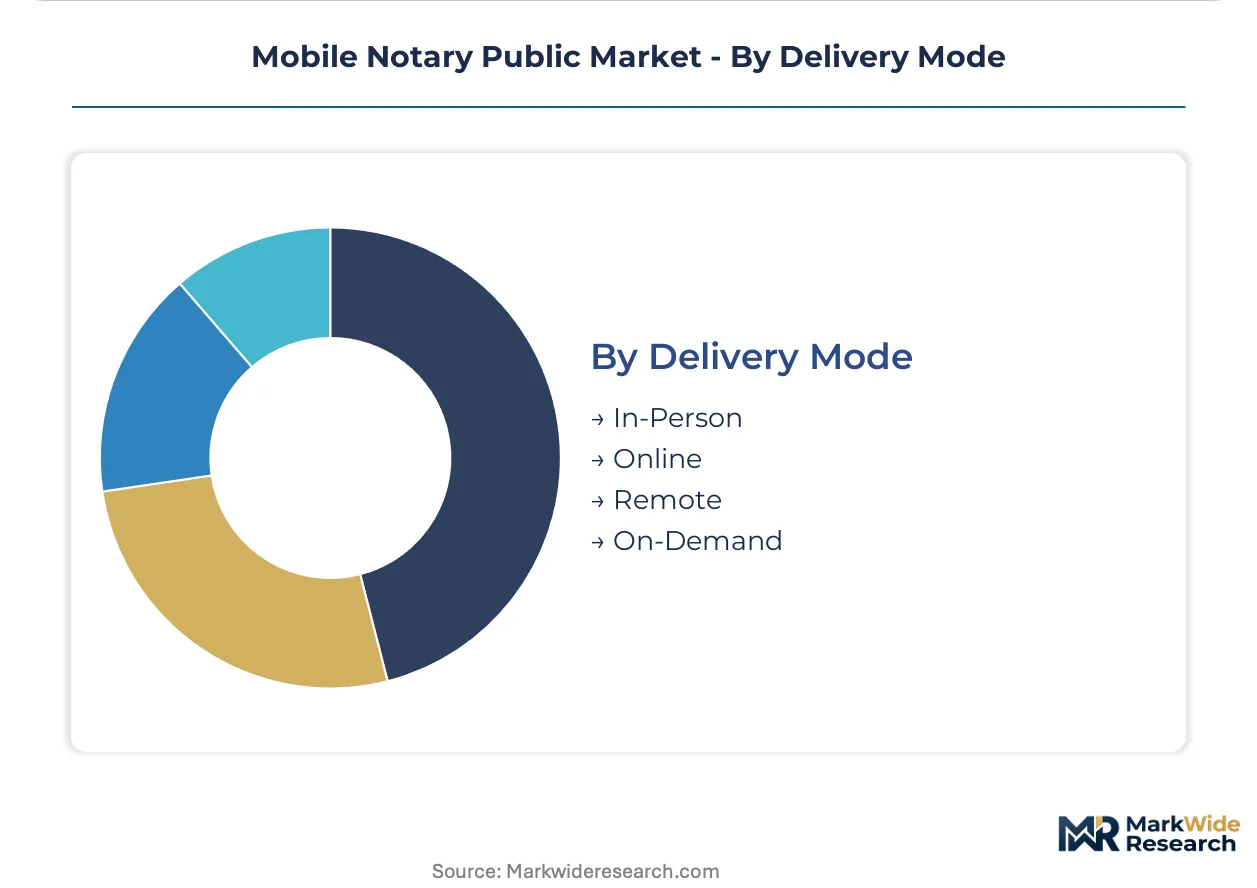
Delivery mode selection reflects document category restrictions, signer technology access, and urgency requirements in combination.
- In-Person:Traditional physical presence model required for certain estate planning instruments and jurisdictions without RON authorization. Wet-ink persistence maintains demand despite convenience disadvantages.
- Online:Asynchronous document submission with electronic notarization and return delivery. Eliminates scheduling coordination costs for non-urgent transactions.
- Remote:Synchronous audio-visual notarization satisfying multi-state RON requirements where enacted.
- On-Demand:Immediate dispatch models promising sub-two-hour response times in metropolitan corridors.
In-person retains the largest transaction base due to regulatory persistence; remote delivery is gaining share fastest where interstate recognition standards advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commissioned notary density and real estate transaction velocity anchor geographic demand patterns across major economies. Housing market liquidity and state-level remote notarization statutes determine where platform investments concentrate.
United States
Texas, Florida, and California absorb the majority of loan signing volume as mortgage origination pipelines concentrate in these corridors. The SECURE Notarization Act proposals at the federal level seek uniform interstate recognition, though individual states maintain distinct technology mandates. Metropolitan clusters in Dallas-Fort Worth, Miami-Dade, and Los Angeles County drive platform deployment density.
Canada
Cross-border document authentication demand rises with international estate planning and corporate formation activity. Provincial notary regulations vary between common law and civil law jurisdictions, fragmenting compliance requirements. Toronto and Vancouver anchor service demand as financial services and immigration documentation volumes concentrate.
United Kingdom
London's position as a financial services hub generates sustained demand for notarial acts supporting international transactions. The Faculty Office of the Archbishop of Canterbury regulates notary appointments, maintaining qualification barriers that limit workforce scaling. The City of London and Canary Wharf concentrate corporate notary utilization.
Germany
Notarial involvement in real estate transactions is mandatory under German civil law, creating structurally embedded demand. The Federal Chamber of Notaries sets nationwide standards while Länder-level implementation varies. Frankfurt and Munich anchor commercial notary activity as corporate restructuring and property transactions concentrate.
Australia
Sydney and Melbourne drive demand as property settlement volumes and international document authentication needs intersect. State-level regulation of notary appointments creates workforce constraints that platforms address through mobile dispatch models. New South Wales and Victoria legislative frameworks shape technology investment requirements.
Mobile Notary Public Market Competitive Landscape
Global majors compete with regional champions across technology integration and workforce deployment capabilities. The vendor base fragments between e-signature platforms extending into notarization, independent notary networks optimizing geographic coverage, and title insurers embedding services directly. Three archetypes dominate: technology bundlers, workforce aggregators, and vertically integrated closing service providers. M&A activity concentrates on identity-proofing capabilities and state-level notary network acquisitions.
Within the technology bundler tier, DocuSign and Notarize exemplify platform-first strategies leveraging existing user bases. First American Financial Corporation anchors the vertically integrated archetype through title insurance channel control. These three occupy positions that reflect divergent bets on whether RON standardization or workforce density wins market structure.
| Leading Market Players |
|---|
| SignNow |
| 123Notary |
| NotaryCam |
| First American Financial Corporation |
| Notary Jane |
| DocuSign |
| Sunshine Signing |
| The Closing Exchange |
| Notarize |
| Others |
Supply & Pricing Matrix
Commissioned agent labor costs in Texas, Florida, and California anchor pricing tiers across the Mobile Notary Public Market, with platform technology investments and state bond requirements cascading into rate structures that separate enterprise contract pricing from on-demand consumer premiums.
Pricing Analysis
Warranty and service bundling separates platform subscription models from standalone per-transaction rates, with DocuSign and Notarize embedding identity verification and document storage into recurring SaaS tiers while independent notaries charge unbundled travel fees plus per-signature rates. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade, geographic delivery cost, and volume scale. Cost compression in the economy tier is intensifying because mobile app dispatch platforms are automating agent matching. Individual consumers exhibit highest price sensitivity, accepting mobile premiums only when brick-and-mortar access is severely constrained; title insurers show least sensitivity due to captive demand integration.
Supply Chain Analysis
Direct-to-title-insurer channels handle hyperscale mortgage closing demand, while mobile app dispatch platforms aggregate commissioned agent supply for fragmented individual and small-business transactions. Commissioned notary workforce supply concentrates in the United States, Canada, and the United Kingdom where state and provincial appointment systems create credentialing barriers. Technology infrastructure draws from cloud hosting providers, biometric verification vendors, and video conferencing platforms. Single-source vulnerability runs through proprietary identity-proofing technology providers that dominate multi-state RON compliance. Distribution runs through title insurance closing operations, e-signature platform marketplaces, and independent notary network dispatch systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Mobile Notary Public Market is consolidating into a vertical-integration race where control over commissioned agent networks and identity-proofing technology determines margin capture. Title insurers are pursuing downstream integration into closing operations to lock in captive demand streams.
For Market Incumbents: Anticipate regulatory fragmentation as the primary threat, with state-level RON legislation diverging on technology mandates and journal retention rules. Incumbents should pursue backward integration into proprietary identity-verification technology to reduce dependence on third-party biometric vendors. Channel control through exclusive agent network contracts in Texas, Florida, and California protects against platform disintermediation. For New Entrants and Emerging Players: API-first distribution partnerships with e-signature platforms offer the lowest customer acquisition cost route into enterprise legal departments. Rural and exurban counties in states with recent RON authorization present the most penetrable white-space geography, where commissioned agent density remains sparse and platform coverage is thin. White-label notary dispatch services for real estate brokerages provide a defensible go-to-market angle against direct consumer competition. For Investors and Strategic Acquirers: Distressed-cycle entries favor workforce-aggregator platforms with established agent credentialing infrastructure in high-transaction states. Long-term viability hinges on federal RON standardization or durable state-level regulatory moats. Acquisition target archetype: regional notary networks with density in Texas, Florida, or California and existing title insurance channel relationships. The signal to watch is SECURE Notarization Act legislative progress as inflection indicator for interstate recognition investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Identity-Proofing Technology Acquisition | Proprietary biometric verification satisfies divergent state RON mandates without third-party dependency. |
| Agent Network Expansion | Commissioned notary density in Dallas-Fort Worth and Miami-Dade secures loan signing volume capture. |
| Title Insurance Channel Integration | Direct embedding into First American closing operations creates captive recurring demand streams. |
| Rural County Dispatch Infrastructure | GPS-enabled mobile platforms address exurban coverage gaps where traditional notary access remains sparse. |
| Multi-State Compliance Engineering | Unified technology stacks reduce platform maintenance costs across fragmented state legislative environments. |
Research Methodology
Independent corroboration across commissioned notary network operators, title insurance closing officers, and state secretary of state regulatory staff underwrites the qualitative findings in this study. Primary interviews with mobile notary platform executives, real estate brokerage operations managers, and mortgage lender compliance officers combined with secondary validation from National Notary Association training records, state legislative bill tracking databases, and SEC 10-K disclosures from publicly traded title insurers. Bottom-up agent capacity estimates and top-down transaction volume data triangulate market size assessments.
Comparable-period anchoring to historical housing transaction velocity and commissioned notary appointment rates established the forecast baseline across the projection horizon. Segmentation dimensions modeled include service type, client sophistication tier, technology deployment mode, and state-level RON legislative status. CAGRs were derived from housing origination pipeline forecasts and platform adoption curve analysis. Industry-specific inputs incorporate mortgage rate sensitivity and state legislative calendar clustering.
The model holds under continued state-level RON authorization expansion; deviation in federal preemption or interstate recognition restriction would shift addressable geography and technology investment requirements. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Source to Pay Market
Financial Services
Middle East Islamic Finance Market
Financial Services
Solar Powered ATM Market
Financial Services
Saas Escrow Services Market
Financial Services
Commodity Trade Finance Market
Financial Services
Africa Lottery Market
Financial Services
Europe B2C Legal Services Market
Financial Services
Outsource Debt Collection Services Market
Financial Services
Global Treasury Management System (TMS) Market
Financial Services
Global P2P Fundraising Tool Market
Financial Services
Banking Cloud Services Market
Financial Services
China Trade Finance Market
Financial Services
United States Payroll Services Market
Financial Services
Investment Trading Software Market
Financial Services
Global Business Management Consulting Service Market
Financial Services
Credit Rating Software Market