
 Online Sports Betting Market | 2026-2036
Online Sports Betting Market Size, Share, and Industry Trends Forecast 2026-2036
Online Sports Betting Market Analysis
Recreational bettors are unwinding the dominance of professional wagering pools across major platforms. DraftKings leverages its daily fantasy heritage to anchor crossover user acquisition in newly regulated jurisdictions. Flutter Entertainment sustains market leadership through geographic diversification across Europe, Australia, and emerging U.S. markets. Bet365 specializes in live streaming integration that deepens in-play betting engagement.
Online sports betting constitutes a digital wagering ecosystem where operators accept stakes on athletic contests through internet-connected platforms, processing bets via algorithmic odds engines with sub-second latency and geofenced compliance perimeters. The primary commercial purpose centers on converting sports viewership into transactional engagement while extracting margin through vigorish structures. Mobile app deployment leads all device channels by transaction volume, while in-play betting generates the fastest handle expansion as micro-wagering on discrete game events proliferates. Exchange betting occupies a narrower but higher-margin niche where the operator facilitates peer-to-peer matching rather than assuming book risk.
The U.S. market operates under a fragmented state-by-state licensing patchwork with no federal umbrella, creating compliance complexity that advantages operators with established regulatory infrastructure. The UK's Gambling Commission imposes affordability checks and advertising restrictions that constrain customer acquisition economics. Brazil's newly enacted Law 14.790 establishes a federal licensing regime through the Ministry of Finance, opening Latin America's largest addressable population. Stakeholders must monitor how divergent KYC intensity standards across jurisdictions reshape platform development roadmaps and capital allocation priorities.
Market Dynamics
Real-time geolocation verification technology is compressing platform architecture timelines as operators race to satisfy state-level compliance mandates before competitor entry windows close. Mobile-first deployment now dictates capital allocation across product development, payment integration, and KYC infrastructure.
Growth Catalysts
- State-level legalization waves:Fragmented U.S. licensing regimes create sequential market entry opportunities as individual jurisdictions authorize sports wagering. Each new state triggers platform scaling investments.
- Micro-wagering technology:In-play betting engines processing sub-second odds adjustments enable discrete event stakes during live contests. This technology expands transaction frequency per user session.
- Brazil's federal framework:Law 14.790 establishes Ministry of Finance oversight for Latin America's largest addressable betting population. Federal licensing replaces prior regulatory ambiguity.
Market Restraints
- Compliance cost escalation:KYC infrastructure and geofencing technology consume disproportionate platform development budgets. Smaller operators face capital barriers to multi-state expansion.
- Payment processor concentration:Limited banking partnerships for wagering transactions create single-point vulnerabilities. Processor policy shifts disrupt deposit and withdrawal flows.
- Advertising restriction tightening:UK Gambling Commission affordability checks and promotional constraints compress customer acquisition economics. Lifetime value calculations face regulatory headwinds.
Strategic Opportunities
- Esports wagering expansion:Competitive video gaming demographics skew younger than traditional sports betting. Dedicated esports platforms capture adjacent engagement pools.
- Peer-to-peer exchange models:Operator-facilitated matching eliminates book risk while capturing higher-margin commission structures. Exchange liquidity networks reward early scale.
- Streaming-betting convergence:Live sports broadcast integration enables frictionless in-play stake placement. Rights holders and platforms negotiate revenue-sharing for synchronized wagering.
Industry Challenges
- Responsible gaming algorithm deployment:Behavioral monitoring systems must identify problematic patterns without generating excessive false positives. Engineering trade-offs affect user experience and regulatory satisfaction.
- Cross-platform data synchronization:Legacy daily fantasy user databases require integration with new sportsbook architectures. Data migration timelines delay unified product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Online Sports Betting Market |
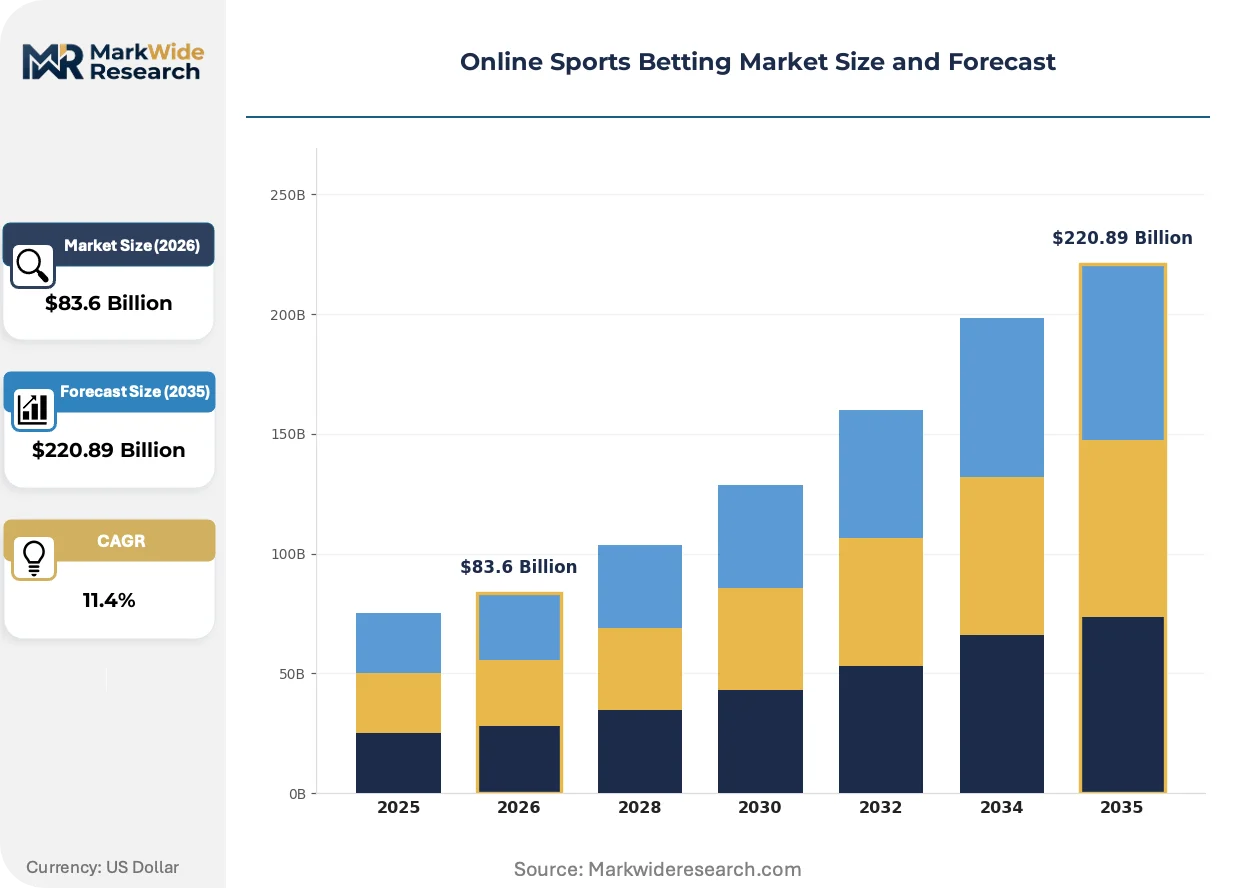
| Market Size in 2026 | $83.6 Billion |
| Market Size in 2035 | $220.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Betting Type: Fixed Odds, In-Play Betting, Exchange Betting, Pool Betting Device Type: Mobile App, Desktop, Tablet, Smart TV Customer Type: Casual Bettors, Professional Bettors, High Rollers, New Users Payment Method: Credit Card, E-Wallet, Bank Transfer, Cryptocurrency |
| Companies Covered | Flutter Entertainment, Caesars Entertainment, DraftKings, Bet365 Group, FanDuel, BetMGM, Penn Entertainment, MGM Resorts International, Playtech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Online Sports Betting Market Emerging Trajectories
Algorithmic personalization engines are reshaping how platforms segment and retain users. Three developments dominate competitive differentiation: infrastructure automation, regulatory technology integration, and behavioral data monetization.
Machine learning-driven odds engines are supplanting static pricing models across major platforms. These systems ingest real-time injury reports, weather conditions, and betting flow imbalances to adjust lines instantaneously. Tier-one operators deploy proprietary models that compress margin leakage during volatile in-play windows.
The UK's affordability check mandates are forcing platform redesigns around financial vulnerability detection. Operators must integrate bank statement analysis and spending pattern assessment into onboarding flows. This regulatory technology burden advantages incumbents with existing compliance infrastructure over new market entrants.
Casual bettor acquisition is displacing professional volume dependence as the primary growth vector. Platforms now optimize for lower-stakes, higher-frequency engagement rather than whale cultivation. This behavioral shift concentrates marketing spend on social media channels and influencer partnerships rather than traditional sports broadcast advertising.
Online Sports Betting Market Segmentation
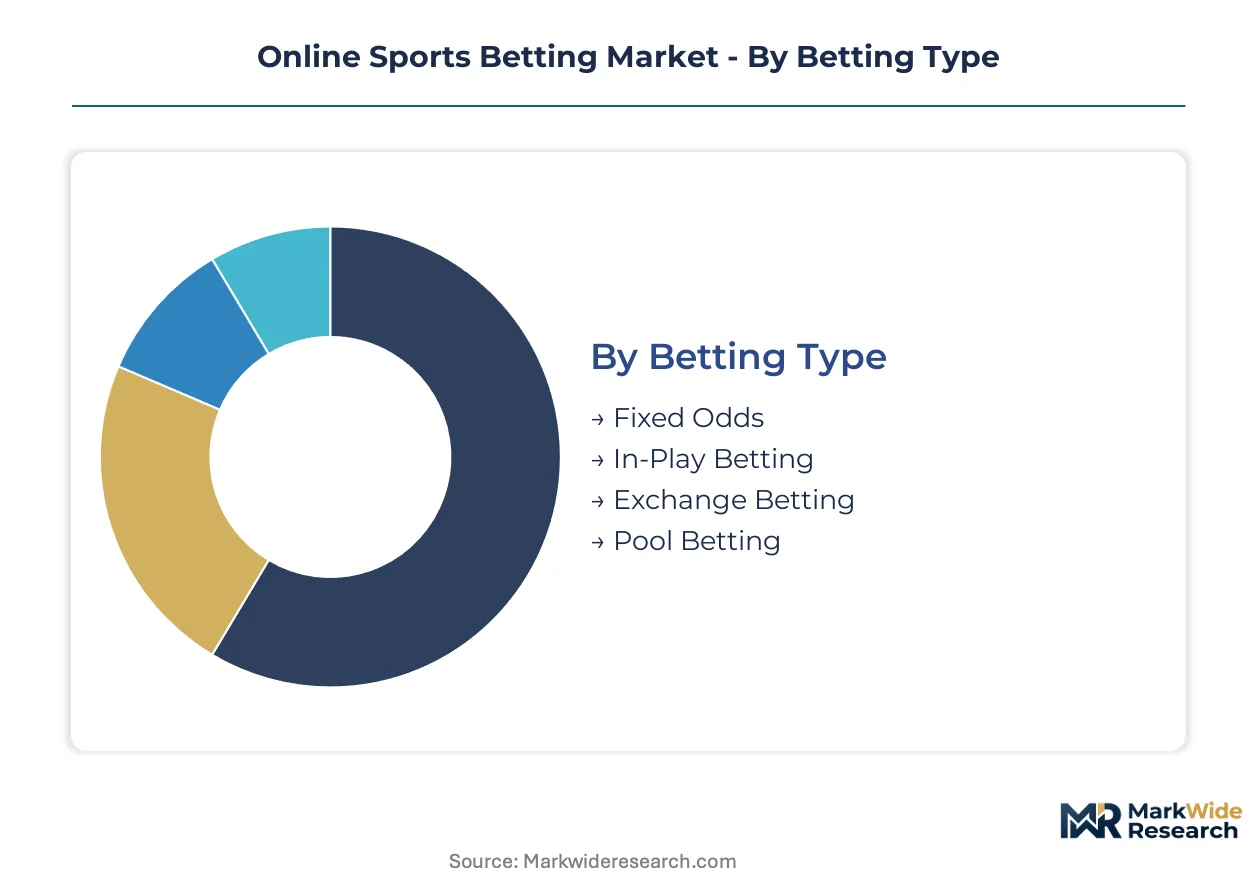
Segmentation in online sports betting determines platform architecture investments and regulatory compliance pathways. Each dimension—betting mechanics, access devices, customer profiles, and payment rails—creates distinct operational requirements and margin structures that shape operator strategy.
Betting Type:
Geographic spread varies sharply: fixed odds dominates mature domestic markets with established regulatory frameworks, while exchange betting concentrates in export-oriented jurisdictions with sophisticated liquidity infrastructure.
- Fixed Odds:Traditional bookmaker-assigned prices lock in profit margins through vigorish structures. Demand concentrates in the United Kingdom and U.S. states with mature licensing, driven by casual bettor familiarity and straightforward risk management for operators.
- In-Play Betting:Real-time odds engines process micro-wagers on discrete game events with sub-second latency. Brazil's newly regulated market and select U.S. states show the steepest adoption curves as mobile penetration enables frictionless live engagement.
- Exchange Betting:Peer-to-peer matching platforms eliminate book risk while capturing commission revenue. Liquidity concentrates in the UK and Australia where regulatory clarity supports secondary market depth.
- Pool Betting:Aggregated stakes distribute winnings across outcome tiers, common in horse racing and lottery-linked wagering. Tote systems retain dominance in legacy racing jurisdictions.
Fixed odds commands the established base. The steepest expansion runs through in-play betting.
Device Type:
Cost tier stratification separates premium native app development from lower-investment responsive web deployments, with customer acquisition economics dictating capital allocation across channels.
- Mobile App:Native iOS and Android applications deliver push notifications, biometric authentication, and geofenced compliance perimeters. Brazil and U.S. state-level markets drive volume as smartphone penetration enables always-on access.
- Desktop:Browser-based platforms retain professional bettor preference for multi-screen analysis and spreadsheet integration. UK exchange users sustain this channel's relevance despite mobile shift.
- Tablet:Mid-tier engagement device for home-based casual sessions. Live streaming integration drives retention in European markets.
- Smart TV:Emerging convergence point for streaming-betting synchronization. Early deployment concentrates in UK and Australian markets with integrated broadcast rights.
Mobile app deployment captures volume leadership. Tablet and smart TV channels are climbing the fastest as living-room engagement deepens.
Customer Type:
Volume concentration versus margin extraction creates divergent platform optimization targets, with casual acquisition displacing whale dependence as the primary growth vector.
- Casual Bettors:Lower-stakes, higher-frequency users acquired through social media and influencer channels. Brazil's emerging market and newly regulated U.S. states show the fastest casual pool expansion.
- Professional Bettors:Algorithmic and arbitrage-focused users demanding high limits and rapid execution. Exchange platforms in the UK and Australia retain this segment despite margin compression.
- High Rollers:VIP-tier users requiring bespoke service and customized risk management. Concierge acquisition costs concentrate marketing spend in mature markets.
- New Users:First-time depositors requiring streamlined onboarding and educational interfaces. KYC automation investments target this segment's conversion funnel.
Casual bettors command the established base. New user acquisition is gaining share fastest as legalization waves expand addressable populations.
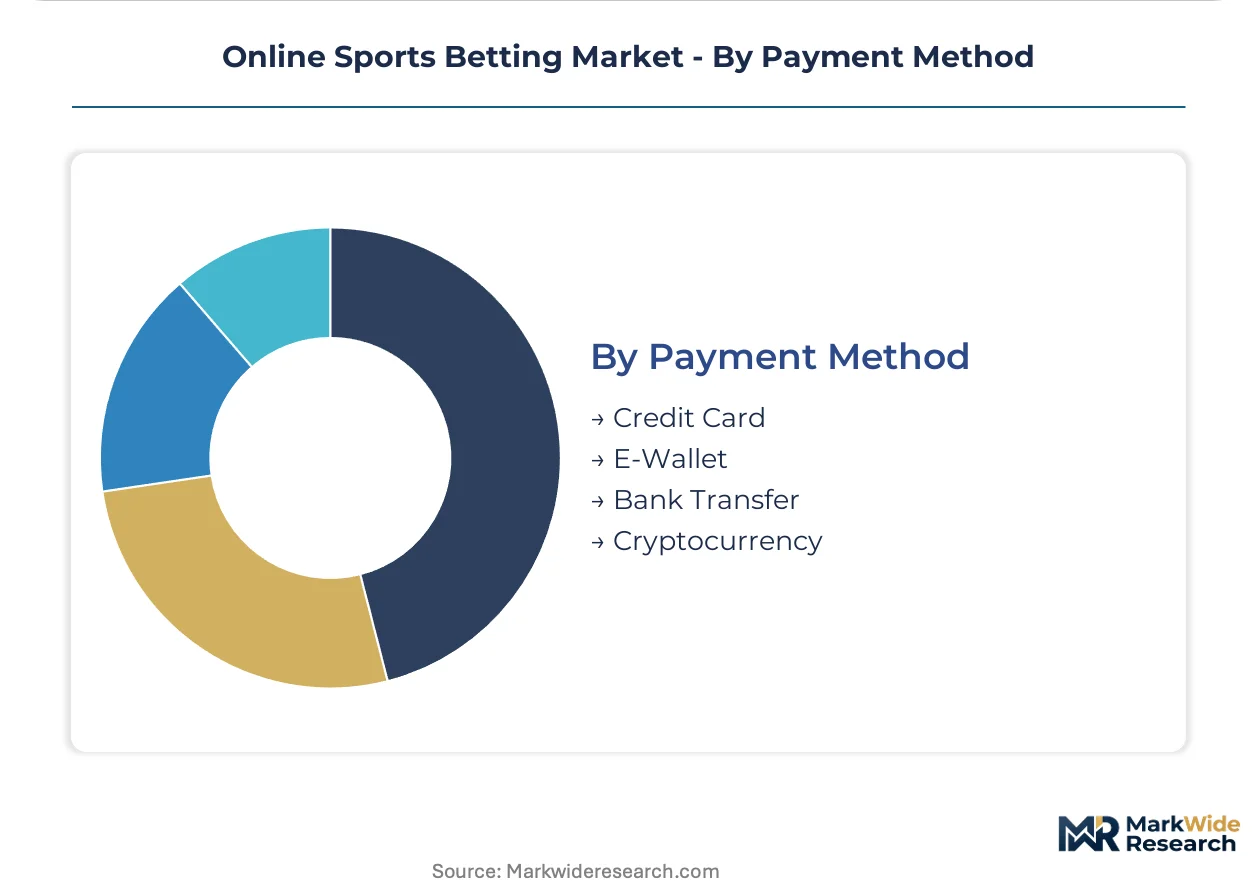
Payment Method:
Regulatory acceptance tiers separate fully integrated banking partnerships from restricted alternative rails, with jurisdiction-specific licensing determining available options.
- Credit Card:Dominant deposit method in UK and mature U.S. markets despite issuer restrictions in certain states. Chargeback risk requires operator hedging.
- E-Wallet:PayPal, Skrill, and regional alternatives enable rapid deposits without direct bank exposure. Brazil's PIX integration and European digital wallets show steepest adoption curves.
- Bank Transfer:High-value withdrawal preference for professional users and VIP tiers. Settlement latency constrains casual bettor utilization.
- Cryptocurrency:Offshore and emerging market adoption bypasses traditional banking friction. Regulatory ambiguity limits deployment in licensed U.S. and UK jurisdictions.
E-wallet penetration commands the established base. Cryptocurrency rails are expanding most quickly in jurisdictions with banking partnership constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The transatlantic fiber optic cable infrastructure underwrites North America's digital wagering throughput, while Brazil's PIX payment rail integration accelerates Latin American market formation. Regulatory fragmentation across these jurisdictions creates divergent platform architecture requirements.
United States
State-level mobile app deployment drives transaction volume as individual jurisdictions authorize sports wagering through ballot measures and legislative action. The Wire Act and state gaming commissions impose geofencing and KYC verification mandates that compress platform development timelines. New York and New Jersey sustain the densest operator concentration, with Manhattan-based technology vendors supplying compliance infrastructure to emerging state markets.
United Kingdom
Exchange betting liquidity and in-play wagering maturity sustain professional and casual bettor engagement across established platforms. The Gambling Commission's affordability check mandates and advertising restrictions reshape customer acquisition economics and onboarding flows. London clusters the headquarters of tier-one operators and regulatory technology vendors serving European markets.
Brazil
Federal licensing under Law 14.790 opens Latin America's largest addressable betting population as smartphone penetration enables mobile-first engagement. The Ministry of Finance oversees operator authorization through a centralized framework replacing prior regulatory ambiguity. São Paulo anchors the domestic technology ecosystem, with local payment processors integrating PIX rails for frictionless deposit flows.
Australia
Exchange betting infrastructure and racing-integrated wagering sustain high-frequency engagement among sophisticated bettors. State-level racing authorities and national consumer protection frameworks impose responsible gaming algorithm requirements. Melbourne and Sydney concentrate operator development centers and broadcast rights negotiation hubs for Asia-Pacific market expansion.
Germany
State treaty harmonization creates a federal licensing pathway for digital sports wagering amid prior interstate fragmentation. The Glücksspielneuregulierungsstaatsvertrag establishes advertising restrictions and deposit limits that constrain marketing intensity. Hesse and North Rhine-Westphalia host the primary technology infrastructure serving German-speaking European markets.
Online Sports Betting Market Vendor Landscape
Concentration sits with diversified entertainment conglomerates and specialized digital wagering platforms. The market structure tiers across global operators with multi-jurisdictional licensing infrastructure, regional specialists with deep local market penetration, and technology vendors supplying platform-as-a-service solutions. Two strategic archetypes dominate: vertically integrated operators controlling product development and compliance infrastructure, and asset-light platforms licensing third-party technology stacks. Competitive moves center on geographic expansion into newly regulated jurisdictions and streaming-betting convergence partnerships with broadcast rights holders.
Within the diversified entertainment tier, Flutter Entertainment and Caesars Entertainment exemplify contrasting strategic postures. Flutter Entertainment, an Ireland-based public limited company, anchors global market presence through geographic diversification across European, Australian, and U.S. state markets. Caesars Entertainment, a Nevada-incorporated resort operator, leverages physical casino infrastructure to anchor digital wagering cross-sell in jurisdictions where integrated resort presence supports brand recognition and regulatory relationships. DraftKings, a Boston-based daily fantasy heritage operator, occupies a position bridging casual bettor acquisition and technology-native platform architecture.
| Leading Market Players |
|---|
| Flutter Entertainment |
| Caesars Entertainment |
| DraftKings |
| Bet365 Group |
| FanDuel |
| BetMGM |
| Penn Entertainment |
| MGM Resorts International |
| Playtech |
| Others |
Supply Flow & Price Mechanics
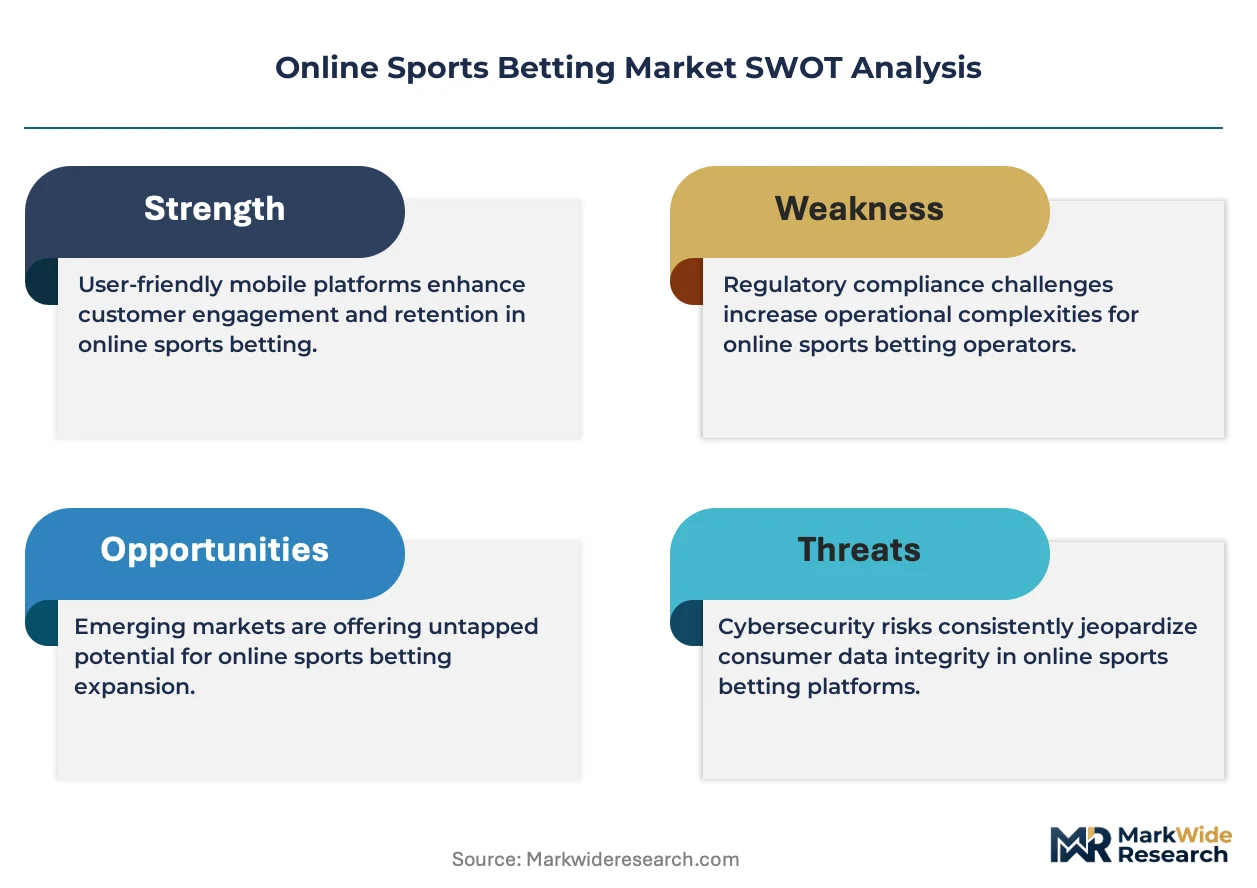
State-level KYC mandates in the United States gate both platform vendor qualification and operator pricing power simultaneously, as compliance infrastructure costs stratify market entry tiers and force margin compression on smaller competitors unable to amortize fixed regulatory technology investments across sufficient transaction volume.
Pricing Analysis
Volume-discount tiering structures dominate operator-platform relationships, with enterprise-scale sportsbooks securing preferential rates on geolocation verification and payment processing APIs. Price differentiation rests on transaction volume thresholds and real-time odds engine latency guarantees, with sub-second in-play platforms commanding premium positioning. Cost compression in mid-tier white-label deployments is intensifying because Brazilian federal licensing under Law 14.790 is flooding the vendor market with new operator entrants. Casual bettor-focused platforms exhibit highest price sensitivity, while exchange operators with professional liquidity pools demonstrate lowest sensitivity due to commission-based rather than vigorish-dependent revenue models.
Supply Chain Analysis
Inventory and lead-time pressures concentrate in real-time geolocation verification hardware and KYC software modules, where demand surges from sequential U.S. state legalizations are outstripping vendor capacity. Supply concentrates in the United States, the United Kingdom, and Israel for core platform infrastructure, with payment processor partnerships drawing from UK-licensed fintechs and U.S. regional banking consortia. Critical dependencies include optical character recognition engines for identity verification, sub-second odds calculation algorithms, and PIX rail integration modules for Brazilian market entry. Single-source vulnerability runs through concentrated banking partnerships for wagering transaction clearing. Distribution runs through API-first platform-as-a-service vendors serving operator white-label deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against social casino and free-to-play gaming platforms that are capturing adjacent engagement pools without regulatory friction, eroding the addressable base for real-money wagering conversion.
For Market Incumbents: Consolidate compliance infrastructure advantages by acquiring specialized KYC technology vendors before federal U.S. framework speculation accelerates vendor valuations. Deepen vertical integration into real-time streaming rights negotiations to lock out competitor access to synchronized in-play betting experiences, defending against exchange-based substitutes.
For New Entrants and Emerging Players: Lead with esports-focused platform architectures targeting Brazil's younger demographic cohorts, where traditional sportsbook brand loyalty remains unformed. Brazil's newly regulated federal framework represents the most penetrable major geography, with PIX-native payment integration serving as the critical go-to-market wedge against incumbent card-dependent onboarding flows.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across real-time geolocation verification sub-segments as U.S. state mandates proliferate. Five-to-ten year viability favors operators with captive compliance technology stacks over asset-light platforms licensing third-party stacks. Acquisition target archetype: mid-tier Brazilian operators with Ministry of Finance licenses and established PIX rail relationships. Signal to watch: U.S. federal legislative momentum toward standardized interstate wagering frameworks.
| Strategic Initiative | Industry Significance |
|---|---|
| Streaming Rights Partnership | Synchronizes live broadcast feeds with in-play betting interfaces, deepening engagement in UK and Australian markets. |
| KYC Technology Acquisition | Captures proprietary identity verification pipelines that accelerate onboarding in fragmented U.S. state jurisdictions. |
| PIX Rail Integration | Enables frictionless deposit flows for Brazil's smartphone-native bettor base under Law 14.790 oversight. |
| Esports Platform Launch | Targets younger demographics with competitive gaming wagering, bypassing saturated traditional sports acquisition channels. |
| Exchange Liquidity Expansion | Builds peer-to-peer matching depth in UK and Australia, capturing higher-margin commission structures than fixed-odd alternatives. |
Methodological Framework
Desk research of regulatory filings, state gaming commission licensing databases, and payment processor partnership disclosures preceded structured interviews with sportsbook platform engineers, compliance technology vendors, state regulatory counsel, and Brazilian Ministry of Finance licensing officials. Primary fieldwork across these stakeholder categories combined with secondary validation against SEC operator filings and state legislative tracking databases. Bottom-up transaction volume modeling triangulated against top-down market sizing from macroeconomic betting participation rates.
Variance-decomposition framing separated volume growth drivers from pricing and margin evolution across the projection horizon. Segmentation dimensions modeled include betting type mechanics, device channel deployment, customer archetype behavior patterns, and payment rail regulatory acceptance tiers. CAGRs were synthesized from trajectory fitting to state-level legalization waves and technology adoption curves. Industry-specific inputs incorporated geolocation verification penetration rates and in-play betting handle expansion patterns.
The analysis sits within stated boundaries; outcomes outside continued state-by-state U.S. legalization momentum or Brazilian federal framework enforcement consistency would require recalibration. Forecasts reflect assumptions regarding mobile penetration trajectories and payment processor policy stability. Revision becomes warranted when federal U.S. wagering preemption legislation crosses committee markup thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Billing and Revenue Management Market
Financial Services
Treasury Management Market
Financial Services
Account Aggregators Market
Financial Services
India Payroll Services Market
Financial Services
Global Automated Algo Trading Market
Financial Services
UK Islamic Finance Market
Financial Services
BFSI Contact Center Analytics Market
Financial Services
Financial Auditing Professional Services Market
Financial Services
Italy Gift Card and Incentive Card Market
Financial Services
Intellectual Property Valuation Market
Financial Services
Online Lottery Market
Financial Services
E-KYC Market
Financial Services
China Factoring Services Market
Financial Services
Europe E-Invoicing Market
Financial Services
Source to Pay Market
Financial Services
Hyperinflation System Market