
 US Urology Devices Market | 2026-2036
US Urology Devices Market Size, Share, and Industry Trends Forecast 2026-2036
US Urology Devices Market Analytics
Buyer concentration among ambulatory surgical centers is shifting as physician-owned specialty practices consolidate into regional platforms. Boston Scientific Corporation leverages its integrated urology portfolio to serve these expanding networks with endoscopic and continence management systems. Fresenius Medical Care AG & Co. KGaA anchors its position through dialysis access and renal care device lines that intersect with urology workflows. Cook Medical specializes in minimally invasive access platforms that compete for placement in high-volume outpatient catheterization labs.
US urology devices encompass diagnostic, therapeutic, and surgical instruments designed for urinary tract and male reproductive system interventions, typically manufactured from biocompatible polymers, stainless alloys, or nitinol with luminal diameters ranging from 3 Fr to 30 Fr depending on anatomical target. These devices serve critical functions in stone fragmentation, tissue resection, stricture dilation, and fluid drainage across inpatient and ambulatory settings. Endoscopy Devices and Robotic Surgery Devices command the dominant value share, with laser-equipped platforms and single-use flexible scopes driving replacement cycles and premium positioning. Catheters represent the highest unit-volume segment but face margin compression from group purchasing organization standardization and domestic manufacturing cost pressures.
FDA 510(k) premarket notification requirements and CMS national coverage determinations jointly shape product development priorities and reimbursement access for novel urology technologies. The FDA's breakthrough devices program creates accelerated pathways for AI-enabled diagnostic scopes and magnetic resonance-guided focal therapy systems, while CMS parallel review processes influence commercial launch sequencing. State-level certificate-of-need regulations in New York and Illinois constrain capital equipment deployment for robotic surgery platforms, creating uneven geographic penetration. Stakeholders must monitor evolving FDA guidance on software-as-a-medical-device classification for urological AI applications and anticipate CMS technology add-on payment decisions that determine hospital adoption economics for next-generation platforms.
Market Dynamics
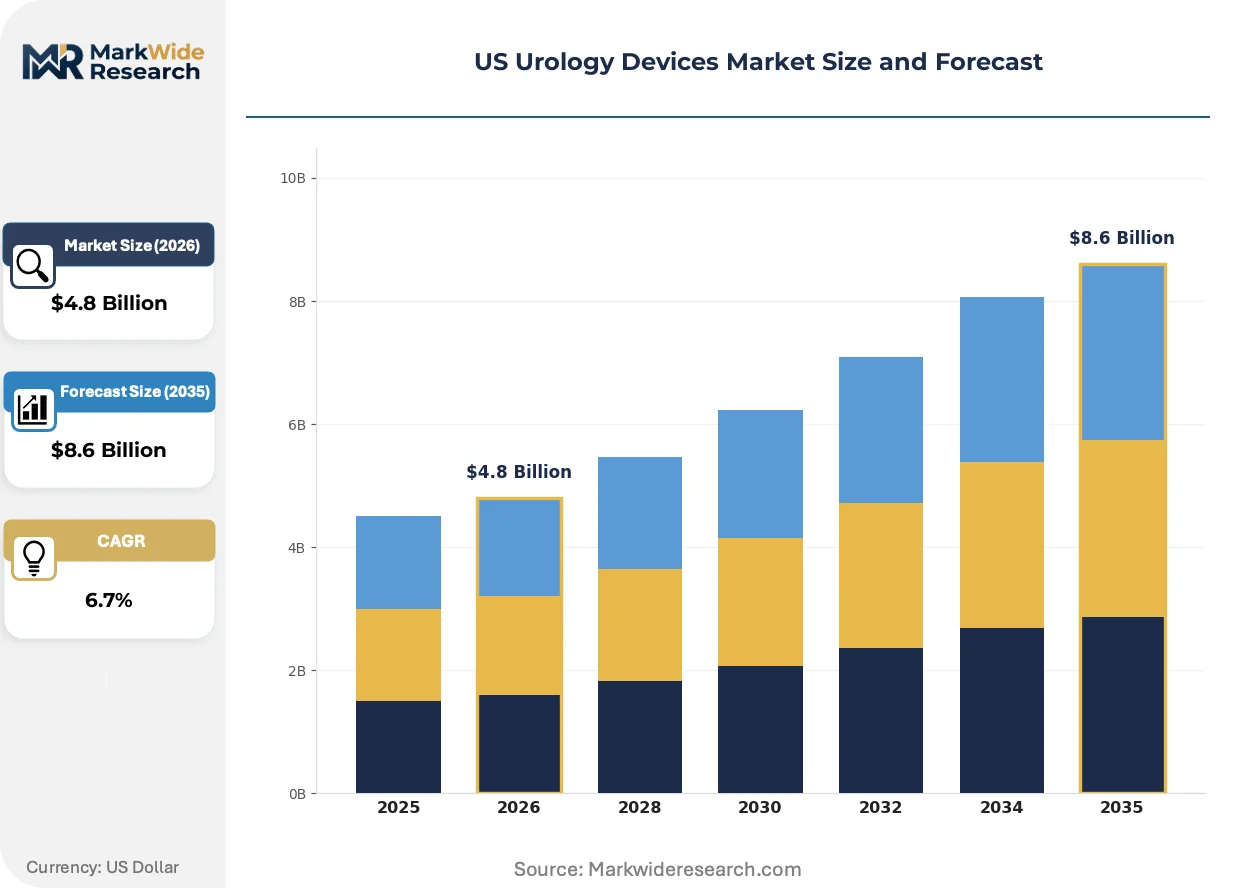
Medicare reimbursement policy is accelerating the migration of urological procedures from hospital inpatient settings to ambulatory surgical centers, compressing capital equipment replacement cycles and reshaping device procurement patterns across the value chain.
Growth Catalysts
- CMS Technology Add-On Payments:Federal reimbursement incentives for breakthrough devices accelerate hospital adoption of next-generation robotic platforms and AI-enabled diagnostic systems.
- Single-Use Flexible Endoscopes:Cross-contamination elimination protocols and sterilization cost reduction drive replacement demand in high-volume outpatient catheterization labs.
- Texas-California-Florida Demand Concentration:Aging demographics and large integrated urology practice networks in these states concentrate procedure volume and device procurement authority.
Market Restraints
- Nitinol Alloy Supply Concentration:Dependence on specialized shape-memory alloy suppliers creates input cost volatility and long-lead constraints for stent and guidewire manufacturers.
- New York and Illinois Certificate-of-Need Laws:State-level capital equipment approval requirements block robotic surgery platform deployment in major metropolitan markets, limiting geographic penetration.
- Reusable Scope Reprocessing Economics:Established capital equipment bases and sunk-cost fallacies slow transition to single-use alternatives despite total cost-of-ownership advantages.
Strategic Opportunities
- Arizona and Nevada Sun Belt Expansion:Retiree population in-migration and certificate-of-need absence create greenfield ambulatory surgical center development corridors with first-mover equipment placement potential.
- AI-Enabled Diagnostic Scope Convergence:Integration of real-time tissue characterization algorithms with flexible cystoscopy platforms creates premium positioning and procedure efficiency gains.
- Physician-Owned Specialty Practice Consolidation:Regional platform formation creates centralized procurement leverage and preferred vendor relationship opportunities for integrated device portfolios.
Industry Challenges
- Software-as-a-Medical-Device Classification Uncertainty:Evolving FDA guidance on AI algorithm validation timelines and predicate device selection creates regulatory submission risk and commercial launch delays.
- Interoperable Data Architecture Integration:Legacy hospital information system compatibility requirements and fragmented electronic health record standards complicate connected device deployment and remote monitoring service rollout.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Urology Devices Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Endoscopy Devices, Robotic Surgery Devices, Surgical Instruments, Catheters End User: Hospitals, Clinics, Ambulatory Surgical Centers, Homecare Settings Application: Prostate Surgery, Stone Management, Incontinence Treatment, UTIs Technology: Laser Technology, Ultrasound Technology, Robotic Technology, Other Technologies |
| Companies Covered | Boston Scientific Corporation, Fresenius Medical Care AG & Co. KGaA, Becton, Dickinson and Company, Olympus Corporation, Stryker Corporation, Intuitive Surgical, Coloplast A/S, Teleflex Incorporated, Cook Medical, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Urology Devices Market Evolving Landscape
Digital health integration and disposable platform economics are converging to redefine clinical workflow efficiency and capital-light service delivery models across urological care settings.
Single-use flexible ureteroscopes are decentralizing stone management procedures from hospital-based surgery centers to office-based labs and ambulatory settings. Urology group practices in Texas and Florida are deploying these platforms at accelerated replacement cycles. The technology is decentralizing procedural authority and compressing the addressable market for capital-intensive reusable systems.
FDA breakthrough device designation pathways are compressing premarket review timelines for magnetic resonance-guided focal therapy systems and AI-enabled diagnostic platforms. The industrial consequence is earlier revenue recognition and competitive positioning advantages for qualifying manufacturers. Robotic surgery device segments are responding by prioritizing predicate device strategies and parallel CMS national coverage determination submissions.
Group purchasing organization standardization is consolidating catheter procurement authority and compressing supplier margins across health system networks. Independent ambulatory surgical centers are responding with direct-to-manufacturer contracting and private-label sourcing arrangements. This pattern is most visible in California, where large integrated delivery networks exert concentrated price leverage on commodity urology consumables.
US Urology Devices Market Segmentation
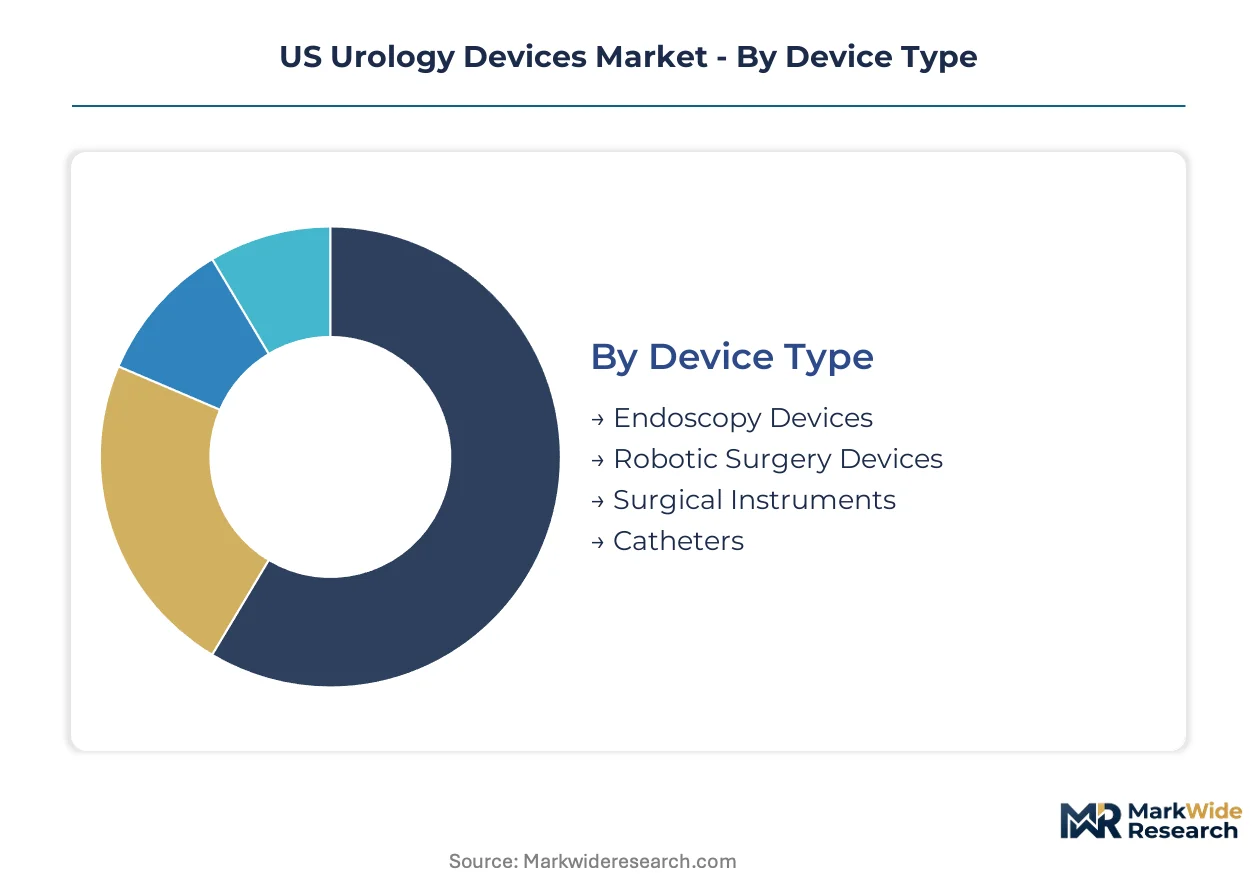
Urology device procurement patterns diverge sharply across clinical settings and technological platforms. Understanding these fault lines reveals where capital deployment concentrates and where margin structures differ most dramatically.
Device Type:
Capital intensity separates the segments most starkly, with robotic platforms requiring multimillion-dollar installations against disposable catheter lines that run on manufacturing scale economies.
- Endoscopy Devices:Flexible and rigid scopes manufactured from biocompatible polymers and fiber-optic bundles deliver visual access across diagnostic and interventional workflows. Demand clusters in Texas and Florida ambulatory surgical centers where stone management procedure volumes justify dedicated cystoscopy suites. Single-use flexible ureteroscopes are compressing replacement cycles as cross-contamination protocols tighten.
- Robotic Surgery Devices:Computer-assisted surgical platforms integrate haptic feedback, 3D visualization, and articulating instrument arms for prostate and renal procedures. California integrated delivery networks anchor installed base expansion, though New York and Illinois certificate-of-need laws block metropolitan deployment. FDA breakthrough device pathways accelerate premarket timelines for next-generation platforms with AI-enabled tissue recognition.
- Surgical Instruments:Resectoscopes, graspers, and stone retrieval baskets manufactured from stainless alloys and nitinol serve open and laparoscopic interventions.
- Catheters:Drainage, intermittent, and Foley catheters in latex and silicone formulations represent the highest unit-volume category with concentrated group purchasing organization price leverage.
Robotic Surgery Devices absorb the bulk of installed capacity; Endoscopy Devices are expanding most quickly.
End User:
Reimbursement economics and procedure complexity create distinct procurement authority patterns across the care continuum.
- Hospitals:Academic medical centers and community hospitals maintain comprehensive urology service lines with capital equipment ownership and in-house sterilization infrastructure. These facilities handle complex oncologic reconstructions and absorb emergency stone complications that exceed ambulatory capabilities. CMS technology add-on payments for breakthrough devices concentrate hospital adoption decisions.
- Ambulatory Surgical Centers:Physician-owned specialty platforms in Arizona and Nevada sun belt corridors are consolidating regional networks and centralizing device procurement leverage. Medicare reimbursement favorability for outpatient urological procedures is accelerating migration from hospital settings. Single-use endoscope economics align with limited sterilization capacity and rapid turnover requirements.
- Clinics:Office-based urology practices handle diagnostic cystoscopy and minor interventions with lower capital thresholds.
- Homecare Settings:Intermittent catheterization and drainage management for neurogenic bladder patients operate on prescription and durable medical equipment reimbursement pathways.
Hospitals retain the deepest capital commitment; Ambulatory Surgical Centers are gaining share fastest.
Application:
Procedure volume distribution and clinical outcome monetization shape segment attractiveness for device manufacturers.
- Stone Management:Ureteroscopic laser lithotripsy and percutaneous nephrolithotomy drive demand for flexible scopes, holmium laser fibers, and access sheaths. Texas and Florida aging demographics concentrate procedure incidence where large urology practice networks enable standardized device protocols. Single-use flexible ureteroscopes are decentralizing stone care from hospitals to office-based labs.
- Prostate Surgery:Robotic-assisted radical prostatectomy and emerging focal therapy platforms command premium device positioning. Magnetic resonance-guided systems with FDA breakthrough designation are compressing commercial launch timelines. California health systems anchor adoption clusters where integrated delivery network purchasing consolidates platform decisions.
- Incontinence Treatment:Sling systems, artificial urinary sphincters, and neuromodulation devices address stress and urge incontinence populations.
- UTIs:Diagnostic catheters and antimicrobial-coated devices target recurrent infection management in outpatient and long-term care contexts.
Stone Management captures the highest procedure velocity; Prostate Surgery commands the steepest technology premium trajectory.
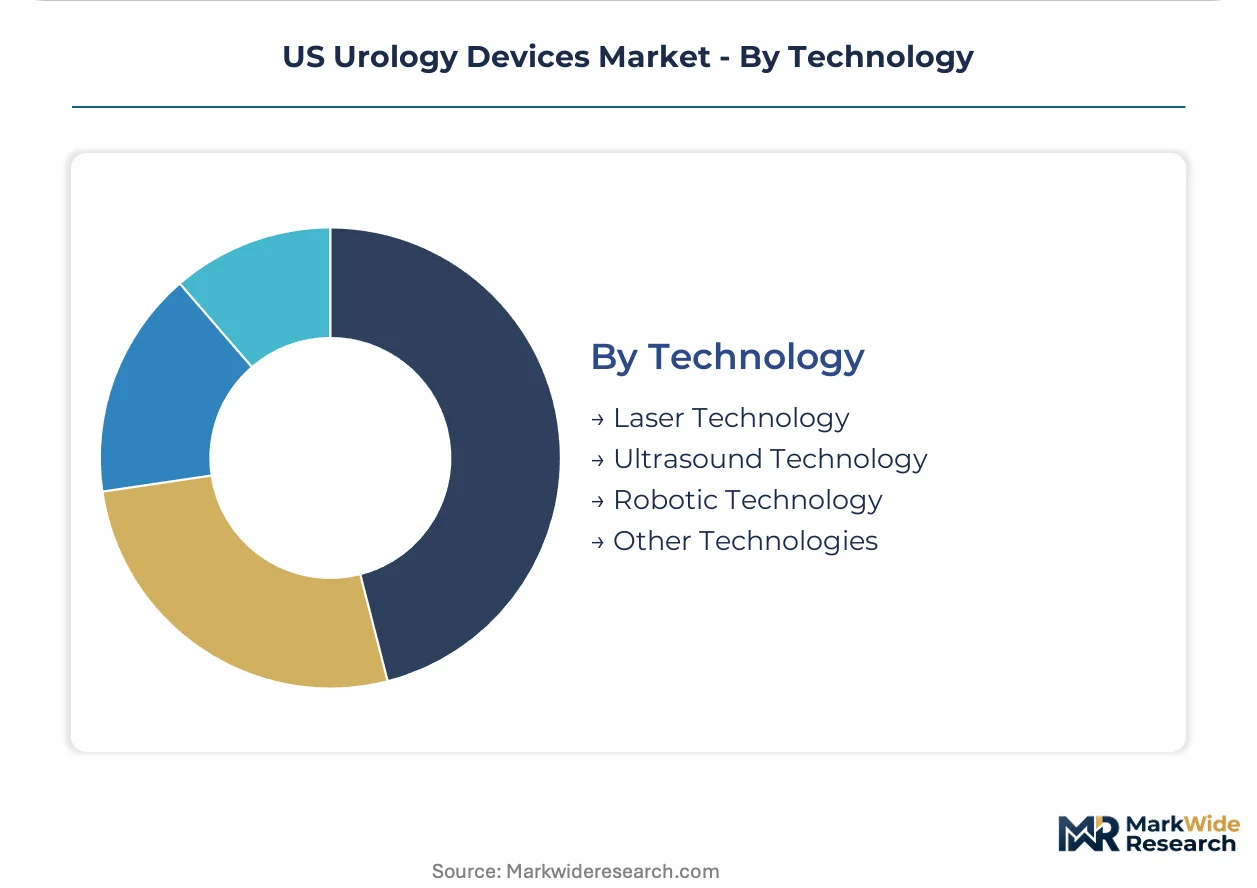
Technology:
Platform differentiation and regulatory pathway complexity segment competitive positioning across energy modalities and automation levels.
- Laser Technology:Holmium and thulium fiber laser systems deliver precise stone fragmentation and soft tissue ablation with minimized thermal spread. Arizona and Nevada ambulatory surgical center expansions are driving portable laser platform placement where space constraints favor compact footprints. Fiber durability and energy efficiency specifications differentiate supplier offerings.
- Robotic Technology:Teleoperated surgical systems integrate instrument articulation, tremor filtration, and 3D visualization for complex pelvic procedures. FDA software-as-a-medical-device guidance evolution creates classification uncertainty for AI-enabled autonomous features. State-level capital equipment regulations in New York and Illinois constrain geographic penetration despite clinical adoption demand.
- Ultrasound Technology:Diagnostic imaging and image-guided intervention platforms serve renal and bladder assessment workflows.
- Other Technologies:Electrosurgical, cryotherapy, and emerging molecular diagnostic platforms fill specialty niches.
Robotic Technology anchors the largest capital deployment; Laser Technology is climbing the fastest on outpatient decentralization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for urology devices concentrates in three Sun Belt states where aging demographics and large integrated practice networks coincide. Texas, Florida, and California absorb disproportionate procedure volume and procurement authority. Geographic expansion corridors are opening in certificate-of-need-free states as Medicare reimbursement accelerates outpatient migration.
Texas
Retiree population growth and oil-wealth medical infrastructure investment drive device procurement concentration. FDA 510(k) clearance pathways enable rapid adoption of single-use endoscope platforms in Dallas and Houston ambulatory surgical centers. Large urology practice networks in the Texas Medical Center corridor standardize procurement protocols across multi-site stone management programs.
Florida
Snowbird migration patterns and Medicare Advantage penetration create sustained demand for prostate and incontinence interventions. State-level ambulatory surgery center licensing reforms expedite facility development in Tampa and Orlando metro areas. Physician-owned specialty platforms in South Florida consolidate regional purchasing leverage for robotic surgery device placement.
California
Integrated delivery networks in Los Angeles and San Francisco Bay Area anchor capital-intensive robotic platform adoption. CMS technology add-on payment eligibility shapes hospital procurement timelines for breakthrough-designated focal therapy systems. Northern California academic medical centers pilot AI-enabled diagnostic scope validation protocols under FDA software-as-a-medical-device guidance.
Arizona
Certificate-of-need absence and retiree in-migration create greenfield ambulatory surgical center development corridors. Phoenix and Tucson metro areas attract first-mover equipment placement for decentralized stone management procedures. Portable holmium laser platforms gain traction where space-constrained facilities favor compact footprints over capital-intensive reusable systems.
Nevada
Las Vegas and Reno healthcare infrastructure expansion targets medical tourism and regional referral catchment. State regulatory permissiveness enables rapid facility licensing compared to neighboring California. Urology group practices deploy single-use flexible scopes at accelerated replacement cycles aligned with limited sterilization capacity.
US Urology Devices Market Competitive Landscape
US-based producers anchor the premium-tier robotic and endoscopy segments; European and Japanese specialists hold entrenched positions in capital equipment and single-use platforms. Market structure tilts toward consolidated procurement authority as ambulatory surgical center networks centralize vendor relationships. Three archetypes dominate: integrated portfolio suppliers spanning diagnostic through surgical platforms, single-technology specialists defending niche positions, and dialysis-access players leveraging renal care intersection. Competitive moves concentrate on preferred vendor contracting with consolidating physician platforms and FDA breakthrough designation pursuit for AI-enabled systems.
Within the integrated portfolio tier, Boston Scientific Corporation and Stryker Corporation exemplify archetypes spanning endoscopic, continence, and stone management platforms. Cook Medical occupies a specialist position in minimally invasive access devices competing for placement in high-volume outpatient catheterization labs. Among dialysis-intersection players, Fresenius Medical Care AG & Co. KGaA anchors renal care device lines that intersect with urology workflows. Intuitive Surgical represents the robotic surgery platform archetype where FDA software-as-a-medical-device classification uncertainty creates competitive positioning stakes for autonomous feature integration.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Fresenius Medical Care AG & Co. KGaA |
| Becton, Dickinson and Company |
| Olympus Corporation |
| Stryker Corporation |
| Intuitive Surgical |
| Coloplast A/S |
| Teleflex Incorporated |
| Cook Medical |
| Others |
Value Network & Pricing Analysis
Nitinol alloy spot pricing volatility cascades through stent and guidewire manufacturing tiers, compressing margins at mid-market suppliers while premium robotic platform vendors absorb input shocks through service bundling. Three-tier pricing structure across premium, standard, and economy levels stratifies procurement authority between academic medical centers, consolidated ambulatory networks, and independent clinics.
Pricing Analysis
Volume-margin splits concentrate unit economics at opposite ends: catheters run on manufacturing scale economies with group purchasing organization price compression, while robotic platforms command multimillion-dollar installations with recurring service revenue. Price differentiation hinges on FDA breakthrough designation status and sterilization validation tier. Cost compression in the catheter segment intensifies as domestic manufacturing wage pressures intersect with GPO consolidation. Independent ambulatory surgical centers exhibit highest price sensitivity; integrated delivery networks in California demonstrate lowest sensitivity due to bundled procurement authority.
Supply Chain Analysis
Regional distribution centers in Texas and Florida anchor hub-and-spoke patterns serving Sun Belt ambulatory surgical center networks with 48-hour replenishment cycles. Nitinol alloy supply concentrates in Japan and Germany; polymer resin feedstocks draw from Texas and Louisiana petrochemical corridors. Single-source vulnerability in shape-memory alloy suppliers creates long-lead constraints for stent manufacturers. Distribution runs through manufacturer-direct field inventory programs for capital equipment and third-party medical distributors for consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
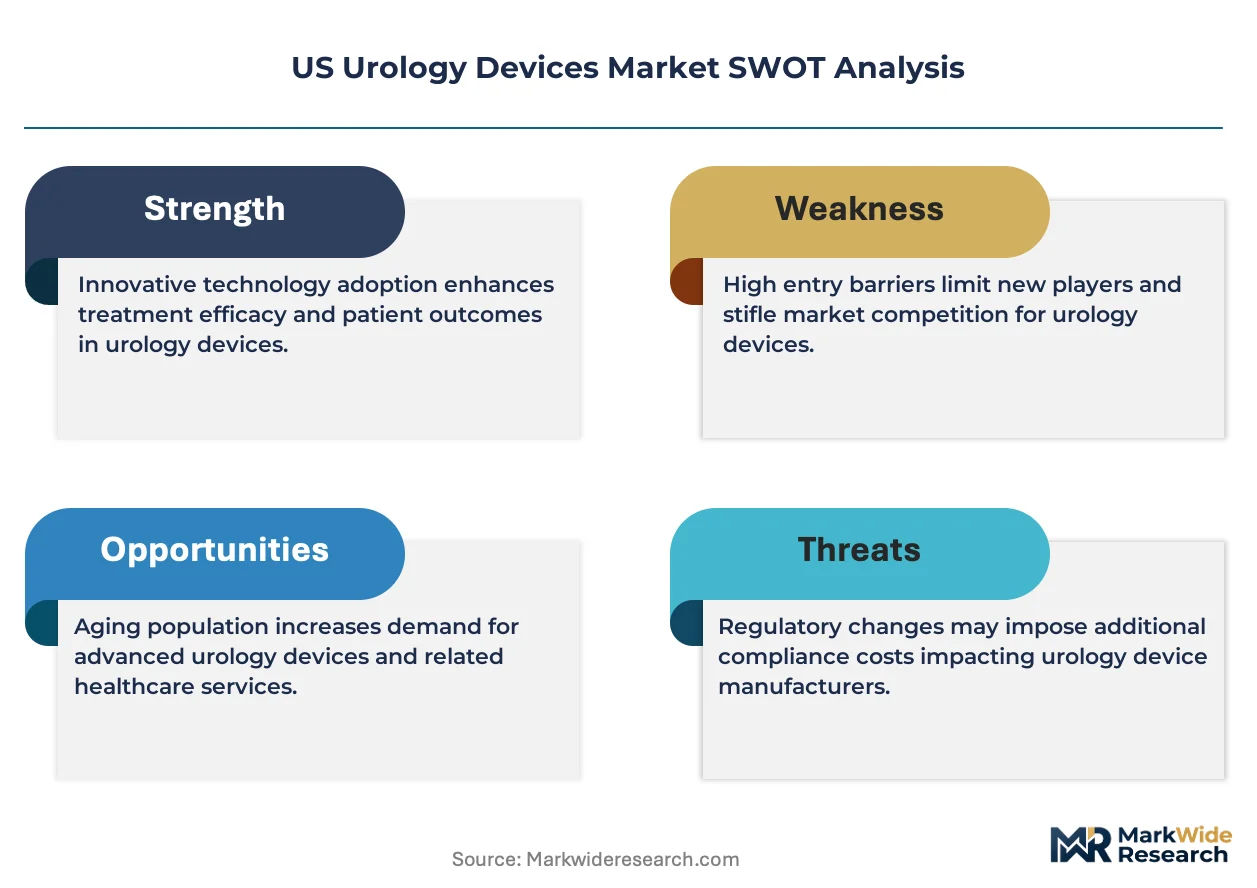
The US urology devices market sits in a technology-transition phase as single-use flexible endoscopes displace capital-intensive reusable systems. This substitution is compressing replacement cycles and decentralizing procedural authority from hospital surgery centers to office-based labs.
For Market Incumbents: Acquire single-use endoscope manufacturing capacity in Arizona or Nevada sun belt corridors to preempt ambulatory surgical center procurement consolidation. Defend against GPO price compression by embedding AI-enabled diagnostic software into scope platforms, creating switching costs through workflow integration. Backward integration into nitinol alloy sourcing hedges input volatility for stent and guidewire portfolios. For New Entrants and Emerging Players: FDA breakthrough device designation in the United States opens a window for AI-enabled tissue characterization platforms targeting prostate focal therapy. White-space concentrates in certificate-of-need-free states where greenfield ambulatory surgical center development outpaces incumbent coverage. Target Arizona and Nevada with portable holmium laser platforms optimized for space-constrained facilities lacking sterilization infrastructure. For Investors and Strategic Acquirers: Distressed-cycle entries favor physician-owned specialty practice platforms in Texas and Florida with centralized procurement leverage and underutilized robotic installed base. Long-term viability hinges on reimbursement policy continuity favoring outpatient migration. Watch CMS technology add-on payment decisions for focal therapy systems as the inflection signal for next-generation platform adoption economics.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Designation Pursuit | Accelerates premarket timelines for AI-enabled diagnostic scopes competing against predicate devices. |
| Single-Use Endoscope Manufacturing Scale-Up | Captures replacement cycle compression as cross-contamination protocols tighten in outpatient labs. |
| Physician-Owned Practice Platform Acquisition | Consolidates regional procurement leverage for preferred vendor contracting in sun belt corridors. |
| Software-as-a-Medical-Device Validation Investment | Addresses FDA classification uncertainty for autonomous tissue recognition features in robotic platforms. |
| Reimbursement Strategy Alignment with CMS | Secures technology add-on payment eligibility for hospital adoption of next-generation focal therapy systems. |
Research Methodology
Independent corroboration across hospital purchasing committee interviews, GPO contracts managers, and biomedical engineers underwrites the qualitative findings in this study. Primary fieldwork with ambulatory surgical center administrators and urology practice executives combined with secondary validation from FDA 510(k) filings, CMS national coverage determinations, and hospital procurement databases. Bottom-up demand modeling across device type, end user, and application segments triangulates against top-down market sizing from trade flow analysis.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions span device type, end user setting, clinical application, and energy modality, with geographic regulatory cluster as an additional modeling layer. CAGRs derive from procedure volume forecasting tied to demographic projections and reimbursement policy trajectories. Forecast inputs incorporate Medicare Advantage penetration rates and certificate-of-need regulatory status by state.
Caveats apply where FDA software-as-a-medical-device guidance evolution or nitinol alloy supply disruptions could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Non-Metastatic Castration-Resistant Prostate Cancer (NMCRPC) Therapeutics Market
Urology
Prostate Cancer Minimally Invasive Surgery Market
Urology
Prostate Cancer Treatment Market
Urology
Global Benign Prostatic Hyperplasia Treatment Market
Urology
Urinary Bag Market
Urology
Self-Intermittent Catheters Market
Urology
Uropathy Treatment Market
Urology
North America Transrectal Ultrasound Market
Urology
Hematuria Treatment Market
Urology
Global Nephrology and Urology Devices Market
Urology
Obstructive Uropathy Treatment Market
Urology
Catheter-Associated Urinary Tract Infections Treatment Market
Urology
Benign Prostatic Hyperplasia Market
Urology
Urinary Tract Infection (UTI) Market
Urology
Global Hydronephrosis Market
Urology
Global Lithotripsy Market