
 Transient Elastography Device Market | 2026-2036
Transient Elastography Device Market Size, Share, and Industry Trends Forecast 2026-2036
Transient Elastography Device Market Analytics
Equipment leasing and pay-per-scan service contracts is rewriting capital deployment for mid-sized diagnostic networks. Echosens leverages its installed base of FibroScan systems to sustain recurring revenue from disposable probes and software subscriptions. Fujifilm Holdings anchors its hepatology portfolio through integrated ultrasound-elastography platforms that compete across Asia-Pacific hospital tenders. Siemens Healthineers differentiates via dual-modality systems combining magnetic resonance elastography with conventional imaging workflows.
Transient elastography devices measure tissue stiffness by tracking shear wave propagation speed, typically quantified in kilopascals (kPa) to grade fibrosis severity without biopsy extraction. Portable devices dominate unit shipments by enabling point-of-care liver assessment in clinics lacking dedicated imaging suites, while fixed systems capture premium pricing in tertiary hospital radiology departments. Ultrasound-based elastography leads technological adoption for routine screening, whereas magnetic resonance imaging elastography occupies the high-accuracy segment for complex hepatic cases and clinical research protocols.
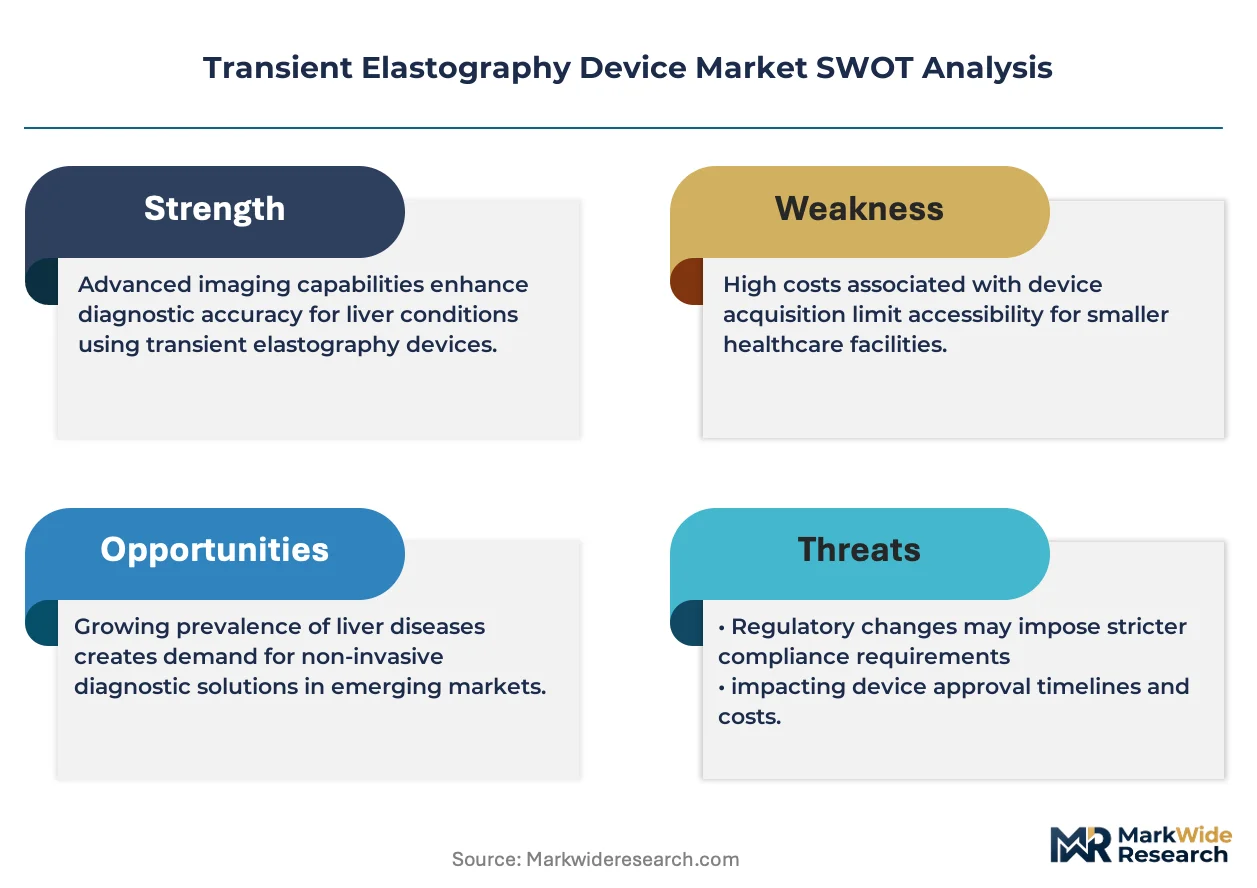
FDA 510(k) premarket notifications and the EU Medical Device Regulation (MDR) impose escalating clinical evidence requirements on algorithm-driven stiffness quantification software. Japan's PMDA maintains distinct technical standards for acoustic radiation force impulse systems that delay foreign manufacturer market entry. Stakeholders must monitor reimbursement code fragmentation across Medicare, national health systems, and private payers to determine where device placement yields sustainable procedure economics.
Market Dynamics
Shear wave elastography software validation requirements under tightening FDA 510(k) pathways are forcing manufacturers to restructure clinical evidence generation, compressing development timelines while elevating R&D spend for algorithm-driven fibrosis quantification systems.
Growth Catalysts
- Chronic Liver Disease Screening Mandates:Germany's national hepatitis C elimination program and Japan's metabolic-associated steatotic liver disease surveillance protocols are institutionalizing non-invasive diagnostic workflows across outpatient networks.
- EU MDR Harmonization:The Medical Device Regulation's unified clinical evidence standards are reducing fragmentation for shear wave elastography systems seeking multi-country hospital tenders.
- Point-of-Care Device Miniaturization:Battery-powered handheld units with integrated probe calibration are enabling liver stiffness assessment in primary care clinics lacking radiology infrastructure.
Market Restraints
- Probe Consumable Cost Concentration:Single-use disposable transducer elements represent 35-45% of lifetime device economics, creating margin pressure for high-volume screening programs.
- Magnetic Resonance Elastography Substitution:Hospital systems with installed MRI bases increasingly route complex hepatic cases to MRE workflows, constraining ultrasound-elastography pricing power in tertiary settings.
- PMDA Technical Barrier:Japan's distinct acoustic radiation force impulse certification requirements impose 18-24 month approval delays versus FDA-cleared device timelines.
Strategic Opportunities
- India Diagnostic Network Expansion:Tier-2 and Tier-3 city hospital procurement under Ayushman Bharat insurance coverage is creating first-mover positioning for portable elastography deployment.
- Artificial Intelligence-Assisted Staging:Machine learning integration with shear wave propagation algorithms promises automated fibrosis scoring that reduces operator-dependent measurement variability.
- Ambulatory Surgery Center Channel:Medicare reimbursement code expansion for non-hospital liver assessment is unlocking device placement in outpatient surgical networks previously restricted to inpatient radiology.
Industry Challenges
- Specialized Sonographer Training Bottleneck:Accurate shear wave acquisition requires 40-60 hours of certified operator training, constraining deployment velocity in markets with limited hepatology imaging specialists.
- Legacy PACS Integration Complexity:Hospital IT departments face 6-9 month integration timelines to embed elastography workstations into existing radiology workflow systems and electronic health record architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transient Elastography Device Market |
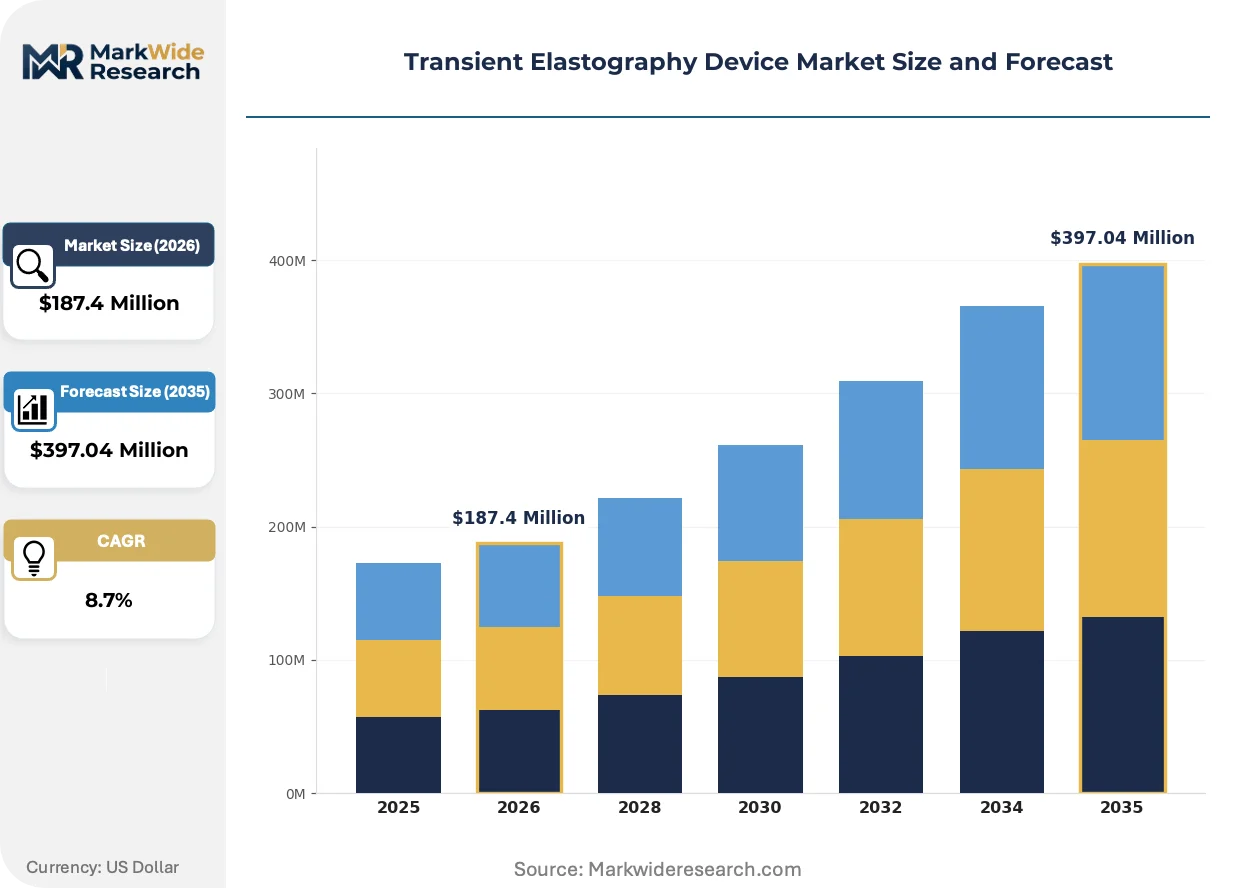
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Devices, Fixed Devices, Handheld Devices, Software Solutions End User: Hospitals, Clinics, Research Laboratories, Diagnostic Centers Technological Feature: Ultrasound-Based, Magnetic Resonance Imaging, Acoustic Radiation Force Impulse, Optical Coherence Tomography Application: Liver Disease Assessment, Fibrosis Assessment, Hepatic Steatosis Evaluation, Clinical Research |
| Companies Covered | Canon Medical Systems, Mindray Medical, Echosens, SuperSonic Imagine, Fujifilm Holdings, GE HealthCare, Philips, Wuxi HISKY Medical Technologies, Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transient Elastography Device Market Evolving Landscape
Algorithmic stiffness quantification and disposable probe economics are compressing traditional capital equipment business models while elevating software-centric recurring revenue streams across diagnostic networks.
Multi-frequency shear wave generation is rendering obsolete single-point measurement devices that cannot discriminate between fibrosis stages in obese patients or those with ascites. Tertiary hospital radiology departments in the United States and Germany are prioritizing these systems for bariatric liver assessment protocols. The technology is rendering obsolete prior-generation devices that required repeated scans to achieve diagnostic confidence.
The EU Medical Device Regulation's post-market surveillance requirements are mandating real-world performance data collection for algorithm-driven diagnostic software. Manufacturers must now maintain active safety monitoring systems that track measurement accuracy across diverse patient populations. Ultrasound-elastography platforms with embedded quality assurance protocols are capturing preferential positioning in European hospital procurement tenders.
Service-based contracting is displacing outright equipment purchase across mid-sized diagnostic networks seeking to align capital outflows with procedure volumes. Pay-per-scan arrangements with minimum volume commitments are proliferating in United States outpatient clinic chains. This model concentrates most visibly in ambulatory settings where seasonal screening demand fluctuations make fixed capital burdens economically unattractive.
Transient Elastography Device Market Segmentation
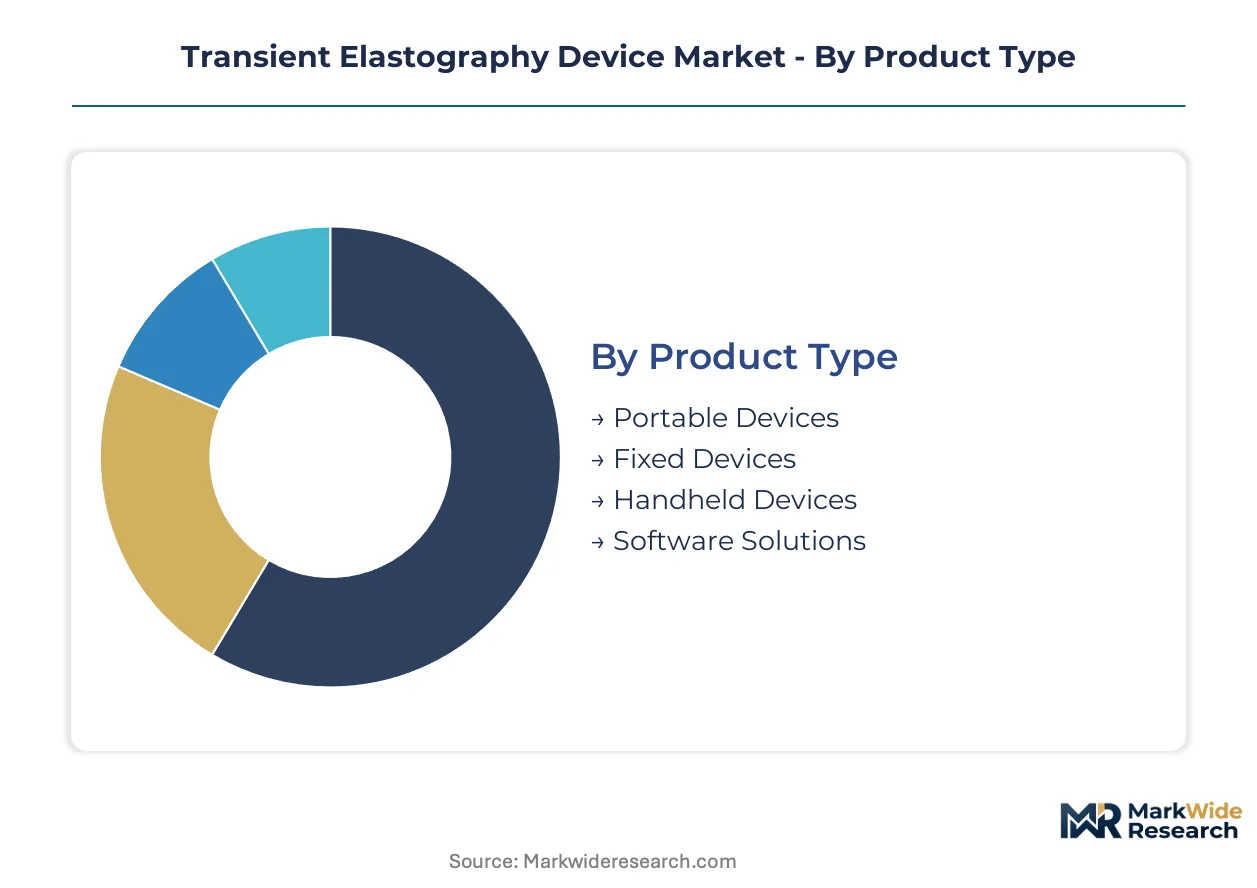
Device form factor and procurement economics determine capital deployment cycles across outpatient networks. Technology modality selection hinges on reimbursement codes and specialist availability in target geographies.
Product Type:
Portable systems turn inventory fastest in mobile screening programs, while fixed installations anchor decade-long depreciation schedules in tertiary radiology departments.
- Portable Devices:Battery-powered units with integrated probe calibration enable point-of-care liver assessment in clinics lacking dedicated imaging suites. Primary care networks in Germany and Japan deploy these for hepatitis C elimination program outreach, though probe consumable costs concentrate lifetime economics.
- Fixed Devices:Trolley-mounted systems with multi-frequency shear wave generation capture premium pricing in hospital radiology departments. United States tertiary centers prioritize these for bariatric liver assessment protocols where single-point measurement devices fail in obese patients.
- Handheld Devices:Pocket-sized units with simplified interfaces target nurse-operated screening workflows in resource-constrained settings.
- Software Solutions:Algorithm-driven stiffness quantification platforms with embedded quality assurance protocols capture recurring revenue through subscription licensing.
Portable devices anchor the volume base while software solutions gain share at the steepest rate.
End User:
Procurement authority concentrates with radiology department heads in hospital systems, while clinic chains prioritize service-based contracting to align capital outflows with procedure volumes.
- Hospitals:Tertiary radiology departments in the United States and Germany route complex hepatic cases through integrated PACS workflows, demanding six-to-nine month IT integration timelines for elastography workstation embedding.
- Clinics:Outpatient chains under Medicare reimbursement code expansion seek pay-per-scan arrangements with minimum volume commitments to avoid fixed capital burdens during seasonal screening fluctuations.
- Research Laboratories:Academic medical centers with NIH or EU Horizon funding drive magnetic resonance elastography adoption for clinical trial endpoints.
- Diagnostic Centers:Independent imaging facilities in India's Tier-2 and Tier-3 cities under Ayushman Bharat coverage create first-mover positioning for device deployment.
Hospitals dominate installed base value while diagnostic centers climb the fastest as outpatient networks expand.
Technological Feature:
Ultrasound-based systems achieve broadest reimbursement coverage, while magnetic resonance modalities command highest per-procedure pricing in complex case routing.
- Ultrasound-Based:Shear wave elastography with real-time B-mode imaging dominates routine screening volumes across outpatient networks. FDA 510(k) premarket notifications and EU MDR harmonization impose escalating clinical evidence requirements on algorithm-driven stiffness quantification.
- Magnetic Resonance Imaging:MRE workflows with dual-modality integration capture complex hepatic cases in hospital systems with installed MRI bases, constraining ultrasound-elastography pricing power in tertiary settings.
- Acoustic Radiation Force Impulse:ARFI systems face PMDA technical barriers in Japan with eighteen-to-twenty-four month approval delays versus FDA-cleared timelines.
- Optical Coherence Tomography:OCT-based elastography remains confined to ophthalmology crossover applications and preclinical hepatic research protocols.
Ultrasound-based systems anchor the volume base while magnetic resonance imaging gains share at the steepest rate in tertiary settings.
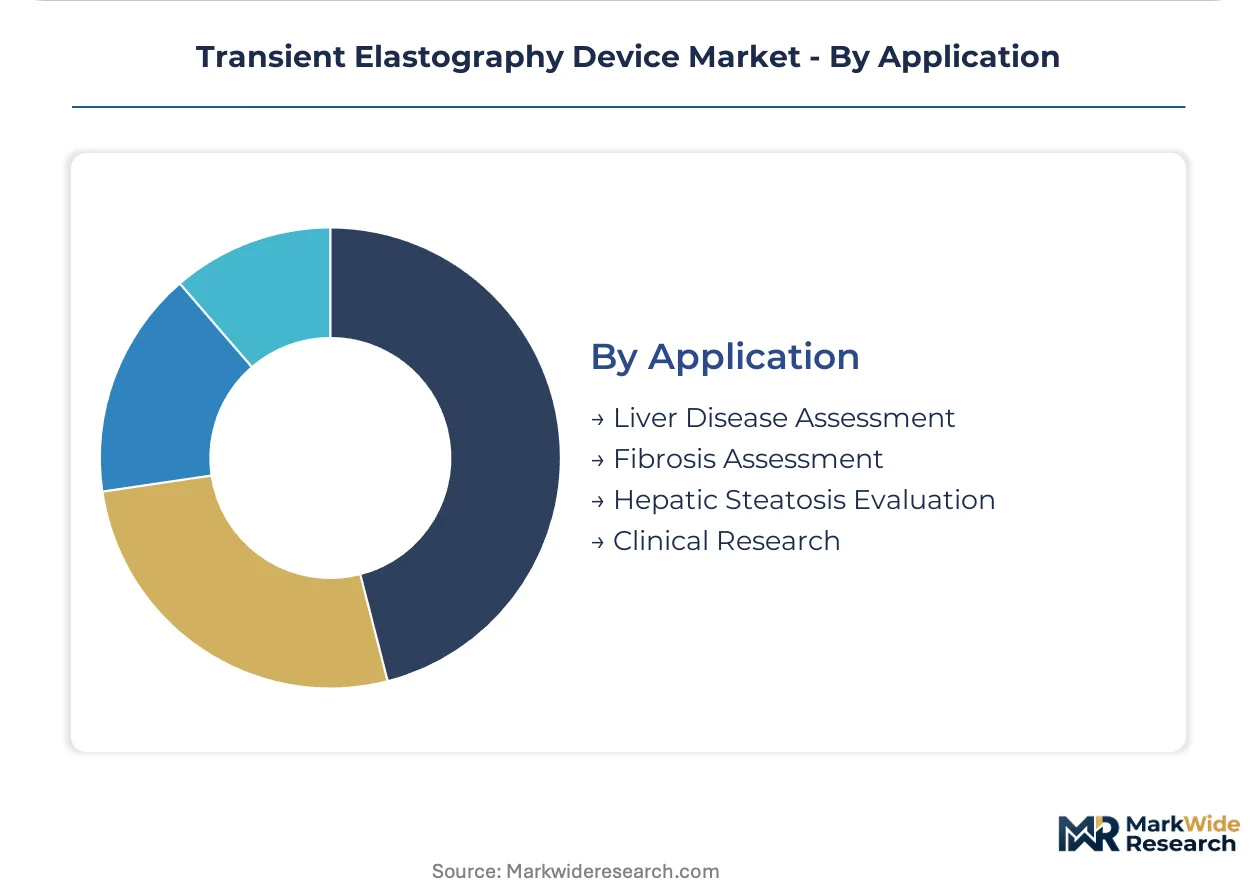
Application:
Liver disease screening commands highest procedure frequency, while clinical research applications sustain premium pricing through grant-funded procurement.
- Liver Disease Assessment:Non-invasive staging of chronic hepatitis and cirrhosis drives majority procedure volumes across screening programs. Germany's national hepatitis C elimination program and Japan's metabolic-associated steatotic liver disease surveillance protocols institutionalize these workflows.
- Fibrosis Assessment:Kilopascal quantification for fibrosis grading without biopsy extraction represents core value proposition for hepatology referral pathways.
- Hepatic Steatosis Evaluation:Fat fraction measurement alongside stiffness quantification addresses metabolic syndrome surveillance in bariatric patient populations.
- Clinical Research:Pharmaceutical trials for NASH therapeutics drive demand for standardized MRE endpoints with centralized reading protocols.
Liver disease assessment anchors the volume base while clinical research expands most quickly on NASH drug development funding.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in transient elastography devices favor established manufacturing bases in Germany, Japan, and the United States, while procurement demand concentrates in health systems with dedicated liver disease screening programs and favorable reimbursement frameworks.
United States
Medicare reimbursement code expansion for non-invasive liver assessment drives ambulatory surgery center procurement. FDA 510(k) premarket notifications impose escalating software validation requirements on shear wave elastography systems. The Mayo Clinic Rochester campus and Cleveland Clinic anchor tertiary radiology adoption for bariatric liver protocols.
Germany
The national hepatitis C elimination program institutionalizes non-invasive diagnostic workflows across outpatient networks. EU Medical Device Regulation harmonization reduces fragmentation for multi-country hospital tenders. Berlin and Munich hospital procurement clusters prioritize integrated PACS-compatible elastography workstations.
Japan
Metabolic-associated steatotic liver disease surveillance protocols create sustained demand for point-of-care assessment tools. PMDA maintains distinct technical standards for acoustic radiation force impulse systems that delay foreign manufacturer entry. Tokyo and Osaka metropolitan hospital networks drive premium fixed-system installations.
India
Ayushman Bharat insurance coverage expands procurement in Tier-2 and Tier-3 city hospitals for first-mover portable device deployment. CDSCO regulatory pathways for ultrasound-based diagnostic equipment streamline import licensing for established manufacturers. Hyderabad and Bangalore diagnostic center clusters adopt handheld units for nurse-operated screening workflows.
China
NMPA approval timelines for shear wave elastography software compress as domestic manufacturers accelerate algorithm development. Dual carbon goals in healthcare infrastructure favor energy-efficient portable systems in rural clinic networks. Shanghai and Guangzhou tertiary hospitals anchor demand for multi-frequency systems in bariatric assessment protocols.
Transient Elastography Device Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in probe and algorithm supply. The vendor base stratifies across three tiers: multinational imaging conglomerates with dual-modality portfolios, mid-scale ultrasound specialists with hepatology-focused platforms, and emerging handheld manufacturers attacking price-sensitive segments. Consolidation pressure intensifies as software-centric recurring revenue models displace pure equipment sales. Dominant competitive moves include strategic partnerships for AI-assisted staging integration and geographic licensing arrangements to bypass PMDA approval delays.
Among European-origin platform developers, Echosens and SuperSonic Imagine exemplify the hepatology-specialist archetype with recurring revenue architectures. Siemens Healthineers and GE HealthCare occupy the diversified imaging conglomerate tier with dual-modality system integration. Fujifilm Holdings represents the Asia-Pacific integrated platform strategy, while Wuxi HISKY Medical Technologies anchors the Chinese domestic manufacturer position in portable device segments.
| Leading Market Players |
|---|
| Canon Medical Systems |
| Mindray Medical |
| Echosens |
| SuperSonic Imagine |
| Fujifilm Holdings |
| GE HealthCare |
| Philips |
| Wuxi HISKY Medical Technologies |
| Siemens Healthineers |
| Others |
Value Network & Pricing Analysis
German and Japanese probe component suppliers anchor upstream margin concentration, with disposable transducer elements capturing 35-45% of lifetime device economics and dictating downstream pricing power for system manufacturers.
Pricing Analysis
Hospital procurement committees anchor three-tier pricing structure across premium, standard, and economy levels for transient elastography systems. Price differentiation stems from FDA 510(k) certification tier and multi-frequency shear wave capability. Cost compression in mid-sized diagnostic networks is intensifying because pay-per-scan service contracts displace capital purchases. Outpatient clinic chains exhibit highest price sensitivity versus tertiary radiology departments with dedicated imaging budgets.
Supply Chain Analysis
Extended payment terms from German probe manufacturers to Asian assembly facilities are reshaping working capital requirements across the value chain. Component sourcing draws from Germany, Japan, and China for piezoelectric crystals, signal processing chipsets, and precision acoustic housings. Single-source vulnerability in FDA-validated algorithm software creates regulatory concentration risk. Distribution runs through regional imaging equipment distributors with GPO contracts for hospital system access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Transient elastography is a high-growth disruption propelled by EU MDR harmonization compressing multi-country approval timelines and accelerating software-centric recurring revenue models.
For Market Incumbents: Entrench installed base loyalty through backward integration into probe manufacturing and captive supply of disposable transducer elements. Accelerate AI-assisted staging R&D to defend against magnetic resonance elastography substitution in tertiary settings. Deepen PACS integration partnerships to extend six-to-nine month IT embedding timelines into switching costs. For New Entrants and Emerging Players: Pursue India's Tier-2 and Tier-3 diagnostic center expansion under Ayushman Bharat coverage as the most penetrable geography. Target handheld device segments for nurse-operated screening workflows with simplified calibration protocols. Deploy direct sales teams to bypass established distributor relationships in price-sensitive outpatient markets. For Investors and Strategic Acquirers: Capital is best deployed toward algorithm-driven software platforms with embedded quality assurance protocols and recurring subscription revenue. Five-to-ten year viability favors vendors with FDA 510(k) clearance momentum and EU MDR technical documentation completeness. Monitor PMDA approval timeline compression for acoustic radiation force impulse systems as inflection indicator for Japan market entry economics.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Software validation requirements are tightening premarket notification pathways for algorithm-driven fibrosis quantification systems. |
| CE Marking Pathway | EU MDR harmonization reduces fragmentation for shear wave elastography systems seeking multi-country hospital tenders. |
| Hospital System Partnership | Integrated PACS-compatible workstations capture six-to-nine month IT embedding timelines in tertiary radiology departments. |
| Software Companion Development | Machine learning integration promises automated fibrosis scoring that reduces operator-dependent measurement variability. |
| Reimbursement Strategy | Medicare code expansion for non-hospital liver assessment unlocks ambulatory surgery center device placement. |
Research Methodology
Initial hypotheses were tested against primary input from hepatology clinicians, hospital purchasing committee members, biomedical engineers, and GPO contracts managers and refined through secondary validation against FDA 510(k) filings, EU MDR technical documentation, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up demand modeling from procedure volumes and top-down market sizing from manufacturer revenue disclosures were triangulated for consistency.
Demand-supply balance across the projection horizon was assessed through segmentation across device form factor, end-user procurement authority, technological modality, and application indication. CAGRs were derived from fitted growth curves anchored to screening program enrollment trajectories and reimbursement code expansion schedules. Forecast inputs incorporated PMDA approval timeline differentials and probe consumable cost concentration effects.
The forecast holds incumbent behavior within observed patterns; aggressive moves by handheld device manufacturers or AI-platform entrants would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Chronic Total Occlusion Devices Market
Medical Devices
US Digital Pregnancy Test Kits Market
Medical Devices
Next Generation Implants (NGI) Market
Medical Devices
Table-Top Autorefractor Market
Medical Devices
United States Implantable Medical Devices Market
Medical Devices
Tattoo Removal Devices Market
Medical Devices
Transcutaneous Oximetry Systems Market
Medical Devices
Digital Blood Pressure Monitors Market
Medical Devices
Veterinary Ultrasound Scanners Market
Medical Devices
Medical Devices Clinical Trials Market
Medical Devices
Peripheral Nerve Stimulators Market
Medical Devices
Global Embolization Particle Market
Medical Devices
Ingestible Smart Pills Market
Medical Devices
Antibiotic-Loaded Bone Cement Market
Medical Devices
Medical Puncture Navigation Robot Market
Medical Devices
Micro Balloon Catheter Market