
 Single Use Cystoscope Market | 2026-2036
Single Use Cystoscope Market Size, Share, and Industry Trends Forecast 2026-2036
Single Use Cystoscope Market Outlook
Hospital procurement is fragmenting as ambulatory surgical centers and urology clinics build direct relationships with manufacturers, bypassing traditional distributor tiers. Ambu A/S leverages its disposable endoscopy platform to sustain volume leadership across European outpatient networks. Karl Storz competes through rigid optical specialization and backward integration into lens manufacturing. Olympus Corporation anchors hospital system contracts with bundled service agreements that lock in multi-year supply commitments.
A single use cystoscope is a sterile, disposable endoscopic instrument featuring a CMOS or CCD image sensor, LED illumination, and a working channel of 6–10 French diameter, manufactured through polymer molding and micro-assembly for one-time urethral and bladder examination without reprocessing. Flexible cystoscopes capture the fastest-growing application share as urologists shift diagnostic workload to office-based settings where sterilization infrastructure is limited. Digital cystoscopes command premium positioning through integrated image processing and wireless connectivity, while rigid variants retain dominance in operative lithotripsy and stent placement where instrument stability is paramount. Pediatric cystoscopes occupy a narrow but protected margin pool given dimensional constraints and specialized training requirements.
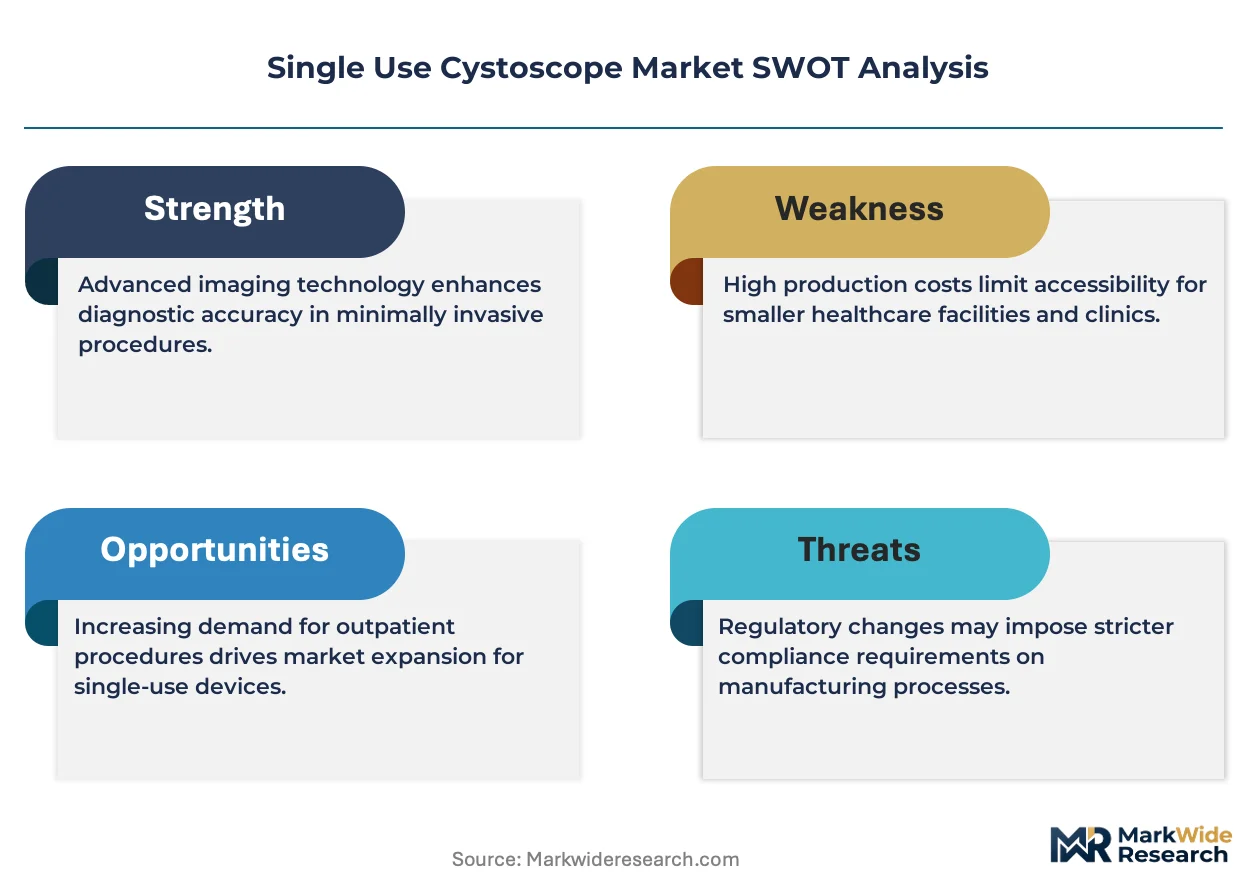
FDA 510(k) premarket notification, EU MDR Class IIa certification, and ISO 13485 quality management standards govern device approval, sterilization validation, and post-market surveillance, raising capital barriers for new entrants while rewarding incumbent documentation depth. Japan's PMDA and South Korea's MFDS impose additional clinical data requirements that extend registration timelines and favor manufacturers with established Asian regulatory affairs capacity. Stakeholders must monitor reimbursement parity between single-use and reusable cystoscopy procedures as payer cost-comparison studies reshape procurement authority across health systems.
Market Dynamics
Hospital sterilization infrastructure constraints and cross-contamination liability exposure are accelerating procurement migration toward sterile, ready-to-use cystoscope designs that eliminate reprocessing workflows entirely.
Growth Catalysts
- EU MDR Class IIa certification pathways:Streamlined conformity assessment procedures for sterile single-use devices reduce time-to-market for manufacturers with established quality management systems under ISO 13485.
- Ambulatory surgical center expansion:United States outpatient facilities lacking autoclave capacity drive volume conversion from reusable to disposable platforms for diagnostic cystoscopy procedures.
- CMOS sensor cost compression:Semiconductor manufacturing scale economies enable high-definition imaging at price points viable for single-use economics.
Market Restraints
- Polymer resin price volatility:Medical-grade polycarbonate and thermoplastic elastomer input costs compress margin structures for manufacturers without backward integration into compound supply.
- East Asian component concentration:LED illumination modules and micro-optical assemblies source predominantly from South Korea and Taiwan, creating geographic supply vulnerability.
- Reusable cystoscope durability:Karl Storz and Olympus rigid optical platforms deliver 500+ use cycles, establishing total-cost-of-ownership benchmarks that disposable alternatives must undercut.
Strategic Opportunities
- Japan PMDA registration:Extended clinical data requirements favor manufacturers with established Tokyo regulatory affairs capacity, creating protected margin pools for compliant entrants.
- Pediatric dimensional specialization:Narrower working channel designs for neonatal and pediatric urology command premium positioning given limited supplier base and specialized training requirements.
- Wireless connectivity convergence:Integration of Bluetooth Low Energy transmission with tablet-based image processing eliminates proprietary tower hardware and expands office-based deployment.
Industry Challenges
- ISO 13485 audit intensity:Notified body scrutiny of sterilization validation documentation extends certification timelines and strains quality assurance staffing.
- Legacy hospital capital depreciation:Sunk investment in reprocessing equipment and sterilization infrastructure creates switching friction among health system procurement committees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single Use Cystoscope Market |
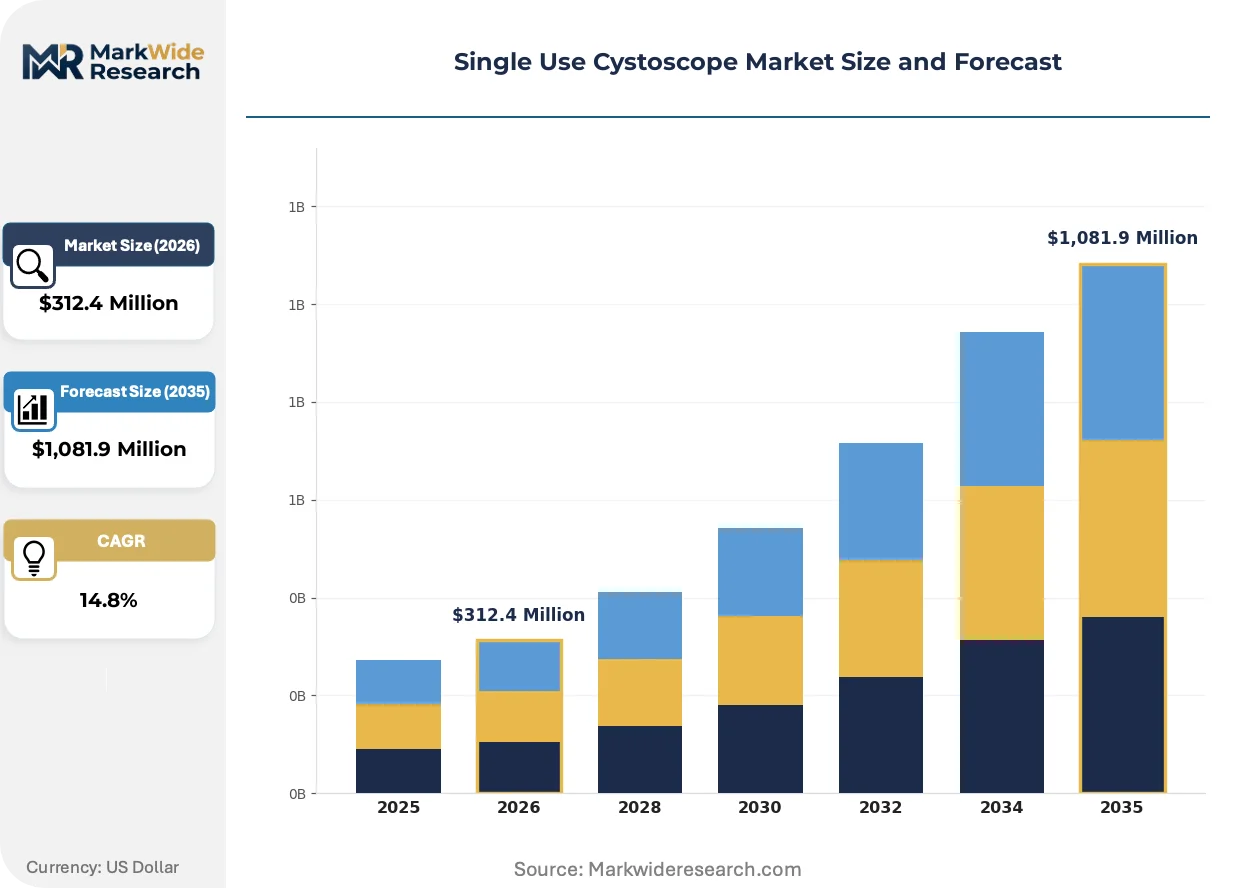
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $1,081.9 Million |
| CAGR (2026 – 2036) | 14.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Cystoscope, Flexible Cystoscope, Pediatric Cystoscope, Digital Cystoscope End User: Hospitals, Clinics, Ambulatory Surgical Centers, Urology Centers Application: Diagnosis, Treatment, Surgical Procedure, Imaging Distribution Channel: Direct Sales, Wholesalers, Online Retail, Distributors |
| Companies Covered | Olympus Corporation, UroViu Corporation, Ambu A/S, Richard Wolf, NeoScope Inc., Karl Storz, Coloplast Group, Stryker Corporation, Boston Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single Use Cystoscope Market Strategic Shifts
Digital imaging architecture and wireless data transmission are compressing the capital equipment footprint required for diagnostic cystoscopy, enabling procedure migration to resource-constrained clinical environments.
CMOS image sensors with integrated LED drivers are digitizing the optical pathway in flexible cystoscope designs, replacing fiber optic bundles and proprietary camera heads. United States urology clinics with limited sterilization infrastructure adopt these platforms at accelerated pace for office-based hematuria workups. This architecture is digitizing the economics of diagnostic cystoscopy by eliminating capital-intensive tower systems and reducing per-procedure setup time.
EU MDR post-market surveillance requirements mandate systematic collection of clinical performance data across device lifecycles, extending documentation obligations beyond premarket clearance. Manufacturers must establish vigilance systems capable of tracing individual sterile units through distribution to end-use facilities. Flexible single-use platforms face heightened scrutiny given their broader deployment across outpatient networks with variable adverse event reporting infrastructure.
Direct manufacturer contracting with ambulatory surgical centers is fragmenting traditional distributor relationships that historically governed hospital system procurement. United States urology clinics now negotiate supply agreements bypassing medical device distributor tiers, compressing channel margins and demanding volume-based pricing structures. Germany exhibits similar pattern through regional purchasing cooperatives that aggregate outpatient clinic demand for sterile disposable platforms.
Single Use Cystoscope Market Segmentation
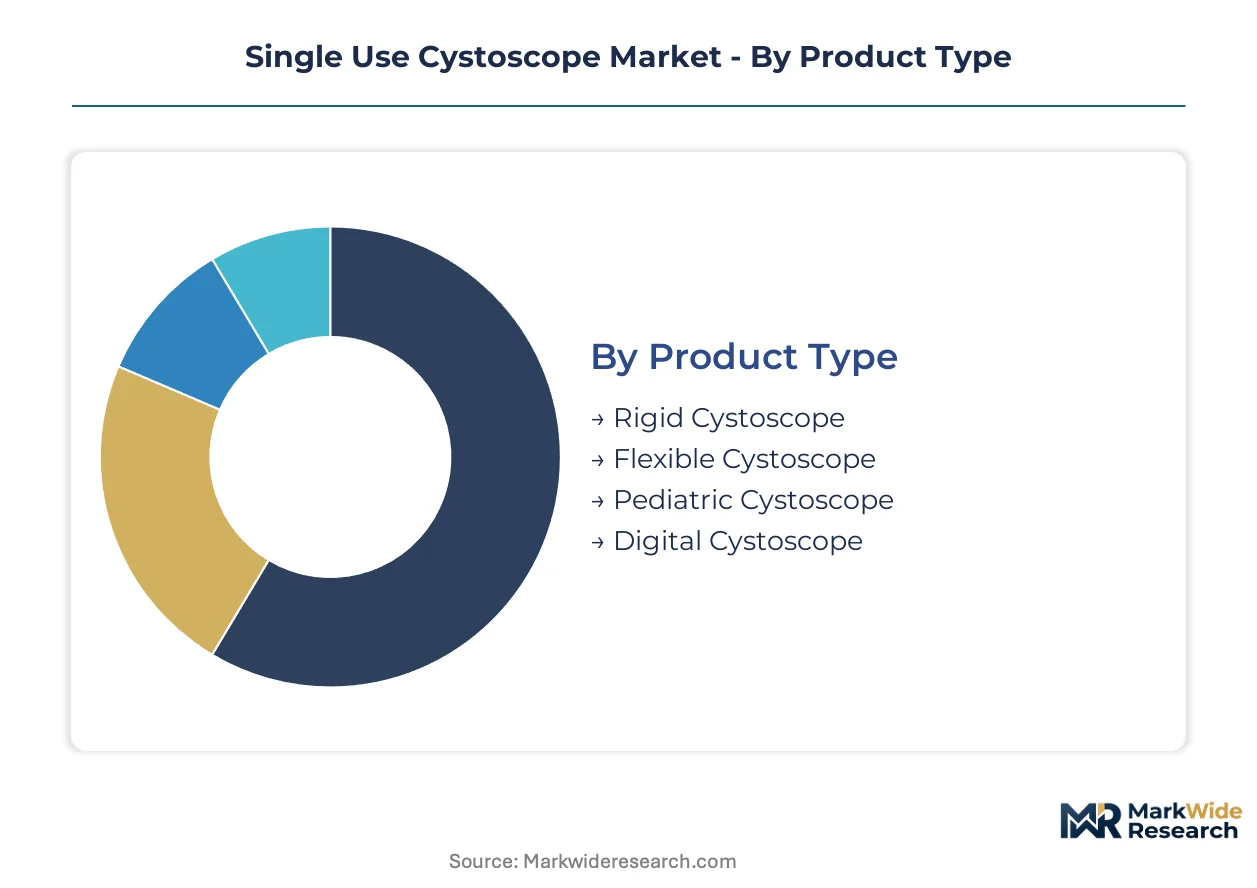
Segmentation in the single use cystoscope market reveals divergent procurement rhythms across clinical settings. Product architecture and end-user infrastructure constraints create distinct inventory turnover profiles that manufacturers must match with supply chain configurations.
Product Type:
Flexible cystoscopes turn inventory fastest in office-based urology practices with limited sterilization capacity, while rigid variants sustain longer replacement cycles anchored to operative lithotripsy suites.
- Rigid Cystoscope:Optical-grade stainless steel and polymer composite construction delivers instrument stability for transurethral lithotripsy and stent placement. Demand concentrates in German hospital operative suites where reusable platform durability benchmarks create switching friction for disposable alternatives.
- Flexible Cystoscope:CMOS sensor-integrated designs with polymer shafts enable navigation through tortuous urethral anatomy without fiber optic bundles. United States ambulatory surgical centers lacking autoclave infrastructure drive volume conversion toward these sterile, ready-to-use platforms for diagnostic hematuria workups.
- Pediatric Cystoscope:Narrower 4–6 French working channels with specialized tip geometry address neonatal and pediatric urology dimensional constraints.
- Digital Cystoscope:Wireless Bluetooth Low Energy transmission architectures eliminate proprietary tower hardware and reduce per-procedure setup time.
Rigid cystoscopes anchor the volume base in operative settings while flexible variants gain share at the steepest rate across outpatient diagnostic migration.
End User:
Cost tier stratification separates capital-intensive hospital systems from lean outpatient operators with minimal infrastructure investment.
- Hospitals:Integrated delivery networks with existing sterilization departments evaluate single-use platforms against sunk capital in reprocessing equipment and technician staffing. Bundled service agreements with multi-year supply commitments lock in procurement relationships.
- Clinics:Office-based urology practices without autoclave capacity convert diagnostic workloads to disposable cystoscopy at accelerated pace. Direct manufacturer contracting bypasses traditional distributor tiers and compresses channel margins.
- Ambulatory Surgical Centers:United States outpatient facilities lacking sterilization infrastructure represent concentrated demand for sterile, ready-to-use designs.
- Urology Centers:Specialized diagnostic and minor operative settings combine procedural volume with limited capital equipment footprints.
Hospitals retain procurement volume leadership while ambulatory surgical centers climb the fastest as outpatient migration accelerates.
Application:
Procedure complexity and reimbursement parity shape segment economics across diagnostic and therapeutic indications.
- Diagnosis:Hematuria evaluation and surveillance cystoscopy for bladder cancer recurrence generate recurring procedural volume with standardized technique requirements.
- Treatment:Transurethral resection and stone fragmentation procedures demand instrument stability and working channel patency under mechanical stress.
- Surgical Procedure:Stent placement and foreign body retrieval require precise instrument control and optical clarity.
- Imaging:High-definition documentation and wireless image transmission enable remote consultation and electronic health record integration.
Diagnostic applications sustain the installed base while imaging functionality expands most quickly through digital platform adoption.
Distribution Channel:
Channel configuration determines margin capture and customer relationship depth across fragmented procurement authority.
- Direct Sales:Manufacturer field organizations negotiate supply agreements with ambulatory surgical centers and regional purchasing cooperatives, bypassing distributor markups.
- Wholesalers:Broad-line medical supply distributors aggregate demand across fragmented clinic networks with standardized product configurations.
- Online Retail:E-commerce platforms serve smaller urology practices with immediate fulfillment requirements and limited procurement staff.
- Distributors:Specialized endoscopy distributors retain relevance in hospital system contracting through technical service and inventory management.
Direct sales channels capture volume leadership in outpatient settings while distributor relationships retain hospital system penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States procurement committees command premium pricing through bundled multi-year agreements, while German outpatient networks extract volume discounts through regional purchasing cooperatives. This asymmetry shapes manufacturer margin allocation across Atlantic markets.
United States
Ambulatory surgical center expansion and urology clinic migration drive sterile disposable adoption where autoclave infrastructure is absent. FDA 510(k) premarket notification pathways accelerate clearance timelines for manufacturers with established quality management systems. Texas and Florida outpatient networks concentrate demand for single-use diagnostic platforms.
Germany
Hospital operative suites maintain rigid cystoscope preference for lithotripsy durability benchmarks, while regional purchasing cooperatives aggregate clinic demand for flexible disposable alternatives. EU MDR Class IIa certification requirements favor incumbent documentation depth over new entrant speed. Bavarian medical technology clusters anchor rigid optical manufacturing.
Japan
PMDA extended clinical data requirements extend registration timelines and favor manufacturers with Tokyo regulatory affairs capacity. Aging demographics expand surveillance cystoscopy volume for bladder cancer recurrence monitoring. Osaka-Kobe industrial corridors concentrate endoscopy component supply.
South Korea
MFDS imposes additional clinical data requirements that parallel Japanese regulatory stringency. LED illumination module manufacturing clusters in Gyeonggi-Do create upstream component concentration for regional device assembly. Seoul Capital Area health systems evaluate single-use economics against reusable platform depreciation.
United Kingdom
NHS procurement frameworks emphasize total-cost-of-ownership analysis comparing disposable platforms against sterilization infrastructure amortization. MHRA post-Brexit regulatory alignment with EU MDR maintains conformity assessment continuity. London and Southeast England urology centers pilot wireless digital cystoscopy for office-based hematuria workups.
Single Use Cystoscope Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying CMOS sensors and LED modules to finished device manufacturers. Market structure concentrates around three to five incumbent groups with deep regulatory documentation and sterilization validation expertise. Strategic archetypes separate disposable endoscopy platform specialists, rigid optical heritage manufacturers, and diversified medtech conglomerates with urology portfolio breadth. Competitive moves center on backward integration into polymer compounding and direct contracting with ambulatory surgical centers to bypass distributor markups.
Among diversified medtech conglomerates, Olympus Corporation and Stryker Corporation occupy positions anchored to hospital system relationships and bundled service agreements. Ambu A/S exemplifies the disposable endoscopy platform specialist archetype with European outpatient network penetration. Karl Storz represents rigid optical heritage manufacturers competing through instrument stability benchmarks in operative settings.
| Leading Market Players |
|---|
| Olympus Corporation |
| UroViu Corporation |
| Ambu A/S |
| Richard Wolf |
| NeoScope Inc. |
| Karl Storz |
| Coloplast Group |
| Stryker Corporation |
| Boston Scientific Corporation |
| Others |
Value Chain & Pricing Dynamics
East Asian component concentration for LED illumination modules and micro-optical assemblies determines both the premium-to-standard pricing spread and the geographic configuration of sterile device manufacturing networks.
Pricing Analysis
The customization-premium spread separates standard flexible cystoscopes from pediatric-specialized and wireless-enabled digital variants. Per-unit transactional pricing dominates, with differentiation driven by CMOS sensor resolution grade and FDA 510(k) versus EU MDR certification tier. Cost compression in standard diagnostic platforms is intensifying because semiconductor manufacturing scale economies reduce CMOS sensor costs. Ambulatory surgical centers exhibit highest price sensitivity due to limited capital budgets, while hospital systems with bundled service agreements show lowest sensitivity.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk assessment for polymer resin and electronic component flows. Manufacturing concentrates in Germany, Japan, and South Korea for optical-grade lens assemblies and LED modules. Raw material dependencies include medical-grade polycarbonate, thermoplastic elastomers, and CMOS wafers. Single-source vulnerability for illumination components sourced from Taiwan and South Korea creates geographic concentration risk. Distribution runs through direct manufacturer contracting with ambulatory surgical centers and specialized endoscopy distributors serving hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in outpatient diagnostic settings where clinic migration and limited sterilization infrastructure create procurement niches for specialized disposable platforms.
For Market Incumbents: Pre-empt emerging entrant capture of pediatric and wireless connectivity segments by accelerating backward integration into polymer compounding and CMOS sensor sourcing. Defend hospital system contracts through expanded bundled service agreements that lock in multi-year supply commitments against substitute technology pressure from rigid reusable platforms. For New Entrants and Emerging Players: Establish a beachhead in United States ambulatory surgical centers lacking autoclave infrastructure by targeting Texas and Florida outpatient networks with volume-based pricing structures. Pediatric dimensional specialization offers protected margin pools given limited supplier base and specialized training requirements. For Investors and Strategic Acquirers: The market sits at an early consolidation phase that favors disposable endoscopy platform specialists with established regulatory documentation depth. Long-term viability over a multi-year horizon rests on sterilization validation expertise and EU MDR compliance infrastructure. The signal to watch is reimbursement parity studies comparing single-use and reusable cystoscopy procedure economics across health systems.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates market entry for novel single-use designs in United States outpatient settings. |
| CE Marking Pathway | Unlocks EU MDR Class IIa certification for sterile devices in German clinic networks. |
| Hospital System Partnership | Secures multi-year bundled agreements with integrated delivery networks. |
| Software Companion Development | Enables wireless Bluetooth Low Energy integration with tablet-based image processing. |
| Reimbursement Strategy | Shapes procurement authority through payer cost-comparison studies. |
Study Parameters
A spread of perspectives from urology practice administrators, hospital purchasing committee members, biomedical engineers, and GPO contracts managers converged on the working assumptions driving volume and value estimates. Primary field engagement combined with secondary validation against FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up facility-level demand modeling and top-down manufacturer shipment analysis were triangulated to establish market size and growth trajectory.
Demand-supply-balance framing anchored the analytical approach across the projection horizon. Segmentation dimensions modeled include product architecture, end-user infrastructure tier, application complexity, and regional regulatory cluster. CAGRs were derived from procedure volume elasticity to outpatient migration trends and cost-compression trajectories in CMOS sensor manufacturing. Industry-specific forecast inputs encompass ambulatory surgical center expansion rates and sterilization infrastructure depreciation schedules.
Sensitivities concentrate around reimbursement parity determinations, polymer resin price volatility, and East Asian supply chain disruptions. Forecasts reflect documented assumptions regarding regulatory clearance timelines and clinic conversion rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Genitourinary Cancers Treatment Market
Urology
Ureter Cancer Treatment Market
Urology
Europe Urology Devices Market
Urology
Obstructive Uropathy Treatment Market
Urology
Asia-Pacific Bladder Disorders Market
Urology
Pelvic Cancer Induced Hemorrhegic Cystitis Market
Urology
Uraemia Treatment Market
Urology
Urinary Incontinence Treatment Drugs Market
Urology
Voiding Cystourethrogram Market
Urology
Global Prostate Cancer Market
Urology
Global Bladder Cancer Therapeutics Market
Urology
Varicocele Treatment Market
Urology
Europe Bladder Disorders Market
Urology
Urothelial Carcinoma Treatment Market
Urology
Urology Robotic Surgery Market
Urology
Urology Devices Market