
 Global Prostate Health Market | 2026-2036
Global Prostate Health Market Size, Share, and Industry Trends Forecast 2026-2036
Global Prostate Health Market Foresight
Precision diagnostics is bifurcating the competitive landscape into premium molecular assay providers and volume-scale imaging equipment suppliers. Astellas Pharma Inc. leverages its urology franchise strength across Asian and European hospital networks. Pfizer Inc. anchors its position through sustained R&D investment in next-generation hormonal therapies. Johnson & Johnson Services, Inc. competes on robotic surgical system placement and surgeon training ecosystem control.
Prostate health encompasses the medical maintenance, disease detection, and therapeutic intervention targeting the male prostate gland, a walnut-sized organ producing seminal fluid and regulated by dihydrotestosterone levels; diagnostic modalities span PSA blood assays, multiparametric MRI, and transrectal ultrasound-guided biopsy, while therapeutics address benign enlargement, malignancy, and inflammatory conditions. Medications and hormonal therapy command the largest revenue pools due to chronic administration requirements and patent-protected formulations, though diagnostic devices represent the fastest-expanding segment as multiparametric MRI and liquid biopsy platforms displace conventional PSA screening in urology clinics across Germany, Japan, and the United States. Surgical instruments maintain premium pricing power in academic medical centers where robotic-assisted radical prostatectomy training programs concentrate.
The FDA governs pharmaceutical approval and device clearance pathways for prostate therapeutics and diagnostics entering the United States, while the EMA's MDR framework and centralized oncology drug assessments shape European market access conditions. Japan's PMDA accelerates sakigake-designated prostate cancer therapies through priority review channels, compressing development-to-commercialization timelines for domestic and foreign sponsors. Stakeholders must monitor how reimbursement authorities in each major market calibrate coverage decisions between established PSA protocols and emerging precision diagnostic platforms.
Market Dynamics
Multiparametric MRI is supplanting conventional PSA screening protocols across urology clinics, compressing diagnostic timelines and redistributing revenue from laboratory services to imaging centers and radiology networks.
Growth Catalysts
- FDA Accelerated Approval Pathways:Oncology therapeutics targeting castration-resistant prostate cancer reach commercialization faster through breakthrough therapy designation, compressing development cycles for hormonal intervention sponsors.
- Japan PMDA Sakigake Priority Review:Domestic and foreign pharmaceutical developers gain compressed regulatory timelines for novel prostate cancer therapies, incentivizing Japan-first launch strategies.
- Robotic Surgical System Placement:Academic medical centers in Germany and the United States anchor demand for surgeon training ecosystems and instrument consumables tied to radical prostatectomy procedures.
Market Restraints
- Reimbursement Calibration Lag:Public and private payers in the United States and Germany maintain coverage gaps between established PSA protocols and emerging liquid biopsy platforms, creating adoption friction.
- Supply Concentration in Imaging Equipment:Magnetic resonance imaging hardware production concentrates among three dominant original equipment manufacturers, exposing procurement functions to extended lead times and premium pricing.
- Technical Limitation in Tissue Sampling:Transrectal ultrasound-guided biopsy carries documented false-negative rates and infectious complication profiles that limit diagnostic confidence in outpatient settings.
Strategic Opportunities
- Underpenetrated Indian Screening Infrastructure:Urban tertiary centers in Mumbai and Delhi lack systematic PSA access programs, creating first-mover positioning for diagnostic service platforms.
- EMA MDR Framework Convergence:Centralized oncology drug assessments and harmonized device clearance pathways reduce market access fragmentation across France, Germany, and Italy.
- Artificial Intelligence-Assisted Radiology:Machine learning algorithms for prostate lesion detection on multiparametric MRI converge with cloud-based image archiving, enabling remote interpretation networks.
Industry Challenges
- Radiologist Specialization Scarcity:Genitourinary radiology fellowship-trained practitioners concentrate in academic medical centers, constraining outpatient clinic expansion of advanced imaging protocols.
- Integration Complexity with Hospital Information Systems:Picture archiving and communication systems require custom middleware development to interface with electronic health record platforms, extending implementation timelines.
- IP Fragmentation in Biomarker Patents:Proprietary gene expression signatures and circulating tumor cell detection methods operate under overlapping licensing claims, complicating assay development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Prostate Health Market |
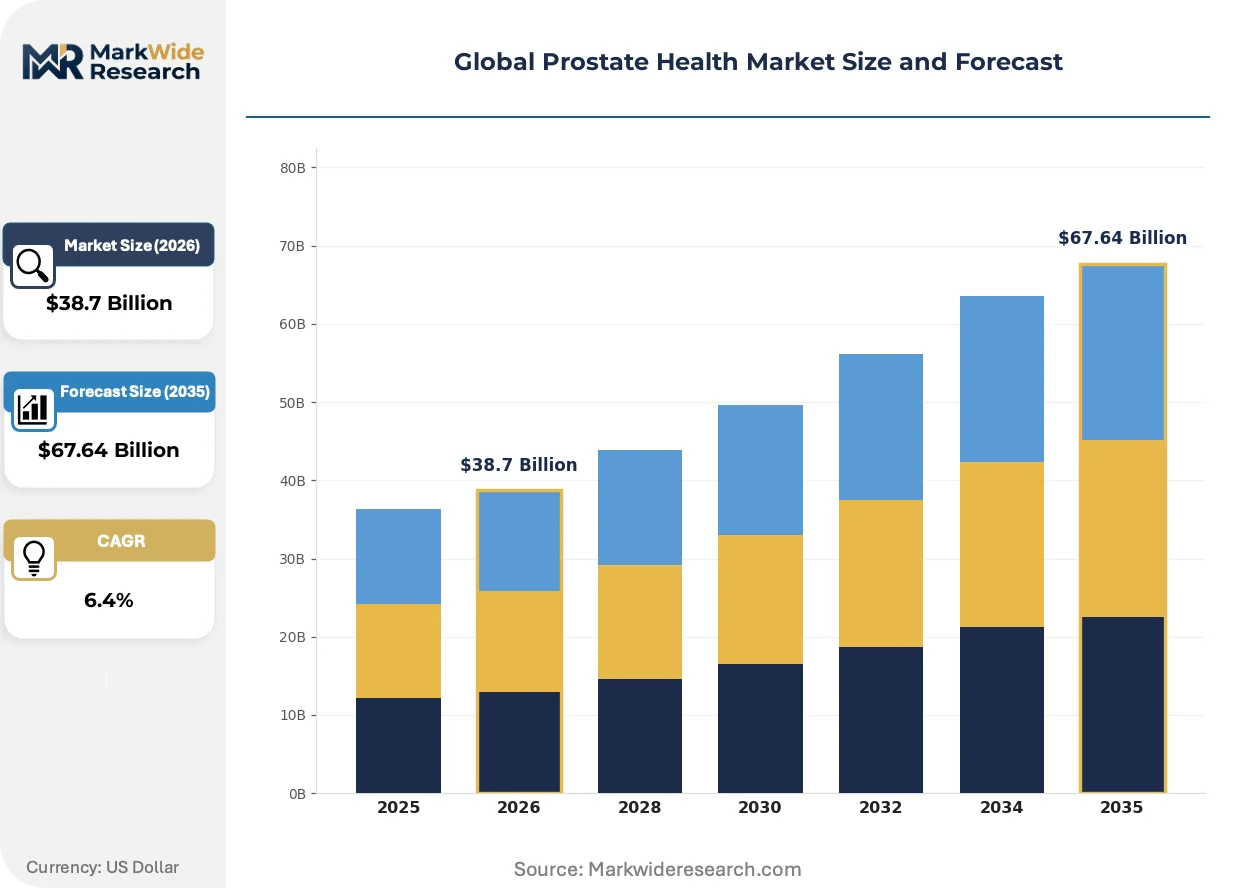
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $67.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Supplements, Diagnostic Devices, Surgical Instruments Application: Benign Prostatic Hyperplasia, Prostate Cancer, Preventive Care, Hormonal Therapy End User: Hospitals, Clinics, Home Care, Rehabilitation Centers Delivery Mode: Oral, Injectable, Topical, Intravenous |
| Companies Covered | Astellas Pharma Inc., GlaxoSmithKline plc., Johnson & Johnson Services, Inc., Pfizer Inc., Eli Lilly and Company, Bayer AG, Abbott Laboratories, Merck & Co., Inc., Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Prostate Health Market Shifts & Advancements
Diagnostic modality substitution and regulatory pathway compression are reconfiguring competitive positioning between pharmaceutical developers, device manufacturers, and service delivery platforms.
Liquid biopsy platforms analyzing circulating tumor DNA and exosomal RNA are supplanting tissue-based molecular profiling in metastatic disease monitoring. Community oncology practices in the United States and hospital networks in Germany are adopting these assays for treatment response assessment. The shift is compressing repeat biopsy requirements and reallocating pathology laboratory revenue toward centralized reference testing.
Japan's PMDA sakigake designation system accelerates priority review for prostate cancer therapeutics demonstrating substantial efficacy improvements over hormonal standards. Domestic sponsors and foreign multinationals compress development-to-commercialization timelines through parallel consultation and pre-submission pathways. The framework most benefits next-generation androgen receptor inhibitors seeking Japan-first or Japan-simultaneous launch positioning.
Urology clinics are unbundling diagnostic service contracts from device procurement agreements, shifting toward per-test reimbursement models with third-party radiology interpretation. Hospital systems in the United States and specialized prostate centers in Germany are outsourcing magnetic resonance imaging acquisition to independent diagnostic facilities. The restructuring concentrates capital expenditure risk among equipment lessors while distributing operational accountability across networked service providers.
Global Prostate Health Market Segmentation
Channel economics in prostate health diverge sharply between acute institutional procurement and chronic outpatient dispensing. Manufacturers must calibrate packaging, pricing, and service bundling to match whether products flow through hospital formularies, urology clinic consignment, or direct-to-patient pharmacy fulfillment.
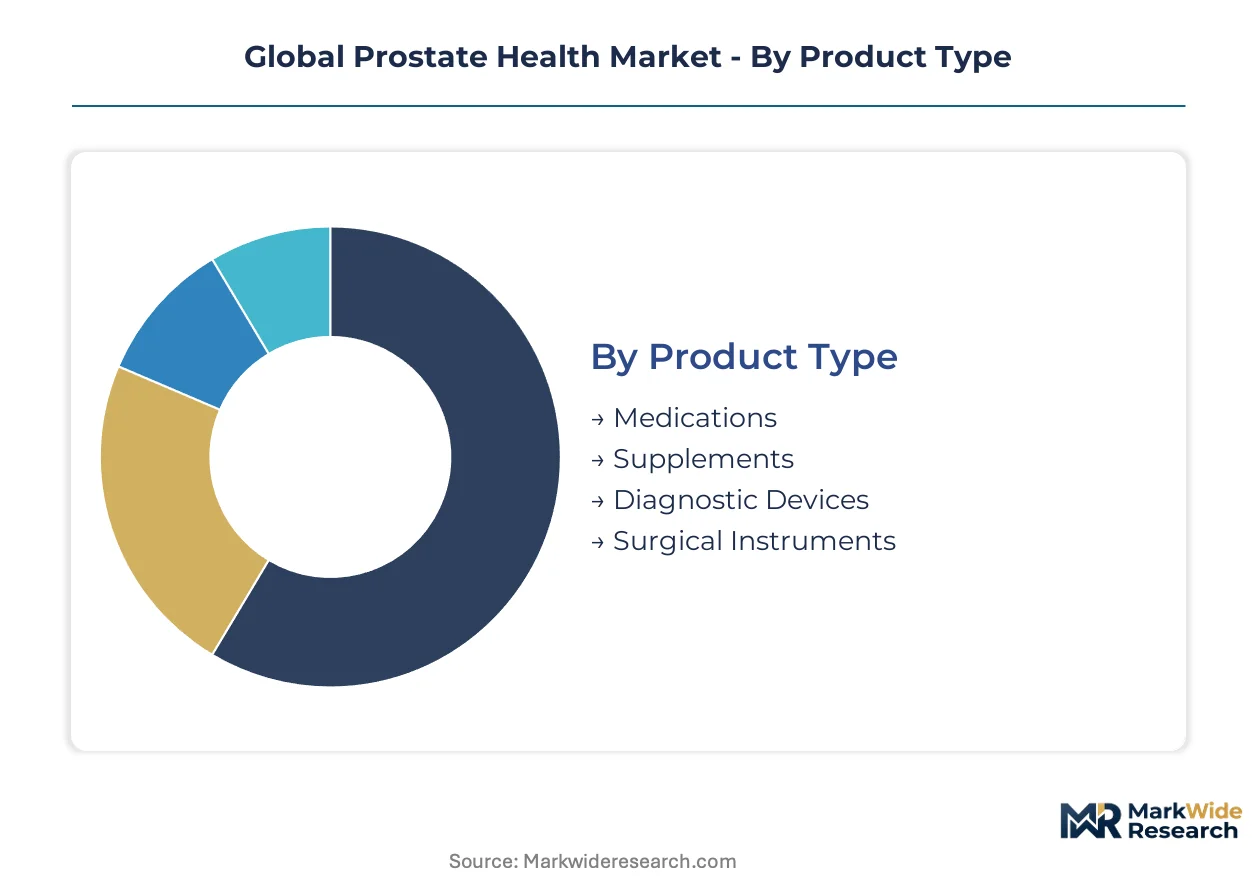
Product Type:
Hospital procurement committees and retail pharmacy chains split volume across these categories, with institutional buyers favoring surgical and diagnostic capital equipment while community channels handle medication replenishment.
- Medications:Chronic oral androgen deprivation therapies, alpha-blockers, and 5-alpha reductase inhibitors require monthly pharmacy dispensing cycles. Demand concentrates in United States Medicare Part D formularies and Japan's NHI reimbursement lists, where prior authorization protocols favor established hormonal standards over novel mechanisms.
- Diagnostic Devices:Multiparametric MRI coils, transrectal ultrasound probes, and liquid biopsy collection kits command capital budget cycles in German university hospitals and Japanese cancer centers. The FDA's 510(k) clearance pathway and Japan PMDA's pre-market consultation compress development timelines for imaging hardware sponsors.
- Supplements:Saw palmetto extracts and lycopene formulations circulate through direct-to-consumer channels and pharmacy OTC sections in the United States.
- Surgical Instruments:Robotic prostatectomy staplers, electrocautery devices, and laparoscopic trocars anchor supply contracts with academic medical centers in Germany and the United States.
By volume, Medications leads. By growth pace, Diagnostic Devices is climbing the fastest.
Application:
Reimbursement intensity and patient acuity stratify these segments, with oncology applications commanding premium pricing and preventive protocols facing coverage gaps.
- Prostate Cancer:Metastatic castration-resistant disease drives demand for next-generation androgen receptor inhibitors and PARP inhibitors. Treatment protocols concentrate in United States NCI-designated cancer centers and Japan's national cancer hospital network, where PMDA sakigake designation accelerates novel therapy access.
- Hormonal Therapy:Chronic testosterone suppression regimens anchor urology clinic revenue in Germany's statutory health insurance system and United States commercial payer networks. Prior authorization requirements and step-therapy protocols create formulary friction for newer LHRH agonist formulations.
- Benign Prostatic Hyperplasia:Minimally invasive thermal therapies and conventional alpha-blocker prescriptions dominate outpatient urology in the United States.
- Preventive Care:PSA screening programs and nutritional counseling face reimbursement variability across German regional sickness funds.
By patient volume, Benign Prostatic Hyperplasia leads. By revenue intensity, Prostate Cancer commands the steepest expansion trajectory.
End User:
Capital commitment thresholds and regulatory accreditation requirements determine which settings can deploy advanced diagnostic and surgical modalities.
- Hospitals:Academic medical centers in the United States, Germany, and Japan anchor demand for robotic surgical systems and multiparametric MRI suites. These institutions control fellowship training pipelines and surgeon certification pathways that lock in equipment vendor relationships.
- Clinics:Community urology practices in the United States and specialized prostate centers in Germany outsource imaging acquisition to independent diagnostic facilities while retaining biopsy and medication management services.
- Home Care:Self-administered LHRH injections and oral antiandrogen regimens expand in United States Medicare Advantage plans with home health benefits.
- Rehabilitation Centers:Post-prostatectomy pelvic floor therapy and continence training concentrate in German outpatient rehabilitation networks.
By procedure volume, Hospitals leads. By growth pace, Clinics is gaining share fastest.
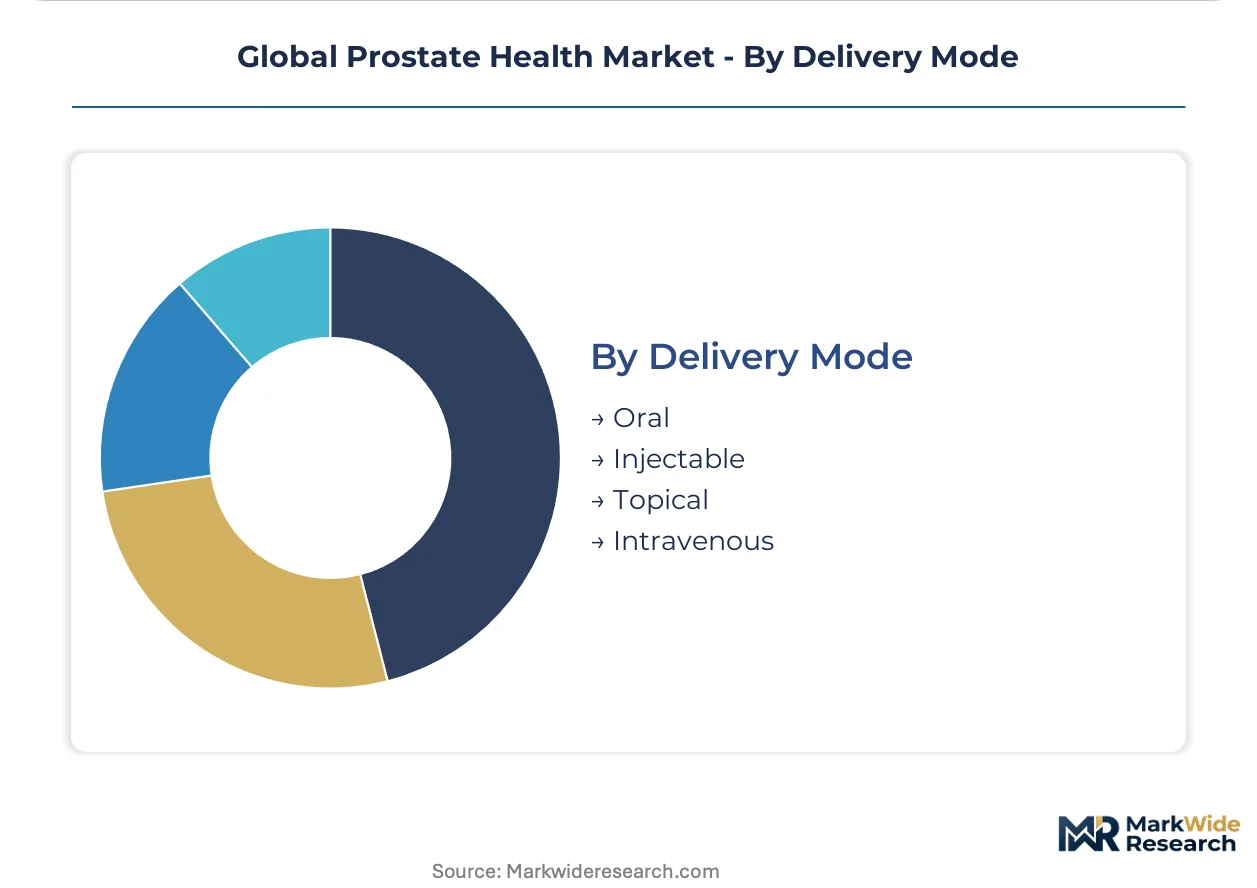
Delivery Mode:
Manufacturing complexity and cold chain requirements shape geographic sourcing patterns for parenteral formulations versus oral solid dose production.
- Oral:Abiraterone acetate, enzalutamide, and dutasteride tablets dominate outpatient dispensing in United States retail pharmacies and Japan's dispensing pharmacy system. Contract manufacturing organizations in India and Ireland supply active pharmaceutical ingredients to formulation facilities in Germany and the United States.
- Injectable:LHRH agonist depot formulations and subcutaneous antiandrogens require aseptic fill-finish capacity concentrated among European and North American CMOs. Germany's Kassenärztliche Bundesvereinigung and Japan's MHLW regulate administration site billing codes.
- Intravenous:Chemotherapy infusions and radioligand therapies anchor hospital outpatient department revenue in United States 340B-eligible facilities.
- Topical:Transdermal testosterone blockers and anesthetic gels occupy niche urology clinic dispensing in Germany.
By prescription volume, Oral leads. By growth pace, Injectable is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Original equipment manufacturers for magnetic resonance imaging hardware concentrate production among three dominant suppliers, creating procurement dependencies for hospitals across major markets. Diagnostic service networks and pharmaceutical distribution channels redistribute revenue toward outpatient settings in countries with mature reimbursement infrastructure.
United States
Medicare Part D formularies and commercial payer networks drive chronic medication dispensing through retail pharmacy chains. The FDA's breakthrough therapy designation compresses development timelines for hormonal intervention sponsors targeting castration-resistant disease. NCI-designated cancer centers in Houston and Boston anchor demand for robotic surgical systems and fellowship training pipelines.
Germany
Statutory health insurance reimbursement and Kassenärztliche Bundesvereinigung billing codes structure outpatient urology clinic revenue around chronic testosterone suppression regimens. The EMA's MDR framework harmonizes device clearance pathways across member states, reducing market access fragmentation. University hospitals in Munich and Heidelberg concentrate multiparametric MRI suite procurement and radiology fellowship programs.
Japan
NHI reimbursement lists and dispensing pharmacy system distribution shape oral antiandrogen market access for chronic administration. The PMDA's sakigake priority review designation accelerates commercialization timelines for novel prostate cancer therapeutics. National cancer hospital networks in Tokyo and Osaka anchor next-generation androgen receptor inhibitor adoption and clinical trial concentration.
India
Urban tertiary centers in Mumbai and Delhi lack systematic PSA access programs, creating positioning opportunities for diagnostic service platform expansion. The CDSCO regulates pharmaceutical approval pathways for prostate therapeutics entering the domestic market. Contract manufacturing organizations in Hyderabad and Ahmedabad supply active pharmaceutical ingredients to formulation facilities serving export markets.
Global Prostate Health Market Competitive Landscape
Concentration sits with multinational pharmaceutical developers and diversified medical technology conglomerates. The competitive structure divides between patent-protected hormonal therapy sponsors and capital equipment vendors controlling surgeon training ecosystems. Three strategic archetypes dominate: chronic medication formulators with established reimbursement relationships, robotic surgical system manufacturers with installed base lock-in, and molecular diagnostic platform developers seeking reference laboratory contracts. M&A activity targets liquid biopsy assay developers, while geographic expansion concentrates on Japanese and German hospital procurement channels.
Among Japan-based pharmaceutical developers, Astellas Pharma Inc. occupies a position exemplifying urology franchise strength across Asian and European hospital networks. Pfizer Inc. and Johnson & Johnson Services, Inc. represent the diversified multinational archetype, with the former anchoring next-generation hormonal therapy R&D positioning and the latter sitting within robotic surgical system placement and surgeon training ecosystem control. These three entities demonstrate how competitive positioning bifurcates between molecular assay premium pricing and volume-scale imaging equipment supply.
| Leading Market Players |
|---|
| Astellas Pharma Inc. |
| GlaxoSmithKline plc. |
| Johnson & Johnson Services, Inc. |
| Pfizer Inc. |
| Eli Lilly and Company |
| Bayer AG |
| Abbott Laboratories |
| Merck & Co., Inc. |
| Novartis AG |
| Others |
Supply & Pricing Matrix
Liquid biopsy collection kits replacing conventional tissue-based molecular profiling are redistributing procurement budgets toward centralized reference laboratories and compressing margins for distributed pathology networks. This substitution simultaneously concentrates supply geography in Germany, Japan, and the United States where FDA and PMDA accreditation requirements filter equipment vendors, while pricing economics bifurcate between premium assay platforms and commoditized sample handling consumables.
Pricing Analysis
FDA breakthrough therapy designation dictates the pricing tier structure for oncology therapeutics targeting castration-resistant prostate cancer, creating premium positioning for novel hormonal interventions against generic LHRH agonist standards. Three-tier pricing structure across premium, standard, and economy levels separates next-generation androgen receptor inhibitors from established oral antiandrogens and off-label hormonal combinations. Cost compression in the standard tier is intensifying because Medicare Part D formulary step-therapy protocols favor incumbent molecules. Community urology clinics exhibit the highest price sensitivity, while NCI-designated cancer centers prioritize clinical efficacy over acquisition cost.
Supply Chain Analysis
Extended lead times for superconducting magnet components in multiparametric MRI hardware strain hospital capital budget cycles and compress vendor negotiation windows. Magnetic resonance imaging equipment production concentrates in Germany, Japan, and the United States, while active pharmaceutical ingredients for hormonal therapies draw from contract manufacturing organizations in India and Ireland. Single-source vulnerability sits with helium-3 isotope supply for advanced imaging coils. Distribution runs through hospital procurement committees for capital equipment and retail pharmacy chains for chronic oral medications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards organizations that control genitourinary radiology training pipelines and robotic surgical system installed bases, while scarcity in fellowship-trained practitioners constrains outpatient clinic expansion of advanced imaging protocols.
For Market Incumbents: Compound installed base lock-in through surgeon training ecosystem control and reference laboratory contract consolidation. Defend against liquid biopsy platform substitution by integrating proprietary biomarker assays into existing hormonal therapy portfolios. Vertical integration into cloud-based image archiving capabilities secures radiology network dependencies. For New Entrants and Emerging Players: Lead with artificial intelligence-assisted lesion detection software targeting community urology clinics lacking in-house genitourinary radiology expertise. Underpenetrated Indian screening infrastructure offers first-mover positioning for diagnostic service platforms combining PSA access programs with mobile imaging units. Reimbursement strategy development must precede commercial launch. For Investors and Strategic Acquirers: The market sits at a modality-substitution phase that favors molecular diagnostic platform developers with FDA 510(k) clearance pathways and established reference laboratory relationships. Long-term viability hinges on portfolio breadth spanning chronic medication formularies and precision diagnostic reimbursement. The signal to watch is PMDA sakigake designation velocity for novel androgen receptor inhibitors.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Academic medical center alliances lock in robotic surgical system placement and surgeon training revenue. |
| Reimbursement Strategy | Payer access specialists navigate Medicare Part D prior authorization protocols for novel hormonal therapies. |
| Software Companion Development | Machine learning algorithms for prostate lesion detection attract radiology network licensing contracts. |
| CE Marking Pathway | EMA MDR framework harmonization reduces market access fragmentation across German and Italian hospital procurement. |
| Regulatory Approval Pathway | PMDA sakigake priority review compresses commercialization timelines for Japan-first launch positioning. |
Research Methodology
A spread of perspectives from urology clinic directors, hospital procurement managers, formulary access specialists, and radiology network administrators converged on the working assumptions for market sizing and growth trajectory. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) clearance databases, PMDA approval records, EMA centralized oncology assessments, and hospital procurement contract filings. Bottom-up demand modeling across product categories triangulated with top-down macroeconomic indicators.
Segmentation dimensions modeled include product type, application, end user, and delivery mode across the projection horizon, with additional stratification by regional regulatory cluster and reimbursement intensity. CAGRs were derived from trend extrapolation of historical approval velocity and adoption curve analysis for emerging diagnostic modalities. Forecast inputs incorporated PMDA sakigake designation timelines and Medicare coverage determination patterns for liquid biopsy platforms.
The analysis sits within stated boundaries; outcomes outside sustained reimbursement expansion for precision diagnostics or prolonged supply constraints in imaging hardware would require recalibration. Forecasts reflect documented assumptions regarding regulatory pathway compression and diagnostic modality substitution velocity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Global Prostate Cancer Market
Urology
Urology Lasers Market
Urology
Urology Robotic Surgery Market
Urology
Urinary Incontinence Therapeutics Market
Urology
Urology Forceps Market
Urology
Penile Cancer Market
Urology
Global Castrate Resistant Prostate Cancer Market
Urology
Chronic Pyelonephritis Treatment Market
Urology
Nordic Urinary Catheters Market
Urology
Global Nephrology and Urology Devices Market
Urology
Urinary Tract Infection Testing Market
Urology
Cystectomy Market
Urology
Varicocele Treatment Market
Urology
Global Lithotripsy Market
Urology
Ureterorenoscopes Market
Urology
Urology Laser Fibers Market