
 Vaterite Market | 2026-2036
Vaterite Market Size, Share, and Industry Trends Forecast 2026-2036
Vaterite Market Analysis
Pharmaceutical formulation is recalibrating vaterite procurement priorities as drug developers seek amorphous calcium carbonate phases for tunable dissolution profiles. Solvay SA leverages its specialty chemicals heritage to sustain pharmaceutical-grade purity thresholds across European supply chains. Minerals Technologies Inc. anchors North American industrial demand through integrated mineral processing infrastructure. Omya AG competes on geographic reach, controlling carbonate distribution networks that span multiple continents.
Vaterite constitutes a metastable polymorph of calcium carbonate distinguished by hexagonal crystal symmetry and higher aqueous solubility than calcite or aragonite, properties exploited in pH-responsive drug carriers and rapid-setting cement formulations. Powder grades command the largest volume share across water treatment and coatings applications where surface area drives reactivity. Pharmaceutical-grade crystals attract the fastest value growth as FDA dissolution testing protocols and EMA bioequivalence guidelines elevate functional performance requirements above commodity specifications. Industrial-grade granules remain mature, with margin compression from construction sector price sensitivity.
EPA effluent standards and REACH substance registration shape product purity thresholds for water treatment and coatings applications, while FDA current Good Manufacturing Practice rules govern pharmaceutical-grade production documentation. China's NMPA bioavailability guidance and GB standards for food additives create parallel compliance architectures that multinational suppliers must navigate simultaneously. Stakeholders should monitor evolving pharmacopeial monographs and carbon border adjustment mechanisms that could restructure cost-competitive sourcing strategies.
Market Dynamics
Pharmaceutical-grade purity thresholds are tightening procurement specifications across calcium carbonate supply chains, forcing mineral processors to recalibrate crystallization controls and documentation protocols to meet FDA and EMA dissolution testing mandates.
Growth Catalysts
- Controlled-release drug delivery:FDA bioavailability standards are elevating demand for metastable polymorphs with tunable dissolution kinetics in oral dosage formulations.
- REACH substance registration:ECHA compliance requirements for industrial coatings are filtering out low-purity carbonate sources, consolidating qualified supplier pools.
- pH-responsive cement chemistry:Rapid-setting formulations exploit vaterite's higher aqueous solubility to accelerate construction cycle times in infrastructure projects.
Market Restraints
- Calcite price arbitrage:The stable polymorph's commodity pricing exerts margin compression on vaterite in non-pharmaceutical applications where functional differentiation is undervalued.
- Chinese mineral processing concentration:Powder grade supply chains exhibit geographic clustering that exposes buyers to carbon border adjustment mechanism risks under EU Green Deal implementation.
- Metastability degradation:Spontaneous phase conversion to calcite during storage limits shelf-life for applications requiring amorphous structure preservation.
Strategic Opportunities
- Indian pharmaceutical manufacturing:CDSCO bioequivalence guidelines are creating parallel certification pathways that reward suppliers with dual FDA-NMPA documentation capabilities.
- Carbon capture mineralization:CO2-to-carbonate synthesis routes offer synthetic vaterite production with embedded emissions credentials for ESG-mandated procurement.
- Direct-to-formulator distribution:Bypassing traditional mineral traders allows API manufacturers to specify crystal morphology and surface area with batch-level traceability.
Industry Challenges
- Crystallization process control:Maintaining hexagonal symmetry across production batches demands precision engineering talent scarce in traditional mining regions.
- Pharmacopeial monograph alignment:Divergent USP, EP, and JP testing protocols create multi-standard compliance costs for pharmaceutical-grade certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vaterite Market |
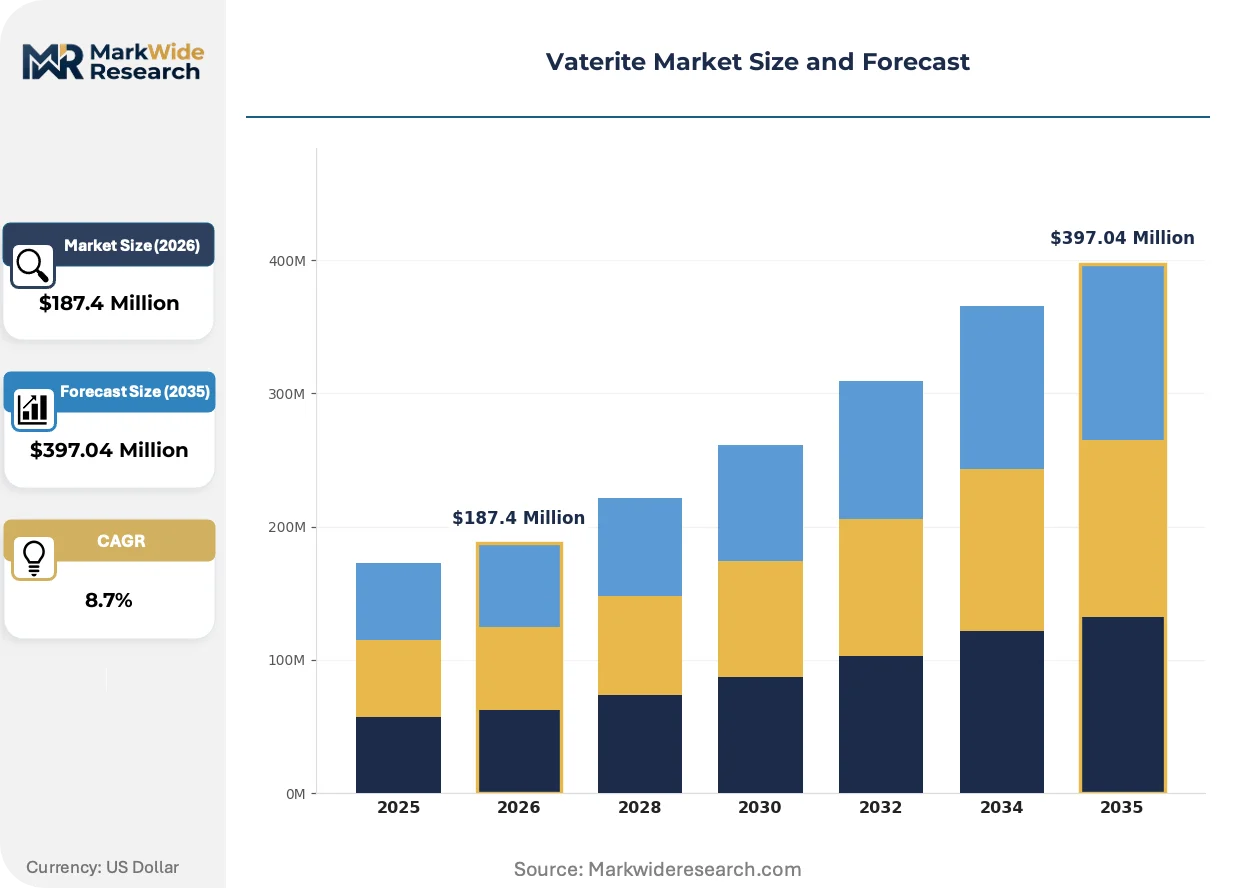
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Crystals, Beads End Use Industry: Construction, Agriculture, Pharmaceuticals, Food & Beverage Grade: Industrial, Food Grade, Pharmaceutical Grade, Technical Application: Water Treatment, Soil Amendment, Coatings, Additives |
| Companies Covered | Conia Minerals & Marbles Co., Carmeuse, Solvay SA, Natural Calcite Powder, Weinrich Minerals, Minerals Technologies Inc., Calspar India, Conia Minerals, Omya AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vaterite Market Emerging Trajectories
Calcium carbonate formulation science is advancing beyond commodity specifications toward engineered crystal architectures that deliver functional performance in regulated end-uses.
Amorphous calcium carbonate stabilization chemistry is rewriting the shelf-life economics of metastable polymorphs. Pharmaceutical formulators in Germany and Switzerland are adopting spray-dried vaterite precursors for implantable depot systems. This technology is compressing the timeline between mineral processing and finished dosage validation.
EMA's revised bioequivalence guidelines for modified-release products are tightening dissolution profile specifications. Industrial consequences include mandatory Q1/Q2 sameness demonstrations for excipient polymorph ratios. European generic drug manufacturers are responding by locking multi-year supply agreements with certified carbonate processors.
Formulator procurement patterns are consolidating supplier relationships around integrated quality systems. API manufacturers in the United States are displacing spot-market mineral purchases with contracted crystal engineering partnerships. This concentration is most visible in oncology drug delivery where batch-to-batch dissolution variance carries clinical trial risk.
Vaterite Market Segmentation
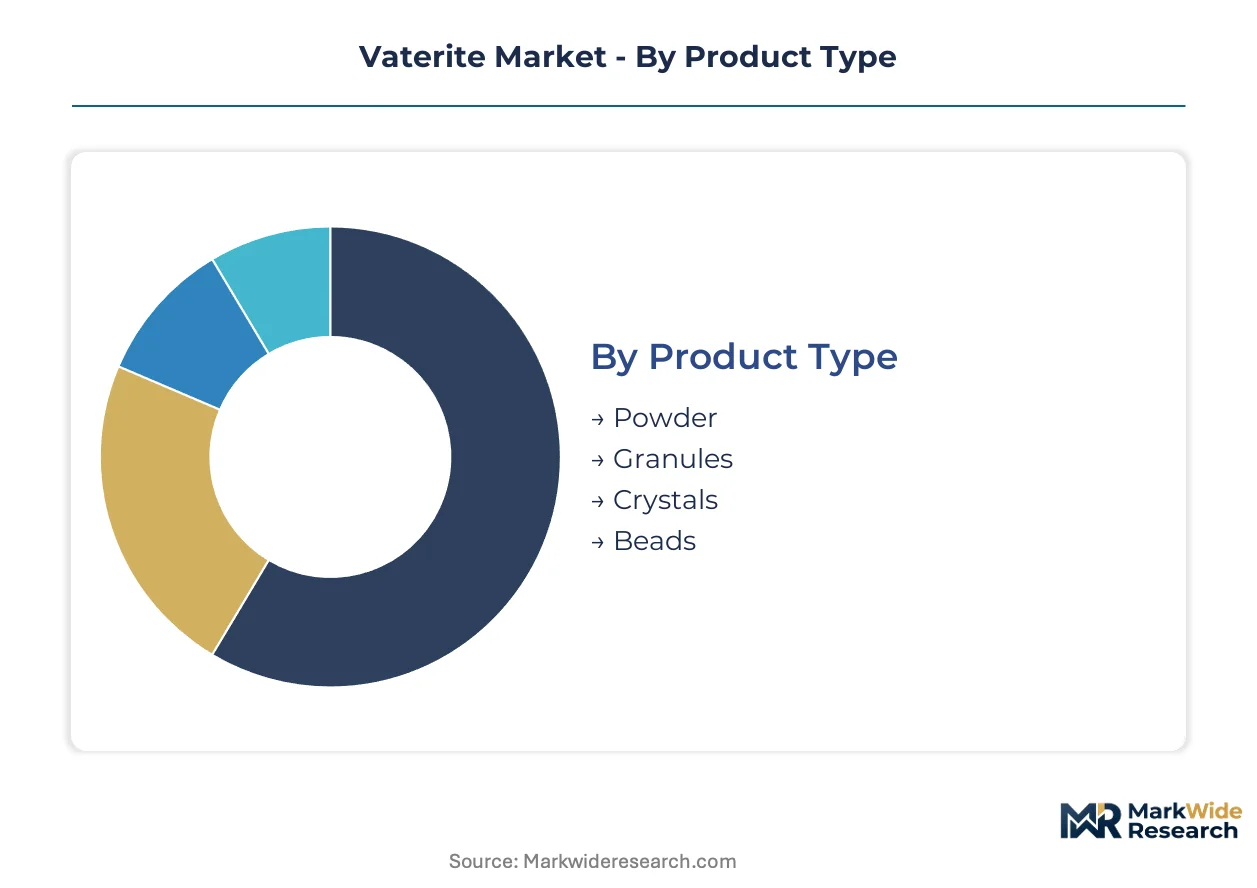
Vaterite procurement decisions hinge on crystallization precision and regulatory documentation depth. Pharmaceutical-grade segments demand FDA dissolution protocols and EMA bioequivalence alignment, while industrial grades compete on surface area metrics and reactivity thresholds.
Product Type:
Certification burdens intensify downstream as particle morphology dictates end-use qualification pathways. Crystals and beads face pharmaceutical-grade purity mandates, whereas powder and granules navigate REACH substance registration and EPA effluent standards.
- Powder:Finely milled particles with elevated surface area-to-volume ratios drive reactivity in water treatment and coatings formulations. Demand concentrates in China's mineral processing clusters and Germany's industrial coatings sector, where REACH compliance filters supplier pools.
- Crystals:Hexagonal crystal symmetry preserves metastable phase integrity for pH-responsive drug carriers. FDA current Good Manufacturing Practice documentation and USP monograph alignment dominate procurement specifications for oral dosage applications.
- Granules:Intermediate particle size supports rapid-setting cement chemistry and construction cycle acceleration. Price sensitivity from infrastructure contractors limits margin expansion despite functional solubility advantages over calcite.
- Beads:Spherical morphology engineered for controlled-release depot systems and implantable drug delivery. Swissmedic and PMDA certification pathways add parallel compliance layers for European and Japanese pharmaceutical markets.
Powder sits at the top of the volume ranking, with crystals climbing the fastest.
End Use Industry:
Application-specific purity thresholds create tiered pricing structures across regulated and commodity sectors. Pharmaceutical and food-grade end-uses absorb compliance costs through premium positioning, while construction and agriculture prioritize cost efficiency.
- Pharmaceuticals:Metastable polymorphs with tunable dissolution kinetics command premium positioning under tightened FDA bioavailability standards. CDSCO bioequivalence guidelines in India create secondary certification demand for suppliers with dual documentation capabilities.
- Construction:Rapid-setting formulations exploit higher aqueous solubility than calcite to compress infrastructure project timelines. Margin compression from commodity carbonate arbitrage limits vaterite penetration where functional differentiation lacks specification.
- Agriculture:Soil amendment applications leverage pH-neutralizing capacity and calcium bioavailability for crop yield optimization. NMPA food additive standards in China and EPA agricultural runoff regulations shape permissible impurity thresholds.
- Food & Beverage:Calcium fortification applications require FSSAI clearance in India and EFSA additive authorizations in Europe. Surface area and particle size distribution determine bioavailability claims on nutritional labeling.
Construction holds the largest volume position, though pharmaceuticals is expanding most quickly.
Grade:
Grade stratification reflects documentation depth and batch traceability requirements. Pharmaceutical and food grades demand crystallization process validation, while industrial and technical grades compete on mineralogical consistency.
- Pharmaceutical Grade:Q1/Q2 sameness demonstrations for excipient polymorph ratios are mandatory under EMA revised bioequivalence guidelines. Multi-year supply agreements with certified processors are displacing spot-market mineral purchases among generic drug manufacturers.
- Industrial:Construction and coatings applications tolerate broader particle size distributions where calcite price arbitrage constrains vaterite adoption. Carbon border adjustment mechanism exposure from Chinese supply concentration adds sourcing risk premiums.
- Food Grade:FSSAI, EFSA, and FDA food additive regulations converge on heavy metal limits and microbial contamination thresholds. Spray-dried precursor technologies are compressing validation timelines between mineral processing and finished product certification.
- Technical:Intermediate purity tier serves water treatment and non-food industrial additives with flexible specification bands. ECHA REACH registration requirements for industrial coatings are consolidating qualified supplier pools.
Industrial grade dominates volume, with pharmaceutical grade showing the steepest expansion trajectory.
Application:
Functional performance requirements vary sharply across reactive and passive deployment modes. Water treatment and coatings demand surface area optimization, while soil amendment and additive applications prioritize dissolution predictability.
- Water Treatment:pH adjustment and heavy metal precipitation applications exploit rapid dissolution kinetics. EPA effluent standards and GB standards in China define permissible discharge concentrations that drive reagent grade selection.
- Coatings:Industrial formulations leverage hexagonal crystal morphology for opacity and rheology control. ECHA REACH substance registration filters out low-purity carbonate sources from European qualified supplier pools.
- Soil Amendment:Agricultural lime alternatives deliver calcium availability with reduced soil compaction versus traditional carbonate sources. NMPA guidance on soil additive safety creates parallel compliance architecture for multinational suppliers.
- Additives:Multi-industry applications span cement accelerators, plastic fillers, and rubber compounding where particle size distribution determines processing behavior. Technical grade specifications balance cost against functional consistency.
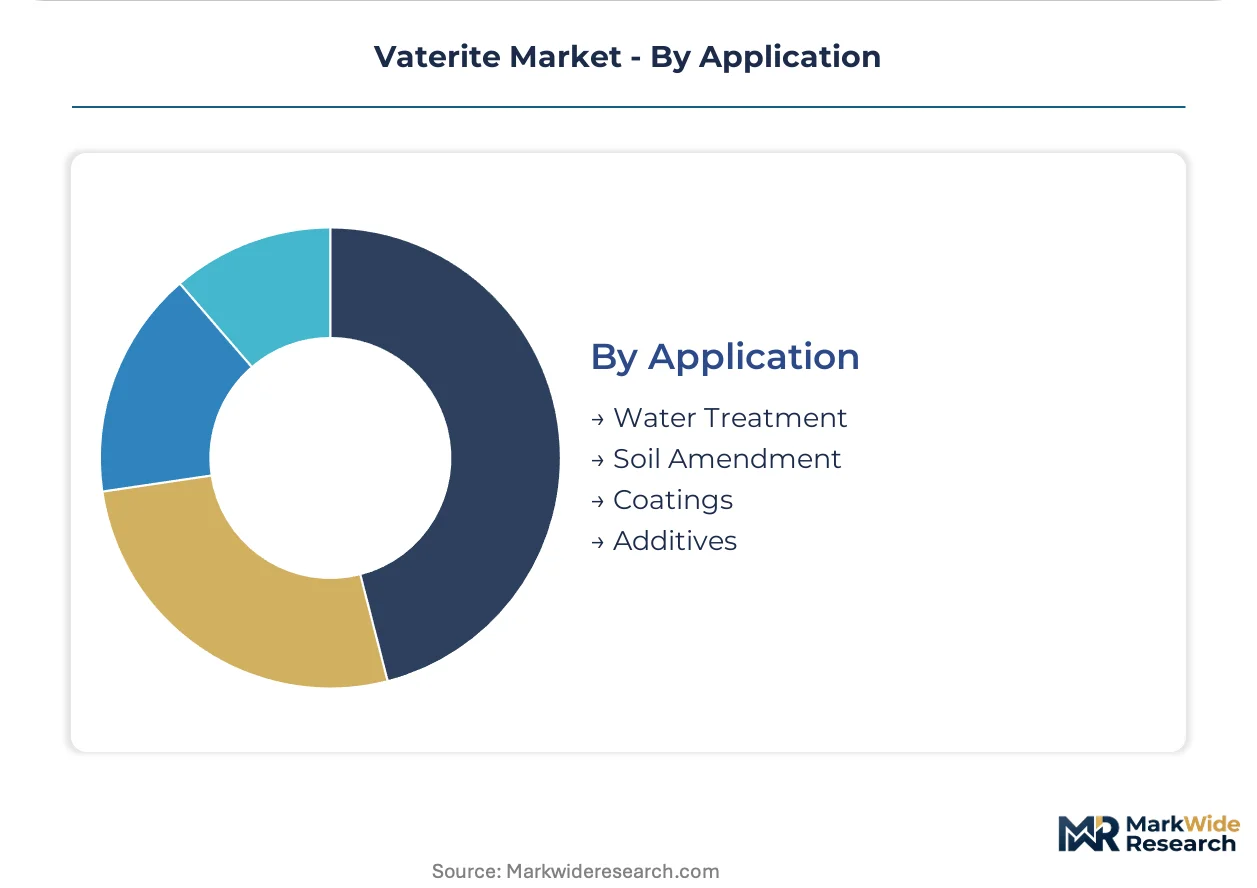
Water treatment leads volume rankings, with coatings gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting vaterite production toward jurisdictions with streamlined compliance pathways. China and India attract pharmaceutical-grade processing investment through lower documentation costs, while European producers defend position via EMA-aligned quality systems that command premium positioning.
China
Mineral processing clusters in Jiangsu and Shandong provinces dominate powder-grade output for water treatment and coatings applications. NMPA bioavailability guidance for pharmaceutical excipients is tightening documentation requirements for domestic API manufacturers. Tianjin's carbonate processing corridor is expanding spray-dried precursor capacity to serve both domestic drug developers and export markets.
Germany
Rhineland-Palatinate and North Rhine-Westphalia host integrated specialty chemical operations serving EMA-regulated pharmaceutical formulators. REACH substance registration for industrial coatings is filtering supplier pools toward documented carbonate sources. The Ludwigshafen chemical cluster maintains crystallization process validation capabilities that support Q1/Q2 sameness demonstrations under revised bioequivalence guidelines.
United States
Pennsylvania and Ohio anchor North American demand through construction and pharmaceutical end-uses. FDA current Good Manufacturing Practice rules govern batch-level traceability for oral dosage applications. The Houston-Galveston corridor is developing carbon capture mineralization pilots that could reshape synthetic vaterite sourcing for ESG-mandated procurement.
India
Gujarat and Maharashtra pharmaceutical manufacturing zones are driving CDSCO bioequivalence certification demand for excipient suppliers. FSSAI food additive regulations create parallel compliance architecture for calcium fortification applications. The Ankleshwar industrial estate is attracting multi-national carbonate processors seeking dual FDA-NMPA documentation capabilities.
Switzerland
Swissmedic certification pathways for implantable depot systems sustain premium positioning for hexagonal crystal morphology suppliers. Basel's pharmaceutical cluster sources spray-dried vaterite precursors for controlled-release oncology formulations. The country's carbon border adjustment exposure is minimal due to domestic mineral processing infrastructure and renewable energy integration.
Vaterite Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical-grade supply consolidating around integrated quality systems while industrial-grade procurement tolerates broader supplier pools. The market structure exhibits tiered concentration: multinational chemical conglomerates control high-purity documentation pathways, regional mineral processors dominate commodity powder grades, and emerging synthetic carbonate producers occupy carbon capture mineralization niches. Dominant competitive moves include backward integration into crystallization process control and geographic expansion toward dual-certification jurisdictions.
Within the multinational chemical tier, Solvay SA and Omya AG exemplify divergent strategic positioning. Solvay SA leverages European specialty chemicals heritage to sustain pharmaceutical-grade purity thresholds across EMA-regulated supply chains. Omya AG competes on geographic reach, controlling carbonate distribution networks that span multiple continents. Minerals Technologies Inc. anchors North American industrial demand through integrated mineral processing infrastructure in the United States.
| Leading Market Players |
|---|
| Conia Minerals & Marbles Co. |
| Carmeuse |
| Solvay SA |
| Natural Calcite Powder |
| Weinrich Minerals |
| Minerals Technologies Inc. |
| Calspar India |
| Conia Minerals |
| Omya AG |
| Others |
Supply Flow & Price Mechanics
Crystallization process engineers in Rhineland-Palatinate command wage premiums that compress margins on pharmaceutical-grade batches while Jiangsu powder mills exploit labor-cost arbitrage to sustain economy-tier positioning for water treatment reagents.
Pricing Analysis
Distributor markups on pharmaceutical-grade crystals run 15-25 points above direct-to-formulator contracts, with EMA-certified batches commanding premium positioning over technical-grade powder. Certification depth and batch-level USP documentation drive price differentiation, while calcite substitution pressure intensifies margin compression in construction applications. Generic drug manufacturers exhibit highest price sensitivity; oncology formulators show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Jiangsu mineral processing clusters for powder-grade feedstock, exposing downstream buyers to carbon border adjustment mechanism disruption. Raw material flows draw from Sichuan limestone quarries, Pennsylvania dolomite deposits, and Omani marine carbonate reserves. Tariff exposure on Chinese-origin powder threatens coatings sector cost structures. Distribution runs through specialty chemical distributors for pharmaceutical grades and bulk mineral traders for industrial applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with EMA's revised bioequivalence guidelines for modified-release products mandating Q1/Q2 sameness demonstrations that lock in multi-year supplier relationships.
For Market Incumbents: Acquire spray-dried precursor production assets in Switzerland or Germany to defend against synthetic carbonate entrants with embedded emissions credentials. Consolidate crystallization process validation capabilities to meet tightening FDA dissolution protocol documentation requirements.
For New Entrants and Emerging Players: Indian CDSCO-certified API manufacturers represent an underserved buyer archetype seeking dual FDA-NMPA documentation capabilities without incumbent supply lock-in. Carbon capture mineralization technology offers synthetic production pathways for ESG-mandated procurement segments.
For Investors and Strategic Acquirers: Specialty chemical conglomerates with pharmaceutical-grade quality systems are the most active acquirer in this space, targeting regional mineral processors for geographic expansion. Watch for carbon border adjustment mechanism implementation timing as inflection indicator for Chinese supply chain restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Crystallization Control | Solvay SA's European specialty chemicals heritage sustains EMA-aligned purity thresholds against commodity competition. |
| Carbon Capture Mineralization Scale-Up | Synthetic production routes embed emissions credentials for procurement teams with ESG mandates. |
| Dual-Certification Documentation Investment | Simultaneous FDA-NMPA capabilities unlock Indian pharmaceutical manufacturing demand expansion. |
| Direct-to-Formulator Distribution Bypass | API manufacturers specify crystal morphology with batch-level traceability, displacing spot-market mineral purchases. |
| Amorphous Calcium Carbonate Stabilization R&D | Spray-dried precursor technologies compress validation timelines for implantable depot systems. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with pharmaceutical formulators, mineral processing plant managers, regulatory affairs specialists, and coatings procurement leads. Secondary validation draws from FDA filings, EMA bioequivalence guideline revisions, ECHA REACH substance registration databases, and customs trade flow records. Bottom-up volume modeling triangulates against top-down industry sizing.
Granularity extends to grade-tier, end-use industry, and regional production hub dimensions across the analysis window. CAGRs derive from segmented growth rate blending with cross-elasticity adjustments for calcite substitution pressure. Forecast inputs incorporate pharmacopeial monograph evolution timelines and carbon border adjustment mechanism implementation scenarios.
Underlying measurement precision varies by segment; pharmaceutical-grade crystal volumes carry tighter precision than technical-grade powder estimates given documentation depth disparities. Forecasts reflect assumptions around regulatory alignment speed and metastability degradation shelf-life economics. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Stoneware Market
Ceramics
Pottery Ceramics Market
Ceramics
Wollastonite Market
Ceramics
Tetramethyl Orthosilicate Market
Ceramics
US Kaolin Market
Ceramics
Advanced Sintering Technologies Market
Ceramics
Ceramic and Natural Stone Tiles Market
Ceramics
Advanced Structural Ceramics Market
Ceramics
Ceramic Fabrication Services Market
Ceramics
Colloidal Alumina Market
Ceramics
Malaysia Ceramic Tiles Market
Ceramics
Zeolite 4A Market
Ceramics
Low Temperature Co-Fired Ceramic (LTCC) Market
Ceramics
Glazed Ceramic Tile Market
Ceramics
Ceramic Setter Plate Market
Ceramics
Ceramic Injection Molding Market